
 Enterprise Resource Planning Market | 2026-2036
Enterprise Resource Planning Market Size, Share, and Industry Trends Forecast 2026-2036
Enterprise Resource Planning Market Analysis
Multi-source vendor strategies is shifting how enterprises procure ERP capabilities, replacing monolithic single-vendor lock-in with modular best-of-breed integrations. SAP SE anchors the high-end segment through deep vertical specialization in process industries. Oracle Corporation competes aggressively in database-integrated ERP suites for large enterprises. Microsoft Corporation extends its position via native cloud connectivity with Office 365 and Azure infrastructure.
Enterprise Resource Planning denotes integrated software architectures that unify financial ledger systems, inventory databases, and human capital records through a shared relational data model and real-time transaction processing. These systems execute material requirements planning algorithms and automate procurement workflows across multi-site operations. Cloud deployment now leads new installations as subscription economics replace perpetual license models. Financial Management functionality captures the largest margin pool given its regulatory audit mandate, while Supply Chain Management shows the fastest expansion as manufacturers seek demand-sensing capabilities.
GDPR enforcement by European data protection authorities compels ERP vendors to embed consent management and data residency controls into core platform architectures. The EU AI Act further shapes product roadmaps by classifying automated decision modules in HR and finance applications as high-risk systems. ISO 27001 certification has become a baseline procurement filter for enterprise buyers evaluating vendor security postures. Stakeholders must weigh interoperability standards against vendor-specific innovation roadmaps when committing to decade-long platform contracts.
Market Dynamics
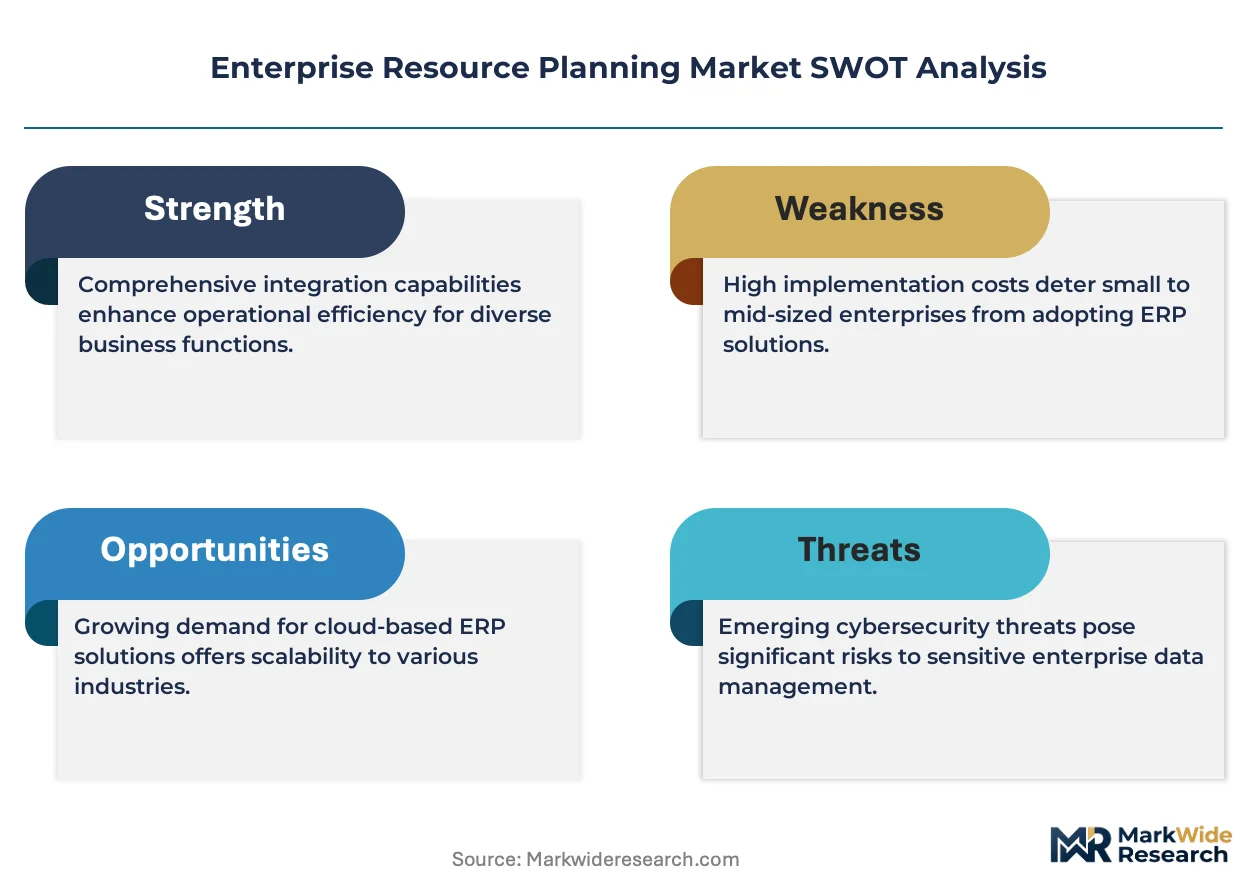
Cloud-native architectures are dismantling the perpetual-license fortress that SAP and Oracle built over three decades, forcing incumbents to reprice subscription tiers and absorb multi-year margin compression while defending installed bases against modular challengers.
Growth Catalysts
- GDPR Article 44 mandates:German manufacturers must maintain EU data residency, compelling ERP refreshes with embedded consent-management modules and audit-trail capabilities.
- Mid-market cloud migration:Indian automotive suppliers are abandoning on-premise legacy stacks for SaaS financial suites that scale with export order volatility.
- AI-enabled demand sensing:Machine learning algorithms embedded in supply-chain modules are compressing forecast-to-fulfillment cycles for US discrete manufacturers.
Market Restraints
- Implementation cost overruns:Large-scale SAP S/4HANA migrations routinely exceed budget by 40-60% due to data-migration complexity and custom-code remediation.
- Consultant supply concentration:Certified implementation partners cluster in Germany, the United States, and India, creating 18-24 month queue bottlenecks for qualified resources.
- Technical debt accumulation:Decades of COBOL and ABAP customizations in legacy Oracle E-Business Suite installations block seamless cloud transitions without functional regression.
Strategic Opportunities
- EU AI Act high-risk classification:Automated HR decision modules require explainability-by-design, creating premium pricing power for vendors with embedded audit frameworks.
- India PLI scheme manufacturing scale:Electronics and pharmaceutical contract manufacturers need multi-entity consolidation tools for incentive compliance and transfer-pricing documentation.
- API-first ecosystem orchestration:Best-of-breed integration platforms are capturing margin pools previously monopolized by suite vendors through composable architecture subscriptions.
Industry Challenges
- Scarce cloud-migration architects:Enterprises face 12-month search cycles for professionals fluent in both legacy ABAP and modern microservices containerization.
- ISO 27001 certification timelines:Vendor security audits now extend 6-9 months, delaying procurement decisions and compressing implementation windows.
- Multi-instance consolidation complexity:Post-merger integration of heterogeneous ERP estates requires data-model harmonization that stalls synergy realization.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Enterprise Resource Planning Market |
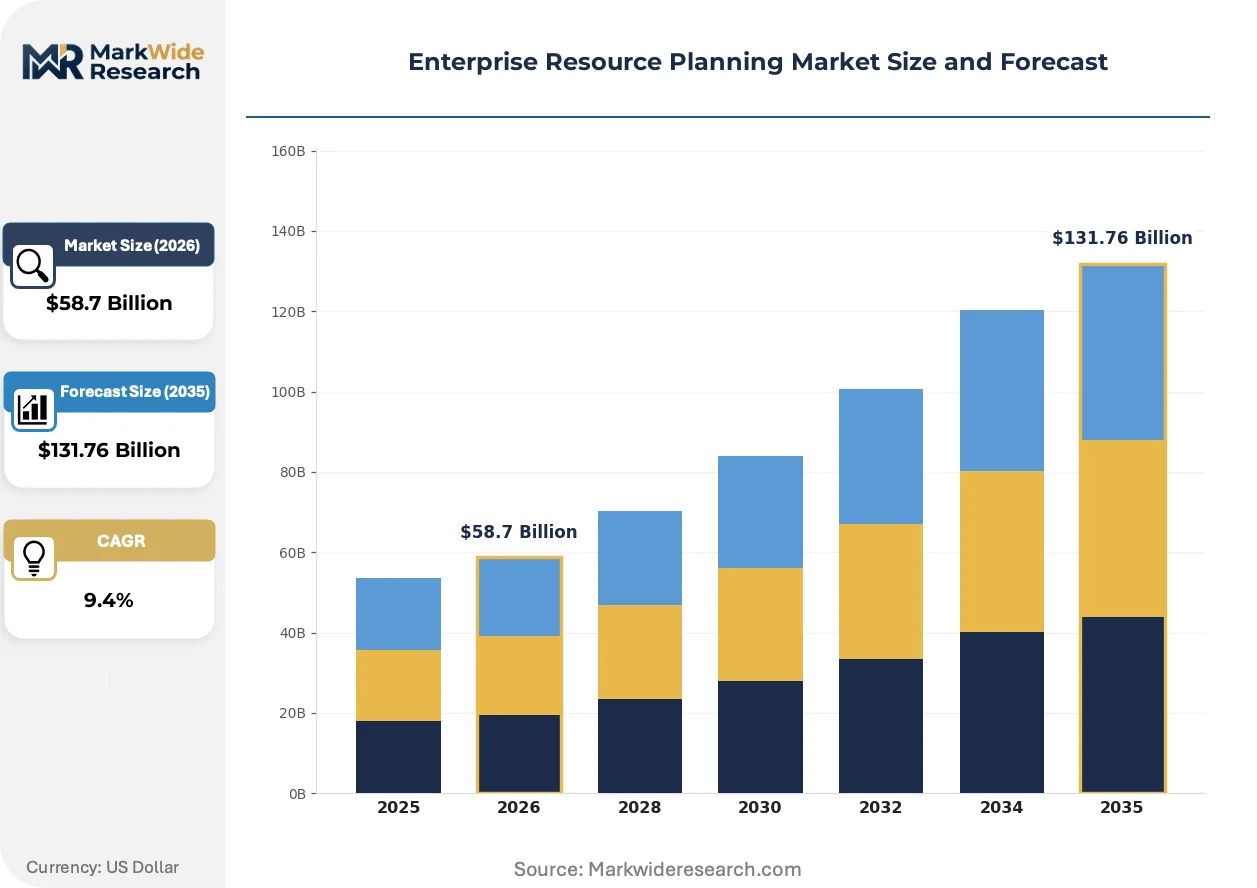
| Market Size in 2026 | $58.7 Billion |
| Market Size in 2035 | $131.76 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
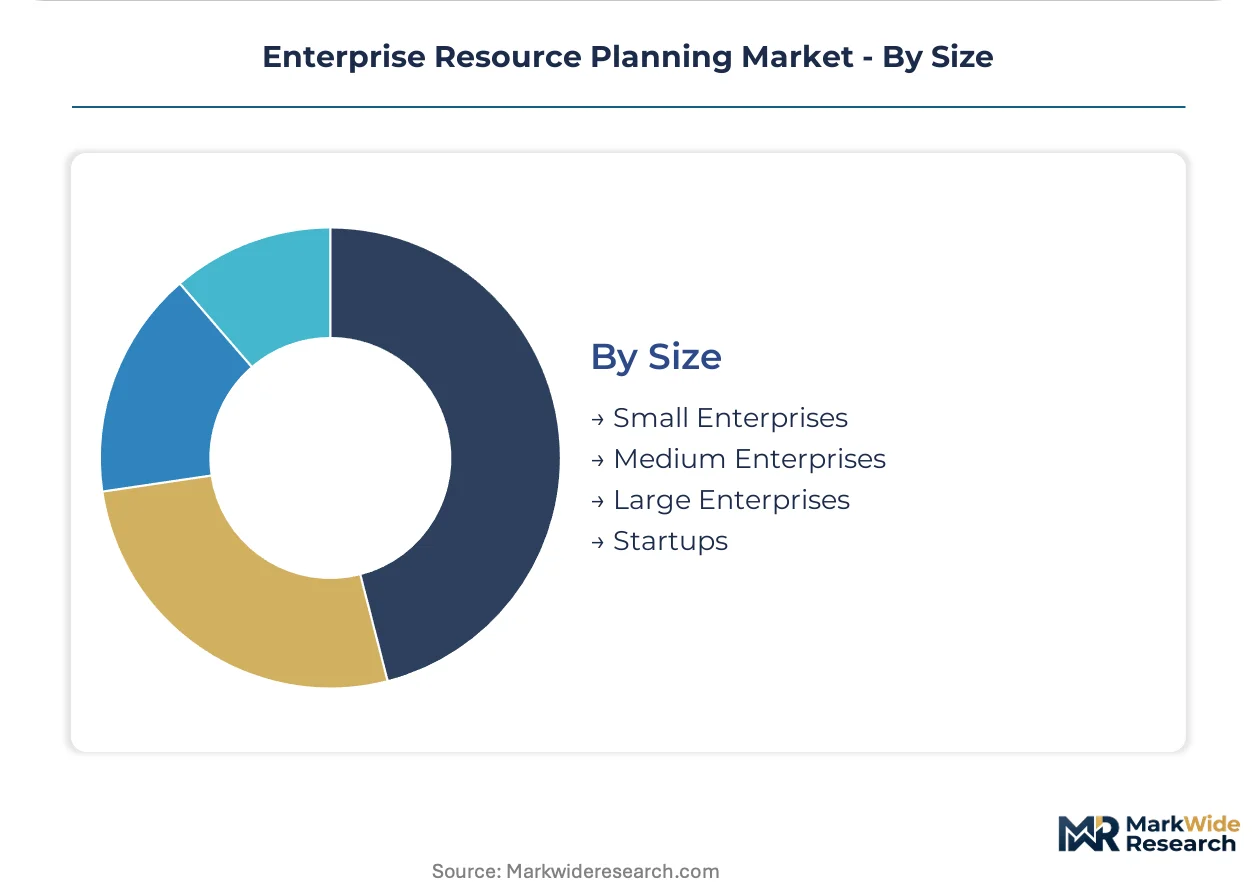
| Segmentation | Deployment: On-Premise, Cloud, Hybrid, SaaS End User: Manufacturing, Retail, Healthcare, Education Functionality: Financial Management, Supply Chain Management, Human Resources, Customer Relationship Management Size: Small Enterprises, Medium Enterprises, Large Enterprises, Startups |
| Companies Covered | SAP SE, Oracle Corporation, Microsoft Corporation, Infor Inc., Sage Group plc, Epicor Software Corporation, IFS AB, Workday Inc., IBM Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Enterprise Resource Planning Market Emerging Trajectories
Embedded intelligence and composable architecture are redrawing competitive boundaries, as buyers reject monolithic suites in favor of interoperable components that swap without vendor lock-in.
Agentic AI orchestration is automating routine procurement approvals, exception handling, and reconciliations within financial modules. Mid-sized manufacturers in Germany are piloting these capabilities fastest, drawn by labor-cost pressures. The technology is automating tier-2 supplier onboarding workflows that previously required manual document verification and credit checks.
The EU AI Act's high-risk system classification is mandating human-in-the-loop overrides for automated hiring and credit decisions embedded in HR and finance modules. Vendors must redesign algorithmic transparency features and maintain decision audit trails spanning seven years. German process manufacturers with unionized workforces face the steepest compliance retrofit costs.
Subscription consumption models are displacing perpetual licenses across the buyer base, with annual recurring revenue metrics now dominating vendor valuation multiples. System integrators are unbundling implementation from software, selling outcome-based transformation contracts with success fees tied to go-live milestones. This shift is most visible in US healthcare provider networks modernizing revenue-cycle management platforms.
Enterprise Resource Planning Market Segmentation
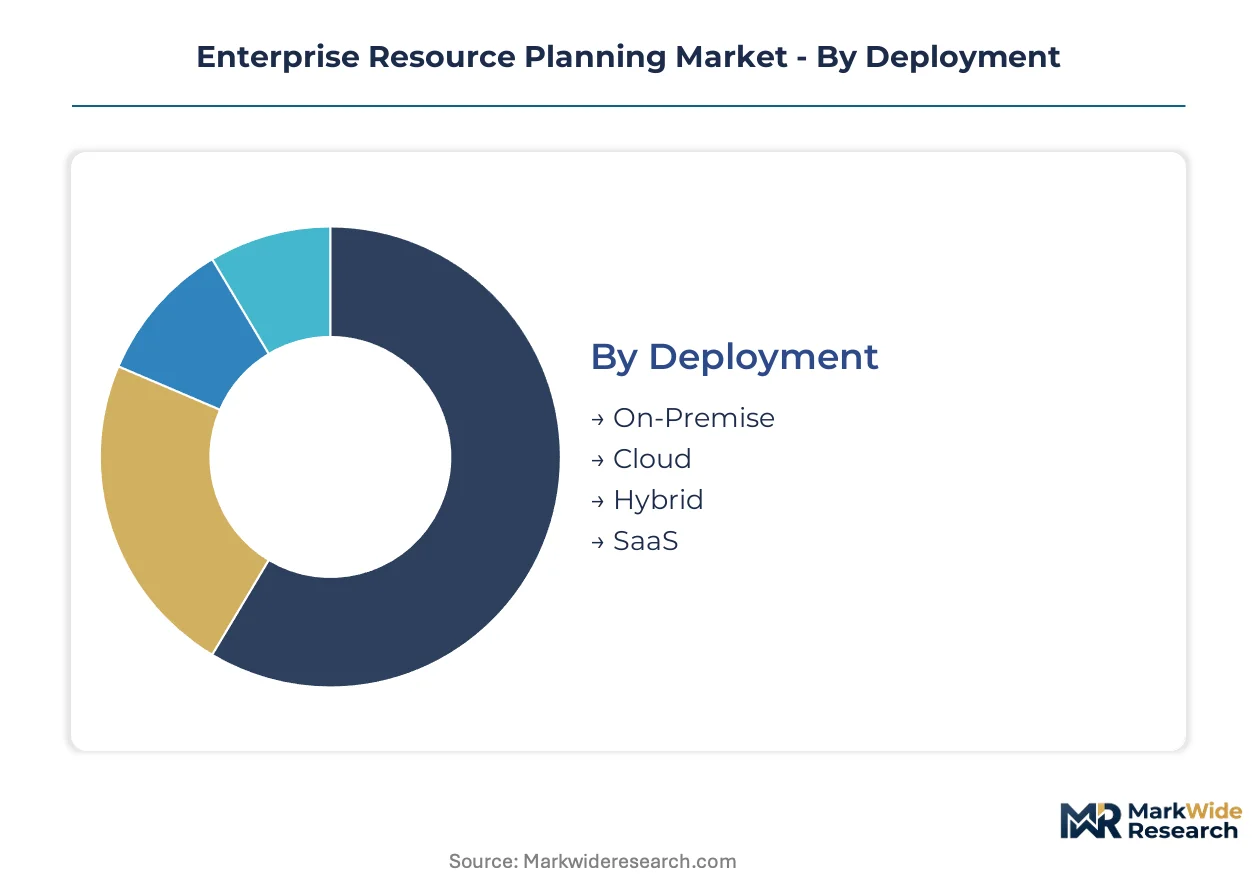
ERP segmentation reveals how vendor R&D investments and buyer procurement priorities diverge across deployment architectures, organizational scale, and functional modules. Understanding these fault lines exposes where margin pools concentrate and where modular challengers can displace incumbents.
Deployment:
Supply concentration in certified implementation partners tilts deployment economics toward models requiring less on-site customization.
- Cloud:Multi-tenant architectures with shared infrastructure layers eliminate perpetual-license capital expenditure. German automotive suppliers and US healthcare networks are migrating fastest, drawn by GDPR-compliant EU data residency options and HIPAA-aligned security frameworks.
- SaaS:Subscription consumption with automatic feature updates shifts vendor incentives toward retention metrics rather than upfront license recognition. Indian contract manufacturers favor this model for scaling with PLI scheme production ramps without infrastructure lock-in.
- On-Premise:Dedicated hardware installations persist in defense and classified government environments where air-gapped security is mandatory.
- Hybrid:Split architectures keep sensitive financial ledgers on-premise while routing customer-facing modules through cloud instances.
Today's leader: Cloud. Tomorrow's challenger: SaaS.
End User:
Cost tier differentiation separates process-intensive verticals requiring deep customization from standardized service sectors.
- Manufacturing:Discrete and process producers demand embedded MRP algorithms, shop-floor connectivity, and multi-entity consolidation for transfer-pricing compliance. German chemical conglomerates and Indian electronics contract manufacturers represent the most demanding buyer cohort.
- Healthcare:Revenue-cycle management, HIPAA audit trails, and supply-chain traceability for pharmaceuticals drive module selection. US hospital networks are modernizing fastest, absorbing implementation cost overruns for regulatory compliance.
- Retail:Omnichannel inventory synchronization and demand-forecasting modules dominate procurement criteria.
- Education:Student information systems and grant-management functionality shape vendor evaluation, with lower complexity tolerance than commercial sectors.
Manufacturing commands premium pricing power; healthcare shows the steepest expansion trajectory as compliance requirements intensify.
Functionality:
Application criticality determines which modules escape best-of-breed substitution and which surrender to specialized challengers.
- Financial Management:General ledger, accounts payable, and regulatory reporting form the non-negotiable core with the deepest switching costs. GDPR and SOX audit mandates preserve incumbent dominance despite subscription repricing pressure.
- Supply Chain Management:Demand-sensing algorithms, supplier collaboration portals, and logistics optimization are gaining share fastest as manufacturers seek inventory velocity. Machine learning embedded in forecasting modules compresses planning cycles for US discrete manufacturers.
- Human Resources:Payroll, benefits administration, and talent management face disruption from specialized HCM suites with superior user experience.
- Customer Relationship Management:Sales force automation and service ticketing increasingly integrate with standalone CRM platforms rather than monolithic ERP suites.
Financial Management anchors vendor retention; Supply Chain Management is climbing the fastest as AI-enabled capabilities mature.
Size:
Customer type stratification creates distinct competitive arenas where mid-market cloud-native vendors challenge incumbent lock-in.
- Large Enterprises:Multi-entity, multi-currency operations with decades of technical debt require complex data-migration architectures. SAP and Oracle defend installed bases through vertical specialization and compliance certification depth.
- Medium Enterprises:Simpler organizational structures enable faster cloud transitions without custom-code remediation bottlenecks. This segment shows the fastest vendor switching as subscription economics reduce switching costs.
- Small Enterprises:Standardized processes allow out-of-box configuration with minimal implementation services, favoring lightweight SaaS suites.
- Startups:Greenfield deployments select cloud-native platforms without legacy baggage, prioritizing API extensibility over feature depth.
Large Enterprises dominate vendor revenue concentration; Medium Enterprises represent the most contested battleground for market share gains.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German manufacturing clusters drive ERP modernization as GDPR enforcement and export compliance reshape procurement priorities across discrete and process industries.
Germany
Automotive and chemical conglomerates anchor demand for embedded MRP algorithms and multi-entity consolidation tools. The EU AI Act mandates human-in-the-loop overrides for automated HR decisions, forcing retrofit investments. Bavarian process manufacturers face the steepest compliance costs for unionized workforce modules.
United States
Healthcare networks and discrete manufacturers propel cloud migration for HIPAA-aligned revenue-cycle platforms and demand-sensing capabilities. FDA audit mandates for pharmaceutical supply-chain traceability accelerate module upgrades. Hospital networks in Texas and the Midwest absorb implementation overruns to maintain compliance certification.
India
Electronics and pharmaceutical contract manufacturers scale SaaS deployments to match PLI scheme production ramps without infrastructure lock-in. DGFT export documentation requirements and RBI foreign-exchange reporting drive financial module refreshes. Karnataka and Tamil Nadu automotive supplier clusters lead mid-market cloud adoption.
United Kingdom
Financial services and professional services firms prioritize GDPR-compliant data residency and SOX-equivalent audit frameworks post-Brexit. The Financial Conduct Authority's operational resilience requirements pressure legacy system replacements. London-based asset managers and Edinburgh fund administrators dominate procurement volume.
Japan
Precision manufacturing and automotive Tier-1 suppliers invest in supply-chain modules with embedded machine learning for inventory velocity. METI's data-free flow with trust initiatives shape vendor selection criteria. Nagoya-based industrial equipment makers and Osaka electronics assemblers represent the most demanding buyer cohort.
Enterprise Resource Planning Market Vendor Landscape
Global majors compete with regional champions across deployment architecture and vertical specialization, creating a tiered structure where scale advantages clash with modular agility. The market consolidates around database-integrated suite vendors, cloud-native challengers, and vertical specialists with deep industry templates. Strategic moves center on subscription repricing to defend installed bases and API-first ecosystem partnerships that unbundle monolithic functionality.
Within the enterprise suite tier, SAP SE and Oracle Corporation anchor high-end positioning through decades of vertical certification depth, while Microsoft Corporation extends cloud-native connectivity via infrastructure integration. These three exemplify the incumbent archetype absorbing margin compression while defending multi-decade customer relationships against modular disaggregation.
| Leading Market Players |
|---|
| SAP SE |
| Oracle Corporation |
| Microsoft Corporation |
| Infor Inc. |
| Sage Group plc |
| Epicor Software Corporation |
| IFS AB |
| Workday Inc. |
| IBM Corporation |
| Others |
Supply Flow & Price Mechanics
Mid-sized German automotive suppliers concentrate procurement power for cloud-native ERP suites, forcing vendors toward subscription consumption models that eliminate perpetual-license capital expenditure. This buyer archetype's compliance-driven refresh cycles tether pricing power to GDPR audit-trail capabilities and EU data residency guarantees.
Pricing Analysis
Input-cost pass-through from certified implementation partner scarcity is intensifying margin compression across deployment tiers. Pricing stratifies across premium, standard, and economy tiers differentiated by vertical specialization depth and ISO 27001 certification status. Cost compression in mid-market SaaS tiers is accelerating because hyperscaler infrastructure fees and consultant queue bottlenecks squeeze vendor margins. Large enterprises with decades of ABAP technical debt show least price sensitivity; Indian contract manufacturers scaling PLI scheme production exhibit highest.
Supply Chain Analysis
Workforce availability constraints in Germany, India, and the United States concentrate certified SAP and Oracle implementation capacity, extending procurement queues to 18-24 months. The ERP supply chain draws from cloud infrastructure providers, systems integration partners, and vertical template developers. Single-source vulnerability in certified ABAP-to-microservices migration architects creates project stall risk. Distribution runs through direct vendor sales, hyperscaler marketplaces, and regional systems integrators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
German process manufacturers face steeper EU AI Act compliance costs than US healthcare networks, creating geographic arbitrage for vendors with pre-certified audit frameworks. This cost differential favors early certification investment in Bavarian chemical clusters over Texas hospital networks.
For Market Incumbents: Deepen vertical specialization in unionized workforce modules to capture EU AI Act high-risk classification premiums. Anchor retention through embedded consent-management architectures that block modular substitution. Expand certified partner networks in Karnataka and Tamil Nadu to relieve consultant queue bottlenecks threatening installed base defense.
For New Entrants and Emerging Players: Launch via API-first ecosystem orchestration to capture margin pools from best-of-breed integration demand. Target medium enterprises with composable architectures that bypass legacy migration complexity. Penetrate fastest through SaaS financial suites for Indian electronics contract manufacturers scaling PLI scheme production.
For Investors and Strategic Acquirers: Cloud-native platform vendors with embedded AI explainability frameworks are the most active acquirer targets in this space. Five-to-ten year viability hinges on compliance certification depth rather than feature breadth. Watch for DGFT export documentation mandate expansion as inflection signal for Indian manufacturing ERP refresh cycles.
| Strategic Initiative | Industry Significance |
|---|---|
| EU AI Act Compliance Certification | Bavarian chemical manufacturers face steepest retrofit costs for unionized workforce modules. |
| API-First Ecosystem Partnership | Best-of-breed integration platforms capture margin pools from monolithic suite unbundling. |
| India PLI Scheme Vertical Expansion | Karnataka electronics contract manufacturers need multi-entity consolidation for incentive compliance. |
| GDPR Data Residency Architecture | German automotive suppliers mandate EU-hosted cloud instances with embedded consent management. |
| Outcome-Based Implementation Contracting | US healthcare networks absorb success-fee structures tied to HIPAA-aligned go-live milestones. |
Methodological Framework
Coverage spans Germany, the United States, India, the United Kingdom, and Japan, with primary inputs from each regional cluster. Primary interviews with CTOs, IT procurement officers, platform engineers, and systems integration specialists combined with secondary validation from SEC filings, hyperscaler capex disclosures, and hospital procurement databases. Bottom-up deployment counts and top-down vendor revenue estimates underwent triangulation.
Granularity-level modeling segmented by deployment architecture, organization size, functional module, and vertical industry across the analysis window. CAGRs derived from trend extrapolation of subscription revenue recognition patterns and cloud migration velocity curves. Forecast inputs incorporated PLI scheme production ramp schedules and EU AI Act implementation timelines.
Forecast precision tightens around the base case; tail outcomes carry wider variance under abrupt GDPR enforcement escalation or hyperscaler infrastructure pricing shocks. Projections reflect assumptions about consultant supply elasticity and legacy technical debt remediation feasibility. Material deviation in EU AI Act audit framework finalization warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
Binary Drivers Market
Software & Services
Global Log Management Software Market
Software & Services
Software Repository Market
Software & Services
Collaborative Office Software Market
Software & Services
Bridge Analysis Software Market
Software & Services
Design Collaboration Software Market
Software & Services
Global Managed File Transfer Software Market
Software & Services
Global Decision Support Software Market
Software & Services
Network Bandwidth Management Software Market
Software & Services
Sales Compensation Software Market
Software & Services
Collaborative Applications Market
Software & Services
Logistics Services Software Market
Software & Services
Sales Enablement Software Market
Software & Services
Global Advanced Planning and Scheduling (APS) Software Market
Software & Services
VFX Software Market
Software & Services
RIP Color Management Software Market