
 Global Desktop As a Service Market | 2026-2036
Global Desktop As a Service Market Size, Share, and Industry Trends Forecast 2026-2036
Global Desktop As a Service Market Foresight
Cloud-native virtualization is rewriting enterprise endpoint architecture by decoupling compute from physical hardware. Microsoft Corporation leverages its Azure ecosystem to anchor hybrid workforce deployments across regulated industries. Amazon Web Services sustains price-performance leadership through Graviton-powered instance families purpose-built for persistent desktop streaming. VMware Inc. specializes in multi-cloud orchestration layers that unify on-premises VDI with hyperscaler-hosted workloads.
Desktop as a Service delivers virtualized Windows, Linux, or macOS environments streamed from centralized cloud data centers to endpoint devices over encrypted protocols, typically operating at sub-50 millisecond latency thresholds for interactive usability. Its primary commercial purpose is to eliminate capital expenditure on desktop hardware while centralizing security patching, data loss prevention, and compliance auditing. Managed DaaS offerings capture the dominant margin pool as enterprises outsource endpoint security and patch lifecycle duties to specialist operators. Hybrid Cloud deployment models are expanding fastest among financial services firms seeking to retain sensitive trading data on-premises while bursting general productivity workloads to public infrastructure. Thin Clients represent the most hardware-optimized access tier, stripping local OS overhead to minimize attack surface and extend replacement cycles.
FDA 21 CFR Part 11 guidelines shape validation requirements for pharmaceutical firms deploying virtualized laboratory workstations, while HIPAA Security Rule mandates govern how healthcare DaaS providers architect encryption and access logging. The EU AI Act and GDPR impose algorithmic transparency and data residency constraints on European deployments, compelling providers to certify regional data center footprints. Stakeholders must monitor how NIST zero-trust architecture mandates reshape authentication requirements for federal contractor desktop environments.
Market Dynamics
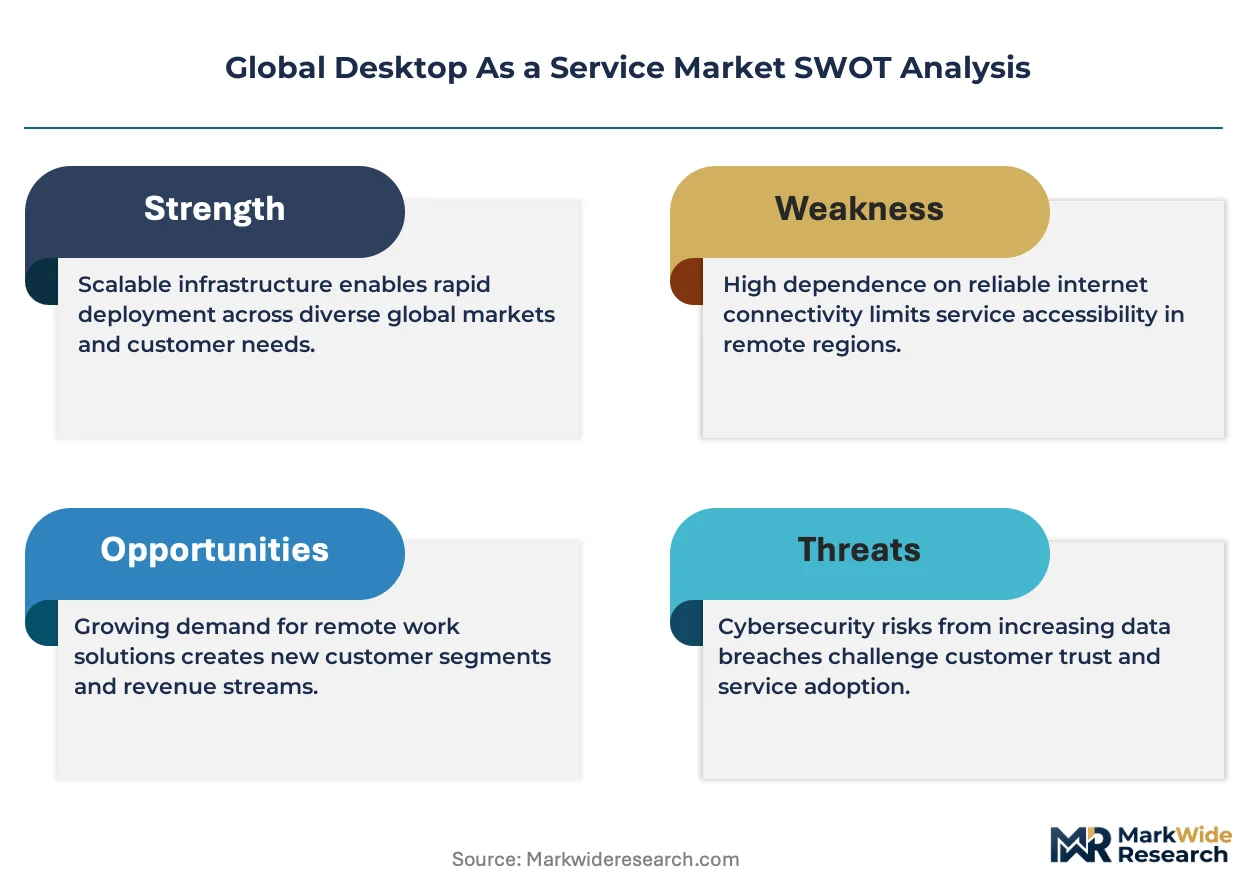
Cloud-native virtualization is decoupling compute from physical hardware, forcing traditional endpoint vendors to rearchitect around subscription-based delivery models and zero-trust security frameworks.
Growth Catalysts
- GDPR and EU AI Act mandates:European enterprises are accelerating managed DaaS adoption to satisfy data residency and algorithmic transparency requirements without building captive infrastructure.
- Federal zero-trust mandates:US agencies are modernizing legacy endpoint environments under NIST guidance, creating concentrated demand for compliant virtual desktop streams.
- Thin client hardware:Healthcare delivery networks are deploying stripped-down access devices to minimize attack surfaces while extending hardware replacement cycles.
Market Restraints
- Hyperscaler concentration:Persistent desktop streaming capacity concentrates among three US-based cloud providers, creating single-source vulnerability for enterprise deployments.
- Latency physics:Sub-50 millisecond interactive thresholds require edge data center proximity that remains unevenly distributed across secondary metros.
- HIPAA validation costs:Healthcare DaaS providers face substantial compliance documentation burdens under the Security Rule's encryption and access logging mandates.
Strategic Opportunities
- India's BIS certification pipeline:Domestic IT services firms are building sovereign DaaS capabilities to capture public sector contracts under local data localization policies.
- GPU-accelerated workstation virtualization:Converging cloud graphics and AI inference workloads are opening new revenue pools in pharmaceutical R&D and media production.
- Managed service channel expansion:Specialist operators are capturing margin pools by assuming endpoint security and patch lifecycle duties from enterprise IT departments.
Industry Challenges
- Multi-cloud orchestration expertise:Enterprises lack personnel capable of unifying on-premises VDI with hyperscaler-hosted workloads across Azure, AWS, and private infrastructure.
- FDA 21 CFR Part 11 validation timelines:Pharmaceutical firms face extended certification cycles when deploying virtualized laboratory workstations for electronic record-keeping.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Desktop As a Service Market |
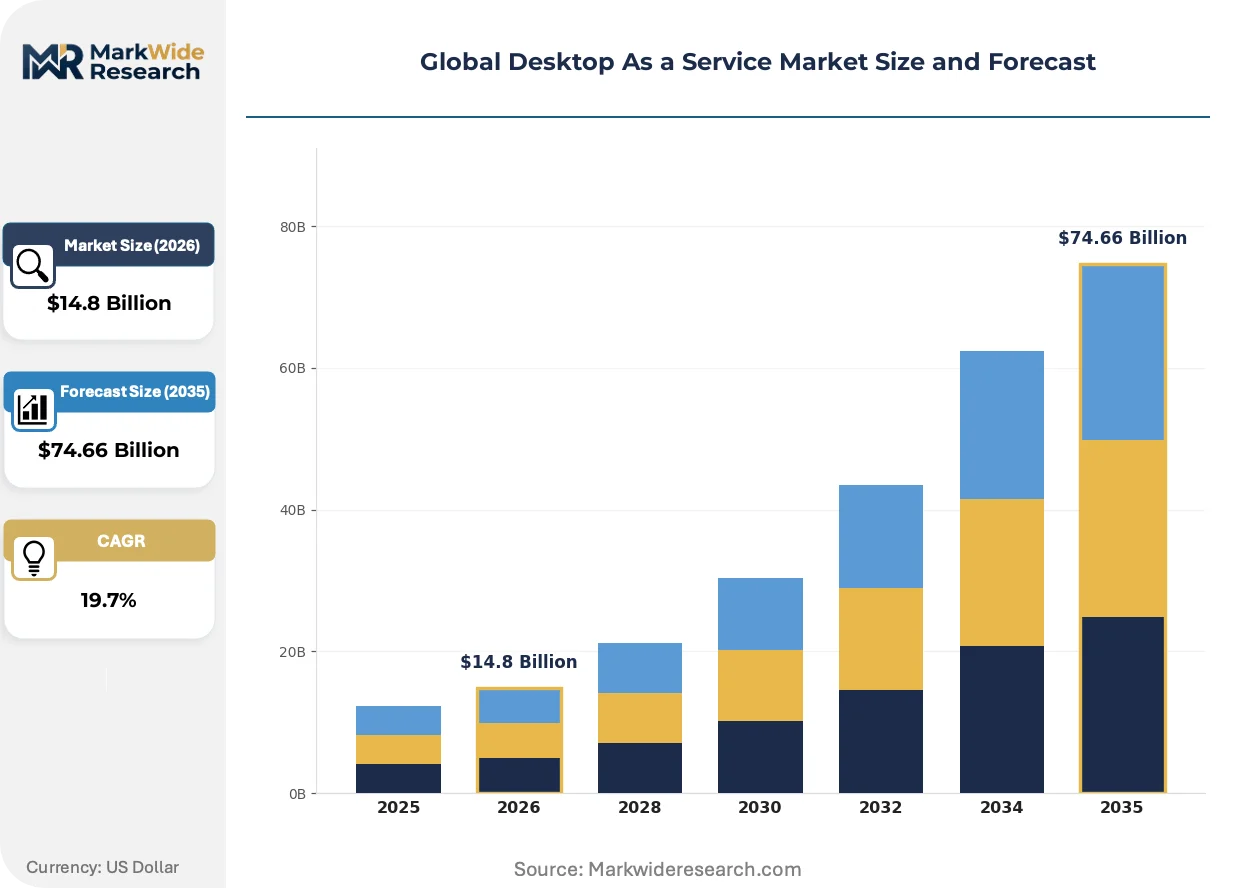
| Market Size in 2026 | $14.8 Billion |
| Market Size in 2035 | $74.66 Billion |
| CAGR (2026 – 2036) | 19.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment Model: Public Cloud, Private Cloud, Hybrid Cloud, Community Cloud Offering Type: Managed DaaS, Non-managed DaaS, Virtual Desktop Infrastructure, Application Streaming End User Industry: BFSI Institutions, Telecommunication Providers, Educational Entities, Government Agencies Access Device: Thin Clients, Laptops, Smartphones, Tablets, Workstations |
| Companies Covered | Amazon Web Services, Microsoft Corporation, VMware Inc., Citrix Systems Inc., Oracle Corporation, IBM Corporation, Google, Nutanix Inc., Fujitsu Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Desktop As a Service Market Shifts & Advancements
Streaming protocols and edge infrastructure are compressing the viable distance between centralized compute and distributed endpoints, reshaping where enterprises locate their desktop workloads.
Browser-based desktop streaming is rendering obsolete thick client software installations across regulated industries. Financial services firms in London and Singapore are deploying Chrome Enterprise and similar HTML5 receivers to eliminate local OS management overhead. This shift is compressing endpoint support costs while expanding device flexibility for hybrid workforces.
CSRD sustainability disclosure rules are compelling European DaaS providers to certify carbon intensity metrics for data center operations. The regulation is triggering infrastructure relocation toward Nordic hydroelectric-powered facilities. German and Dutch enterprises are now embedding emissions reporting into procurement evaluations for managed desktop services.
Consumption-based pricing models are displacing per-seat subscriptions in mid-market manufacturing and logistics verticals. Channel partners in the US Midwest are unbundling hardware, software, and management tiers to match variable workforce scaling. This pattern is most visible among seasonal employers and project-based professional services firms seeking to align IT spend with actual usage patterns.
Global Desktop As a Service Market Segmentation
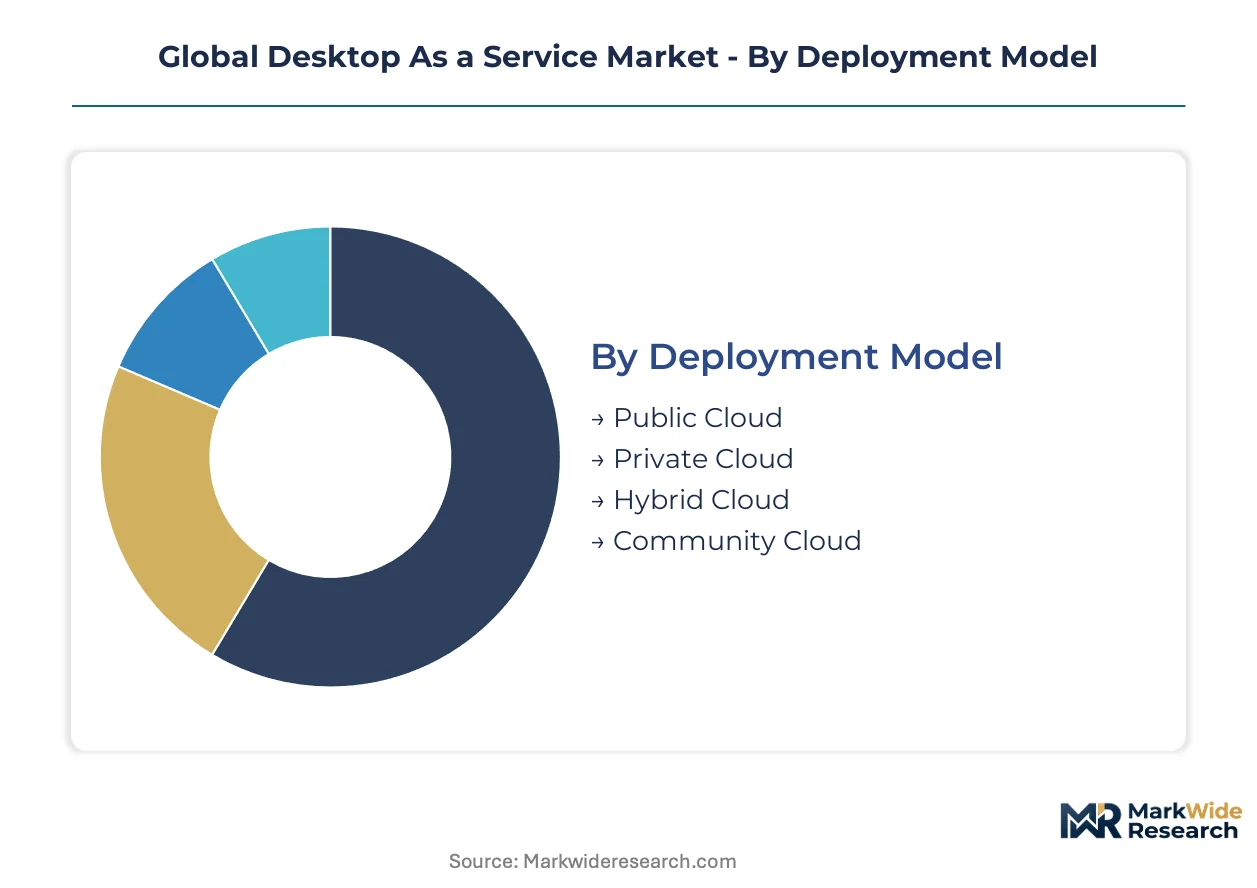
Desktop as a Service architectures fragment across deployment topology, service responsibility models, industry-specific compliance requirements, and endpoint hardware categories. Each dimension carries distinct margin structures and vendor capability requirements that reshape competitive positioning.
Deployment Model:
Cost tier differentiation separates infrastructure ownership models from fully outsourced consumption patterns.
- Public Cloud:Multi-tenant infrastructure pools compute resources across shared hyperscaler data centers. Demand concentrates among mid-market enterprises in the United States seeking to eliminate capital expenditure on endpoint hardware while meeting NIST zero-trust authentication mandates.
- Hybrid Cloud:Unified orchestration layers span on-premises VDI and burst capacity to public infrastructure. Financial services firms in London and Singapore retain sensitive trading data locally while pushing general productivity workloads to cloud instances.
- Private Cloud:Single-tenant dedicated environments serving regulated workloads requiring data residency certification.
- Community Cloud:Shared infrastructure restricted to specific industry cohorts with mutual compliance obligations.
Public Cloud commands the established base. The steepest expansion runs through Hybrid Cloud.
Offering Type:
Service maturity levels distinguish full lifecycle outsourcing from self-managed virtualization stacks.
- Managed DaaS:Specialist operators assume endpoint security, patch lifecycle, and compliance documentation duties. Healthcare delivery networks across Germany and the Netherlands outsource HIPAA and GDPR validation burdens to certified providers.
- Virtual Desktop Infrastructure:Enterprise-controlled virtualization stacks requiring internal expertise in multi-cloud orchestration across Azure, AWS, and private infrastructure.
- Non-managed DaaS:Raw infrastructure provisioning without operational support services.
- Application Streaming:Isolated software delivery without full desktop virtualization overhead.
Managed DaaS captures the dominant margin pool. Application Streaming is gaining share fastest among browser-first deployment strategies.
End User Industry:
Regulatory intensity varies sharply across vertical compliance frameworks and data sensitivity requirements.
- BFSI Institutions:Trading floors and retail banking operations require sub-50 millisecond latency with granular audit trails. Singaporean and Swiss private banks deploy virtual desktops to satisfy cross-border data governance while enabling mobile advisor workflows.
- Government Agencies:Federal contractors modernize legacy endpoint environments under mandatory zero-trust architecture timelines. United States civilian and defense agencies concentrate procurement through FedRAMP-authorized service catalogs.
- Telecommunication Providers:Network operators virtualize customer service and field engineering workstations.
- Educational Entities:Universities and K-12 districts provision semester-scaled lab environments.
BFSI Institutions anchor premium pricing tiers. Government Agencies show the steepest budget acceleration through federal modernization mandates.
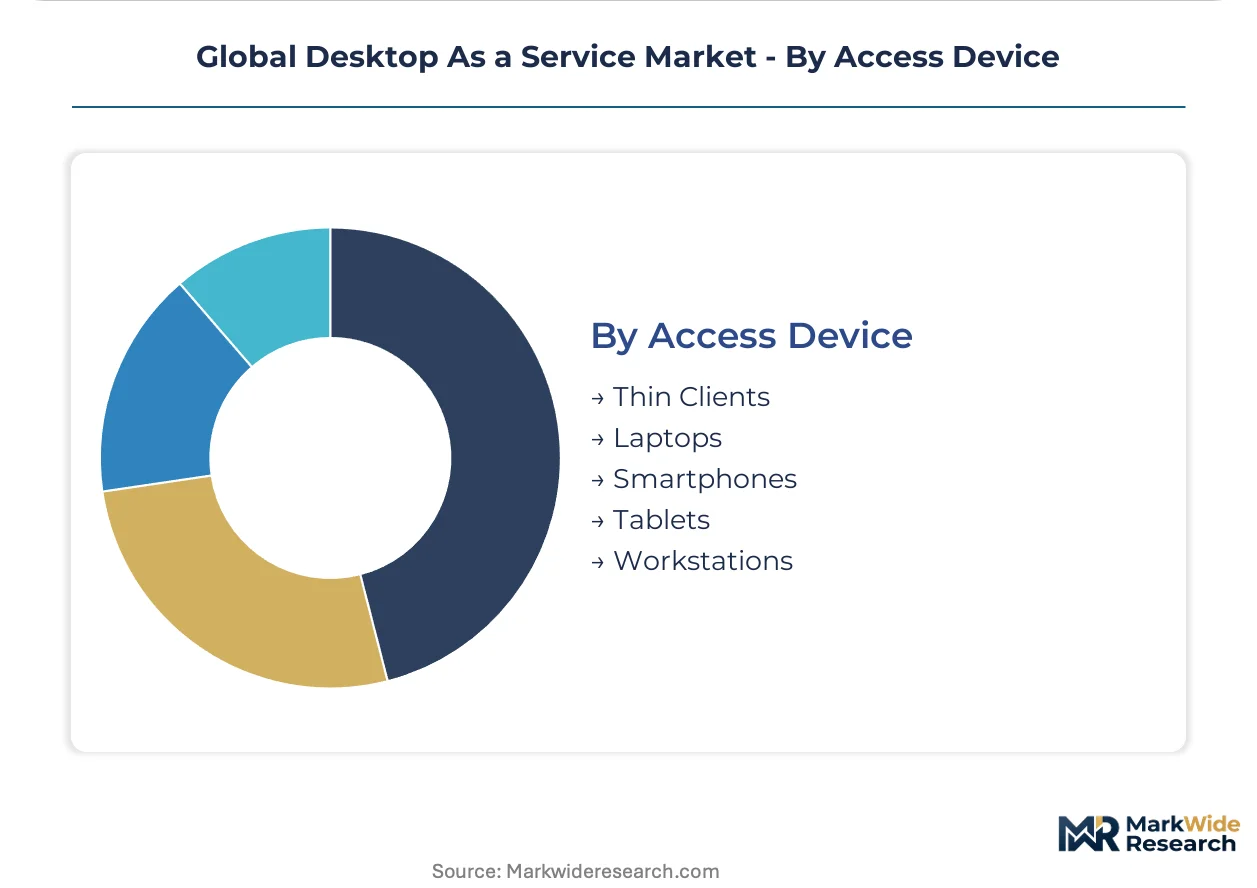
Access Device:
Hardware optimization levels determine attack surface exposure and replacement cycle economics.
- Thin Clients:Stripped-down access devices eliminate local OS overhead to minimize security exposure. Healthcare systems in the United States extend hardware replacement cycles while satisfying HIPAA Security Rule encryption mandates.
- Workstations:GPU-accelerated endpoints support pharmaceutical R&D and media production workloads requiring cloud graphics and AI inference convergence.
- Laptops:Full-capability mobile endpoints retaining local processing for offline continuity.
- Tablets:Touch-optimized form factors for field service and clinical bedside access.
- Smartphones:Pocket-scale emergency access tier with constrained screen real estate.
Thin Clients dominate hardware-optimized deployments. Workstations are climbing the fastest through GPU virtualization demand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States-based hyperscalers export virtual desktop infrastructure to European and Asian enterprise buyers seeking compliant cloud workspaces. Cross-border data governance requirements reshape procurement patterns across destination markets. Regulatory divergence between source and buyer jurisdictions creates certification complexity for managed service providers.
United States
Federal agencies and healthcare systems drive concentrated demand for FedRAMP-authorized virtual desktop streams. NIST zero-trust architecture mandates accelerate legacy endpoint modernization timelines through 2027. Washington D.C. and Northern Virginia data center clusters host the dominant share of government-compliant DaaS capacity.
Germany
Automotive manufacturers and pharmaceutical firms outsource endpoint security to certified managed operators. GDPR and EU AI Act compliance requirements compel providers to certify regional data center footprints in Frankfurt and Berlin. CSRD sustainability disclosure rules trigger infrastructure relocation toward Nordic hydroelectric-powered facilities.
United Kingdom
Financial services firms in London deploy hybrid cloud models retaining sensitive trading data locally while bursting general workloads. The Financial Conduct Authority's operational resilience guidelines shape vendor selection criteria for virtual desktop deployments. Canary Wharf and City of London technology clusters concentrate demand for sub-50 millisecond latency streams.
India
Domestic IT services firms build sovereign DaaS capabilities to capture public sector contracts under BIS certification and local data localization policies. The country's national IT regulator mandates encryption standards for government cloud deployments. Bengaluru and Hyderabad technology corridors emerge as primary development centers for indigenous virtual desktop platforms.
Singapore
Private banks and wealth management operations virtualize advisor workstations to satisfy cross-border data governance while enabling mobile workflows. The Monetary Authority of Singapore's technology risk management guidelines govern outsourcing arrangements for financial institutions. Marina Bay and Raffles Place financial districts anchor premium-tier demand for compliant desktop streaming.
Global Desktop As a Service Market Competitive Landscape
Channel-controlling players compete with product-specialist players across deployment topology and service maturity tiers. Hyperscale cloud providers anchor the consolidated infrastructure layer while specialist operators capture margin pools in managed security and compliance documentation. Three archetypes dominate: vertically integrated platform owners, multi-cloud orchestration specialists, and regional managed service providers. Competitive moves concentrate on strategic partnerships with systems integrators and portfolio diversification into GPU-accelerated workstation virtualization.
Among United States-based platform owners, Amazon Web Services and Microsoft Corporation occupy positions spanning infrastructure and application layers. VMware Inc. exemplifies the multi-cloud orchestration archetype with unified management across on-premises and hyperscaler-hosted workloads. These three anchors represent distinct competitive vectors: price-performance leadership through purpose-built instance families, ecosystem integration across productivity suites, and abstraction layers decoupling workloads from underlying infrastructure.
| Leading Market Players |
|---|
| Amazon Web Services |
| Microsoft Corporation |
| VMware Inc. |
| Citrix Systems Inc. |
| Oracle Corporation |
| IBM Corporation |
| Nutanix Inc. |
| Fujitsu Ltd. |
| Others |
Supply & Pricing Matrix
Hyperscaler concentration risk among three US-based cloud providers determines both tiered pricing spreads and supply chain configuration in the DaaS market. Single-source dependency for persistent desktop streaming capacity forces enterprises to accept bundled infrastructure pricing while driving channel partners toward multi-cloud orchestration investments.
Pricing Analysis
Next-generation GPU-accelerated workstation virtualization commands premium positioning against standard persistent desktop tiers and legacy VDI alternatives. Three-tier pricing structure across premium GPU-enabled, standard persistent, and economy non-persistent levels reflects performance certification and compliance documentation bundling. Pricing pressure stems from Graviton-powered instance families delivering improved price-performance ratios in general productivity workloads. Mid-market manufacturing verticals exhibit highest price sensitivity through consumption-based unbundling, while financial services firms in London and Singapore accept premium tiers for sub-50 millisecond latency guarantees.
Supply Chain Analysis
Supply-chain finance facilities from hyperscalers extend payment terms for channel partners deploying thin client hardware at enterprise scale. Manufacturing concentrates in Taiwan, China, and South Korea for semiconductor components powering edge data center infrastructure. Raw material dependencies span advanced processors, high-bandwidth memory modules, and specialized networking silicon. Single-source vulnerability persists for GPU virtualization chipsets used in pharmaceutical R&D workloads. Distribution runs through systems integrators and managed service providers capturing margin pools in compliance documentation and security lifecycle management.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating among federal agencies and healthcare delivery networks consolidating procurement through FedRAMP-authorized catalogs and HIPAA-certified provider shortlists.
For Market Incumbents: Entrench hybrid cloud orchestration capabilities across Azure, AWS, and private infrastructure to defend against specialist operators capturing managed service margin pools. Invest in Nordic hydroelectric-powered data center certifications to satisfy CSRD sustainability disclosure requirements from German and Dutch enterprises. Deepen vertical integration into GPU-accelerated workstation virtualization for pharmaceutical R&D segments. For New Entrants and Emerging Players: Establish a beachhead in India's sovereign DaaS market under BIS certification and local data localization policies. Target seasonal employers and project-based professional services firms seeking consumption-based pricing alignment. Pursue browser-first deployment strategies eliminating thick client software installation overhead. For Investors and Strategic Acquirers: EU AI Act implementation reshapes the acquisition landscape toward providers with certified regional data center footprints and algorithmic transparency documentation capabilities. Long-term viability centers on managed service operators assuming endpoint security and patch lifecycle duties from enterprise IT departments. Monitor NIST zero-trust architecture mandate acceleration as federal contractor demand inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| FedRAMP Authorization Acquisition | Unlocks federal agency procurement pipelines under mandatory zero-trust modernization timelines. |
| GPU Workstation Virtualization Launch | Captures pharmaceutical R&D and media production revenue pools through cloud graphics convergence. |
| Nordic Data Center Footprint Expansion | Satisfies CSRD carbon intensity disclosure requirements from German automotive and pharmaceutical buyers. |
| Managed Security Service Integration | Assumes HIPAA and GDPR validation burdens outsourced by healthcare delivery networks. |
| Browser-Based Streaming Protocol Development | Eliminates thick client overhead for financial services firms deploying Chrome Enterprise receivers. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with cloud infrastructure architects, managed service provider executives, healthcare IT security officers, and federal procurement specialists; and secondary validation through hyperscaler capex disclosures, SEC filings, FedRAMP authorization databases, and EU regulatory implementation notices. Bottom-up triangulation across deployment model, service maturity tier, and industry vertical dimensions anchored volume estimates. Top-down cross-checks against hyperscaler reported cloud revenue segments refined growth trajectory assumptions.
Forecast inputs span public cloud, hybrid cloud, private cloud, and community cloud deployment topologies across managed DaaS, virtual desktop infrastructure, and application streaming service models. End-user industry segmentation incorporates BFSI, government agencies, healthcare delivery networks, and telecommunications providers with distinct compliance framework requirements. CAGRs derive from elasticity-adjusted adoption curves incorporating NIST zero-trust mandate acceleration and EU AI Act compliance deadlines. GPU virtualization penetration and thin client hardware refresh cycles provide additional industry-specific forecast inputs.
Sensitivities concentrate around hyperscaler pricing strategy shifts, edge data center buildout pace in secondary metros, and regulatory timeline adjustments for federal zero-trust mandates. Forecasts reflect documented assumptions on latency threshold achievability and managed service outsourcing propensity by enterprise size tier. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
Global Back Testing Software Market
Software & Services
Chatbot Builder Software Market
Software & Services
Supplier Quality Management Applications Market
Software & Services
Global Funeral Home Software Market
Software & Services
Global Storm Tracking Apps Market
Software & Services
Global Document Management Software Market
Software & Services
Global Note Taking App Market
Software & Services
Enterprise Data Observability Software Market
Software & Services
Software Consulting Market
Software & Services
SRM Software Market
Software & Services
School Timetable Software Market
Software & Services
Mobile Application Development Platform (MADP) Market
Software & Services
Content Distribution Software Market
Software & Services
Data Exchange Platform Services Market
Software & Services
Application Lifecycle Management (ALM) Market
Software & Services
Online Recruitment Software Market