
 Global UIUX Software Market | 2026-2036
Global UIUX Software Market Size, Share, and Industry Trends Forecast 2026-2036
Global UIUX Software Market Foresight
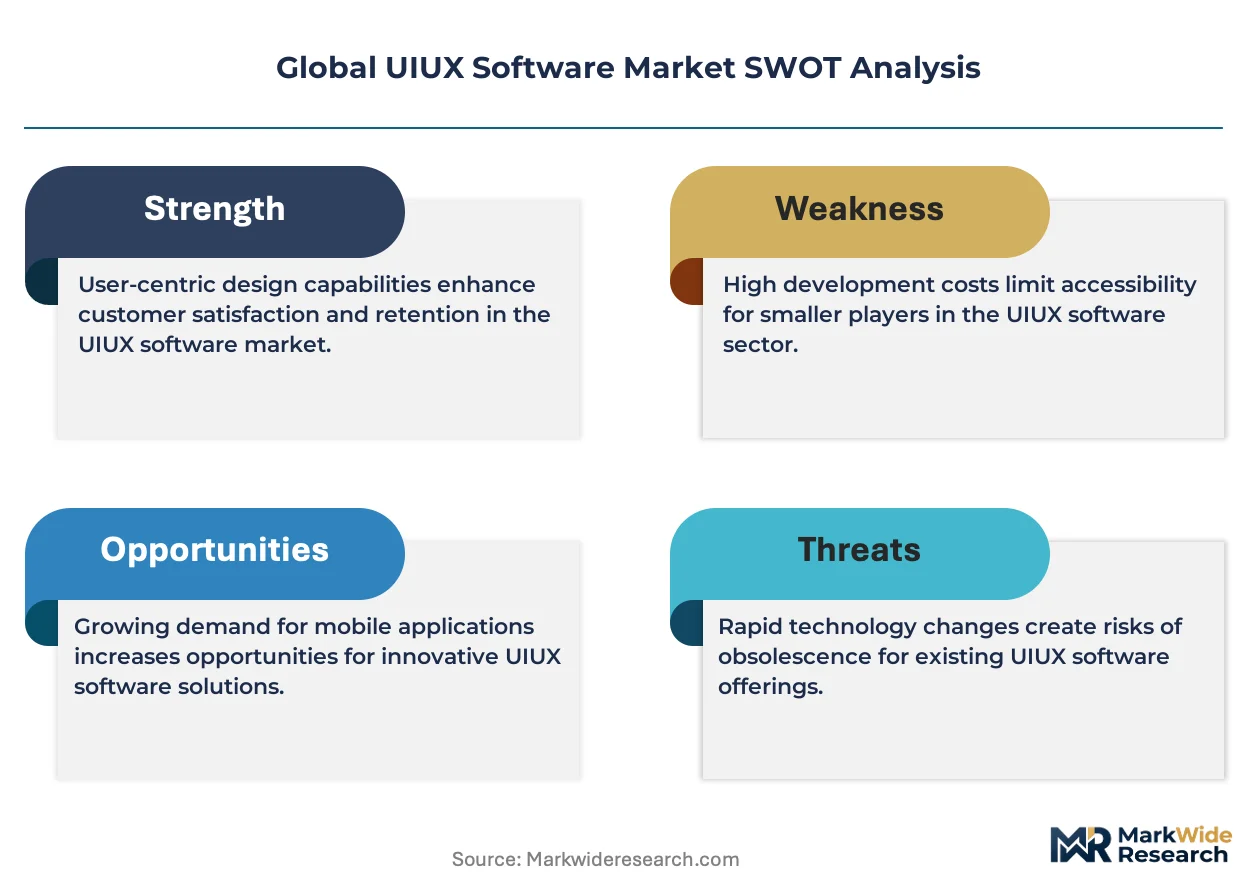
WCAG 2.1 AA accessibility certification is collapsing the vendor landscape for enterprise contracts. Adobe leverages its Creative Cloud integration to sustain platform stickiness across design workflows. Figma anchors real-time collaboration standards that competitors now struggle to match. Sketch dominates native macOS performance but navigates limited cross-platform reach.
UIUX software encompasses digital design platforms that enable interface prototyping, interaction mapping, and usability validation through vector-based rendering engines and component libraries. These tools serve product teams by translating user research into interactive specifications for development handoff. Cloud-based deployment leads solution type adoption as distributed teams require synchronous editing environments. Prototyping tools capture the fastest expansion within solution categories, driven by low-code integration demands. Enterprise software application segments concentrate margin pools where procurement cycles extend tool commitments across multi-year licenses.
FDA digital health interface guidelines, EU Web Accessibility Directive enforcement, and Japan's JIS X 8341 standards collectively elevate compliance burdens for market entry. These frameworks force vendors to embed accessibility auditing natively rather than bolt on aftermarket features. Stakeholders must monitor how generative AI capabilities reshape skill requirements and procurement criteria for design tooling investments.
Market Dynamics
WCAG 2.1 AA certification mandates from enterprise procurement teams are compressing vendor eligibility and forcing accessibility auditing into native product architecture rather than aftermarket add-ons.
Growth Catalysts
- EU Web Accessibility Directive enforcement:Public sector software procurement in member states now requires verifiable conformance, expanding addressable market for compliant vendors.
- Low-code integration demands:Product teams require prototyping tools that export directly to production-ready components, accelerating replacement of static design workflows.
- Japan's JIS X 8341 standards:Corporate and government digital interface procurement in Tokyo and Osaka clusters elevates certification requirements for market entry.
Market Restraints
- Cloud infrastructure concentration:Real-time collaboration features depend on AWS, Azure, and Google Cloud regions, creating single-point vulnerability for synchronous editing services.
- macOS hardware dependency:Vector rendering performance optimization for Apple Silicon limits cross-platform parity and expands total cost of ownership for heterogeneous device fleets.
- FDA digital health interface guidelines:Medical device software design tools face extended validation timelines and documentation burdens that deter generalist vendors.
Strategic Opportunities
- Generative AI convergence with design systems:Automated component generation from natural language prompts opens whitespace for vendors embedding large language models natively.
- Germany's BFSG accessibility implementation:Federal and state-level digital service mandates create procurement windows for WCAG-certified solutions through 2025 enforcement deadlines.
- Design-to-code automation:Emerging developer handoff protocols that eliminate manual specification translation capture budget from separate documentation tooling.
Industry Challenges
- Accessibility engineering talent scarcity:Native WCAG auditing implementation requires specialized engineers familiar with screen reader interaction patterns and cognitive load metrics.
- Multi-year procurement cycle compression:Enterprise software teams demand pilot-to-deployment timelines under 90 days, straining traditional vendor onboarding and customization revenue models.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global UIUX Software Market |
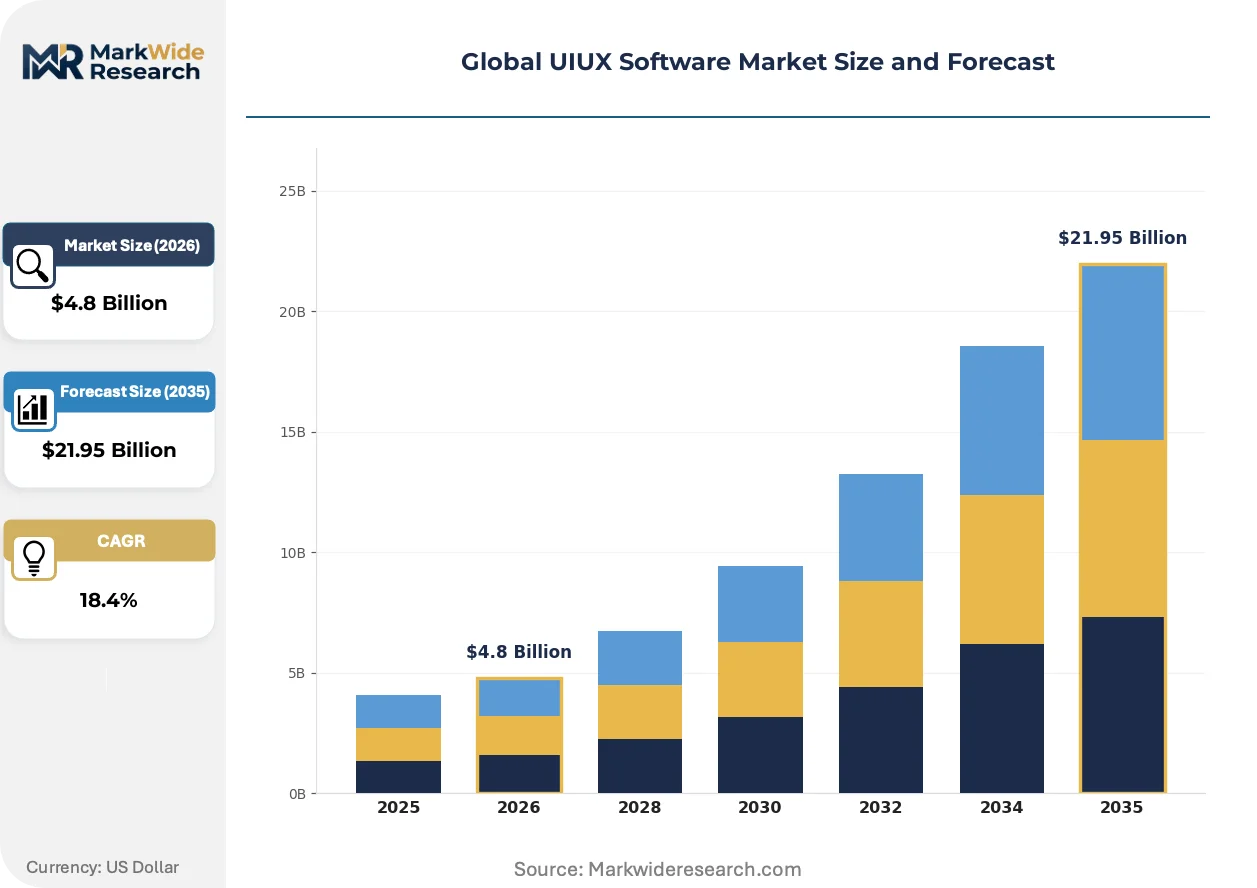
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $21.95 Billion |
| CAGR (2026 – 2036) | 18.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: Cloud-Based, On-Premises, Hybrid, Web-Based, Desktop Solution Type: Prototyping Tools, Wireframing Tools, User Testing Platforms, Collaboration Software, Design Systems Application: Mobile App Design, Website Design, Enterprise Software, E-commerce Platforms, Gaming Interfaces End User: Startups, Digital Agencies, Freelancers, Large Enterprises, Educational Institutions |
| Companies Covered | Figma, Adobe, InVision Studio, Sketch, Webflow, Lucidchart, Axure, Balsamiq, Bubble, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global UIUX Software Market Shifts & Advancements
Generative capabilities are restructuring how design specifications translate into production assets, compressing traditional handoff workflows and redefining skill requirements for product teams.
Component-based design systems are decomposing monolithic prototyping into modular, API-driven asset libraries. Enterprise product organizations in financial services and healthcare are mandating these architectures for brand consistency at scale. This decomposition is collapsing the boundary between design and development tooling, forcing vendors to embed runtime validation or cede integration revenue to adjacent categories.
Japan's METI has issued supplementary guidance interpreting JIS X 8341 for software-as-a-service interfaces, requiring annual third-party certification for public sector contracts. Japanese electronics and automotive manufacturers are extending these requirements to supplier ecosystems. Vendors without Tokyo-based compliance documentation are losing RFP eligibility across keiretsu procurement networks.
Subscription fatigue among mid-market product teams is fragmentizing purchasing authority toward departmental credit-card thresholds below central IT procurement. Design tool spending is shifting from enterprise-wide agreements to team-level purchasing with monthly cancellation flexibility. This pattern is most pronounced in United States SaaS-heavy technology clusters where headcount volatility discourages multi-year commitments.
Global UIUX Software Market Segmentation
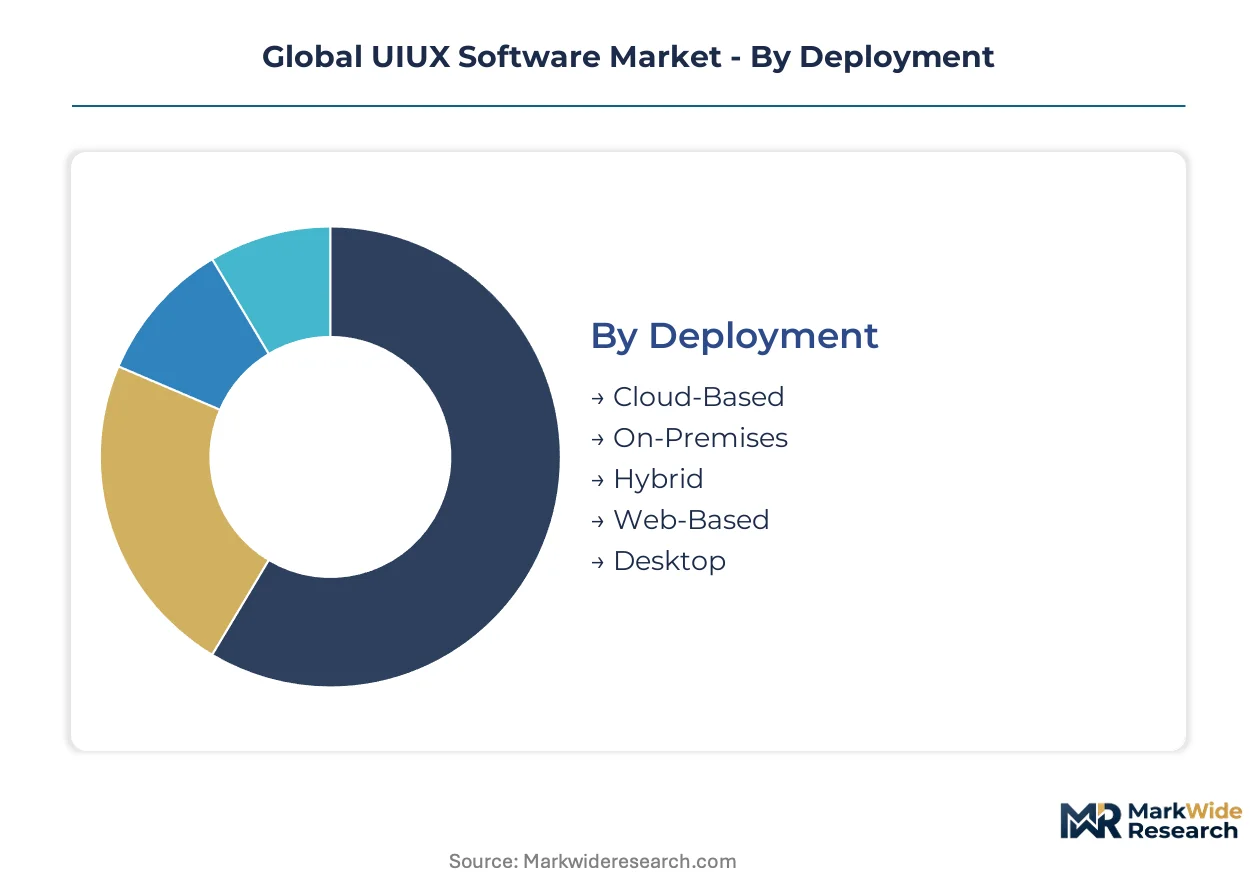
Deployment architecture and solution specialization determine vendor positioning in enterprise procurement cycles. Procurement teams weight accessibility certification, collaboration latency, and integration depth differently across segment boundaries.
Deployment:
Margin pools concentrate where synchronous editing demands intersect with enterprise security requirements.
- Cloud-Based:Multi-tenant architectures with regional edge deployment support real-time vector rendering for distributed product teams. Demand clusters in United States SaaS technology corridors and Germany's federal digital service procurement windows, driven by EU Web Accessibility Directive enforcement timelines.
- On-Premises:Air-gapped installations with localized component libraries serve defense contractors and financial institutions with data sovereignty mandates. Japan's electronics keiretsu networks and German automotive suppliers favor this architecture for intellectual property protection.
- Hybrid:Split workflows between cloud collaboration and local rendering balance accessibility with compliance.
- Web-Based:Browser-native execution eliminates client installation friction for ad-hoc stakeholder reviews.
- Desktop:Native Apple Silicon optimization delivers superior vector performance for individual designers.
Cloud-Based deployment holds the dominant share, while Hybrid configurations are gaining share fastest among regulated industries.
Solution Type:
Application breadth separates platform vendors from point solution specialists in procurement evaluations.
- Prototyping Tools:Interactive specification environments with component-to-code export capabilities compress developer handoff timelines. United States technology startups and Germany's BFSG-mandated public sector projects drive replacement of static mockup workflows.
- Design Systems:Centralized token management and version-controlled component libraries enforce brand consistency across product portfolios. Financial services institutions in New York and London mandate these architectures for multi-product governance.
- Wireframing Tools:Low-fidelity layout validation for early-stage concept testing.
- User Testing Platforms:Integrated analytics for task completion and heat mapping.
- Collaboration Software:Comment threading and approval routing for stakeholder alignment.
Prototyping Tools command the largest revenue pool, with Design Systems expanding most quickly as enterprises consolidate tooling sprawl.
Application:
Interface complexity and regulatory exposure shape solution requirements and pricing tolerance.
- Mobile App Design:Native iOS and Android component libraries with gesture interaction mapping support platform-specific human interface guidelines. Demand concentrates in San Francisco Bay Area consumer technology and Tokyo mobile gaming studios facing JIS X 8341 certification requirements.
- Enterprise Software:Complex data visualization and workflow configuration interfaces require accessibility auditing for Section 508 and WCAG 2.1 AA conformance. Procurement cycles extend across multi-year licenses with embedded professional services.
- Website Design:Responsive breakpoint management for marketing and content properties.
- E-commerce Platforms:Conversion-optimized checkout flows and personalization integration.
- Gaming Interfaces:HUD element design and controller input mapping for immersive experiences.
Enterprise Software captures the highest contract values, though Mobile App Design is climbing the fastest as super-app ecosystems proliferate.
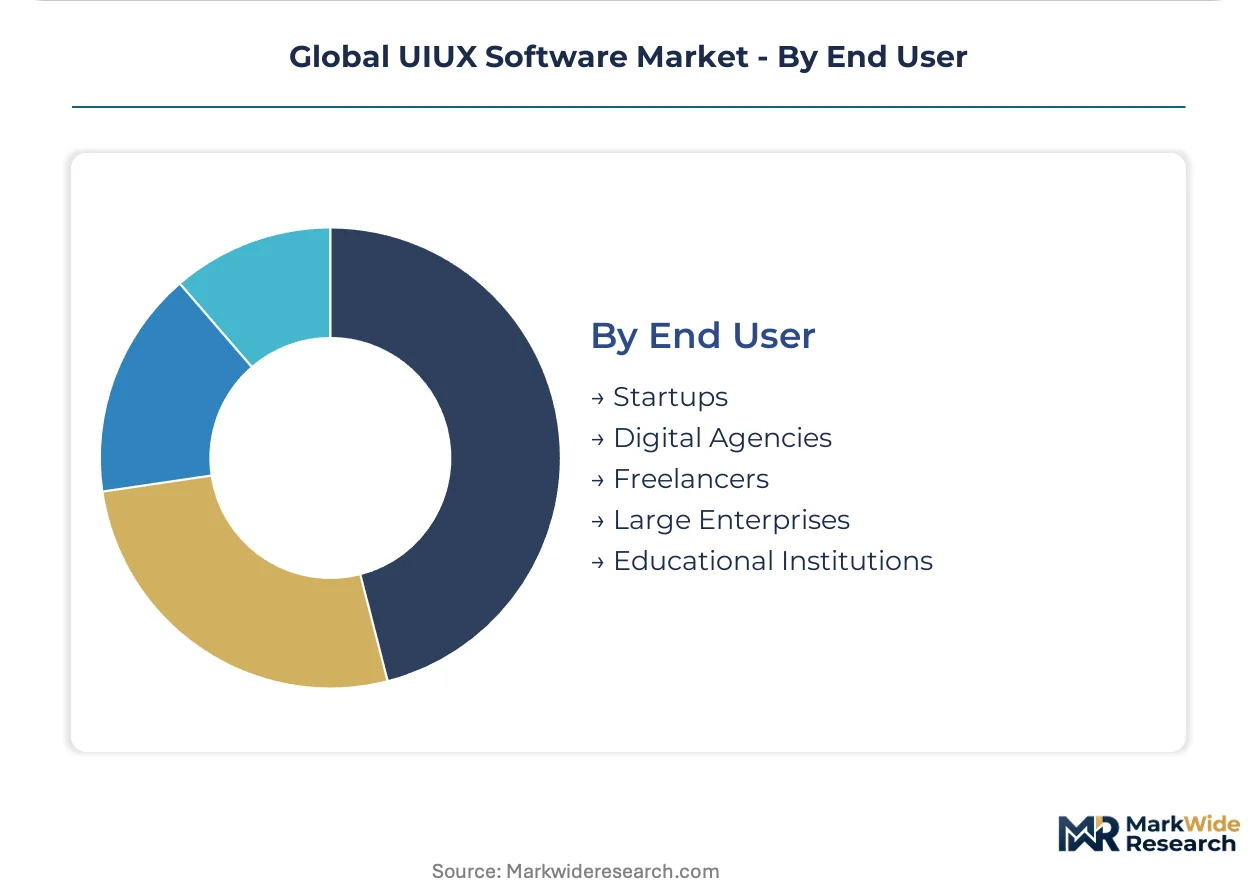
End User:
Purchasing authority fragmentation creates parallel sales motions with divergent contract structures.
- Large Enterprises:Centralized procurement with mandatory WCAG 2.1 AA certification, multi-year commitments, and security audit requirements. Germany's federal agencies and Japan's METI-regulated manufacturers represent concentrated demand with extended validation timelines.
- Startups:Team-level credit card purchasing with monthly cancellation flexibility and API-first integration requirements. Velocity-focused product organizations in United States venture capital corridors favor rapid onboarding over feature depth.
- Digital Agencies:Project-based licensing with client-specific compliance documentation.
- Freelancers:Individual subscriptions with cross-platform portability.
- Educational Institutions:Volume licensing for curriculum integration and student skill development.
Large Enterprises dominate absolute spending, while Startups are expanding their aggregate share fastest through departmental purchasing fragmentation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Enterprise software procurement teams in the United States, Germany, and Japan concentrate the highest contract values for WCAG 2.1 AA-certified design tooling. Cloud deployment demand clusters around SaaS technology corridors and federal digital service mandates.
United States
FDA digital health interface guidelines and Section 508 procurement rules shape vendor eligibility for enterprise contracts. San Francisco Bay Area technology startups and New York financial services institutions drive replacement of static design workflows with prototyping tools. West Coast venture capital corridors favor rapid onboarding over multi-year commitments.
Germany
BFSG accessibility implementation deadlines through 2025 create procurement windows for compliant solutions. EU Web Accessibility Directive enforcement mandates verifiable conformance for public sector software procurement. Berlin and Munich federal agencies extend validation timelines across multi-year licenses.
Japan
METI supplementary guidance interpreting JIS X 8341 for SaaS interfaces requires annual third-party certification. Tokyo and Osaka electronics keiretsu networks extend requirements to supplier ecosystems. Automotive manufacturers in Nagoya clusters demand Tokyo-based compliance documentation for RFP eligibility.
United Kingdom
Public sector digital service standards align procurement with WCAG 2.1 AA conformance requirements. London financial services institutions mandate component-based design systems for multi-product governance. Southeast technology corridors concentrate demand for cloud-based collaboration platforms.
South Korea
Seoul Capital Area mobile gaming studios and consumer technology developers drive native iOS and Android component library adoption. National disability rights frameworks elevate interface accessibility requirements for government digital services. Pangyo Techno Valley clusters concentrate startup demand for rapid-deployment prototyping tools.
Global UIUX Software Market Competitive Landscape
Player mix skews toward cloud-native collaboration platforms with embedded accessibility auditing capabilities. Market structure consolidates around vendors offering synchronous editing and design-to-code automation. Strategic archetypes include integrated creative suites, real-time collaboration specialists, and component-system platforms. Dominant competitive moves encompass generative AI feature integration and WCAG certification acceleration.
Within the cloud-native tier, Figma and Adobe occupy positions as archetype anchors for real-time collaboration and creative suite integration respectively. Sketch exemplifies native performance optimization for specific hardware ecosystems. Webflow represents the emerging design-to-code automation vector where visual development environments compress traditional handoff workflows. These three companies collectively illustrate how vendor positioning stratifies across collaboration depth, platform breadth, and output automation capabilities.
| Leading Market Players |
|---|
| Figma |
| Adobe |
| InVision Studio |
| Sketch |
| Webflow |
| Lucidchart |
| Axure |
| Balsamiq |
| Bubble |
| Others |
Supply & Pricing Matrix
WCAG 2.1 AA certification mandates from enterprise procurement teams gate both vendor qualification and price differentiation simultaneously, compressing supply eligibility while stratifying contract values across compliance tiers. United States federal agencies and German federal digital service windows enforce these standards through multi-year procurement cycles that reward certified vendors with pricing power over uncertified competitors.
Pricing Analysis
Multi-year enterprise licensing contracts with annual indexation to cloud infrastructure costs dominate the market, separating premium-tier accessibility-certified platforms from standard-tier collaboration tools and economy-tier wireframing utilities. Price differentiation rests on native WCAG auditing depth and real-time collaboration latency guarantees, with procurement teams in Japan's METI-regulated sectors showing lowest price sensitivity due to compliance-driven vendor lock-in. Cost compression in mid-market team subscriptions is intensifying because departmental credit-card purchasing fragments volume leverage.
Supply Chain Analysis
The United States, Germany, and Japan anchor cloud infrastructure deployment for synchronous editing services, with regional edge nodes feeding from AWS, Azure, and Google Cloud data centers. Vector rendering engines and component library architectures draw from specialized accessibility engineering talent pools concentrated in San Francisco Bay Area, Berlin, and Tokyo technology corridors. Single-source vulnerability in hyperscaler regions creates supply chain risk for real-time collaboration uptime. Distribution runs through direct enterprise sales teams and self-service web portals with API-first integration protocols.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Native accessibility engineering expertise functions as the critical scarce capability in this market, with vendors embedding WCAG auditing architectures commanding procurement preference over bolt-on compliance alternatives. Product teams, procurement officers, and compliance auditors all face talent gaps that reshape competitive positioning.
For Market Incumbents: Consolidate platform stickiness through deeper Creative Cloud or design-system integration that raises switching costs for enterprise accounts facing 90-day pilot-to-deployment mandates. Acquire specialized accessibility engineering teams to accelerate native WCAG auditing capabilities before Germany's BFSG enforcement deadlines close procurement windows to uncertified vendors. For New Entrants and Emerging Players: Design-to-code automation layers where incumbent prototyping tools force manual developer handoff represent the most penetrable service gap. Target United States venture-backed startups with monthly-cancelable subscriptions and generative AI component generation features that compress specification-to-production timelines. Lead with API-first integration protocols that bypass incumbent onboarding friction. For Investors and Strategic Acquirers: Germany's BFSG accessibility implementation through 2025 reshapes the acquisition landscape toward WCAG-certified component-system platforms with federal procurement relationships. Vendors with Tokyo-based JIS X 8341 documentation and keiretsu network access represent durable 5-10 year holdings. Monitor annual third-party certification renewal rates as the signal indicating compliance moat sustainability.| Strategic Initiative | Industry Significance |
|---|---|
| Generative AI Integration | Automated component generation from natural language prompts compresses design-to-development workflows for product teams. |
| Accessibility Certification Acceleration | Native WCAG 2.1 AA auditing architectures unlock eligibility for United States federal and German BFSG-mandated procurement windows. |
| Design-to-Code Automation | Runtime validation protocols eliminate manual specification translation, capturing budget from separate documentation tooling categories. |
| Regional Edge Deployment | Localized cloud infrastructure reduces collaboration latency for distributed teams in Tokyo, Berlin, and San Francisco clusters. |
| Component System Platformization | API-driven asset libraries enforce brand consistency across multi-product portfolios for New York and London financial services institutions. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with enterprise UX directors, IT procurement officers, platform engineers, and accessibility compliance leads. Secondary validation drew from SEC filings, hyperscaler capex disclosures, App Annie usage data, and EU public procurement databases. Bottom-up segment sizing and top-down market triangulation reconciled deployment model, solution type, and end-user organization scale across the analysis window.
Across the projection horizon, the analytical framework modeled cloud versus on-premises deployment architectures, prototyping versus design systems solution categories, and large enterprise versus startup purchasing authority segments. CAGRs were derived from regression analysis against software-as-a-service adoption curves and accessibility regulation enforcement timelines. Integration complexity tiers and regional procurement pattern differentials served as industry-specific forecast inputs.
Forecasts assume regulatory continuity in WCAG 2.1 AA, EU Web Accessibility Directive, and JIS X 8341 enforcement regimes; material policy shifts would require re-modeling vendor eligibility and addressable market boundaries. Generative AI capability maturation and accessibility engineering talent availability represent specific risk factors that could revise growth trajectories. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
CAM Software Market
Software & Services
Website Builder Tool Market
Software & Services
Radio Propagation Software Market
Software & Services
Digital Illustration App Market
Software & Services
Global Professional Service Automation (PSA) Software Market
Software & Services
Sports Facility Scheduling and Management Software Market
Software & Services
Virtual Studio Software Market
Software & Services
Digital Customer Onboarding Software Market
Software & Services
Anti-Plagiarism for the Education Sector Market
Software & Services
Global Web Scraper Software Market
Software & Services
Computational Medicine and Drug Discovery Software Market
Software & Services
Online Paint Editor App Market
Software & Services
Aviation Software Market
Software & Services
Entity Management Software Market
Software & Services
Voice to Text on Mobile Devices Market
Software & Services
Apache Spark Market