
 Parks and Playground Inspection Software Market | 2026-2036
Parks and Playground Inspection Software Market Size, Share, and Industry Trends Forecast 2026-2036
Parks and Playground Inspection Software Market Insights
Municipal park departments is recalibrating inspection workflows as liability pressures mount across public recreation systems. The Play Inspection Company leverages decades of playground safety expertise to anchor its software credibility with UK local authorities. ParkZapp competes through mobile-first field tools designed for rapid defect documentation. Playground Guardian differentiates by combining inspection software with certified training programs for park maintenance crews.
Parks and Playground Inspection Software encompasses digital platforms that schedule, execute, document, and archive safety audits of recreational equipment and surfacing against injury-prevention protocols. Core functionality requires offline-capable mobile data capture, photographic geotagging, and automated hazard-ranking algorithms that flag critical failures for immediate remediation. Cloud-Based deployment leads adoption among municipalities seeking centralized multi-site oversight without server infrastructure. Automated Reporting features command premium positioning as litigation-ready documentation becomes standard procurement criteria. Hybrid Solutions show fastest expansion where rural districts with intermittent connectivity demand synchronized field-to-office workflows.
ASTM International publishes F1487 equipment safety standards that directly shape software checklist architectures and failure classification hierarchies. The U.S. Consumer Product Safety Commission maintains playground safety handbook guidelines that drive incident management module requirements across North American vendors. ISO 31000 risk management principles increasingly influence enterprise procurement specifications for multi-national park operators. Stakeholders must monitor how evolving surfacing impact attenuation testing protocols will force recalibration of inspection frequency algorithms and sensor integration roadmaps.
Market Dynamics
Liability litigation against municipal park departments is accelerating software procurement as injury claims drive demand for litigation-ready documentation systems. ASTM F1487 compliance mandates now require digital audit trails that paper-based inspections cannot satisfy.
Growth Catalysts
- ASTM F1487 Standard:Equipment safety protocols mandate standardized checklists that only specialized software platforms can automate. Municipalities face penalties for non-compliance.
- Mobile Field Capture:Offline-capable smartphone documentation eliminates paper delays and accelerates hazard reporting from remote playground sites.
- Surfacing Impact Testing:New attenuation measurement requirements force inspection frequency increases that manual scheduling cannot accommodate.
Market Restraints
- Budget Cycles:Municipal procurement operates on annual appropriations that delay multi-year software licensing commitments.
- Rural Connectivity Gaps:Intermittent cellular coverage in exurban districts limits real-time cloud synchronization for field inspectors.
- Legacy Asset Registers:Incomplete equipment inventories force expensive pre-implementation data cleansing projects.
Strategic Opportunities
- Sensor Integration:IoT wear measurement devices converging with inspection platforms enable predictive maintenance scheduling before failures occur.
- Insurance Underwriting:Carriers are mandating certified digital inspection records for municipal liability policy renewals.
- Training Bundles:Certified playground safety courses attached to software subscriptions create recurring revenue streams.
Industry Challenges
- Inspector Certification Bottlenecks:National Recreation and Park Association credentialing backlogs delay qualified staff deployment.
- Multi-System Integration:Work order management platforms require custom API development to connect with existing municipal ERP systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Parks and Playground Inspection Software Market |
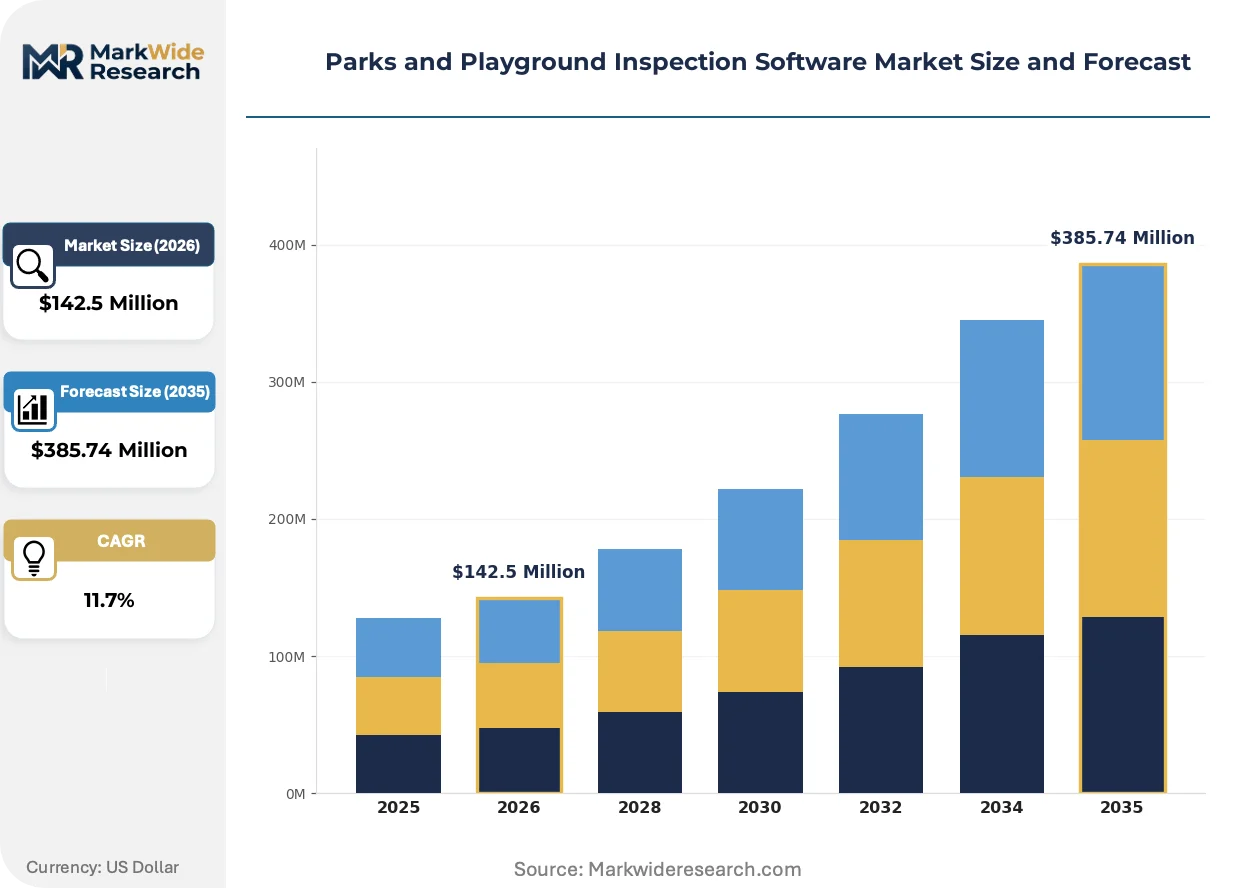
| Market Size in 2026 | $142.5 Million |
| Market Size in 2035 | $385.74 Million |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Mobile Apps, Web-Based Solutions, Hybrid Solutions, Inspection Tools End User: Municipalities, Private Parks, Schools, Inspection Agencies Deployment: Cloud-Based, On-Premise, SaaS, Platform as a Service Feature: Automated Reporting, Compliance Tracking, Incident Management, User Feedback |
| Companies Covered | The Play Inspection Company, RoSPA Play Safety, ParkZapp, MCS, Playmapping, Playground Guardian, Playmaintain, OpenGov, CityReporter, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Parks and Playground Inspection Software Market Trends and Innovations
Computer vision and automated hazard detection are redefining how playground safety audits are executed and validated. Vendors are racing to embed machine learning models that reduce inspector subjectivity.
Computer vision algorithms trained on ASTM F1487 failure patterns are expanding into mobile inspection workflows. Large municipal park departments in California and Texas are piloting automated image recognition for entrapment hazard detection. This capability is compressing inspection cycle times while standardizing defect classification across distributed maintenance crews.
The U.S. Consumer Product Safety Commission is tightening surfacing depth requirements under updated playground safety handbook guidelines. Software vendors must recalibrate automated measurement modules to capture granular depth data at multiple test points. Park departments in Florida and Illinois are responding by requiring vendor certification against the revised protocols before contract award.
Subscription pricing for inspection platforms is displacing perpetual license models among budget-constrained municipalities. Annual recurring arrangements lower upfront capital requirements and bundle automatic standard updates. This shift is most visible in mid-sized cities across the Midwest where finance directors prioritize operational expenditure classification over capital appropriations.
Parks and Playground Inspection Software Market Segmentation
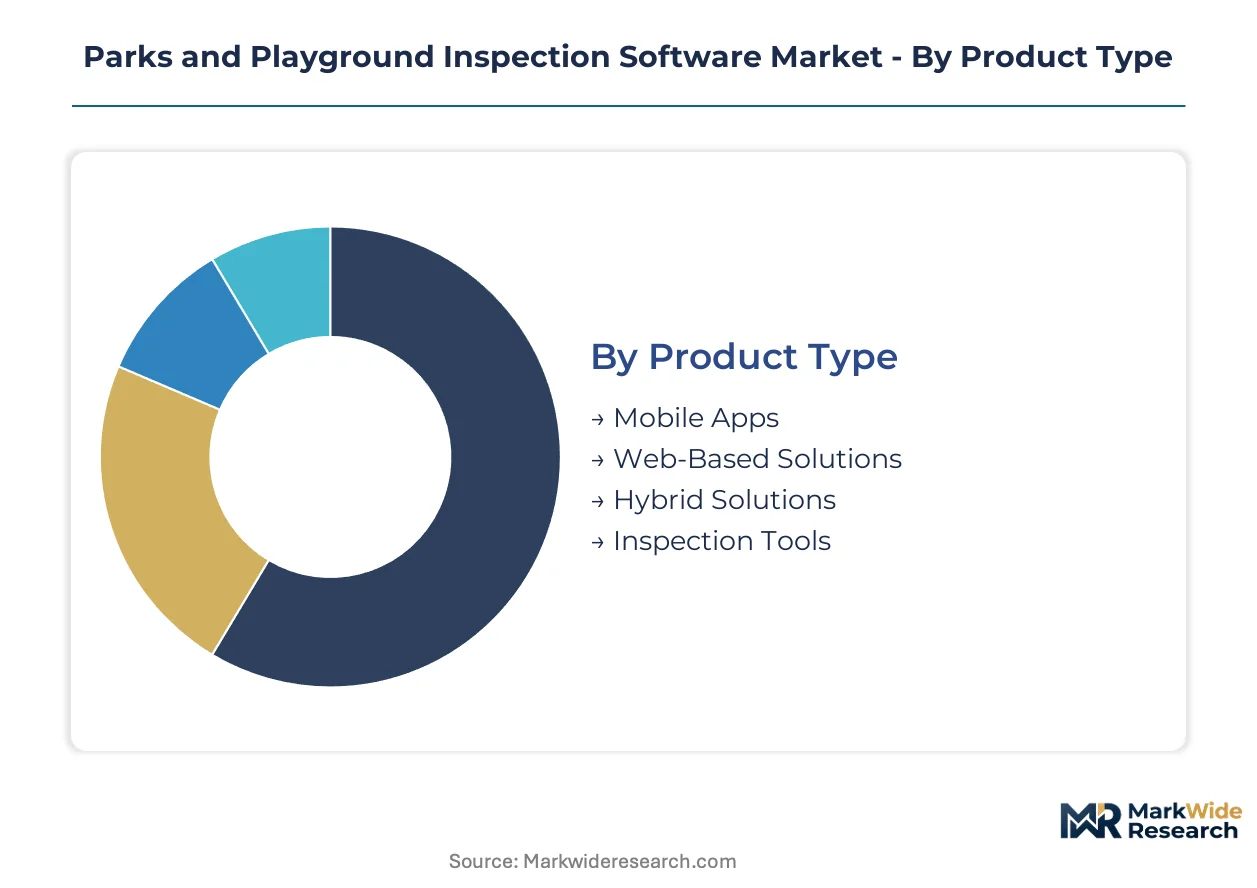
Parks and playground inspection software vendors structure offerings around four distinct axes: product architecture, customer procurement authority, infrastructure deployment, and functional capability. Each segmentation dimension carries different margin profiles and sales cycle lengths.
Product Type:
Capital intensity varies sharply across product architectures, with hybrid solutions demanding the heaviest upfront engineering investment for offline synchronization engines.
- Mobile Apps:Native iOS and Android applications prioritize field usability with offline data caching and photographic geotagging. Municipal park departments in Texas and Florida concentrate procurement here due to inspector mobility requirements.
- Web-Based Solutions:Browser-centric platforms deliver centralized dashboard access for administrative oversight and multi-site aggregation. Demand clusters among mid-sized municipalities seeking lower total cost of ownership without mobile complexity.
- Hybrid Solutions:Dual-mode architectures synchronize field-captured data through intermittent connectivity to cloud backends. Rural districts across the American Midwest drive adoption where cellular coverage gaps prevent pure cloud dependency.
- Inspection Tools:Hardware-integrated modules combining software with calibrated measurement devices for surfacing depth and impact attenuation testing.
Hybrid Solutions absorb the bulk of installed capacity; Mobile Apps are expanding most quickly.
End User:
Customer type determines pricing elasticity and contract structure, with inspection agencies commanding the longest evaluation cycles due to multi-client certification requirements.
- Municipalities:City and county park departments constitute the core revenue base, driven by liability exposure and ASTM F1487 compliance mandates. Procurement concentrates in the United States where litigation frequency pressures budget allocation toward documentation systems.
- Private Parks:Commercial recreation operators including campground chains and resort properties prioritize brand protection through systematic safety protocols. California and Texas private operators lead adoption among this segment.
- Schools:K-12 districts and university systems manage playground portfolios under tighter budget constraints than municipal counterparts.
- Inspection Agencies:Third-party safety certification firms require multi-tenant architectures serving diverse client bases simultaneously.
Municipalities retain the dominant share of annual contract value; Private Parks show the steepest expansion trajectory.
Deployment:
Infrastructure preference tracks IT maturity and data sovereignty posture, with cloud architectures displacing on-premise systems fastest among smaller jurisdictions lacking dedicated technical staff.
- Cloud-Based:Multi-tenant SaaS architectures eliminate server maintenance burdens and enable automatic standard updates. Municipalities under 100,000 population favor this model for operational expenditure classification.
- On-Premise:Self-hosted installations persist where data residency requirements or legacy ERP integration demands local control. State-level park systems in the American Northeast maintain this preference.
- SaaS:Subscription software models with annual recurring revenue structures lower upfront capital barriers for budget-constrained customers.
- Platform as a Service:API-centric architectures enabling custom workflow development for large municipal ERP ecosystems.
Cloud-Based deployment claims the majority of new implementations; Platform as a Service is climbing the fastest among enterprise-scale prospects.
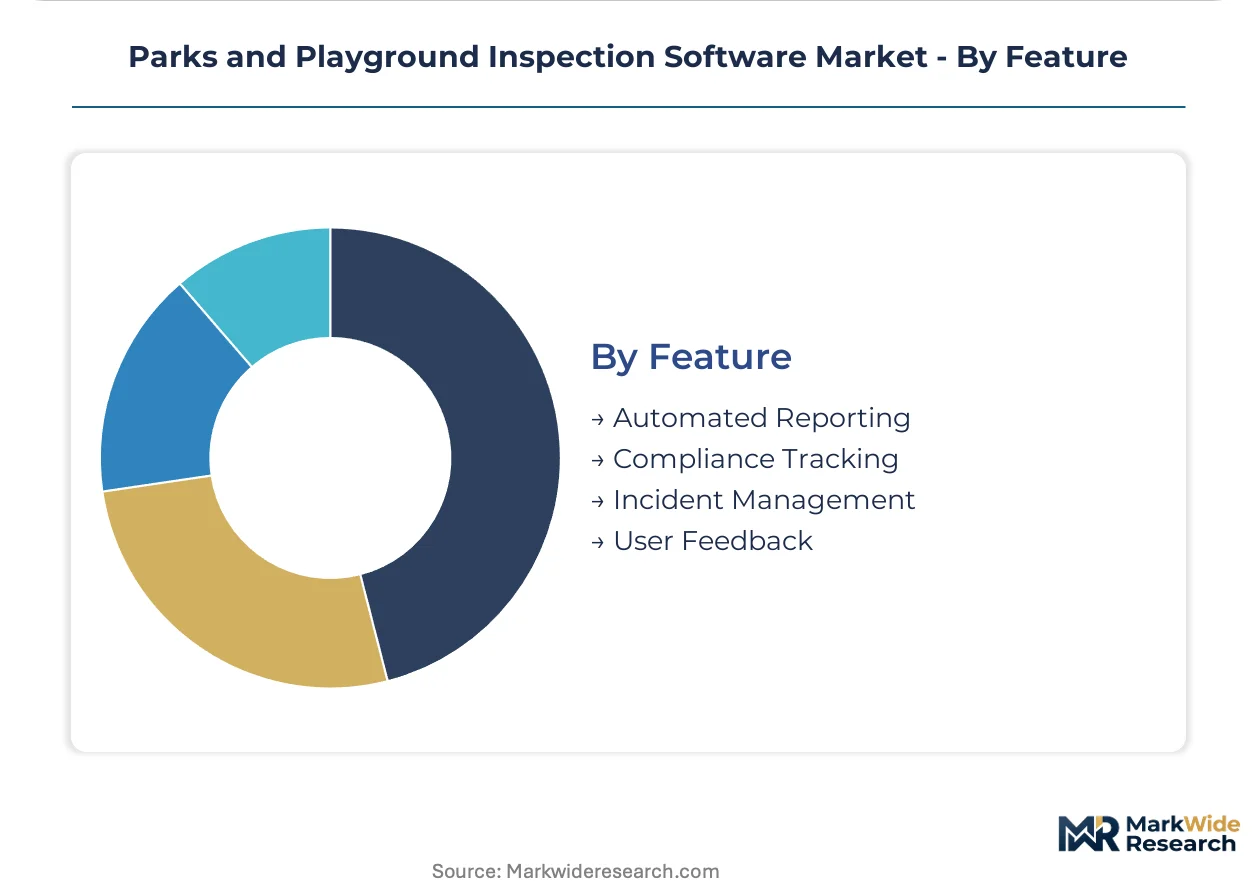
Feature:
Functional module prioritization reflects litigation preparedness versus operational efficiency tradeoffs, with automated reporting commanding premium positioning.
- Automated Reporting:Litigation-ready documentation generation with timestamped photographic evidence and standardized ASTM F1487 checklists. This capability drives premium pricing across all customer tiers.
- Compliance Tracking:Continuous monitoring against evolving CPSC playground safety handbook guidelines and state-level amendments. Florida and Illinois park departments mandate this module for contract eligibility.
- Incident Management:Structured workflows for injury documentation, witness capture, and regulatory notification.
- User Feedback:Public-facing portals enabling citizen hazard reporting with photographic submission and GPS coordinates.
Automated Reporting dominates module attachment rates; User Feedback is gaining share fastest as open-government initiatives expand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Enterprise zones in Texas and Florida accelerate municipal software procurement through property tax abatements tied to public safety technology adoption. These incentives concentrate vendor sales operations and implementation resources in Sun Belt metropolitan corridors.
United States
Liability litigation against municipal park departments drives ASTM F1487 compliance software procurement across California, Texas, and Florida. The U.S. Consumer Product Safety Commission maintains playground safety handbook guidelines that shape incident management module requirements. Dallas-Fort Worth and Houston metropolitan park systems deploy cloud-based inspection platforms for multi-site centralized oversight.
United Kingdom
Local authority budget pressures prioritize litigation-ready documentation systems for playground safety audits. The Play Inspection Company anchors software credibility with decades of playground safety expertise serving UK municipal clients. Greater London boroughs lead adoption of mobile-first inspection tools for rapid defect documentation across dispersed recreation assets.
Canada
Provincial liability frameworks in Ontario and British Columbia mandate standardized safety audit trails for public recreation facilities. Health Canada guidelines influence surfacing impact attenuation testing protocols that software platforms must accommodate. Toronto and Vancouver park departments pilot hybrid deployment models addressing urban-rural connectivity gaps.
Australia
Council amalgamation programs in New South Wales and Victoria drive demand for centralized multi-site inspection management. Standards Australia AS 4685 playground equipment standards shape software checklist architectures for equipment safety protocols. Sydney and Melbourne metropolitan councils prioritize automated reporting modules for litigation preparedness.
Germany
Municipal insurance carriers mandate certified digital inspection records for playground liability policy renewals in Bavaria and North Rhine-Westphalia. DIN EN 1176 playground equipment standards influence failure classification hierarchies embedded in audit software. Munich and Cologne park administrations evaluate sensor-integrated inspection platforms for predictive maintenance scheduling.
Parks and Playground Inspection Software Market Competitive Landscape
Top-tier vendors anchor municipal procurement channels, while mid-tier specialists compete through training bundling and mobile-first differentiation. The vendor base organizes around three strategic archetypes: safety-certification bodies extending into software, pure-play SaaS developers prioritizing field usability, and government technology platforms broadening into recreation asset management. Dominant competitive moves include geographic expansion into English-speaking Commonwealth markets and strategic partnerships with municipal insurance underwriters.
Within the safety-certification archetype, The Play Inspection Company and RoSPA Play Safety represent UK-based specialists leveraging decades of playground safety expertise to anchor software credibility with local authorities. ParkZapp occupies a position among mobile-native developers prioritizing rapid defect documentation for field inspectors. Playground Guardian exemplifies the training-bundle approach, combining inspection platforms with certified crew education programs to create recurring revenue streams.
| Leading Market Players |
|---|
| The Play Inspection Company |
| RoSPA Play Safety |
| ParkZapp |
| MCS |
| Playmapping |
| Playground Guardian |
| Playmaintain |
| OpenGov |
| CityReporter |
| Others |
Pricing and Supply Chain Analysis
Private-equity-rolled-up municipal software specialists concentrate supply capacity in Texas and Florida, enabling disciplined subscription pricing through consolidated sales operations and standardized implementation playbooks. Their ownership structure prioritizes recurring revenue predictability, feeding pricing rigidity that resists discounting even as budget-constrained rural districts demand flexible procurement terms.
Pricing Analysis
Short lead-time deployments command premium positioning in municipal procurement cycles, while extended implementation timelines unlock standard-tier discounts for patient buyers. Pricing stratifies across premium, standard, and economy tiers anchored to compliance certification depth and after-sales training bundling. Cost compression in the economy tier is intensifying because open-source alternatives and low-code platforms erode entry-level margins. School districts exhibit the sharpest price sensitivity due to capital expenditure constraints, whereas enterprise municipal park systems in California and Texas demonstrate inelastic demand for litigation-ready documentation modules.
Supply Chain Analysis
Reverse-logistics flows for hardware-integrated inspection tools—calibrated impact attenuation devices and wear sensors—concentrate refurbishment capacity in the United States and Germany, extending equipment lifecycles for budget-conscious municipalities. Core software development draws from engineering talent pools in the United States, United Kingdom, and Canada, with cloud infrastructure tethered to hyperscaler regions in Virginia, Frankfurt, and Sydney. Single-source vulnerability in ASTM F1487 certification content creates supply chain risk, as accredited safety expertise concentrates among a handful of playground safety institutes. Distribution runs through direct municipal sales teams and government technology aggregators like OpenGov.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
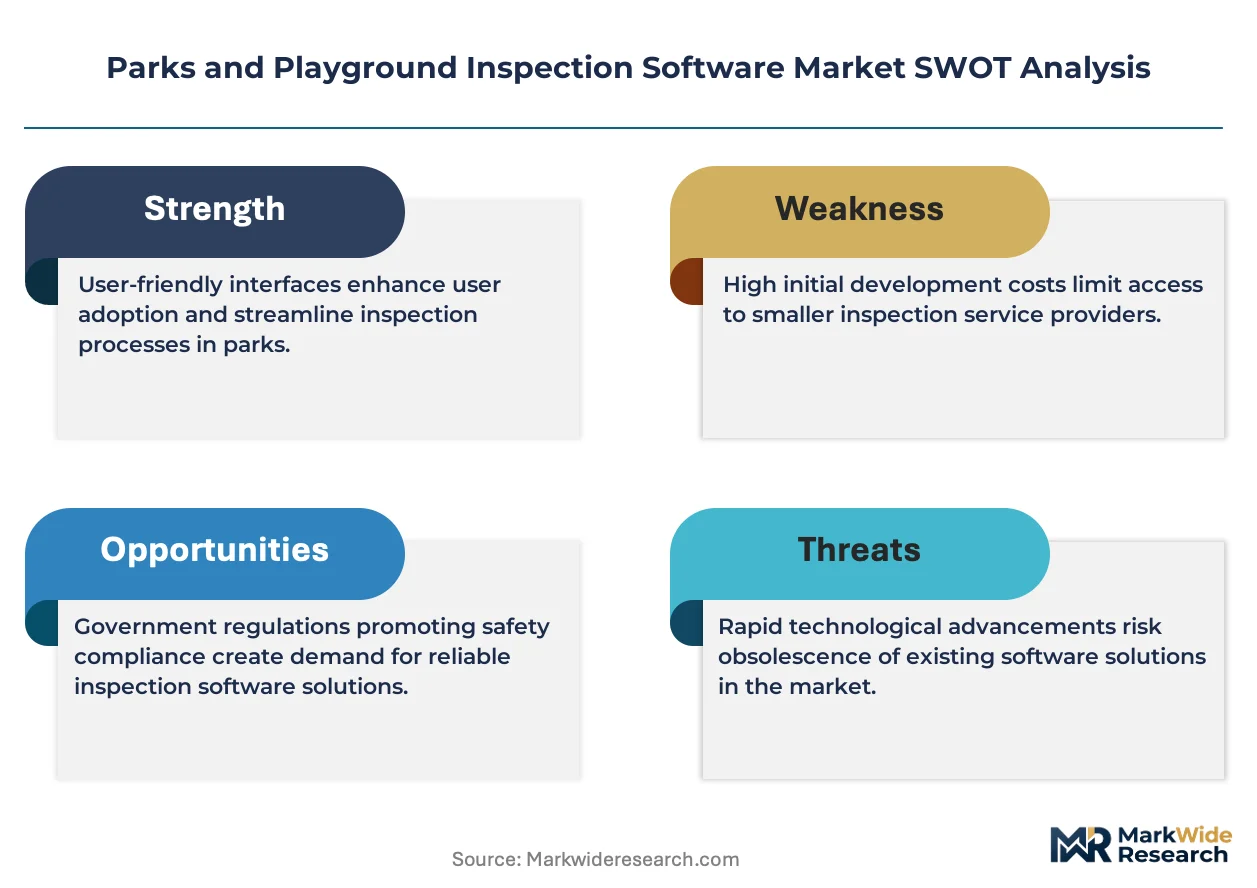
Supply-constrained certified inspector capacity props pricing power for training-integrated software bundles, as NRPA credentialing backlogs limit qualified staff deployment faster than platform expansion.
For Market Incumbents: Anchor defensive positioning through exclusive partnerships with municipal insurance underwriters mandating certified digital inspection records for liability policy renewals. Deepen backward integration into inspector certification programs to capture margin pools currently flowing to third-party training bodies. Sensor-integrated predictive maintenance modules represent the priority R&D frontier for platform differentiation against pure-play SaaS entrants. For New Entrants and Emerging Players: Rural school districts with intermittent connectivity and tight capital cycles present the most penetrable buyer archetype, underserved by incumbent cloud-first architectures. White-space targets include hybrid deployment models with offline synchronization engines and per-inspection transactional pricing that bypasses annual appropriation barriers. A channel partnership with regional education cooperatives offers the clearest go-to-market angle for bypassing entrenched municipal procurement channels. For Investors and Strategic Acquirers: Distressed-cycle entries favor mobile-native inspection tool developers in the American Midwest, where rural connectivity gaps have stalled incumbent platform adoption and created acquisition opportunities at compressed valuations. Long-term viability hinges on sensor integration roadmaps and API ecosystems enabling ERP connectivity. Watch for inflection signals in insurance underwriting mandates, as carrier requirements for certified digital inspection records will consolidate procurement authority toward compliant platform vendors.| Strategic Initiative | Industry Significance |
|---|---|
| Sensor Integration Partnership | IoT wear measurement convergence with inspection platforms enables predictive maintenance scheduling before equipment failures occur. |
| Insurance Underwriter Certification | Mandated digital inspection records for municipal liability policy renewals lock in recurring revenue through carrier-driven procurement. |
| Training Bundle Expansion | Certified playground safety courses attached to software subscriptions capture margin pools from third-party certification bodies. |
| Hybrid Deployment Architecture | Offline-capable field synchronization addresses rural connectivity gaps and expands addressable market beyond urban cloud-dependent municipalities. |
| Computer Vision Module Development | Machine learning models for automated hazard detection reduce inspector subjectivity and compress audit cycle times for large park departments. |
Research Methodology
Multi-period observation of municipal software procurement patterns, inspector certification pipeline flows, and ASTM F1487 compliance litigation outcomes anchored the trend analysis, supplemented by interviews with park department safety officers, municipal IT procurement managers, playground equipment manufacturers, and insurance underwriters specializing in public recreation liability. Secondary validation drew from CPSC playground safety handbook revisions, NRPA credentialing statistics, municipal budget appropriation records, and cloud infrastructure deployment disclosures. Bottom-up segmentation modeling triangulated against top-down market sizing from equipment installation databases and park asset inventory estimates.
Input-output matrices mapped deployment model adoption curves, feature module attachment rates, and customer tier expansion patterns across the projection horizon. Segmentation dimensions modeled include product architecture, procurement authority, infrastructure preference, and functional capability, with additional granularity on connectivity constraints and litigation exposure levels. CAGRs were derived from fitted growth curves calibrated to historical software procurement velocity and compliance mandate implementation timelines. Forecast inputs incorporated sensor technology cost trajectories and insurance underwriting requirement diffusion rates.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to surfacing impact testing protocol revisions and federal playground safety funding allocations. Forecasts reflect documented assumptions regarding municipal budget stability and inspector certification throughput capacity. Practitioners should monitor CPSC guideline amendment schedules and state-level liability law shifts for early signals of compliance-driven procurement acceleration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
Global Home Inspection Software Market
Software & Services
Global Log Management Software Market
Software & Services
Graphical User Interface (GUI) Design Software Market
Software & Services
Global Subscription Billing Software Market
Software & Services
Enterprise Data Observability Software Market
Software & Services
Global Process Mining Software Market
Software & Services
Ecommerce Inventory Management Software Market
Software & Services
Global Applicant Tracking Software Market
Software & Services
Account-Based Data Software Market
Software & Services
Global Political Campaign Software Market
Software & Services
Japan Qualitative Data Analysis Software Market
Software & Services
Freight Forwarding Software Market
Software & Services
Product Optimization Software Market
Software & Services
Augmented Reality Software Development Kit Market
Software & Services
Storyboarding Software Market
Software & Services
Test Automation Market