
 Yacht Management Software Market | 2026-2036
Yacht Management Software Market Size, Share, and Industry Trends Forecast 2026-2036
Yacht Management Software Market Analytics
ISO 27001-grade security certification is collapsing from a premium add-on into a baseline procurement requirement. Seahub leverages cloud-native architecture to sustain multi-vessel data synchronization across dispersed fleets. Voly anchors its position through deep accounting engine specialization for superyacht operations. Pelagian differentiates via maintenance tracking modules that control work-order workflows for refit yards.
Yacht management software denotes integrated digital platforms that consolidate vessel operations, technical maintenance, financial administration, and regulatory compliance through centralized databases with API connectivity to onboard IoT sensors and shore-side service networks. These systems automate flag-state reporting, crew certification tracking, and procurement workflows to reduce administrative overhead for vessel operators and management companies. Cloud-based deployment leads the architecture mix by eliminating on-premise hardware burdens for mobile fleets, while maintenance tracking captures disproportionate R&D investment due to its integration with predictive analytics and OEM parts ecosystems. Charter companies represent the fastest-growing end-user category as they demand real-time availability dashboards and guest-experience portals to compete with hotel-grade hospitality benchmarks.
The International Maritime Organization enforces carbon intensity indicator reporting that shapes software feature roadmaps toward emissions analytics modules. The EU F-Gas Regulation and REACH compliance obligations from ECHA force refrigerant tracking and hazardous materials documentation into platform core functionality. Flag administrations including the UK's MCA and Australia's AMSA mandate electronic safety management systems that accelerate digitalization mandates. Stakeholders must weigh regulatory alignment velocity against user-experience polish when selecting vendor partnerships.
Market Dynamics
The International Maritime Organization's carbon intensity indicator mandate forces software vendors to embed emissions analytics as core architecture rather than peripheral modules. Charter operators now demand real-time vessel performance dashboards that satisfy both regulatory filing obligations and guest-experience benchmarks.
Growth Catalysts
- EU MRV Regulation:Mandatory monitoring, reporting, and verification of CO2 emissions from maritime transport compels fleet operators to adopt automated data-capture platforms that streamline compliance documentation.
- Cloud-native architecture:Elimination of on-premise server infrastructure reduces capital barriers for smaller charter companies seeking centralized fleet visibility without dedicated IT departments.
- Mediterranean charter corridor:Concentrated demand from France, Italy, and Greece creates network effects where regional service-provider integration accelerates platform adoption among competing operators.
Market Restraints
- Satellite connectivity costs:Persistent high-bandwidth expenses for offshore data transmission constrain real-time IoT sensor deployment on vessels operating beyond coastal cellular range.
- Flag-state fragmentation:Divergent electronic safety management system requirements between the UK's MCA, Australia's AMSA, and other national administrations multiply certification burdens for multi-flag fleets.
- Cyber insurance premiums:ISO 27001 certification has shifted from competitive advantage to baseline requirement, yet annual audit and insurance costs disproportionately burden sub-fifty-vessel operators.
Strategic Opportunities
- Predictive maintenance convergence:Integration of OEM parts databases with machine-learning failure prediction creates recurring revenue streams through automated spare-parts procurement workflows.
- Guest-experience portals:Underdeveloped digital concierge interfaces for charter clients represent white-space functionality that platforms can monetize per-booking or per-guest.
- EU F-Gas Regulation:Mandatory refrigerant tracking and leak detection documentation opens specialized module opportunities for platforms serving superyacht refit yards.
Industry Challenges
- Maritime cybersecurity expertise:Shortage of professionals holding both seafaring certifications and information-security credentials delays secure platform deployments.
- Legacy system interoperability:Proprietary data formats from incumbent onboard equipment manufacturers obstruct API standardization and extend integration timelines.
- Crew digital literacy gaps:Heterogeneous training levels among vessel personnel impede consistent utilization of maintenance-tracking modules and safety-management workflows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Yacht Management Software Market |
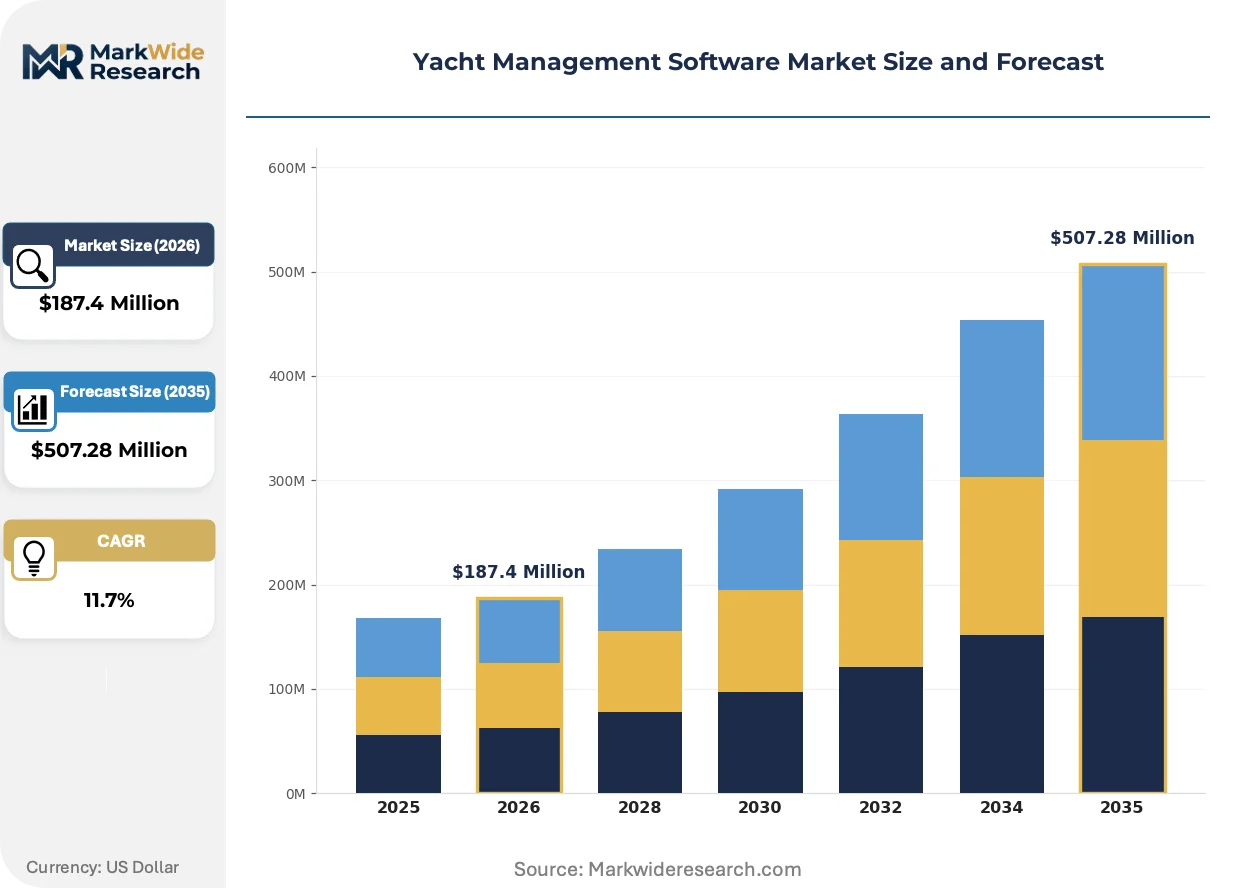
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $507.28 Million |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fleet Management, Maintenance Tracking, Accounting Solutions, Scheduling Tools End User: Private Owners, Charter Companies, Yacht Brokers, Service Providers Deployment: Cloud-Based, On-Premise, Hybrid, Mobile Application Feature: Inventory Management, Reporting Tools, Compliance Tracking, Customer Portal |
| Companies Covered | Shipshape, Seahub, Voly, Pelagian, YachtWyse, Quaynote, Southware Yacht Management, Vessel Vanguard, WinMK, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Yacht Management Software Market Evolving Landscape
Software architecture is bifurcating between lightweight charter-focused platforms and heavy asset-management systems for superyacht fleets. This divergence reflects divergent buyer priorities: operational agility versus regulatory depth.
IoT sensor integration is bifurcating the vendor landscape. Onboard equipment manufacturers now embed proprietary data streams that platform vendors must license or reverse-engineer. Charter operators adopt these integrated stacks fastest, accepting vendor lock-in for reduced deployment friction. The structural consequence compresses standalone hardware-agnostic platforms into niche retrofit markets.
REACH compliance obligations from ECHA force hazardous materials documentation into platform core functionality. Chemical inventory tracking for paints, solvents, and cleaning agents now requires lot-number traceability from purchase through disposal. Superyacht management companies serving EU-flagged vessels face the steepest adaptation curves, accelerating procurement of specialized environmental modules.
Buyer preference is compressing software evaluation cycles. Charter company procurement teams now pilot platforms during single-season contracts rather than multi-year commitments. This behavioral shift rewards vendors with rapid onboarding protocols and modular pricing that aligns with Mediterranean seasonal patterns. The trend concentrates in the France-Italy-Greece corridor where charter density enables competitive benchmarking.
Yacht Management Software Market Segmentation
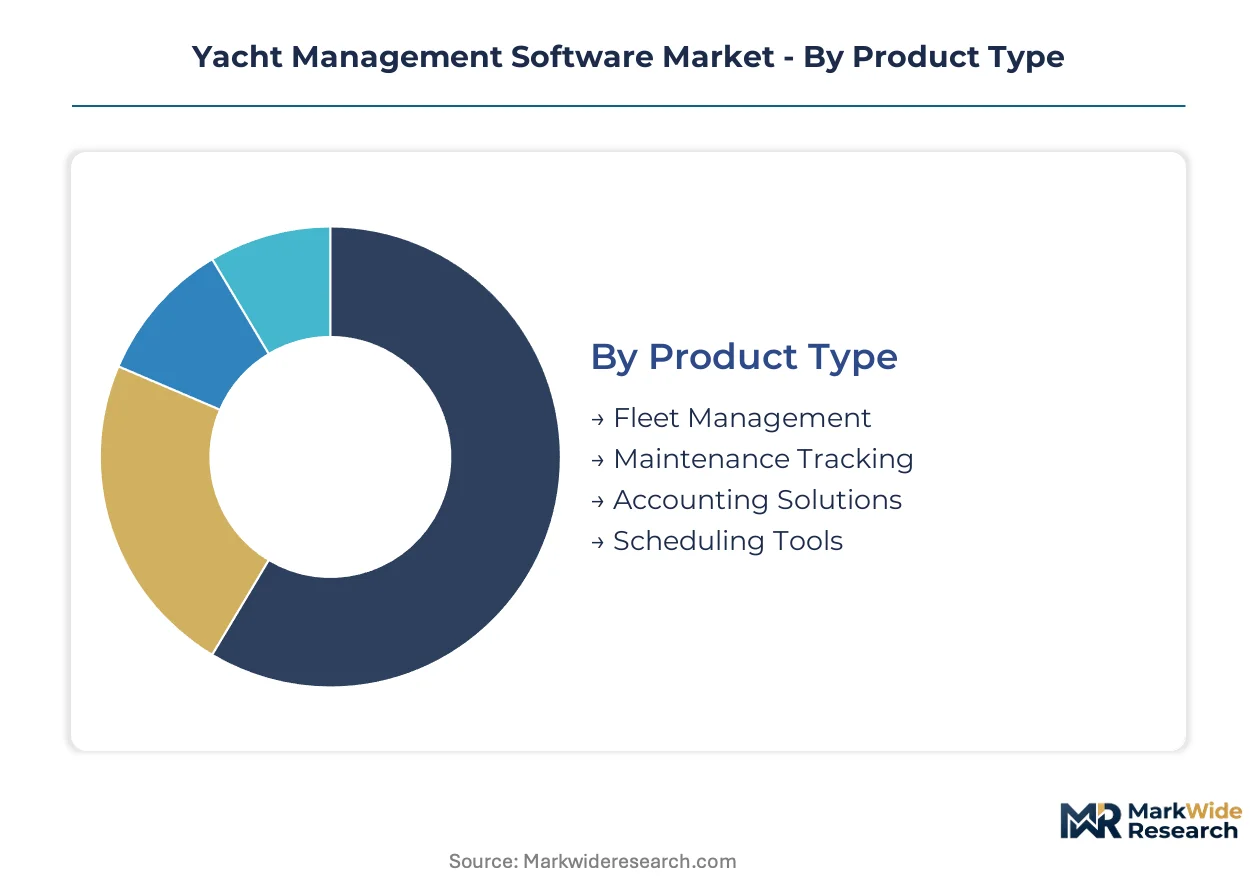
Segmentation in yacht management software reflects divergent operational priorities across vessel scale and regulatory exposure. Procurement patterns split between integrated suites for multi-vessel operators and modular point solutions for single-yacht owners.
Product Type:
Fleet Management and Maintenance Tracking flow through direct enterprise sales channels with extended implementation cycles, while Accounting Solutions and Scheduling Tools increasingly distribute through SaaS marketplaces and partner networks.
- Fleet Management:Centralized dashboards aggregate vessel telemetry, crew scheduling, and regulatory documentation across dispersed fleets. Demand concentrates among Mediterranean charter operators in France, Italy, and Greece seeking unified visibility across seasonal rotations. The EU MRV regulation accelerates procurement as operators automate emissions reporting workflows.
- Maintenance Tracking:Work-order orchestration modules integrate with OEM parts databases and predictive analytics engines. Superyacht management companies in the France-Italy-Greece corridor drive adoption as refit yards demand digital audit trails for warranty claims and class society inspections.
- Accounting Solutions:Specialized ledgers handle multi-currency vessel operating accounts, crew payroll across flag states, and charter revenue recognition.
- Scheduling Tools:Charter availability calendars and guest itinerary coordination for hospitality-grade service delivery.
Fleet Management dominates installed base. Maintenance Tracking is where expansion concentrates.
End User:
Cost tier differentiation separates enterprise-grade platforms for Charter Companies from lightweight subscriptions for Private Owners, with Yacht Brokers and Service Providers occupying mid-market pricing bands.
- Charter Companies:Real-time availability engines and guest-experience portals compete with hotel-grade hospitality benchmarks. Operators across the Mediterranean corridor in France, Italy, and Greece adopt fastest due to competitive density and seasonal contract flexibility.
- Private Owners:Simplified mobile interfaces for single-vessel administration with reduced feature depth and lower subscription thresholds.
- Yacht Brokers:Transaction facilitation tools linking vessel specifications with buyer qualification workflows and documentation exchange.
- Service Providers:Subcontractor coordination modules for refit yards, provisioning companies, and technical specialists.
Charter Companies command the steepest expansion trajectory. Private Owners retain the largest addressable pool.
Deployment:
Volume concentration favors Cloud-Based architectures eliminating on-premise hardware burdens, while On-Premise and Hybrid retain niche positions for vessels with intermittent connectivity or heightened security requirements.
- Cloud-Based:Multi-tenant SaaS platforms enable shore-side fleet managers to synchronize with vessel crews without dedicated IT infrastructure. Adoption concentrates among sub-fifty-vessel operators seeking capital expenditure avoidance.
- On-Premise:Local server installations for vessels operating under stringent data sovereignty requirements or extended offshore passages beyond reliable satellite coverage.
- Hybrid:Edge computing nodes aboard vessels with periodic cloud synchronization for bandwidth-constrained environments.
- Mobile Application:Native iOS and Android interfaces for crew members executing maintenance tasks and safety inspections on deck.
Cloud-Based architectures dominate new procurement. Mobile Application is gaining share fastest among crew-facing workflows.
Feature:
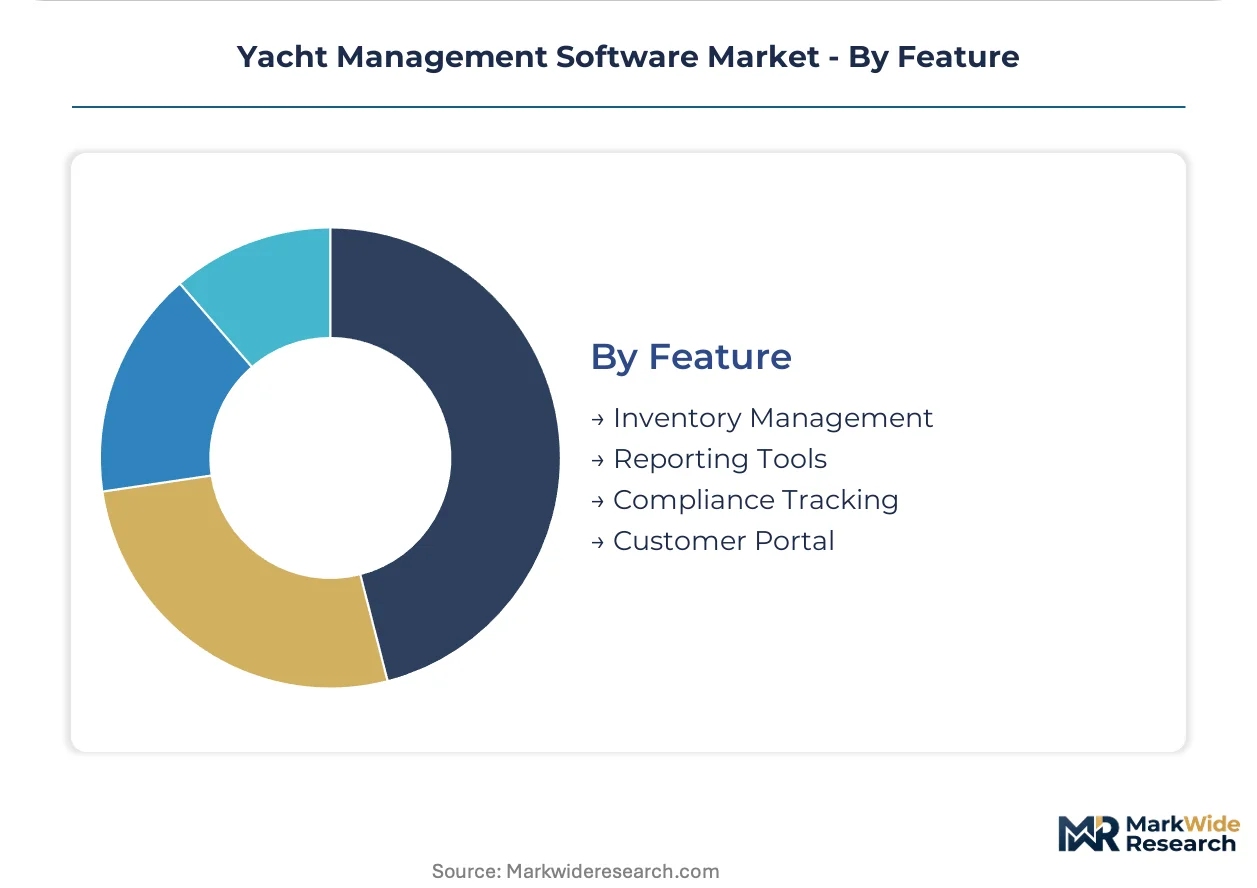
Application maturity separates Compliance Tracking as a regulatory-mandated baseline from Customer Portal as an emerging differentiation layer for charter hospitality.
- Compliance Tracking:Automated flag-state reporting for the UK's MCA, Australia's AMSA, and other national administrations with electronic safety management system mandates. Superyacht operators face the steepest adaptation curves.
- Customer Portal:Digital concierge interfaces for charter guests managing itineraries, provisioning preferences, and shore excursion bookings. Mediterranean operators in France, Italy, and Greece pilot these modules during single-season contracts.
- Inventory Management:Chemical lot-number traceability for REACH compliance with paints, solvents, and cleaning agents from purchase through disposal.
- Reporting Tools:Customizable dashboards for vessel performance analytics and stakeholder communication.
Compliance Tracking anchors platform architecture. Customer Portal represents the most underdeveloped expansion vector.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Mediterranean charter corridor channels software procurement from France, Italy, and Greece toward management companies operating seasonal fleets across the Adriatic and Aegean. Superyacht builders in the Netherlands and Germany export vessel specifications that shape platform integration requirements for northern European operators.
France
Charter operators along the Côte d'Azur deploy guest-experience portals to match hotel-grade hospitality benchmarks. The EU MRV regulation compels fleet managers to automate emissions reporting for vessels calling at Marseille and Nice. Antibes and Monaco host the densest concentration of superyacht management companies piloting predictive maintenance modules during winter refit seasons.
Italy
Shipyards in Viareggio and Livorno drive demand for work-order orchestration systems that digitize warranty claims and class society inspections. REACH compliance obligations from ECHA force chemical inventory tracking for paints and solvents used in refit operations. The Tuscany-Liguria corridor anchors the country's software adoption velocity.
Greece
Island-hopping charter fleets require cloud-native platforms that synchronize dispersed vessels across the Cyclades and Ionian islands. The IMO's carbon intensity indicator mandate shapes procurement priorities for operators based in Athens and Piraeus. Santorini and Mykonos emerge as testing grounds for mobile-first crew interfaces.
United States
Florida-based charter companies adopt integrated fleet platforms to manage Caribbean winter rotations and New England summer circuits. The US Coast Guard's electronic safety management system directives accelerate digitalization among operators in Fort Lauderdale and Palm Beach. The Intracoastal Waterway corridor concentrates demand for real-time vessel tracking.
United Kingdom
MCA-mandated electronic safety management systems drive compliance-tracking procurement among London-based management companies serving global superyacht fleets. Southampton and Portsmouth anchor the country's maritime technology cluster. British flag-state requirements shape software feature roadmaps for vendors targeting Commonwealth administrations.
Yacht Management Software Market Competitive Landscape
Listed leaders compete with private specialists across cloud-native architecture and regulatory compliance depth. The vendor landscape segments into three tiers: enterprise-grade suite providers, maintenance-tracking specialists, and lightweight charter-focused platforms. Strategic differentiation concentrates on API connectivity to onboard IoT sensors and shore-side service networks. Competitive moves cluster around predictive maintenance convergence and guest-experience portal development.
Within the cloud-native tier, Seahub and Voly exemplify divergent specialization strategies. Pelagian occupies a position among maintenance-tracking specialists serving superyacht refit yards. These three companies represent the archetype spectrum from fleet-wide synchronization engines to work-order workflow controllers.
| Leading Market Players |
|---|
| Shipshape |
| Seahub |
| Voly |
| Pelagian |
| YachtWyse |
| Quaynote |
| Southware Yacht Management |
| Vessel Vanguard |
| WinMK |
| Others |
Value Network & Pricing Analysis
Sixty-to-ninety-day implementation cycles for cloud-native yacht management platforms concentrate pricing power among vendors with proven Mediterranean deployment track records, while charter operators in France, Italy, and Greece leverage seasonal contract flexibility to compress subscription terms.
Pricing Analysis
Charter company procurement teams anchor pricing negotiations around modular SaaS tiers calibrated to fleet scale, with ISO 27001 certification grade and API integration depth serving as primary price differentiation drivers. Cost compression in the mid-market tier intensifies as cloud-native entrants displace legacy on-premise installations. Private owners exhibit highest price sensitivity due to limited vessel operating budgets, while superyacht management companies show lowest sensitivity when compliance automation reduces regulatory penalty exposure.
Supply Chain Analysis
Just-in-time provisioning dominates software delivery, though predictive maintenance modules require strategic stockpiling of OEM parts database licenses. Development talent concentrates in the United Kingdom, the Netherlands, and Germany, with cloud infrastructure resting on hyperscaler data centers in Ireland and France. Single-source vulnerability around satellite connectivity providers for offshore IoT transmission constrains fleet-wide real-time synchronization. Distribution runs through direct enterprise sales for fleet management suites and SaaS marketplaces for lightweight scheduling tools.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation across flag-state compliance requirements creates niche specialization opportunities as the IMO's carbon intensity mandate and EU MRV regulation force divergent feature development priorities.
For Market Incumbents: Secure API control points by embedding deeper into onboard equipment manufacturer data streams before proprietary protocols harden into industry standards. Invest in predictive maintenance convergence with OEM parts ecosystems to defend against cloud-native challengers attacking the refit yard segment. For New Entrants and Emerging Players: Differentiate on guest-experience portal functionality, the most underdeveloped white-space in Mediterranean charter operations. Target single-season contract pilots in the France-Italy-Greece corridor where rapid onboarding protocols outweigh multi-year feature depth. Pursue mobile-first crew interfaces for island-hopping fleets as the go-to-market wedge. For Investors and Strategic Acquirers: Long-term, this sits as a regulatory-compliance compounder play because emissions analytics and electronic safety management mandates deepen software embedment into vessel operations. Acquisition targets should display maintenance-tracking specialization with existing OEM parts database integrations. Watch for IMO carbon intensity enforcement tightening as the inflection signal accelerating procurement velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Predictive Maintenance Convergence | Machine-learning failure prediction tied to OEM parts procurement creates recurring revenue streams for superyacht refit yards. |
| Guest-Experience Portal Development | Digital concierge interfaces for charter clients in France, Italy, and Greece capture hospitality-grade differentiation. |
| API Integration with IoT Sensors | Real-time vessel telemetry synchronization satisfies EU MRV emissions reporting and guest-performance dashboards simultaneously. |
| Compliance Module Specialization | REACH chemical tracking and F-Gas refrigerant documentation address steepest adaptation curves for EU-flagged superyachts. |
| Mobile-First Crew Interface | Native iOS and Android maintenance workflows penetrate bandwidth-constrained island-hopping fleets across the Cyclades and Ionian islands. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of flag administration filings, maritime technology trade publications, and charter operator procurement disclosures. Primary interviews engaged fleet managers at Mediterranean charter companies, technical directors at superyacht management firms, software platform product leads, and refit yard operations heads. Secondary validation drew from IMO regulatory circulars, EU MRV verification body reports, and cloud infrastructure provider service documentation. Bottom-up vessel count estimates triangulate against top-down fleet operator spending surveys.
Segmentation dimensions modeled span deployment architecture, vessel scale tier, end-user category, and geographic adoption cluster across the analysis window. CAGRs derive from regression against historical software procurement velocity correlated with regulatory mandate implementation phases. Forecast inputs incorporate charter seasonality patterns in the Mediterranean corridor and satellite connectivity cost trajectories for offshore IoT deployment.
Material uncertainties — flag-state electronic safety management system mandate delays, hyperscaler pricing volatility, maritime cybersecurity incident frequency — sit outside the modeled envelope. Forecasts reflect assumptions about regulatory enforcement consistency and cloud infrastructure cost curves. Revision becomes warranted when IMO carbon intensity penalty thresholds tighten beyond current guidance.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
Engineering Software Market
Software & Services
Backend-As-A-Service Market
Software & Services
Data Integration Software Market
Software & Services
Lab Automation Software Market
Software & Services
Global Electrical Computer-Aided Design (ECAD) Market
Software & Services
Global Translation Software Market
Software & Services
Employee Wellness Software Market
Software & Services
Global Document Control Software Market
Software & Services
Video Converter Software Market
Software & Services
Global Business Card Software Market
Software & Services
Talent Acquisition Software Market
Software & Services
Theatrical Distribution Software Market
Software & Services
Europe Pharmacy POS Software Market
Software & Services
Automotive Dealer Management Systems (DMS) Market
Software & Services
Enterprise Content Management Software Market
Software & Services
Mind Mapping Software Market