
 France Factory Automation and Industrial Controls Market | 2026-2036
France Factory Automation and Industrial Controls Market Size, Share, and Industry Trends Forecast 2026-2036
France Factory Automation and Industrial Controls Market Foresight
France's industrial equipment supply base is restructuring around digital-native manufacturing platforms. Schneider Electric SE leverages its Grenoble R&D campus to anchor domestic programmable logic controller supply chains. Siemens AG competes through deep integration of supervisory control software with motion hardware. ABB Ltd specializes in collaborative robot deployments for mid-sized French automotive suppliers.
Factory automation and industrial controls encompass electromechanical systems, software platforms, and sensor networks that execute, monitor, and optimize production processes with cycle-time precision measured in milliseconds. These systems enable continuous manufacturing flow, defect reduction, and real-time process adjustment across discrete and process industries. Programmable logic controllers and human machine interface products command established margin pools due to their ubiquity in retrofit installations. Industrial robots and machine vision are gaining share fastest as French packaging operations and electronics assembly lines pursue flexible batch production.
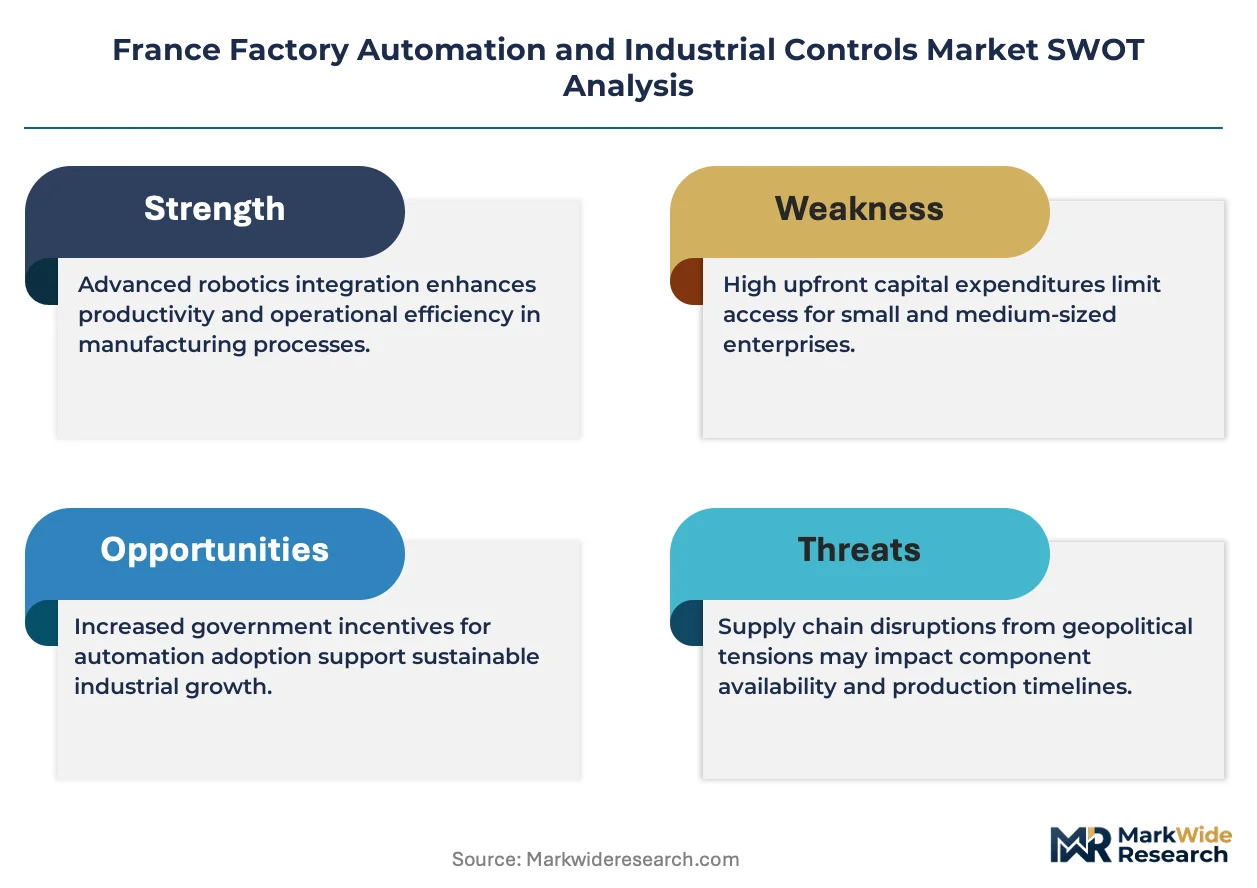
France's national regulator ANSM oversees safety standards for pharmaceutical manufacturing equipment, while EU REACH and CE marking frameworks govern chemical exposure limits and electromagnetic compatibility in control enclosures. The EU AI Act introduces conformity requirements for autonomous decision-making systems on factory floors. Stakeholders must monitor how France transposes these Brussels directives into national enforcement schedules affecting system validation protocols.
Market Dynamics
France's factory automation market is restructuring around the EU Green Deal's decarbonization mandates, which are forcing energy-intensive manufacturers to accelerate control system replacements before 2030 compliance deadlines bite.
Growth Catalysts
- EU AI Act conformity requirements:French automotive and pharmaceutical manufacturers must upgrade to certified autonomous decision-making systems, creating immediate retrofit demand for validated control platforms.
- Île-de-France industrial corridor concentration:Packaging operations and electronics assembly lines in the Paris periphery are deploying collaborative robotics to enable flexible batch production at scale.
- ANSM pharmaceutical equipment standards:Safety validation protocols for manufacturing automation are tightening, requiring continuous monitoring system upgrades across French drug production facilities.
Market Restraints
- Semiconductor component supply concentration:Programmable logic controller production depends on specialized chip supply chains concentrated in East Asian foundries, exposing French system integrators to input volatility.
- REACH chemical exposure compliance:Control enclosure materials face escalating substance restriction testing costs, compressing margins for mid-tier panel builders serving process industries.
- Technical labor scarcity:Commissioning engineers with certified expertise in safety-integrated motion control are concentrated around Grenoble and Toulouse, constraining deployment velocity.
Strategic Opportunities
- Auvergne-Rhône-Alpes manufacturing base:Underpenetrated mid-sized automotive suppliers in the Lyon-Saint-Étienne corridor present white space for collaborative robot integration services.
- Machine vision-electromechanical convergence:Packaging lines are merging optical inspection with adaptive servo systems, enabling defect-free flexible production without mechanical changeover.
- EU CSRD reporting mandates:Large French industrials must install energy monitoring controls to capture Scope 1-2 emissions data, creating pull for connected sensor networks.
Industry Challenges
- CE marking timeline compression:Control system validation protocols for electromagnetic compatibility are extending certification cycles, delaying revenue recognition for system integrators.
- Legacy PLC integration friction:Brownfield sites running 1990s-era Schneider Electric Modicon platforms face complex migration paths to modern Ethernet-based architectures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | France Factory Automation and Industrial Controls Market |
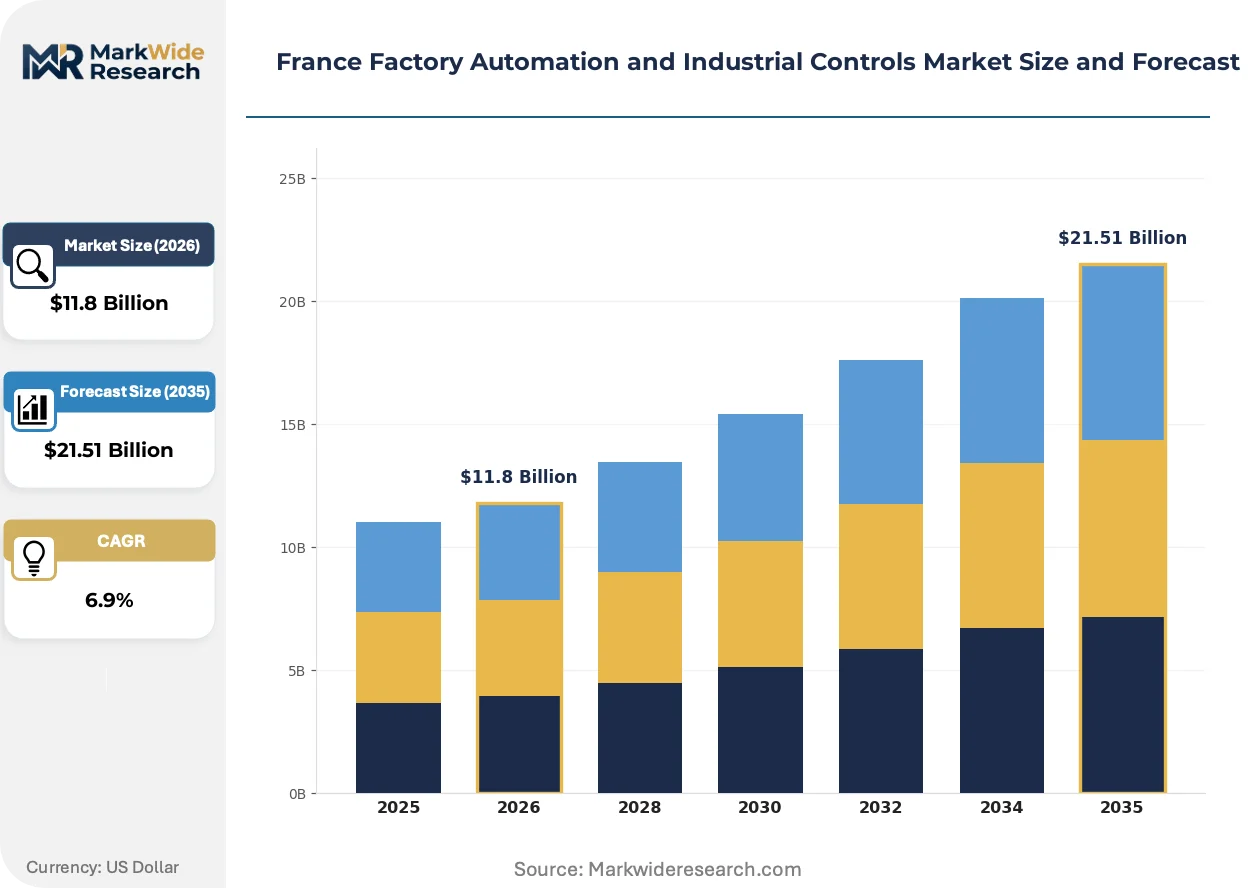
| Market Size in 2026 | $11.8 Billion |
| Market Size in 2035 | $21.51 Billion |
| CAGR (2026 – 2036) | 6.9% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Programmable Logic Controllers, Human Machine Interface, Sensors, Industrial Robots, Motion Control Devices Technology: Distributed Control Systems, SCADA, Supervisory Control, Embedded Systems, Machine Vision Application: Automotive Manufacturing, Food Processing, Chemical Production, Electronics Assembly, Packaging Operations End User Industry: Manufacturing Plants, Energy Facilities, Aerospace Suppliers, Pharmaceuticals Producers, Consumer Goods Factories |
| Companies Covered | Rockwell Automation Inc, Emerson Electric Company, Schneider Electric SE, Omron Corporation, Mitsubishi Electric Corporation, Siemens AG, Honeywell International Inc, Yokogawa Electric Corporation, ABB Ltd, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
France Factory Automation and Industrial Controls Market Shifts & Advancements
Edge computing architectures are consolidating control intelligence at the machine level, displacing centralized PLC hierarchies and enabling millisecond-cycle autonomous adjustments without cloud latency.
Time-sensitive networking over standard Ethernet is consolidating motion control, safety, and process data onto unified cabling infrastructures. French automotive assembly lines are adopting this convergence fastest, collapsing the traditional separation between information technology and operational technology domains. The structural result is compressing system integration costs while demanding new skill sets from commissioning engineers.
The EU AI Act's risk-based classification system is mandating conformity assessments for autonomous quality inspection systems. French pharmaceutical manufacturers face the steepest compliance burden, as ANSM enforcement schedules require validated documentation of algorithmic decision trails. Mid-sized packaging operations are responding by delaying autonomous deployments until certification pathways clarify.
After-sales service unbundling is fragmenting traditional automation vendor relationships. French electronics assemblers are procuring predictive maintenance analytics separately from hardware, favoring specialized software firms over integrated suppliers. This pattern concentrates in Occitanie's aerospace subcontractor cluster, where buyers prioritize operational technology cybersecurity certifications over legacy brand loyalty.
France Factory Automation and Industrial Controls Market Segmentation
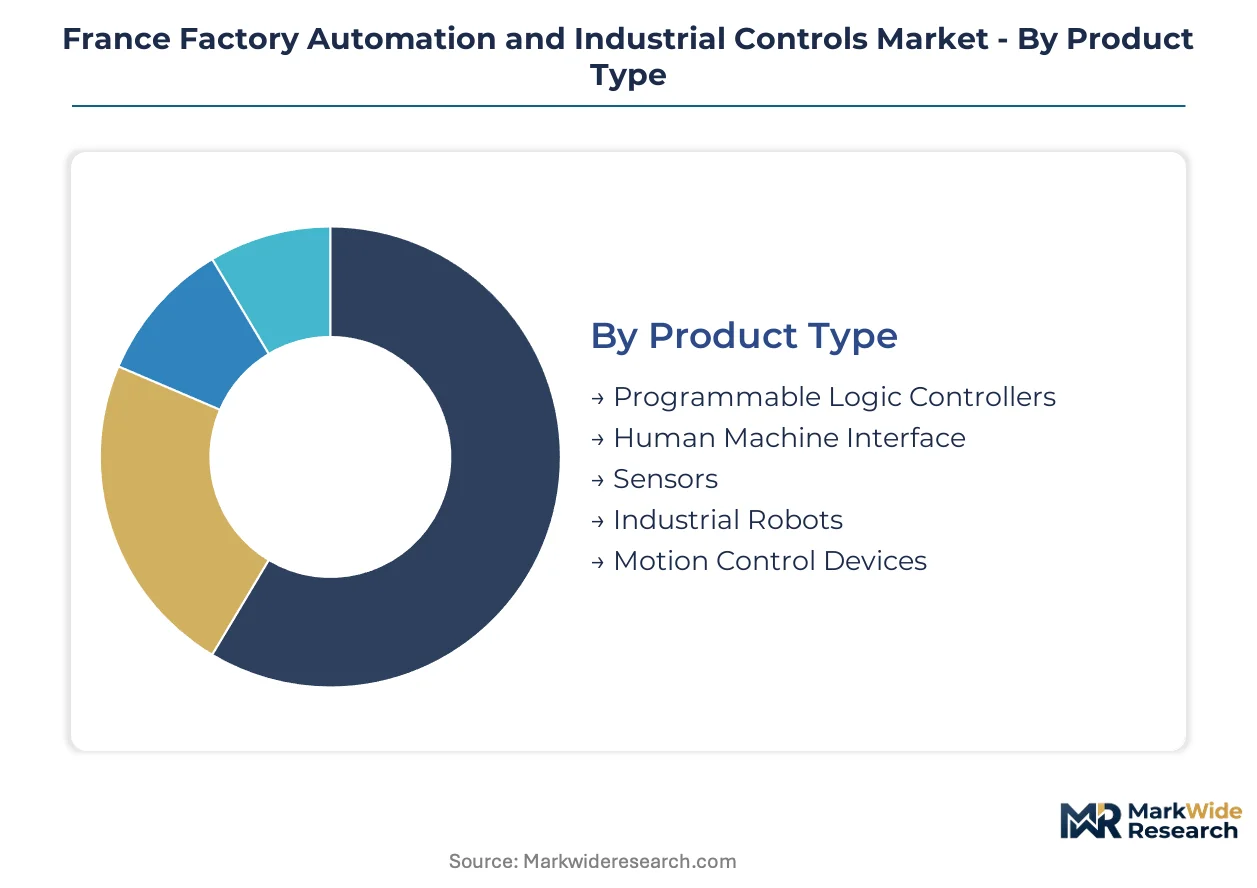
Segmentation reveals how French industrial buyers allocate capital across control hierarchies. Procurement patterns diverge sharply between brownfield retrofit sites and greenfield digital-native facilities, with Île-de-France electronics assemblers driving premium technology uptake while Auvergne-Rhône-Alpes automotive suppliers prioritize ruggedized motion hardware.
Product Type:
Supply concentration for critical components shapes competitive dynamics across hardware categories, with programmable logic controller production anchored by Grenoble-based R&D operations and sensor networks pulling from distributed European foundries.
- Programmable Logic Controllers:Ruggedized computing platforms executing ladder logic and structured text with deterministic cycle times. Renault and Stellantis assembly lines in Hauts-de-France deploy these for powertrain sequencing, constrained by semiconductor lead times from East Asian foundries.
- Industrial Robots:Articulated and collaborative manipulators with force-limiting safety systems enabling human-robot coexistence. Mid-sized automotive suppliers in Lyon-Saint-Étienne corridor are deploying Universal Robots and ABB units for flexible batch production of electric vehicle subassemblies.
- Human Machine Interface:Touch panels and industrial PCs providing operator visualization of process states.
- Sensors:Photoelectric, inductive, and pressure transducers converting physical variables to digital signals.
- Motion Control Devices:Servo drives and variable frequency drives governing motor torque and velocity.
Programmable Logic Controllers absorb the bulk of installed capacity; Industrial Robots are expanding most quickly.
Technology:
Application requirements determine technology selection, with continuous process industries demanding redundant control architectures while discrete manufacturers prioritize flexible reprogrammability.
- Machine Vision:Optical inspection systems combining cameras, lighting, and edge-processing algorithms for defect detection. L'Oréal packaging operations in Île-de-France deploy Cognex and Keyence systems for cosmetic container verification, driven by EU AI Act conformity requirements for validated quality documentation.
- Distributed Control Systems:Hierarchically organized controllers managing continuous processes with redundant failover. TotalEnergies refineries in Normandy and Grand Est rely on Yokogawa and Emerson architectures for distillation column control, constrained by legacy integration complexity.
- SCADA:Supervisory software aggregating field-level data for centralized monitoring.
- Supervisory Control:Advanced process control layers optimizing setpoints across multiple loops.
- Embedded Systems:Dedicated microcontrollers integrated into smart field devices.
Distributed Control Systems retain the largest installed base; Machine Vision is climbing the fastest.
Application:
End-use sector maturity influences automation intensity, with automotive maintaining highest robot density while food processing accelerates from low baselines.
- Automotive Manufacturing:Body-in-white welding, paint application, and final assembly sequencing. Stellantis Sochaux and Renault Flins plants are retrofitting lines for electric vehicle platforms, requiring new collaborative robot deployments and battery handling safety systems.
- Electronics Assembly:Surface-mount technology placement, testing, and packaging operations. Thales and Safran aerospace electronics facilities in Occitanie demand precision motion control for avionics component placement, constrained by cleanroom certification requirements.
- Food Processing:Hygienic handling, packaging, and traceability systems.
- Chemical Production:Batch and continuous reactor control with safety instrumented systems.
- Packaging Operations:Cartoning, palletizing, and labeling with flexible format changeover.
Automotive Manufacturing commands dominant capital allocation; Electronics Assembly is gaining share fastest.
End User Industry:
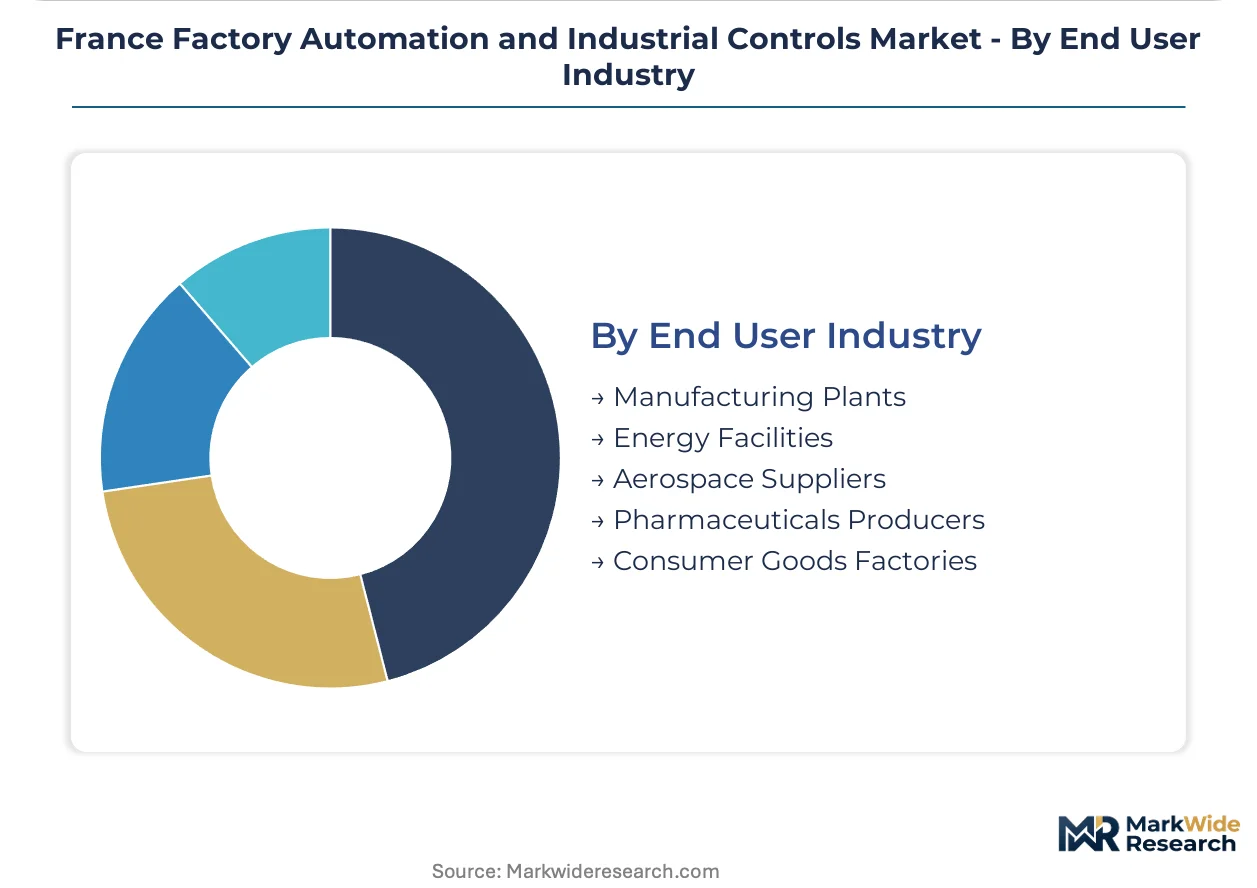
Customer scale and regulatory exposure create tiered demand patterns, with pharmaceutical producers paying premiums for validated systems and energy facilities prioritizing cybersecurity-hardened architectures.
- Pharmaceuticals Producers:Sanofi and Servier manufacturing sites governed by ANSM validation protocols. Fill-finish lines for biologics require continuous monitoring systems with 21 CFR Part 11 electronic records compliance, driving demand for audit-trail-capable control platforms.
- Aerospace Suppliers:Safran, Thales, and Dassault Aviation subcontractors producing airframe and avionics components. Occitanie and Nouvelle-Aquitaine clusters demand AS9100-certified quality systems with full component traceability, constraining vendor qualification timelines.
- Manufacturing Plants:General discrete and process manufacturing operations.
- Energy Facilities:Power generation and grid infrastructure control systems.
- Consumer Goods Factories:High-volume packaging and assembly for retail distribution.
Manufacturing Plants absorb the bulk of installed capacity; Pharmaceuticals Producers are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Grenoble's semiconductor research ecosystem anchors French control system supply chains, while Parisian industrial demand pulls automation investment toward the Île-de-France corridor.
Île-de-France
Packaging operations and electronics assembly lines drive collaborative robotics deployment around Paris. ANSM pharmaceutical equipment standards mandate validated control platforms for Sanofi manufacturing sites. L'Oréal cosmetic container verification systems exemplify machine vision integration at scale.
Auvergne-Rhône-Alpes
Mid-sized automotive suppliers in the Lyon-Saint-Étienne corridor pursue flexible batch production for electric vehicle subassemblies. EU Green Deal decarbonization deadlines force energy-efficient servo system upgrades. Schneider Electric's Grenoble R&D campus anchors domestic programmable logic controller development.
Hauts-de-France
Renault and Stellantis powertrain sequencing operations demand ruggedized computing platforms with deterministic cycle times. REACH chemical exposure compliance escalates testing costs for control enclosure materials. Dunkirk industrial zone retrofit projects concentrate brownfield automation migration.
Occitanie
Safran and Thales aerospace electronics facilities require precision motion control for avionics component placement. EU AI Act conformity assessments delay autonomous quality inspection deployments. Toulouse commissioning engineer scarcity constrains safety-integrated motion control deployment velocity.
Normandy
TotalEnergies distillation column operations rely on redundant failover architectures for continuous process control. CE marking electromagnetic compatibility protocols extend certification cycles for system integrators. Le Havre petrochemical corridor presents legacy distributed control system integration complexity.
France Factory Automation and Industrial Controls Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue software-defined control architectures and predictive maintenance analytics. The vendor base stratifies across integrated hardware-software platforms, specialized motion control suppliers, and component-focused sensor manufacturers. Three archetypes dominate: diversified industrial conglomerates with captive distribution, regional system integrators with vertical expertise, and software-native entrants unbundling after-sales service. Competitive moves concentrate on strategic partnerships for edge computing integration and portfolio diversification into collaborative robotics.
Among France-based industrial conglomerates, Schneider Electric SE exemplifies the integrated platform archetype, anchoring domestic supply chains through Grenoble-based research operations. Siemens AG and ABB Ltd represent the diversified multinational tier, with the former emphasizing supervisory control software integration and the latter specializing in collaborative robot deployments for mid-sized automotive suppliers. These three entities occupy positions spanning the full control hierarchy from field-level sensors to enterprise planning systems.
| Leading Market Players |
|---|
| Rockwell Automation Inc |
| Emerson Electric Company |
| Schneider Electric SE |
| Omron Corporation |
| Mitsubishi Electric Corporation |
| Siemens AG |
| Honeywell International Inc |
| Yokogawa Electric Corporation |
| ABB Ltd |
| Others |
Supply & Pricing Matrix
Family-owned mid-cap panel builders across Auvergne-Rhône-Alpes and Hauts-de-France anchor French control system supply chains, their conservative balance sheets limiting aggressive pricing competition while reinforcing long-term service relationships with automotive OEMs. Their ownership structure shapes procurement behavior, favoring stable contract terms over spot-market volatility and embedding after-sales service into hardware pricing.
Pricing Analysis
Warranty and predictive maintenance bundling separates premium-tier offerings from unbundled hardware transactions in French factory automation. Three-tier pricing structure across premium, standard, and economy levels reflects CE certification grade and ANSM validation status for pharmaceutical applications. Cost compression in standard-tier programmable logic controllers is intensifying because semiconductor input volatility forces margin sacrifice to retain Renault and Stellantis volume. Mid-sized automotive suppliers in Lyon-Saint-Étienne corridor exhibit highest price sensitivity, while Sanofi manufacturing sites accept premiums for validated audit-trail systems.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale buyer demand from Renault and Stellantis, while regional system integrators serve fragmented mid-tier packaging operations. Semiconductor components draw from Taiwan, South Korea, and Germany, with specialized industrial microcontrollers resting on East Asian foundry capacity. Servo drive power electronics and optical sensor arrays are tethered to German and Japanese component supply. Single-source vulnerability in advanced motion control chips exposes French integrators to allocation risk. Distribution runs through Schneider Electric's captive network and independent automation distributors serving Occitanie aerospace clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
France's factory automation market sits at a technology-transition inflection, with edge-computing architectures displacing centralized PLC hierarchies and forcing incumbent vendors to rebuild software competencies. Time-sensitive networking convergence is collapsing traditional information technology and operational technology separation.
For Market Incumbents: Cement control over safety-integrated motion certification pathways by deepening captive supply of ASIL-D servo systems, insulating against emerging software-native entrants unbundling predictive maintenance. Prioritize Grenoble R&D capacity expansion to anchor domestic PLC development and preempt Siemens AG supervisory control software integration moves. For New Entrants and Emerging Players: Launch via specialized machine vision integration services targeting underpenetrated Auvergne-Rhône-Alpes mid-sized automotive suppliers, where collaborative robot deployment velocity outpaces incumbent service capacity. White space concentrates in Occitanie aerospace subcontractor clusters demanding OT cybersecurity certifications over legacy brand loyalty. For Investors and Strategic Acquirers: EU AI Act conformity assessment bottlenecks at ANSM are the leading indicator that validated algorithmic decision-trail capabilities will command acquisition premiums. Five-to-ten year viability favors targets with pharmaceutical equipment validation expertise and embedded energy monitoring sensor networks. Monitor CE marking electromagnetic compatibility protocol extensions as margin compression signal for system integrators.| Strategic Initiative | Industry Significance |
|---|---|
| Edge Computing Platform Integration | Consolidates control intelligence at machine level for Stellantis assembly line retrofits. |
| Backward Integration into Servo Drive Manufacturing | Captures margin pools in power electronics supplying Lyon-Saint-Étienne automotive corridor. |
| EU AI Act Conformity Certification | Unlocks pharmaceutical automation contracts governed by ANSM validation protocols. |
| Time-Sensitive Networking Infrastructure Deployment | Enables unified Ethernet architectures collapsing IT-OT domain separation at Renault Flins. |
| Predictive Maintenance Analytics Unbundling | Addresses Occitanie aerospace demand for OT cybersecurity-certified software over integrated hardware. |
Research Methodology
Document review covered EU regulatory filings, semiconductor trade data, and ANSM enforcement schedules, complemented by interviews with plant engineers at Renault and Stellantis facilities, automation procurement leads at Sanofi, and aftermarket service heads at regional system integrators. Secondary validation drew from ECHA REACH substance restriction databases, CE marking electromagnetic compatibility protocols, and EU AI Act implementation guidance. Bottom-up demand modeling triangulated against top-down industrial production indices.
Segment-level outputs across the analysis window reflect product type, technology, application, and end-user industry dimensions, with regional splits calibrated to Île-de-France and Auvergne-Rhône-Alpes industrial production data. CAGRs were derived from installed base replacement cycles and greenfield capital expenditure trajectories, incorporating EU Green Deal decarbonization compliance deadlines and ANSM pharmaceutical equipment standard revision timelines as demand pull factors.
Semiconductor allocation disruptions, CE marking timeline extensions, and ANSM enforcement schedule accelerations are the dominant revision risks to base-case assumptions. Forecasts reflect documented assumptions regarding collaborative robot adoption velocity and time-sensitive networking penetration rates. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Automation
Global Intelligent Completion Market
Industrial Automation
Industrial Automation Spares Market
Industrial Automation
Predictive Maintenance Market
Industrial Automation
Model Based Manufacturing Technologies Market
Industrial Automation
Digital Transformation in Manufacturing Market
Industrial Automation
Global Distribution Feeder Automation System Market
Industrial Automation
North America Process Automation Market
Industrial Automation
United Kingdom Factory Automation and Industrial Control Systems Market
Industrial Automation
Global Smart Warehousing Market
Industrial Automation
Sortation Systems Market
Industrial Automation
Europe Warehouse Automation Systems Market
Industrial Automation
Europe Automation Components Market
Industrial Automation
Smart Industries Market
Industrial Automation
Motion Control Drive Market
Industrial Automation
Industrial Automation Device Manager Software Market
Industrial Automation
Smart Warehouse System Market