
 Global Permit Management Software Market | 2026-2036
Global Permit Management Software Market Size, Share, and Industry Trends Forecast 2026-2036
Global Permit Management Software Market Foresight
Cloud infrastructure is broadening the addressable base for permit management vendors serving mid-sized municipalities. VelocityEHS leverages its environmental compliance heritage to anchor enterprise accounts with complex multi-site permitting needs. Cloudpermit sustains a product specialization in building departments with streamlined plan review modules. OpenGov competes aggressively on channel control through its established government ERP relationships.
Permit management software orchestrates the intake, review, approval, and inspection tracking of regulatory licenses across built environment and industrial operations. Platforms typically integrate geospatial data layers, automated workflow engines, and document repositories to compress approval cycles from weeks to days. Cloud-based deployment leads adoption curves among municipalities with limited IT staffing, while workflow automation captures disproportionate margin pools through recurring configuration services. On-premise installations retain footholds in defense-adjacent and critical infrastructure settings with stringent data sovereignty requirements.
The EPA's stormwater and air quality permitting mandates shape product roadmaps for environmental compliance modules. The EU Green Deal's building renovation wave and F-Gas Regulation compliance deadlines drive feature prioritization across European deployments. Stakeholders must monitor how emerging building performance standards in multiple jurisdictions force retrofitting of legacy permit databases with carbon accounting integrations.
Market Dynamics
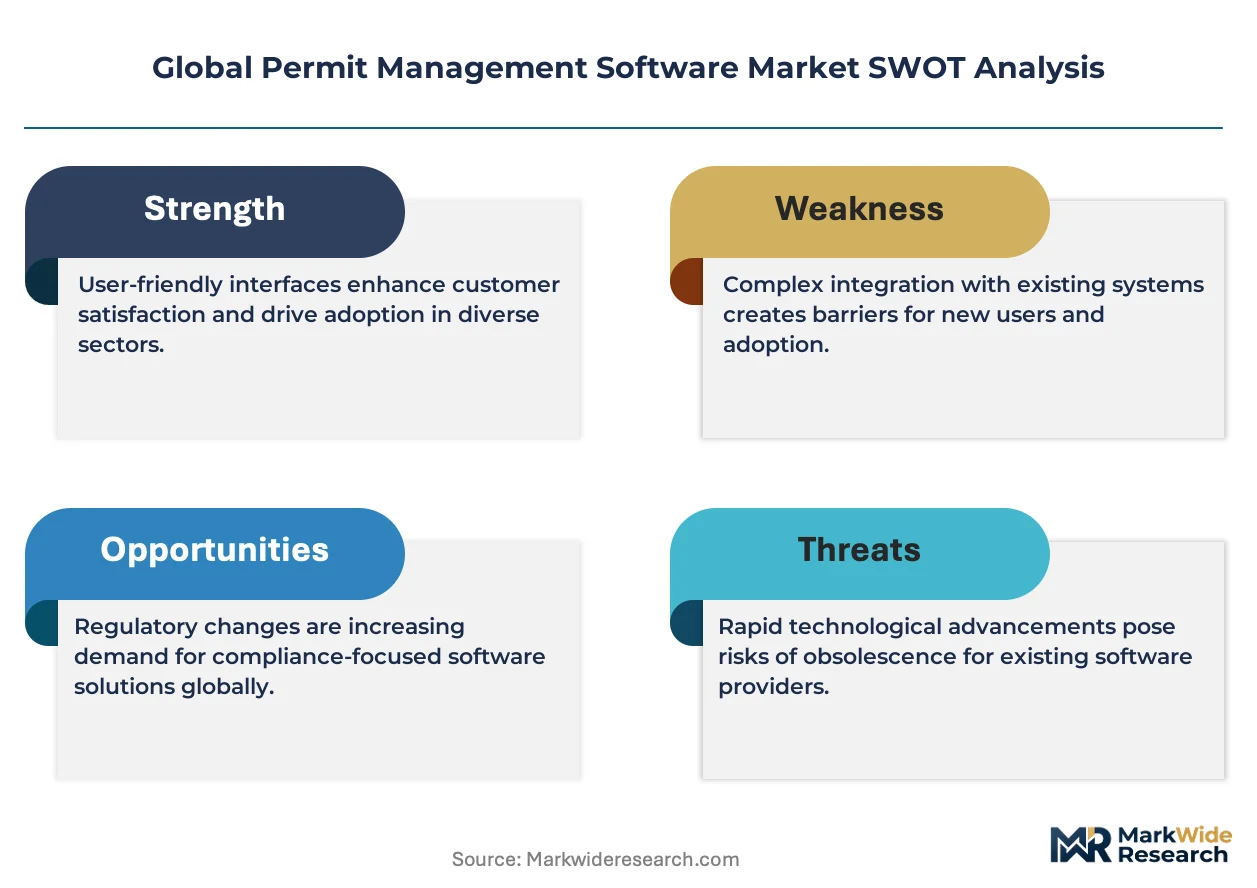
Municipal budget constraints and workforce shortages are compressing procurement cycles for permit management platforms, forcing vendors to deliver pre-configured cloud deployments that eliminate traditional implementation timelines.
Growth Catalysts
- EU AI Act compliance mandates:European agencies require auditable decision trails for automated permit approvals, accelerating replacement of legacy paper-based systems with workflow-integrated platforms.
- Building electrification codes:Jurisdictions across Germany, California, and Ontario now mandate carbon accounting in renovation permits, expanding software scope beyond basic intake and inspection tracking.
- Mid-sized municipality cloud migration:IT staffing gaps in cities with populations between 50,000 and 500,000 residents are eliminating on-premise deployment preferences previously held by smaller jurisdictions.
Market Restraints
- Data sovereignty requirements:Defense-adjacent and critical infrastructure operators in the United States and Saudi Arabia mandate air-gapped installations, fragmenting vendor R&D across incompatible deployment architectures.
- Interoperability standards gaps:Lack of unified APIs between geospatial information systems and permit databases forces expensive custom integration work for multi-jurisdictional implementations.
- Subscription fatigue:Municipal finance officers facing simultaneous SaaS transitions across ERP, CRM, and citizen service platforms are extending replacement cycles for permit software.
Strategic Opportunities
- Industrial environmental permitting:EPA stormwater and air quality mandates create expansion paths beyond municipal building departments into manufacturing and energy facility compliance workflows.
- Mobile inspection tools:Field staff adoption of smartphone-based data capture is opening subscription tiers for offline-capable inspection modules previously bundled only in enterprise packages.
- Climate disclosure convergence:CSRD reporting requirements in Europe and emerging building performance standards in British Columbia and New South Wales position permit data as inputs for corporate carbon accounting systems.
Industry Challenges
- Legacy database migration complexity:Decades of unstructured permit records in proprietary formats resist automated extraction, inflating implementation costs and timeline risk for vendor project teams.
- Cross-functional workflow design:Building, fire, and environmental departments within single municipalities operate independent approval hierarchies, complicating unified platform configuration.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Permit Management Software Market |
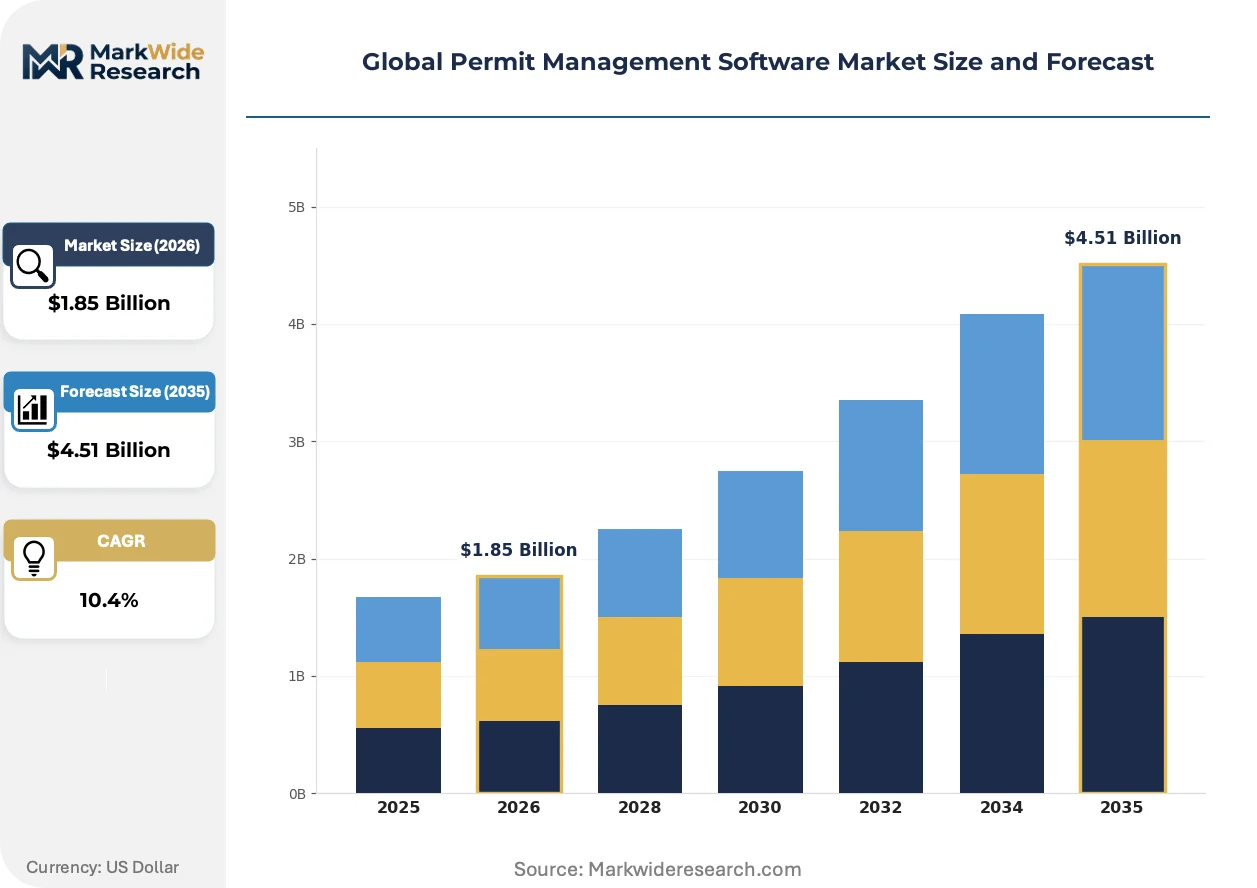
| Market Size in 2026 | $1.85 Billion |
| Market Size in 2035 | $4.51 Billion |
| CAGR (2026 – 2036) | 10.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: Cloud-Based, On-Premise, Hybrid, Private Cloud Solution Offering: Access Control, Incident Management, Workflow Automation, Reporting & Analytics, Document Management Use Case: Construction Management, Environmental Compliance, Facility Maintenance, Event Coordination End User: Government Agencies, Manufacturing Plants, Educational Institutions, Energy Providers, Transportation Authorities |
| Companies Covered | CityView Suite, Intelex, Granicus, GovPilot, VelocityEHS, Cloudpermit, iWorQ Systems, OpenGov, Asite, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Permit Management Software Market Shifts & Advancements
Permit management software architecture is fragmenting into composable service layers that separate intake, review, and inspection functions into independently upgradeable components.
Microservices-based permit engines are modularizing core workflow logic into API-accessible building blocks. Mid-sized vendors are adopting this architecture to compete against integrated suites, allowing customers to embed permit functionality within existing citizen portals without full platform replacement. This modularity is compressing sales cycles by reducing upfront commitment requirements.
The EU Green Deal's building renovation wave is forcing feature prioritization across European deployments. Member state agencies must track embodied carbon in material approvals and energy performance certificates alongside traditional structural and safety reviews. German federal building codes now require software vendors to pre-validate renovation permit applications against regional energy efficiency databases before formal submission.
Subscription pricing for inspection scheduling modules is displacing perpetual license models in North American municipal procurement. Finance departments prefer operational expenditure classification for cloud-hosted solutions, while vendor revenue teams capture expansion through usage-based inspection volume tiers. This shift is most visible in California and Texas municipalities with active housing development pipelines.
Global Permit Management Software Market Segmentation
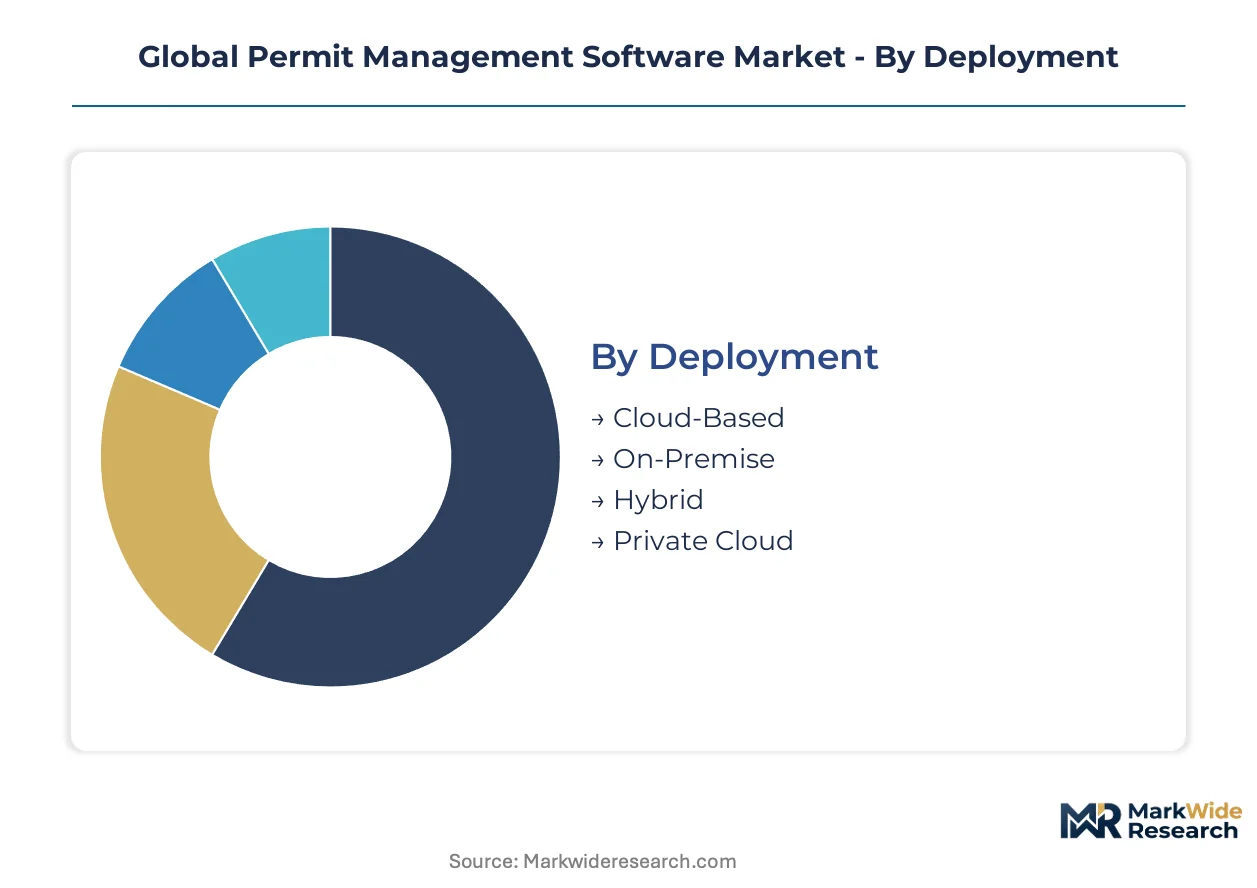
Permit management software segments diverge sharply by compliance burden and IT infrastructure maturity. Deployment architecture determines audit trail capabilities for EU AI Act and EPA mandates, while solution depth separates basic workflow tools from platforms handling carbon accounting integration.
Deployment:
Certification requirements vary dramatically by deployment mode, with air-gapped installations demanding FERC and defense-grade validation while cloud deployments prioritize GDPR and state-level data residency compliance.
- Cloud-Based:Multi-tenant SaaS architectures with automatic security patching serve municipalities in California and Texas lacking dedicated IT staff. German agencies favor these for EU Green Deal reporting integration, though GDPR Article 28 processor agreements extend procurement timelines.
- On-Premise:Air-gapped servers with hardware security modules satisfy Saudi Aramco and U.S. Department of Defense data sovereignty mandates. Saudi Arabia's National Cybersecurity Authority and U.S. FERC critical infrastructure rules force perpetual license retention despite higher total cost of ownership.
- Hybrid:Split architectures keep sensitive permit records on-premise while routing citizen-facing intake to public cloud. Ontario municipalities use this for Personal Information Protection compliance without sacrificing mobile inspection accessibility.
- Private Cloud:Single-tenant hosted environments deliver cloud economics with dedicated infrastructure isolation. Energy providers in Alberta and Queensland select these for CSRD-aligned carbon disclosure without multi-tenant risk exposure.
Cloud-Based sits at the top of the volume ranking, with Hybrid climbing the fastest as mid-sized jurisdictions balance compliance and flexibility.
Solution Offering:
Cost tier stratification separates enterprise-grade automation from entry-level digitization, with workflow engines commanding premium pricing against basic document repositories.
- Workflow Automation:Rules-based routing engines with conditional approval hierarchies compress German building permit cycles from months to weeks. California cities embed these with Title 24 energy code validation, triggering automatic rejection of non-compliant renovation applications.
- Reporting & Analytics:Dashboards aggregating permit velocity, inspection backlog, and fee collection power municipal performance management. British Columbia and New South Wales agencies leverage these for building performance standard benchmarking against climate targets.
- Access Control:Role-based permissions with multi-factor authentication protect sensitive applicant data. Standard feature across all deployment tiers with limited differentiation.
- Incident Management:Tracks safety violations and stop-work orders through resolution. Heavy demand from OSHA-regulated manufacturing facilities.
- Document Management:Centralized storage with version control and redaction tools. Baseline capability increasingly commoditized.
Workflow Automation sits at the top of the volume ranking, with Reporting & Analytics climbing the fastest as climate disclosure mandates expand.
Use Case:
Application maturity varies by regulatory complexity, with environmental compliance requiring the deepest system integration against evolving EPA and ECHA rule sets.
- Environmental Compliance:Stormwater NPDES permits and air quality Title V authorizations demand real-time monitoring data feeds. EPA's MS4 mandates in Florida and Texas drive manufacturing facility deployments with sensor integration.
- Construction Management:Building permits with plan review, inspection scheduling, and certificate of occupancy issuance. California's CalGreen codes and Germany's federal building regulations force energy performance pre-validation.
- Facility Maintenance:Recurring operational permits for hazardous materials storage and fire safety system certification. Less complex workflows with faster implementation cycles.
- Event Coordination:Temporary permits for public gatherings with crowd capacity and emergency access requirements. Seasonal demand concentration limits platform stickiness.
Construction Management sits at the top of the volume ranking, with Environmental Compliance climbing the fastest as EPA enforcement intensifies.
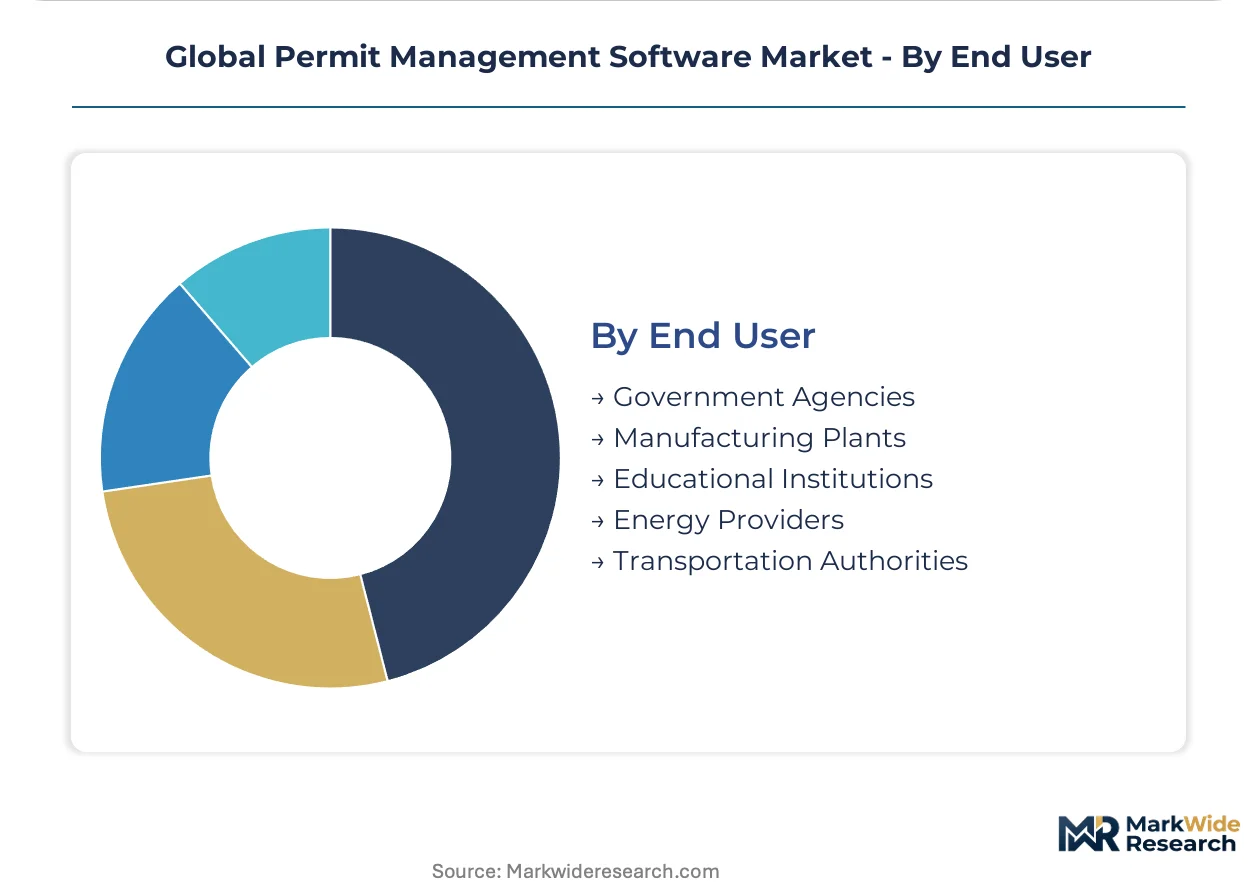
End User:
Customer type determines procurement authority and integration complexity, with government agencies presenting the longest sales cycles but largest contract values.
- Government Agencies:Municipal building departments and county environmental health divisions with multi-year appropriations cycles. German state-level agencies require pre-certification against federal energy database connectivity.
- Manufacturing Plants:Chemical, pharmaceutical, and automotive facilities managing EPA and ECHA permit portfolios. Dow and BASF sites demand enterprise scalability with plant-level workflow customization.
- Energy Providers:Utilities navigating FERC hydropower licensing and state PUC construction authorizations. Duke Energy and E.ON deployments span generation, transmission, and distribution permit types.
- Transportation Authorities:State DOTs and port authorities with linear project permitting across multiple jurisdictions. California High-Speed Rail Authority exemplifies complex multi-county coordination needs.
- Educational Institutions:University facilities departments with research laboratory safety permits. Smaller addressable market with decentralized purchasing authority.
Government Agencies sit at the top of the volume ranking, with Manufacturing Plants climbing the fastest as EPA enforcement targets industrial facilities.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German municipal building departments anchor software demand through complex federal-state permitting hierarchies. California housing agencies and Texas environmental authorities compress procurement cycles amid staffing shortages.
United States
California's Title 24 energy codes and Texas MS4 stormwater mandates drive platform replacement. EPA enforcement intensifies across Florida manufacturing corridors. Miami-Dade County integrates air quality monitoring with permit workflows.
Germany
Federal building codes require pre-validation against regional energy databases. EU AI Act compliance forces auditable decision trails in Bavarian municipalities. Hamburg digitizes environmental clearance processes ahead of federal deadlines.
Canada
Ontario's Personal Information Protection rules favor hybrid cloud architectures. British Columbia building performance standards mandate carbon accounting in renovation permits. Vancouver accelerates multi-jurisdictional workflow integration.
Australia
New South Wales agencies benchmark permit data against climate disclosure targets. Queensland energy providers select private cloud deployments for CSRD alignment. Sydney commercial development pressures compress approval timelines.
Saudi Arabia
National Cybersecurity Authority mandates air-gapped installations for critical infrastructure. Aramco facility permits require hardware security modules. Riyadh municipal digitization proceeds alongside data sovereignty enforcement.
Global Permit Management Software Market Competitive Landscape
Global majors compete with regional champions across deployment architecture preferences. The vendor base separates into cloud-native SaaS providers, legacy ERP extenders, and environmental compliance specialists. Three archetypes dominate: workflow automation platforms, government ERP integrators, and industrial permitting specialists. M&A activity concentrates on geospatial data layer acquisitions, while strategic partnerships target API interoperability standards.
Within the environmental compliance tier, VelocityEHS anchors enterprise accounts with multi-site permitting heritage. Cloudpermit exemplifies building department specialization through streamlined plan review modules. OpenGov occupies a position within government ERP relationships, competing aggressively on channel control across North American municipalities.
| Leading Market Players |
|---|
| CityView Suite |
| Intelex |
| Granicus |
| GovPilot |
| VelocityEHS |
| Cloudpermit |
| iWorQ Systems |
| OpenGov |
| Asite |
| Others |
Supply & Pricing Matrix
Full-stack software engineering talent concentration in Bangalore and Warsaw creates labor-cost differentials that widen pricing-tier spreads between premium enterprise suites and mid-market SaaS offerings.
Pricing Analysis
Input-cost pass-through from cloud infrastructure providers shapes vendor margin structures, with AWS and Azure compute storage fees compressing gross margins for multi-tenant SaaS operators. Pricing stratifies across enterprise, professional, and essential tiers based on workflow automation depth and API integration volume. Pricing pressure stems from municipal procurement officers demanding consumption-based inspection modules rather than seat-based subscriptions. Government agencies exhibit highest price sensitivity due to appropriations-cycle constraints, while energy providers accept premium tiers for air-gapped deployment certification.
Supply Chain Analysis
Certification gating through FedRAMP, ISO 27001, and SOC 2 Type II compliance restricts vendor eligibility for U.S. federal and German state contracts. Software development concentrates in India, Poland, and the United States, with quality assurance and localization distributed across Ireland and Singapore. Raw material dependencies include open-source framework licensing, geospatial data feed subscriptions, and identity verification API credits. Single-source vulnerability runs through Esri's ArcGIS platform for geospatial layer integration. Distribution runs through direct enterprise sales teams, systems integrator partnerships, and government procurement cooperatives.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in permit management software rests on automation-driven implementation cost reduction and tiered upsell to carbon-accounting modules.
For Market Incumbents: Extend workflow automation capabilities into environmental compliance verticals before specialized entrants capture EPA-mandated manufacturing accounts. Consolidate position through backward integration into geospatial data layer providers, reducing Esri dependency. Channel control investments in government ERP partnerships defend against OpenGov's municipal relationship leverage. For New Entrants and Emerging Players: Systems integrators with existing municipal IT modernization contracts represent the fastest path to embedded deployment. White-space concentration sits in mid-sized U.S. cities between 50,000 and 200,000 residents lacking dedicated permit IT staff. Target California and Texas housing authorities with pre-configured Title 24 and MS4 compliance templates delivered through channel partner co-sell arrangements. For Investors and Strategic Acquirers: Valuations sit cheapest among on-premise legacy vendors with air-gapped installation expertise serving defense and critical infrastructure segments. Long-term viability favors vendors with EU AI Act audit-trail capabilities and CSRD carbon disclosure integrations. Watch EPA enforcement intensity in Florida and Texas manufacturing corridors as inflection signal for environmental compliance module demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Geospatial Data Layer Acquisition | Reduces third-party Esri dependency while embedding location intelligence directly into permit workflows. |
| EU AI Act Compliance Certification | Unlocks Bavarian and Hamburg municipal procurement requiring auditable automated decision trails. |
| Mobile Inspection Module Launch | Captures subscription expansion from California field staff adopting offline-capable smartphone data capture. |
| Carbon Accounting Integration | Positions permit data as CSRD-aligned inputs for British Columbia and New South Wales building performance disclosure. |
| Hybrid Cloud Architecture Deployment | Satisfies Ontario Personal Information Protection rules without sacrificing mobile inspection accessibility. |
Research Methodology
Multiple input streams — municipal IT director interviews, vendor product roadmap disclosures, and regulatory filing analysis — were reconciled against secondary validation. Primary fieldwork engaged government CIOs, building department managers, environmental compliance officers, and systems integrator architects across Germany, California, Texas, and Ontario. Secondary sources included EPA enforcement databases, EU Green Deal implementation guidelines, FERC critical infrastructure rulings, and municipal procurement records. Bottom-up deployment estimates and top-down market sizing were triangulated to constrain variance.
Data-stream reconciliation across deployment mode, solution depth, use case complexity, and end-user procurement authority informed the analytical framework. Modeled dimensions spanned cloud versus on-premise architecture, workflow automation versus basic digitization, construction versus environmental compliance applications, and government agency versus industrial facility buyers. CAGRs were derived from trajectory fitting to historical adoption curves adjusted for regulatory mandate timing. Forecast inputs incorporated EPA enforcement budget allocations, EU Green Deal building renovation targets, and municipal IT staffing survey data.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to EPA rulemaking velocity and EU AI Act implementation consistency. Projections reflect assumptions around municipal cloud migration willingness and geospatial API standardization progress. A model refresh is warranted upon material change in federal infrastructure spending authorization or state-level building code electrification mandates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
PLM Software Market
Software & Services
Mobile Application Testing Services (MATS) Market
Software & Services
Global Customer Success Software Market
Software & Services
PCB CAD Software Market
Software & Services
Global Contract Management Software Market
Software & Services
Sales Dialer Software Market
Software & Services
SMS Marketing Software Market
Software & Services
IT Services Market
Software & Services
Global Online Expense Management Software Market
Software & Services
Contract Abstraction Software Market
Software & Services
Global Nosql Database Market
Software & Services
Global Product Lifecycle Management Software Market
Software & Services
Global Version Control Systems Market
Software & Services
Server Virtualization Software Market
Software & Services
Global Screen Mirroring Apps Market
Software & Services
Procurement Software Market