
 Auto Software Market | 2026-2036
Auto Software Market Size, Share, and Industry Trends Forecast 2026-2036
Auto Software Market Insights
The EU Green Deal is shifting procurement criteria across European automakers toward software-centric vehicle architectures. NVIDIA Corporation leverages its DRIVE platform to dominate AI-powered autonomous development. Continental AG anchors European production with embedded systems spanning powertrain and chassis domains. Robert Bosch GmbH sustains R&D intensity across middleware and operating system layers for safety-critical applications.
Auto software encompasses embedded firmware, real-time operating systems, middleware stacks, and application-layer programs that orchestrate vehicle functions through ECU networks with sub-millisecond latency requirements. Its primary purpose is to enable software-defined vehicle platforms where functional updates deploy over-the-air without hardware changes. Application software captures expanding margin pools as automakers monetize subscription features and personalized cockpit experiences. Fleet management solutions within the solution dimension are growing fastest as logistics operators demand predictive maintenance and route optimization. AI-powered technology leads investment allocation, though cybersecurity solutions are deepening as regulatory pressure intensifies.
The EU AI Act and UNECE WP.29 cybersecurity regulations are reshaping product standards, forcing OEMs to certify autonomous algorithms and secure over-the-air update pipelines before market access. NHTSA in the United States and MIIT in China are converging on similar software integrity mandates, creating multi-jurisdictional compliance burdens for global suppliers. Stakeholders must monitor divergence between European AI liability frameworks and American product liability precedents when architecting platform governance models.
Market Dynamics
The transition to software-defined vehicle architectures is restructuring value capture across the automotive value chain. Functional safety requirements under UNECE WP.29 and the EU AI Act are forcing OEMs to decouple hardware from software lifecycles.
Growth Catalysts
- EU AI Act compliance mandates:European automakers must certify autonomous algorithms before market access, accelerating investment in verification tooling and middleware layers.
- Over-the-air update proliferation:Fleet operators demand continuous feature deployment without physical recalls, expanding addressable revenue per vehicle.
- German engineering cluster concentration:Stuttgart, Munich, and Wolfsburg anchor deep talent pools for safety-critical embedded systems development.
Market Restraints
- Semiconductor supply concentration:Advanced driver-assistance SoCs depend on TSMC's 5nm and 7nm capacity, creating single-source vulnerability for European Tier-1 suppliers.
- Functional safety certification costs:ISO 26262 ASIL-D compliance requires 18-36 month validation cycles, compressing margin on mid-volume vehicle programs.
- Cybersecurity liability fragmentation:Divergence between UNECE WP.29, NHTSA guidance, and MIIT standards forces redundant engineering for global platforms.
Strategic Opportunities
- Subscription monetization white space:Personalized cockpit experiences and autonomous feature unlocking represent underexploited recurring revenue streams.
- India PLI scheme for automotive electronics:Production-linked incentives are attracting software development centers to Bangalore and Pune for cost-optimized engineering.
- Digital twin convergence:Virtual validation environments are compressing hardware-in-the-loop testing cycles for powertrain calibration.
Industry Challenges
- Embedded systems talent scarcity:Real-time operating system expertise and functional safety engineering skills command 40-60% wage premiums across European automotive hubs.
- Legacy ECU integration complexity:Heterogeneous controller networks from 2015-2020 vehicle generations resist centralized zonal architectures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Auto Software Market |
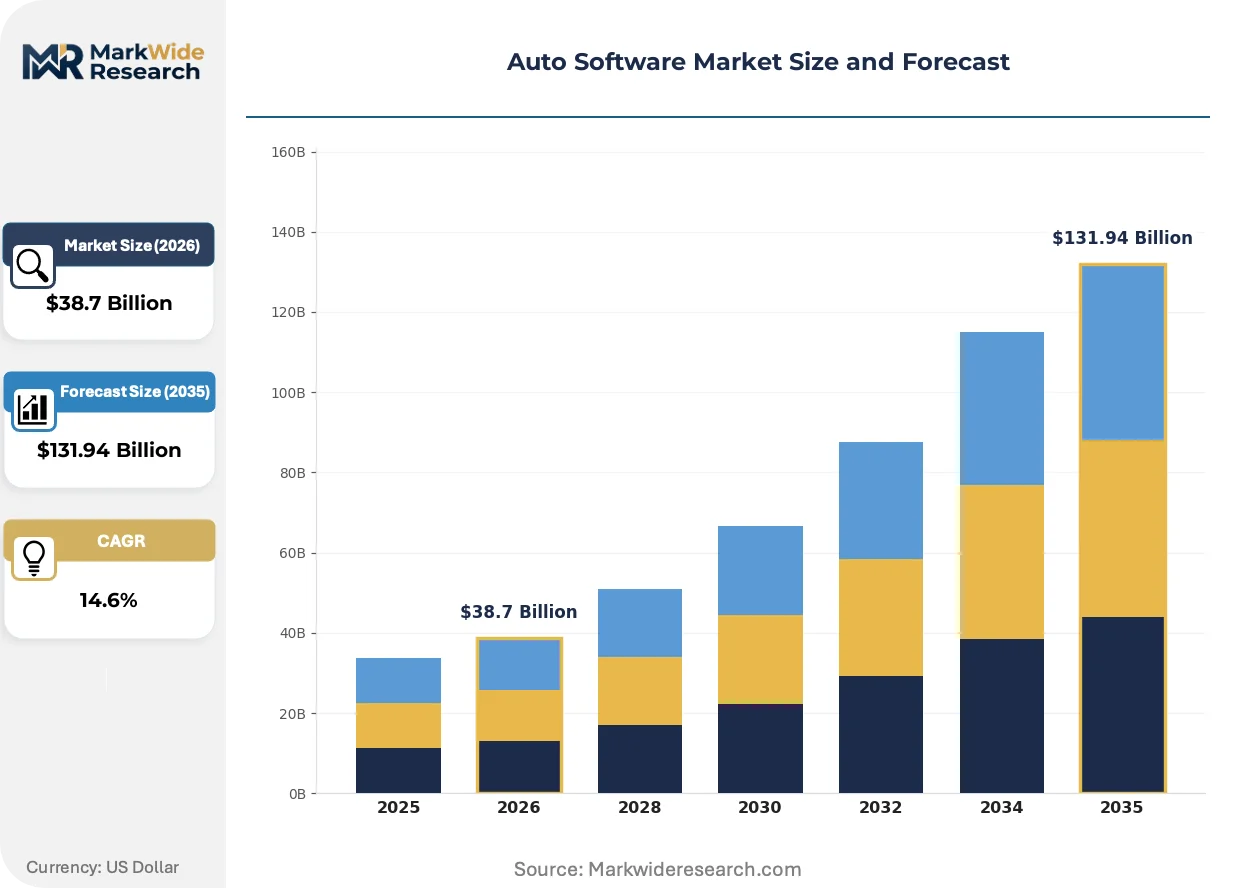
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $131.94 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Embedded Systems, Operating Systems, Middleware, Application Software Solution: Fleet Management, Telematics, Driver Assistance, Vehicle-to-Everything End User: OEMs, Automotive Service Providers, Aftermarket Suppliers, Rental Companies Technology: AI-Powered, Cloud-Based, Cybersecurity Solutions, Big Data Analytics |
| Companies Covered | Robert Bosch GmbH, NVIDIA Corporation, NXP Semiconductors, Continental AG, BlackBerry Limited, Elektrobit, Renesas Electronics Corporation, Microsoft Corporation, Wind River Systems, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Auto Software Market Trends and Innovations
Generative AI is penetrating automotive software workflows, compressing code generation and validation timelines. Virtualization technologies are decoupling software stacks from underlying silicon, enabling hardware-agnostic deployment.
Containerized middleware is electrifying the architecture of in-vehicle compute platforms. Tier-1 suppliers adopt Docker-based deployment for non-safety-critical applications, reducing integration testing overhead. This approach is compressing time-to-market for infotainment and connectivity features.
REACH and RoHS substance restrictions are reshaping semiconductor packaging choices for automotive-grade components. European suppliers must document full material transparency through supply tiers, elevating compliance costs for legacy chip designs. Powertrain control modules face the steepest reformulation requirements.
Fleet procurement is consolidating software sourcing decisions at the holding-company level rather than individual OEM divisions. Logistics operators now mandate API-standardized telematics platforms across mixed-brand vehicle pools. This concentration is most visible in German and Dutch commercial vehicle leasing markets.
Auto Software Market Segmentation
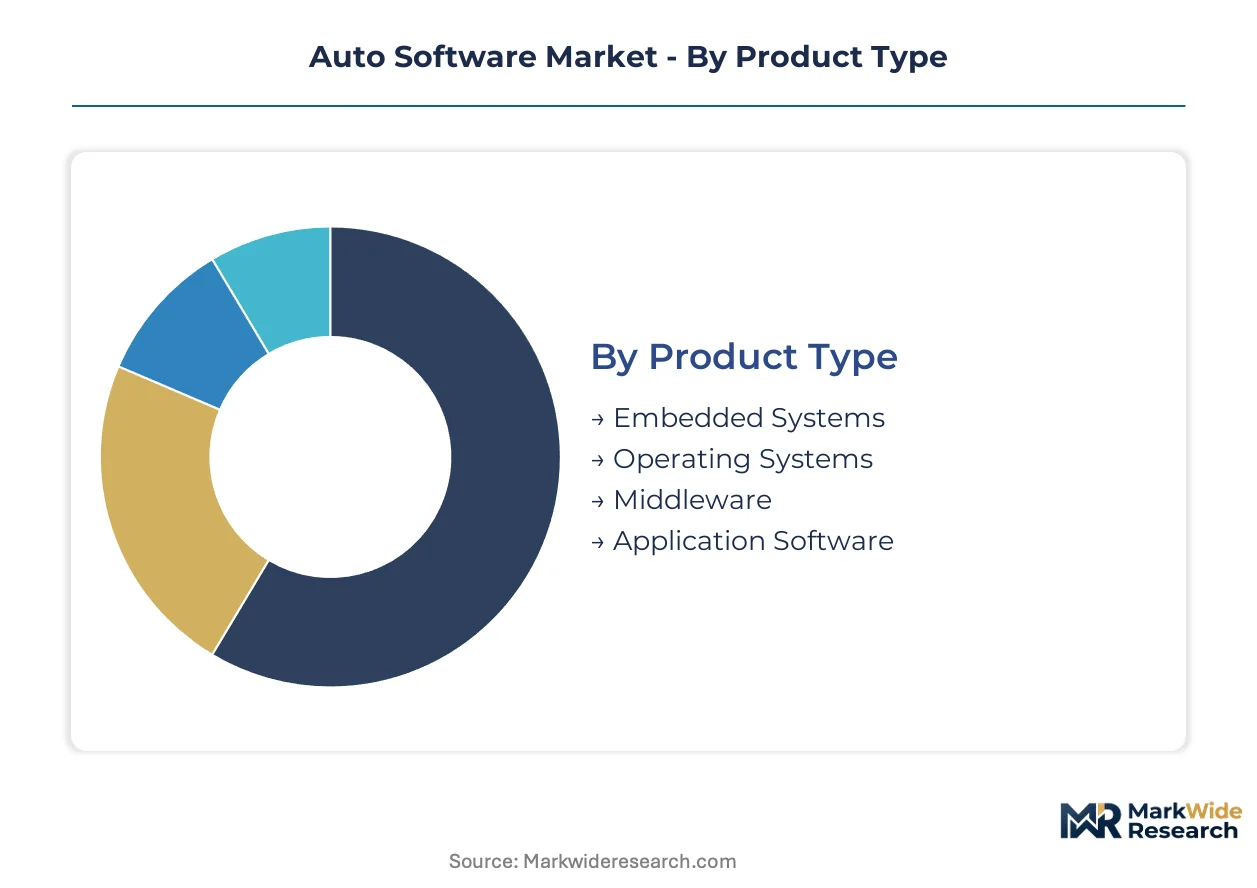
Software-defined vehicle architectures fragment procurement decisions across multiple technical and commercial dimensions. Certification requirements under UNECE WP.29 and the EU AI Act create divergent compliance burdens across segment categories, reshaping supplier qualification criteria.
Product Type:
Certification intensity varies sharply across this category, with safety-critical layers demanding ISO 26262 ASIL-D validation while application layers face lighter conformity assessment.
- Application Software:Encompasses infotainment platforms, digital cockpit interfaces, and subscription-enabled feature modules that deploy over-the-air. Demand concentrates among German premium OEMs monetizing personalized experiences through recurring billing models. This segment faces lighter functional safety mandates but carries GDPR and cybersecurity certification obligations under UNECE WP.29.
- Middleware:Serves as the abstraction layer between operating systems and applications, managing data routing and service orchestration across heterogeneous ECU networks. Stuttgart-based engineering clusters anchor development for this layer, driven by decoupling requirements from the EU AI Act's algorithm traceability provisions.
- Operating Systems:Real-time kernels and hypervisors governing task scheduling with deterministic latency guarantees.
- Embedded Systems:Firmware-level controllers executing powertrain and chassis functions with sub-millisecond response requirements.
Embedded systems sit at the top of the volume ranking, with application software climbing the fastest.
Solution:
Customer procurement scale determines cost tier positioning, with fleet operators commanding volume discounts unavailable to individual vehicle owners.
- Fleet Management:Combines predictive maintenance algorithms, route optimization engines, and asset tracking dashboards for logistics operators. German and Dutch commercial vehicle leasing markets anchor demand, driven by total cost of ownership reduction mandates and API-standardized telematics requirements across mixed-brand pools.
- Driver Assistance:Encompasses adaptive cruise control, lane-keeping systems, and automated parking functions requiring sensor fusion and real-time decision logic. Development concentrates in Munich and Wolfsburg engineering corridors, constrained by EU AI Act algorithm certification timelines and liability framework uncertainties.
- Telematics:Connectivity modules transmitting vehicle diagnostics and location data to cloud platforms.
- Vehicle-to-Everything:Communication stacks enabling direct data exchange between vehicles, infrastructure, and pedestrians.
Fleet management commands the steepest expansion trajectory, while telematics maintains the broadest installed base.
End User:
Integration complexity and liability exposure differentiate procurement patterns across customer types, with OEMs internalizing safety-critical development while outsourcing non-core functions.
- OEMs:Original equipment manufacturers consolidating software architecture ownership to capture recurring revenue streams and control update cadence. German automakers dominate internal development spending, driven by EU Green Deal procurement criteria favoring software-centric vehicle definitions.
- Automotive Service Providers:Independent repair networks and diagnostic specialists requiring standardized access to vehicle data and calibration tools. This segment is gaining regulatory support through right-to-repair legislation in multiple European jurisdictions.
- Aftermarket Suppliers:Third-party developers of retrofit infotainment and connectivity solutions.
- Rental Companies:Fleet operators prioritizing telematics integration and remote vehicle management capabilities.
OEMs retain the dominant procurement volume, with automotive service providers gaining share fastest.
Technology:
Investment allocation splits between performance-tier technologies commanding premium pricing and foundational capabilities requiring defensive spending.
- AI-Powered:Machine learning models for autonomous perception, predictive maintenance, and natural language interfaces. NVIDIA's DRIVE platform anchors development infrastructure, with European automakers accelerating verification tooling investment to satisfy EU AI Act conformity assessment requirements.
- Cybersecurity Solutions:Intrusion detection systems, secure boot mechanisms, and encryption protocols protecting over-the-air update pipelines. Regulatory pressure from UNECE WP.29 and divergent NHTSA guidance forces redundant engineering for global platform deployment.
- Cloud-Based:Offboard compute resources for data-intensive processing and fleet-scale analytics.
- Big Data Analytics:Pattern recognition engines extracting operational insights from vehicle telemetry streams.
AI-powered technologies lead R&D allocation, with cybersecurity solutions deepening most rapidly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Automotive software engineering first achieved industrial scale in Germany's Stuttgart and Wolfsburg corridors during the 1980s, when Bosch and Volkswagen pioneered electronic engine management. Today, development clusters span four continents with distinct regulatory and procurement characteristics.
Germany
Bosch, Continental, and Elektrobit anchor embedded systems development for powertrain and chassis domains. The EU AI Act and UNECE WP.29 cybersecurity regulations force 18-36 month certification cycles for autonomous algorithms. Stuttgart, Munich, and Wolfsburg concentrate safety-critical engineering talent commanding 40-60% wage premiums.
United States
NVIDIA's DRIVE platform dominates AI-powered autonomous development infrastructure across Detroit and Silicon Valley engineering centers. NHTSA software integrity mandates converge with European standards but retain distinct product liability precedents. Michigan and California host competing clusters for driver-assistance validation and cloud-based fleet analytics.
China
MIIT cybersecurity standards and GB protocol requirements shape domestic software architecture decisions for local OEMs. MIIT's software integrity mandates create parallel compliance burdens for global suppliers seeking market access. Shanghai and Shenzhen engineering centers focus on telematics and V2X communication stacks for smart city integration.
India
The PLI scheme for automotive electronics attracts software development centers to Bangalore and Pune for cost-optimized engineering. BIS certification requirements and TRAI data localization rules influence cloud architecture choices. These clusters supply middleware and application-layer development for European and North American Tier-1 suppliers.
Japan
Renesas Electronics and Toyota-affiliated engineering groups sustain real-time operating system expertise for safety-critical applications. METI industrial policy prioritizes autonomous driving and connected vehicle standards. Nagoya and Tokyo corridors concentrate embedded firmware development for hybrid powertrain control modules.
Auto Software Market Competitive Landscape
Premium-margin players sit above commodity-margin players across functional safety certification tiers, with ISO 26262 ASIL-D validation separating price-insensitive safety-critical suppliers from cost-pressured infotainment vendors. The vendor base clusters around three strategic archetypes: semiconductor-platform providers, Tier-1 embedded systems integrators, and specialized middleware developers. Dominant competitive moves include strategic partnerships for zonal architecture development and technology licensing for virtualization layers.
Within the semiconductor-platform tier, NVIDIA Corporation and NXP Semiconductors exemplify divergent positioning—NVIDIA occupying the AI-acceleration premium segment, NXP anchoring mixed-signal integration for body and powertrain domains. Among Tier-1 systems integrators, Robert Bosch GmbH and Continental AG represent the German engineering cluster's vertical depth across middleware and operating system layers. BlackBerry Limited sits within the specialized tier, its QNX heritage exemplifying safety-critical kernel expertise.
| Leading Market Players |
|---|
| Robert Bosch GmbH |
| NVIDIA Corporation |
| NXP Semiconductors |
| Continental AG |
| BlackBerry Limited |
| Elektrobit |
| Renesas Electronics Corporation |
| Microsoft Corporation |
| Wind River Systems |
| Others |
Pricing and Supply Chain Analysis
TSMC's 5nm wafer pricing cascades through automotive semiconductor procurement into three-tier pricing structures across premium, standard, and economy levels, with EU AI Act compliance costs compressing margins on mid-volume vehicle programs. German Tier-1 suppliers pass certification overhead to OEMs while absorbing foundry markups on advanced driver-assistance SoCs.
Pricing Analysis
Subscription-royalty hybrid models dominate safety-critical software layers, with ISO 26262 ASIL-D certification grade commanding 40-60% premiums over uncertified application code. Price differentiation separates infotainment vendors facing cost compression from embedded systems suppliers capturing defensive margins. Pricing pressure stems from semiconductor foundry concentration in Taiwan, squeezing mid-tier suppliers between raw material inflation and OEM procurement consolidation. Fleet operators exhibit lowest price sensitivity due to total cost of ownership frameworks, while aftermarket retrofitters face acute margin pressure from standardized telematics mandates.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale procurement for zonal architecture components, bypassing traditional distribution layers for software-defined vehicle platforms. Supply concentrates in Taiwan for advanced SoC fabrication, Germany for middleware development, and India for cost-optimized application engineering. Raw material dependencies span 5nm silicon wafers, automotive-grade memory modules, and rare earth elements for sensor packaging. Single-source vulnerability at TSMC's foundry capacity creates structural risk for European Tier-1 suppliers dependent on 7nm and 5nm process nodes.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Auto software markets offer margin-expansion pathways through subscription monetization of over-the-air features, offsetting hardware cost-down pressures from zonal architecture consolidation.
For Market Incumbents: Extend functional safety certification ownership into middleware layers to defend against emerging virtualization specialists. Deepen backward integration into real-time operating system kernels. Anchor capacity in Stuttgart and Munich engineering corridors to capture EU AI Act verification tooling demand. Certification investment in ISO 26262 ASIL-D scope expansion represents the critical defensive lever against margin erosion. For New Entrants and Emerging Players: Cloud-native development platforms offer the most penetrable entry vector for fleet management SaaS targeting German and Dutch logistics operators. Target API-standardized telematics procurement consolidating at holding-company level rather than individual OEM divisions. India PLI scheme incentives enable cost-optimized engineering delivery for European Tier-1 outsourcing demand. For Investors and Strategic Acquirers: Asymmetric upside sits with specialized middleware developers holding EU AI Act algorithm traceability tooling. Five-to-ten year viability hinges on regulatory compliance depth rather than feature velocity alone. Acquisition target archetype: virtualization-layer specialists with automotive safety-critical heritage. Watch for divergence between European AI liability frameworks and American product liability precedents as inflection signal for platform governance model investments.| Strategic Initiative | Industry Significance |
|---|---|
| Software-Defined Vehicle Investment | Enables recurring revenue streams through over-the-air feature deployment for German premium OEMs. |
| Platform Standardization | Reduces integration testing overhead across heterogeneous ECU networks from legacy vehicle generations. |
| Strategic Partnership | Accelerates zonal architecture development through NVIDIA DRIVE platform integration for autonomous perception. |
| Acquisition of Specialist Firm | Captures QNX heritage safety-critical kernel expertise for middleware layer consolidation. |
| Geographic Manufacturing Footprint | Leverages India PLI scheme incentives for cost-optimized application-layer engineering delivery. |
Research Methodology
Coverage spans Germany, United States, China, and India, with primary inputs from each regional cluster. Primary interviews engaged OEM platform engineers, Tier-1 supplier procurement leads, automotive software architects, and fleet management operators. Secondary validation drew from vehicle production databases, IHS Markit registration data, SEC filings from semiconductor suppliers, and EU regulatory filings under AI Act and UNECE WP.29 frameworks. Bottom-up segment modeling triangulated against top-down market sizing across product type, solution, end user, and technology dimensions.
Granularity-level modeling deployed vehicle-class, propulsion architecture, content per vehicle, OEM tier, and regional production cluster as segmentation dimensions. CAGRs derived from S-curve penetration analysis of software-defined vehicle adoption rates, weighted by regulatory mandate timelines across jurisdictions. Forecast inputs incorporated semiconductor foundry capacity allocation, embedded systems talent wage trajectories, and certification cycle duration estimates for functional safety validation.
Semiconductor supply disruption, regulatory divergence between NHTSA and EU AI Act liability frameworks, and embedded systems talent scarcity are the dominant revision risks to base-case projections. Forecasts reflect documented assumptions regarding zonal architecture transition speed and subscription monetization penetration. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
Global Open Source Services Market
Software & Services
Global Software Asset Management Market
Software & Services
Cemetery Software Market
Software & Services
Semiconductor Fabrication Software Market
Software & Services
CAM Software Market
Software & Services
Case Management Software (CMS) Market
Software & Services
Online Donation Software Market
Software & Services
Global Recruiting Software Market
Software & Services
North America Digital Marketing Software Market
Software & Services
Global Time Tracking Software Market
Software & Services
Electronic Design Automation Software Market
Software & Services
Shift Planning Software Market
Software & Services
Global Programming Software Market
Software & Services
Europe Enterprise Resource Planning (ERP) Software Market
Software & Services
Procurement Software Market
Software & Services
Life Sciences Software Market