
 Salesforce Services Market | 2026-2036
Salesforce Services Market Size, Share, and Industry Trends Forecast 2026-2036
Salesforce Services Market Outlook
Mid-market enterprises are redrawing the Salesforce services landscape as they shift from basic CRM deployment toward AI-powered automation and analytics. Accenture leverages its multi-cloud integration expertise to capture complex enterprise transformations. Capgemini anchors its position through industry-specific accelerators for financial services and healthcare clients. Deloitte differentiates via end-to-end advisory that connects Salesforce implementations with broader digital strategy and change management.
Salesforce services encompass the design, configuration, integration, and ongoing optimization of cloud-based customer relationship management platforms, typically involving API-driven connectivity with enterprise systems, data model customization, and workflow automation across sales, service, and marketing functions. These services enable organizations to unify customer data, automate revenue operations, and deploy predictive analytics for commercial decision-making. Implementation services currently occupy the largest revenue pool as enterprises undertake foundational platform builds, while integration services represent the fastest-expanding segment due to API proliferation and multi-cloud architectures. Among customer types, enterprises sustain the deepest consulting relationships, though startups are generating disproportionate growth in specialized configuration and training demand.
FDA data integrity requirements shape healthcare implementations by mandating audit trails and validation documentation for Salesforce deployments managing patient and clinical information. EMA guidelines and EU GDPR compliance frameworks drive European demand for certified architects who embed privacy-by-design into customer data architectures. Stakeholders must monitor how emerging AI governance standards from the EU AI Act and evolving state-level privacy laws in the US reshape certification requirements and implementation methodologies for intelligent CRM systems.
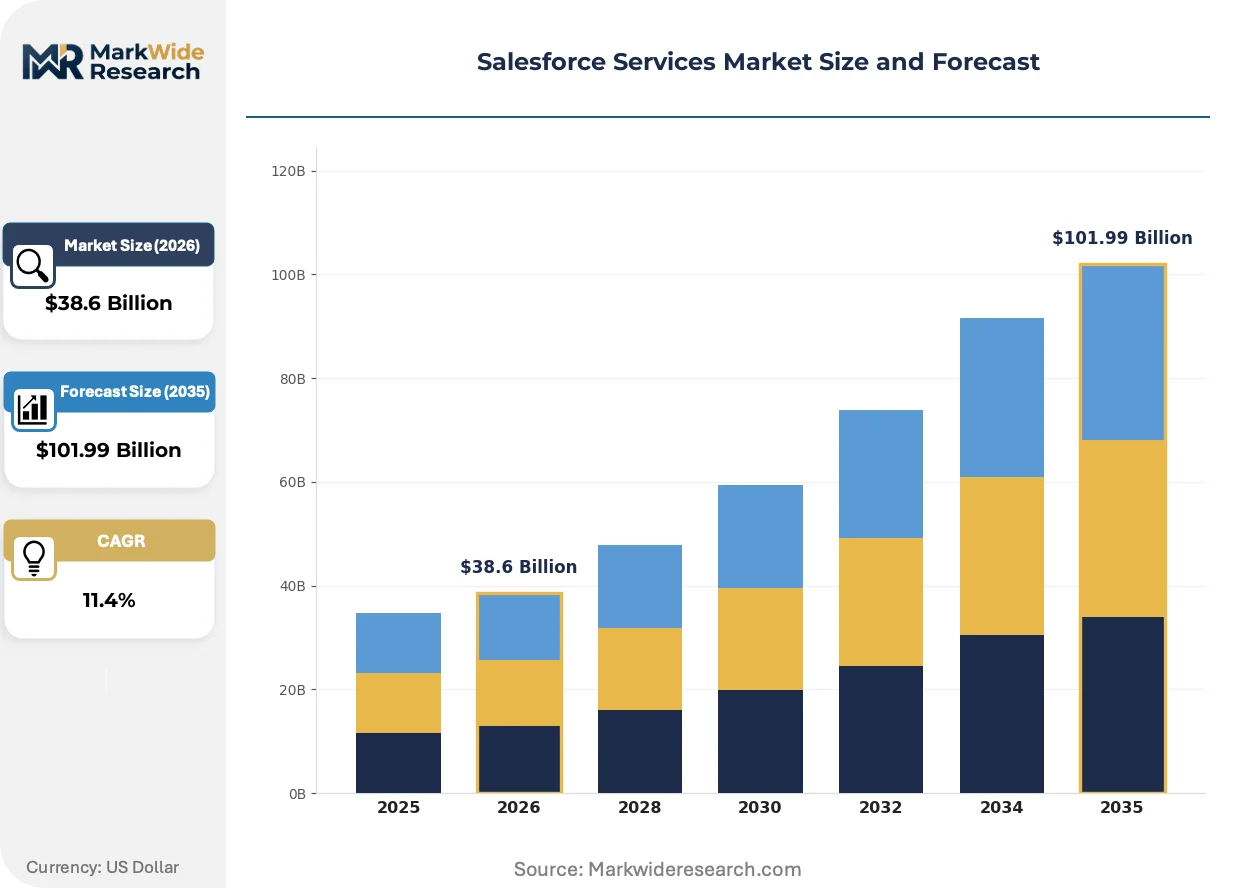
Market Dynamics
AI-powered automation is fragmenting traditional Salesforce implementation models as enterprises demand predictive analytics embedded directly into customer workflows rather than standalone CRM deployments.
Growth Catalysts
- EU AI Act cloud migration mandates:European enterprises must modernize customer data infrastructure by 2026, accelerating demand for certified Salesforce architects who embed privacy-by-design into AI-enabled CRM systems.
- Healthcare revenue cycle modernization:US hospitals and payers are replacing legacy patient management systems with unified platforms that integrate clinical, billing, and engagement data through Salesforce Health Cloud configurations.
- API proliferation:The average enterprise now operates 15+ cloud applications, creating sustained demand for integration specialists who connect Salesforce with ERP, data warehouse, and marketing automation stacks.
Market Restraints
- Certified talent scarcity:Salesforce-certified architects and developers command premium rates that inflate project costs by 40-60% versus generalist IT consultants, compressing margins for mid-tier implementation partners.
- Multi-cloud complexity:Enterprises running Salesforce alongside AWS, Azure, and Google Cloud face escalating integration debt as API versioning and security protocol mismatches multiply maintenance overhead.
- GDPR-EU AI Act compliance layering:European implementations require simultaneous adherence to data residency, algorithmic transparency, and audit trail mandates, extending project timelines and documentation burden.
Strategic Opportunities
- India mid-market penetration:PLI scheme incentives for digital transformation are driving manufacturing and financial services firms toward cloud CRM adoption, with implementation demand growing faster than certified partner supply.
- Agentic AI convergence:Salesforce Einstein GPT integrated with autonomous workflow engines enables proactive customer intervention, opening new advisory revenue streams for partners who configure predictive service models.
- Outcome-based pricing models:Risk-sharing contracts tied to customer acquisition cost reduction or churn rate improvement are displacing time-and-materials billing, aligning vendor incentives with client success metrics.
Industry Challenges
- Data architecture skill gaps:Shortage of practitioners who can design unified customer data models across Salesforce Data Cloud, Snowflake, and proprietary lakehouses delays enterprise-scale deployments.
- Validation documentation burden:FDA 21 CFR Part 11 requirements for healthcare and life sciences implementations demand extensive IQ/OQ/PQ protocols that extend project phases by 4-8 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Salesforce Services Market |
| Market Size in 2026 | $38.6 Billion |
| Market Size in 2035 | $101.99 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Implementation, Integration, Consulting, Training Customer Type: Small Businesses, Enterprises, Non-Profits, Startups Deployment Model: Public Cloud, Private Cloud, Hybrid Cloud, On-Premise Industry Vertical: Healthcare, Finance, Retail, Education |
| Companies Covered | Accenture, Capgemini, Cognizant, Tata Consultancy Services (TCS), Infosys, IBM, Deloitte, Reply, TTMS (Transition Technologies Managed Services), Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Salesforce Services Market Strategic Shifts
Composable architecture principles are displacing monolithic CRM deployments as enterprises prioritize modular, API-first customer data platforms that adapt to shifting channel requirements.
Low-code workflow automation is fragmenting traditional Salesforce development by enabling business analysts to configure complex approval chains and data transformations without engineering support. Mid-market healthcare and financial services organizations are adopting these tools fastest, compressing implementation cycles from 12 months to 6-8 weeks for standard use cases. This democratization is eroding the premium that pure technical configurators once commanded, forcing partners to differentiate through industry-specific IP and change management expertise.
EU AI Act algorithmic transparency requirements are mandating explainable AI documentation for Salesforce Einstein predictions used in credit scoring, patient triage, and insurance underwriting. European financial services and healthcare enterprises must now maintain model cards and bias audit trails that satisfy both GDPR data protection impact assessments and AI Act conformity assessments. Certified consulting partners who build automated documentation pipelines into their deployment methodologies are capturing preferred vendor status with compliance-conscious buyers.
Subscription fatigue among enterprise buyers is compressing Salesforce contract renewal cycles and intensing scrutiny of utilization rates. Procurement functions in US healthcare systems and German manufacturing conglomerates are unbundling platform licenses from implementation services, negotiating direct with Salesforce while competitively tendering configuration work to regional specialists. This disintermediation is fragmenting the traditional systems integrator model and elevating niche partners who demonstrate vertical-specific accelerators and faster time-to-value proofs.
Salesforce Services Market Segmentation
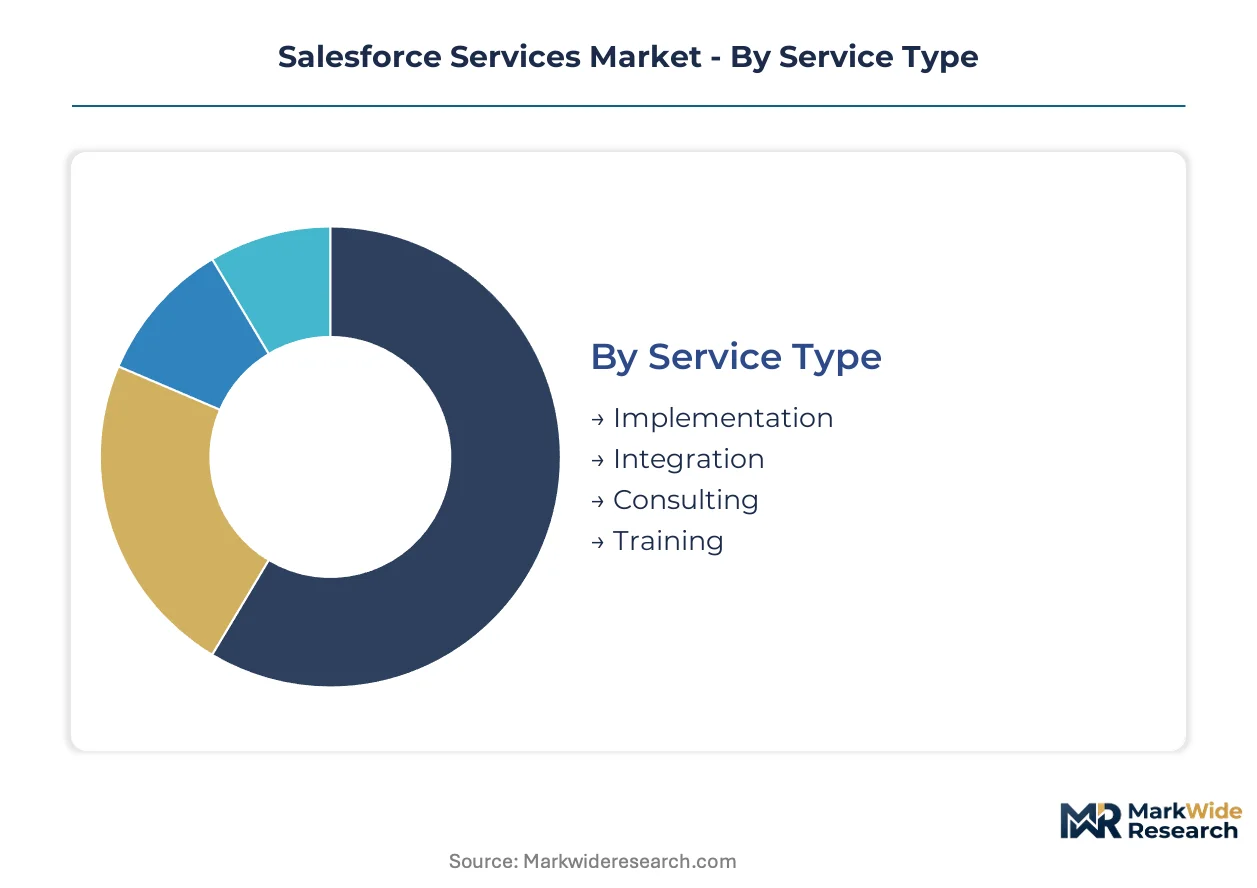
Salesforce services fragment along four distinct axes that determine pricing power, project complexity, and partner selection criteria. Service type and customer size shape revenue concentration, while deployment model and industry vertical dictate regulatory exposure and technical architecture requirements.
Service Type:
Implementation services concentrate in domestic US healthcare and financial services modernization programs. Integration demand spreads across European multi-cloud environments subject to GDPR and EU AI Act mandates.
- Implementation:Foundational platform builds encompassing data model customization, workflow automation, and security configuration. US hospitals and payers drive sustained demand through Health Cloud deployments replacing legacy patient management infrastructure. FDA 21 CFR Part 11 validation protocols extend project timelines significantly.
- Integration:API-driven connectivity with ERP, data warehouse, and marketing automation stacks. European enterprises facing cloud migration deadlines under EU AI Act compliance frameworks generate the steepest growth trajectory as multi-cloud architectures proliferate.
- Consulting:Strategic advisory connecting Salesforce deployments with broader digital transformation roadmaps.
- Training:Certification programs and change management support for internal administrator enablement.
Implementation commands the established base. The steepest expansion runs through Integration.
Customer Type:
Enterprise relationships sustain the deepest consulting engagements and longest contract durations. Startup demand concentrates in rapid configuration and specialized training for venture-backed scale-ups.
- Enterprises:Complex multi-year transformations requiring dedicated account teams and industry-specific accelerators. Healthcare systems and financial institutions in the United States anchor this segment through revenue cycle modernization and customer data unification initiatives.
- Startups:Disproportionate growth in specialized configuration demand as venture-backed firms prioritize speed-to-deployment over customization depth. India mid-market penetration through PLI scheme incentives amplifies this segment's expansion rate.
- Small Businesses:Standardized package implementations with limited customization scope.
- Non-Profits:Discounted licensing programs driving basic CRM adoption for donor management and volunteer coordination.
Enterprises anchor revenue stability. Startups generate the most rapid volume acceleration.
Deployment Model:
Public cloud dominates new adoption while hybrid configurations address data residency requirements in regulated European and US healthcare environments.
- Public Cloud:Native Salesforce infrastructure delivering automatic updates and elastic scalability. Mid-market retail and education organizations in the United States favor this model for cost predictability and minimal IT overhead.
- Hybrid Cloud:Split architectures separating customer engagement data in cloud from sensitive records in controlled environments. European financial services firms under GDPR and EU AI Act mandates drive specialized demand for certified architects who embed privacy-by-design.
- Private Cloud:Dedicated single-tenant instances for organizations with stringent isolation requirements.
- On-Premise:Legacy installations persisting in defense and classified government contexts with air-gapped security requirements.
Public cloud captures volume leadership. Hybrid deployments climb the fastest as compliance layering intensifies.
Industry Vertical:
Healthcare implementations carry the highest regulatory burden and documentation requirements. Finance generates premium pricing for risk-sensitive AI-enabled CRM configurations.
- Healthcare:Health Cloud deployments integrating clinical, billing, and patient engagement data. FDA data integrity requirements mandate audit trails and IQ/OQ/PQ validation documentation that extends project phases substantially. US hospital systems and European pharmaceutical companies dominate demand.
- Finance:Einstein GPT deployments for credit scoring and insurance underwriting subject to algorithmic transparency mandates. EU AI Act conformity assessments and GDPR data protection impact assessments create specialized consulting opportunities for automated documentation pipelines.
- Retail:Commerce Cloud and Service Cloud configurations for omnichannel customer experience unification.
- Education:Student lifecycle management and alumni engagement platforms with lighter compliance requirements.
Healthcare sustains the deepest implementation relationships. Finance delivers the fastest value-per-project expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Certified Salesforce architects concentrate in the United States, the United Kingdom, Germany, and India, with demand patterns shaped by distinct regulatory mandates and cloud migration timelines across each jurisdiction.
United States
Healthcare systems and financial institutions drive sustained implementation demand through Health Cloud and Einstein GPT deployments. FDA 21 CFR Part 11 requirements mandate extensive validation documentation for patient data systems. The Boston-Cambridge corridor anchors specialized consulting density for life sciences configurations.
United Kingdom
Financial services firms modernize customer data infrastructure ahead of evolving algorithmic transparency standards. The Financial Conduct Authority's operational resilience rules pressure legacy system replacements. London's fintech cluster generates concentrated demand for integration specialists connecting Salesforce with banking cores.
Germany
Industrial conglomerates and automotive suppliers pursue GDPR-compliant customer data unification across distributed operations. The KBA and BSI frameworks influence secure cloud architecture requirements. The Munich-Stuttgart axis hosts the densest concentration of certified architects serving manufacturing verticals.
India
Mid-market manufacturing and financial services firms accelerate cloud CRM adoption under PLI scheme incentives. RBI guidelines on data localization shape hybrid deployment preferences. Bengaluru and Hyderabad emerge as primary delivery hubs where implementation demand outpaces certified partner supply.
France
Healthcare and insurance enterprises navigate CNIL enforcement of GDPR data protection impact assessments for AI-enabled CRM. The ANSM's pharmacovigilance requirements extend to Salesforce deployments managing clinical relationships. The Paris-Saclay cluster concentrates specialized consulting for regulated industries.
Salesforce Services Market Competitive Environment
Concentration sits with global systems integrators who embed multi-cloud expertise and industry-specific accelerators into their service architectures. The vendor base organizes into three strategic tiers: full-service transformation partners commanding complex enterprise engagements, mid-tier specialists competing on vertical depth and speed-to-deployment, and regional boutiques capturing standardized configuration work. Dominant competitive moves include vertical acquisition of niche Salesforce consultancies and strategic partnerships with hyperscale cloud providers to secure preferred architecture status.
Within the full-service transformation tier, Accenture, Deloitte, and Capgemini exemplify the archetype of multi-cloud integration specialists who capture enterprise-scale implementations through dedicated industry verticals. Accenture represents the scale-driven consolidation model with embedded Health Cloud and Financial Services Cloud accelerators. Deloitte occupies a position connecting Salesforce deployments with broader digital strategy advisory and organizational change management. Capgemini anchors the European-centric delivery model with concentrated expertise in GDPR and EU AI Act compliance layering. These three entities collectively demonstrate how certification density and regulatory specialization determine competitive positioning in regulated verticals.
| Leading Market Players |
|---|
| Accenture |
| Capgemini |
| Cognizant |
| Tata Consultancy Services (TCS) |
| Infosys |
| IBM |
| Deloitte |
| Reply |
| TTMS (Transition Technologies Managed Services) |
| Others |
Value Chain & Pricing Dynamics
Certified architect density in India and Eastern Europe creates asymmetric scale economies that compress delivery costs for mid-tier implementation partners while elevating price floors for GDPR-validated engagements in Germany and France. This geographic concentration of credentialed talent simultaneously anchors supply-side capacity and stratifies pricing power across compliance-tiered service lines.
Pricing Analysis
Volume-discount tiering structures separate enterprise Health Cloud implementations from mid-market standard configurations and startup rapid-deployment packages. Price differentiation hinges on Salesforce certification tier—Technical Architect credentials command substantial premiums over Administrator-level engagements—and vertical specialization depth, with FDA-validated healthcare deployments carrying documentation surcharges. Cost compression in the mid-market tier is intensifying because low-code automation tools enable business analysts to displace certified developers for standard workflow configurations. Startup buyers exhibit acute price sensitivity and unbundle platform licenses from implementation services, while US hospital systems prioritize compliance assurance over rate negotiation.
Supply Chain Analysis
Inbound logistics costs for specialized healthcare and financial services accelerators remain minimal given the knowledge-intensive nature of Salesforce services, though talent mobility between Bengaluru and Hyderabad delivery hubs affects project staffing velocity. Supply concentrates in India for implementation scale, the United States for domain expertise, and Germany for compliance architecture. The talent pipeline draws from computer science graduates, existing Salesforce administrators seeking credential advancement, and ERP specialists cross-training on cloud CRM platforms. Single-source vulnerability manifests in certified Technical Architect scarcity, with demand outstripping accredited supply by substantial margins. Distribution runs through direct enterprise sales, hyperscaler marketplace listings, and regional system integrator partnerships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
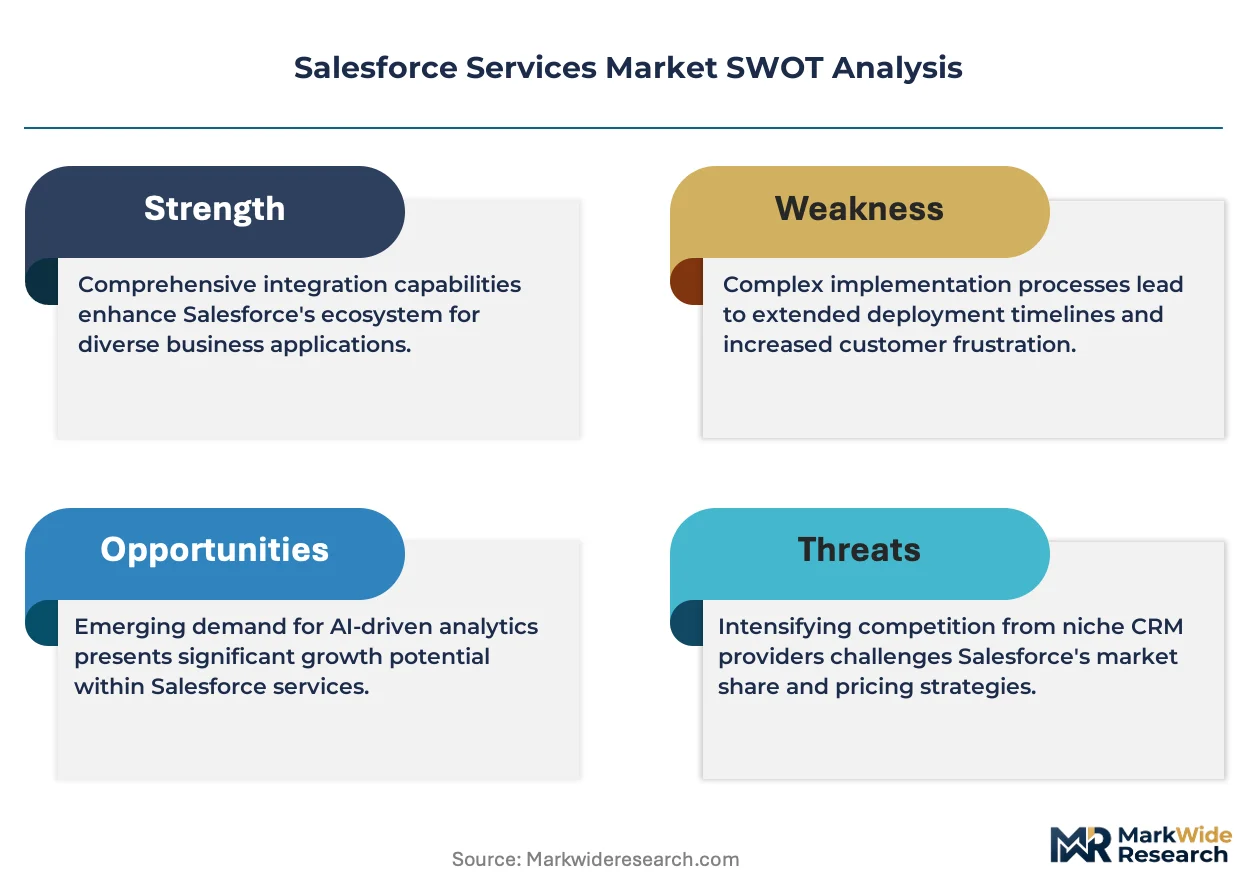
Salesforce services constitute a platform-economics inflection where API proliferation and multi-cloud interoperability are displacing monolithic CRM deployment models, with ecosystem orchestration capability determining vendor survival.
For Market Incumbents: Secure certification density in EU AI Act and GDPR compliance architecture to defend margin position against mid-tier specialists automating standard configurations. Invest in Health Cloud and Financial Services Cloud accelerators that embed FDA validation protocols and algorithmic transparency documentation pipelines. Channel control through hyperscaler marketplace preferred status represents a critical lever against disintermediation.
For New Entrants and Emerging Players: Salesforce Technical Architect certification fast-tracks enable rapid credibility establishment with European financial services buyers facing algorithmic transparency mandates. White-space targets include India mid-market manufacturing firms under PLI scheme incentives and US healthcare regional networks modernizing revenue cycle infrastructure. A vertical-specific accelerator strategy—pre-built patient engagement workflows or credit scoring model documentation templates—accelerates time-to-first-revenue versus generalist positioning.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors specialized consultancies with automated compliance documentation IP and captive certification pipelines over pure staff-augmentation models. Long-term viability rests on outcome-based pricing adoption and Einstein GPT integration capability. Acquisition target archetypes demonstrate vertical accelerators, certified architect bench depth, and established FDA or EMA validation methodologies. The signal to watch is Salesforce's Agentic AI roadmap disclosure and partner certification requirements for autonomous workflow deployment.
| Strategic Initiative | Industry Significance |
|---|---|
| Vertical Accelerator Development | Pre-built Health Cloud configurations reduce FDA validation timelines for hospital system implementations. |
| Compliance Automation Investment | Automated EU AI Act documentation pipelines capture preferred vendor status with European financial services buyers. |
| Outcome-Based Pricing Transition | Risk-sharing contracts tied to customer acquisition cost reduction align vendor incentives with client success metrics. |
| Hyperscaler Partnership Deepening | Preferred architecture status with AWS and Azure secures integration project referrals for multi-cloud environments. |
| India Delivery Hub Expansion | Bengaluru and Hyderabad talent concentration addresses certified architect scarcity for mid-market penetration. |
Study Parameters
A spread of perspectives from Salesforce implementation directors, healthcare CIOs modernizing patient management infrastructure, financial services compliance officers, and certified Technical Architects converged on the working assumptions driving this analysis. Primary fieldwork combined structured interviews with secondary validation against SEC filings from major systems integrators, Salesforce partner program tier disclosures, FDA 21 CFR Part 11 guidance documents, and EU AI Act implementation timelines. Bottom-up project pipeline analysis across service type and customer size segments was triangulated against top-down addressable market sizing from cloud CRM adoption curves.
Segmentation dimensions modeled encompass service type, customer size, deployment model, and industry vertical with particular attention to healthcare and financial services regulatory exposure. The analytical framework projects demand evolution across the analysis window by applying adoption elasticity coefficients to cloud migration mandates and AI governance compliance deadlines. CAGRs were derived from weighted average growth rates across segment-specific demand curves, with inputs including certified partner capacity expansion, low-code automation penetration rates, and outcome-based pricing adoption velocity.
Decision-makers should treat outputs as directional under assumptions of sustained EU AI Act enforcement timelines and stable Salesforce platform roadmap commitment; material deviation would warrant model refresh. Specific risk factors include abrupt certification requirement changes, hyperscaler competitive encroachment on implementation services, and regional data localization mandates that fragment delivery architectures. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
K8s Market
Software & Services
Ground Handling Software Market
Software & Services
Instant Messaging Software Market
Software & Services
Building Information Modeling (BIM) Extraction Software Market
Software & Services
North America Workforce Management Software Market
Software & Services
Audio and Video Editing Software Market
Software & Services
Global Email Management Software Market
Software & Services
Electronic Batch Records Market
Software & Services
Lead Management Software Market
Software & Services
Global OEE Software Market
Software & Services
Europe HR Payroll Software Market
Software & Services
Human Resource Management Software Market
Software & Services
North America Saas-Based Expense Management Market
Software & Services
Collaborative Whiteboard Software Market
Software & Services
Global Online Survey Software Market
Software & Services
Global Managed File Transfer Software Market