
 Software Consulting Market | 2026-2036
Software Consulting Market Size, Share, and Industry Trends Forecast 2026-2036
Software Consulting Market Intelligence
The shortage of cloud architects and AI engineers is rotating project timelines toward longer engagements and higher bill rates. EPAM Systems leverages its Eastern European delivery centers to sustain cost-competitive talent pipelines. Thoughtworks differentiates through agile methodology depth and social impact positioning. ScienceSoft anchors mid-market revenue through fixed-price healthcare and fintech contracts.
Software consulting encompasses advisory, implementation, and managed services for enterprise application architecture, spanning code-level development through board-level digital strategy. Practitioners deliver functional specifications, integration protocols, and security compliance frameworks that translate business requirements into deployable systems. Custom Software Development and Cloud Migration command the largest revenue pools within Service Type, while Artificial Intelligence and Cybersecurity segments within Technology Focus attract premium pricing due to capability scarcity. The Dedicated Team engagement model is displacing fixed-price structures for clients with multi-year transformation roadmaps.
FDA 21 CFR Part 11, EU GDPR, and SEC cybersecurity disclosure rules shape compliance-driven consulting demand across life sciences, data-intensive industries, and publicly traded clients. ISO 27001 certification has become a baseline qualifier for vendor selection in regulated sectors. Stakeholders must monitor how generative AI tooling alters the labor mix between junior consultants and automated code generation platforms.
Market Dynamics
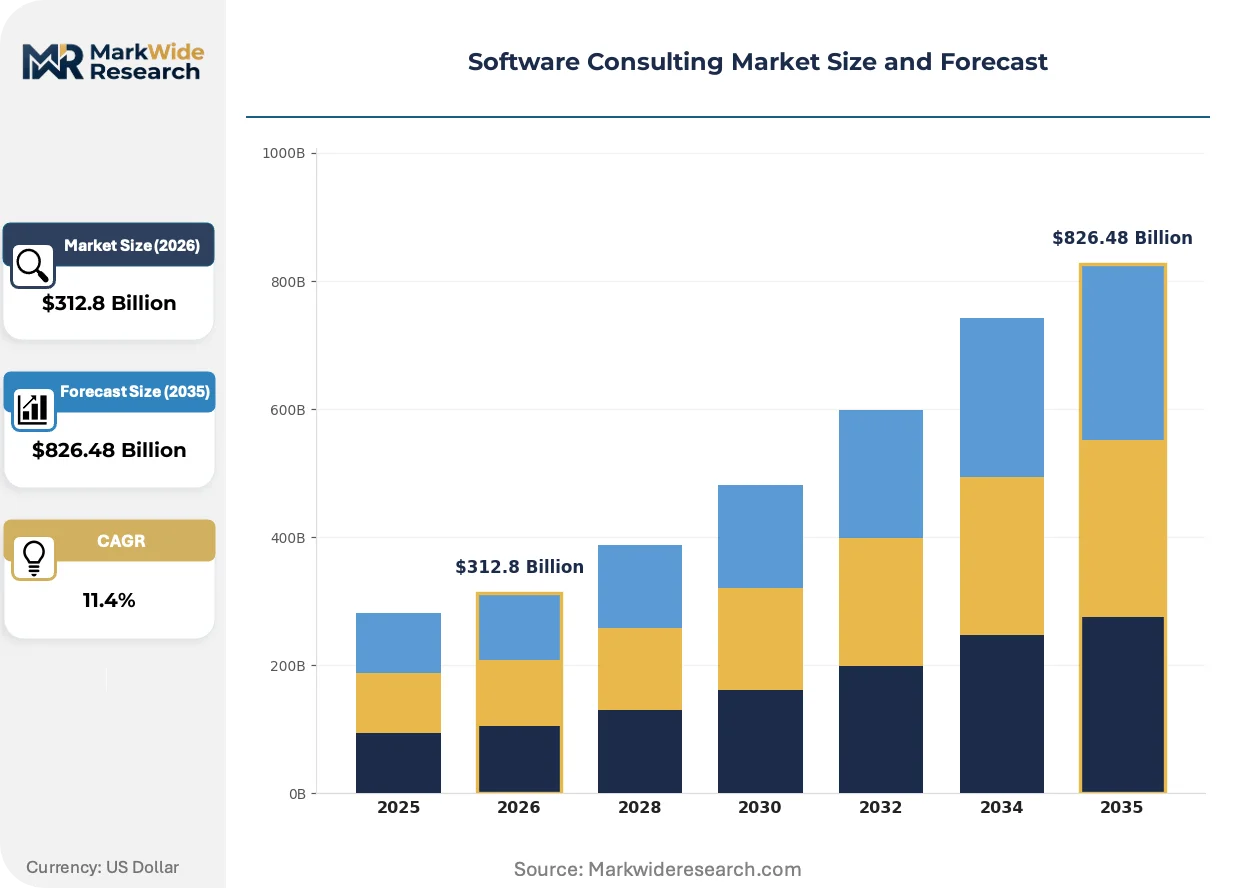
The Dedicated Team engagement model is displacing fixed-price structures as clients with multi-year transformation roadmaps seek flexibility over cost certainty. Cloud migration and AI integration mandates from financial services firms are compressing project timelines while extending contract durations.
Growth Catalysts
- EU AI Act compliance deadlines:European banking clients are expanding advisory budgets for algorithmic auditing and risk classification frameworks. Procurement criteria now prioritize vendors with documented conformity assessment procedures.
- Industry 4.0 implementation gaps:Germany's Mittelstand manufacturers lack internal digital expertise and are outsourcing entire smart factory architectures to specialized consultancies.
- FDA 21 CFR Part 11 validation requirements:Life sciences companies require electronic record and signature systems that demand specialized compliance consulting for audit trails and data integrity protocols.
Market Restraints
- Cloud architect scarcity:The shortage of certified AWS, Azure, and GCP specialists in Western Europe and North America is inflating bill rates and extending project kickoff delays by 4-8 weeks.
- ISO 27001 certification barriers:Smaller consultancies face capital-intensive security infrastructure investments to meet baseline vendor qualification requirements in regulated sectors.
- Generative AI code generation:Automated programming tools threaten to commoditize junior consultant labor pools that traditionally staffed implementation-heavy engagements.
Strategic Opportunities
- SEC cybersecurity disclosure rules:Publicly traded clients must report material cybersecurity incidents within four business days, creating sustained demand for incident response retainers and board-level advisory.
- Cybersecurity-Cloud convergence:Zero-trust architecture implementations combined with multi-cloud orchestration represent white-space service bundles that few competitors have packaged.
- Eastern European delivery expansion:Poland, Romania, and Ukraine offer cost-competitive engineering talent pipelines for Western European clients seeking nearshore alternatives to Indian offshore models.
Industry Challenges
- Agile methodology standardization:Clients demand SAFe or Scrum certification credentials that require continuous training investment and create personnel retention vulnerabilities.
- Legacy ERP integration complexity:SAP S/4HANA and Oracle Cloud migrations require specialized functional knowledge that sits with aging consultant populations approaching retirement.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Software Consulting Market |
| Market Size in 2026 | $312.8 Billion |
| Market Size in 2035 | $826.48 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Custom Software Development, System Integration, Application Management, Cloud Migration, IT Strategy Consulting, Change Management Technology Focus: Artificial Intelligence, Blockchain, Internet of Things, Big Data Analytics, Cybersecurity, Robotic Process Automation Client Type: Startups, Small and Medium Enterprises, Large Enterprises, Nonprofit Organizations Engagement Model: Time and Material, Fixed Price, Dedicated Team, Outcome-Based, Managed Services |
| Companies Covered | Thoughtworks, SoftTeco, EPAM Systems, Improving, Radixweb, ScienceSoft, Intellias, SCAND, Innowise, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Software Consulting Market Strategic Shifts & Innovations
Generative AI tooling is fundamentally altering the labor composition within consulting engagements. Automation of code generation, documentation, and testing protocols is compressing junior staffing ratios while elevating demand for architectural oversight and client relationship management.
Edge computing infrastructure is miniaturizing data processing requirements for manufacturing and healthcare clients. Automotive OEMs and hospital networks are deploying containerized microservices directly on factory floors and clinical devices. This distributed architecture is miniaturizing the traditional centralized cloud migration project scope into discrete, repeatable edge deployment modules that consultancies productize as subscription offerings.
The EU AI Act risk classification system is mandating conformity assessments for high-risk AI applications in credit scoring, recruitment, and medical diagnostics. Banking and HR technology vendors must document algorithmic transparency and human oversight mechanisms. German automotive suppliers and French insurance groups are engaging consultancies to build model cards, bias testing protocols, and governance committees before product launch deadlines.
Enterprise buyers are unbundling managed services from implementation contracts. Healthcare systems and mid-market manufacturers now source cloud architecture design separately from ongoing operational support. This disaggregation is most pronounced in the United States, where CIOs cite cost transparency and vendor accountability as primary drivers for multi-sourcing strategies that fragment traditional end-to-end consulting relationships.
Software Consulting Market Segmentation
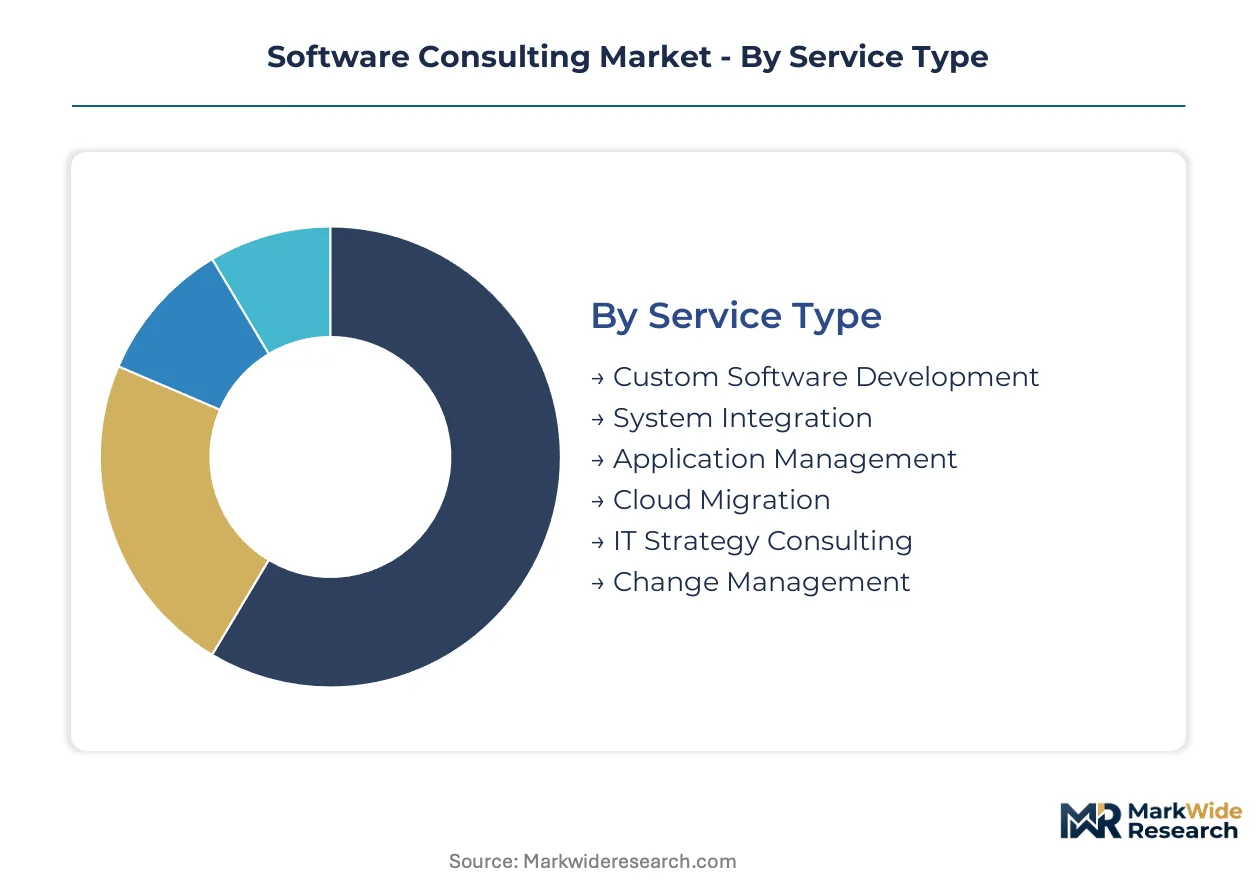
Segmentation in software consulting reveals how procurement patterns and margin structures diverge across service delivery modes and technology specializations. Buyers match engagement models to transformation maturity, while technology focus determines pricing premiums and talent scarcity.
Service Type:
Margin pools concentrate in implementation-heavy segments where specialized labor commands premium bill rates and multi-year contract visibility.
- Custom Software Development:Tailored application builds spanning mobile, web, and enterprise platforms with proprietary codebases. Financial services firms in Germany and the United States drive demand for trading platforms and customer-facing digital products under EU AI Act and SEC compliance deadlines. Scarcity of full-stack engineers with domain expertise sustains pricing power.
- Cloud Migration:Lift-and-shift infrastructure transitions plus cloud-native re-architecture for AWS, Azure, and GCP environments. Mittelstand manufacturers outsource entire migration programs due to internal capability gaps, creating sustained demand for German-speaking delivery teams with ISO 27001 credentials.
- System Integration:API orchestration and middleware deployment connecting legacy ERP to modern SaaS stacks.
- Application Management:Ongoing maintenance, patching, and performance optimization for deployed software assets.
- IT Strategy Consulting:Board-level digital roadmaps and technology investment prioritization.
- Change Management:Organizational redesign and workforce transition programs accompanying technology deployments.
The dominant share belongs to Custom Software Development, while Cloud Migration is closing the gap fastest.
Technology Focus:
Application intensity varies sharply by sector, with regulated industries paying steep premiums for compliance-validated expertise.
- Artificial Intelligence:Machine learning model development, MLOps infrastructure, and algorithmic auditing for high-risk applications under EU AI Act classification. French insurance groups and German automotive suppliers engage consultancies for bias testing protocols and model cards before product launches.
- Cybersecurity:Zero-trust architecture, incident response, and SEC disclosure readiness for publicly traded clients. The four-business-day incident reporting mandate creates retainer-based revenue visibility.
- Big Data Analytics:Data lake architecture and real-time processing pipelines.
- Internet of Things:Edge computing deployments for manufacturing floors and clinical devices.
- Robotic Process Automation:Workflow automation for back-office finance and HR functions.
- Blockchain:Distributed ledger implementations for supply chain traceability and digital identity.
Artificial Intelligence captures the largest premium tier, with Cybersecurity expanding most quickly on regulatory tailwinds.
Client Type:
Contract structures and sales cycles diverge dramatically across organizational scale and procurement sophistication.
- Large Enterprises:Multi-year transformation programs with dedicated team engagements and outcome-based pricing. German banking clients structure algorithmic auditing contracts around EU AI Act conformity assessment milestones.
- Small and Medium Enterprises:Fixed-scope projects with compressed timelines and standardized deliverables. Mid-market manufacturers favor fixed-price healthcare and fintech contracts with defined acceptance criteria.
- Startups:Equity-linked or deferred compensation structures with high-risk, high-reward profiles.
- Nonprofit Organizations:Grant-funded capacity building with constrained budgets and open-source technology preferences.
Large Enterprises dominate contract value, while Small and Medium Enterprises are gaining share fastest on Industry 4.0 outsourcing trends.
Engagement Model:
Pricing mechanics and risk allocation shift as clients prioritize flexibility over cost certainty in multi-year roadmaps.
- Dedicated Team:Long-term staff augmentation with monthly billing and direct client oversight. Financial services firms expanding cloud migration and AI integration mandates favor this structure for roadmap flexibility.
- Fixed Price:Scope-bound deliverables with defined acceptance criteria and vendor risk absorption. Healthcare systems and mid-market manufacturers use this for budget predictability on discrete implementation phases.
- Time and Material:Hourly or daily billing for exploratory or undefined scope engagements.
- Outcome-Based:Performance-linked compensation tied to measurable business metrics.
- Managed Services:Ongoing operational support with SLA-governed service levels.
Dedicated Team structures hold the largest share, with Outcome-Based models climbing the fastest as procurement teams demand accountability.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
SEC cybersecurity disclosure rules anchor the United States as the dominant geography, mandating four-day incident reporting windows that sustain retainer demand. German regulators enforce EU AI Act conformity assessments that reshape procurement across Mittelstand manufacturers. British financial services firms expand algorithmic auditing budgets under FCA supervision.
United States
Financial services firms in New York and Chicago compress cloud migration timelines while extending contract durations for AI integration mandates. SEC disclosure requirements for material cybersecurity incidents create sustained demand for incident response retainers and board-level advisory services. The Boston-Cambridge corridor concentrates healthcare consulting for FDA 21 CFR Part 11 validation protocols.
Germany
Mittelstand manufacturers in Baden-Württemberg and Bavaria outsource entire Industry 4.0 smart factory architectures due to internal digital expertise gaps. KBA and EU AI Act compliance deadlines drive algorithmic auditing contracts with documented conformity assessment procedures. Stuttgart's automotive supplier cluster engages consultancies for bias testing protocols and model governance committees.
United Kingdom
London-based banking clients structure procurement around FCA expectations for algorithmic transparency in credit scoring and recruitment applications. GDPR enforcement by the Information Commissioner's Office elevates ISO 27001 certification to baseline vendor qualification. The Manchester-Leeds corridor concentrates mid-market fintech consulting for cloud-native re-architecture.
Poland
Warsaw and Krakow delivery centers supply cost-competitive engineering talent pipelines for Western European clients seeking nearshore alternatives. Polish consultancies capture German-speaking cloud migration contracts requiring ISO 27001 credentials and EU AI Act readiness. The Wrocław technology cluster specializes in SAP S/4HANA integration for aging ERP estates.
India
Bangalore and Hyderabad delivery hubs sustain implementation-heavy engagements for global financial services firms despite generative AI automation threats. RBI guidelines on cybersecurity frameworks for regulated entities create compliance-driven demand for zero-trust architecture consulting. The Mumbai-Pune corridor concentrates healthcare and fintech fixed-price contracts with defined acceptance criteria.
Software Consulting Market Key Industry Players
A small set of integrated leaders sits above a broader specialist tier that fragments across technology focus areas and geographic delivery models. The upper tier captures multi-year transformation programs with dedicated team engagements, while specialists anchor mid-market revenue through fixed-price healthcare and fintech contracts. Three archetypes dominate: Eastern European delivery-scale players, agile methodology boutiques, and compliance-certified healthcare specialists. Competitive intensity centers on M&A for talent pipeline security and strategic partnerships for multi-cloud orchestration capabilities.
Within the Eastern European delivery-scale tier, EPAM Systems exemplifies cost-competitive talent pipeline architecture through Polish and Ukrainian delivery centers. Thoughtworks occupies a position within agile methodology depth and social impact positioning. ScienceSoft anchors the compliance-certified healthcare specialist archetype through fixed-price contracts with defined acceptance criteria.
| Leading Market Players |
|---|
| Thoughtworks |
| SoftTeco |
| EPAM Systems |
| Improving |
| Radixweb |
| ScienceSoft |
| Intellias |
| SCAND |
| Innowise |
| Others |
Cost & Logistics Intelligence
ISO 27001 certification gates both vendor qualification and price differentiation in regulated software consulting segments, forcing consultancies to absorb capital-intensive security infrastructure investments before accessing premium client budgets. This certification barrier simultaneously concentrates supply among credential-holding firms and stratifies pricing across compliance-validated and non-certified tiers.
Pricing Analysis
Eastern European delivery centers command 30-40% bill rate discounts versus Western European equivalents for equivalent cloud architecture skill sets. Three-tier pricing structure across premium, standard, and economy levels separates ISO 27001-certified specialists from methodology-only boutiques and offshore implementation shops. Cost compression in the standard tier intensifies because generative AI tooling commoditizes junior development labor. Mid-market manufacturers exhibit highest price sensitivity, while financial services firms under SEC disclosure mandates show lowest sensitivity for incident response retainers.
Supply Chain Analysis
Certified cloud architect pipelines in Poland, Romania, and Ukraine constitute the primary chokepoint constraining Western European project kickoff timelines. Talent supply draws from computer science graduate pools in Warsaw, Krakow, and Wrocław technology clusters, with secondary feeds from Ukrainian displacement networks. Single-source vulnerability concentrates in AWS/Azure/GCP certification pathways controlled by hyperscaler training ecosystems. Distribution runs through direct enterprise sales teams for large engagements and platform-mediated marketplaces for staff augmentation contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Software consulting sits in early-cycle expansion as EU AI Act compliance deadlines force algorithmic auditing adoption across banking and insurance verticals that previously self-certified AI governance.
For Market Incumbents: Fortify talent pipeline security through captive delivery center investments in Poland and Romania before cloud architect scarcity worsens project kickoff delays. Deepen ISO 27001 certification moats to defend margin position against agile methodology boutiques lacking security infrastructure. Prioritize M&A targets with documented EU AI Act conformity assessment capabilities to preempt regulatory-driven procurement shifts. For New Entrants and Emerging Players: Differentiate on edge computing deployment modules for German Mittelstand manufacturers seeking productized smart factory architectures. Target healthcare systems with FDA 21 CFR Part 11 validation expertise as the most penetrable segment given incumbent capacity constraints. Pursue equity-linked compensation structures with venture-backed fintechs to bypass cash-constrained procurement barriers. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across compliance-certified healthcare specialists requiring ISO 27001 infrastructure investments. Long-term viability favors vertically integrated players controlling Eastern European delivery capacity and Western European client relationships. Monitor EU AI Act enforcement patterns as the signal to watch for algorithmic auditing demand inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Delivery Center Expansion | Polish and Romanian talent pipelines reduce bill rate inflation for Western European cloud migration contracts. |
| EU AI Act Certification Investment | Documented conformity assessment procedures unlock algorithmic auditing revenue from Deutsche Bank and BNP Paribas procurement. |
| Agile Methodology Acquisition | SAFe and Scrum credential portfolios defend against automated code generation commoditizing implementation labor. |
| Healthcare Compliance Specialization | FDA 21 CFR Part 11 validation expertise captures fixed-price contracts from Boston-Cambridge life sciences clusters. |
| Zero-Trust Architecture Bundling | Cybersecurity-cloud convergence packages address SEC four-day disclosure mandates for publicly traded clients. |
Research Approach
Operator-level perspectives from CTOs, IT procurement officers, platform engineers, and channel partners anchored the qualitative base for this software consulting analysis. Primary fieldwork combined structured interviews with secondary validation across SEC filings, hyperscaler capex disclosures, EU regulatory registries, and ISO certification databases. Bottom-up engagement model sizing triangulated against top-down vertical spending estimates from financial services and healthcare procurement benchmarks.
Sensitivity analysis tested bill rate assumptions, talent pipeline expansion scenarios, and regulatory enforcement timelines across the projection horizon. Segmentation dimensions modeled include service type, technology focus, organization size, deployment complexity, and regional adoption pattern. CAGRs derived from historical contract value trajectories and forward procurement intention surveys, with specific weighting for cloud migration mandate acceleration and AI integration budget expansion.
The analysis sits within stated boundaries; outcomes outside sustained EU AI Act enforcement or generative AI capability plateau would require recalibration. Forecasts reflect documented assumptions about certification barrier persistence and Eastern European talent availability. Practitioners should keep alternative scenarios live as hyperscaler training capacity and regulatory interpretation evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
Construction Simulation Software Market
Software & Services
Content As a Service (Caas) Market
Software & Services
Software Construction Components Market
Software & Services
Global Organizational Change Management Software Market
Software & Services
Global Accounts Receivable Software Market
Software & Services
Resonator Design Software Market
Software & Services
Global Audit Software Market
Software & Services
Lease Accounting Software Market
Software & Services
Product Analytics Software Market
Software & Services
Business Email Market
Software & Services
Session Support Software Market
Software & Services
Talent Acquisition Software Market
Software & Services
Sales Platforms Software Market
Software & Services
Debt Collection Software Market
Software & Services
Poultry Farm Management Software Market
Software & Services
Global Disclosure Management Software Market