
 Exercise and Weight Loss Apps Market | 2026-2036
Exercise and Weight Loss Apps Market Size, Share, and Industry Trends Forecast 2026-2036
Exercise and Weight Loss Apps Market Analytics
Multi-source content aggregation is hardening as the dominant sourcing pattern, with developers blending proprietary algorithms with licensed nutrition databases and third-party wearable APIs. Noom leverages behavioral psychology frameworks to sustain user retention rates that anchor its subscription economics. Apple competes through tight hardware-software integration, while Peloton differentiates with instructor-led content that controls premium pricing power.
Exercise and weight loss apps are software platforms that deploy accelerometer data, GPS telemetry, and biometric inputs to calculate energy expenditure, macronutrient balance, and cardiovascular load, primarily serving consumers pursuing structured fitness outcomes and medical weight management. Calorie tracking and activity tracking dominate feature set adoption, though meal planning represents the fastest-expanding segment as users seek integrated diet-exercise workflows. Freemium subscription models capture the largest user base, while annual subscriptions concentrate margin pools through reduced churn and upfront cash conversion.
FDA scrutiny of apps making disease-related claims and FTC enforcement against deceptive before-and-after marketing are reshaping product standards and user onboarding disclosures. GDPR in Europe and state-level biometric privacy laws in Illinois and Texas add compliance layers for cross-platform data handling. Stakeholders must monitor how evolving digital health classifications affect reimbursement eligibility and platform liability exposure.
Market Dynamics
Employer-sponsored wellness programs are consolidating purchasing power across the Exercise and Weight Loss Apps Market, creating concentrated B2B subscription pipelines that reshape developer go-to-market economics and feature prioritization.
Growth Catalysts
- HIPAA-aligned data frameworks:Enterprise health plans mandate encrypted biometric storage, accelerating FDA-cleared app certifications for reimbursement eligibility.
- Accelerometer-GPS fusion:Smartphone sensor stacks now deliver clinical-grade activity telemetry without peripheral hardware, collapsing cost barriers for mass deployment.
- Illinois and Texas:State biometric privacy statutes force transparency in facial recognition and body-metric collection, paradoxically building user trust that lifts conversion rates.
Market Restraints
- FTC Section 5 enforcement:Deceptive before-and-after imagery triggers consent decrees that freeze marketing spend and demand legal review of all user testimonials.
- GDPR Article 9:Health data special-category classification imposes purpose-limitation constraints that block secondary monetization through ad targeting.
- Third-party API dependency:Wearable device manufacturers control raw biometric feeds, extracting licensing fees that compress SaaS margins at scale.
Strategic Opportunities
- GLP-1 medication integration:Prescription weight-loss drug protocols create demand for companion apps that track appetite, dosage timing, and muscle preservation metrics.
- Medicare Advantage carve-outs:Supplemental benefit expansions open reimbursement pathways for digital obesity management tools in retiree populations.
- Computer vision meal logging:On-device food recognition eliminates manual barcode scanning, reducing friction in diet-exercise workflow convergence.
Industry Challenges
- Behavioral science talent scarcity:Subscription retention depends on habit-formation design expertise that outbids adjacent industries for PhD-level psychologists.
- ISO 27001 certification timelines:Enterprise security audits extend sales cycles by six to nine months, delaying revenue recognition against fixed development costs.
- Legacy EHR interoperability:Hospital system data silos resist API connections that would enable physician-supervised app prescriptions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Exercise and Weight Loss Apps Market |
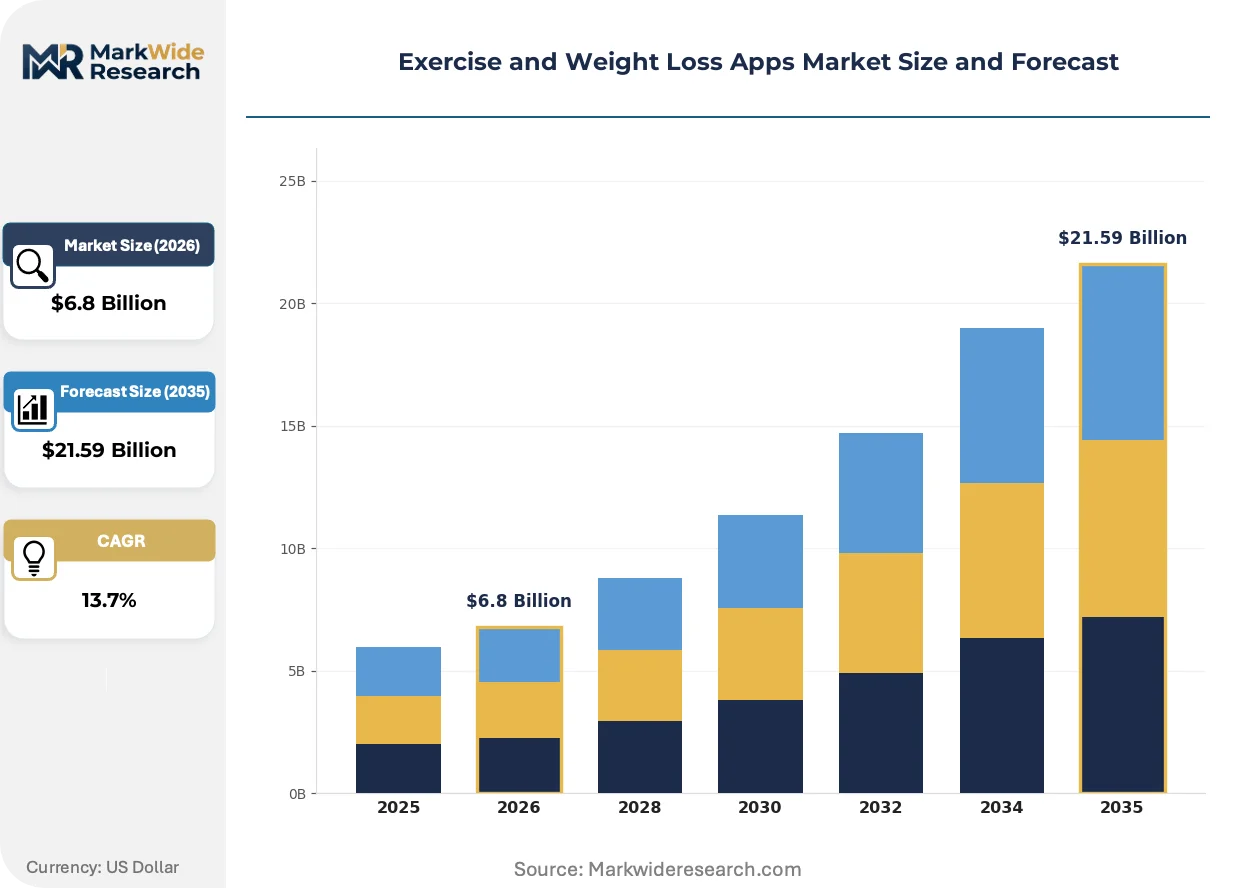
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $21.59 Billion |
| CAGR (2026 – 2036) | 13.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Application Type: Calorie Tracking, Workout Logging, Meal Planning, Progress Monitoring Subscription Model: Free, Freemium, Monthly Subscription, Annual Subscription Target Audience: Fitness Enthusiasts, Weight Watchers, Casual Users, Trainers Feature Set: Personalized Workouts, Community Support, Nutrition Guides, Activity Tracking |
| Companies Covered | MyFitnessPal, Noom, Fitbit, Peloton, Apple, Samsung, Strava, WeightWatchers, Garmin, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Exercise and Weight Loss Apps Market Evolving Landscape
Multi-modal sensor fusion and AI-driven personalization are compressing feature differentiation cycles, forcing developers to embed predictive analytics deeper into workout and nutrition workflows.
On-device machine learning is consolidating inference capabilities for real-time form correction and injury-risk scoring. Boutique fitness chains embed these SDKs into branded member apps, cutting cloud latency for rep-counting accuracy. The technology is consolidating hardware-software bundles that previously required separate wearable purchases.
FDA De Novo classification pathways for software-as-medical-device are tightening predicate device requirements for apps claiming disease-related outcomes. Developers must submit clinical validation studies that extend time-to-market by eighteen to twenty-four months. Diabetes prevention program sponsors face the steepest compliance burden as glucose-management claims trigger premarket review.
Annual prepaid subscriptions are displacing monthly billing as the dominant B2B procurement format. Corporate wellness administrators negotiate enterprise licenses that bundle dependent coverage, locking in twelve-month commitments. United States employer channels show the fastest format migration as benefits platforms integrate app access into health savings account structures.
Exercise and Weight Loss Apps Market Segmentation
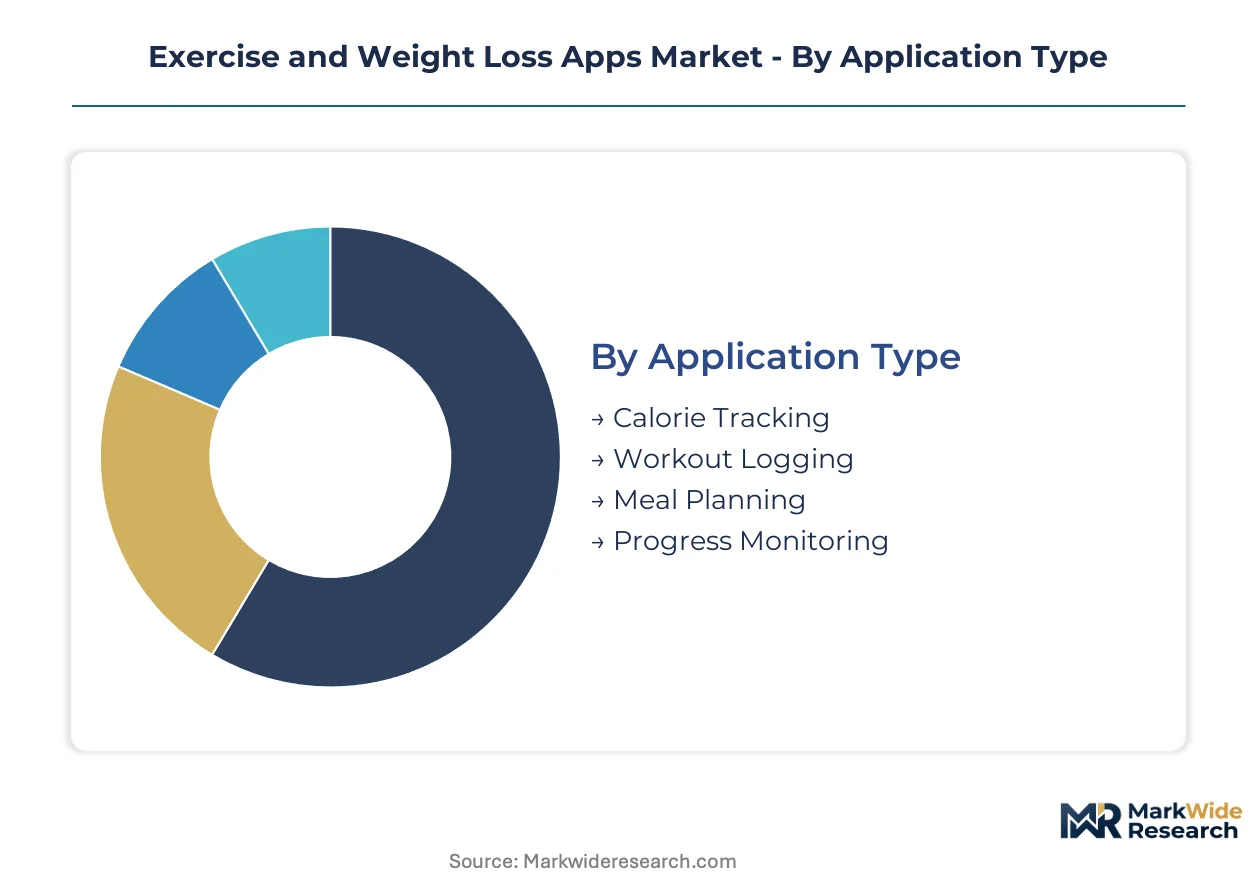
Segmentation in exercise and weight loss apps determines pricing power, retention economics, and regulatory exposure. Developers configure feature depth and data handling protocols differently across user cohorts and revenue models.
Application Type:
Standardization dominates core tracking functions while premium tiers layer predictive analytics and clinical integrations.
- Calorie Tracking:Macro logging interfaces with USDA and licensed nutrition databases to calculate energy balance. Employer wellness programs in the United States concentrate procurement here as HIPAA-aligned data frameworks become mandatory. FDA scrutiny of disease-related claims intensifies compliance costs for metabolic health positioning.
- Workout Logging:Accelerometer-GPS fusion enables rep counting and route mapping without peripheral hardware. Fitness enthusiasts drive subscription conversion through strength progression algorithms and recovery metrics.
- Meal Planning:Computer vision food recognition reduces manual entry friction. Gaining share fastest among weight management protocols paired with GLP-1 medications.
- Progress Monitoring:Biometric trend visualization and body composition tracking. Illinois and Texas biometric privacy statutes force explicit consent flows that extend onboarding sequences.
Most installed capacity flows through Calorie Tracking. Expansion is steepest in Meal Planning.
Subscription Model:
Revenue concentration tracks willingness to prepay versus tolerance for interruptive monetization.
- Freemium:Gated premium features sustain acquisition funnels with 2-4% conversion rates typical. The largest user base by volume compresses margins through support costs.
- Annual Subscription:Upfront cash conversion and reduced churn anchor enterprise procurement. Corporate wellness administrators negotiate bundled dependent coverage in twelve-month commitments.
- Free:Ad-supported or loss-leader distribution for hardware ecosystem lock-in. Apple deploys this to drive Watch and Fitness+ attachment.
- Monthly Subscription:Flexible commitment for seasonal users and trial-to-paid transitions. Higher churn erodes lifetime value against annual equivalents.
Revenue pools concentrate in Annual Subscription. User acquisition flows predominantly through Freemium.
Target Audience:
Behavioral design complexity escalates with user motivation heterogeneity and outcome accountability.
- Fitness Enthusiasts:Performance optimization and periodization protocols. Demand concentrates for power meter and heart rate variability integrations.
- Weight Watchers:Medical weight management and clinician-supervised protocols. Medicare Advantage carve-outs open reimbursement pathways for this cohort.
- Casual Users:Habit formation and streak mechanics drive retention. Noom's behavioral psychology frameworks target this segment specifically.
- Trainers:Client management dashboards and program prescription tools. B2B licensing extracts premium pricing against consumer tiers.
Enterprise procurement skews toward Trainers. Expanding most quickly among Weight Watchers as prescription drug protocols proliferate.
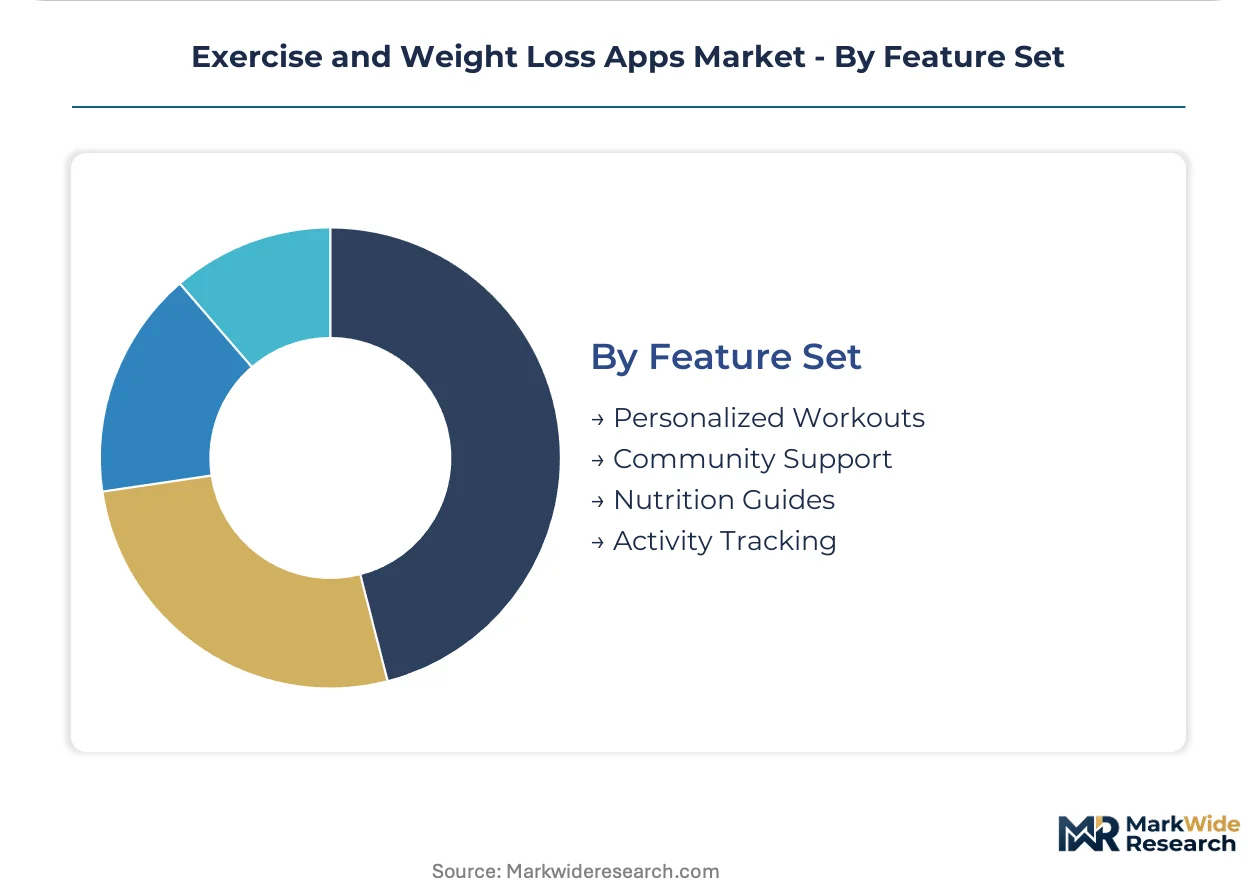
Feature Set:
Hardware-software integration depth separates premium positioning from commodity tracking.
- Activity Tracking:Smartphone sensor fusion delivers clinical-grade telemetry without wearables. Peloton and Apple compete through proprietary hardware lock-in.
- Personalized Workouts:AI-driven adaptation to fatigue, schedule constraints, and equipment availability. On-device machine learning reduces cloud latency for real-time form correction.
- Community Support:Instructor-led content and peer accountability structures. Peloton's premium pricing power derives from charismatic instructor IP.
- Nutrition Guides:Registered dietitian content and meal timing protocols. FDA De Novo classification requirements extend time-to-market for disease-related claims.
Retention economics depend most heavily on Personalized Workouts. Steepest expansion trajectory sits with Nutrition Guides as GLP-1 companion apps proliferate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage is concentrating developer operations in jurisdictions where HIPAA-aligned data frameworks lower compliance costs relative to GDPR Article 9 constraints. The United States captures the largest share of B2B subscription pipelines as employer-sponsored wellness programs consolidate purchasing power.
United States
Employer-sponsored wellness incentives and high smartphone penetration drive subscription growth across corporate channels. FDA scrutiny of disease-related health claims and FTC Section 5 enforcement against deceptive marketing reshape product standards and onboarding disclosures. Silicon Valley and Austin clusters house the dominant share of behavioral psychology design talent that anchors retention economics.
Germany
GDPR Article 9 special-category classification imposes purpose-limitation constraints that block secondary monetization through ad targeting. BfDI enforcement of biometric data transparency builds user trust that lifts conversion rates for premium tiers. Berlin and Munich clusters concentrate EU-facing development operations seeking regulatory clarity before scaling across member states.
United Kingdom
Post-Brexit data adequacy arrangements create friction for cross-border biometric handling while preserving NHS integration opportunities for clinical-grade apps. MHRA oversight of software-as-medical-device classifications extends time-to-market for diabetes prevention protocols. London fintech corridors channel corporate wellness procurement through benefits platform integrations.
Japan
Aging demographics and Medicare-equivalent reimbursement pathways open digital obesity management tools to retiree populations. METI promotion of healthcare data portability standards accelerates API interoperability with hospital EHR systems. Tokyo and Osaka metropolitan areas concentrate telehealth infrastructure that supports physician-supervised app prescriptions.
Australia
TGA classification pathways for wellness apps claiming metabolic health outcomes demand clinical validation studies that compress margin pools. State-level biometric privacy statutes in Victoria and New South Wales mirror Illinois and Texas transparency requirements. Sydney and Melbourne clusters serve as Asia-Pacific regulatory testing grounds before scaling into Southeast Asian markets.
Exercise and Weight Loss Apps Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue GLP-1 medication companion protocols and computer vision meal logging. The market structures around three tiers: hardware-integrated ecosystems, behavioral psychology specialists, and freemium acquisition engines. Strategic moves concentrate on FDA De Novo certification races and annual prepaid subscription format migration that locks in enterprise procurement.
Within the behavioral psychology tier, Noom exemplifies habit-formation design expertise that outbids adjacent industries for PhD-level talent. Among hardware-integrated ecosystems, Apple and Peloton anchor premium positioning through proprietary sensor stacks and instructor-led content IP. These three occupy positions where tight hardware-software integration or charismatic instructor networks control pricing power against commodity tracking alternatives.
| Leading Market Players |
|---|
| MyFitnessPal |
| Noom |
| Fitbit |
| Peloton |
| Apple |
| Samsung |
| Strava |
| WeightWatchers |
| Garmin |
| Others |
Value Network & Pricing Analysis
Certification-grade divergence between FDA-cleared medical device apps and wellness-tracker commodities manifests in both subscription pricing power and supply chain qualification depth. Premium tiers command enterprise procurement through HIPAA-aligned data frameworks while commodity tracking tools compete on sensor-fusion cost minimization.
Pricing Analysis
Direct-to-employer enterprise licenses bypass consumer app store margins that typically extract thirty percent from direct subscriptions. Annual prepaid commitments anchor B2B pricing through reduced churn economics, while freemium tiers face acute price sensitivity among casual users with sub-five-percent conversion rates. Cost compression in computer vision meal logging is intensifying because on-device inference eliminates cloud processing fees. Fitness enthusiasts demonstrate least price sensitivity for heart rate variability and power meter integrations.
Supply Chain Analysis
ISO 27001 and FDA De Novo certification gating concentrates development operations in the United States, Germany, and Japan where regulatory clarity accelerates enterprise sales cycles. Proprietary algorithm development draws from licensed nutrition databases, third-party wearable APIs, and behavioral psychology research partnerships. Single-source vulnerability in Apple HealthKit and Google Fit API access threatens margin pools through licensing fee escalation. Distribution runs through employer benefits platforms and direct-to-consumer app stores with minimal intermediary layers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in this market rests on annual subscription format migration and GLP-1 medication companion protocol development that captures reimbursement eligibility.
For Market Incumbents: To counter emerging entrants with computer vision meal logging, deepen proprietary hardware-software integration through accelerometer-GPS fusion patents and secure ISO 27001 certification ahead of enterprise procurement cycles. Lock in twelve-month prepaid commitments through dependent-coverage bundling in corporate wellness negotiations. For New Entrants and Emerging Players: Capture Medicare Advantage carve-out opportunities for retiree obesity management and GLP-1 companion tracking protocols where reimbursement pathways remain underdeveloped. Target clinician-supervised weight management segments through HIPAA-aligned data frameworks that incumbent wellness trackers lack. For Investors and Strategic Acquirers: Asymmetric upside sits with behavioral psychology design specialists possessing PhD-level habit-formation expertise that adjacent industries cannot replicate. Long-term viability over the five-to-ten year window favors platforms with FDA De Novo clearance progress and annual subscription concentration above freemium dependence. Watch for GLP-1 drug formulary expansion as inflection signal for companion app reimbursement eligibility.| Strategic Initiative | Industry Significance |
|---|---|
| FDA De Novo Certification Pursuit | Unlocks Medicare Advantage reimbursement and enterprise procurement eligibility for diabetes prevention protocols. |
| Annual Prepaid Subscription Migration | Reduces churn and anchors cash conversion through corporate wellness twelve-month commitment structures. |
| GLP-1 Companion Protocol Development | Captures emerging demand for appetite tracking and muscle preservation metrics alongside prescription weight-loss drugs. |
| On-Device Machine Learning Integration | Eliminates cloud latency for real-time form correction and reduces recurring infrastructure costs. |
| Behavioral Psychology Talent Acquisition | Secures scarce PhD-level habit-formation expertise that anchors subscription retention economics against commodity alternatives. |
Research Methodology
Coverage spans the United States, Germany, United Kingdom, Japan, and Australia, with primary inputs from each market cluster combining interviews with digital health product executives, corporate benefits administrators, FDA regulatory consultants, behavioral psychology researchers, and hospital procurement committees. Secondary validation draws from FDA 510(k) and De Novo filings, CMS Medicare Advantage supplemental benefit data, employer wellness platform disclosures, and state biometric privacy statute tracking. Bottom-up subscription volume modeling triangulates against top-down enterprise procurement value estimates.
Granularity-level modeling operates at application type, subscription model, target audience, and feature set dimensions across the projection horizon. CAGRs derive from segment-level growth trajectory analysis incorporating smartphone penetration curves, employer wellness program adoption rates, and GLP-1 prescription volume expansion. Forecast inputs include HIPAA-aligned data framework certification timelines and FDA software-as-medical-device classification pathway durations.
Underlying measurement precision varies by segment; annual subscription and B2B procurement data carry tighter precision than freemium conversion rate estimates. Forecasts reflect assumptions regarding regulatory clarity stability and employer wellness budget continuity. A model refresh is warranted upon material change in FDA digital health classification guidance or Medicare Advantage supplemental benefit expansion scope.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
Resonator Design Software Market
Software & Services
Enterprise Backup and Recovery Software Market
Software & Services
K8s Market
Software & Services
Latin America Cloud Workforce Management Software Market
Software & Services
Social Collaboration Software Market
Software & Services
Global Decision Making Software Market
Software & Services
Quick Service Restaurants (QSR) IT Market
Software & Services
Global Architect Software Market
Software & Services
UI Design Software Market
Software & Services
Multivariate Testing Software Market
Software & Services
Global Disclosure Management Software Market
Software & Services
Yacht Management Software Market
Software & Services
HCS Software and Services Market
Software & Services
Europe Pharmacy POS Software Market
Software & Services
Global Android Kiosk Software Market
Software & Services
Asia-Pacific Database Management Software Market