
 Philippines Telecom Towers Market | 2026-2036
Philippines Telecom Towers Market Size, Share, and Industry Trends Forecast 2026-2036
Philippines Telecom Towers Market Insights
Co-location bundling is rebalancing buyer choice across the Philippines tower landscape. edotco Group leverages its regional engineering playbook to sustain build-to-suit momentum in Luzon. American Tower anchors its portfolio through long-term master lease agreements with Globe and Smart. PhilTower competes by specializing in rapid-deployment rooftop solutions for dense urban barangays.
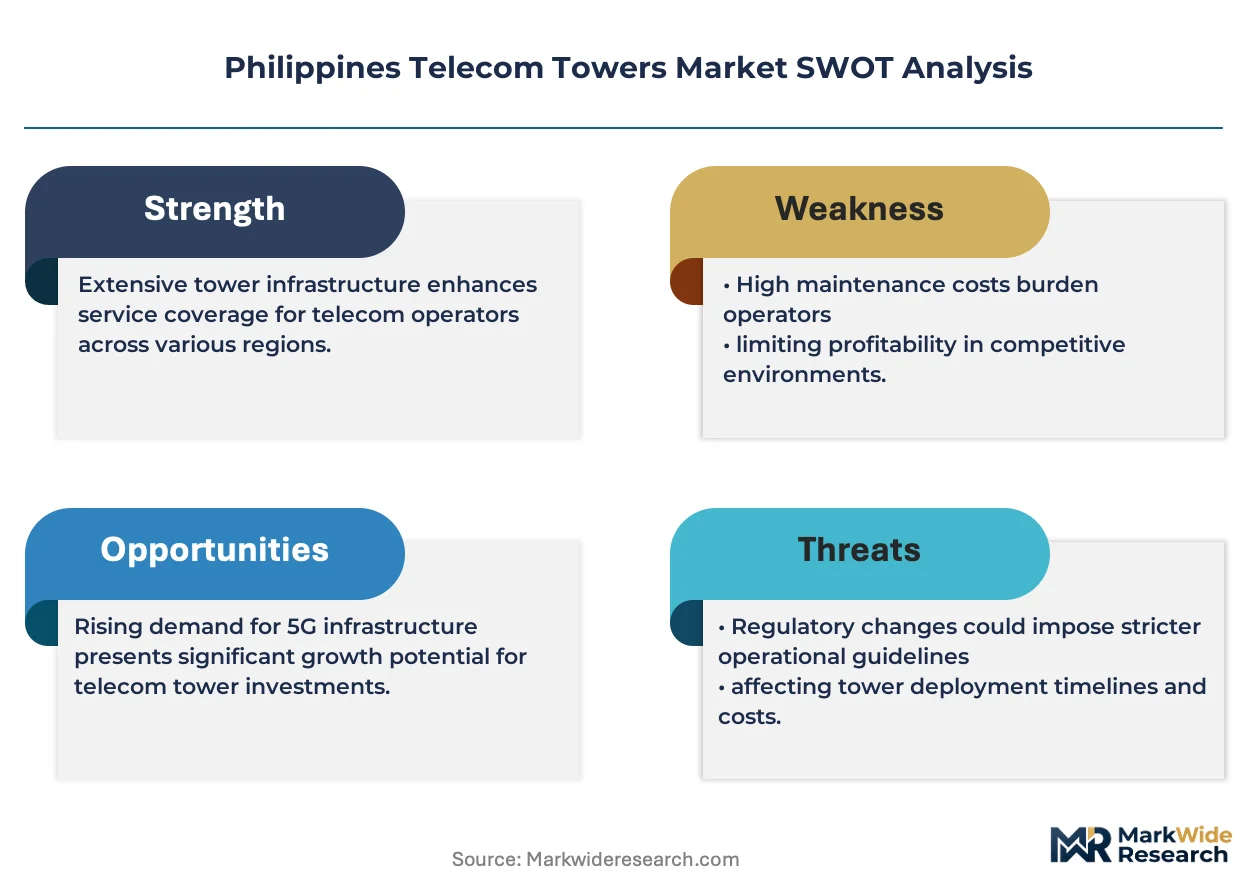
Telecom towers are steel or reinforced concrete structures engineered to support multiple antenna arrays at heights typically ranging from 30 to 120 meters, designed to withstand typhoon wind loads specified under Philippine building codes. Their primary commercial purpose is to provide elevated, interference-minimized platforms for radio frequency transmission serving mobile and fixed wireless networks. Lattice towers dominate new greenfield construction in Visayas and Mindanao where terrain and wind exposure favor guy-wire-stabilized geometries. 5G-ready monopole installations represent the fastest-growing technology segment as carriers densify coverage in Cebu, Davao, and Cagayan de Oro. Rooftop deployments in Metro Manila constitute a mature, margin-compressed category where site acquisition costs and lessor escalation clauses erode operator returns.
The Department of Information and Communications Technology enforces common tower guidelines that mandate infrastructure sharing, while the National Telecommunications Commission governs spectrum allocation and tower registration protocols that directly shape deployment timelines. Local government units impose barangay-level permitting and zoning ordinances that create fragmented approval pathways, particularly in ecologically sensitive areas. Stakeholders must monitor how DICT's evolving common tower framework interacts with NTC's spectrum release schedules to anticipate where co-location economics will shift from optional to compulsory.
Market Dynamics
The DICT's common tower policy is compressing infrastructure economics by mandating multi-tenant access, forcing mobile network operators to abandon siloed buildouts in favor of shared steel and accelerated co-location timelines across Luzon, Visayas, and Mindanao.
Growth Catalysts
- 5G spectrum release:NTC's allocation of mid-band frequencies in 3.5 GHz and 26 GHz ranges is compelling carriers to densify macro sites and small cells in Metro Manila and Cebu.
- CALABARZON subscriber density:Concentrated demand across Cavite, Laguna, Batangas, Rizal, and Quezon provinces justifies multi-tenant greenfield investments with faster tenancy fill rates.
- Typhoon-resilient engineering:Revised National Building Code wind load specifications for lattice and monopole structures are extending asset lifespans and reducing insurance premiums for tower operators.
Market Restraints
- Steel price volatility:Fluctuations in hot-rolled coil and galvanized structural sections directly inflate fabrication costs for lattice towers and guyed masts.
- Barangay permitting fragmentation:Local government unit zoning ordinances create inconsistent approval timelines, particularly in ecologically sensitive watershed areas and indigenous territories.
- Site acquisition cost escalation:Rooftop lessors in Metro Manila's dense barangays are negotiating aggressive annual escalation clauses that erode tower operator margins.
Strategic Opportunities
- Mindanao underserved corridors:Davao del Sur, South Cotabato, and Maguindanao provinces present low-tenancy competition zones for build-to-suit deployments.
- Edge data center co-location:Convergence of 5G radio access networks with distributed computing nodes is creating hybrid infrastructure demand at tower base stations.
- DICT rural connectivity mandate:The National Broadband Plan's unserved and underserved area classifications are unlocking public funding for shared infrastructure in geographically isolated and disadvantaged regions.
Industry Challenges
- RF engineer shortage:Specialized talent for interference modeling, line-of-sight verification, and antenna pattern optimization remains concentrated in Metro Manila consulting firms.
- Legacy 2G/3G decommissioning complexity:Carriers must coordinate antenna swap schedules with active tenant migration timelines without disrupting voice and data services.
- Environmental compliance timelines:Certificate of Non-Overlap requirements from the National Commission on Indigenous Peoples and DENR Environmental Compliance Certificates add six to fourteen months to project schedules.
Report Scope
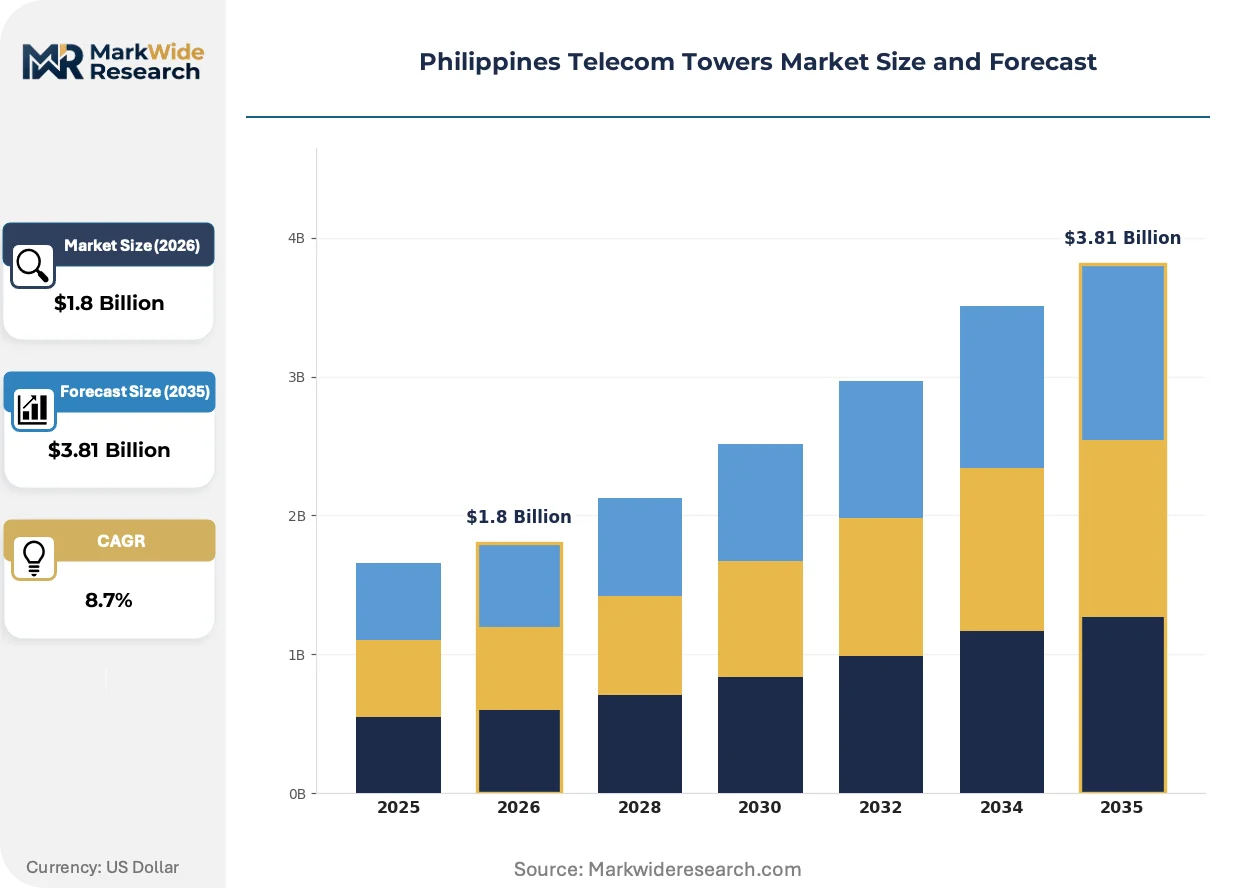
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Philippines Telecom Towers Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: Monopole, Lattice Tower, Stealth Tower, Guyed Tower Technology: 4G, 5G, LTE, Wi-Fi End User: Telecommunication Operators, ISPs, Government, Enterprises Installation Type: Onshore, Rooftop, Greenfield, Brownfield |
| Companies Covered | edotco Group, American Tower, PhilTower, Pinnacle Towers, EdgePoint Infrastructure, Unity, LBS Digital Infrastructure, Frontier Tower Associates, ALT Global Solutions, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Philippines Telecom Towers Market Trends and Innovations
Steel-to-concrete hybrid designs and intelligent monitoring systems are redefining structural performance benchmarks. These shifts intersect with regulatory pressure for faster deployment and carrier demand for operational visibility.
Active antenna systems with integrated radio units are integrating baseband processing directly at the tower top, eliminating feeder cable losses. Globe and Smart are deploying these in Cebu and Davao to support 64T64R massive MIMO configurations. This compression of the radio chain is integrating power and cooling loads into tower structural design criteria, forcing civil engineers to recalculate load distributions for active cooling cabinets.
DICT's common tower policy is mandating infrastructure sharing through standardized lease rates and open access provisions. The framework compels mobile network operators to divest captive tower portfolios and lease from independent infrastructure providers. Visayas and Mindanao greenfield projects are most affected, with carriers now prioritizing tenancy availability over proprietary control in site selection decisions.
Mobile network operators are consolidating vendor relationships from fragmented regional contractors toward national master service agreements with integrated engineering-procurement-construction firms. This concentration displaces the traditional barangay-level site acquisition broker model. The shift is most visible in CALABARZON and Central Luzon, where carriers now demand single-accountability contracts covering civil works, electrical installation, and regulatory documentation.
Philippines Telecom Towers Market Segmentation
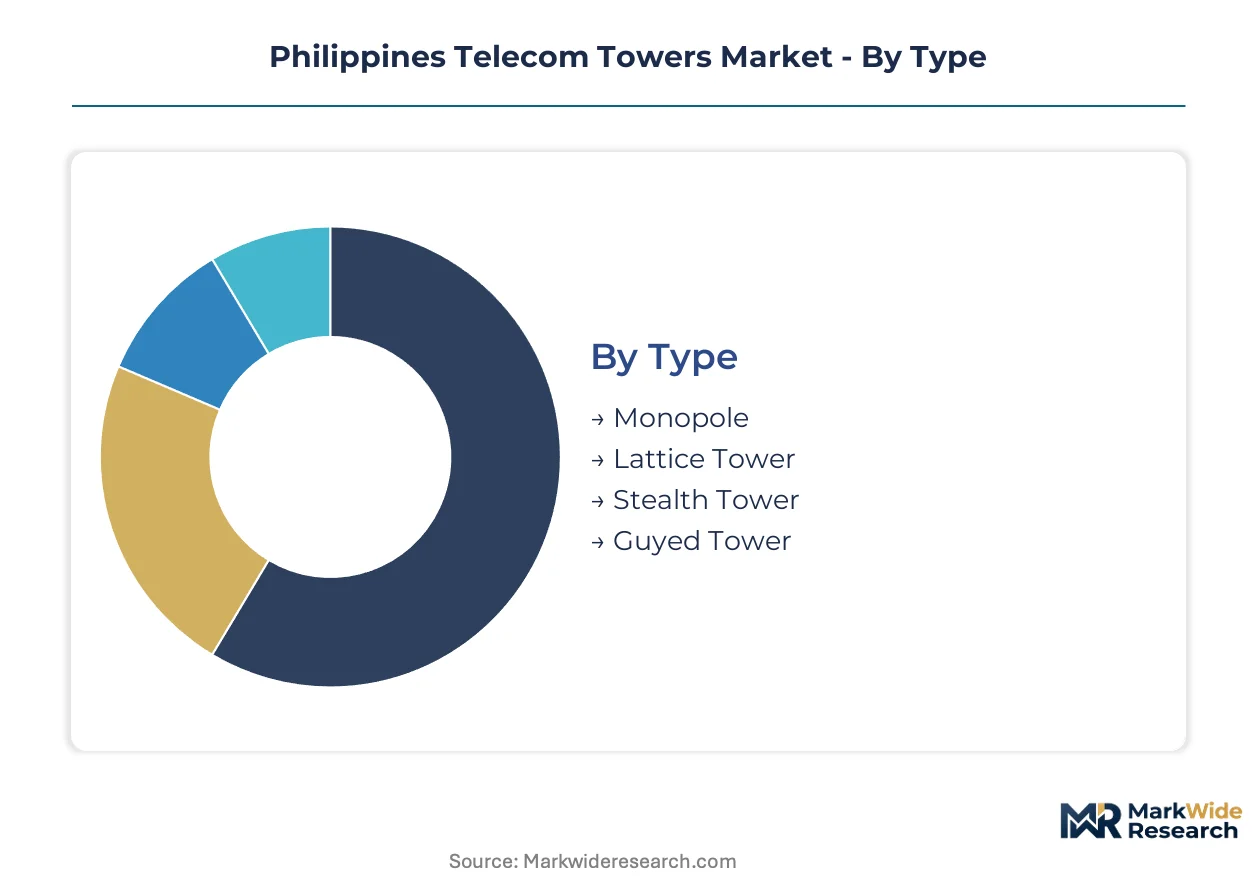
Structural design choices in Philippine telecom towers dictate foundation costs, wind load engineering, and tenant density potential. Carrier deployment strategies vary sharply across tower geometries and technology generations, reshaping procurement patterns for independent infrastructure providers.
Type:
Capital intensity varies dramatically across structural geometries, with foundation depth and steel tonnage driving upfront investment differentials.
- Monopole:Single-stem steel or reinforced concrete shafts minimize ground footprint and visual impact. Metro Manila and Cebu carriers favor these for 5G densification where zoning restrictions limit lattice visibility.
- Lattice Tower:Triangular or square-section steel truss frameworks with bolted angle sections withstand typhoon wind loads through distributed structural redundancy. Visayas and Mindanao greenfield sites concentrate demand here due to lower material costs per meter of height.
- Stealth Tower:Concealed designs mimic trees, flagpoles, or building elements to satisfy aesthetic ordinances in heritage districts and tourist zones.
- Guyed Tower:Masts stabilized by tensioned wire arrays reduce steel mass but require larger land parcels for anchor foundations.
Lattice configurations absorb the bulk of installed capacity; monopole installations are expanding most quickly.
Technology:
Radio access network evolution determines antenna array specifications, power requirements, and structural load calculations at the tower top.
- 5G:Mid-band and millimeter-wave deployments demand dense site spacing and massive MIMO antenna arrays. CALABARZON provinces lead tenancy commitments as Globe and Smart accelerate coverage obligations.
- 4G:Macro layer densification continues in secondary cities where subscriber growth outpaces 5G handset penetration.
- LTE:Existing infrastructure supports voice-over-LTE fallback and machine-to-machine connectivity in industrial zones.
- Wi-Fi:Carrier-grade outdoor access points mount on lower tower sections for localized hotspot coverage.
5G-ready specifications command premium lease rates; 4G capacity additions still generate the majority of annual tenancy contracts.
End User:
Tenant credit quality and contract duration vary substantially across customer categories, influencing tower operator financing structures.
- Telecommunication Operators:Globe, Smart, and DITO anchor demand with 10-15 year master lease agreements and standardized co-location terms mandated under DICT common tower policy.
- ISPs:Fixed wireless access providers lease sectorized capacity for last-mile broadband distribution in underserved barangays.
- Government:DICT rural connectivity programs and disaster response agencies procure dedicated tower access for public safety networks.
- Enterprises:Mining, plantation, and logistics operators lease private network capacity in geographically isolated commercial zones.
Mobile network operators dominate tenancy revenue; ISP contracts are climbing fastest as fixed wireless access displaces fiber in remote provinces.
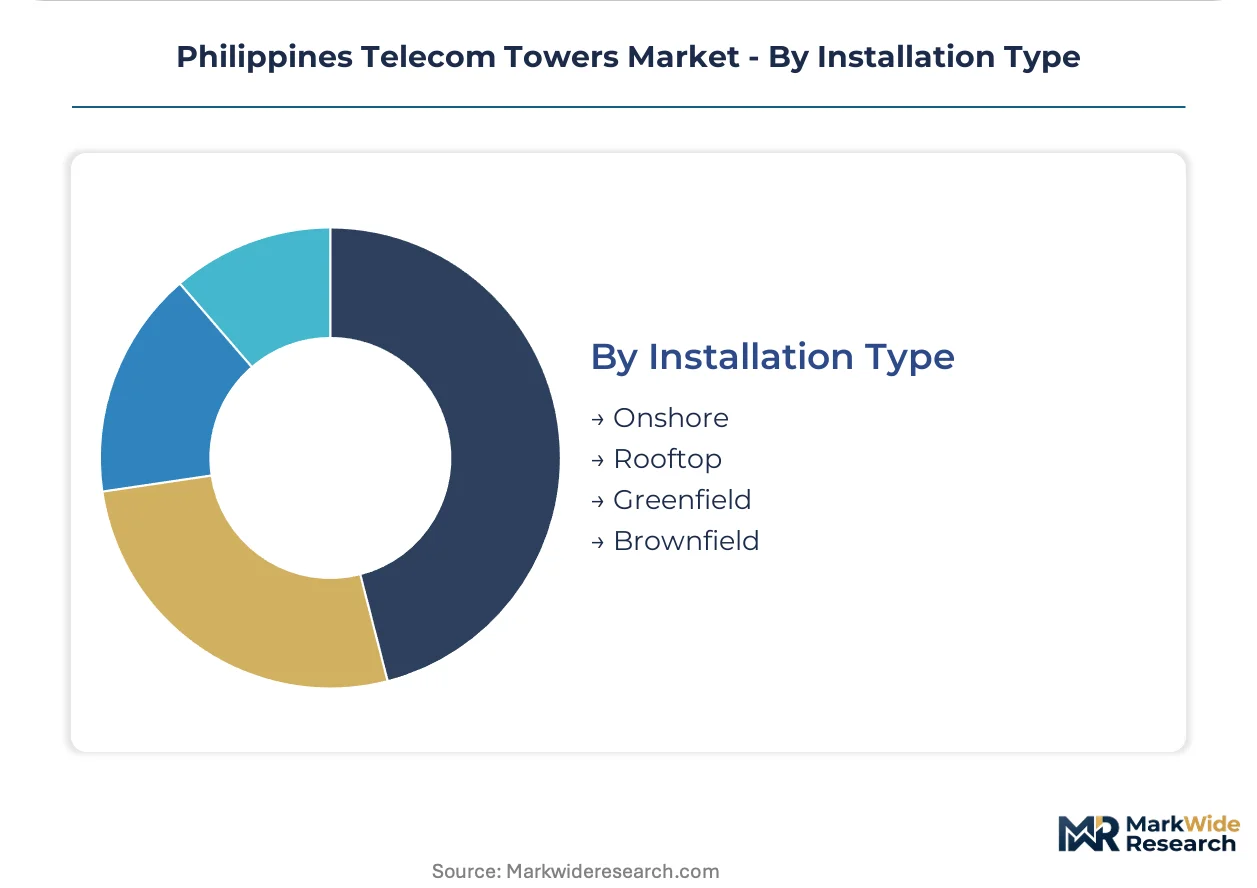
Installation Type:
Site acquisition economics and permitting complexity separate deployment models, with urban constraints favoring adaptive reuse over greenfield construction.
- Rooftop:Existing building structures host antenna arrays without dedicated land procurement. Metro Manila's dense barangays concentrate this mature segment where lessor escalation clauses compress margins.
- Greenfield:Purpose-built tower structures on acquired land parcels enable maximum tenant capacity and future structural loading.
- Onshore:Ground-based installations exclude offshore or floating platforms, covering standard terrestrial deployment.
- Brownfield:Legacy tower assets undergo structural reinforcement and electrical upgrades to accommodate additional tenants and heavier antenna loads.
Greenfield deployments absorb the majority of new capital expenditure; rooftop modifications are gaining share fastest as carriers exhaust available ground sites in Greater Manila.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Metro Manila generates tower demand that outstrips provincial construction capacity, forcing carriers to source structural steel from CALABARZON fabrication clusters while DICT policy redirects investment toward underserved corridors in Mindanao.
Metro Manila
Subscriber density across sixteen cities and one municipality sustains the nation's highest tenancy ratios per structure. The National Capital Region's barangay-level zoning ordinances impose strict height restrictions and aesthetic requirements that favor monopole and stealth tower deployments over lattice configurations. Makati, Taguig, and Quezon City concentrate co-location activity where Globe, Smart, and DITO compete for limited rooftop and greenfield sites.
CALABARZON
Cavite, Laguna, Batangas, Rizal, and Quezon provinces absorb the majority of new greenfield capital as Metro Manila site exhaustion pushes deployment outward. DICT's common tower policy accelerates multi-tenant construction in this corridor where subscriber growth outpaces infrastructure stock. Batangas and Laguna host emerging tower fabrication clusters that supply lattice and monopole sections to Luzon-wide deployment programs.
Central Visayas
Cebu Island anchors demand across the Visayas island group with 5G densification driving monopole installations in Cebu City and Mandaue. The National Telecommunications Commission's spectrum release schedules for mid-band frequencies compel carriers to accelerate macro site construction. Bohol and Negros Oriental present secondary opportunities where lower tenancy competition permits faster build-to-suit returns.
Davao Region
Davao del Sur and Davao City concentrate Mindanao's most advanced carrier infrastructure with 5G-ready monopole deployments supporting massive MIMO configurations. DICT's rural connectivity mandate unlocks public funding for shared infrastructure in Davao Oriental and Davao Occidental where private returns alone would not justify investment. The region's typhoon exposure favors lattice tower engineering over monopole alternatives for structural resilience.
Bangsamoro and Soccsksargen
Maguindanao, South Cotabato, and Sultan Kudarat provinces represent underserved corridors with minimal incumbent tower density and limited co-location alternatives. The National Commission on Indigenous Peoples' Certificate of Non-Overlap requirements extend permitting timelines in these territories where ancestral domain claims intersect with proposed site locations. Cotabato City and General Santos anchor commercial demand while surrounding municipalities rely on carrier-funded rural coverage obligations.
Philippines Telecom Towers Market Competitive Landscape
The competitive structure tilts toward independent infrastructure providers with captive MNO relationships. Three operator categories dominate: regional tower specialists with engineering-procurement-construction integration, global infrastructure platforms with balance sheet capacity for portfolio aggregation, and domestic challengers competing on rapid-deployment speed. Market consolidation proceeds through master lease agreement renegotiations and brownfield asset acquisitions rather than greenfield buildout races.
Among regional specialists, edotco Group and PhilTower occupy positions emphasizing build-to-suit velocity and rooftop deployment expertise respectively. American Tower anchors the global infrastructure tier with long-term tenancy contracts. These three exemplify divergent strategic postures: engineering-led regional expansion, urban density specialization, and scale-driven portfolio amortization across technology generations.
| Leading Market Players |
|---|
| edotco Group |
| American Tower |
| PhilTower |
| Pinnacle Towers |
| EdgePoint Infrastructure |
| Unity |
| LBS Digital Infrastructure |
| Frontier Tower Associates |
| ALT Global Solutions |
| Others |
Pricing and Supply Chain Analysis
Hot-rolled coil and galvanized structural sections flow from CALABARZON fabrication clusters through three pricing tiers: premium 5G-ready monopole specifications, standard lattice configurations for typhoon zones, and economy rooftop deployments in Metro Manila's saturated barangays. Steel price volatility transmits directly to tower operators, compressing margins on fixed-rate master lease agreements while site acquisition costs in dense urban districts escalate independently.
Pricing Analysis
Margin tightening in rooftop deployments reflects aggressive lessor escalation clauses negotiated by Metro Manila building owners. Three-tier pricing structure across premium, standard, and economy levels differentiates by structural load capacity, wind resistance certification, and co-location readiness. Cost-down pressure on greenfield lattice towers accelerates because mobile network operators consolidate procurement under national master service agreements. Price sensitivity concentrates among independent infrastructure providers competing for tenancy fill, while telecommunication operators anchor demand with volume-committed long-term contracts.
Supply Chain Analysis
ISO 3834 welding certification and Philippine National Building Code compliance gating restrict qualified structural steel fabricators to CALABARZON and Central Luzon industrial zones. Geographic supply concentration centers on domestic Philippine fabrication with secondary sourcing from Chinese and South Korean steel mills for specialized high-strength sections. Raw material dependencies rest on hot-rolled coil, zinc for galvanization, and high-tensile bolts for lattice connections. Single-source vulnerability concentrates in typhoon-grade engineering expertise held by regional specialists. Distribution runs through engineering-procurement-construction firms delivering integrated civil works, electrical installation, and regulatory documentation to carrier deployment programs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Philippines telecom towers market functions as a cost-of-compliance arena where DICT's common tower policy erects regulatory moats favoring operators with established barangay permitting relationships and National Commission on Indigenous Peoples certification track records.
For Market Incumbents: Cement tenancy retention through structural reinforcement investments that accommodate heavier 5G massive MIMO antenna loads, locking in Globe and Smart master lease renewals. Accelerate brownfield acquisitions in Visayas and Mindanao before DICT rural connectivity mandates attract new entrants. Vertical integration into CALABARZON fabrication capacity insulates against steel price volatility threatening fixed-rate contract profitability. For New Entrants and Emerging Players: DICT's rural connectivity mandate in geographically isolated and disadvantaged regions opens a window for build-to-suit deployments in Maguindanao, South Cotabato, and Davao Oriental where incumbent tower density remains minimal. Target Mindanao's underserved corridors with rapid-deployment lattice solutions engineered for typhoon resilience. Pursue tenancy partnerships with DITO CME as the third mobile network operator expands coverage obligations outside Metro Manila saturation zones. For Investors and Strategic Acquirers: Renegotiation of American Tower's long-term Globe and Smart master lease agreements is the leading indicator that tenancy rate compression has reached cyclical lows, signaling portfolio valuation recovery. Long-term viability hinges on operators with demonstrated National Commission on Indigenous Peoples Certificate of Non-Overlap procurement velocity and DENR Environmental Compliance Certificate approval track records. Watch for DICT common tower policy amendments that could convert voluntary co-location into compulsory infrastructure sharing.| Strategic Initiative | Industry Significance |
|---|---|
| Master Lease Agreement Renegotiation | Long-term Globe and Smart tenancy commitments stabilize revenue visibility for independent tower operators. |
| Typhoon-Resilient Engineering Certification | National Building Code wind load compliance extends asset lifespan and reduces insurance premiums. |
| Barangay Permitting Relationship Development | Local government unit zoning approval velocity determines deployment timelines in Metro Manila. |
| 5G-Ready Monopole Capacity Expansion | Massive MIMO antenna accommodation commands premium lease rates from carriers densifying coverage. |
| Brownfield Asset Acquisition | Existing tower portfolios in Visayas and Mindanao offer faster tenancy fill than greenfield construction. |
Research Methodology
Independent corroboration across tower operator tenancy databases, National Telecommunications Commission spectrum allocation records, and DICT rural connectivity program filings underwrites the qualitative findings. Primary interviews with mobile network operator infrastructure executives, independent tower company site acquisition managers, CALABARZON steel fabrication procurement leads, and barangay zoning officers combined with secondary validation from customs import data, SEC 10-K infrastructure disclosures, and DENR Environmental Compliance Certificate registries. Bottom-up tenancy commitment aggregation and top-down capital expenditure triangulation anchored market sizing.
Rate-of-change decomposition across the analysis window disaggregated expansion into 5G densification, 4G capacity addition, and rural coverage obligation components. Segmentation modeling incorporated structural type, radio access technology generation, end-user tenant category, and installation configuration dimensions. CAGRs derived from carrier-reported cell site deployment targets, DICT National Broadband Plan milestone schedules, and independent infrastructure provider build-to-suit backlog disclosures. Forecast inputs included NTC mid-band spectrum release timelines and typhoon frequency assumptions affecting structural engineering specifications.
The model assumes a particular technology adoption path; alternative pathways for Open RAN architecture and active antenna system integration would alter the outlook. Forecasts reflect assumptions regarding DICT policy enforcement consistency, barangay permitting standardization progress, and steel price normalization trajectories. A model refresh is warranted upon material change in NTC spectrum auction schedules or National Commission on Indigenous Peoples consent protocol revisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Telecommunications Infrastructure
Thailand Telecom Towers Market
Telecommunications Infrastructure
Global Telecom Towers Market
Telecommunications Infrastructure
Fiber to the X (FTTX) Market
Telecommunications Infrastructure
Wireless Infrastructure Market
Telecommunications Infrastructure
Slovenia Telecom Market
Telecommunications Infrastructure
South Korea Telecom Tower Market
Telecommunications Infrastructure
Japan Telecom Towers Market
Telecommunications Infrastructure
Global Telecom Cable Market
Telecommunications Infrastructure
Brazil Telecom Tower Market
Telecommunications Infrastructure
Fixed Telephony Service Market
Telecommunications Infrastructure
Session Initiation Protocol (SIP) Trunk Market
Telecommunications Infrastructure
Europe 5G Infrastructure Market
Telecommunications Infrastructure
Canada Telecom Towers Market
Telecommunications Infrastructure
Global Integrated Telecom Infrastructure Market
Telecommunications Infrastructure
Small Cell Backhaul Market
Telecommunications Infrastructure
France Telecom Towers Market