
 Global RFID in Healthcare Market | 2026-2036
Global RFID in Healthcare Market Size, Share, and Industry Trends Forecast 2026-2036
Global RFID in Healthcare Market Foresight
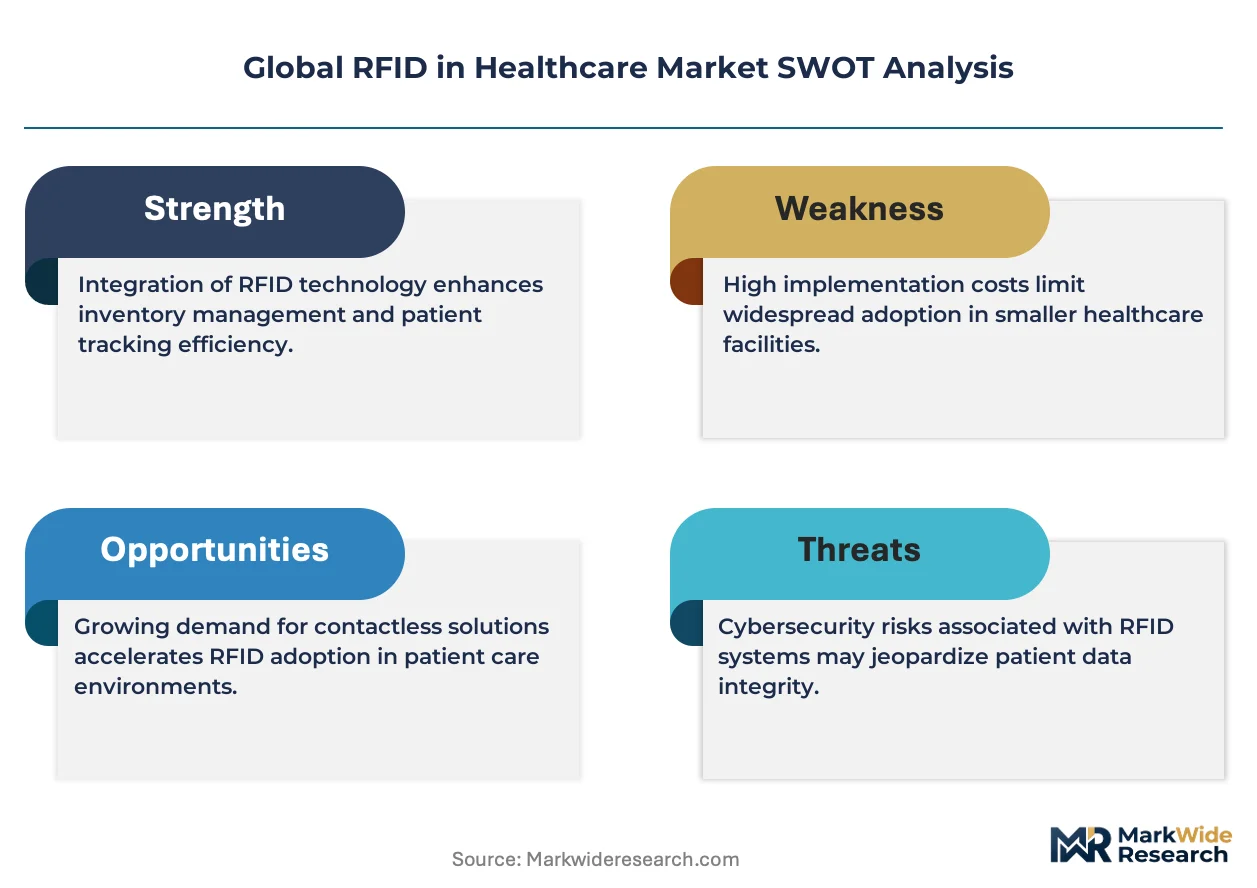
Modular RFID system bundling is consolidating buyer choice around integrated hardware-software platforms rather than standalone tags. Zebra Technologies Corporation anchors its position through end-to-end visibility solutions spanning printers, readers, and analytics software. Impinj, Inc. specializes in RAIN RFID chip design, leveraging semiconductor R&D intensity to differentiate on read sensitivity and tag density. Siemens Healthineers operates at the intersection of clinical workflow software and device connectivity, competing on embedded RFID within imaging and laboratory equipment.
RFID in healthcare encompasses radio-frequency identification systems that use electromagnetic fields to automatically identify and track tags attached to medical assets, patients, or pharmaceuticals, typically operating across low-frequency to ultrahigh-frequency bands with read ranges from near-contact to 15 meters. These systems serve the primary commercial purpose of eliminating manual data entry, reducing identification errors, and enabling real-time location awareness across clinical environments. Passive RFID tags dominate unit volumes due to minimal per-unit cost, while active RFID tags capture premium margin pools in high-value asset tracking where continuous location monitoring justifies battery-powered beaconing. Asset tracking and patient identification applications lead adoption as hospitals prioritize operational efficiency and Joint Commission compliance, with medication management representing the fastest-growing application segment as unit-dose barcode-RFID hybrid verification expands.
The FDA's Unique Device Identification rule and the EU Medical Device Regulation shape product standards by mandating machine-readable identifiers on implantable and high-risk devices, directly expanding compliant RFID tag demand. HIPAA in the United States and GDPR in Europe constrain how patient-linked RFID data flows across cloud platforms, forcing vendors to architect edge-processing and localized data retention. Stakeholders must monitor how FDA guidance on cybersecurity for networked medical devices intersects with RFID reader infrastructure, as this convergence will determine which integrated platform vendors gain procurement preference in integrated delivery networks.
Market Dynamics
Hospital procurement departments are consolidating vendor relationships around integrated RFID platforms that bundle hardware, software, and analytics into single-contract arrangements, compressing the addressable market for standalone tag suppliers and elevating platform-scale vendors with end-to-end visibility architectures.
Growth Catalysts
- FDA Unique Device Identification mandate:The rule requires machine-readable identifiers on implantable and high-risk medical devices, directly expanding demand for compliant RFID tags in US health systems.
- EU Medical Device Regulation traceability requirements:MDR enforcement is accelerating tag integration across European supply chains for device lifecycle tracking and post-market surveillance compliance.
- Japan's METI digital health infrastructure investments:Government funding for hospital digitization is driving RAIN RFID deployment for real-time asset location in tertiary care facilities.
Market Restraints
- Semiconductor supply concentration:RAIN RFID chip fabrication depends on concentrated Asian foundry capacity, exposing tag manufacturers to input volatility and allocation constraints.
- HIPAA and GDPR data localization:Patient-linked RFID data flows face strict residency requirements, forcing costly edge-processing architectures and limiting cloud-native platform economics.
- Passive tag read-range limitations: Ultrahigh-frequency passive tags struggle in liquid-rich clinical environments, restricting deployment in blood banks and IV fluid inventory management.
Strategic Opportunities
- India's hospital digitization gap:Private hospital chains in tier-2 and tier-3 cities remain underpenetrated by automated identification systems, creating first-mover advantage for integrated platform vendors.
- Medication management unit-dose verification:Hybrid barcode-RFID verification at the point of administration represents an emerging high-value application with Joint Commission compliance pull-through.
- AI-enabled predictive maintenance convergence:RFID asset location data is converging with machine learning platforms to forecast equipment failure before clinical workflow disruption.
Industry Challenges
- Clinical workflow integration complexity:RFID systems must interface with legacy EHR, CMMS, and nurse call platforms, requiring expensive custom middleware development and extended implementation timelines.
- Biomedical engineering talent scarcity:Health systems lack personnel trained in both clinical device management and RFID network administration, slowing deployment velocity and increasing vendor dependency.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global RFID in Healthcare Market |
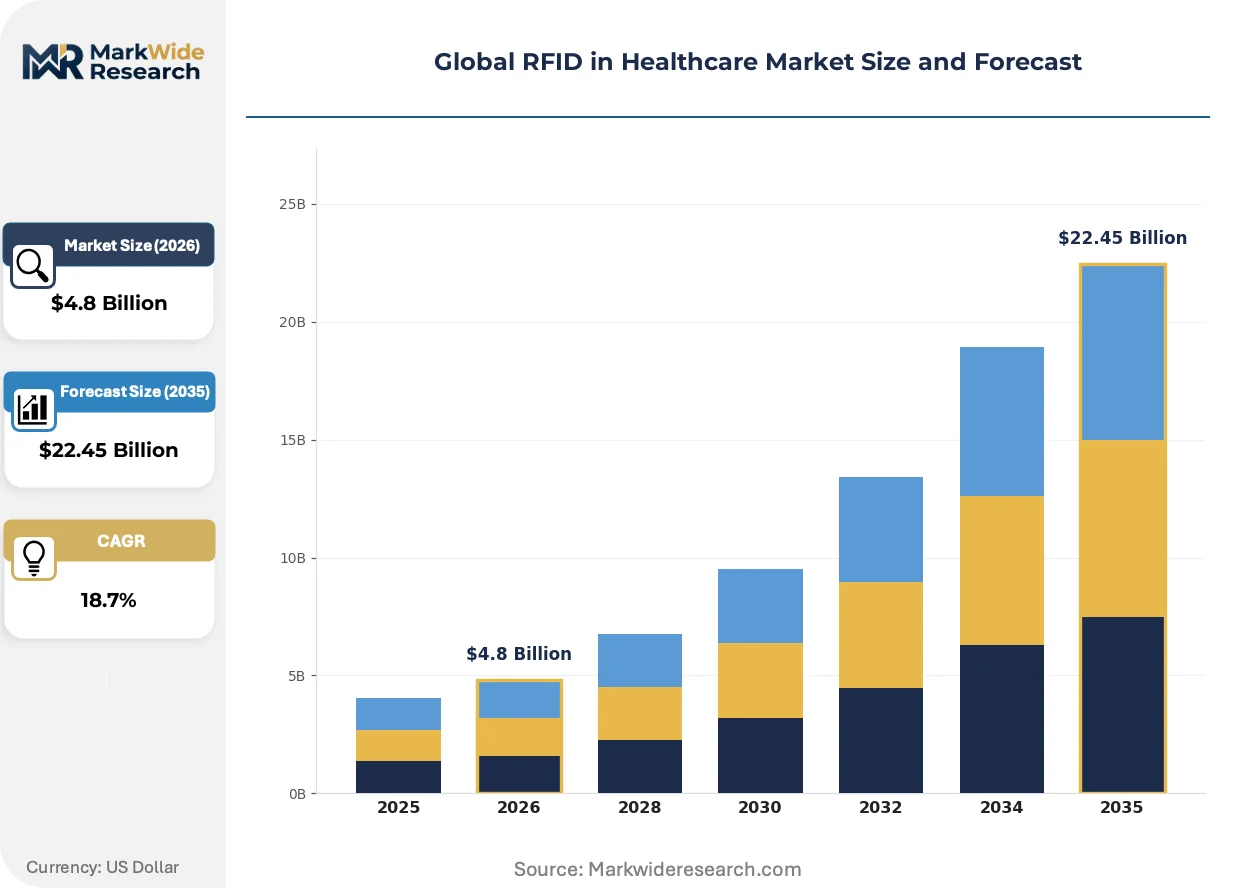
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $22.45 Billion |
| CAGR (2026 – 2036) | 18.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Active RFID Tags, Passive RFID Tags, Semi-Passive RFID Tags, RFID Readers, RFID Antennas Application: Asset Tracking, Patient Identification, Medication Management, Blood Tracking, Surgical Instrument Management End User: Hospitals, Diagnostic Laboratories, Ambulatory Surgical Centers, Long-Term Care Facilities, Pharmacies Technology: Ultrahigh Frequency, High Frequency, Low Frequency, Microwave, Near Field Communication |
| Companies Covered | Alien Technology Corporation, CenTrak, Inc., Zebra Technologies Corporation, Avery Dennison Corporation, Mobile Aspects, Inc., Impinj, Inc., GAO RFID Inc., Siemens Healthineers, Honeywell International Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global RFID in Healthcare Market Shifts & Advancements
RFID technology is migrating from discrete point solutions toward embedded intelligence within clinical workflows, with innovation concentrating on sensor fusion, regulatory-aligned data architectures, and procurement models that prioritize outcome guarantees over capital expenditure.
Sensor-integrated RFID tags are converging with temperature and humidity monitoring capabilities for cold-chain pharmaceutical tracking. Specialty pharmacies and hospital pharmacies in Germany and the United States are adopting these multi-sensor platforms for biologics inventory management. This convergence is compressing the market for standalone environmental loggers while elevating tag vendors with integrated sensing portfolios.
REACH and RoHS substance restrictions are reshaping tag material specifications across European healthcare supply chains. Manufacturers must reformulate adhesives and substrates to eliminate restricted substances while maintaining sterilization compatibility and read performance. Implantable device manufacturers face the steepest compliance burden, driving preference for European-based tag suppliers with established regulatory documentation.
Health system procurement departments are consolidating supplier relationships around performance-based contracts that tie vendor compensation to asset utilization improvements and patient safety metrics. Integrated delivery networks in the United States are leading this shift, replacing traditional hardware purchasing with subscription models that bundle tags, readers, software, and analytics. This transformation favors platform-scale vendors with balance sheet capacity to absorb upfront deployment costs.
Global RFID in Healthcare Market Segmentation
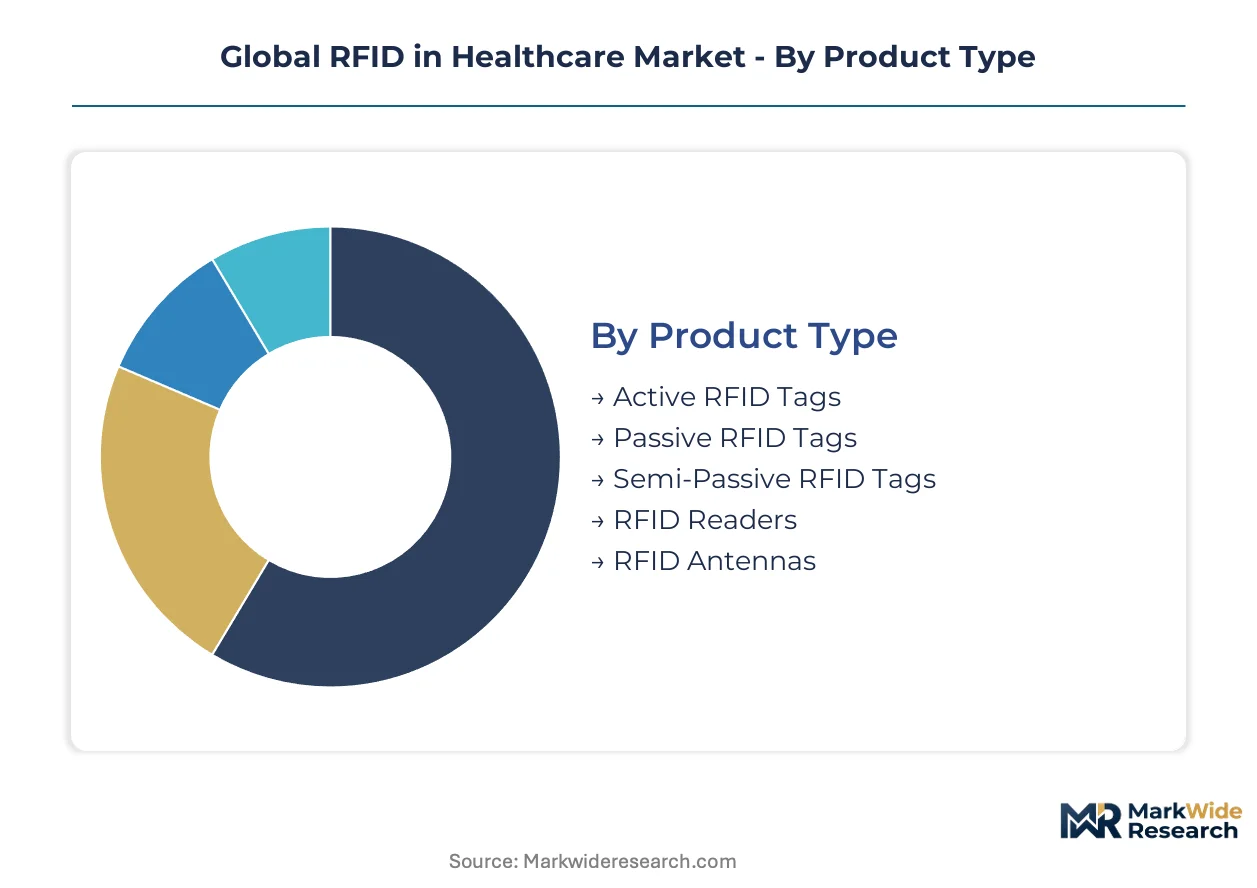
RFID segmentation in healthcare reflects divergent technology lifecycles and procurement consolidation patterns. Upgrade cycles vary sharply across product categories, with passive tag infrastructure refreshing every 5-7 years while active beacon networks demand continuous battery management and reader firmware evolution.
Product Type:
Replacement-cycle timing separates mature passive tag markets from emerging active beacon deployments, with hospital capital budgets cycling hardware refresh across multi-year horizons.
- Active RFID Tags:Battery-powered beacons transmit continuous location signals across 30-100 meter ranges, enabling real-time telemetry for ventilators and infusion pumps. Demand concentrates in tertiary US hospitals pursuing Joint Commission-compliant equipment visibility, constrained by biomedical engineering staffing gaps for battery lifecycle management.
- Passive RFID Tags:Unpowered inlays harvest reader energy for sub-15 meter identification, dominating pharmaceutical unit-dose and implantable device UDI compliance. German hospital networks and Japanese METI-funded digitization projects are driving RAIN UHF tag procurement for asset location workflows.
- Semi-Passive RFID Tags:Battery-assisted backscatter extends read range for temperature-sensitive biologics tracking in specialty pharmacy cold chains.
- RFID Readers:Fixed and handheld interrogators form infrastructure backbones, with US integrated delivery networks consolidating around single-vendor platform contracts.
- RFID Antennas:Circular and linear polarized designs optimize read zones for portal, shelf, and mobile configurations in clinical environments.
Passive RFID Tags sit at the top of the volume ranking, with Active RFID Tags climbing the fastest as continuous location monitoring displaces periodic inventory audits.
Application:
Application maturity tracks regulatory enforcement intensity, with FDA UDI and EU MDR mandates accelerating traceability deployment ahead of elective efficiency investments.
- Asset Tracking:Real-time location systems for mobile medical equipment reduce rental expenditure and eliminate hoarding behaviors. US health systems lead deployment scale, though Japan's tertiary hospitals are expanding METI-funded infrastructure for operational visibility.
- Patient Identification:Wristband and badge-based RFID verification prevents wrong-patient errors during medication administration and specimen collection. EU GDPR compliance constraints are forcing edge-processing architectures that increase per-deployment cost in European installations.
- Medication Management:Unit-dose verification at dispensing and administration points addresses Joint Commission medication safety goals.
- Blood Tracking:Cold-chain integrity monitoring for blood products leverages temperature-sensing tag integration.
- Surgical Instrument Management:Sterilization-cycle counting and set completeness verification reduce retained foreign object risk.
Asset Tracking commands the largest installed base, with Medication Management gaining share fastest as hybrid barcode-RFID verification expands beyond early-adopter health systems.
End User:
End-user procurement sophistication determines platform versus point-solution preference, with capital scale and IT integration capability shaping vendor selection criteria.
- Hospitals:Acute care facilities deploy comprehensive RFID architectures spanning asset, patient, and pharmaceutical workflows. US integrated delivery networks and German university hospitals are consolidating vendor relationships around outcome-based subscription contracts rather than capital purchases.
- Diagnostic Laboratories:Specimen tracking and workflow automation drive RFID adoption for high-throughput sample management.
- Ambulatory Surgical Centers:Limited IT staffing favors turnkey implantable device tracking solutions for UDI compliance.
- Long-Term Care Facilities:Wander management and resident identification applications leverage lower-frequency RFID for near-field reliability.
- Pharmacies:Hospital and specialty pharmacies deploy sensor-integrated tags for biologics cold-chain integrity.
Hospitals dominate procurement volume, with Diagnostic Laboratories expanding most quickly as laboratory automation investments accelerate post-pandemic.
Technology:
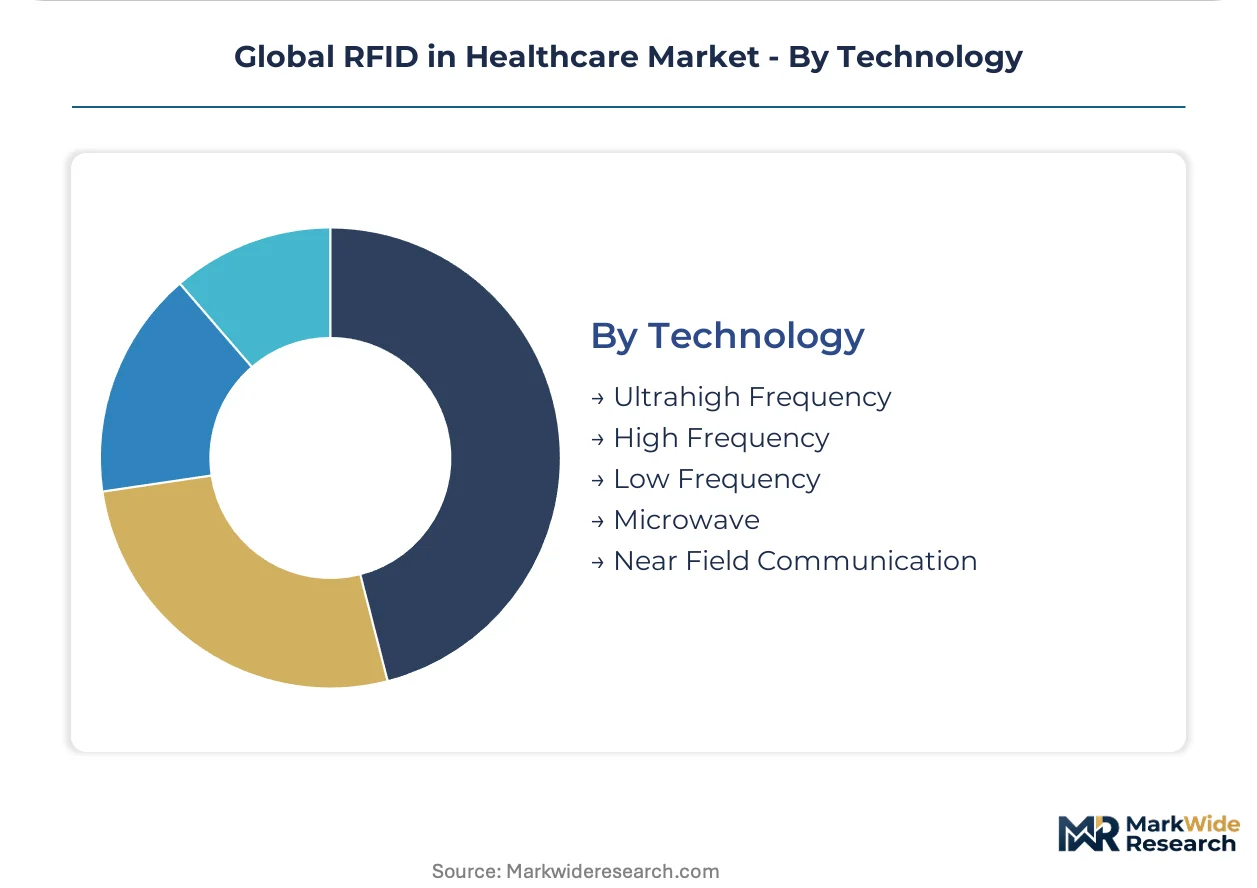
Technology selection trades read range against environmental interference, with liquid-rich clinical settings constraining ultrahigh-frequency deployment in favor of high-frequency alternatives.
- Ultrahigh Frequency:860-960 MHz RAIN RFID delivers 10-15 meter read ranges for asset location and supply chain visibility. US and German health systems are standardizing on UHF for enterprise-wide deployments, though signal attenuation in blood banks and IV fluid storage limits penetration.
- High Frequency:13.56 MHz NFC and ISO 15693 protocols enable reliable near-field reads in liquid-rich environments. Patient wristband and medication blister pack applications favor HF for immunity to body-tissue interference.
- Low Frequency:125-134 kHz systems penetrate metal and liquid with limited range, sustaining niche surgical instrument and endoscope tracking.
- Microwave:2.45 GHz and 5.8 GHz active systems support long-range beaconing for high-value asset telemetry.
- Near Field Communication:Smartphone-compatible short-range protocols enable patient and staff credential verification without dedicated reader infrastructure.
Ultrahigh Frequency holds the broadest deployment base, with Near Field Communication ascending fastest as bring-your-own-device integration reduces capital requirements for patient engagement workflows.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
RFID healthcare tracking originated in US hospital systems during the early 2000s asset management wave, then diffused to German university hospitals and Japanese tertiary facilities as digitization mandates accelerated. Today deployment patterns reflect divergent regulatory enforcement timelines and health system capital cycles.
United States
FDA's Unique Device Identification rule and Joint Commission patient safety mandates drive enterprise RFID adoption across integrated delivery networks. HIPAA data residency requirements force edge-processing architectures that increase per-deployment infrastructure costs. The Boston-Cambridge corridor hosts concentrated health IT vendors developing RFID-EHR middleware for Massachusetts General and adjacent academic medical centers.
Germany
EU Medical Device Regulation traceability deadlines accelerate compliant tag procurement for implantable device manufacturers. REACH and RoHS substance restrictions reshape adhesive formulations for sterilization-compatible tags. The Rhine-Ruhr industrial belt concentrates RFID printer and reader manufacturing, with Siemens Healthineers anchoring embedded device connectivity from Erlangen headquarters.
Japan
METI digital health infrastructure grants fund RAIN RFID deployment for real-time asset location in Tokyo and Osaka tertiary hospitals. PMDA post-market surveillance requirements align with MDR-equivalent traceability standards. The Kansai region's medical device cluster in Osaka Prefecture drives demand for sterilization-cycle tracking tags on surgical instrument sets.
India
Private hospital chains in tier-2 and tier-3 cities remain underpenetrated by automated identification, creating whitespace for integrated platform vendors. CDSCO medical device registration rules are tightening traceability expectations for imported implants. The Delhi-NCR corridor sees pilot deployments at Apollo and Max Healthcare facilities for pharmaceutical cold-chain monitoring.
United Kingdom
NHS England's operational efficiency programs prioritize asset tracking to reduce medical equipment rental expenditure across London teaching hospitals. GDPR constraints on patient-linked RFID data mirror German edge-processing requirements. The Cambridge-Oxford-London golden triangle hosts emerging health tech ventures developing NFC-enabled patient verification workflows.
Global RFID in Healthcare Market Competitive Landscape
Premium-margin players sit above commodity-margin players across platform integration depth, with end-to-end visibility vendors capturing subscription economics while standalone tag suppliers face procurement consolidation pressure. The vendor base stratifies into three tiers: semiconductor specialists controlling RAIN RFID chip design, integrated platform vendors bundling hardware-software-analytics, and regional system integrators serving single-hospital deployments. Dominant competitive moves include strategic partnerships between tag manufacturers and EHR vendors, plus backward integration by platform vendors into captive reader production.
Within the integrated platform tier, Zebra Technologies Corporation and Siemens Healthineers occupy positions spanning printer-reader infrastructure through clinical workflow software. Impinj, Inc. anchors the semiconductor-specialist archetype with RAIN RFID chip design intensity. CenTrak, Inc. exemplifies the real-time location system pure-play model. These three entities represent divergent margin structures: chip design captures R&D-intensive premiums, platform bundling secures recurring subscription revenue, and location-system specialization targets high-value asset telemetry niches.
| Leading Market Players |
|---|
| Alien Technology Corporation |
| CenTrak, Inc. |
| Zebra Technologies Corporation |
| Avery Dennison Corporation |
| Mobile Aspects, Inc. |
| Impinj, Inc. |
| GAO RFID Inc. |
| Siemens Healthineers |
| Honeywell International Inc. |
| Others |
Supply & Pricing Matrix
RAIN RFID chip fabrication costs cascade through three downstream pricing tiers, with foundry capacity allocation in Taiwan and South Korea determining tag manufacturer margins before hospital procurement departments negotiate platform-scale contracts. Semiconductor input volatility compresses margin pools for standalone passive tag suppliers while elevating integrated vendors with captive reader production and subscription pricing power.
Pricing Analysis
Outcome-based subscription contracts now dominate hospital procurement, replacing capital expenditure models with recurring revenue tied to asset utilization metrics. Three-tier pricing structure across enterprise platform, mid-tier bundled, and economy tag-only levels separates vendors by software-analytics depth and EHR integration certification. Cost compression in passive inlays is intensifying because foundry allocation constraints force tag manufacturers to absorb silicon price swings. Standalone tag suppliers face acute price sensitivity from Indian and Southeast Asian hospital chains, while US integrated delivery networks prioritize outcome guarantees over per-unit tag economics.
Supply Chain Analysis
Single-source vulnerability sits with Taiwan-based foundry capacity for RAIN RFID chip fabrication, where concentrated 12-inch wafer production feeds global tag manufacturing. Raw material dependencies include silicon wafers, copper antenna substrates, and sterilization-compatible adhesives subject to REACH and RoHS compliance. Tariff exposure runs through US-China medical device component trade flows, particularly for reader electronics and printer hardware. Distribution runs through authorized healthcare IT distributors in Germany and Japan, direct platform vendor relationships with US IDNs, and emerging third-party logistics channels for Indian private hospital chains.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
RFID in healthcare operates as a regulatory compounder where FDA's UDI mandate and EU MDR traceability deadlines generate durable demand pull-through for compliant tag and platform vendors.
For Market Incumbents: Lock in hospital system relationships through EHR-embedded workflow integration that raises switching costs for competing platforms. Deepen backward integration into captive reader manufacturing to defend margin pools against commoditizing passive tag suppliers. The threat of AI-enabled predictive maintenance convergence from industrial IoT vendors demands accelerated software companion development for asset telemetry analytics. For New Entrants and Emerging Players: EHR middleware specialists represent the most penetrable channel for platform access without direct reader hardware investment. India's tier-2 and tier-3 private hospital chains offer whitespace for integrated platform vendors willing to absorb upfront deployment costs against long-term subscription revenue. A go-to-market angle through Joint Commission compliance consulting creates differentiated entry against established hardware vendors. For Investors and Strategic Acquirers: Consolidation pressure builds where standalone tag manufacturers lack software-analytics capabilities to meet procurement department platform consolidation demands. Acquisition targets include RAIN RFID chip design specialists with FDA UDI certification documentation and European-based tag suppliers with established REACH compliance portfolios. The signal to watch is hospital GPO contract consolidation toward single-vendor platform arrangements, which will determine which integrated vendors achieve procurement preference at scale.| Strategic Initiative | Industry Significance |
|---|---|
| FDA UDI Compliance Certification | Unlocks procurement access to US implantable device manufacturers facing mandate deadlines. |
| Hospital System Partnership | Secures outcome-based subscription contracts with IDNs replacing capital purchase models. |
| Sensor-Integrated Tag Development | Captures biologics cold-chain monitoring demand from German specialty pharmacies. |
| EHR Middleware Integration | Reduces clinical workflow friction that slows deployment velocity and extends sales cycles. |
| Edge-Processing Architecture Investment | Addresses HIPAA and GDPR data localization constraints limiting cloud-native platform economics. |
Research Methodology
Multiple input streams — hospital procurement database analysis, GPO contract documentation, and CMS Medicare reimbursement filings — were reconciled against primary interviews with biomedical engineers, hospital purchasing committee members, and RFID platform vendor sales executives. Secondary validation drew from FDA UDI database extracts, EU MDR notified body certification records, and METI digital health infrastructure grant disclosures. Bottom-up tag volume estimates and top-down platform revenue analysis were triangulated to constrain forecast variance.
Data-stream reconciliation applied across product type, application, end-user facility scale, and regional regulatory cluster dimensions throughout the forecast period. CAGRs were derived from installed base refresh cycles, mandate enforcement timelines, and digitization investment intensity by health system capital availability. Industry-specific forecast inputs included Joint Commission survey deficiency patterns and PMDA post-market surveillance reporting volumes.
Revisions become necessary when semiconductor foundry allocation disruptions, regulatory guidance changes on cybersecurity for networked medical devices, or health system merger activity that consolidates procurement authority materialize. Forecasts reflect documented assumptions about mandate enforcement consistency and capital budget availability. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Healthcare IT
Healthcare Revenue Cycle Management (RCM) Software Market
Healthcare IT
Technology Spending on Revenue Cycle Management Market
Healthcare IT
Global Technology Spending on Core Administration in Healthcare Market
Healthcare IT
US Healthcare IT Market
Healthcare IT
Europe Hospital Capacity Management Solutions Market
Healthcare IT
US Long Term Care Software Market
Healthcare IT
Clinical Healthcare IT Market
Healthcare IT
Hand Hygiene Monitoring System Market
Healthcare IT
Metabolic Rate Analysis System Market
Healthcare IT
Healthcare Mobility Solutions Market
Healthcare IT
Healthcare Technology Management Market
Healthcare IT
Aged Care Software Market
Healthcare IT
Non-Clinical Homecare Software Market
Healthcare IT
North America Internet of Medical Things (Iomt) Market
Healthcare IT
Post-Acute Transition Care Coordination Platform Market
Healthcare IT
Digital Mhealth Solution Market