
 Secure Messaging in Healthcare Market | 2026-2036
Secure Messaging in Healthcare Market Size, Share, and Industry Trends Forecast 2026-2036
Secure Messaging in Healthcare Market Analytics
Specialty clinics and ambulatory surgery centers is redrawing procurement patterns in secure healthcare messaging, overtaking traditional hospital IT departments as the fastest-growing buyer archetype. TigerConnect leverages cloud-native architecture to anchor enterprise deployments across multi-hospital networks. Vocera Communications dominates clinical workflow integration with voice-enabled secure messaging for nursing staff. Imprivata differentiates through biometric authentication layers that sustain compliance in high-acuity environments.
Secure messaging in healthcare denotes encrypted, audit-capable communication platforms engineered for clinical workflows, typically employing AES-256 encryption, TLS 1.3 transport protocols, and role-based access controls to protect protected health information during provider-to-provider and provider-to-patient exchanges. Cloud-based technology leads deployment preference due to lower capital overhead and faster implementation cycles, while API-based integration levels capture expanding margin pools as health systems demand seamless connectivity with existing EHR infrastructure. Mobile application delivery represents the fastest-growing technology segment, reflecting clinician demand for smartphone-native workflows that operate outside fixed workstation environments.
FDA oversight of clinical decision support functions embedded within messaging platforms, coupled with HIPAA Security Rule enforcement by the Office for Civil Rights, shapes product development roadmaps and liability frameworks for vendors seeking US market access. GDPR compliance requirements in Europe impose data residency constraints that fragment cloud architecture strategies across jurisdictions. Stakeholders must monitor evolving CMS reimbursement rules for remote patient monitoring, as payment policy shifts will determine whether secure messaging remains a cost center or becomes a revenue-generating clinical service line.
Market Dynamics
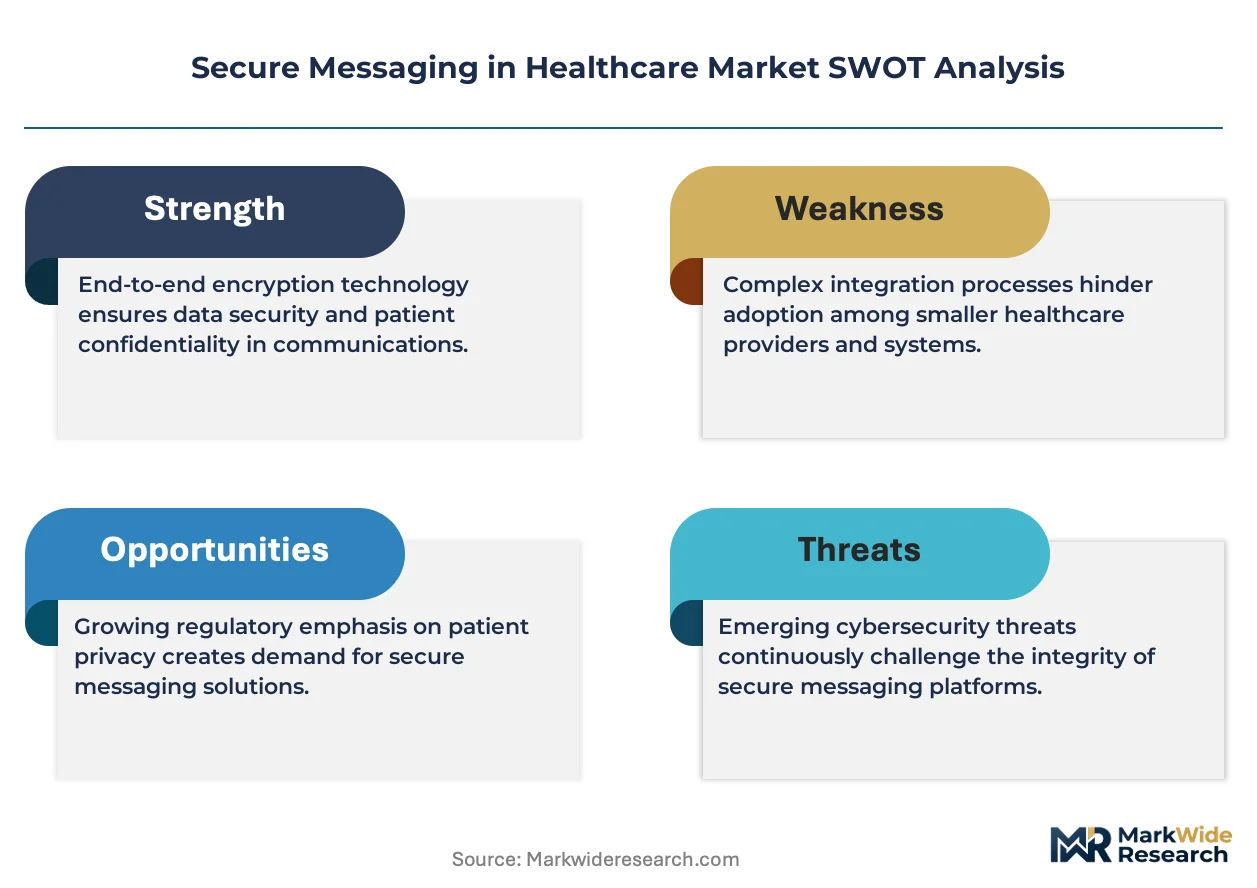
Hospital system consolidation in the United States is compressing vendor lists and forcing secure messaging platforms to prove enterprise scalability across multi-facility networks, reshaping competitive dynamics toward integrated suite providers and away from point solutions.
Growth Catalysts
- HIPAA Security Rule enforcement:The Office for Civil Rights intensifies audit activity, compelling healthcare organizations to replace consumer-grade messaging with purpose-built clinical platforms that provide audit trails and access controls.
- Telehealth workflow embedding:Virtual care models integrate encrypted communication into routine clinical operations, creating persistent demand for messaging infrastructure that bridges synchronous video and asynchronous text.
- API-first architecture:Health systems demand seamless connectivity with existing EHR infrastructure, rewarding vendors who deliver robust integration layers that reduce implementation friction.
Market Restraints
- Data residency fragmentation:GDPR compliance requirements in Europe impose jurisdictional constraints that complicate cloud architecture strategies and inflate operational overhead for multi-national deployments.
- Biometric hardware costs:High-acuity environments require fingerprint or facial recognition authentication layers, adding capital expenditure that slows adoption in budget-constrained ambulatory settings.
- FDA oversight expansion:Clinical decision support functions embedded within messaging platforms trigger medical device classification requirements, extending development timelines and liability exposure.
Strategic Opportunities
- Specialty clinic penetration:Ambulatory surgery centers and specialty clinics represent underpenetrated buyers with distinct workflow requirements and faster procurement cycles than hospital IT departments.
- Remote patient monitoring convergence:CMS reimbursement rules for RPM create pathways to transform secure messaging from cost center into revenue-generating clinical service line.
- Smartphone-native deployment:Mobile application delivery channels enable clinicians to operate outside fixed workstation environments, opening new user segments in home health and emergency medical services.
Industry Challenges
- Cybersecurity talent scarcity:Healthcare organizations struggle to recruit specialists capable of configuring role-based access controls and managing TLS 1.3 certificate lifecycles across distributed environments.
- Legacy EHR integration complexity:Proprietary data formats and inconsistent HL7 FHIR implementation create friction when connecting modern messaging platforms to decades-old hospital information systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Secure Messaging in Healthcare Market |
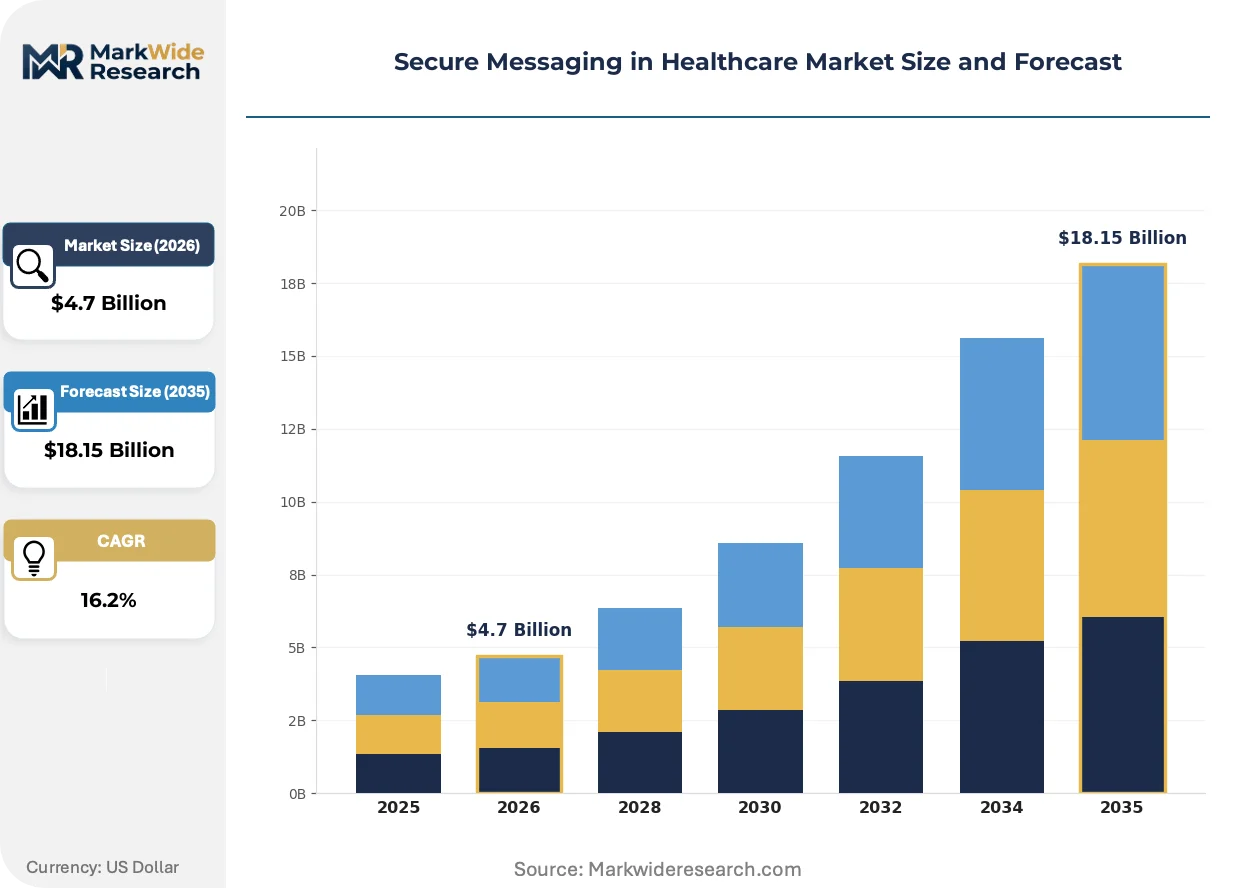
| Market Size in 2026 | $4.7 Billion |
| Market Size in 2035 | $18.15 Billion |
| CAGR (2026 – 2036) | 16.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Encryption, Cloud-Based, On-Premise, Mobile Application End User: Clinics, Hospitals, Labs, Telehealth Providers Compliance Standard: HIPAA, GDPR, Confidentiality Agreements, ISO 27001 Integration Level: Standalone, EHR Integrated, API-Based, Cross-Platform |
| Companies Covered | TigerConnect, Vocera Communications, Imprivata, OnPage, Spok, PerfectServe, QliqSOFT, PatientSafe Solutions, Hypercare, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Secure Messaging in Healthcare Market Evolving Landscape
Encrypted communication infrastructure is fragmenting into modular components that health systems assemble rather than purchase as monolithic suites, forcing vendors to compete on interoperability credentials and API depth.
AES-256 encryption with TLS 1.3 transport protocols now serves as the baseline security layer for clinical messaging platforms. Specialty clinics and ambulatory surgery centers adopt these standards faster than hospital networks due to lighter governance overhead. Cloud-native architecture is decomposing traditional on-premise deployment models, enabling faster scaling but introducing new vendor dependency risks.
GDPR data residency requirements reshape how vendors architect cloud infrastructure across European jurisdictions. National regulators in France, Germany, and the Netherlands enforce divergent interpretations of lawful processing, fragmenting previously unified deployment strategies. Healthcare organizations respond by demanding region-specific instance isolation and contractual data location guarantees.
Clinicians now expect smartphone-native workflows that mirror consumer messaging experiences while maintaining clinical-grade security. Nursing staff and emergency physicians drive this preference, rejecting workstation-tethered solutions that interrupt care continuity. United States health systems lead this behavioral shift, with rural hospitals and community clinics following urban academic medical centers by eighteen to twenty-four months.
Secure Messaging in Healthcare Market Segmentation
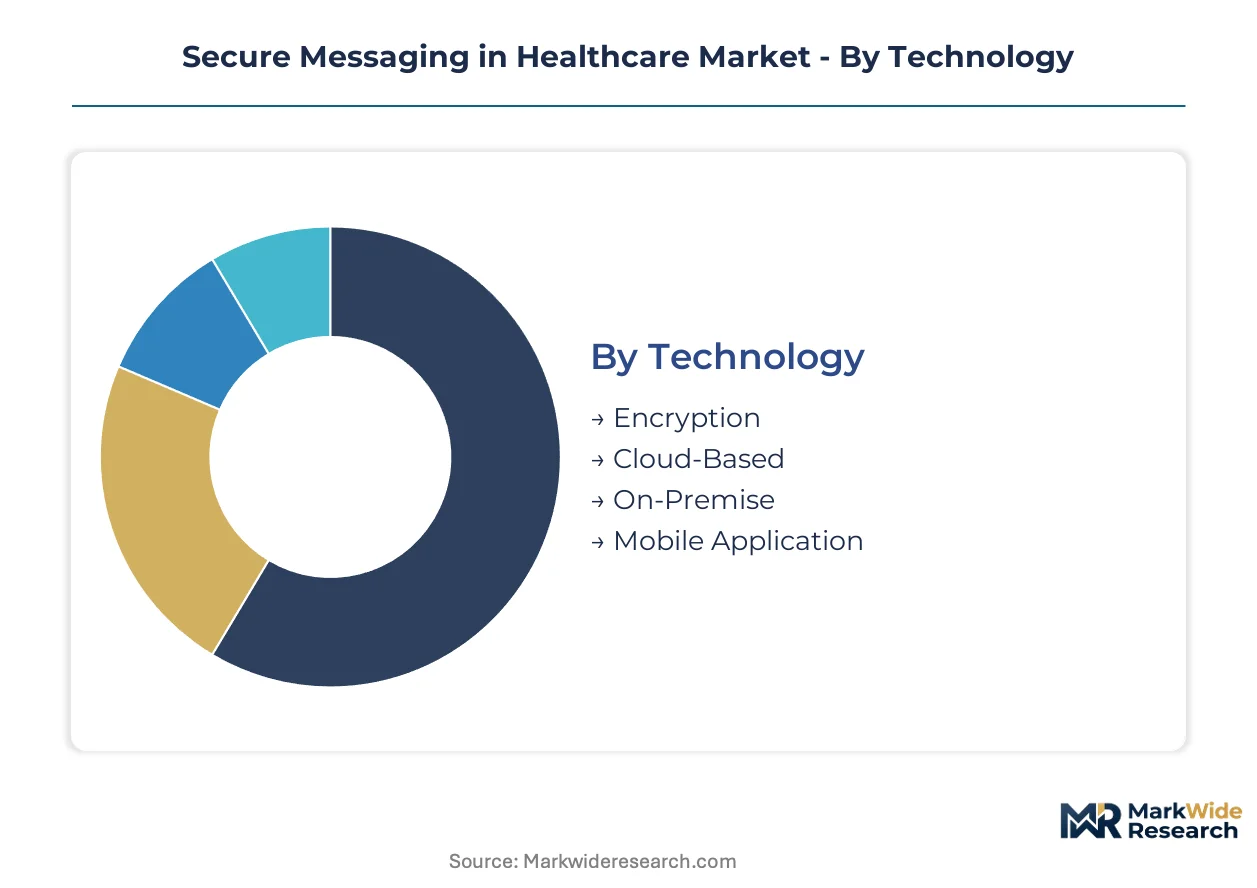
Segmentation in secure healthcare messaging reveals how compliance mandates, deployment architectures, and clinical workflow integration create divergent value pools. Vendors must align technical roadmaps with the substitution pressures each segment faces from adjacent communication technologies.
Technology:
Cloud-Based and Mobile Application segments confront the most acute substitution pressure from consumer-grade platforms that clinicians already use daily, forcing vendors to differentiate through audit trails and clinical workflow embedding.
- Cloud-Based:Multi-tenant architectures with elastic compute provisioning enable rapid scaling across hospital networks without capital infrastructure. Demand concentrates in United States health systems pursuing enterprise consolidation, driven by federal interoperability rules that mandate seamless data exchange across facilities. Cloud deployments reduce implementation cycles from months to weeks.
- Mobile Application:Native iOS and Android applications with biometric authentication layers support smartphone-native clinical workflows outside fixed workstation environments. Nursing staff and emergency physicians in United States academic medical centers drive adoption fastest, rejecting tethered solutions that interrupt care continuity. Push notification architectures require hardened TLS 1.3 certificate management.
- Encryption:AES-256 cipher implementations with end-to-end key management serve as the foundational security layer across all deployment modes. United States HIPAA enforcement elevates encryption from feature to procurement prerequisite.
- On-Premise:Air-gapped server installations within hospital data centers satisfy data residency requirements for high-acuity environments. European GDPR interpretations and United States Department of Defense facilities sustain residual demand despite cloud migration trends.
Cloud-Based retains volume leadership; Mobile Application holds the steepest expansion curve.
End User:
Cost tier stratification separates enterprise hospital deployments from ambulatory settings, with procurement authority and budget scale determining solution sophistication and vendor selection criteria.
- Telehealth Providers:Virtual care platforms embed encrypted messaging into synchronous video workflows, requiring asynchronous text bridges for pre-visit triage and post-visit follow-up. United States reimbursement policy shifts toward remote patient monitoring create revenue-generating service line potential beyond cost center status. API-first architectures dominate procurement specifications.
- Hospitals:Multi-facility networks demand enterprise scalability with role-based access controls spanning emergency departments, surgical suites, and administrative functions. United States hospital system consolidation compresses vendor lists toward integrated suite providers. Biometric authentication layers add capital expenditure in high-acuity zones.
- Clinics:Specialty and primary care ambulatory settings prioritize rapid deployment and lower total cost of ownership over deep EHR integration. Faster procurement cycles than hospital IT departments enable point solution penetration.
- Labs:Diagnostic and pathology services require secure result delivery workflows with automated alert routing to ordering physicians. Integration with laboratory information systems shapes vendor selection.
Hospitals retain volume leadership; Telehealth Providers hold the steepest expansion curve.
Compliance Standard:
Geographic jurisdiction determines which compliance frameworks carry binding procurement weight, fragmenting vendor product development and cloud architecture strategies across markets.
- HIPAA:United States Security Rule enforcement by the Office for Civil Rights mandates audit trails, access controls, and breach notification protocols for all covered entities. Intensifying audit activity compels replacement of consumer-grade messaging. Business associate agreements structure vendor liability frameworks.
- GDPR:European data residency requirements impose jurisdictional constraints on cloud infrastructure, with France, Germany, and the Netherlands enforcing divergent lawful processing interpretations. Region-specific instance isolation becomes contractual necessity.
- ISO 27001:Information security management system certification provides vendor-agnostic assurance framework adopted by multinational health systems seeking standardized procurement criteria across operating geographies.
- Confidentiality Agreements:Contractual data protection clauses supplement regulatory frameworks in private pay and research settings where statutory coverage gaps exist.
HIPAA retains volume leadership; GDPR holds the steepest expansion curve.
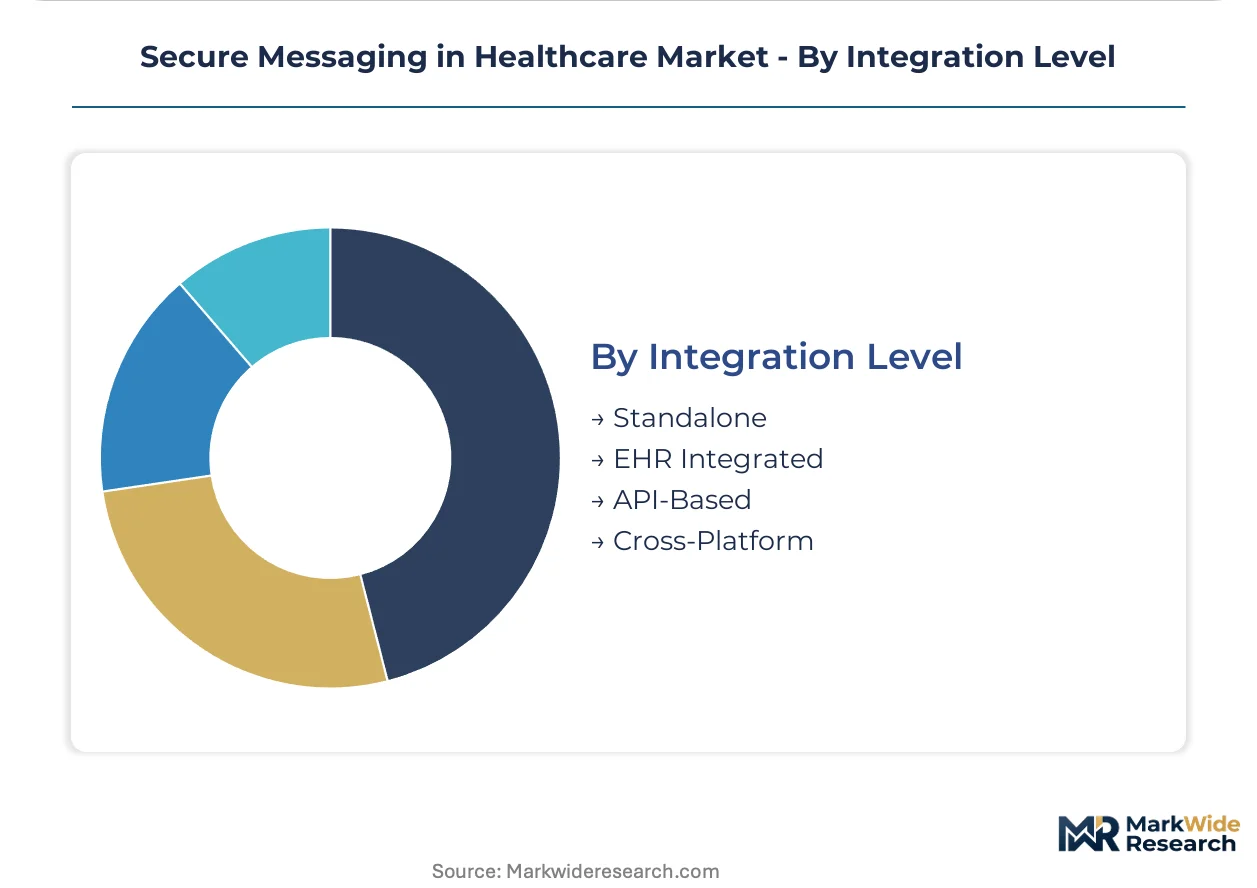
Integration Level:
Margin concentration shifts toward API-based and EHR-integrated deployments as health systems prioritize seamless connectivity over standalone functionality, reshaping vendor competitive positioning.
- API-Based:RESTful and FHIR-compliant interfaces enable bidirectional data flow between messaging platforms and existing clinical systems without proprietary middleware. United States health systems reward vendors reducing implementation friction through robust integration layers. Developer ecosystem depth becomes differentiation axis.
- EHR Integrated:Native modules within Epic, Cerner, and Meditech environments embed messaging into established clinical workflows with unified authentication. Deep integration captures premium pricing but extends sales cycles.
- Standalone:Purpose-built messaging platforms without EHR connectivity serve niche use cases and budget-constrained settings willing to sacrifice workflow continuity for cost reduction.
- Cross-Platform:Interoperability layers spanning multiple vendor ecosystems address health system consolidation scenarios with heterogeneous legacy infrastructure.
EHR Integrated retains volume leadership; API-Based holds the steepest expansion curve.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States healthcare IT backbone, anchored by the Health Information Technology for Economic and Clinical Health Act infrastructure investments, underwrites North American dominance in secure clinical messaging deployment and vendor headquarters concentration.
United States
Hospital system consolidation and federal interoperability mandates from the Office of the National Coordinator drive enterprise-scale secure messaging procurement across multi-facility networks. HIPAA Security Rule enforcement by the Office for Civil Rights intensifies audit activity, compelling replacement of consumer-grade platforms. The Boston-Cambridge health tech corridor and Silicon Valley host the dominant vendor ecosystems.
Germany
GDPR data residency requirements and the Digital Care Act (DVG) reimbursement frameworks accelerate encrypted clinical communication adoption in statutory health insurance networks. The country's national pharmaceutical regulator enforces strict data localization for telemedicine platforms. The Rhine-Ruhr metropolitan region concentrates health IT procurement authority for university hospital networks.
United Kingdom
NHS Digital's mandate for secure communication standards across integrated care systems creates centralized procurement pathways for clinical messaging infrastructure. The Medicines and Healthcare products Regulatory Agency oversees software-as-medical-device classifications for decision-support features. London's NHS trusts lead deployment velocity, with Manchester and Birmingham health systems following by twelve to eighteen months.
France
The national health data hub (Health Data Hub) and ANSM/CNIL joint oversight of digital health tools reshape vendor compliance requirements for cloud-hosted clinical communication. Data residency constraints fragment previously unified European deployment strategies. The Paris-Saclay cluster concentrates health informatics research and vendor development activity.
Japan
Revised telemedicine reimbursement rules under Ministry of Health, Labour and Welfare guidelines embed encrypted messaging into routine virtual care workflows. PMDA software guidance documents establish liability frameworks for clinical decision support functions. The Tokyo-Osaka corridor dominates health system procurement scale and vendor partnership formation.
Secure Messaging in Healthcare Market Competitive Landscape
Concentration sits with cloud-native platform specialists and clinical workflow integrators competing for enterprise health system contracts. The vendor landscape exhibits moderate fragmentation beneath a tier of scaled incumbents, with point solution providers filling niche ambulatory segments. Two strategic archetypes dominate: integrated suite providers leveraging EHR partnerships, and mobile-first specialists capturing nursing and emergency physician workflows. Competitive moves center on API ecosystem expansion and biometric authentication layer acquisition.
Within the cloud-native enterprise tier, TigerConnect and Vocera Communications exemplify divergent positioning strategies, while Imprivata occupies a position in high-acuity authentication specialization. TigerConnect anchors multi-hospital network deployments through elastic infrastructure. Vocera Communications represents voice-enabled workflow integration for bedside care teams. Imprivata exemplifies biometric-layer compliance architecture for controlled clinical environments.
| Leading Market Players |
|---|
| TigerConnect |
| Vocera Communications |
| Imprivata |
| OnPage |
| Spok |
| PerfectServe |
| QliqSOFT |
| PatientSafe Solutions |
| Hypercare |
| Others |
Value Network & Pricing Analysis
Cloud-native infrastructure substitution for on-premise server deployments simultaneously redistributes vendor cost structures toward recurring SaaS models and compresses capital expenditure barriers for ambulatory buyers. This shift concentrates pricing power with multi-tenant platform operators while fragmenting procurement authority across specialty clinic networks.
Pricing Analysis
Volume-discount tiering structures separate enterprise hospital networks from ambulatory surgery centers and specialty clinics. Three-tier pricing stratifies across premium EHR-integrated deployments, standard API-connected configurations, and economy standalone licenses. Price differentiation rests on certification depth—HIPAA Business Associate Agreement complexity and ISO 27001 audit scope—rather than core encryption standards. Cost compression in the economy tier intensifies because consumer-grade platform substitution threatens budget-conscious clinic segments. Telehealth providers exhibit lowest price sensitivity due to CMS reimbursement pathway monetization, while independent primary care practices face acute budget constraints.
Supply Chain Analysis
TLS 1.3 certificate authority bottlenecks in United States and European Union jurisdictions constrain rapid platform scaling for vendors pursuing multi-national deployment. Cloud infrastructure provisioning draws from hyperscaler data center networks concentrated in Virginia, Frankfurt, and Singapore regions. AES-256 cryptographic module sourcing hinges on FIPS 140-2 validated hardware security modules from United States and South Korean semiconductor fabricators. Single-source vulnerability in biometric authentication sensor supply creates procurement risk for high-acuity environment deployments. Distribution runs through direct enterprise sales teams supplemented by health system GPO contracting vehicles.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Secure healthcare messaging functions as a service-attach opportunity where API management and compliance audit subscriptions expand faster than core platform licensing. Recurring revenue from clinical workflow integration layers outpaces one-time implementation fees.
For Market Incumbents: Compound defensive moats through biometric authentication layer acquisition and EHR-native module deepening. TigerConnect and Vocera Communications face substitution threat from consumer-platform entrants exploiting clinician familiarity. Vertical integration into TLS certificate lifecycle management reduces dependency on third-party infrastructure vendors.
For New Entrants and Emerging Players: Lead with smartphone-native deployment targeting emergency medical services and home health agencies where workstation-tethered incumbents lack presence. Specialty clinics in United States secondary metropolitan areas offer fastest procurement cycles and lowest competitive density. API-first go-to-market positioning reduces implementation friction against legacy EHR environments.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed cloud communication platforms seeking healthcare vertical expansion. Five-to-ten year viability hinges on FDA oversight navigation for clinical decision support functions. Watch CMS remote patient monitoring reimbursement rule expansion as inflection signal for revenue model transformation from cost center to service line.
| Strategic Initiative | Industry Significance |
|---|---|
| Biometric Authentication Acquisition | Fingerprint and facial recognition layers satisfy HIPAA Security Rule access control mandates in high-acuity zones. |
| API Ecosystem Expansion | FHIR-compliant interfaces reduce Epic and Cerner integration friction for hospital system consolidation scenarios. |
| GDPR Data Residency Architecture | Region-specific cloud instance isolation enables French and German statutory health insurance network penetration. |
| Remote Patient Monitoring Convergence | CMS reimbursement alignment transforms secure messaging from administrative cost center to billable clinical service. |
| Mobile-First Clinical Workflow Design | Native iOS and Android applications capture nursing staff and emergency physician smartphone-native preferences. |
Research Methodology
A spread of perspectives from hospital CIOs, telehealth platform engineers, GPO contracts managers, and HIPAA compliance officers converged on the working assumptions underlying demand modeling. Primary fieldwork combined structured interviews with secondary validation against FDA 510(k) filings, CMS Medicare reimbursement databases, hospital procurement records, and Office for Civil Rights breach notification archives. Bottom-up facility-level deployment tracking triangulated against top-down vendor revenue attribution across cloud infrastructure and mobile application delivery segments.
Segmentation dimensions modeled include deployment architecture, end-user facility type, compliance standard jurisdiction, and EHR integration depth across the projection horizon. CAGRs were derived from facility adoption curve analysis and vendor booking pattern reconciliation. Forecast inputs incorporated HIPAA audit enforcement intensity trajectories and telehealth reimbursement policy evolution without assuming specific regulatory calendar dates.
Forecasts assume regulatory continuity in United States HIPAA Security Rule enforcement and European GDPR data residency interpretations; material policy shifts would require re-modeling provider liability frameworks and cloud architecture strategies. Practitioners should keep alternative scenarios live as FDA software-as-medical-device classification scope and CMS remote patient monitoring payment rules evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Healthcare IT
Pharmaceutical Quality Management Systems Market
Healthcare IT
Prior Authorization Software Market
Healthcare IT
Neurosurgery Software Market
Healthcare IT
Global Cancer Registry Software Market
Healthcare IT
Healthcare IT Services Market
Healthcare IT
Healthcare Credentialing Software Market
Healthcare IT
Operating Room Management Software Market
Healthcare IT
Veterinary Practice Management Software Market
Healthcare IT
North America Long-Term Care Software Market
Healthcare IT
Medical Specimen Tracking System Market
Healthcare IT
IP-Based Nurse Call System Market
Healthcare IT
Healthcare Smart Card Reader Market
Healthcare IT
Clinical Perinatal Software Market
Healthcare IT
Patient Self-Service Kiosks Market
Healthcare IT
Integrated Operating Room Management Systems Market
Healthcare IT
Ambulatory Surgical Centers IT Services Market