
 North America Long-Term Care Software Market | 2026-2036
North America Long-Term Care Software Market Size, Share, and Industry Trends Forecast 2026-2036
North America Long-Term Care Software Market Intelligence
Subscription-based analytics modules is realigning how vendors monetize long-term care platforms. PointClickCare leverages cloud infrastructure to anchor its dominance in skilled nursing interoperability. McKesson Corporation sustains channel control through distribution networks that extend into pharmacy management workflows. Netsmart Technologies specializes in behavioral health integration within post-acute settings.
Long-term care software comprises clinical documentation, billing, scheduling, and regulatory compliance applications designed for post-acute and residential care settings. These systems typically integrate HL7 FHIR interfaces, real-time claims scrubbing engines, and medication administration records to coordinate care across multidisciplinary teams. Cloud-based solutions now lead deployment preference as nursing homes retire legacy client-server architectures. Home healthcare agencies represent the fastest-growing end-user category, driven by Medicare Advantage expansion into community-based services. Maintenance services capture concentrated margin pools as facilities prioritize uptime guarantees over upfront licensing.
CMS Conditions of Participation enforce minimum electronic health record functionality for Medicare-certified facilities, while HIPAA Security Rule audits shape vendor data architecture requirements. State Medicaid agencies in Texas, Florida, and California layer supplemental certification standards that fragment procurement specifications. Ontario's Ministry of Long-Term Care mandates standardized reporting protocols that differ from US federal frameworks. Stakeholders must monitor divergence between federal payment reform timelines and state implementation schedules when committing to platform investments.
Market Dynamics
CMS reimbursement rules are forcing skilled nursing facilities to abandon fragmented point solutions in favor of unified platforms that demonstrate measurable clinical outcomes. State Medicaid agencies layer supplemental requirements that fragment procurement timelines and vendor qualification processes.
Growth Catalysts
- Interoperability mandates:CMS Conditions of Participation require Medicare-certified facilities to demonstrate seamless data exchange across care transitions, accelerating replacement of legacy siloed systems.
- Medicare Advantage expansion:Payers are directing volume toward community-based care settings, creating demand for mobile-first documentation tools among home health agencies.
- Texas Medicaid waivers:State-level supplemental certification standards for managed long-term services and supports are mandating real-time reporting capabilities that legacy infrastructure cannot satisfy.
Market Restraints
- Implementation cost structure:Cloud migration requires substantial upfront capital for data migration and staff retraining, straining independent nursing home operators with thin operating margins.
- Vendor concentration risk:Dominant cloud infrastructure providers create single points of failure for mission-critical uptime guarantees that facilities cannot tolerate.
- Technical debt burden:Decades-old client-server architectures in incumbent facilities resist modular upgrade paths, forcing rip-and-replace decisions that extend sales cycles.
Strategic Opportunities
- Behavioral health convergence:Post-acute settings are absorbing behavioral health integration requirements that existing EHR platforms address inadequately, opening white space for specialized modules.
- Ontario standardization:The province's mandated reporting protocols differ materially from US frameworks, creating demand for configurable platforms that span both regulatory environments.
- Subscription analytics:Predictive risk stratification tools are penetrating skilled nursing workflows as facilities seek to reduce preventable hospital readmissions and capture value-based payments.
Industry Challenges
- Clinical informatics talent scarcity:Facilities struggle to recruit staff capable of configuring population health dashboards and interpreting algorithmic alerts.
- HIPAA Security Rule audit complexity:Vendor data architecture must satisfy evolving OCR enforcement priorities that delay product releases and extend compliance timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Long-Term Care Software Market |
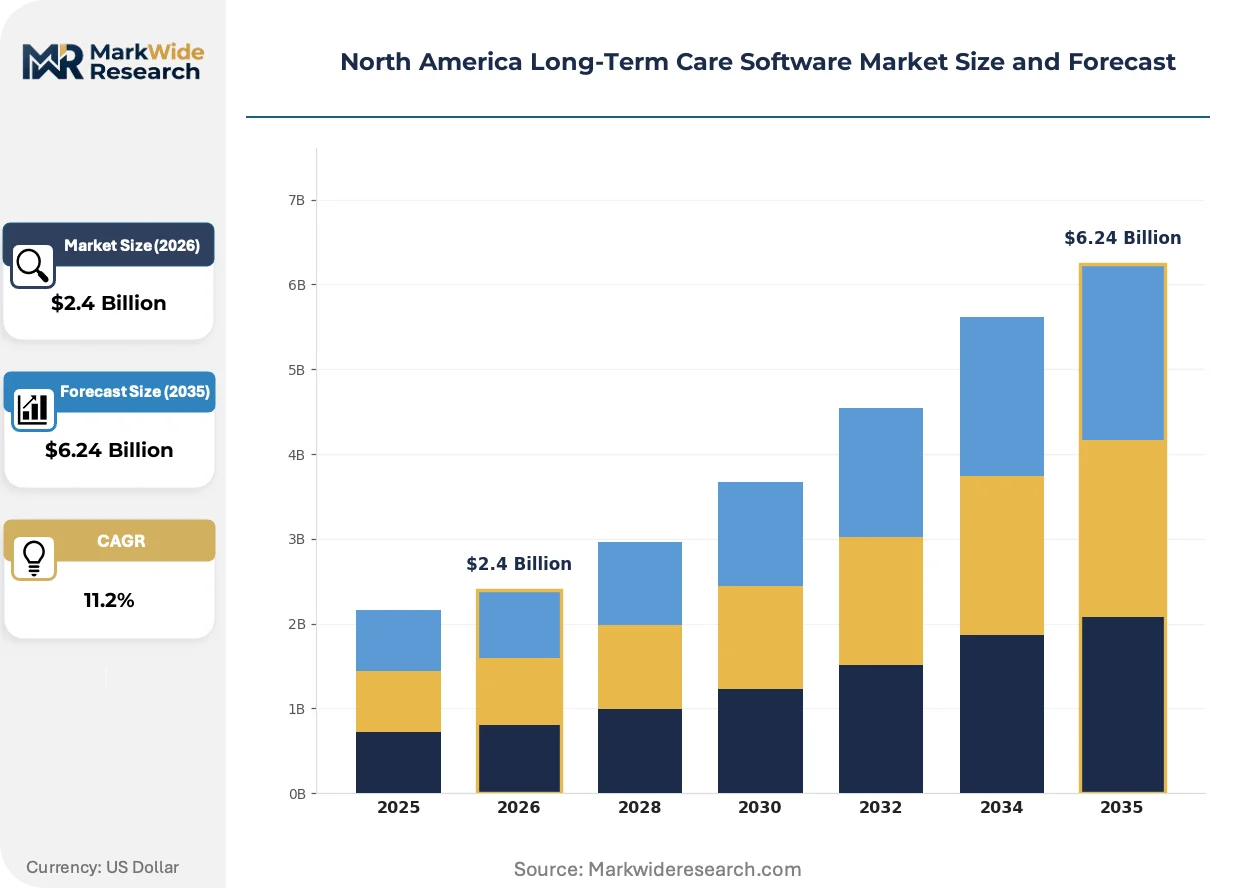
| Market Size in 2026 | $2.4 Billion |
| Market Size in 2035 | $6.24 Billion |
| CAGR (2026 – 2036) | 11.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cloud-Based Solutions, On-Premises Solutions, Hybrid Solutions, Mobile Applications End User: Nursing Homes, Home Healthcare Agencies, Assisted Living Facilities, Continuing Care Retirement Communities Installation: Remote Installation, On-Site Installation, Self-Service Installation, Customized Installation Service Type: Training Services, Maintenance Services, Consulting Services, Technical Support |
| Companies Covered | Veradigm LLC (Allscripts Healthcare), McKesson Corporation, PointClickCare, Medtelligent, Inc., VITALS SOFTWARE, Netsmart Technologies, Inc., Cerner Corporation (Oracle Corporation), Omnicell, Inc., MatrixCare, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Long-Term Care Software Market Strategic Shifts & Innovations
Artificial intelligence is penetrating clinical documentation workflows, automating coding accuracy and risk adjustment calculations that previously demanded specialized staff. Vendors are racing to embed predictive capabilities that differentiate commodity platform offerings.
Natural language processing is absorbing unstructured clinical notes into structured data repositories that feed quality measurement and reimbursement optimization. Skilled nursing facilities are piloting ambient documentation tools that capture provider-patient encounters without keyboard entry. This automation is compressing documentation burden and redirecting nursing hours toward direct care activities.
CMS Conditions of Participation updates are mandating minimum electronic health record functionality thresholds for Medicare certification eligibility. Facilities must demonstrate interoperability capabilities and quality reporting submission by specified deadlines or face reimbursement penalties. Skilled nursing operators in Texas and Florida are prioritizing vendor selection based on proven compliance track records rather than feature breadth.
Consolidated purchasing by multi-facility operators is compressing vendor sales cycles and intensifying price competition. Large regional chains are demanding standardized platforms across their portfolios, displacing the historical pattern of site-by-site procurement autonomy. This concentration is most visible in California and New York, where private equity-backed operators have aggregated substantial bed capacity.
North America Long-Term Care Software Market Segmentation
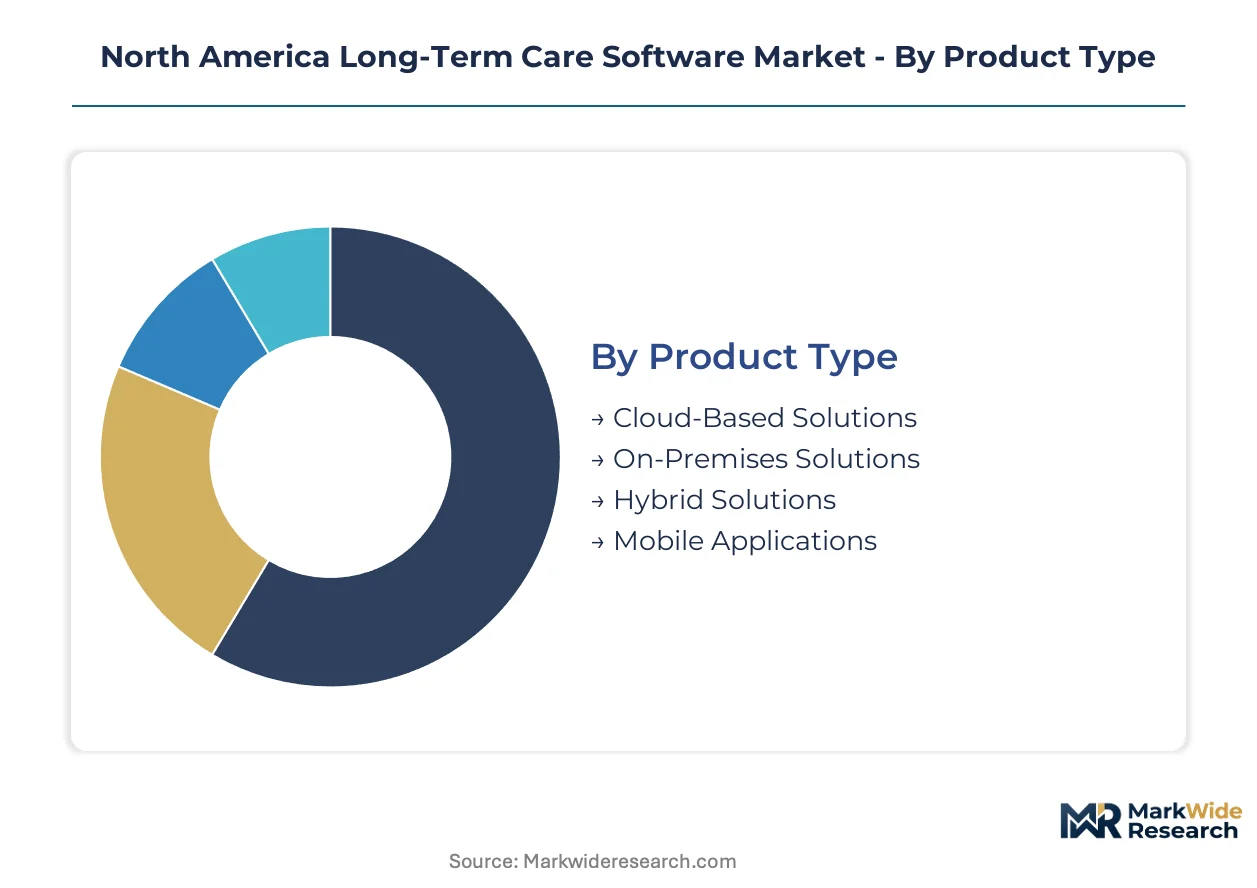
Long-term care software procurement patterns diverge sharply across facility types and deployment models. Understanding these fault lines reveals where vendors must align certification requirements with customer operational constraints.
Product Type:
CMS Conditions of Participation and HIPAA Security Rule audits impose distinct compliance burdens across deployment architectures. Cloud-based platforms face OCR scrutiny of vendor data architecture, while on-premises installations trigger direct facility liability for breach notification.
- Cloud-Based Solutions:Multi-tenant architectures with HL7 FHIR interfaces enable real-time claims scrubbing and seamless care transitions. Demand concentrates among multi-facility operators in California and New York seeking standardized portfolios. CMS interoperability mandates accelerate displacement of legacy infrastructure.
- On-Premises Solutions:Client-server architectures retained by independent nursing homes with thin operating margins resist modular upgrade paths. Texas and Florida facilities prioritize these for perceived data sovereignty despite higher HIPAA audit complexity.
- Hybrid Solutions:Bridge architectures for facilities transitioning off legacy systems.
- Mobile Applications:Medicare Advantage expansion into community-based services drives home health deployment.
Leading the category by volume: Cloud-Based Solutions. Growing fastest: Mobile Applications.
End User:
Customer type determines pricing tolerance and implementation timeline. Private equity-backed chains demand enterprise-grade uptime guarantees, while independent operators prioritize subscription flexibility over feature breadth.
- Nursing Homes:Skilled nursing facilities require integrated EHR platforms with medication administration records and regulatory compliance modules. Ontario's Ministry of Long-Term Care mandates standardized reporting protocols that differ from US federal frameworks.
- Home Healthcare Agencies:Mobile-first documentation tools capture provider-patient encounters without keyboard entry. Medicare Advantage volume direction toward community-based settings compresses sales cycles for this segment.
- Assisted Living Facilities:Lower acuity settings with lighter CMS certification requirements.
- Continuing Care Retirement Communities:Multi-level campuses requiring configurable platforms spanning independent living through skilled nursing.
Home Healthcare Agencies expand most quickly. Nursing Homes retain the largest installed base.
Installation:
Deployment method shapes margin structure and customer lock-in duration. Vendors are racing to embed predictive capabilities that differentiate commodity platform offerings through implementation expertise.
- Remote Installation:Cloud-native platforms deploy through automated provisioning with minimal facility IT staff involvement. Concentrated demand among home health agencies with distributed workforces and limited technical infrastructure.
- On-Site Installation:Legacy system migrations require substantial upfront capital for data migration and staff retraining. Independent nursing home operators in Texas and Florida favor vendors with proven compliance track records.
- Self-Service Installation:Lightweight mobile applications with guided setup workflows.
- Customized Installation:Enterprise contracts with multi-facility operators demanding tailored interoperability configurations.
Remote Installation dominates new cloud deployments. Customized Installation commands premium pricing.
Service Type:
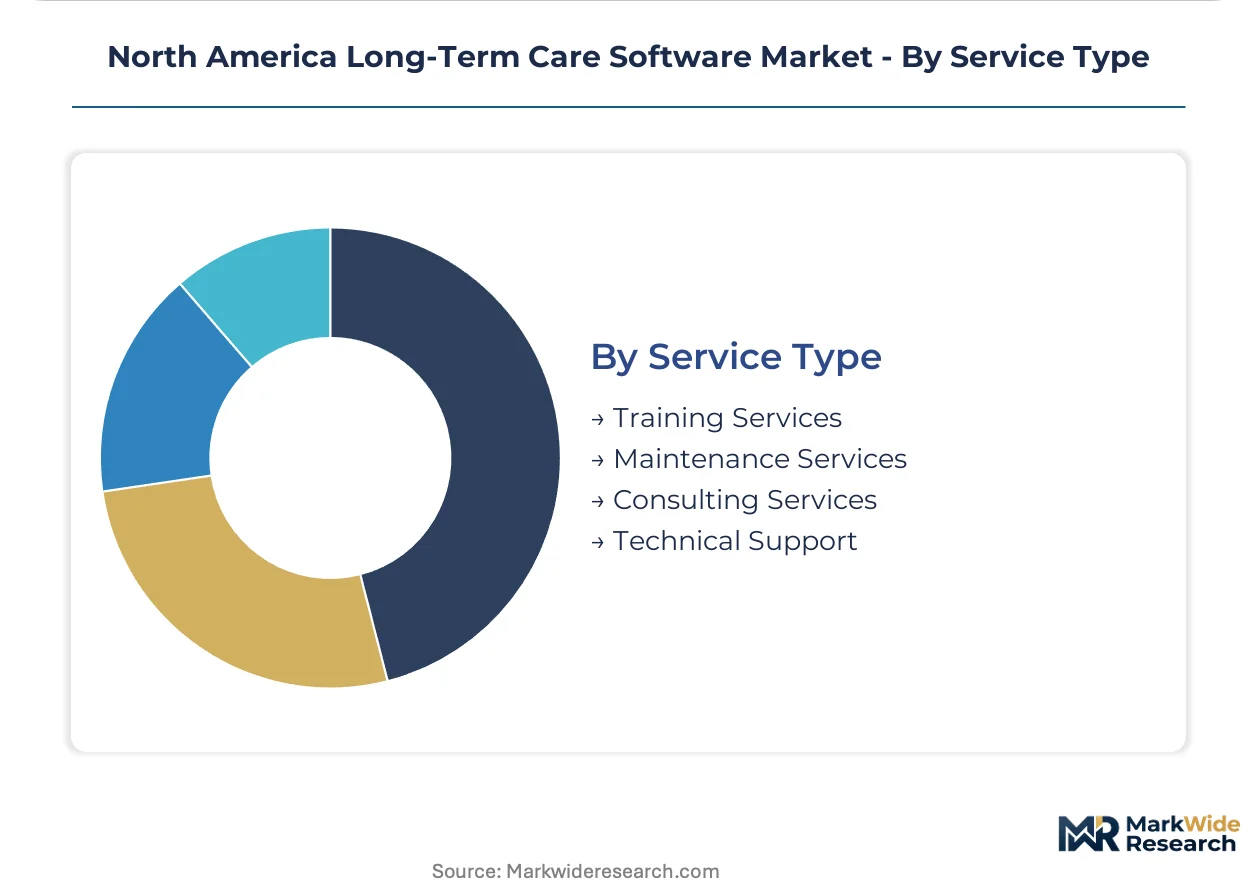
Recurring revenue concentration varies dramatically across service categories. Maintenance and support contracts capture margin pools as facilities prioritize uptime guarantees over upfront licensing.
- Training Services:Clinical informatics talent scarcity forces vendors to absorb education burden for population health dashboard configuration. Facilities struggle to recruit staff capable of interpreting algorithmic alerts.
- Maintenance Services:Uptime guarantees and 24/7 technical response command concentrated margin pools. Multi-facility operators in California and New York demand standardized service level agreements across portfolios.
- Consulting Services:Workflow optimization and regulatory compliance preparation.
- Technical Support:Break-fix and escalation management for mission-critical system failures.
Maintenance Services generate the highest recurring revenue share. Training Services face pricing pressure from self-service alternatives.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Greater Boston anchors North American long-term care software development, hosting dense clusters of health informatics talent and proximity to Medicare policy formation. The corridor's concentration of academic medical centers accelerates pilot deployments for emerging interoperability standards.
United States
Skilled nursing facilities across Texas and Florida drive procurement volume as state Medicaid waivers mandate real-time reporting capabilities. CMS Conditions of Participation enforce minimum electronic health record functionality thresholds that accelerate legacy system replacement. California and New York multi-facility operators demand standardized cloud platforms across consolidated portfolios.
Canada
Ontario's Ministry of Long-Term Care mandates standardized reporting protocols that differ materially from US federal frameworks, creating demand for configurable platforms. Quebec's aging population density concentrates deployment in Montreal and Quebec City corridors. British Columbia's health authority structure favors province-wide procurement contracts over facility-level decisions.
Mexico
Private hospital chains in Mexico City Metro and Monterrey are piloting post-acute care documentation tools for medical tourism accreditation. The national pharmaceutical regulator shapes data localization requirements for cross-border patient records. Guadalajara's technology corridor hosts emerging software development for Spanish-language clinical interfaces.
North America Long-Term Care Software Market Key Industry Players
Capital-heavy infrastructure providers compete with asset-light SaaS developers for dominance in long-term care technology procurement. The vendor landscape consolidates around three strategic tiers: cloud-native specialists, legacy platform incumbents with migration services, and pharmacy-integrated healthcare IT conglomerates. M&A activity concentrates among private equity-backed regional operators seeking standardized portfolios. Strategic partnerships between EHR vendors and telehealth platforms reshape care coordination capabilities.
Within the cloud-native specialist tier, PointClickCare and Netsmart Technologies occupy positions defined by post-acute workflow depth. McKesson Corporation anchors the pharmacy-integrated conglomerate archetype through distribution network control. These three entities exemplify divergent competitive vectors: interoperability infrastructure, behavioral health convergence, and medication management workflow integration.
| Leading Market Players |
|---|
| Veradigm LLC (Allscripts Healthcare) |
| McKesson Corporation |
| PointClickCare |
| Medtelligent, Inc. |
| VITALS SOFTWARE |
| Netsmart Technologies, Inc. |
| Cerner Corporation (Oracle Corporation) |
| Omnicell, Inc. |
| MatrixCare |
| Others |
Cost & Logistics Intelligence
Cloud infrastructure costs cascade through long-term care software pricing tiers as vendors pass hyperscale compute commitments downstream to skilled nursing operators and home health agencies. Texas Medicaid waiver mandates for real-time reporting capabilities concentrate procurement among facilities capable of absorbing premium uptime guarantees, while independent operators in Florida gravitate toward subscription flexibility that masks underlying infrastructure expenditure.
Pricing Analysis
Uptime guarantees anchor pricing stratification across enterprise and mid-market segments. Three-tier pricing structure across premium, standard, and economy levels separates multi-facility chains demanding cross-portfolio standardization from independent nursing homes prioritizing modular entry points. Cost compression in the economy tier intensifies because legacy client-server migration timelines stretch vendor implementation resources. Private equity-backed chains exhibit least price sensitivity, while independent operators with thin margins drive hardest bargain on subscription terms.
Supply Chain Analysis
Direct-to-facility channels handle hyperscale buyer demand from consolidated operators in California and New York, while value-added resellers serve fragmented independent markets. Software development concentrates in the United States, Canada, and India, with clinical informatics talent scarcity in Greater Boston and Toronto feeding into platform engineering capacity. The supply chain draws from hyperscale cloud providers, specialized healthcare data architecture firms, and compliance consulting networks. Single-source vulnerability around dominant cloud infrastructure providers creates mission-critical risk exposure. Distribution runs through vendor direct sales, regional implementation partners, and GPO-affiliated procurement consortia.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Clinical informatics talent scarcity props pricing power for vendors capable of embedding implementation expertise into subscription bundles. Platform engineering capacity constraints limit rapid scaling by new entrants.
For Market Incumbents: Lock in channel control through exclusive partnerships with pharmacy management workflow providers that extend distribution reach beyond core EHR modules. Defensive consolidation should prioritize behavioral health integration capabilities as post-acute settings absorb mental health coordination requirements. Vertical integration into predictive analytics engines preserves margin pools threatened by commodity platform competition. For New Entrants and Emerging Players: Independent nursing home operators in Texas and Florida represent the most penetrable buyer archetype, as these facilities prioritize proven compliance track records over feature breadth and remain underserved by enterprise-focused incumbents. White-space targets include mobile-first documentation tools for Medicare Advantage home health expansion and configurable platforms bridging Ontario provincial reporting with US federal frameworks. Go-to-market execution should emphasize rapid deployment timelines that compress legacy migration pain. For Investors and Strategic Acquirers: CMS Conditions of Participation enforcement actions against non-compliant facilities are the leading indicator that vendor consolidation will accelerate among platforms with demonstrated interoperability certification. Long-term viability centers on cloud-native architectures capable of spanning US and Canadian regulatory environments. Acquisition targets should display deep post-acute workflow specialization rather than horizontal EHR breadth. Watch Texas Medicaid waiver expansion timelines as inflection signal for regional procurement volume shifts.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | HL7 FHIR interoperability anchors Medicare certification eligibility for skilled nursing facilities. |
| Strategic Partnership | Telehealth platform alliances reshape care coordination capabilities across post-acute transitions. |
| Acquisition of Specialist Firm | Behavioral health module developers command premium valuations amid convergence requirements. |
| Geographic Expansion | Ontario and Quebec deployment builds configurable platform credentials for dual-jurisdiction operators. |
| Product Launch | Ambient documentation tools capture nursing hours for direct patient care activities. |
Research Approach
CMS Medicare cost reports, state Medicaid waiver documentation, and hospital procurement databases formed the secondary backbone of data collection. Primary interviews with skilled nursing facility IT directors, home health agency operations managers, long-term care software product executives, and GPO contracts specialists validated demand-side assumptions. Bottom-up triangulation across facility-level technology expenditure patterns combined with top-down reconciliation against vendor-reported subscription revenue streams.
Bottom-up modeling segmented the market by deployment architecture, end-user facility type, and service category across the analysis window. CAGRs derived from facility adoption curve projections, regulatory deadline impacts, and Medicare Advantage penetration assumptions. Forecast inputs incorporated HL7 FHIR implementation timelines, state-level Medicaid technology incentive programs, and cloud infrastructure cost trajectories.
Revisions become necessary when CMS Conditions of Participation enforcement priorities shift, HIPAA Security Rule audit scopes expand, or hyperscale cloud provider pricing structures destabilize vendor margin models. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Healthcare IT
US Dental Clearing Houses Market
Healthcare IT
North America Wireless Healthcare Market
Healthcare IT
Healthcare AIDC Market
Healthcare IT
Interactive Patient Care Systems Market
Healthcare IT
Global Personal Health Records Software Market
Healthcare IT
US Practice Management Systems Market
Healthcare IT
Asia Pacific Healthcare IT Market
Healthcare IT
Middle East and Africa Nurse Call Systems Market
Healthcare IT
Global Dental Software Market
Healthcare IT
Ambulatory Surgical Centers IT Services Market
Healthcare IT
Hospital Workforce Management Software Market
Healthcare IT
Healthcare Smart Card Reader Market
Healthcare IT
US Urgent Care Center Software Market
Healthcare IT
Healthcare Claims Management Software Market
Healthcare IT
Healthcare HR Software Market
Healthcare IT
US Revenue Cycle Management Market