
 Global IT Spending in Healthcare Market | 2026-2036
Global IT Spending in Healthcare Market Size, Share, and Industry Trends Forecast 2026-2036
Global IT Spending in Healthcare Market Foresight
North American health IT infrastructure is consolidating as hospital networks merge and standardize their technology stacks. Epic Systems Corporation leverages its integrated electronic health record architecture to dominate large academic medical centers. Cerner Corporation anchors significant market presence through deep revenue cycle management deployments across multi-hospital systems. Oracle Corporation competes aggressively in cloud infrastructure for healthcare, extending its database dominance into clinical analytics platforms.
Global IT spending in healthcare encompasses all information technology expenditures by healthcare providers, payers, and intermediaries, including hardware procurement, software licensing, cloud services, cybersecurity systems, and professional implementation services, typically governed by interoperability standards such as HL7 FHIR and region-specific data protection protocols, primarily serving to improve clinical outcomes, reduce operational costs, and enable value-based care delivery. Electronic Health Records within the technology dimension sustains the largest installed base despite maturing growth rates, while Artificial Intelligence represents the fastest-expanding segment as diagnostic algorithms gain regulatory clearance. Cloud Computing captures disproportionate capital allocation as health systems migrate from on-premise legacy architectures to scalable subscription models.
FDA software-as-medical-device regulations, EU AI Act risk classifications for clinical algorithms, and HIPAA data security requirements collectively reshape product development roadmaps and procurement criteria for vendors seeking multi-jurisdictional deployment. EMA guidelines on algorithmic transparency and WHO digital health standards further complicate cross-border market access for emerging platform providers. Stakeholders must monitor evolving reimbursement policies for AI-enabled diagnostics and the fragmentation of national health data governance frameworks to anticipate where capital deployment will unlock sustainable returns.
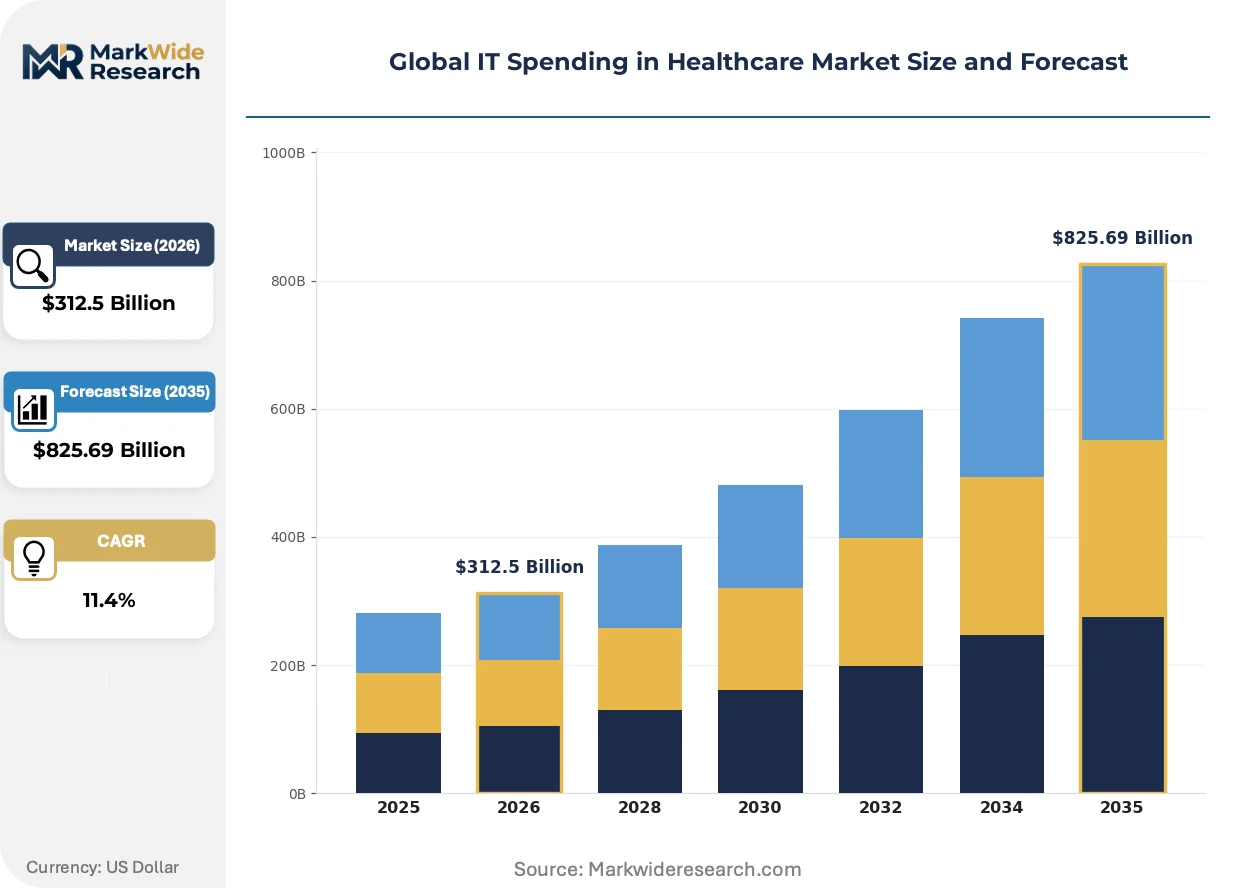
Market Dynamics
Cloud migration is forcing hospital systems to dismantle decades-old on-premise architectures, compressing vendor consolidation timelines as IT departments prioritize interoperability over best-of-breed point solutions.
Growth Catalysts
- FDA Software-as-Medical-Device Framework:Clearer regulatory pathways for algorithmic diagnostics accelerate commercialization timelines for AI-enabled imaging and clinical decision support tools across US health systems.
- HL7 FHIR Interoperability Mandates:Government-mandated data exchange standards in the United States, Germany, and India compel EHR vendors to open APIs, reducing switching costs and enabling platform unification.
- Remote Patient Monitoring Infrastructure:Chronic disease management programs in Medicare Advantage and Germany's statutory health insurance funds drive sensor deployment and cloud analytics procurement.
Market Restraints
- Cybersecurity Talent Scarcity:Health systems face acute shortages of HIPAA-qualified security architects, inflating implementation costs for zero-trust network architectures.
- Legacy Data Migration Complexity:Decades of unstructured clinical records in proprietary formats create technical debt that slows cloud transitions and extends ROI timelines.
- EU AI Act Risk Classification:High-risk algorithmic diagnostic requirements impose documentation burdens and conformity assessment costs that disadvantage smaller vendors.
Strategic Opportunities
- Rural Health IT Modernization:India's Ayushman Bharat Digital Mission and US Rural Health Clinic funding streams create procurement windows for telemedicine and cloud EHR platforms in underserved regions.
- AI-Enabled Clinical Documentation:Ambient intelligence technologies that automate physician note-taking address burnout while capturing structured data for quality reporting.
- Subscription-Based Cybersecurity Services:Managed detection and response models reduce upfront capital requirements for mid-size hospital systems facing ransomware exposure.
Industry Challenges
- Interoperability Implementation Gaps:Semantic differences between vendor FHIR implementations persist, requiring costly custom integration work for health information exchanges.
- Algorithmic Bias Validation:Clinical AI developers struggle to assemble representative training datasets that satisfy FDA and EMA standards for demographic equity across patient populations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global IT Spending in Healthcare Market |
| Market Size in 2026 | $312.5 Billion |
| Market Size in 2035 | $825.69 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Electronic Health Records, Telemedicine, Cloud Computing, Artificial Intelligence, Blockchain, Cybersecurity Solution: Clinical Information Systems, Revenue Cycle Management, Patient Engagement, Pharmacy Management, Imaging Informatics, Health Analytics Application: Remote Patient Monitoring, Diagnostic Imaging, Medical Research, Population Health Management, Personalized Medicine, Emergency Response End User: Hospitals, Ambulatory Care Centers, Diagnostic Laboratories, Health Insurance Providers, Telehealth Companies, Government Health Agencies |
| Companies Covered | Epic Systems Corporation, Cerner Corporation, Allscripts Healthcare Solutions, Athenahealth, Oracle Corporation, GE HealthCare, Optum, McKesson Corporation, InterSystems Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global IT Spending in Healthcare Market Shifts & Advancements
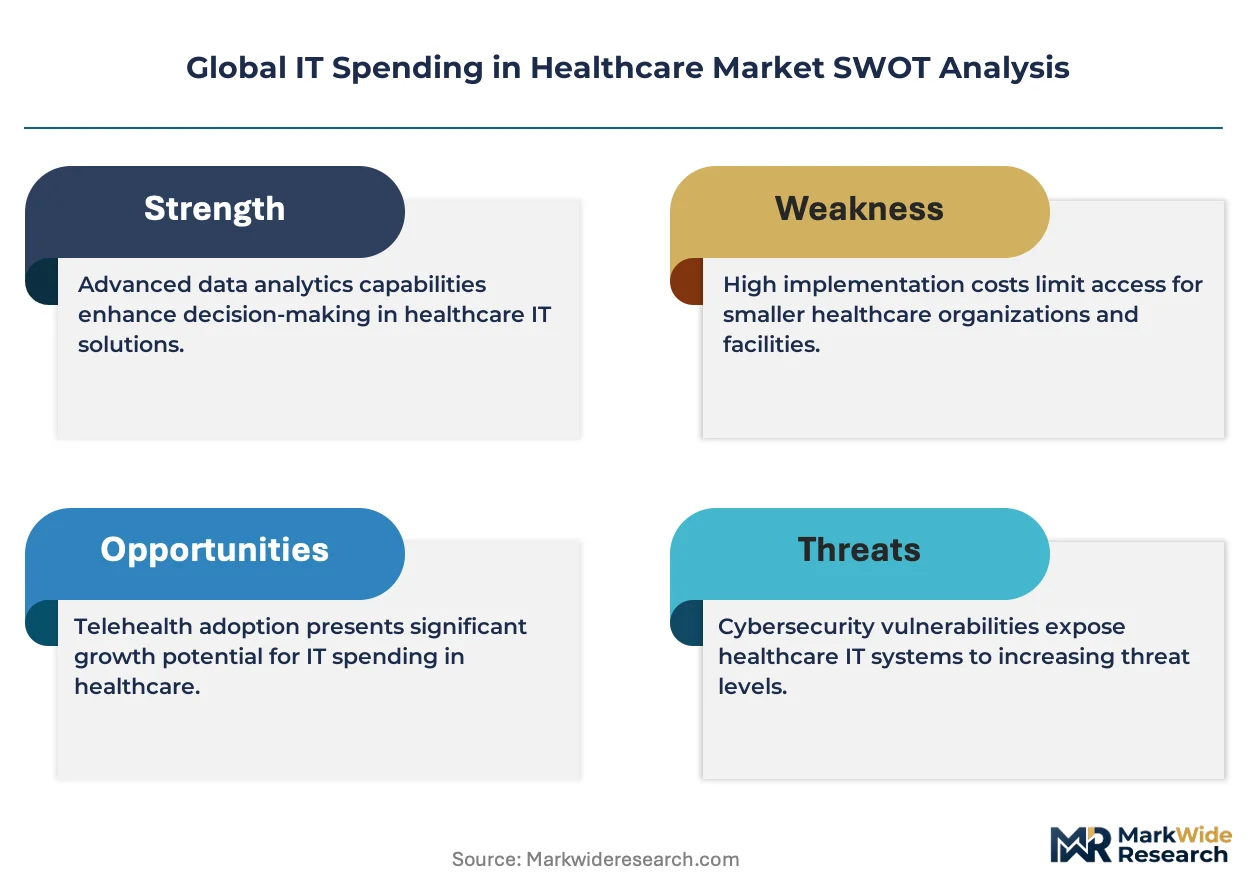
Healthcare IT architecture is fragmenting into composable service layers, enabling health systems to swap components without platform lock-in while regulatory pressure accelerates algorithmic transparency requirements.
Microservices-based EHR architecture is modularizing core clinical workflows into discrete, API-connected functions. Large academic medical centers in the United States and Germany are piloting headless EHR implementations that separate data storage from user interfaces. This decomposition is compressing vendor switching costs and enabling best-of-breed clinical application marketplaces.
The EU AI Act's high-risk system obligations are reshaping product development roadmaps for diagnostic algorithm vendors. Conformity assessment requirements and post-market monitoring mandates favor established players with regulatory affairs infrastructure. European health systems are prioritizing procurement criteria that include algorithmic explainability documentation and bias audit trails.
Hospital procurement departments are unbundling EHR contracts into separate data platform, application, and implementation workstreams. Large multi-hospital systems in the United States and India are negotiating direct cloud infrastructure agreements with hyperscalers, bypassing traditional vendor-hosted models. This disintermediation concentrates negotiating leverage with sophisticated IT governance functions while fragmenting vendor relationships.
Global IT Spending in Healthcare Market Segmentation
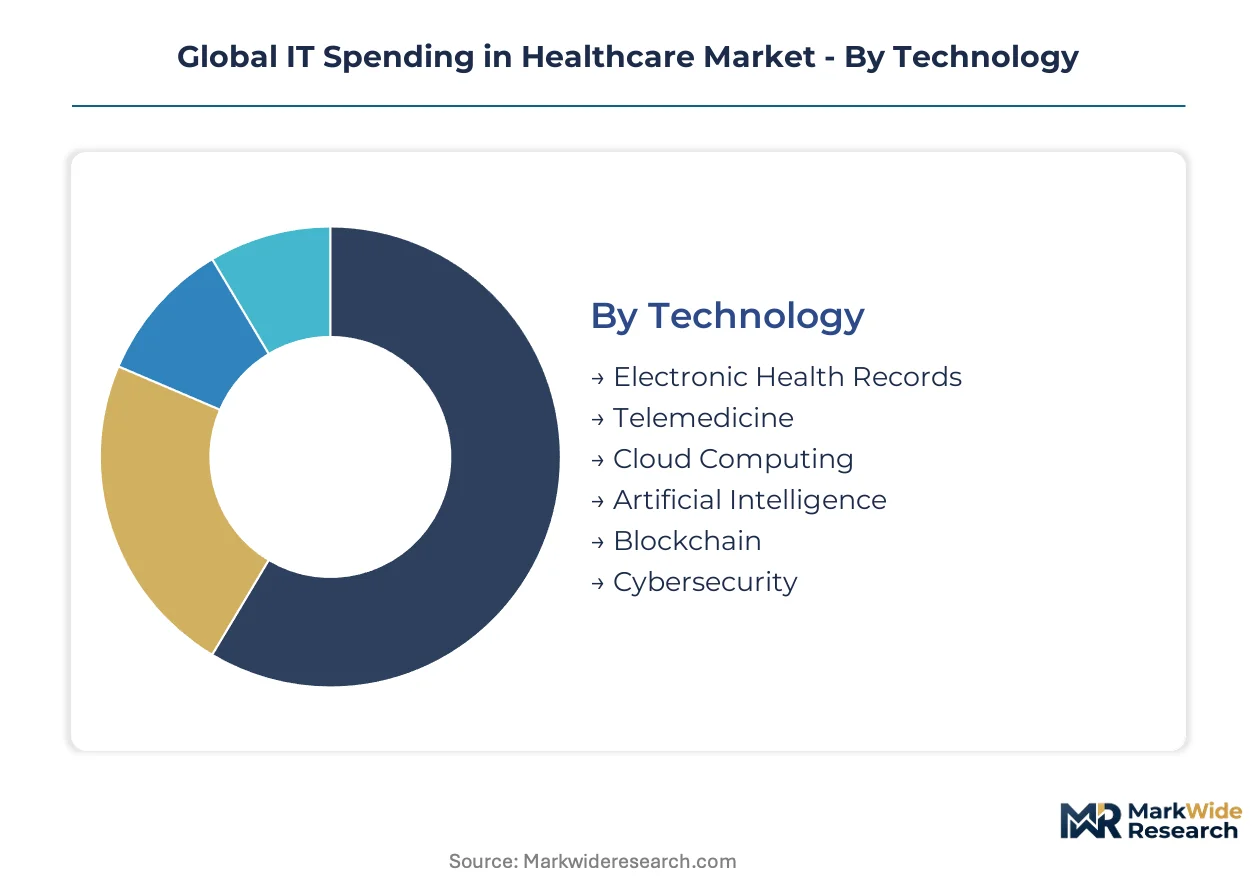
Healthcare IT procurement decisions fragment across technology layers, solution types, clinical applications, and institutional end users. Each segmentation dimension carries distinct vendor dynamics, regulatory exposure, and capital deployment patterns that shape competitive positioning.
Technology:
Supply concentration in cloud infrastructure and AI platforms is compressing vendor margins while accelerating consolidation among legacy on-premise providers.
- Electronic Health Records:Core clinical data repositories integrating patient history, medication lists, and care plans across inpatient and ambulatory settings. Large hospital systems in the United States and Germany prioritize EHR vendors with native HL7 FHIR APIs to reduce interoperability friction.
- Artificial Intelligence:Machine learning algorithms for diagnostic imaging, clinical decision support, and predictive analytics requiring FDA or EMA clearance. Academic medical centers in the United States and India drive procurement of radiology AI tools as regulatory pathways stabilize.
- Cloud Computing:Scalable infrastructure-as-a-service and platform-as-a-service deployments replacing on-premise data centers.
- Telemedicine:Real-time video consultation platforms and asynchronous store-and-forward diagnostic services.
- Cybersecurity:Zero-trust network architectures, endpoint detection, and HIPAA-compliant encryption for protected health information.
- Blockchain:Distributed ledger applications for pharmaceutical supply chain integrity and patient consent management.
Today's leader: Electronic Health Records. Tomorrow's challenger: Artificial Intelligence.
Solution:
Cost tier differentiation separates enterprise-grade integrated suites from modular point solutions targeting mid-size health systems.
- Clinical Information Systems:Computerized physician order entry, medication administration records, and nursing documentation modules. Hospitals in Germany and India prioritize CIS vendors with embedded clinical pathway protocols to support standardized care delivery.
- Revenue Cycle Management:Patient registration, insurance eligibility verification, claims processing, and denial management workflows. United States health systems anchor RCM procurement decisions on Medicare Advantage risk adjustment accuracy and prior authorization automation.
- Patient Engagement:Portal platforms, appointment scheduling, and automated outreach for care plan adherence.
- Health Analytics:Population-level reporting, quality measure dashboards, and operational performance benchmarking.
- Imaging Informatics:Picture archiving and communication systems with vendor-neutral archive architectures.
- Pharmacy Management:Inventory control, drug interaction checking, and automated dispensing integration.
Revenue Cycle Management captures the steepest expansion trajectory as value-based reimbursement models proliferate.
Application:
Volume concentration in remote patient monitoring and diagnostic imaging is attracting hyperscaler infrastructure investment and specialized AI development.
- Remote Patient Monitoring:Continuous glucose monitors, blood pressure cuffs, and pulse oximeters transmitting data to cloud analytics platforms. Medicare Advantage plans in the United States and Germany's statutory health insurance funds scale RPM deployments for chronic heart failure and diabetes management.
- Diagnostic Imaging:AI-enhanced interpretation of CT, MRI, and mammography studies with computer-aided detection. Tertiary hospitals in India and the United States drive procurement of FDA-cleared algorithms for lung nodule and fracture detection.
- Population Health Management:Risk stratification tools and care coordination platforms for accountable care organizations.
- Personalized Medicine:Pharmacogenomic decision support and targeted therapy matching based on molecular profiling.
- Medical Research:Clinical trial management systems and real-world evidence data platforms.
- Emergency Response:Dispatch optimization, field triage protocols, and disaster surge capacity systems.
Remote Patient Monitoring dominates current procurement cycles. Diagnostic Imaging holds the strongest AI monetization potential.
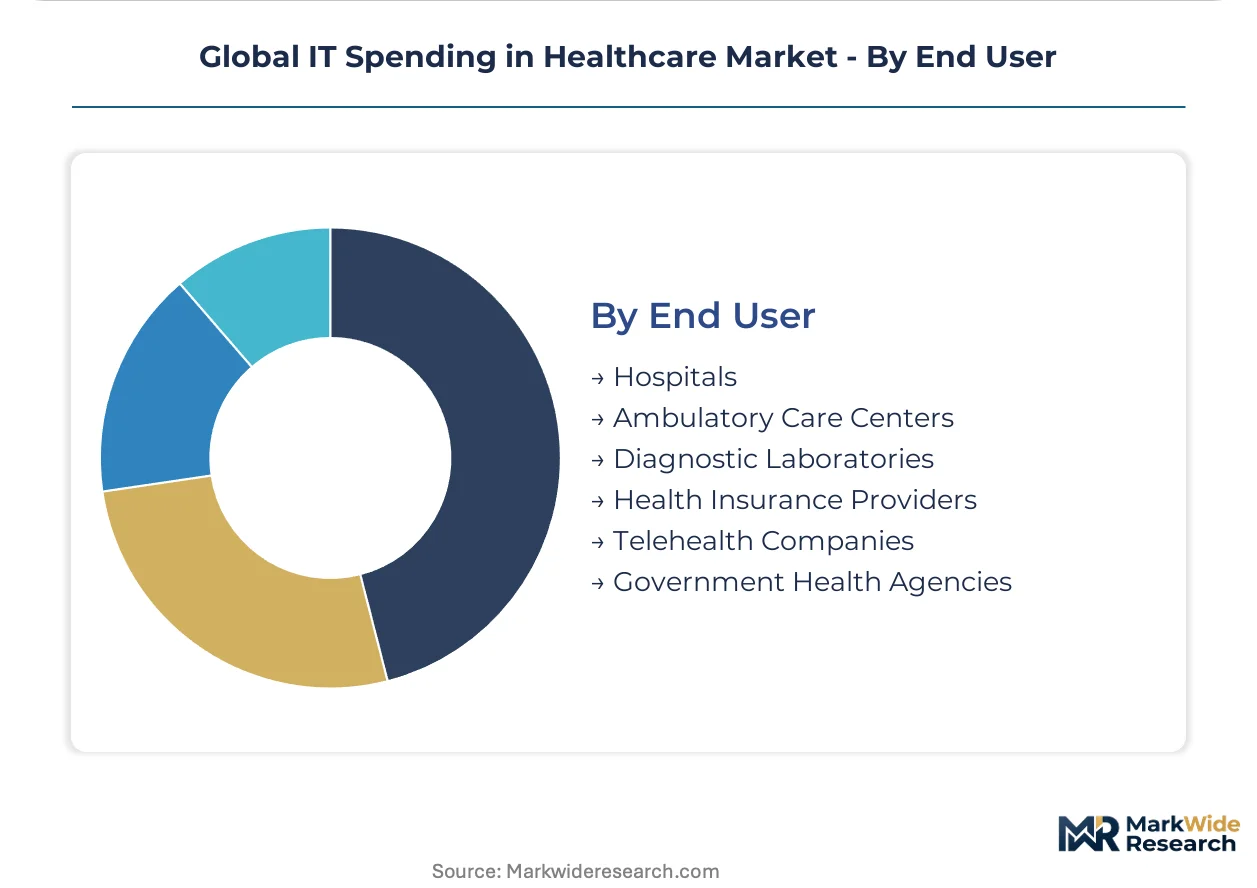
End User:
Customer type fragmentation creates divergent purchasing authority structures, with hospital IT committees controlling large capital outlays while ambulatory sites favor subscription elasticity.
- Hospitals:Integrated delivery networks and standalone acute care facilities with multi-year EHR implementation timelines. Large systems in the United States negotiate directly with hyperscalers for cloud infrastructure, bypassing traditional vendor hosting.
- Ambulatory Care Centers:Specialty clinics and primary care practices prioritizing lightweight, mobile-first EHR interfaces with telemedicine integration.
- Diagnostic Laboratories:High-throughput testing facilities requiring laboratory information system interoperability with ordering provider workflows.
- Health Insurance Providers:Payers deploying care management platforms and fraud detection analytics across provider networks.
- Telehealth Companies:Virtual-first care delivery startups with API-first architecture requirements and rapid scaling needs.
- Government Health Agencies:National health IT infrastructure programs including India's Ayushman Bharat Digital Mission and United States public health surveillance systems.
Hospitals command the largest contract values. Telehealth Companies represent the most dynamic growth profile.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage is reshaping vendor deployment strategies as the FDA's software-as-medical-device pathway accelerates US commercialization timelines while EU AI Act compliance costs push algorithm development toward jurisdictions with lighter documentation burdens. Health systems in Germany and India are capturing disproportionate infrastructure investment as their national digital health programs create procurement windows absent in saturated North American markets.
United States
Medicare Advantage risk adjustment accuracy and prior authorization automation drive procurement of revenue cycle management platforms. The FDA's 510(k) clearance pathway for diagnostic algorithms compresses time-to-market for imaging AI vendors. Large academic medical centers in Boston and Palo Alto pilot headless EHR architectures that separate data layers from user interfaces.
Germany
Statutory health insurance funds scale chronic disease management programs requiring remote patient monitoring infrastructure. The EU AI Act's high-risk system obligations impose conformity assessment costs that favor established vendors with regulatory affairs capacity. Berlin and Munich anchor health IT clusters where hospital networks negotiate directly with hyperscalers for cloud infrastructure.
India
Ayushman Bharat Digital Mission creates procurement windows for telemedicine and cloud EHR platforms in underserved rural regions. CDSCO guidelines on software-as-medical-device are stabilizing as the regulator aligns with FDA precedent. Bangalore and Hyderabad concentrate health IT development centers serving domestic hospital chains and export markets.
United Kingdom
NHS England's federated data platform mandates accelerate procurement of interoperability-compliant clinical systems. MHRA recognition of FDA-cleared algorithms streamlines market access for US-based diagnostic AI vendors. London's health tech corridor attracts venture deployment in ambient clinical documentation technologies.
Japan
PMDA's software-as-medical-device framework is maturing as the regulator issues guidance on machine learning-enabled diagnostics. METI subsidies for hospital digitization target mid-size facilities with legacy paper records. Tokyo and Osaka medical districts prioritize procurement of AI-enhanced imaging interpretation for aging population screening programs.
Global IT Spending in Healthcare Market Competitive Landscape
United States vendors anchor the enterprise EHR tier; European specialists hold regulatory compliance advantages. The vendor base concentrates around three strategic archetypes: integrated platform providers with native interoperability, modular point-solution vendors targeting mid-size systems, and hyperscaler infrastructure layers disintermediating traditional hosting arrangements. M&A activity accelerates as cloud migration compresses switching costs, while strategic partnerships between algorithm developers and EHR incumbents lock in distribution channels.
Within the integrated platform tier, Epic Systems Corporation and Cerner Corporation exemplify vendors capturing large hospital system contracts through deep clinical workflow embedding. Oracle Corporation occupies a position as the hyperscaler infrastructure anchor competing aggressively in cloud analytics. These three entities represent contrasting strategic postures: workflow-native incumbency, revenue cycle management specialization, and database-to-cloud extension.
| Leading Market Players |
|---|
| Epic Systems Corporation |
| Cerner Corporation |
| Allscripts Healthcare Solutions |
| Athenahealth |
| Oracle Corporation |
| GE HealthCare |
| Optum |
| McKesson Corporation |
| InterSystems Corporation |
| Others |
Supply & Pricing Matrix
Backward integration into cloud infrastructure anchors vendor pricing power as health systems negotiate directly with hyperscalers, bypassing traditional EHR-hosted models and compressing margins for legacy platform providers across the United States, Germany, and India.
Pricing Analysis
Distributor margin capture concentrates in implementation services and change management consulting rather than software licensing. Three-tier pricing structure across premium, standard, and economy levels separates enterprise EHR deployments from modular point solutions and open-source alternatives. Cost compression in mid-tier subscriptions intensifies because hyperscaler infrastructure commoditizes hosting layers. Safety-net hospitals and rural clinics exhibit highest price sensitivity while academic medical centers prioritize workflow integration over license cost.
Supply Chain Analysis
GPU and specialized AI accelerator supply rests on Taiwanese semiconductor foundries and South Korean memory producers, with cloud infrastructure hardware drawing from Chinese server assembly and Indian software development centers. Critical dependencies span NVIDIA AI chips, high-bandwidth memory modules, and HIPAA-compliant data center certifications. Single-source vulnerability concentrates in advanced node semiconductor fabrication. Distribution runs through direct enterprise sales teams and systems integrators rather than channel partners.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story where procurement committees prioritize FDA-cleared algorithms and EU AI Act-compliant documentation over cost minimization, elevating vendors with embedded regulatory affairs infrastructure.
For Market Incumbents: Lock in distribution channels through strategic API partnerships with emerging diagnostic algorithm developers, neutralizing the threat of modular point solutions that bypass integrated EHR workflows. Prioritize certification investment for EU AI Act high-risk system conformity assessments to create switching costs for hospital systems facing documentation burdens.
For New Entrants and Emerging Players: Enter via rural health IT modernization programs in India's Ayushman Bharat Digital Mission and US federally qualified health centers, where incumbent footprint remains shallow. Target subscription-based cybersecurity services for mid-size hospital systems as the most penetrable segment, leveraging managed detection and response models that reduce upfront capital requirements.
For Investors and Strategic Acquirers: Roll-up economics work for regulatory affairs specialists because EU AI Act and FDA software-as-medical-device frameworks create documentation moats that favor scaled compliance infrastructure over venture-stage automation. Long-term viability favors vendors with embedded clinical workflow relationships rather than standalone algorithm developers. Watch reimbursement policy shifts for AI-enabled diagnostics as the inflection signal for capital deployment timing.
| Strategic Initiative | Industry Significance |
|---|---|
| FDA Software-as-Medical-Device Submission | Accelerates commercialization timelines for diagnostic algorithms across US health systems under 510(k) pathway. |
| EU AI Act Conformity Assessment | Opens procurement access to German statutory health insurance funds requiring high-risk system documentation. |
| Hospital System Partnership | Locks in multi-year EHR implementation contracts with integrated delivery networks prioritizing interoperability. |
| Hyperscaler Cloud Integration | Enables direct infrastructure negotiations with Oracle and AWS, disintermediating traditional vendor hosting. |
| Reimbursement Strategy Development | Secures Medicare Advantage coverage for remote patient monitoring devices driving sensor deployment. |
Research Methodology
Direct dialogue with hospital CIOs, health system procurement committees, FDA regulatory consultants, and biomedical engineers grounded qualitative findings, combined with secondary validation from FDA 510(k) filings, CMS Medicare claims data, hospital GPO contracts, and HL7 FHIR implementation reports. Bottom-up and top-down triangulation cross-checked vendor revenue disclosures against health system capital expenditure surveys.
Segmentation outputs across technology layers, solution types, clinical applications, and institutional end users fed into the analytical framework over the projection horizon. CAGRs derived from regression analysis of historical procurement cycles and policy implementation timelines, incorporating cloud migration velocity and AI regulatory clearance rates as healthcare-specific forecast inputs.
The model holds under stable reimbursement policy and regulatory pathway continuity; deviation in FDA enforcement posture or EU AI Act implementation timelines would shift vendor commercialization schedules. A small set of named triggers including CMS coverage determinations and hyperscaler healthcare-specific contract structures warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Healthcare IT
Asia Pacific Healthcare IT Market
Healthcare IT
Veterinary Dental Software Market
Healthcare IT
Europe Outpatient Software Market
Healthcare IT
Asia-Pacific Dental Practice Management Software Market
Healthcare IT
Hospital Workforce Management Software Market
Healthcare IT
Assisted Living Software Market
Healthcare IT
Global Orthopedic Software Market
Healthcare IT
Clinical Communication and Collaboration Market
Healthcare IT
Radiation Dose Optimisation Software Market
Healthcare IT
Global Computerized Physician Order Entry (CPOE) Systems Market
Healthcare IT
Pharma Management Software Market
Healthcare IT
Pharmaceutical Software Market
Healthcare IT
High-Value Healthcare Asset Tracking and Recovery Platforms Market
Healthcare IT
Middle East and Africa Nurse Call Systems Market
Healthcare IT
Global Patient Intake Software Market
Healthcare IT
Practice Management System (PMS) Market