
 Cognitive Assessment and Training in Healthcare Market | 2026-2036
Cognitive Assessment and Training in Healthcare Market Size, Share, and Industry Trends Forecast 2026-2036
Cognitive Assessment and Training in Healthcare Market Intelligence
A widening capability gap in artificial intelligence infrastructure is bifurcating the competitive landscape. Cambridge Cognition Ltd. leverages proprietary algorithms for pharmaceutical trial endpoints, sustaining leadership in regulated research environments. Cogstate Ltd. dominates digital cognitive testing for sports concussion protocols, while CogniFit competes in direct-to-consumer brain training subscriptions with adaptive difficulty engines.
Cognitive assessment and training in healthcare encompasses standardized digital tools that measure attention, memory, executive function, and processing speed through validated psychometric protocols, typically administered via touchscreen interfaces with millisecond response-time logging. Its primary commercial purpose spans early neurodegenerative disease detection, post-stroke rehabilitation monitoring, and clinical trial efficacy endpoints for central nervous system therapeutics. Assessment Tools command the deepest margin pools due to diagnostic reimbursement codes, while Gamification Solutions attract the fastest growth among senior care providers seeking engagement-driven adherence. Artificial Intelligence segments lead R&D allocation as natural language processing enables automated speech-pattern analysis for mild cognitive impairment screening.
The FDA regulates cognitive assessment software under its software-as-medical-device pathway, requiring clinical validation for diagnostic claims, while HIPAA mandates encryption standards for cloud-based neuropsychological data storage. The EU AI Act classifies cognitive diagnostic algorithms as high-risk systems, imposing conformity assessment burdens that favor established players with quality management systems. Stakeholders must monitor evolving reimbursement decisions by CMS and private payers, as coverage determinations for remote cognitive monitoring will dictate addressable market expansion more than technological capability alone.
Market Dynamics
The FDA's software-as-medical-device framework is compressing product development timelines while fragmenting competitive positioning between algorithm developers and clinical validation specialists. This regulatory pathway bifurcation is forcing capital allocation toward either regulated diagnostic claims or wellness-adjacent consumer positioning.
Growth Catalysts
- Medicare Reimbursement Expansion:CMS coverage determinations for remote neuropsychological monitoring are unlocking hospital procurement budgets for digital cognitive assessment platforms across United States health systems.
- EU AI Act High-Risk Classification:Conformity assessment requirements for cognitive diagnostic algorithms are accelerating consolidation around established quality management systems, favoring scaled vendors.
- Speech-Pattern Analysis:Natural language processing automation is decomposing traditional neuropsychologist-administered screening into scalable mild cognitive impairment detection workflows.
Market Restraints
- Clinical Validation Costs:FDA 510(k) pathway requirements for diagnostic claims impose multi-million-dollar evidence-generation burdens that exclude pre-revenue algorithm developers.
- Cloud Infrastructure Concentration:HIPAA-compliant neuropsychological data storage depends on a narrow tier of encrypted cloud providers, creating vendor lock-in and pricing power asymmetries.
- Behavioral Substitution:Paper-based Mini-Mental State Examination protocols persist in resource-constrained long-term care facilities, delaying digital platform penetration.
Strategic Opportunities
- Post-Stroke Rehabilitation Monitoring:Underpenetrated acute care-to-home transition protocols in Germany present white space for continuous cognitive recovery tracking outside hospital settings.
- Adaptive Difficulty Engines:Convergence of reinforcement learning with psychometric item-response theory enables personalized brain training adherence optimization for senior care providers.
- Japan's Dementia Prevention Initiative:METI-backed cognitive health screening mandates are creating procurement tailwinds for validated digital assessment tools in municipal health centers.
Industry Challenges
- Neuropsychologist Talent Scarcity:Specialized clinical validation expertise for FDA submissions commands premium compensation, constraining vendor scaling velocity.
- Legacy EHR Integration Friction:Health system procurement committees prioritize cognitive platforms with pre-built HL7 FHIR connectors, disadvantaging point-solution developers.
- Cross-Border Data Sovereignty:HIPAA and GDPR divergent encryption and consent requirements complicate unified platform deployment for multinational hospital chains.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cognitive Assessment and Training in Healthcare Market |
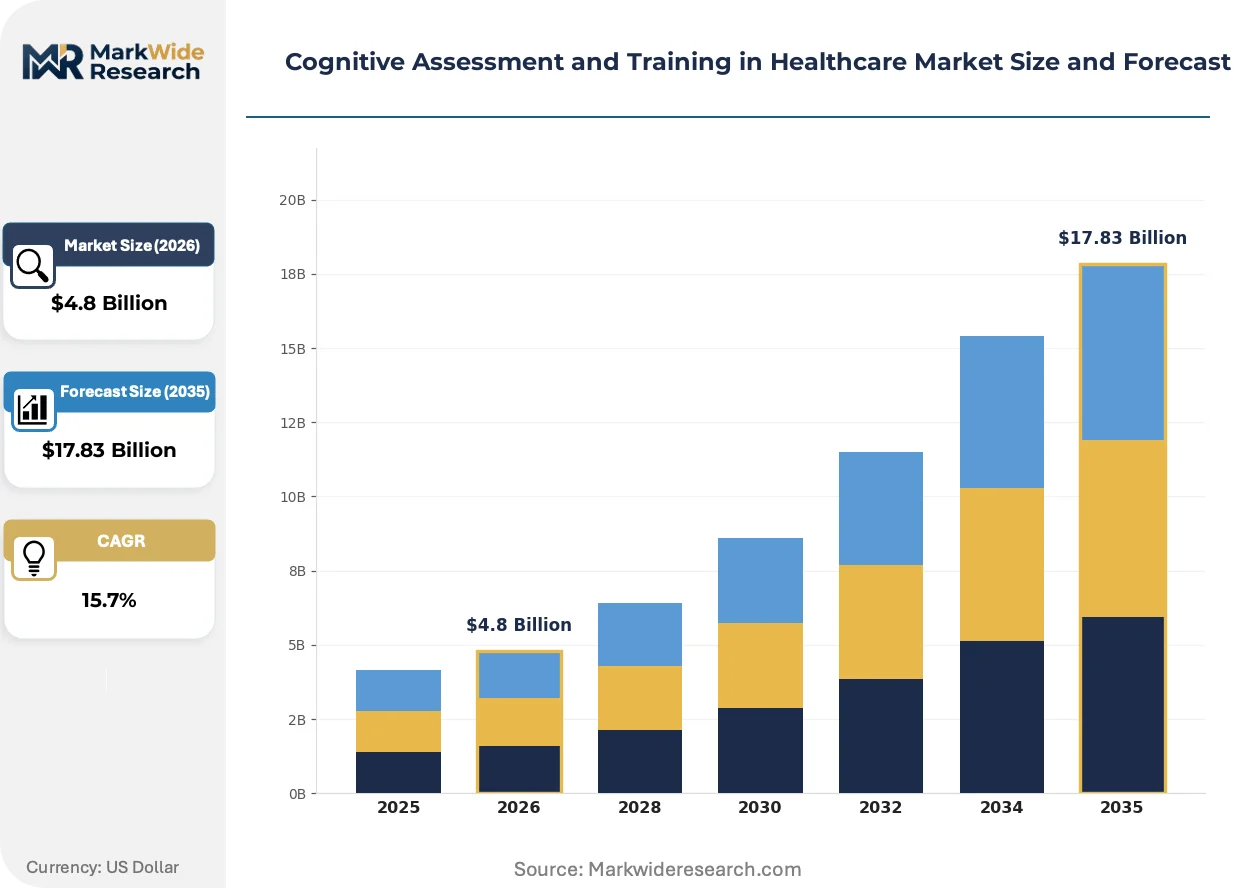
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $17.83 Billion |
| CAGR (2026 – 2036) | 15.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cognitive Training Software, Assessment Tools, Gamification Solutions, Neurofeedback Systems End User: Hospitals, Rehabilitation Centers, Senior Care Facilities, Outpatient Clinics Technology: Artificial Intelligence, Virtual Reality, Mobile Applications, Wearable Devices Delivery Mode: On-Premise, Cloud-Based, Hybrid, Subscription-Based |
| Companies Covered | Cambridge Cognition Ltd., Cogstate Ltd., CogniFit, Pearson, BrainCheck, PAR, Inc., Signant Health, Bracket, Posit Science, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cognitive Assessment and Training in Healthcare Market Strategic Shifts & Innovations
Algorithmic automation is decomposing traditional assessment modalities into componentized, API-deliverable cognitive tests. This technical shift is redrawing competitive boundaries between diagnostic device manufacturers and software-native entrants.
Natural language processing is decomposing speech-pattern biomarker extraction into real-time mild cognitive impairment screening. Memory clinics in the United States are adopting automated phonetic analysis tools that compress 45-minute neuropsychologist evaluations into 10-minute patient interactions. This capability is decomposing the historical monopoly of specialized assessment centers on early dementia detection.
The EU AI Act's high-risk system classification is mandating conformity assessment procedures for cognitive diagnostic algorithms deployed in European healthcare settings. Algorithm developers must now maintain post-market performance monitoring and human oversight protocols that increase operational overhead. Germany's notified bodies are experiencing backlog accumulation, delaying product launches for vendors without established quality management certifications.
Hospital procurement committees are unbundling cognitive assessment from bundled neurology service contracts and establishing standalone digital health vendor qualification processes. This buying-pattern evolution is displacing incumbent medical device distributors who historically controlled neuropsychological testing supply relationships. The United Kingdom's National Health Service is most visible in this transition, with integrated care systems issuing direct tenders for remote monitoring platforms.
Cognitive Assessment and Training in Healthcare Market Segmentation
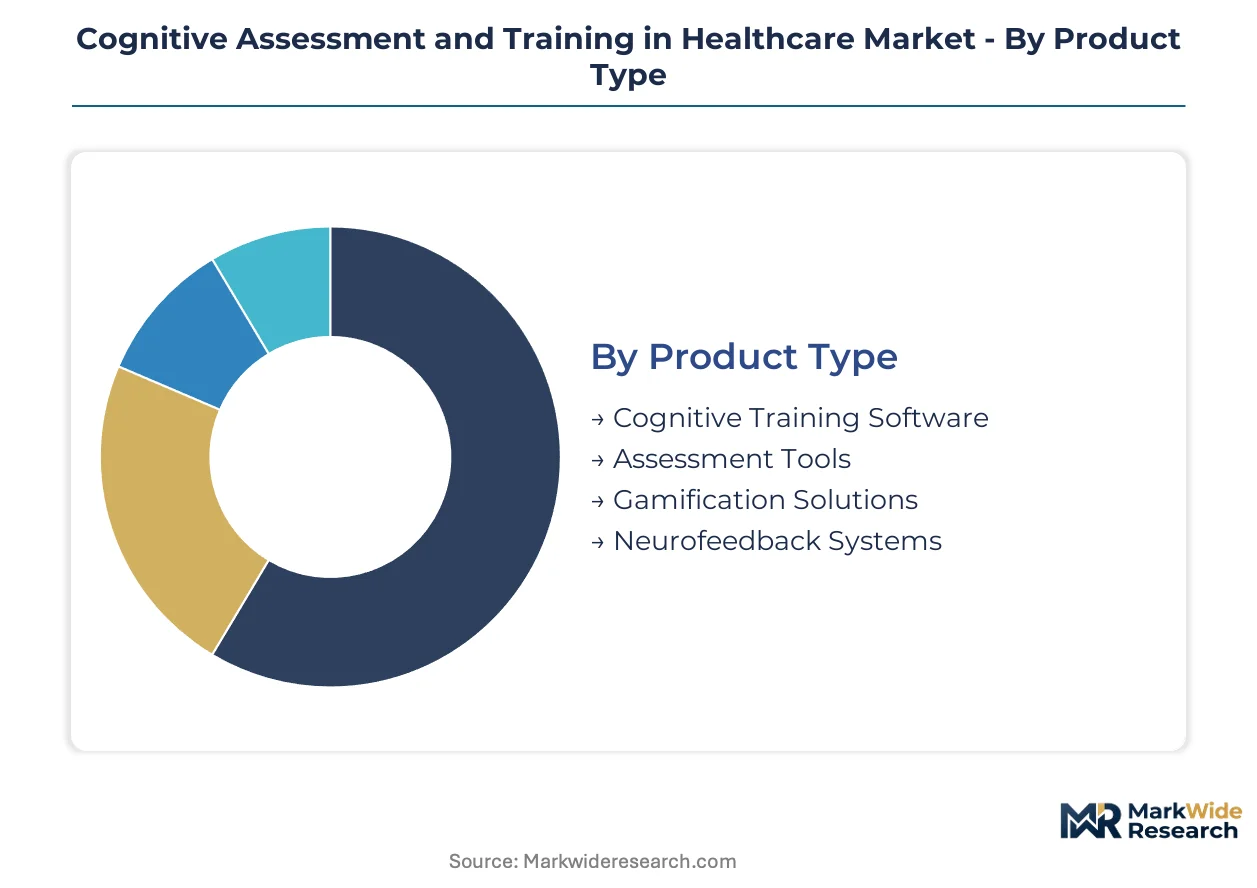
Segmentation in cognitive healthcare reveals divergent commercial strategies across reimbursement pathways, technology stacks, and care settings. Each dimension exposes distinct margin profiles and regulatory exposure that shape vendor positioning.
Product Type:
Assessment Tools and Cognitive Training Software concentrate demand in the United States where Medicare reimbursement codes favor diagnostic claims, while Gamification Solutions and Neurofeedback Systems find stronger traction in self-pay European and Asian markets.
- Assessment Tools:Validated psychometric protocols delivered via touchscreen interfaces with millisecond response-time logging. Demand concentrates in United States hospital neurology departments where FDA 510(k) clearance unlocks insurance reimbursement for early dementia detection workflows.
- Cognitive Training Software:Adaptive difficulty engines using reinforcement learning to personalize brain training regimens. Rehabilitation centers in Germany and Japan are expanding procurement for post-stroke cognitive recovery protocols outside acute care settings.
- Gamification Solutions:Engagement-driven adherence platforms for senior care providers seeking measurable participation metrics.
- Neurofeedback Systems:Real-time EEG-based cognitive state monitoring hardware-software combinations.
Assessment Tools holds the largest share; momentum sits with Gamification Solutions.
End User:
Cost tier differentiation separates capital-intensive hospital deployments from subscription-light senior care facility rollouts, with outpatient clinics occupying a mid-tier hybrid position.
- Hospitals:Enterprise-scale platforms requiring HL7 FHIR EHR integration and HIPAA-compliant cloud infrastructure. United States health systems dominate procurement volume as CMS coverage determinations for remote neuropsychological monitoring unlock capital budgets.
- Senior Care Facilities:Engagement-focused platforms prioritizing adherence metrics over diagnostic precision. Japan's METI-backed dementia prevention initiatives are accelerating municipal health center procurement of validated screening tools.
- Rehabilitation Centers:Continuous monitoring solutions bridging acute care-to-home transitions.
- Outpatient Clinics:Scalable API-deliverable cognitive tests for distributed neurology practices.
Hospitals command the deepest margin pools; senior care facilities are climbing the fastest.
Technology:
Volume concentration favors Artificial Intelligence segments where natural language processing automation decomposes traditional neuropsychologist evaluations, while Virtual Reality and Wearable Devices remain niche deployments.
- Artificial Intelligence:Automated speech-pattern analysis and phonetic biomarker extraction for mild cognitive impairment screening. Memory clinics in the United States are compressing 45-minute neuropsychologist evaluations into 10-minute patient interactions.
- Mobile Applications:Direct-to-consumer distribution bypassing institutional procurement committees. Adaptive difficulty engines using psychometric item-response theory enable personalized adherence optimization.
- Virtual Reality:Immersive environments for executive function assessment and rehabilitation.
- Wearable Devices:Continuous cognitive state monitoring through physiological signal capture.
Artificial Intelligence holds the largest share; Mobile Applications are gaining share fastest.
Delivery Mode:
Supply concentration in HIPAA-compliant cloud infrastructure creates vendor lock-in for Cloud-Based and Hybrid deployments, while On-Premise solutions persist in security-sensitive European installations.
- Cloud-Based:Scalable API architectures with encrypted neuropsychological data storage. HIPAA and GDPR divergent requirements complicate unified platform deployment for multinational hospital chains.
- Subscription-Based:Recurring revenue models aligning vendor incentives with long-term patient engagement outcomes. Senior care providers in Germany favor predictable operational expenditure over capital-intensive perpetual licenses.
- On-Premise:Localized data sovereignty for jurisdictions with strict patient information localization mandates.
- Hybrid:Edge-compute assessment processing with centralized analytics aggregation.
Cloud-Based holds the largest share; Subscription-Based represents the fastest-growing trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power in the United States exceeds Germany by a factor of two due to Medicare reimbursement advantages, while Japan's municipal procurement frameworks compress vendor margins despite volume concentration.
United States
CMS coverage determinations for remote neuropsychological monitoring unlock hospital capital budgets for digital cognitive platforms. The FDA's software-as-medical-device pathway accelerates product clearance for diagnostic claims. Memory clinics in Boston and San Francisco deploy automated speech-pattern analysis tools that compress traditional evaluations from 45 minutes to 10 minutes.
Germany
Post-stroke rehabilitation monitoring creates white space for continuous cognitive recovery tracking outside acute care settings. The EU AI Act's high-risk system classification imposes conformity assessment burdens that favor established vendors with quality management certifications. Notified body backlogs in Berlin and Munich delay product launches for uncertified algorithm developers.
Japan
METI-backed dementia prevention initiatives accelerate municipal health center procurement of validated screening tools. The country's national pharmaceutical regulator maintains stringent clinical validation requirements for diagnostic software claims. Tokyo and Osaka clusters concentrate demand for senior care engagement platforms with adherence metrics.
United Kingdom
Integrated care systems issue direct tenders for remote cognitive monitoring platforms outside traditional neurology service contracts. GDPR encryption standards for cloud-based neuropsychological data storage complicate multinational platform deployment. London's NHS trusts lead procurement unbundling from incumbent medical device distributors.
Canada
Health Canada regulates cognitive assessment software under medical device frameworks requiring clinical evidence for diagnostic claims. Provincial reimbursement variability creates pricing fragmentation across Ontario and Quebec health systems. Toronto's academic medical centers pioneer API-deliverable cognitive test integration with Epic EHR deployments.
Cognitive Assessment and Training in Healthcare Market Key Industry Players
Technology leadership and cost leadership are held by different player archetypes across the cognitive assessment landscape. The vendor base separates into three tiers: pharmaceutical trial endpoint specialists, direct-to-consumer brain training platforms, and clinical validation service providers. Algorithm developers compete for FDA 510(k) clearances while wellness-positioned entrants bypass regulatory burdens entirely. Consolidation accelerates around quality management systems as the EU AI Act raises compliance barriers.
Within the regulated research tier, Cambridge Cognition Ltd. and Cogstate Ltd. exemplify divergent specialization strategies. Cambridge Cognition occupies a position anchored to pharmaceutical trial endpoints with proprietary algorithm portfolios. Cogstate sits within the sports concussion protocol segment where digital cognitive testing commands premium positioning. CogniFit represents the direct-to-consumer archetype with subscription-based brain training distribution outside institutional procurement channels.
| Leading Market Players |
|---|
| Cambridge Cognition Ltd. |
| Cogstate Ltd. |
| CogniFit |
| Pearson |
| BrainCheck |
| PAR, Inc. |
| Signant Health |
| Bracket |
| Posit Science |
| Others |
Cost & Logistics Intelligence
Cloud infrastructure substitution for on-premise server deployments simultaneously shifts supply geography toward HIPAA-compliant data centers in the United States and compresses pricing premiums for software-native vendors competing against hardware-anchored incumbents. This technical displacement concentrates procurement leverage among encrypted cloud providers while fragmenting margin capture between algorithm developers and clinical validation specialists.
Pricing Analysis
The customization-premium spread separates FDA 510(k)-cleared diagnostic platforms from wellness-positioned consumer tools. SaaS-tiered subscription models dominate, with price differentiation driven by certification tier and EHR integration depth. Pricing pressure intensifies in the direct-to-consumer tier as adaptive difficulty engines commoditize basic brain training functionality. Senior care facilities exhibit highest price sensitivity; pharmaceutical trial endpoint specialists command lowest.
Supply Chain Analysis
Just-in-time API deployment preferences among outpatient clinics contrast with strategic stockpiling of validation documentation by vendors pursuing EU AI Act conformity. Supply concentrates in United States cloud infrastructure, German quality management certification bodies, and Japanese municipal health procurement frameworks. Component dependencies span natural language processing libraries, touchscreen hardware, and encrypted neuropsychological data storage. Single-source vulnerability in HIPAA-compliant cloud providers creates lock-in risk. Distribution runs through hospital procurement committees and direct-to-consumer app marketplaces.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Paper-based Mini-Mental State Examination protocols represent a persistent substitution threat that digital platform vendors must actively displace through reimbursement alignment and workflow integration.
For Market Incumbents: Fortify market position by deepening FDA 510(k) clearance portfolios for diagnostic claims and securing pre-built HL7 FHIR connectors with Epic and Cerner deployments. Threat of wellness-adjacent consumer positioning from algorithm developers demands channel control through hospital system exclusive partnerships. For New Entrants and Emerging Players: FDA breakthrough device designation fast-track unlocks accelerated clearance timelines for speech-pattern analysis tools targeting memory clinic workflows. White space concentrates in post-stroke rehabilitation monitoring across German acute care-to-home transitions. Go-to-market angle should emphasize API-deliverable cognitive tests for distributed neurology practices seeking scalable screening protocols. For Investors and Strategic Acquirers: EU AI Act high-risk system classification reshapes the acquisition landscape toward vendors with established quality management certifications and post-market surveillance infrastructure. Long-term viability centers on platforms capable of spanning regulated diagnostic claims and wellness-adjacent consumer markets. Acquisition target archetype: algorithm developers with proprietary phonetic biomarker extraction and existing notified body relationships. Signal to watch: CMS national coverage determinations for remote neuropsychological monitoring crossing threshold into standard benefit category.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Submission | Unlocks Medicare reimbursement codes for diagnostic cognitive assessment platforms in United States hospital systems. |
| CE Marking Pathway | EU AI Act conformity assessment enables deployment across German memory clinics and rehabilitation centers. |
| Hospital System Partnership | NHS integrated care system direct tenders displace incumbent medical device distributor relationships in United Kingdom. |
| Software Companion Development | Adaptive difficulty engines using reinforcement learning optimize adherence metrics for Japanese senior care providers. |
| Reimbursement Strategy | CMS coverage determinations for remote neuropsychological monitoring dictate addressable market expansion velocity. |
Research Approach
A standing panel of neuropsychologists, hospital procurement managers, GPO contracts specialists, and FDA regulatory consultants provided ongoing calibration across primary interview cycles and secondary source validation. Stakeholder input combined with CMS Medicare reimbursement databases, FDA 510(k) clearance records, hospital procurement system tenders, and EU notified body conformity assessment filings. Bottom-up vendor revenue triangulation against top-down addressable market sizing anchored forecast consistency.
Consistency checks validated volume and value outputs against external benchmarks across the projection horizon. Segmentation modeling incorporated product type, end user archetype, technology stack, and delivery mode dimensions with regional regulatory cluster overlays. CAGRs derived from fitted growth curves applied to validated baseline estimates. Industry-specific inputs included pharmaceutical trial endpoint adoption rates and municipal health center procurement velocity under Japan's METI-backed initiatives.
Decision-makers should treat outputs as directional under assumptions of stable CMS reimbursement policy and EU AI Act implementation timelines; material deviation would warrant model refresh. Forecasts embed assumptions regarding cloud infrastructure cost trajectories and neuropsychologist talent supply elasticity. Revision becomes warranted when FDA software-as-medical-device pathway modification or CMS national coverage determination shifts cross implementation thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Healthcare IT
Hospital Capacity Management Solutions Market
Healthcare IT
US Urgent Care Center Software Market
Healthcare IT
High-Value Healthcare Asset Tracking and Recovery Platforms Market
Healthcare IT
Global Orthopedic Software Market
Healthcare IT
E-Prescribing Market
Healthcare IT
Pharma Management Software Market
Healthcare IT
Global Telepharmacy Market
Healthcare IT
US Long Term Care Software Market
Healthcare IT
Global Pharmacy Management System Market
Healthcare IT
North American Dental Software Market
Healthcare IT
Femtech Market
Healthcare IT
ECG Management Systems Market
Healthcare IT
US Dental Clearing Houses Market
Healthcare IT
Revenue Cycle Management (RCM) Market
Healthcare IT
Clinical Perinatal Software Market
Healthcare IT
Global Patient Flow Management Solutions Market