
 Hand Hygiene Monitoring System Market | 2026-2036
Hand Hygiene Monitoring System Market Size, Share, and Industry Trends Forecast 2026-2036
Hand Hygiene Monitoring System Market Analysis
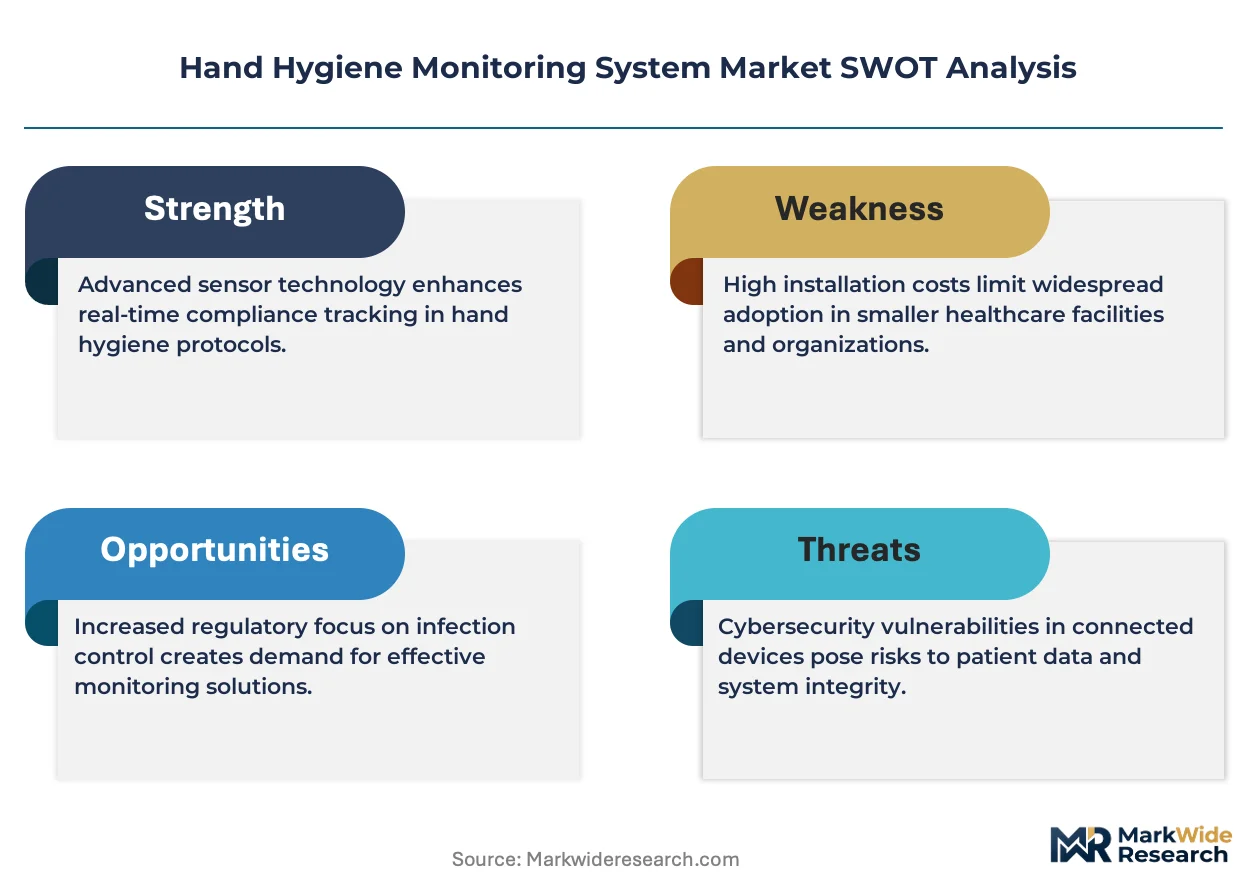
Joint Commission accreditation standards are redrawing competitive boundaries in the hand hygiene monitoring system market. Ecolab leverages its institutional cleaning contracts to bundle monitoring hardware with consumable supply agreements. BioVigil Healthcare Systems specializes in badge-based compliance verification, anchoring its position in academic medical centers with complex workflow requirements.
Hand hygiene monitoring systems encompass sensor networks, wearable badges, and software platforms that detect, record, and report sanitization events in clinical environments. These systems typically integrate RFID or Bluetooth Low Energy transponders with alcohol-based rub dispensers to capture compliance timestamps and duration data for infection control auditing. Wall-mounted sensors and stationary monitors currently occupy the largest installed base, though wearable devices represent the fastest-expanding category as hospitals seek real-time staff tracking without fixed infrastructure dependency. Cloud-based deployment models are capturing margin pools previously held by on-premise installations, particularly among multi-site health systems requiring centralized dashboard analytics.
FDA guidance on medical device data systems, CDC healthcare infection control recommendations, and Joint Commission National Patient Safety Goals collectively shape product design requirements and hospital procurement criteria in the United States. The EU Medical Device Regulation and GDPR data handling constraints add compliance layers for vendors serving European facilities. Stakeholders must weigh interoperability investments against the risk of stranded assets as health system IT architectures consolidate around unified electronic health record platforms.
Market Dynamics
Cloud-based IoT architectures are displacing legacy audit methods as health systems consolidate IT infrastructure around unified electronic health record platforms. This shift compresses vendor margins while elevating interoperability requirements.
Growth Catalysts
- Joint Commission National Patient Safety Goals:Accreditation standards now tie infection rates to facility credentials, compelling acute care hospitals to automate compliance verification.
- Wearable BLE transponders:Badge-based systems eliminate fixed infrastructure dependency, accelerating deployment in academic medical centers with complex workflow patterns.
- Reimbursement policy linkage:United States, Germany, and Japan now connect infection metrics to payment rates, creating procurement urgency.
Market Restraints
- GDPR data handling constraints:European facilities face compliance layers that extend procurement timelines and increase legal review costs.
- Semiconductor supply concentration:Sensor component sourcing remains concentrated in East Asian foundries, exposing hardware vendors to input volatility.
- Legacy system interoperability gaps:Existing on-premise installations resist cloud migration without costly middleware development.
Strategic Opportunities
- Long-term care underpenetration:Skilled nursing facilities in the United States lack automated monitoring, presenting greenfield installation potential.
- AI-enabled predictive analytics:Machine learning convergence with real-time compliance data enables outbreak risk scoring before cluster formation.
- Outcome-based contracting:CMS infection reduction incentives allow vendors to structure performance-linked revenue models.
Industry Challenges
- Clinical workflow integration:Frontline nursing staff resist additional documentation burdens, requiring change management investment.
- Multi-site data standardization:Health system mergers create fragmented telemetry formats that complicate centralized dashboard deployment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Hand Hygiene Monitoring System Market |
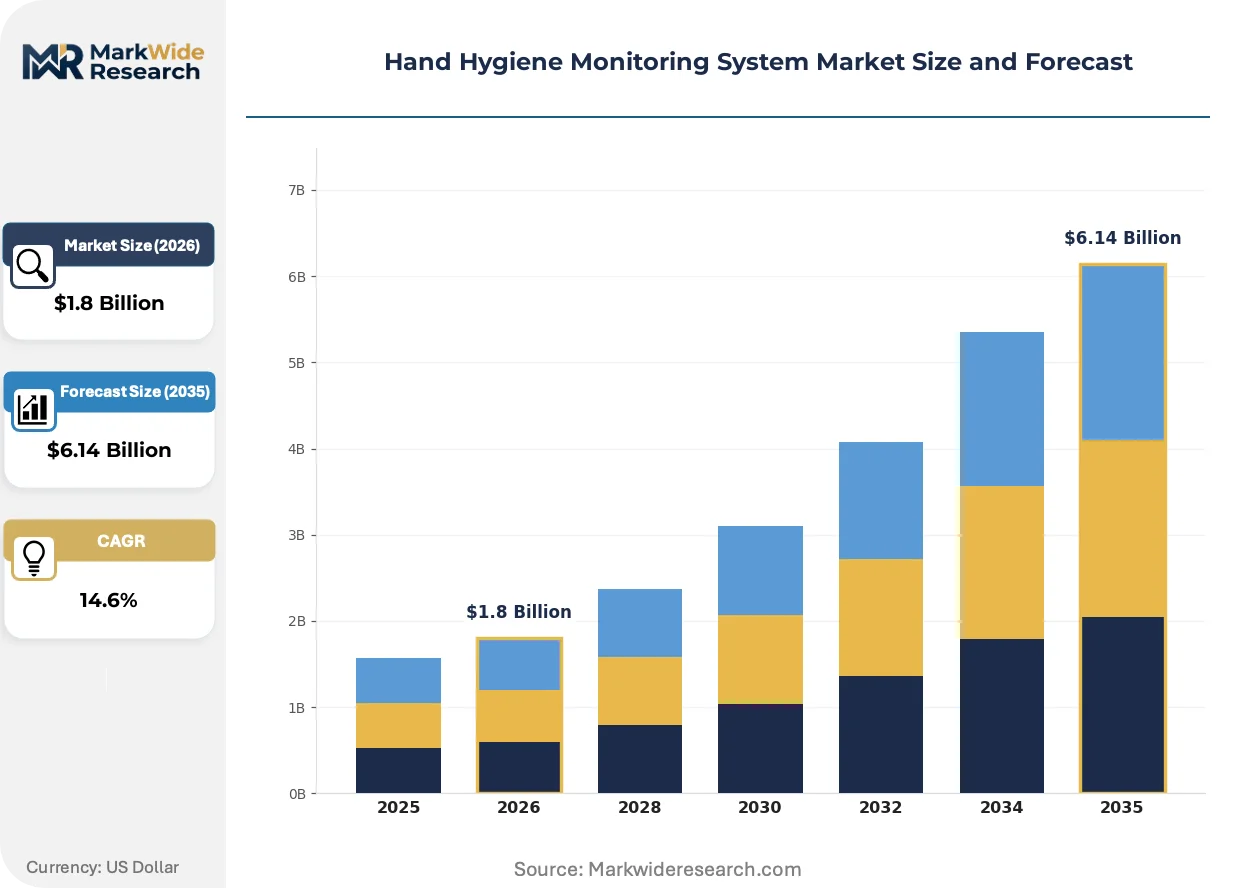
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $6.14 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Wearable Devices, Mobile Applications, Wall-mounted Sensors, Stationary Monitors End User: Hospitals, Clinics, Long-term Care Facilities, Research Laboratories Technology: RFID, IoT Solutions, Bluetooth, Cloud-based Systems Deployment: On-premise, Cloud-based, Hybrid, SaaS |
| Companies Covered | Deb Group Ltd., HandGiene Corp., Ecolab, Midmark Corporation, Stanley Healthcare, GOJO Industries, Halma plc, Avanos Medical, BioVigil Healthcare Systems, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Hand Hygiene Monitoring System Market Emerging Trajectories
Real-time location systems are reshaping how compliance data flows from point-of-care to infection control committees. Three developments dominate vendor roadmaps.
Computer vision-based hand hygiene verification is displacing RFID badge dependency in high-throughput emergency departments. These camera systems detect motion patterns and alcohol rub duration without staff-worn hardware. Major academic medical centers in Boston and Philadelphia are piloting installations. The technology is displacing fixed infrastructure investments while raising privacy governance requirements.
EU Medical Device Regulation reclassification is elevating software-as-a-medical-device scrutiny for cloud analytics platforms. Vendors must now maintain technical documentation and post-market surveillance comparable to Class IIa hardware. German hospital procurement offices are extending vendor qualification timelines by eight to twelve months. This regulatory friction favors established players with dedicated regulatory affairs functions.
Subscription pricing for compliance-as-a-service is replacing capital expenditure models among mid-size community hospitals. Third-party financing vehicles now bundle sensor hardware, software licenses, and maintenance into per-bed monthly fees. This shift transfers technology obsolescence risk from hospital balance sheets to vendor P&L statements. The model is most visible in United States health systems with constrained capital allocation committees.
Hand Hygiene Monitoring System Market Segmentation
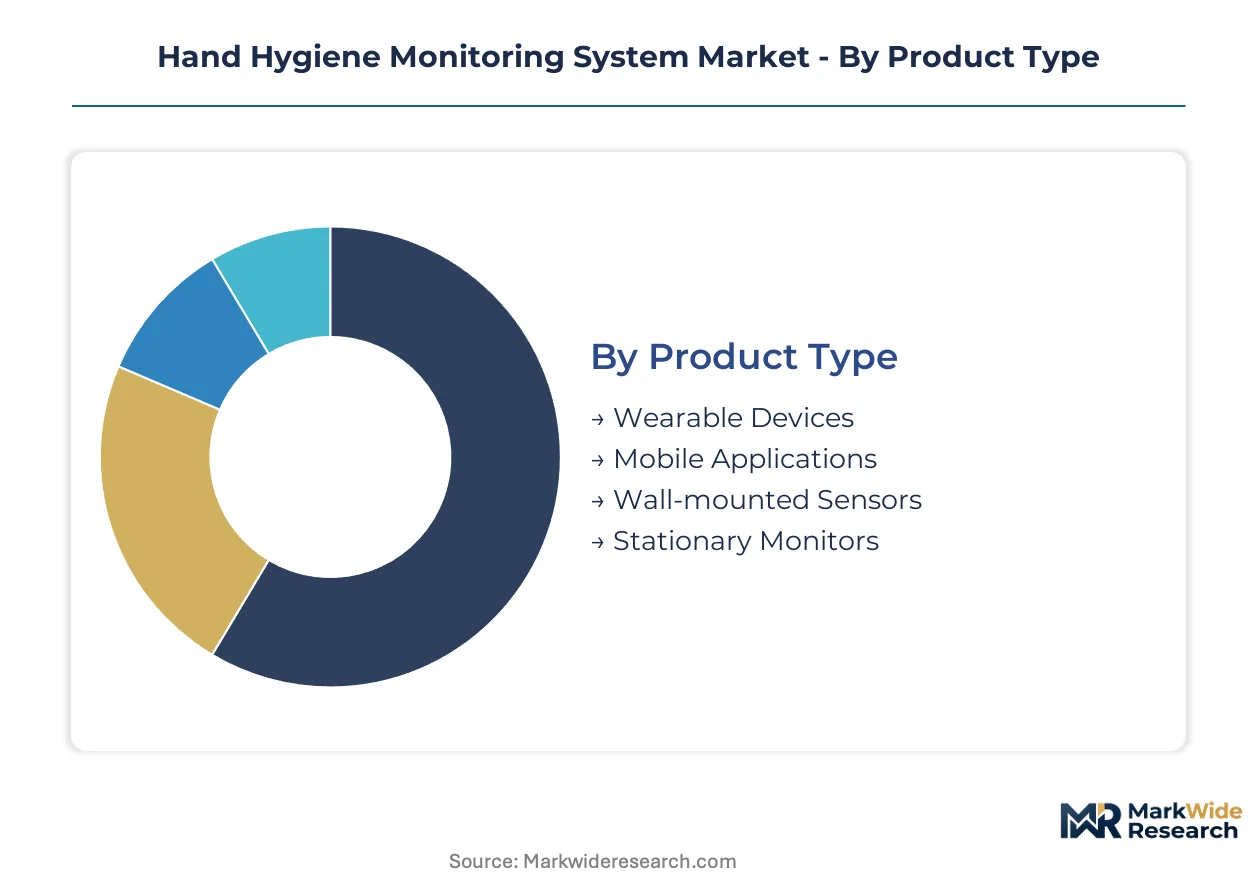
Segmentation in hand hygiene monitoring reveals distinct technology adoption curves across facility types and infrastructure maturity. Procurement patterns diverge sharply between capital-constrained community hospitals and multi-site academic systems with centralized IT governance.
Product Type:
Wall-mounted sensors face intensifying substitution pressure from wearable BLE transponders that eliminate fixed infrastructure dependency.
- Wearable Devices:Badge-based systems integrate Bluetooth Low Energy transponders with alcohol rub dispensers to capture compliance timestamps without fixed reader installation. Demand concentrates in academic medical centers with complex workflow patterns, driven by Joint Commission accreditation requirements for automated verification. These devices are gaining share fastest among facilities undergoing renovation where rewiring costs deter wall-mounted alternatives.
- Wall-mounted Sensors:Stationary RFID readers and infrared detectors mounted at point-of-care locations form the largest installed base. United States community hospitals with constrained capital allocation favor these units for their lower per-bed deployment cost, though retrofitting legacy buildings triggers electrical contractor delays.
- Mobile Applications:Smartphone-based compliance logging leverages existing hospital-issued devices for event capture. Germany's GDPR implementation has slowed adoption due to biometric data handling restrictions on personal devices.
- Stationary Monitors:Fixed computer vision systems with camera-based hand hygiene verification are piloting in Boston and Philadelphia emergency departments. Privacy governance requirements extend procurement timelines.
Wall-mounted sensors retain volume leadership; wearable devices hold the steepest expansion curve.
End User:
Cost tier stratification separates integrated delivery networks with enterprise procurement authority from independent facilities purchasing through group purchasing organizations.
- Hospitals:Acute care facilities with Joint Commission accreditation mandates drive the majority of system deployments. United States hospital systems now tie infection metrics to CMS reimbursement rates, creating procurement urgency for automated compliance verification.
- Long-term Care Facilities:Skilled nursing facilities in the United States remain underpenetrated, presenting greenfield installation potential as Medicaid waiver programs expand infection control requirements.
- Clinics:Ambulatory surgery centers and outpatient dialysis units deploy lighter cloud-based configurations without enterprise IT integration.
- Research Laboratories:Biosafety level facilities require specialized compliance documentation for grant funding compliance, favoring systems with audit-grade data export capabilities.
Hospitals command the dominant revenue share; long-term care facilities are expanding most quickly.
Technology:
Application-specific performance requirements favor RFID for high-throughput emergency departments while IoT architectures win in multi-site consolidation scenarios.
- IoT Solutions:Cloud-connected sensor networks with centralized dashboard analytics are displacing legacy audit methods as health systems consolidate IT infrastructure around unified electronic health record platforms. This shift compresses vendor margins while elevating interoperability requirements.
- Cloud-based Systems:Software-as-a-service deployment transfers technology obsolescence risk from hospital balance sheets to vendor P&L statements. Subscription pricing dominates among mid-size United States community hospitals with constrained capital allocation committees.
- RFID:Passive and active radio-frequency identification systems provide mature, low-latency event detection for high-throughput clinical environments. German hospital procurement offices extend qualification timelines under EU Medical Device Regulation reclassification.
- Bluetooth:BLE transponders enable real-time staff tracking without fixed infrastructure dependency, accelerating deployment in Japan's academic medical centers with complex workflow patterns.
RFID maintains the largest installed base; IoT solutions are climbing the fastest.
Deployment:
Customer type segmentation separates enterprise health systems with dedicated IT security teams from independent facilities relying on vendor-managed infrastructure.
- Cloud-based:Third-party hosted platforms with per-bed monthly subscription fees eliminate capital expenditure barriers. United States multi-site health systems require centralized dashboard analytics across dozens of facilities.
- SaaS:Fully vendor-managed compliance-as-a-service bundles sensor hardware, software licenses, and maintenance into operational expenditure. This model is most visible in health systems with constrained capital allocation committees.
- On-premise:Locally hosted installations persist in facilities with strict data residency requirements or limited internet reliability. Legacy system interoperability gaps resist cloud migration without costly middleware development.
- Hybrid:Mixed architectures deploy edge computing for real-time compliance alerts with cloud aggregation for enterprise analytics. GDPR data handling constraints in European facilities favor this architecture for sensitive staff location data.
On-premise retains legacy dominance; cloud-based deployment is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Reimbursement policies in the United States, Germany, and Japan now tie infection rates to facility accreditation, creating procurement urgency for automated compliance verification. CMS penalties for hospital-acquired infections and similar frameworks abroad are accelerating capital deployment toward sensor networks and wearable badges.
United States
Joint Commission National Patient Safety Goals mandate automated hand hygiene verification for acute care accreditation. FDA guidance on medical device data systems shapes product design requirements for vendors serving American hospitals. Boston and Philadelphia academic medical centers pilot computer vision-based verification in high-throughput emergency departments.
Germany
EU Medical Device Regulation reclassification elevates software-as-a-medical-device scrutiny for cloud analytics platforms. GDPR data handling constraints extend procurement timelines by eight to twelve months as hospital qualification processes tighten. The Rhine-Ruhr metropolitan region concentrates vendor regulatory affairs functions serving Central European facilities.
Japan
METI infection control standards and PMDA device registration requirements drive adoption of real-time staff tracking systems. Reimbursement policy linkage to infection metrics creates procurement urgency comparable to the United States model. Academic medical centers in Tokyo and Osaka deploy BLE transponder networks to manage complex workflow patterns.
United Kingdom
NHS infection prevention frameworks and Care Quality Commission standards compel hospital trusts toward automated compliance documentation. CE marking requirements under retained EU law maintain technical barriers for non-European vendors. London and the Southeast health system clusters consolidate procurement through centralized IT governance structures.
Australia
TGA medical device regulations and state-based health department infection control policies shape vendor market entry requirements. Cloud-based deployment models gain traction among multi-site public health networks seeking centralized dashboard analytics. New South Wales and Victoria hospital systems lead procurement volume in the Asia-Pacific region outside Japan.
Hand Hygiene Monitoring System Market Vendor Landscape
Player mix skews toward diversified hygiene conglomerates and specialized healthcare technology developers. Market structure exhibits moderate consolidation around institutional cleaning contract holders and badge-based workflow specialists. Two strategic archetypes dominate: bundled solution providers leveraging consumable supply relationships, and pure-play compliance technology developers targeting academic medical centers. Competitive moves center on cloud platform interoperability investments and subscription pricing model transitions.
Among diversified conglomerates, Ecolab and Halma plc represent the bundled service archetype, anchoring positions through institutional contract relationships. BioVigil Healthcare Systems occupies the specialized technology tier, exemplifying badge-based compliance verification for complex clinical workflows. Deb Group Ltd. and GOJO Industries sit within the hygiene supply-integrated segment, leveraging dispenser infrastructure for monitoring system deployment. These three archetypes reflect divergent paths to hospital procurement access.
| Leading Market Players |
|---|
| Deb Group Ltd. |
| HandGiene Corp. |
| Ecolab |
| Midmark Corporation |
| Stanley Healthcare |
| GOJO Industries |
| Halma plc |
| Avanos Medical |
| BioVigil Healthcare Systems |
| Others |
Supply Flow & Price Mechanics
Sixteen-week lead times for BLE transponder chipsets concentrate pricing power with East Asian foundries, compressing margins for hardware vendors while elevating subscription-based SaaS models that transfer obsolescence risk to buyers.
Pricing Analysis
Cost-plus contracts indexed to semiconductor commodity benchmarks dominate hardware procurement, with three-tier pricing structure across premium, standard, and economy levels tied to FDA clearance tier and cloud analytics bundling. Price differentiation separates Joint Commission-validated systems from basic compliance loggers, while subscription pricing for compliance-as-a-service gains share among capital-constrained community hospitals. Cost compression in sensor hardware is intensifying because foundry capacity constraints limit component sourcing flexibility. Community hospitals exhibit highest price sensitivity, whereas multi-site academic systems prioritize interoperability over per-bed cost.
Supply Chain Analysis
Taiwan Strait transit vulnerabilities expose hardware vendors to concentrated foundry risk, as Taiwan, South Korea, and Japan anchor BLE chipset and RFID sensor production. Supply chains draw from rare earth magnets for badge enclosures, medical-grade plastics for dispenser housings, and cloud infrastructure from hyperscale providers. Single-source vulnerability in 7nm BLE fabrication creates procurement contingency requirements. Distribution runs through group purchasing organizations for independent facilities and direct enterprise contracts for integrated delivery networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Hospital capital expenditure cycles are recovering from pandemic-induced deferrals, with Joint Commission accreditation deadlines creating procurement urgency that compresses sales cycles and elevates competitive intensity.
For Market Incumbents: Shield installed base relationships by embedding predictive analytics modules that raise switching costs for health systems with centralized EHR consolidation. Deepen backward integration into BLE chipset sourcing through multi-year foundry offtakes to secure allocation against fabless entrants. Prioritize regulatory affairs capacity expansion to navigate EU MDR reclassification timelines that now extend vendor qualification by eight to twelve months.
For New Entrants and Emerging Players: AI-enabled outbreak risk scoring represents an underserved service layer where incumbents under-serve infection control committees seeking predictive capabilities. Long-term care facilities in the United States present the most penetrable segment, with Medicaid waiver expansion creating greenfield installation potential absent entrenched vendor relationships. Structure compliance-as-a-service offerings with per-bed monthly fees to bypass capital committee approval barriers.
For Investors and Strategic Acquirers: Carve-out targets emerge from diversified hygiene conglomerates seeking to monetize non-core monitoring technology divisions amid portfolio rationalization. The five-to-ten-year viability window favors vendors with cloud-native architectures and established hospital system partnerships over legacy on-premise installers. Watch CMS infection reduction incentive expansion as the inflection indicator for performance-linked contracting adoption.
| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | EU MDR reclassification elevates documentation requirements for cloud analytics platforms serving German hospitals. |
| Hospital System Partnership | Multi-site IDN consolidation creates enterprise procurement authority favoring vendors with centralized dashboard capabilities. |
| Software Companion Development | AI-enabled predictive analytics modules differentiate offerings for infection control committees seeking outbreak risk scoring. |
| Reimbursement Strategy | CMS infection metric linkages to payment rates create procurement urgency for automated compliance verification systems. |
| Backward Integration | Captive supply of BLE transponder chipsets secures allocation against fabless competitors during foundry capacity constraints. |
Methodological Framework
Initial hypotheses were tested against primary input from infection control officers, hospital procurement managers, biomedical engineers, and GPO contracts specialists and refined through secondary validation against FDA 510(k) filings, CMS Medicare cost reports, Joint Commission accreditation databases, and hospital procurement system records. Bottom-up facility-level deployment estimates triangulated with top-down vendor revenue analysis.
Variance decomposition across product type, end user, technology architecture, and deployment model segments shaped analytical framework construction over the projection horizon. CAGRs derived from logistic diffusion curves fitted to historical adoption patterns, with inputs including health system IT consolidation timelines and regulatory deadline schedules.
Forecasts assume regulatory continuity in FDA device data systems guidance and EU MDR implementation; material policy shifts would require re-modeling. Practitioners should keep alternative scenarios live as reimbursement linkage expansion and semiconductor supply normalization evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Healthcare IT
Medical IoT Software Market
Healthcare IT
Global Accountable Care Solutions Market
Healthcare IT
High-Value Healthcare Asset Tracking and Recovery Platforms Market
Healthcare IT
Pharma Management Software Market
Healthcare IT
Operating Room Management Software Market
Healthcare IT
Pharmaceutical Software Market
Healthcare IT
Operating Room Software Market
Healthcare IT
Global Pharmaceutical Quality Management Software Market
Healthcare IT
Assisted Living Software Market
Healthcare IT
Healthcare Credentialing Software Market
Healthcare IT
Asia-Pacific Dental Practice Management Software Market
Healthcare IT
Global Pharma Knowledge Management Software Market
Healthcare IT
Veterinary Practice Management Software Market
Healthcare IT
Americas Healthcare Human Resources (HR) Software Market
Healthcare IT
Global Hospital Asset Tracking and Inventory Management Systems Market
Healthcare IT
Global IT Spending in Healthcare Market