
 Technology Spending on Revenue Cycle Management Market | 2026-2036
Technology Spending on Revenue Cycle Management Market Size, Share, and Industry Trends Forecast 2026-2036
Technology Spending on Revenue Cycle Management Market Analytics
Hospital end-user demand is pivoting toward integrated revenue cycle platforms that unify clinical documentation with billing workflows. Epic Systems Corporation anchors this shift through its deep EHR-revenue cycle integration across major academic medical centers. Cerner Corporation competes aggressively on cloud migration roadmaps for regional health systems. McKesson Corporation leverages its pharmaceutical distribution backbone to extend RCM services into specialty pharmacy billing, a niche with complex reimbursement dynamics.
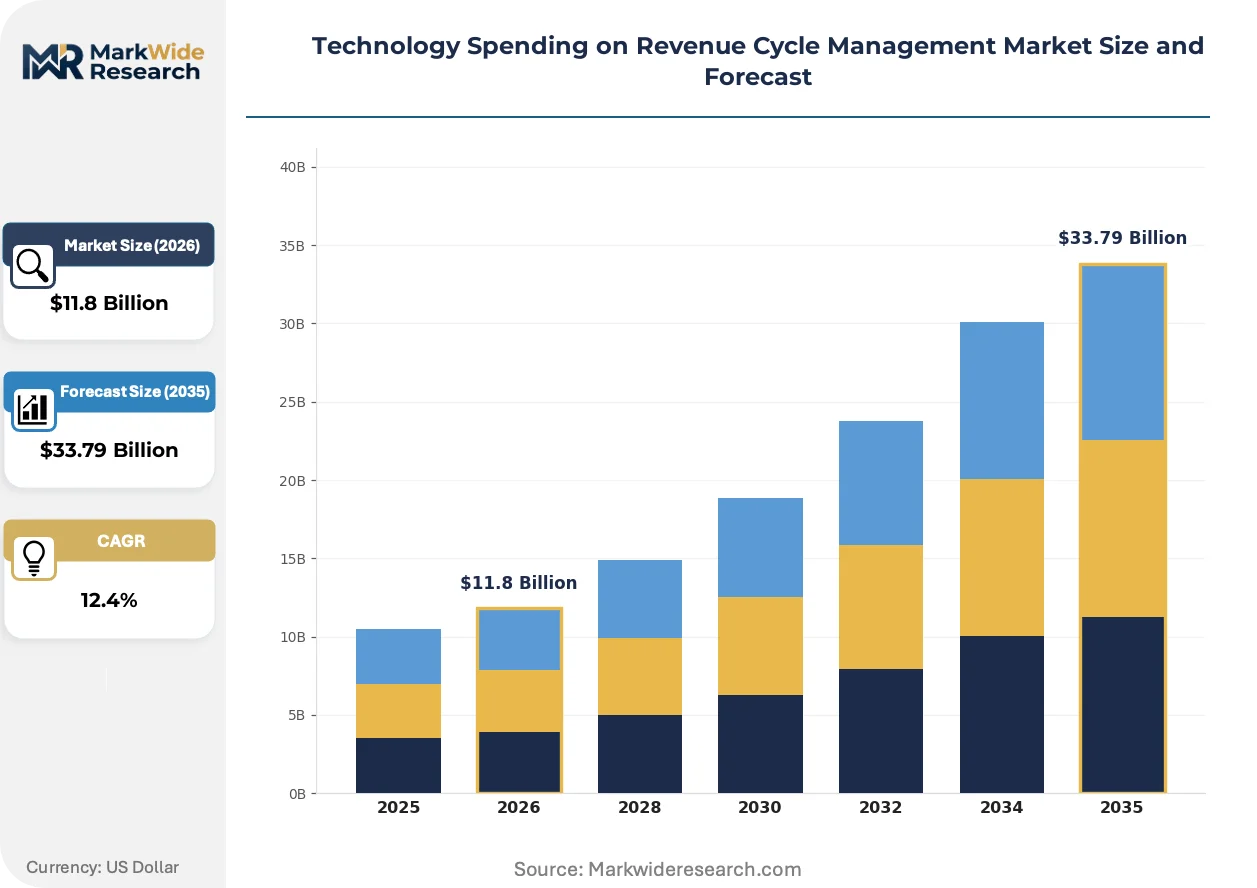
Technology spending on revenue cycle management encompasses software, services, and infrastructure expenditures that automate patient registration, coding, claims submission, payment collection, and denial management across healthcare provider organizations. Core platforms typically integrate HL7 FHIR interoperability standards, robotic process automation for claims scrubbing, and real-time eligibility verification APIs to reduce days in accounts receivable below thirty. Software Solutions dominate current procurement budgets as hospitals replace legacy billing engines, while Cloud-Based deployment is capturing the fastest expansion trajectory as IT departments shed on-premises maintenance burdens. Managed Services retains durable margin pools where vendors assume full operational responsibility for denial management and patient financial engagement.
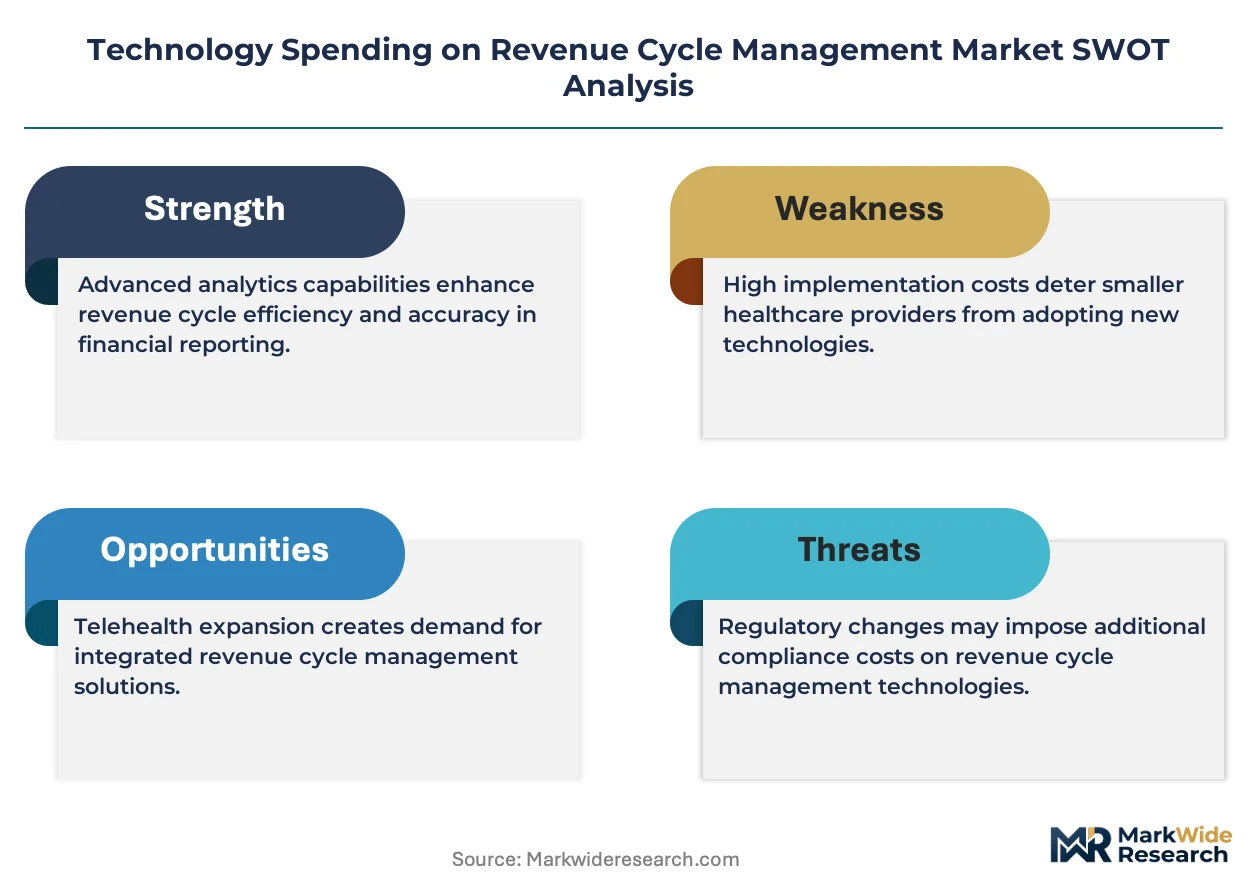
CMS price transparency rules and the No Surprises Act enforcement by HHS are compelling hospitals to upgrade patient estimation and out-of-network billing capabilities, directly stimulating RCM technology refresh cycles. FDA oversight of clinical decision support tools increasingly intersects with revenue cycle platforms where diagnostic coding accuracy affects reimbursement integrity. Stakeholders must weigh the trade-off between vertical platform consolidation from EHR vendors versus best-of-breed specialty tools as payer contract complexity intensifies.
Market Dynamics
Hospital procurement committees are consolidating vendor relationships around platforms that embed CMS price transparency compliance directly into patient access workflows, compressing evaluation cycles from eighteen months to under six.
Growth Catalysts
- CMS Price Transparency Mandates:HHS enforcement of machine-readable file requirements and good faith estimates is compelling health systems to replace legacy estimation engines with automated patient cost calculators.
- Prior Authorization Digitization:The shift from fax-based to API-driven prior auth workflows is accelerating platform replacements among specialty clinics and ambulatory surgery centers.
- Cloud Infrastructure Maturation:Health system IT departments are shedding on-premises data center obligations, creating procurement urgency for SaaS-native revenue cycle platforms with automatic compliance updates.
Market Restraints
- Integration Tax:Custom HL7 FHIR mapping between EHRs and standalone RCM modules consumes 40% of implementation budgets, deterring mid-size hospitals from best-of-breed strategies.
- Talent Scarcity:Certified medical coders with dual expertise in clinical documentation and denial management command compensation premiums that strain rural health system operating margins.
- Payer Concentration:Dominance of three national payers in commercial markets creates asymmetric negotiation leverage, forcing providers to absorb technology costs without proportional rate increases.
Strategic Opportunities
- Rural Health System Modernization:Critical access hospitals in the US Mountain West and Great Plains remain underserved by integrated platforms, presenting whitespace for cloud-native vendors with rapid-deployment methodologies.
- Specialty Pharmacy Billing Convergence:Infusion centers and oncology clinics require RCM tools that reconcile medical and pharmacy benefit adjudication, a capability gap unaddressed by generic hospital billing systems.
- Real-Time Eligibility APIs:Payer-provider data exchange standards mandated by the No Surprises Act are creating openings for middleware vendors that normalize disparate payer response formats.
Industry Challenges
- Legacy Debt Burden:Decades-old patient accounting systems with custom COBOL extensions require expensive parallel-running migrations that delay cloud transitions by 24-36 months.
- Denial Appeal Complexity:Payer-specific clinical documentation requirements vary across fifty state Medicaid programs, forcing providers to maintain redundant coding workflows or accept elevated write-off rates.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Technology Spending on Revenue Cycle Management Market |
| Market Size in 2026 | $11.8 Billion |
| Market Size in 2035 | $33.79 Billion |
| CAGR (2026 – 2036) | 12.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Software Solutions, Consulting Services, Implementation Services, Managed Services Deployment Model: Cloud-Based, On-Premises, Hybrid, Web-Based End User: Hospitals, Clinics, Laboratory Services, Health Systems Functionality: Billing Solutions, Revenue Analysis, Payment Processing, Claims Management |
| Companies Covered | Optum, Epic Systems Corporation, R1 RCM, Cerner Corporation, McKesson Corporation, Change Healthcare, Allscripts Healthcare Solutions, Oracle, 3M Health Information Systems, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Technology Spending on Revenue Cycle Management Market Evolving Landscape
Revenue cycle technology is converging with clinical workflow platforms, eroding the historical boundary between documentation integrity and billing accuracy. Three forces are compressing this convergence timeline.
Robotic process automation for claims scrubbing is overtaking rules-based edit engines that require manual configuration updates. Community health systems and independent physician associations are adopting RPA modules at the fastest clip, driven by staffing constraints in business offices. The technology is overtaking legacy clearinghouse relationships by embedding denial prediction directly into charge capture workflows.
CMS interoperability rules under the 21st Century Cures Act are mandating standardized patient access APIs that expose cost estimation data. Hospital legal departments are restructuring vendor contracts to assign liability for data accuracy, shifting risk allocation toward technology suppliers. Academic medical centers with complex payer mixes are experiencing the steepest compliance costs, accelerating consolidation around EHR-native estimation tools.
Subscription pricing for RCM platforms is displacing perpetual license models that dominated hospital capital budgets for two decades. Finance committees now classify software spend as operating expenditure, compressing approval hierarchies and shortening procurement cycles. Regional health systems in the US Southeast are leading this transition, attracted by predictable cash outflows and automatic feature updates.
Technology Spending on Revenue Cycle Management Market Segmentation
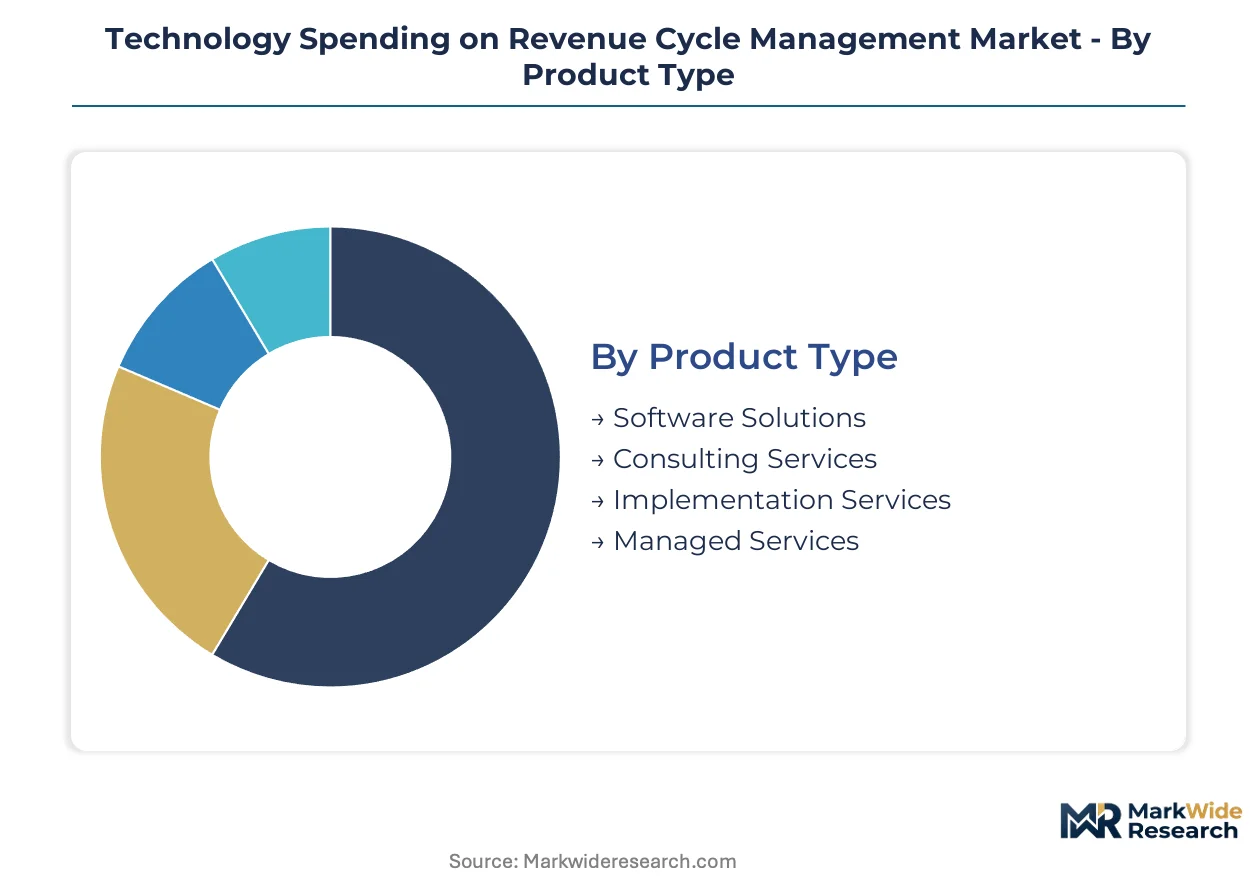
RCM technology procurement patterns diverge sharply across product architectures, delivery models, and care settings. Understanding these fault lines reveals where vendor consolidation pressures concentrate and where specialty providers retain pricing power.
Product Type:
Software Solutions command the largest absolute spend while Managed Services capture the highest margin premiums per contract. The volume-premium split separates capital-intensive platform purchases from recurring operational expenditures.
- Software Solutions:Core platforms embed HL7 FHIR interoperability, robotic process automation for claims scrubbing, and real-time eligibility verification APIs. Hospital networks in the US Southeast are replacing legacy billing engines with SaaS-native alternatives that automate CMS price transparency compliance.
- Managed Services:Vendors assume full operational responsibility for denial management, patient financial engagement, and accounts receivable optimization. Critical access hospitals in rural Texas and Montana outsource entire revenue cycle functions to offset certified coder talent scarcity.
- Consulting Services:Workflow redesign and payer contract optimization advisory for mid-size health systems navigating No Surprises Act implementation.
- Implementation Services:Data migration, EHR-RCM integration, and staff training programs with 12-18 month engagement horizons.
Mature deployment sits with Software Solutions. Newer deployment is concentrated in Managed Services.
Deployment Model:
Cloud infrastructure maturation is redistributing procurement budgets away from capital-intensive on-premises installations toward subscription-based operating expenditures. The cost tier separation reflects IT department staffing constraints and compliance update velocity requirements.
- Cloud-Based:SaaS-native platforms with automatic regulatory updates, API-first architectures, and elastic compute scaling. Epic Systems and Oracle are expanding installed bases among integrated delivery networks in California and New York that prioritize rapid CMS mandate adaptation.
- Hybrid:Sensitive patient accounting data remains on-premises while eligibility verification and claims submission leverage cloud APIs. Regional health systems in Illinois and Ohio adopt this model to balance security governance with interoperability requirements.
- On-Premises:Legacy data center installations with custom COBOL extensions requiring dedicated maintenance teams.
- Web-Based:Lightweight browser-accessible modules for specialty clinics and independent physician associations with limited IT infrastructure.
Established infrastructure characterizes On-Premises. Cloud-Based deployment is climbing the fastest.
End User:
Procurement authority and contract scale separate hospital network central purchasing from distributed clinic decision-making. The customer type dimension determines platform complexity requirements and implementation timeline tolerance.
- Hospitals:Academic medical centers and community hospitals require integrated platforms unifying clinical documentation with billing workflows. Major centers in Massachusetts and Pennsylvania anchor demand for EHR-native revenue cycle tools with complex payer mix management.
- Health Systems:Multi-hospital integrated delivery networks consolidate vendor relationships across dozens of facilities. IDNs in Florida and Arizona are compressing evaluation cycles from eighteen months to under six for CMS compliance-embedded platforms.
- Clinics:Ambulatory surgery centers and specialty clinics prioritize API-driven prior authorization and rapid-deployment methodologies.
- Laboratory Services:Independent diagnostic facilities with distinct billing requirements for molecular and pathology testing reimbursement.
Consolidated purchasing dominates Health Systems. Fragmented procurement characterizes Clinics.
Functionality:
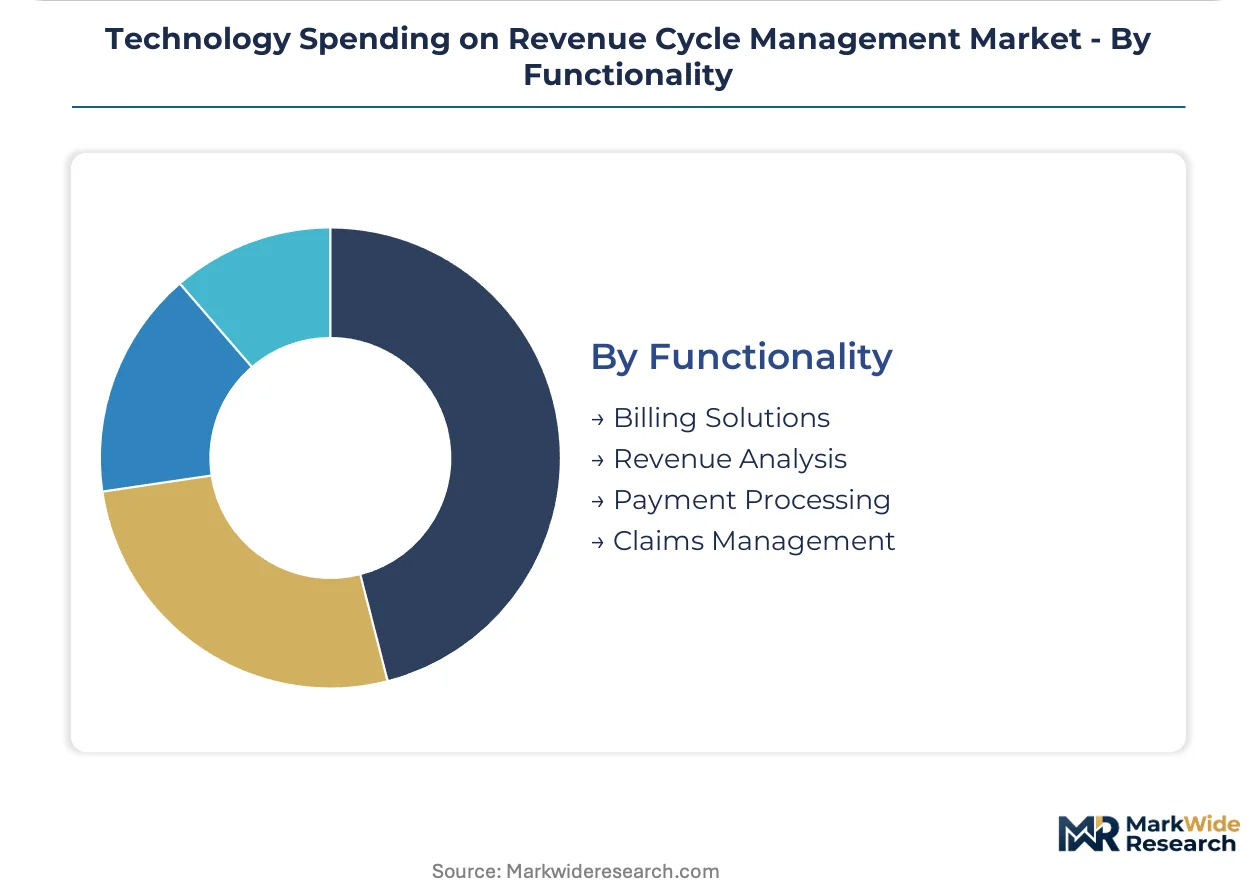
Workflow integration depth separates point solutions from comprehensive platforms. The application maturity spectrum ranges from legacy claims clearinghouse relationships to predictive denial analytics.
- Billing Solutions:Patient estimation engines, charge capture modules, and automated coding assistance that embed price transparency compliance directly into patient access workflows. Hospital legal departments in Michigan and Georgia are restructuring contracts to assign data accuracy liability toward technology suppliers.
- Claims Management:Real-time claims scrubbing, denial prediction, and appeal workflow automation with payer-specific clinical documentation requirements. Oncology clinics in North Carolina require tools reconciling medical and pharmacy benefit adjudication.
- Revenue Analysis:Payer mix optimization, contract modeling, and bad debt forecasting dashboards for finance committees.
- Payment Processing:Patient financial engagement portals, payment plan automation, and point-of-service collection tools.
Deep integration defines Billing Solutions. Claims Management is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
US hospital networks cluster around CMS Innovation Center zones and HHS-designated health IT testbeds, concentrating procurement authority in integrated delivery networks spanning multiple states.
United States
Academic medical centers in Massachusetts and Pennsylvania anchor demand for EHR-native revenue cycle platforms with complex payer mix management. HHS enforcement of No Surprises Act machine-readable file requirements compels health systems to replace legacy estimation engines. IDNs in Florida and Arizona compress vendor evaluation cycles from eighteen months to under six for compliance-embedded platforms.
Germany
University hospitals in Bavaria and North Rhine-Westphalia pilot FHIR-based billing interoperability under BfArM digital health guidance. The country's national hospital regulator mandates standardized cost accounting for DRG reimbursement accuracy. Berlin-Brandenburg health networks integrate RCM modules with electronic patient records to streamline sickness fund claims.
United Kingdom
NHS Trusts in London and the Southeast accelerate procurement of automated patient financial engagement tools amid Payment by Results tariff complexity. NHS England digitization mandates drive cloud migration of legacy patient accounting systems. Midlands hospital networks consolidate vendor relationships around platforms embedding NHS price transparency requirements.
Japan
Metropolitan hospitals in Tokyo and Osaka invest in claims scrubbing automation to navigate MHLW Diagnosis Procedure Combination revisions. PMDA guidance on software as a medical device intersects with diagnostic coding accuracy requirements. Nagoya medical centers adopt API-driven prior authorization to reduce DPC claim rejection rates.
India
Corporate hospital chains in Maharashtra and Karnataka deploy revenue cycle platforms to manage cashless insurance claim volumes from IRDAI-regulated payers. Ayushman Bharat digital health mission incentives accelerate cloud-based billing adoption. Delhi-NCR health systems integrate RCM with ABHA health IDs for seamless claims processing.
Technology Spending on Revenue Cycle Management Market Competitive Landscape
Top-tier vendors anchor integrated delivery networks, while mid-market specialists serve regional health systems and ambulatory clinics. The vendor base stratifies across three tiers: EHR-native platform providers, standalone RCM pure-plays, and healthcare IT conglomerates with distribution backbones. Dominant competitive moves include cloud migration roadmaps and specialty pharmacy billing convergence.
Within the EHR-native tier, Epic Systems Corporation and Cerner Corporation exemplify platform consolidation strategies that unify clinical documentation with billing workflows. Oracle occupies a position at the infrastructure convergence end, leveraging cloud compute scale for health system IT departments shedding on-premises obligations. Optum represents the payer-provider vertical integration archetype, embedding claims management expertise directly into provider technology stacks.
| Leading Market Players |
|---|
| Optum |
| Epic Systems Corporation |
| R1 RCM |
| Cerner Corporation |
| McKesson Corporation |
| Change Healthcare |
| Allscripts Healthcare Solutions |
| Oracle |
| 3M Health Information Systems |
| Others |
Value Network & Pricing Analysis
CMS price transparency mandates gate qualified supply and premium-tier pricing access for vendors embedding automated patient cost estimation into EHR-native platforms. Hospitals assign data accuracy liability to technology suppliers, compressing margins for standalone RCM modules while rewarding integrated platforms with compliance-embedded architectures.
Pricing Analysis
Short lead-time deployment commands premium pricing for cloud-native RCM platforms with rapid CMS mandate adaptation capabilities. Three-tier pricing structure across premium, standard, and economy levels separates EHR-native integrated solutions from best-of-breed specialty tools and basic claims clearinghouse relationships. Cost compression in the mid-market tier is intensifying because health system IT departments prioritize subscription SaaS models over perpetual licenses. Rural critical access hospitals exhibit highest price sensitivity due to constrained operating margins, while academic medical centers with complex payer mixes demonstrate lowest sensitivity to upfront licensing costs.
Supply Chain Analysis
Dual-sourcing requirements from hospital procurement committees mandate multi-vendor qualification for core billing platforms and denial management services. Technology supply concentrates in the United States, India, and Ireland for software development and cloud infrastructure hosting. Raw material dependencies center on API middleware components, HL7 FHIR interoperability modules, and robotic process automation engines. Single-source vulnerability runs through concentrated clearinghouse networks for claims submission. Distribution runs through direct enterprise sales teams serving integrated delivery networks, with channel partners penetrating independent physician associations and ambulatory surgery centers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Technology spending on revenue cycle management is consolidating around EHR-native platforms as CMS mandate complexity forces standalone vendors toward acquisition or exit. Integration tax burdens and talent scarcity are accelerating this consolidation trajectory.
For Market Incumbents: Acquire cloud-native RCM specialists with automated denial prediction capabilities to fortify platform depth against best-of-breed challengers. Extend backward integration into specialty pharmacy billing adjudication engines to capture infusion center and oncology clinic workflows. Cement hospital network relationships through multi-year managed services contracts that assume full operational responsibility for patient financial engagement.
For New Entrants and Emerging Players: Begin with API-driven prior authorization middleware targeting ambulatory surgery centers and specialty clinics underserved by legacy clearinghouse relationships. Rural health systems in the US Mountain West present the most penetrable geography due to persistent vendor coverage gaps. Deploy rapid-deployment methodologies with 90-day implementation horizons to circumvent lengthy hospital procurement cycles.
For Investors and Strategic Acquirers: Health system consolidation announcements are the leading indicator that procurement authority will centralize around fewer vendor relationships, elevating platform scale requirements. Mid-market RCM pure-plays with specialty pharmacy billing convergence capabilities represent the most attractive acquisition archetype over the long-term horizon. Watch for FDA guidance intersecting diagnostic coding accuracy requirements as the signal for reimbursement integrity platform valuations.
| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Unifies clinical documentation with billing workflows across Epic Systems and Cerner deployments. |
| Cloud Migration Roadmap | Enables health systems to shed on-premises data center obligations under Oracle infrastructure. |
| Specialty Pharmacy Billing Convergence | Addresses medical-pharmacy benefit adjudication gaps in oncology and infusion center settings. |
| Acquisition of Specialist Firm | Captures robotic process automation capabilities for claims scrubbing and denial prediction. |
| Strategic Partnership | Secures real-time eligibility API access under No Surprises Act payer-provider data exchange mandates. |
Research Methodology
CMS Medicare cost reports, hospital procurement databases, and GPO contracts formed the secondary backbone for sizing technology expenditure patterns. Primary interviews with hospital CIOs, revenue cycle directors, health system purchasing committees, and payer contract specialists validated deployment model preferences and vendor selection criteria. Bottom-up and top-down triangulation anchored market size estimates across software solutions, managed services, and implementation services segments.
Bottom-up modeling aggregated facility-level procurement data while top-down analysis cross-referenced aggregate health IT spending disclosures. Segmentation dimensions spanned product type, deployment model, end user, and functionality complexity across the projection horizon. CAGRs were derived from trend extrapolation of CMS mandate compliance spending and cloud infrastructure migration velocity. Forecast inputs incorporated HL7 FHIR adoption curves and robotic process automation penetration rates in business office operations.
Underlying measurement precision varies by segment; cloud-based deployment and software solutions carry tighter precision than hybrid installations and consulting services. Forecasts reflect assumptions around CMS enforcement continuity and payer API standardization timelines. Deviation in No Surprises Act implementation pace or Medicaid program denial appeal complexity would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Healthcare IT
Global Pharmaceutical Quality Management Software Market
Healthcare IT
US Long Term Care Software Market
Healthcare IT
Epharmacy Market
Healthcare IT
Medical IoT Software Market
Healthcare IT
Ambulatory Surgical Centers IT Services Market
Healthcare IT
Veterinary Practice Management Software Market
Healthcare IT
Healthcare Workforce Management Systems Market
Healthcare IT
Commercial Pharmaceutical Analytics Market
Healthcare IT
Hospital Workforce Management Software Market
Healthcare IT
Healthcare Contact Center Solution Market
Healthcare IT
Cognitive Assessment and Training in Healthcare Market
Healthcare IT
Global Patient Intake Software Market
Healthcare IT
Global Back-End Revenue Cycle Management Market
Healthcare IT
Operating Room Management Software Market
Healthcare IT
Healthcare IT Outsourcing Market
Healthcare IT
Healthcare IT Market