
 Europe Kidney Cancer Diagnostics Market | 2026-2036
Europe Kidney Cancer Diagnostics Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Kidney Cancer Diagnostics Market Foresight
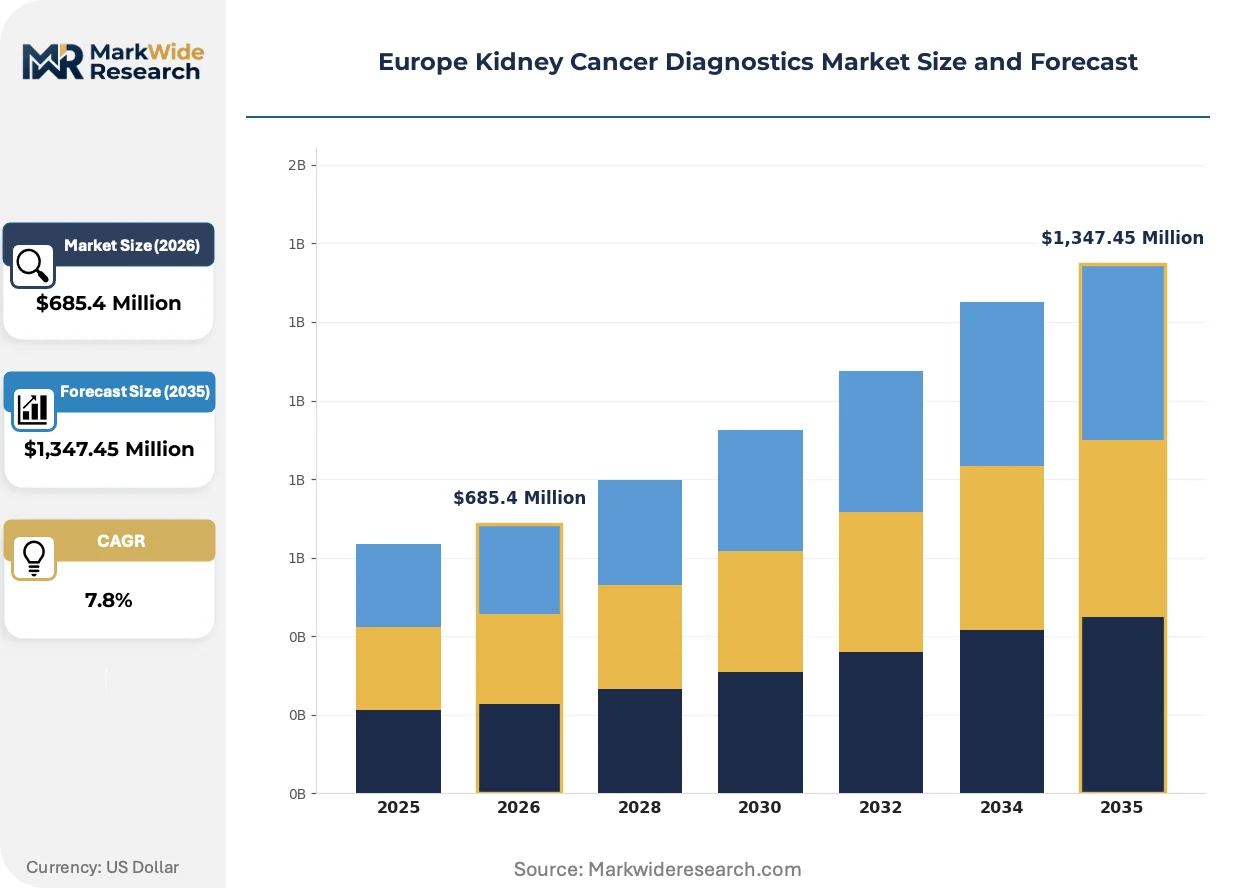
The Europe kidney cancer diagnostics market is pivoting on a widening split between premium molecular profiling platforms and commodity imaging services. Siemens Healthineers leverages its installed base of CT and MRI systems to dominate hardware-intensive hospital workflows. Roche Holding AG sustains leadership in companion diagnostics through deep assay menus for renal cell carcinoma biomarker detection.
Europe kidney cancer diagnostics encompasses imaging modalities, biomarker assays, scanner hardware, and analytical software used to detect, stage, and monitor renal malignancies. CT imaging remains the structural workhorse for initial tumor characterization, while PET applications for metastatic surveillance represent the fastest-growing technology segment. Biomarker testing commands concentrated margin pools as laboratories seek CE-marked liquid biopsy alternatives to tissue-based protocols.
The EU In Vitro Diagnostic Regulation and EMA companion diagnostic guidelines shape product registration timelines and clinical evidence requirements across member states. Germany's national cancer plan and France's HAS evaluation framework further stratify reimbursement access for novel diagnostic platforms. Stakeholders must monitor MDR transition deadlines and evolving HTA criteria to secure sustainable market access positions.
Market Dynamics
The Europe kidney cancer diagnostics market pivots on the MDR transition deadline forcing CE-marked companion diagnostic recertification. Siemens Healthineers and Roche Holding AG face compressed timelines to validate renal cell carcinoma assay menus under stricter clinical evidence requirements, reshaping competitive positioning between hardware incumbents and molecular testing specialists.
Growth Catalysts
- EU MDR compliance mandates:The In Vitro Diagnostic Regulation accelerates hospital laboratory investments in CE-marked liquid biopsy platforms for renal cell carcinoma staging. Academic medical centers in Germany anchor reference workflows driving standardization.
- Molecular profiling expansion:PET imaging applications for metastatic surveillance represent the fastest-growing technology segment as hospital networks prioritize whole-body staging protocols over repeat CT scanning.
- France HAS evaluation framework:The national health authority's HTA criteria create transparent reimbursement pathways for novel diagnostic platforms, reducing market access friction for biomarker assay developers.
Market Restraints
- MDR transition cost concentration:Small-to-mid diagnostic developers face disproportionate compliance burdens from EMA companion diagnostic guideline updates, consolidating innovation capacity toward scaled manufacturers.
- Tissue biopsy protocol stickiness:Established histopathology workflows in Southern European hospital networks resist displacement by liquid biopsy alternatives despite inferior patient throughput.
- Scanner hardware depreciation cycles:Extended replacement timelines for CT and MRI systems in public hospital procurement compress near-term platform upgrade demand across Spain and Italy.
Strategic Opportunities
- Underpenetrated Polish and Romanian markets:Limited molecular profiling infrastructure in Eastern European oncology centers creates first-mover positioning for CE-marked assay menu expansion.
- AI-augmented imaging analysis:Machine learning algorithms for renal tumor characterization are converging with radiology workflow software, enabling automated staging reports that reduce specialist interpretation bottlenecks.
- EU Green Deal procurement incentives:Sustainability-linked tender criteria favor energy-efficient diagnostic hardware, rewarding manufacturers with modular platform architectures and reduced contrast agent waste profiles.
Industry Challenges
- MDR technical documentation expertise scarcity:Limited pool of regulatory affairs specialists familiar with EMA companion diagnostic evidentiary standards delays product registration timelines for mid-cap developers.
- Multi-modal data integration complexity:Hospital IT systems struggle to unify imaging DICOM archives with biomarker laboratory information management systems, fragmenting patient records across departmental silos.
- Reimbursement code alignment delays:National health technology assessment bodies in Belgium and the Netherlands apply inconsistent valuation methodologies for combined imaging-biomarker diagnostic pathways.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Kidney Cancer Diagnostics Market |
| Market Size in 2026 | $685.4 Million |
| Market Size in 2035 | $1,347.45 Million |
| CAGR (2026 – 2036) | 7.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Imaging, Biomarkers, Scanners, Software End User: Hospitals, Diagnostic Labs, Research Institutes, Clinics Technology: CT, MRI, Ultrasound, PET Application: Screening, Early Detection, Monitoring, Prognosis |
| Companies Covered | Roche Holding AG, QIAGEN NV, Siemens Healthineers AG, Abbott Laboratories, Illumina Inc, Koninklijke Philips NV, Thermo Fisher Scientific Inc, Hologic Inc, GE HealthCare Technologies Inc, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Kidney Cancer Diagnostics Market Shifts & Advancements
Artificial intelligence and liquid biopsy technologies are actively compressing diagnostic timelines for renal cell carcinoma staging. Three interconnected developments are reshaping how European hospitals detect, characterize, and monitor kidney malignancies.
Multiparametric MRI sequences with radiomics extraction are converging with cloud-based analysis platforms to quantify tumor heterogeneity metrics previously requiring invasive sampling. Leading German academic medical centers deploy these protocols for active surveillance decisions in small renal masses, compressing the diagnostic pathway from imaging to treatment planning. The technology is converging with established CT staging workflows, enabling hybrid imaging strategies that reduce radiation exposure in younger patient cohorts.
The EU MDR's 2026 full enforcement deadline is compressing product registration timelines for novel companion diagnostics. EMA evidentiary requirements now mandate prospective clinical validation studies for renal cell carcinoma biomarker assays, extending development cycles by 18-24 months. French and German notified bodies are prioritizing submissions from manufacturers with existing ISO 13485 quality management certifications, creating tiered access speeds based on prior regulatory maturity.
Hospital procurement committees are unbundling imaging hardware from long-term service contracts, shifting toward performance-based maintenance agreements with uptime guarantees. Nordic hospital networks lead this transition, negotiating separate vendor relationships for equipment, software licenses, and technical support. The model disrupts traditional bundled pricing from Siemens Healthineers and GE Healthcare, forcing componentized cost transparency in tender processes across Denmark, Sweden, and Norway.
Europe Kidney Cancer Diagnostics Market Segmentation
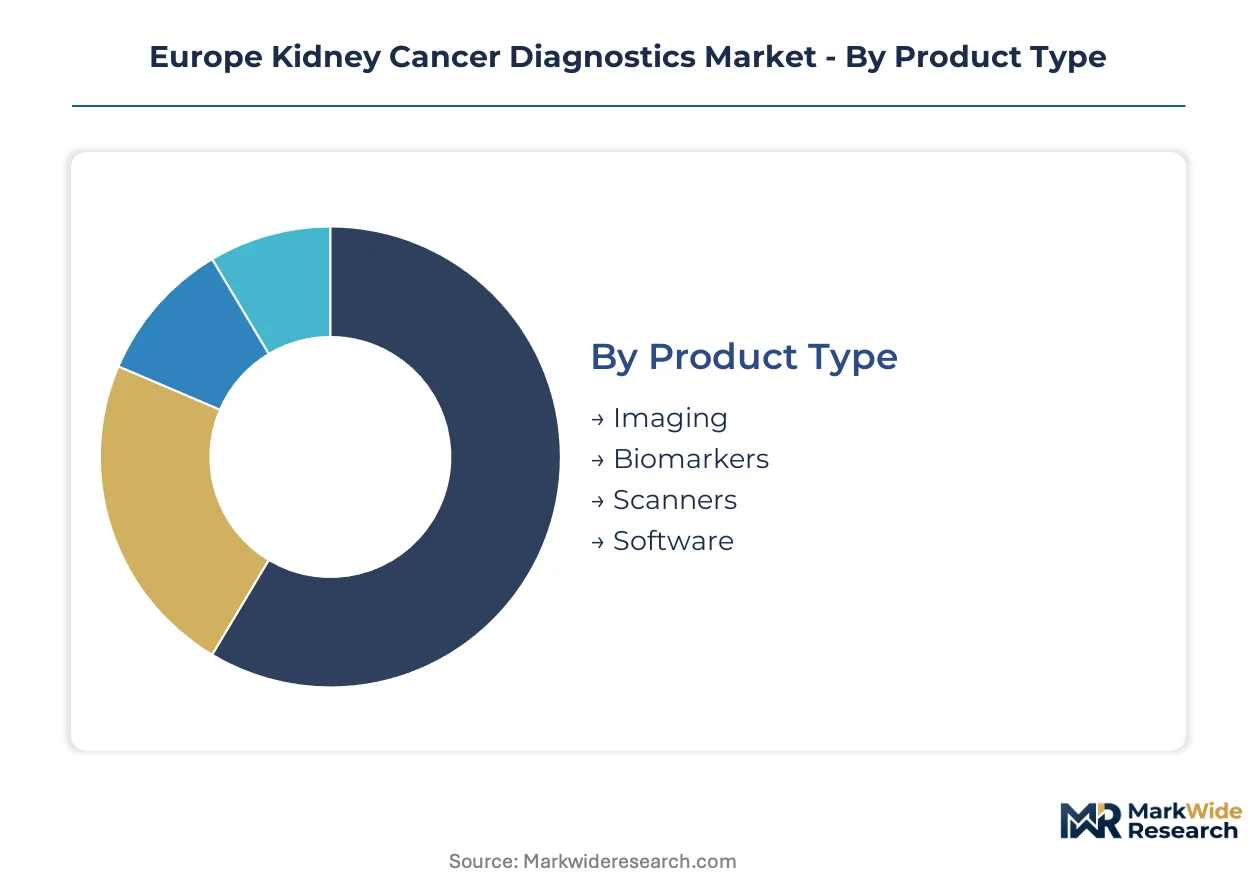
Diagnostic workflows for renal cell carcinoma fragment across hardware platforms, molecular assays, and analytical software, each commanding distinct procurement channels and reimbursement codes. Hospital networks in Germany and France prioritize integrated imaging-biomarker pathways, while Eastern European markets remain hardware-dependent with limited molecular infrastructure.
Product Type:
Supply concentration in molecular diagnostics tilts toward Roche and Siemens Healthineers, while imaging hardware consolidates around established radiology vendors with deep installed bases.
- Imaging:CT and MRI protocols dominate initial tumor characterization workflows, with German academic medical centers anchoring reference standards for multiparametric sequences. Demand concentrates in hospital networks seeking CE-marked platforms for MDR compliance, compressing procurement timelines for replacement systems.
- Biomarkers:Liquid biopsy assays for renal cell carcinoma staging command concentrated margin pools as laboratories pursue non-invasive alternatives to tissue protocols. France's HAS evaluation framework accelerates reimbursement access for novel companion diagnostics, drawing assay developers toward Paris and Lyon hospital clusters.
- Scanners:Hardware procurement cycles extend across Southern European public health systems, with Spain and Italy deferring platform upgrades amid budget constraints.
- Software:AI-augmented radiology workflow tools enable automated tumor segmentation, reducing specialist interpretation bottlenecks in high-volume Nordic centers.
Imaging absorbs the bulk of installed capacity; biomarkers are expanding most quickly.
End User:
Cost tier stratification separates premium academic workflows from commodity diagnostics in peripheral clinics, with reimbursement codes determining access speed.
- Hospitals:Comprehensive cancer centers in Germany and France integrate imaging, biopsy, and molecular profiling under single institutional umbrellas, enabling same-day diagnostic pathways. Siemens Healthineers leverages long-term service contracts to defend hardware positions in these anchor accounts.
- Diagnostic Labs:Independent reference laboratories in the Netherlands and Belgium specialize in biomarker assay processing, capturing overflow from hospital capacity constraints. EMA companion diagnostic guidelines shape their CE-marked menu investments.
- Research Institutes:Academic consortia drive validation studies for novel radiomics signatures, though commercial translation timelines extend 18-24 months under tightened MDR evidence requirements.
- Clinics:Outpatient urology practices in Poland and Romania rely on referral networks for complex staging, limiting direct platform investment.
Hospitals retain the dominant share of capital deployment; diagnostic labs are gaining share fastest.
Technology:
Application urgency stratifies technology selection, with metastatic surveillance driving premium PET adoption while initial staging remains CT-dependent.
- CT:Non-contrast and multiphase protocols remain the structural workhorse for initial renal mass characterization, with radiation dose optimization priorities shaping hardware replacement cycles in Nordic networks.
- MRI:Multiparametric sequences with radiomics extraction quantify tumor heterogeneity for active surveillance decisions, converging with cloud-based analysis platforms at leading German centers.
- Ultrasound:Point-of-care applications concentrate in screening workflows for high-risk populations, though sensitivity limitations restrict definitive staging use.
- PET:Whole-body metabolic surveillance for metastatic renal cell carcinoma represents the steepest expansion trajectory, as hospital networks prioritize single-session staging over repeat CT scanning.
CT absorbs the bulk of procedure volume; PET is climbing the fastest.
Application:
Maturity gradients separate established screening protocols from emerging prognostic applications, with reimbursement codes lagging technology capability.
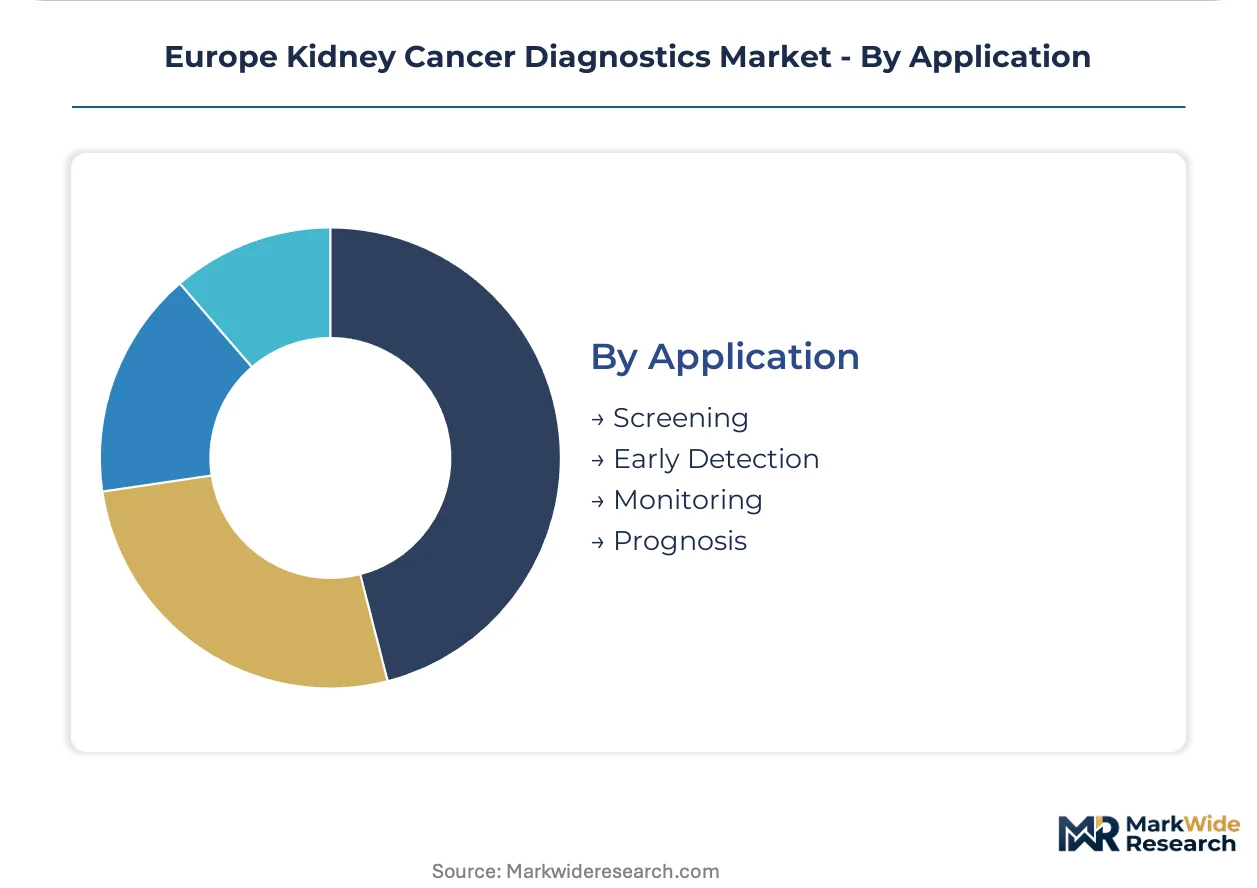
- Screening:Population-level programs remain limited, with incidental detection during abdominal imaging for unrelated indications driving the majority of early-stage diagnoses.
- Early Detection:Small renal mass protocols deploy multiparametric MRI for characterization, enabling surveillance-versus-surgery decisions without immediate biopsy.
- Monitoring:Post-treatment surveillance workflows combine imaging intervals with liquid biopsy trending, though data integration across hospital IT systems fragments patient records.
- Prognosis:Molecular risk stratification assays for adjuvant therapy selection command premium pricing, with EMA evidentiary requirements extending validation timelines for novel signatures.
Monitoring absorbs the bulk of recurring revenue; prognosis is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Munich anchors Europe's kidney cancer diagnostics activity through Siemens Healthineers' headquarters and the University Hospital's molecular profiling consortium. German academic medical centers set reference standards that radiate across neighboring health systems.
Germany
Academic medical centers in Berlin and Heidelberg drive molecular profiling standardization for renal cell carcinoma staging. The national cancer plan channels federal reimbursement toward integrated imaging-biomarker pathways. Bavaria's hospital networks concentrate CE-marked companion diagnostic validation studies under tightened MDR timelines.
France
Paris and Lyon hospital clusters attract assay developers seeking HAS evaluation framework clearance for novel biomarker platforms. The national health authority's transparent HTA criteria reduce market access friction compared to fragmented Southern European systems. Île-de-France's comprehensive cancer centers integrate same-day diagnostic workflows.
United Kingdom
London's NHS trusts pilot AI-augmented radiology tools for renal tumor characterization amid workforce constraints. MHRA post-Brexit regulatory divergence creates parallel compliance tracks for CE-marked and UKCA-marked diagnostics. Cambridge research consortia validate radiomics signatures for active surveillance protocols.
Netherlands
Amsterdam and Rotterdam house independent reference laboratories specializing in biomarker assay overflow from hospital capacity constraints. Dutch health technology assessment bodies apply inconsistent valuation methodologies for combined imaging-biomarker pathways. The Randstad region concentrates diagnostic infrastructure procurement committees.
Poland
Warsaw and Krakow oncology centers rely on referral networks for complex staging due to limited molecular profiling infrastructure. EU structural funds channel investment toward CE-marked platform adoption in Eastern European markets. The underpenetrated market creates first-mover positioning for assay menu expansion.
Europe Kidney Cancer Diagnostics Market Competitive Landscape
Premium-margin players sit above commodity-margin players across the hardware-software divide in European kidney cancer diagnostics. Siemens Healthineers and Roche Holding AG anchor the upper tier through installed base depth and companion diagnostic assay menus. Mid-scale molecular specialists and regional imaging distributors populate the fragmented middle. Consolidation pressures intensify as MDR compliance costs favor scaled manufacturers with existing ISO 13485 certifications.
Among diversified health technology conglomerates, Siemens Healthineers AG and Roche Holding AG exemplify the integrated platform archetype spanning imaging hardware and molecular testing. Thermo Fisher Scientific Inc occupies a position within the laboratory solutions tier. These three anchors represent distinct strategic postures: hardware-centric service bundling, companion diagnostic regulatory depth, and research-to-clinical workflow integration respectively.
| Leading Market Players |
|---|
| Roche Holding AG |
| QIAGEN NV |
| Siemens Healthineers AG |
| Abbott Laboratories |
| Illumina Inc |
| Koninklijke Philips NV |
| Thermo Fisher Scientific Inc |
| Hologic Inc |
| GE HealthCare Technologies Inc |
| Others |
Supply & Pricing Matrix
Private-equity-rolled-up molecular diagnostics specialists have consolidated assay menu portfolios across Germany and France, tightening pricing discipline through centralized procurement negotiations with hospital networks while compressing distributor margins in Southern European markets.
Pricing Analysis
Value-based pricing anchored to patient throughput outcomes dominates CE-marked companion diagnostic contracts, with Siemens Healthineers and Roche Holding AG commanding premium positioning through ISO 13485 certification tiers and long-term service bundling. Price differentiation separates MDR-validated assay menus from legacy platforms facing recertification deadlines. Pricing pressure stems from compressed hospital procurement timelines in Spain and Italy, where budget constraints extend hardware depreciation cycles. Academic medical centers in Germany exhibit lowest price sensitivity due to federal reimbursement guarantees, while Polish and Romanian oncology centers prioritize per-test economy tiers.
Supply Chain Analysis
Regional distribution centers in Germany, the Netherlands, and Belgium anchor hub-and-spoke patterns for CE-marked reagents and consumables, with Siemens Healthineers operating captive logistics networks for scanner hardware. Component dependencies center on specialized contrast agents from Switzerland, rare-earth magnets for MRI systems sourced from China, and semiconductor chips for PET detector arrays manufactured in Taiwan. Single-source vulnerability concentrates in isotope supply chains for radiopharmaceutical production. Distribution runs through GPO-negotiated contracts with hospital purchasing committees, supplemented by direct-to-laboratory channels for reference biomarker processing.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Supply constraints in MDR-notified body capacity prop pricing power for manufacturers with existing ISO 13485 certifications, as recertification backlogs extend validation timelines for mid-scale competitors.
For Market Incumbents: Extend service contract penetration in German academic medical centers to defend installed base positions against emerging AI-augmented radiology entrants. Deepen backward integration into cloud-based analysis platforms for radiomics extraction, capturing recurring software revenue streams. Prioritize HAS evaluation framework submissions in France to secure reimbursement codes ahead of competitor assay launches. For New Entrants and Emerging Players: EU MDR in Europe opens a window for CE-marked liquid biopsy platforms targeting Poland and Romania, where molecular profiling infrastructure remains underdeveloped relative to Western European benchmarks. Focus initial commercialization on independent reference laboratories in the Netherlands and Belgium, capturing overflow capacity from hospital network constraints. Pursue tender participation for EU structural fund allocations in Eastern European oncology center upgrades. For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-scale molecular diagnostics developers with pending MDR submissions but constrained regulatory affairs capacity in Germany. Long-term viability hinges on consolidation into scaled manufacturers with notified body relationships and established hospital GPO contracts. Monitor EMA companion diagnostic guideline updates as inflection signals for valuation compression among pre-revenue assay developers.| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | MDR recertification timelines determine competitive access speed across German hospital networks. |
| Hospital System Partnership | Long-term service agreements with Siemens Healthineers defend imaging hardware positions in France. |
| Software Companion Development | AI-augmented radiology tools reduce specialist interpretation bottlenecks in Nordic centers. |
| Reimbursement Strategy | HAS evaluation framework clearance unlocks premium pricing for novel biomarker platforms in Paris. |
| Regulatory Approval Pathway | EMA companion diagnostic guidelines shape evidentiary requirements for renal cell carcinoma assays. |
Research Methodology
EMA submission databases, hospital procurement records, and CE marking registries formed the secondary backbone, cross-referenced with primary interviews involving regulatory affairs specialists at notified bodies, biomedical engineers at German academic medical centers, GPO contracts managers, and laboratory directors at French reference networks. Bottom-up triangulation across assay menu volumes and top-down validation against imaging procedure databases ensured consistency.
Historical trendline analysis of CT and PET installation rates, biomarker test volumes, and companion diagnostic reimbursement decisions established baseline growth patterns across the projection horizon. Segmentation modeling incorporated product type, end user tier, technology application, and national regulatory cluster dimensions. CAGRs derived from weighted average of procedure volume trajectories and pricing evolution assumptions, with specific inputs from MDR transition deadline impacts and EU Green Deal procurement criteria adoption curves.
The model assumes a particular technology adoption path; alternative pathways for AI-augmented radiomics would alter the outlook if regulatory validation timelines compress unexpectedly. Forecasts reflect documented assumptions regarding MDR enforcement consistency and HAS evaluation framework stability. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Diagnostics
Adenovirus Diagnostic Testing Market
Diagnostics
Hypopituitarism Diagnostics Market
Diagnostics
Global Coagulation Analyzers Market
Diagnostics
Global Inflammatory Bowel Disease (IBD) Diagnostic Market
Diagnostics
North America Antinuclear Antibody Test Market
Diagnostics
Europe Antinuclear Antibody Test Market
Diagnostics
Antimicrobial Resistance Diagnostics Market
Diagnostics
Self-Administered HPV Test Market
Diagnostics
Pancreatic Cyst Diagnostics Market
Diagnostics
Diagnostic Exosome Biomarkers Market
Diagnostics
Fungal Antigens Market
Diagnostics
Shrimps Disease Diagnostics Market
Diagnostics
Glaucoma Diagnostics Market
Diagnostics
US Tissue Diagnostics Market
Diagnostics
Acute Ischemic Stroke Diagnosis Market
Diagnostics
Global Transplant Diagnostics Market