
 Psychosis Diagnostics Market | 2026-2036
Psychosis Diagnostics Market Size, Share, and Industry Trends Forecast 2026-2036
Psychosis Diagnostics Market Analytics
North American laboratory infrastructure is reshaping competitive dynamics in psychosis diagnostics. Quest Diagnostics leverages its national specimen collection network to sustain volume leadership in routine metabolic monitoring for antipsychotic therapy. LabCorp competes through integrated behavioral health contracts with regional hospital systems. Genomind anchors pharmacogenomic positioning with clinician-facing decision support tools.
Psychosis diagnostics encompasses biological and behavioral assessment modalities designed to detect, subtype, and monitor schizophrenia spectrum and related psychotic disorders through measurable physiological or psychological indicators. Neuroimaging modalities including structural MRI and functional PET quantify dopaminergic pathway anomalies, while biomarker panels measure inflammatory cytokines and neurotransmitter metabolites to support differential diagnosis. Genetic testing segments show the steepest growth trajectory as polygenic risk scores gain clinical validation, though psychological assessments retain the largest installed base due to reimbursement familiarity. Telemedicine-enabled remote cognitive assessment is displacing traditional in-person screening in outpatient facilities, creating new margin pools for platform developers.
FDA breakthrough device designation and CLIA laboratory certification requirements shape product development timelines and commercial access for US market participants. The EU AI Act and MDR framework impose additional validation burdens on algorithmic diagnostic tools seeking European market entry. Stakeholders must monitor evolving FDA guidance on AI-enabled diagnostic software and CMS reimbursement determinations for digital biomarkers to anticipate revenue recognition timing and capital allocation priorities.
Market Dynamics
Biomarker validation pipelines and FDA breakthrough device designations are compressing commercialization timelines while fragmenting competitive advantage across molecular diagnostic platforms and neuroimaging modalities.
Growth Catalysts
- Pharmacogenomic reimbursement expansion:CMS coverage determinations for polygenic risk scoring in antipsychotic selection are pulling test volumes into centralized laboratory networks.
- Integrated care network consolidation:Hospital system mergers in the United States are standardizing biomarker-based screening protocols across service lines.
- Telemedicine infrastructure maturation:Remote cognitive assessment platforms are capturing outpatient volumes previously served by in-person psychological evaluation.
Market Restraints
- CLIA laboratory certification complexity:High-complexity testing requirements create capital barriers for novel platform developers seeking US market entry.
- EU AI Act validation burdens:Algorithmic diagnostic tools face extended conformity assessment timelines under the MDR framework before European commercialization.
- Reimbursement code fragmentation:Inconsistent CPT coding for digital biomarkers across US commercial payers compresses realized revenue per test.
Strategic Opportunities
- Underpenetrated rural networks:Federally qualified health centers in the United States lack access to centralized laboratory infrastructure for metabolic monitoring.
- Inflammatory cytokine panel expansion:C-reactive protein and interleukin-6 biomarkers are gaining traction for psychosis subtyping beyond traditional neurotransmitter metabolites.
- AI-enabled predictive triage:Machine learning risk stratification tools are qualifying for accelerated FDA review under breakthrough device pathways.
Industry Challenges
- Neuroimaging specialist scarcity:Radiologist training pipelines for functional PET interpretation lag deployment of new scanner installations.
- Multi-modal data integration complexity:Electronic health record systems struggle to reconcile structured biomarker outputs with unstructured clinical notes.
- Biobank specimen quality variance:Pre-analytical handling protocols for blood-based biomarkers remain inconsistent across collection sites.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Psychosis Diagnostics Market |
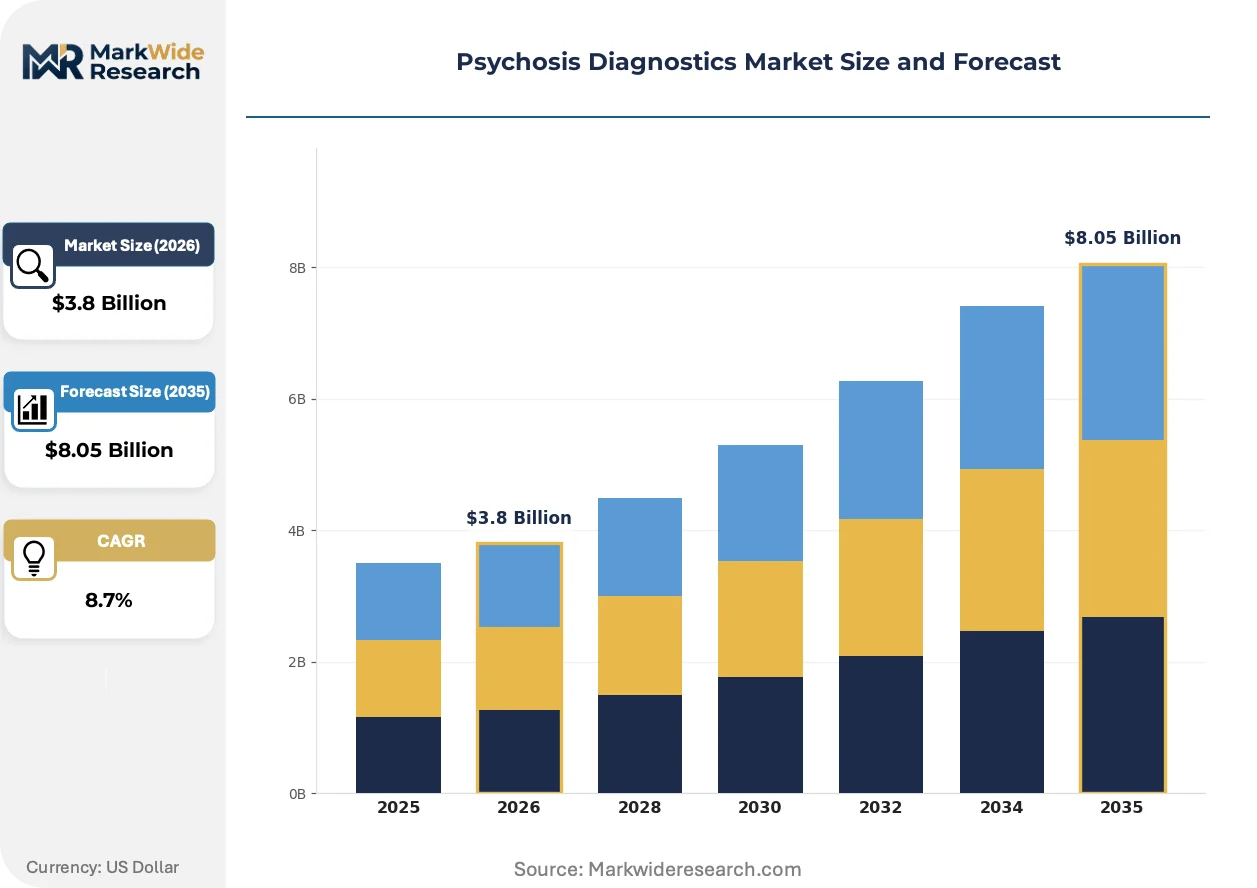
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.05 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Blood Tests, Imaging Techniques, Psychological Assessments, Genetic Testing Technology: Neuroimaging, Biomarkers, Telemedicine, Mobile Health Solutions Application: Clinical Research, Hospital Settings, Outpatient Facilities, Emergency Departments End User: Psychiatrists, Neurologists, General Practitioners, Research Institutions |
| Companies Covered | Quest Diagnostics, LabCorp, Genomind, Myriad Genetics, GeneDx, Polaris Genomics, CNSDose, MedGenome, Invitae Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Psychosis Diagnostics Market Evolving Landscape
Diagnostic modality boundaries are dissolving as molecular, imaging, and digital assessment tools converge into unified clinical decision workflows.
Polygenic risk scoring is migrating from research-grade applications into commercial pharmacogenomic panels. Psychiatric treatment centers in the United States are adopting these tools for antipsychotic selection protocols. The technology is compressing trial-and-error prescribing cycles while creating new revenue pools for laboratories with bioinformatics infrastructure.
FDA guidance on AI-enabled diagnostic software is forcing algorithm developers to establish predetermined change control plans. This requirement extends validation timelines but reduces post-market submission burdens for iterative model updates. Cloud-based diagnostic platforms serving US hospital networks are restructuring engineering teams to accommodate this documentation load.
Remote cognitive assessment is capturing outpatient screening volumes through telemedicine-enabled platforms. Community mental health centers are replacing in-person neuropsychological batteries with tablet-based testing protocols. This shift concentrates most visibly in the United States where integrated care networks seek to extend service reach without proportional staff expansion.
Psychosis Diagnostics Market Segmentation
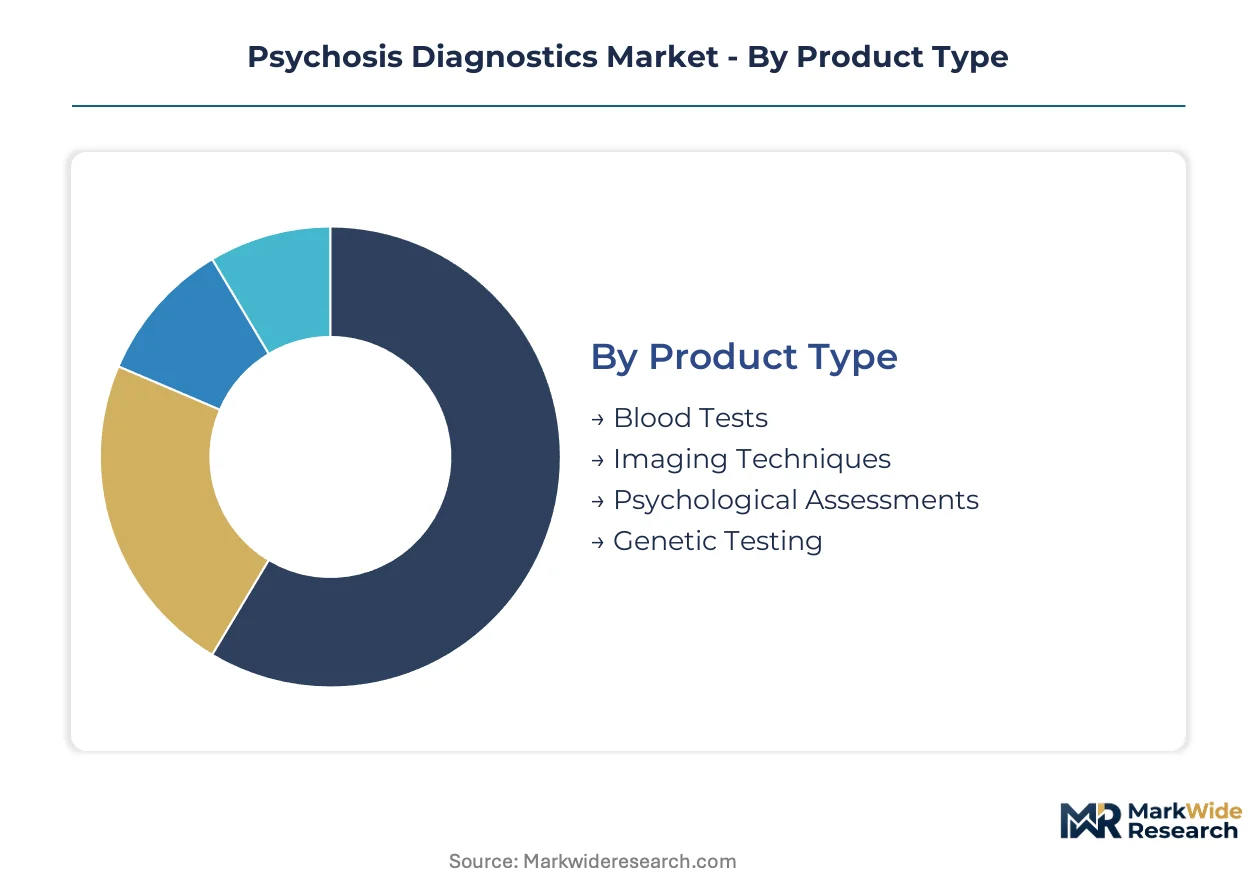
Segmentation in psychosis diagnostics reveals how reimbursement pathways, technical complexity, and care delivery settings fragment revenue pools across molecular, imaging, and digital modalities. Understanding these divides clarifies where capital allocation concentrates and where platform developers face structural barriers to scale.
Product Type:
After-sales service intensity varies sharply across product categories, with imaging systems demanding multi-year maintenance contracts and consumable-based tests requiring continuous reagent supply logistics.
- Imaging Techniques:Structural MRI and functional PET systems quantify dopaminergic pathway anomalies through capital-intensive hardware requiring specialized radiologist interpretation. Hospital systems in the United States anchor procurement volumes as integrated care networks consolidate neuroimaging infrastructure under centralized service lines.
- Genetic Testing:Polygenic risk scoring and pharmacogenomic panels analyze antipsychotic metabolism variants through CLIA-certified laboratory workflows. CMS coverage determinations for psychiatric pharmacogenomics are pulling test volumes into Quest Diagnostics and LabCorp processing networks.
- Blood Tests:Inflammatory cytokine and neurotransmitter metabolite panels support differential diagnosis through standardized laboratory protocols.
- Psychological Assessments:Structured clinical interviews and cognitive batteries retain the largest installed base due to established CPT reimbursement codes.
Psychological Assessments holds the largest share; momentum sits with Genetic Testing.
Technology:
Cost tier stratification separates capital-intensive neuroimaging hardware from software-enabled telemedicine platforms with minimal marginal delivery costs.
- Biomarkers:Blood-based inflammatory panels and neurotransmitter metabolites enable quantitative psychosis subtyping through centralized laboratory infrastructure. C-reactive protein and interleukin-6 measurements are gaining clinical traction beyond traditional dopaminergic markers in United States academic medical centers.
- Telemedicine:Remote cognitive assessment platforms displace in-person neuropsychological batteries through tablet-based testing protocols. Community mental health centers in rural United States markets adopt these tools to extend service reach without proportional psychiatrist staffing expansion.
- Neuroimaging:Structural and functional brain mapping modalities require radiologist interpretation pipelines that lag scanner deployment timelines.
- Mobile Health Solutions:Smartphone-based digital phenotyping and passive monitoring applications capture real-world behavioral data streams.
Neuroimaging commands premium pricing; Telemedicine is climbing the fastest.
Application:
Volume concentration patterns diverge between centralized hospital laboratory networks and distributed outpatient screening environments.
- Hospital Settings:Inpatient psychiatric units and emergency departments deploy multi-modal diagnostic protocols combining biomarker panels with structured clinical assessment. United States hospital system mergers are standardizing screening workflows across acquired service lines, concentrating procurement authority at regional integrated care networks.
- Clinical Research:Academic medical centers and pharmaceutical sponsors utilize advanced neuroimaging and genetic profiling for trial enrichment and mechanistic understanding. NIH-funded consortia in the United States drive demand for standardized biomarker collection protocols across multi-site schizophrenia studies.
- Outpatient Facilities:Community mental health centers and private psychiatric practices deliver longitudinal monitoring through lower-complexity testing modalities.
- Emergency Departments:Acute care settings require rapid triage tools for psychosis differential diagnosis against substance-induced or medical etiologies.
Hospital Settings holds the largest share; Clinical Research shows the steepest expansion trajectory.
End User:
Customer type determines pricing power and purchasing process complexity, with institutional procurement contrasting against individual clinician ordering patterns.
- Psychiatrists:Specialist physicians drive adoption of pharmacogenomic testing and structured assessment tools for antipsychotic selection and treatment monitoring. United States psychiatric group practices with EHR-integrated decision support are standardizing biomarker-informed prescribing protocols.
- Research Institutions:Academic medical centers and contract research organizations purchase research-grade neuroimaging and multi-omic profiling for mechanistic studies and clinical trials. NIMH-funded centers in the United States maintain dedicated biobanking infrastructure for longitudinal specimen collection.
- Neurologists:Specialists in neurodegenerative and movement disorders utilize psychosis diagnostics for differential diagnosis in atypical presentations.
- General Practitioners:Primary care gatekeepers require simplified screening tools for initial psychosis detection and referral decisions.
Psychiatrists holds the largest share; Research Institutions is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Diagnostic platform developers concentrate laboratory infrastructure and regulatory filing resources in markets with established reimbursement pathways for biomarker-based psychosis screening. The United States anchors commercialization timelines through FDA breakthrough device designations and CMS coverage determinations.
United States
Integrated care network consolidation drives standardized biomarker protocols across hospital systems. FDA breakthrough device designation accelerates commercialization timelines for novel diagnostic platforms. Boston and San Francisco biotech clusters host pharmacogenomic developers refining polygenic risk scoring for antipsychotic selection.
Germany
Academic medical centers in Heidelberg and Munich advance neuroimaging validation for dopaminergic pathway quantification. EMA centralized procedures and MDR conformity assessments shape European market entry timelines for algorithmic diagnostic tools. Baden-Württemberg's precision medicine initiatives support multi-modal diagnostic research consortia.
United Kingdom
NHS England's mental health transformation program creates procurement opportunities for remote cognitive assessment platforms. MHRA regulatory science collaborations with FDA streamline parallel submission pathways for AI-enabled diagnostics. London's digital health cluster attracts telemedicine platform developers targeting outpatient screening volumes.
Japan
PMDA's Sakigake designation system accelerates review timelines for novel biomarker panels in psychiatric applications. Tokyo and Osaka academic hospitals lead adoption of pharmacogenomic testing for clozapine metabolism monitoring. METI's healthcare innovation fund supports domestic development of blood-based psychosis subtyping assays.
Australia
TGA's priority review pathway compresses approval timelines for diagnostic software with breakthrough potential. Melbourne and Sydney research institutes drive inflammatory cytokine panel validation for first-episode psychosis prediction. Medical Research Future Fund grants support telemedicine infrastructure for rural mental health service extension.
Psychosis Diagnostics Market Competitive Landscape
National laboratory networks and specialized pharmacogenomic developers split the market between volume-scale metabolic monitoring and high-margin genetic interpretation services. The competitive structure tiers across three archetypes: integrated diagnostic conglomerates with specimen collection infrastructure, bioinformatics-focused pharmacogenomic specialists, and emerging AI-enabled platform developers. Consolidation pressures intensify as hospital system procurement centralization favors vendors with comprehensive test menus and EHR integration capabilities.
Within the integrated laboratory tier, Quest Diagnostics and LabCorp exemplify scale-driven positioning through national specimen processing networks and established commercial payer contracts. Genomind anchors the pharmacogenomic specialist archetype with clinician-facing decision support tools. These three companies represent divergent strategic bets on whether psychosis diagnostics revenue pools concentrate in centralized laboratory infrastructure or point-of-care genetic interpretation services.
| Leading Market Players |
|---|
| Quest Diagnostics |
| LabCorp |
| Genomind |
| Myriad Genetics |
| GeneDx |
| Polaris Genomics |
| CNSDose |
| MedGenome |
| Invitae Corporation |
| Others |
Value Network & Pricing Analysis
Overcapacity in United States CLIA-certified laboratory infrastructure is compressing per-test margins while forcing suppliers toward high-complexity genetic interpretation services where pricing power remains intact. This utilization dynamic shapes both procurement consolidation among hospital networks and the geographic footprint of new platform development.
Pricing Analysis
FDA breakthrough device designation dictates the pricing tier structure across psychosis diagnostics, with designated platforms commanding premium reimbursement during exclusivity windows before CMS fee schedule compression. Three-tier pricing structure across premium pharmacogenomic panels, standard metabolic monitoring, and economy-scale psychological assessments reflects certification intensity and bioinformatics overhead. Cost compression in routine blood-based biomarkers is intensifying because Quest Diagnostics and LabCorp volume contracts standardize pricing across integrated care networks. Federally qualified health centers exhibit highest price sensitivity due to capped federal reimbursement, while academic medical centers show lowest sensitivity given research funding cross-subsidies.
Supply Chain Analysis
Extended payment terms from hospital procurement departments are forcing diagnostic developers toward supply-chain finance facilities to bridge reagent inventory cycles. Manufacturing concentration in the United States, Germany, and China shapes component availability for imaging hardware and assay kits. Reagent supply draws from specialized chemical producers in Switzerland and Japan for neurotransmitter metabolite standards. Single-source vulnerability in CRISPR guide RNA synthesis for polygenic risk scoring creates procurement risk for pharmacogenomic panel developers. Distribution runs through national laboratory networks for centralized processing, with direct-to-clinic logistics emerging for point-of-care genetic testing platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Psychosis diagnostics sits in early-cycle expansion as FDA breakthrough designations validate novel biomarker platforms and pull reimbursement into mainstream psychiatric workflows. Pharmacogenomic penetration in antipsychotic selection remains below twenty percent, creating substantial runway for platform developers with bioinformatics infrastructure.
For Market Incumbents: Entrench position through EHR-integrated decision support tools that lock in psychiatrist prescribing workflows and raise switching costs for competing laboratories. Defend against emerging AI-enabled triage platforms by accelerating CLIA certification for algorithmic diagnostic outputs in emergency department settings. Prioritize backward integration into biobanking infrastructure to control pre-analytical specimen quality variance that degrades test reproducibility.
For New Entrants and Emerging Players: Establish a beachhead in rural United States mental health networks where federally qualified health centers lack centralized laboratory access for metabolic monitoring. Target inflammatory cytokine panel expansion for first-episode psychosis subtyping, a segment with minimal incumbent concentration and emerging clinical validation. Pursue telemedicine-enabled remote cognitive assessment as the go-to-market angle, leveraging tablet-based deployment to bypass capital-intensive imaging hardware requirements.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across telemedicine diagnostic platforms as cloud infrastructure commodifies and marginal delivery costs approach zero. The five-to-ten year viability window favors bioinformatics specialists with proprietary polygenic risk scoring algorithms over capital-heavy imaging hardware developers. Acquisition target archetype: pharmacogenomic developers with CMS coverage determination momentum and clinician-facing software interfaces. Watch FDA guidance on AI-enabled diagnostic software as the inflection signal for algorithmic platform valuations.
| Strategic Initiative | Industry Significance |
|---|---|
| FDA Breakthrough Device Pathway | Accelerates commercialization timelines for novel biomarker platforms seeking CMS reimbursement. |
| CLIA Laboratory Certification | Creates capital barriers that protect incumbent processing networks from low-cost entrants. |
| Pharmacogenomic Reimbursement Strategy | CMS coverage determinations for polygenic risk scoring concentrate volume in national laboratories. |
| Hospital System Partnership | Integrated care network consolidation standardizes screening protocols across acquired service lines. |
| Software Companion Development | EHR-integrated decision support tools lock in psychiatrist prescribing workflows and raise switching costs. |
Research Methodology
Operator-level perspectives from diagnostic laboratory executives, psychiatric clinician-investigators, hospital procurement managers, and FDA regulatory affairs specialists anchored the qualitative base. Primary interviews combined with secondary validation against FDA 510(k) and breakthrough device filings, CMS national coverage determination records, and CLIA laboratory certification databases. Bottom-up test volume modeling and top-down market sizing triangulated across the analysis window.
Scenario-bracketing around biomarker validation timelines and CMS reimbursement decisions framed the analytical approach across product type, technology modality, application setting, and end-user archetype segmentation. CAGRs derived from weighted average of historical adoption curves and penetration ceiling analysis. Forecast inputs incorporated pharmacogenomic coverage expansion trajectories and telemedicine infrastructure deployment rates in rural United States markets.
Stress conditions across FDA review timeline delays, CMS reimbursement code fragmentation, and EU AI Act validation burdens were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about regulatory pathway success rates and commercial payer contracting dynamics. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Diagnostics
Cellular Health Screening Market
Diagnostics
Glaucoma Diagnostics Market
Diagnostics
Human Immunodeficiency Virus Rapid Test Kit Market
Diagnostics
Hepatitis Test Solution and Diagnosis Market
Diagnostics
Viral Molecular Diagnostics Market
Diagnostics
Allergy Diagnostics Market
Diagnostics
Mexico in-Vitro Diagnostics Market
Diagnostics
Global Rheumatoid Arthritis Diagnostic Tests Market
Diagnostics
Inflammatory Markers Market
Diagnostics
Febrile Antigen Kits Market
Diagnostics
Netherlands in-Vitro Diagnostics Market
Diagnostics
Point of Care (Poc) Molecular Diagnostics Market
Diagnostics
Bilirubin Blood Test Market
Diagnostics
Infectious Disease Point-Of-Care (POC) Diagnostics Market
Diagnostics
Food Allergy Diagnostics and Therapeutics Market
Diagnostics
Thyroid Cancer Diagnostics Market