
 Johne's Disease Diagnostics Market | 2026-2036
Johne's Disease Diagnostics Market Size, Share, and Industry Trends Forecast 2026-2036
Johne's Disease Diagnostics Market Intelligence
Multi-source procurement of diagnostic reagents is broadening as veterinary laboratories diversify supply chains to mitigate raw-material volatility. IDEXX Laboratories leverages extensive distribution networks across North American veterinary channels. Zoetis anchors its position through integrated livestock health portfolios spanning diagnostics and therapeutics. Thermo Fisher Scientific competes on molecular platform breadth, extending PCR assay development for paratuberculosis detection.
Johne's Disease Diagnostics encompass laboratory and point-of-care methods for detecting Mycobacterium avium subspecies paratuberculosis infection in ruminants, with PCR assays achieving sensitivity thresholds below 10 colony-forming units per milliliter of fecal sample. These tools serve primarily to prevent economic losses from reduced milk yield, premature culling, and trade restrictions in infected herds. ELISA Kits dominate routine screening programs due to cost efficiency and throughput capacity in high-volume dairy settings. Molecular Diagnostics commands premium positioning where confirmatory testing and strain-typing applications justify higher per-test expenditure. Rapid Testing segments gain traction in field-based veterinary deployments where turnaround time determines intervention speed.
USDAAPHIS coordinates the national Johne's Disease control program through voluntary herd-status frameworks, while FDA oversight of veterinary diagnostic device quality standards shapes product registration pathways. State-level agriculture departments in Wisconsin and California enforce mandatory testing protocols for interstate movement certification. Stakeholders must monitor evolving harmonization between federal herd-health initiatives and private-sector assay validation requirements.
Market Dynamics
Dairy herd consolidation across the Upper Midwest and California is concentrating testing volume into fewer, larger accounts with standardized procurement protocols. USDAAPHIS voluntary herd-status frameworks are tightening into de facto mandates as interstate movement certification requirements expand.
Growth Catalysts
- USDAAPHIS Voluntary Herd Status Framework:Interstate commerce rules now effectively mandate Johne's certification for premium milk pricing tiers, pulling reluctant producers into screening programs.
- PCR Sensitivity Thresholds:Molecular platforms detecting below 10 colony-forming units per milliliter enable earlier intervention, reducing economic losses from subclinical shedding.
- Large-Scale Dairy Consolidation:Wisconsin and California operations exceeding 5,000 head now treat diagnostics as capital equipment rather than discretionary spend.
Market Restraints
- Reagent Supply Concentration:Polymerase chain reaction master mixes and antigen preparations concentrate among three specialty chemical suppliers, creating input volatility risk.
- Fecal Sample Logistics:Cold-chain requirements for molecular testing limit point-of-care deployment in remote grazing operations without laboratory infrastructure.
- Serological Cross-Reactivity:ELISA kits face technical limitations distinguishing Mycobacterium avium subspecies paratuberculosis from environmental mycobacteria in heavily contaminated samples.
Strategic Opportunities
- Texas Panhandle Expansion:Underpenetrated dairy growth corridors in the Texas High Plains lack established veterinary laboratory networks, creating first-mover channel opportunities.
- Blockchain Traceability Integration:Convergence of diagnostic data with supply chain tracking systems enables premium export certification to Canadian and Mexican markets.
- FDA Quality System Regulation Alignment:Streamlined 510(k) pathways for veterinary diagnostics with human food safety implications accelerate product registration timelines.
Industry Challenges
- Veterinary Diagnostic Technician Shortage:Laboratory accreditation requirements for mycobacterial culture work exceed available trained personnel in rural service territories.
- Legacy Herd Management Software Integration:Test result data formats lack standardization with dominant dairy management platforms, forcing manual reconciliation workflows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Johne's Disease Diagnostics Market |
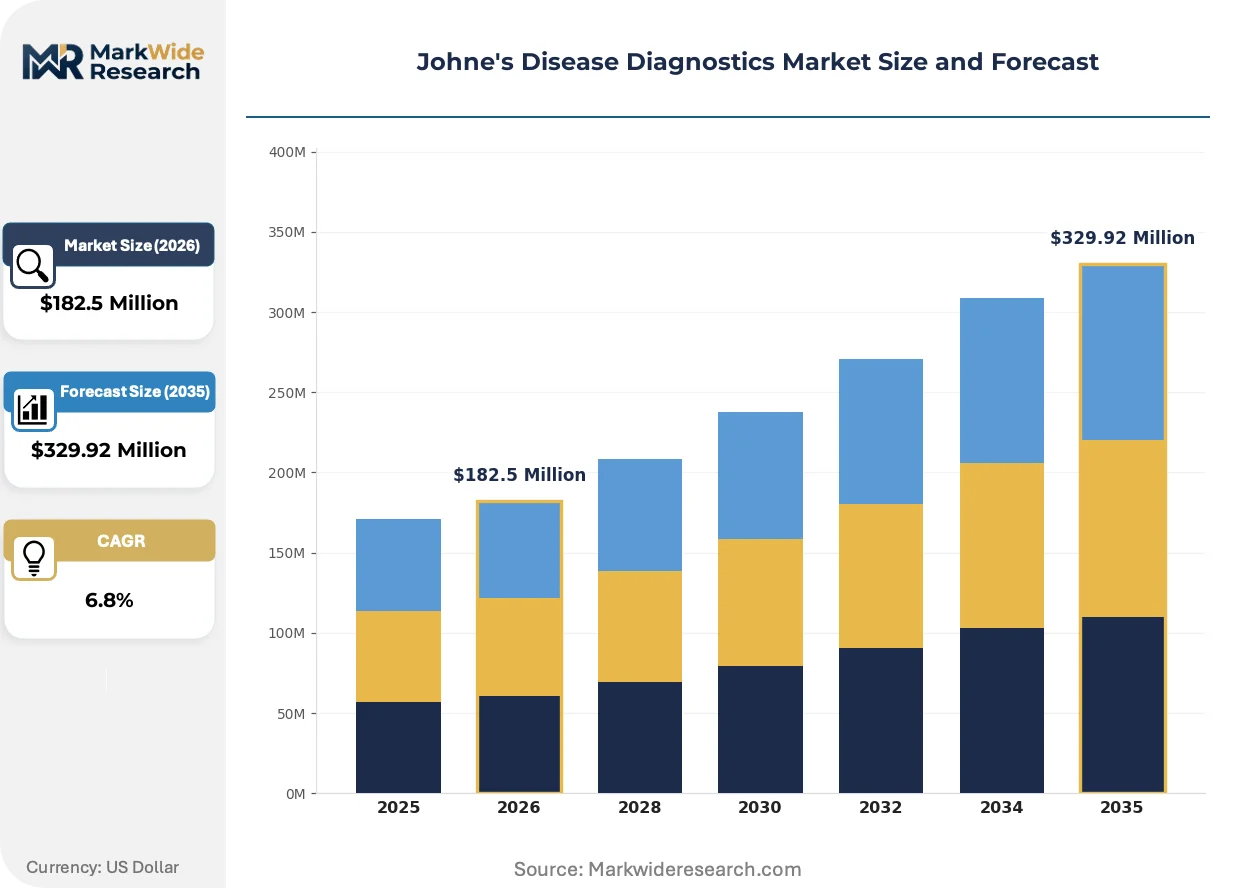
| Market Size in 2026 | $182.5 Million |
| Market Size in 2035 | $329.92 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: ELISA Kits, PCR Assays, Culture Media, Antigen Tests End User: Dairies, Veterinary Clinics, Research Laboratories, Livestock Farms Application: Animal Health Monitoring, Research Studies, Disease Control, Diagnostic Testing Technology: Molecular Diagnostics, Immunological Techniques, Biochemical Testing, Rapid Testing |
| Companies Covered | Thermo Fisher Scientific, IDEXX Laboratories, Zoetis, PBD Biotech, IDVet, VMRD, BioMérieux SA, INDICAL BIOSCIENCE GmbH, Tetracore, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Johne's Disease Diagnostics Market Strategic Shifts & Innovations
Diagnostic platforms are converging around multiplex capabilities that consolidate Johne's detection with broader ruminant pathogen panels. This consolidation is compressing equipment footprints and reagent procurement complexity for high-throughput laboratories.
Loop-mediated isothermal amplification technology is unifying rapid field detection with laboratory-grade sensitivity. Regional veterinary diagnostic networks in the Corn Belt are adopting these platforms for same-day turnaround. The technology is unifying previously separate screening and confirmatory workflows into single-visit protocols.
California Department of Food and Agriculture mandatory testing protocols for Grade A milk production facilities are tightening assay validation requirements. Producers must now document third-party proficiency testing for ELISA interpretations used in interstate shipping documentation. Large integrated operations are responding by bringing molecular confirmation capacity in-house rather than relying on state laboratory backlogs.
Consolidated procurement through dairy cooperative purchasing alliances is displacing individual veterinarian practice ordering. These alliances negotiate multi-year reagent supply contracts with volume-tier pricing structures. The shift is most visible in the Northeast, where cooperative membership covers over seventy percent of milk production volume.
Johne's Disease Diagnostics Market Segmentation
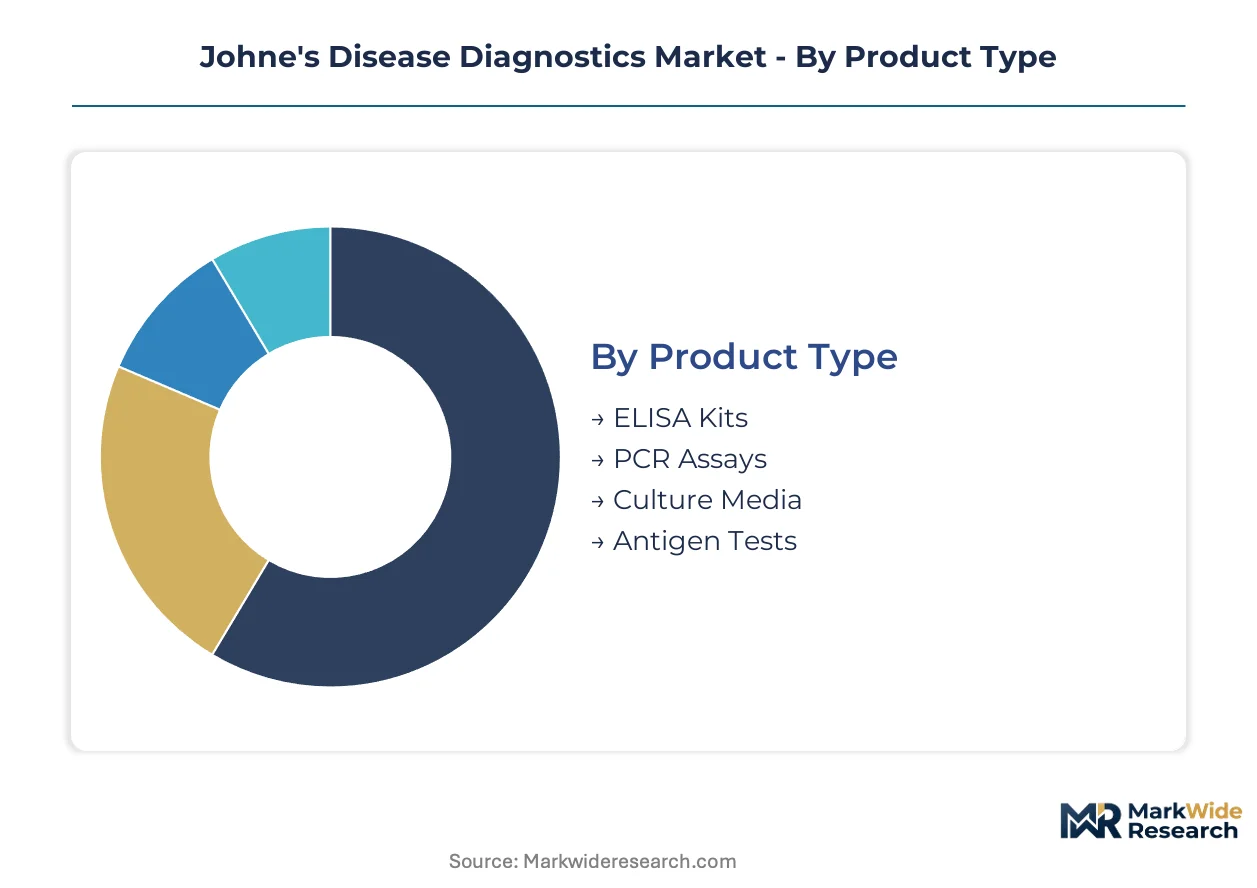
Diagnostic procurement patterns in Johne's disease testing diverge sharply between high-throughput dairy cooperatives and fragmented livestock operations. Understanding these segment boundaries clarifies where assay manufacturers must configure pricing tiers and service models to capture volume versus margin.
Product Type:
Cost tier determines procurement channel selection, with capital-constrained operations prioritizing per-test economics over sensitivity specifications.
- ELISA Kits:Enzyme-linked immunosorbent assays detect MAP-specific antibodies in serum or milk samples with batch processing capacity exceeding 90 tests per hour. Demand concentrates in Wisconsin and California dairy cooperatives where USDAAPHIS herd-status certification mandates routine screening of entire milking strings. These kits face margin pressure from consolidated cooperative purchasing alliances negotiating multi-year supply contracts.
- PCR Assays:Polymerase chain reaction platforms amplify IS900 insertion sequences for detection below 10 colony-forming units per milliliter of fecal material. Large integrated operations exceeding 5,000 head in California's Central Valley are bringing this capacity in-house to bypass state laboratory backlogs and accelerate culling decisions. Reagent supply concentration among three specialty chemical suppliers creates input volatility risk for this segment.
- Culture Media:Solid and liquid formulations support mycobacterial isolation for definitive diagnosis in regulatory submissions.
- Antigen Tests:Lateral flow devices deliver qualitative results without laboratory infrastructure for field-based veterinary screening.
Volume sits with ELISA Kits; growth tilts toward PCR Assays.
End User:
Customer type shapes testing frequency, with dairy operations driving recurring revenue streams distinct from episodic research or clinical demand.
- Dairies:Commercial milk production facilities operate continuous screening programs tied to Grade A certification requirements. The Texas Panhandle expansion corridor lacks established veterinary laboratory networks, creating first-mover channel opportunities for diagnostic distributors. Blockchain traceability integration with supply chain tracking systems enables premium export certification for these operations.
- Veterinary Clinics:Mixed-animal practices serve smaller livestock holdings with intermittent testing needs and price-sensitive procurement.
- Research Laboratories:Academic and government facilities conduct strain-typing and vaccine efficacy studies requiring specialized assay formats.
- Livestock Farms:Beef cattle and small ruminant operations test primarily for interstate movement compliance rather than production economics.
Revenue concentrates in Dairies; expansion is steepest in Veterinary Clinics adopting rapid point-of-care platforms.
Application:
Application maturity determines validation burden, with diagnostic testing facing heavier regulatory scrutiny than research use.
- Diagnostic Testing:Confirmatory and screening workflows for regulatory compliance and herd management decisions. California Department of Food and Agriculture protocols now require third-party proficiency testing documentation for ELISA interpretations used in interstate shipping. Fecal sample cold-chain requirements for molecular confirmation limit deployment in remote grazing territories without laboratory infrastructure.
- Animal Health Monitoring:Surveillance programs tracking subclinical shedding and transmission dynamics within herds.
- Disease Control:Eradication and certification programs aligned with USDAAPHIS voluntary herd-status frameworks.
- Research Studies:Epidemiological and pathogenesis investigations with flexible validation requirements.
Diagnostic Testing commands the revenue base; Animal Health Monitoring is climbing the fastest as producers shift from episodic testing to continuous surveillance.
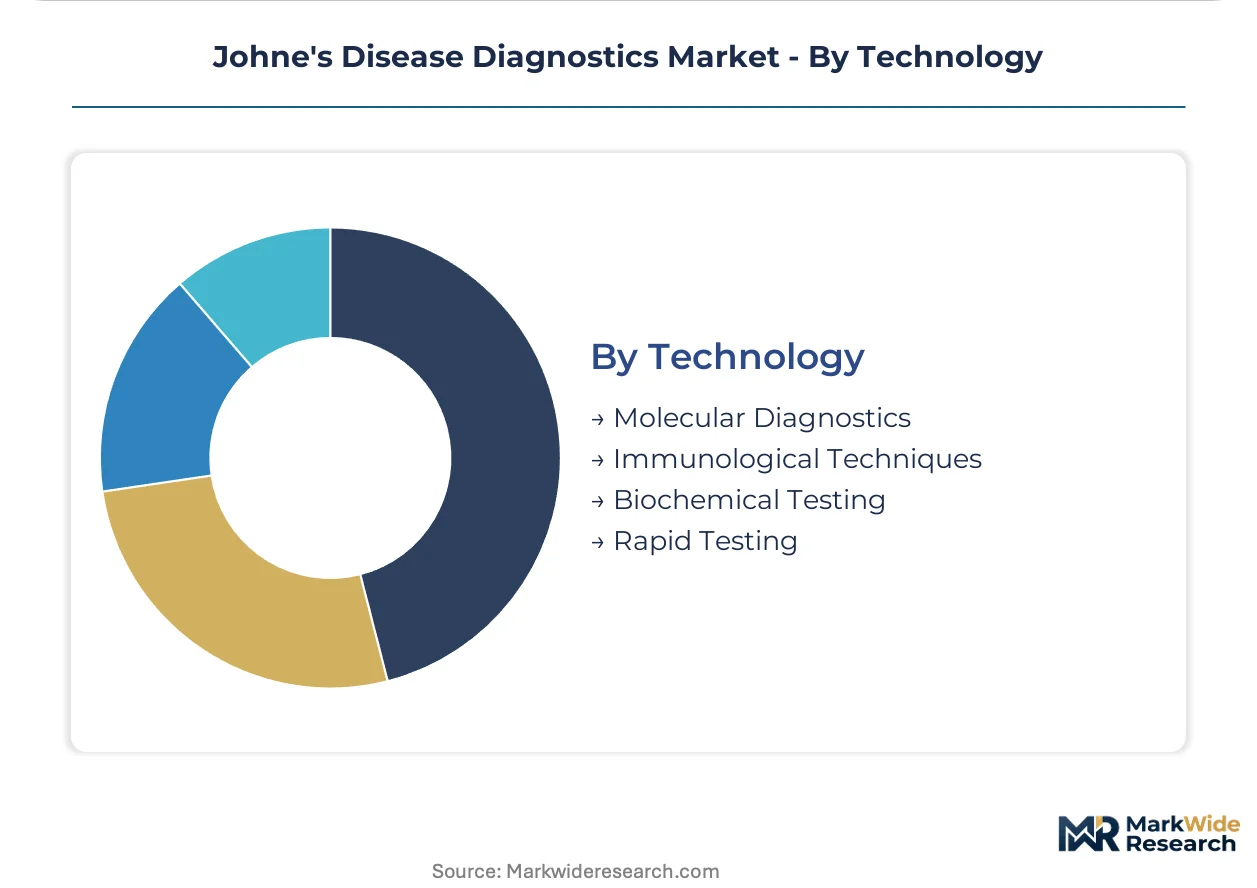
Technology:
Technology selection reflects the tension between throughput requirements and sensitivity thresholds in different testing contexts.
- Molecular Diagnostics:PCR and loop-mediated isothermal amplification platforms achieve laboratory-grade sensitivity in field-deployable formats. Regional veterinary diagnostic networks in the Corn Belt are adopting these technologies for same-day turnaround, unifying previously separate screening and confirmatory workflows. Veterinary diagnostic technician shortages for mycobacterial culture work accelerate this substitution.
- Immunological Techniques:Antibody and antigen detection methods dominate high-volume screening with established cost structures.
- Rapid Testing:Isothermal amplification and lateral flow devices compress result timelines for intervention speed.
- Biochemical Testing:Traditional culture-based methods retain regulatory acceptance for definitive diagnosis.
Immunological Techniques anchor current volume; Molecular Diagnostics is gaining share fastest as sensitivity requirements tighten and field platforms mature.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Commercial dairy density concentrates testing demand in three countries with large-scale herd consolidation. Regulatory frameworks in these markets now effectively mandate screening through certification requirements for interstate and export commerce.
United States
Wisconsin and California dairy cooperatives exceeding 5,000 head drive volume through USDAAPHIS herd-status certification requirements. The FDA oversees veterinary diagnostic device quality standards that shape product registration pathways for assay manufacturers. The Texas Panhandle expansion corridor lacks established veterinary laboratory networks, creating first-mover channel opportunities for diagnostic distributors.
Germany
Bavarian and Lower Saxon dairy operations maintain rigorous Johne's control programs tied to EU export certification standards. EFSA guidelines on animal health surveillance influence national implementation of screening mandates across federal states. The Münsterland cluster anchors demand for high-throughput ELISA processing in cooperative laboratory networks.
Netherlands
Intensive dairy farming in Gelderland and Overijssel provinces generates concentrated demand for molecular confirmation testing. The country's national veterinary regulator enforces strict proficiency testing requirements for laboratories conducting MAP diagnostics. Wageningen University research partnerships accelerate adoption of loop-mediated isothermal amplification platforms in regional diagnostic networks.
Canada
Alberta and Quebec dairy boards coordinate voluntary Johne's control programs that increasingly function as de facto mandates for premium milk pricing tiers. Health Canada oversight of veterinary biologics shapes assay import and registration pathways. The Calgary-Edmonton corridor concentrates testing volume in centralized provincial laboratory infrastructure.
Australia
Victorian and New South Wales dairy regions maintain surveillance programs aligned with international trade access requirements for MAP-free certification. The TGA regulates veterinary diagnostic devices under a risk-based framework that accelerates approval for PCR-based platforms. The Gippsland dairy cluster drives demand for rapid turnaround testing to support culling decisions in large integrated operations.
Johne's Disease Diagnostics Market Key Industry Players
Portfolio diversification dominates the current landscape as assay manufacturers expand from single-pathogen offerings to multiplex ruminant health panels. The vendor base organizes into three tiers: diversified life science conglomerates with extensive distribution infrastructure, specialized veterinary diagnostic firms with deep livestock channel relationships, and emerging molecular platform developers focused on field-deployable sensitivity. M&A activity concentrates among mid-cap specialists seeking geographic footprint expansion. Technology licensing agreements accelerate access to isothermal amplification and CRISPR-based detection methods without internal R&D investment.
Within the diversified conglomerate tier, Thermo Fisher Scientific and IDEXX Laboratories exemplify scale-driven positioning through extensive North American veterinary channel penetration. Zoetis anchors the integrated livestock health portfolio archetype, spanning diagnostics and therapeutics through unified sales relationships with large dairy operations. These three companies represent the dominant competitive anchors against which specialized players differentiate on assay specificity or regional service density.
| Leading Market Players |
|---|
| Thermo Fisher Scientific |
| IDEXX Laboratories |
| Zoetis |
| PBD Biotech |
| IDVet |
| VMRD |
| BioMérieux SA |
| INDICAL BIOSCIENCE GmbH |
| Tetracore |
| Others |
Cost & Logistics Intelligence
Consolidated dairy cooperative purchasing alliances in Wisconsin and California now negotiate multi-year reagent supply contracts with volume-tier pricing structures, forcing assay manufacturers to reconfigure production planning around fewer, larger accounts with standardized procurement protocols and compressed margin profiles.
Pricing Analysis
Volume concentrates in ELISA Kits where per-test economics dominate procurement decisions; margins concentrate in PCR Assays where confirmatory sensitivity commands premium positioning. Three-tier pricing structure separates certified-laboratory-grade diagnostics from field-deployable rapid tests from basic screening reagents. Cost compression in the ELISA tier is intensifying because cooperative purchasing alliances leverage collective volume for multi-year contract concessions. Small veterinary clinics exhibit highest price sensitivity; large integrated operations exceeding 5,000 head prioritize sensitivity specifications over unit cost.
Supply Chain Analysis
Domestic-content preferences in USDAAPHIS proficiency testing documentation reshape sourcing toward North American reagent manufacturing where feasible. Polymerase chain reaction master mixes and antigen preparations draw from specialty chemical suppliers concentrated in the United States, Germany, and the Netherlands. Single-source vulnerability runs through three specialty chemical suppliers controlling critical PCR reagent inputs. Distribution runs through dairy cooperative purchasing alliances displacing individual veterinarian practice ordering across the Upper Midwest and California.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
USDAAPHIS voluntary herd-status frameworks function as de facto compliance mandates, erecting regulatory validation barriers that protect incumbents with established FDA quality system alignment while raising capital requirements for new assay entrants.
For Market Incumbents: To counter emerging molecular platform developers with field-deployable sensitivity, anchor position through backward integration into PCR master mix production and accelerate FDA 510(k) pathway alignment for multiplex ruminant health panels. Channel control through exclusive distribution agreements with dairy cooperative purchasing alliances remains critical for volume defense. For New Entrants and Emerging Players: Enter via the Texas Panhandle expansion corridor where underpenetrated dairy growth lacks established veterinary laboratory networks. Target rapid point-of-care platforms for veterinary clinics adopting same-day turnaround protocols. A go-to-market angle emphasizing blockchain traceability integration with supply chain tracking systems unlocks premium export certification positioning. For Investors and Strategic Acquirers: The window for entry favors specialized veterinary diagnostic firms with deep livestock channel relationships and validated assay specificity. Long-term viability rests on convergence toward multiplex capabilities consolidating Johne's detection with broader pathogen panels. Watch FDA quality system regulation alignment acceleration as the inflection signal for registration timeline compression.| Strategic Initiative | Industry Significance |
|---|---|
| Multiplex Platform Development | Consolidates Johne's detection with broader ruminant pathogen panels for high-throughput laboratories. |
| Backward Integration into Reagents | Mitigates input volatility risk from three specialty chemical suppliers controlling PCR master mixes. |
| FDA 510(k) Pathway Alignment | Streamlines product registration for veterinary diagnostics with human food safety implications. |
| Blockchain Traceability Integration | Enables premium export certification to Canadian and Mexican markets through supply chain data convergence. |
| Regional Diagnostic Network Expansion | Captures first-mover channel opportunities in Texas Panhandle dairy growth corridors lacking laboratory infrastructure. |
Research Approach
USDAAPHIS program documentation, FDA veterinary diagnostic device registration filings, and state agriculture department testing protocols formed the secondary backbone. Primary interviews with veterinary diagnostic laboratory directors, dairy cooperative procurement managers, assay manufacturer regulatory affairs leads, and large-integrated-operation herd managers combined with secondary validation. Bottom-up and top-down triangulation cross-checked reagent procurement volume against dairy herd consolidation data.
Bottom-up modeling built from individual assay pricing tiers and testing frequency by herd size; top-down validation checked against aggregate dairy industry screening expenditure patterns. Segmentation dimensions spanned product type, end user, application, and technology across the projection horizon. CAGRs derived from trend extrapolation of testing volume growth in consolidated operations and regulatory mandate expansion. Industry-specific inputs included USDAAPHIS herd-status certification penetration rates and PCR sensitivity threshold adoption curves.
Forecast precision tightens around the base case; tail outcomes carry wider variance under reagent supply disruption scenarios or veterinary diagnostic technician shortage acceleration. Forecasts reflect assumptions of continued dairy herd consolidation and regulatory harmonization between federal herd-health initiatives and private-sector assay validation requirements. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Diagnostics
Haptoglobin Reagent Market
Diagnostics
Global Liver Disease Diagnostics Market
Diagnostics
In Vitro Diagnostics (IVD) Quality Control Market
Diagnostics
Creatinine Test Market
Diagnostics
Global Non-Small Cell Lung Cancer Diagnostics Market
Diagnostics
Urinary Protein Reagents Market
Diagnostics
Global Tissue Diagnostics Market
Diagnostics
At-Home Cancer Testing Market
Diagnostics
Global Chlamydia Infection Diagnostics Market
Diagnostics
North America Ovarian Cancer Diagnostics Market
Diagnostics
Diabetes Diagnostics Market
Diagnostics
Brain Cancer Diagnostics Market
Diagnostics
Global Yersiniosis Diagnostics and Treatment Market
Diagnostics
Sexually Transmitted Diseases Diagnostics Market
Diagnostics
Global Molecular Diagnostics Services Market
Diagnostics
Global Respiratory Diagnostics Market