
 DNA and RNA Probes Market | 2026-2036
DNA and RNA Probes Market Size, Share, and Industry Trends Forecast 2026-2036
DNA and RNA Probes Market Outlook
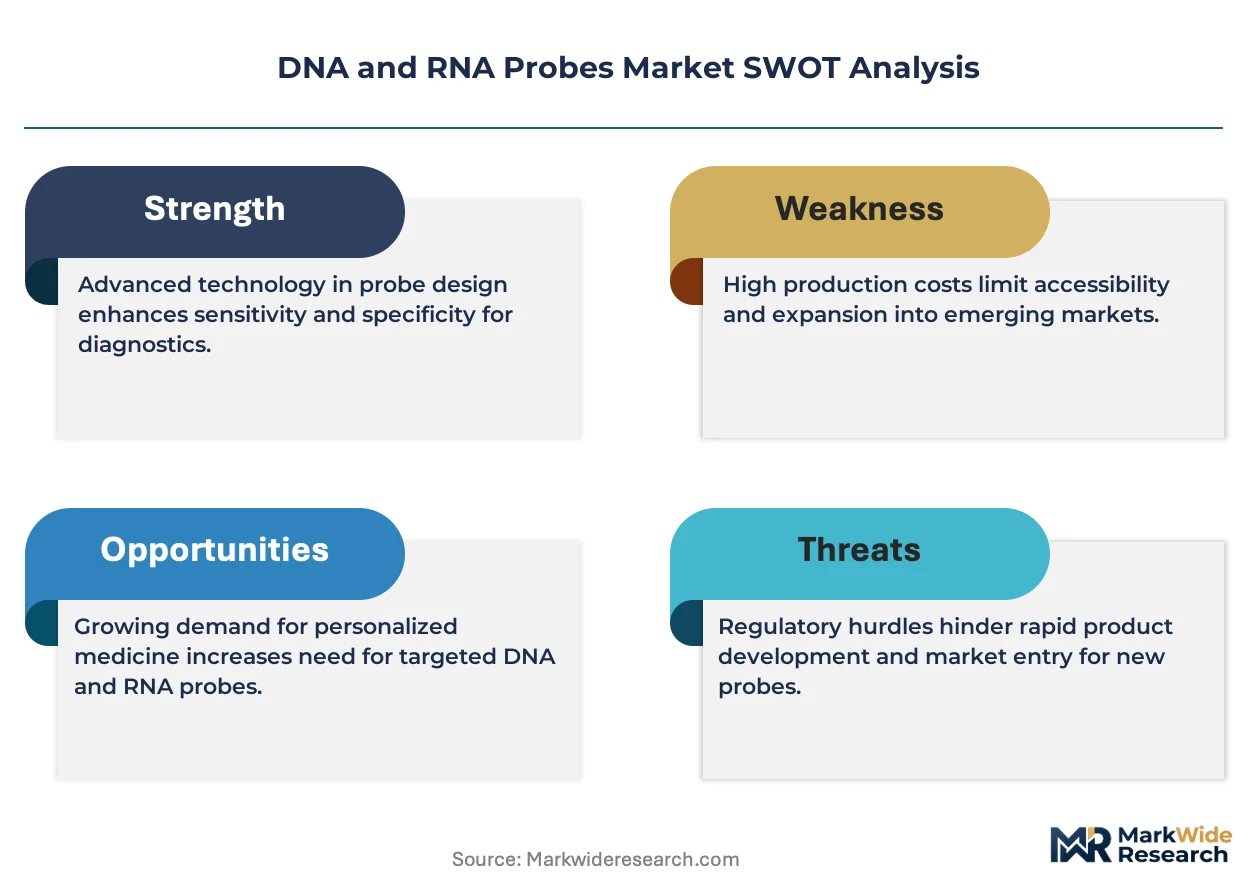
Modular probe panel configurations is rebalancing purchasing decisions across diagnostic laboratories and research institutions. Thermo Fisher Scientific leverages its integrated reagent-instrument ecosystem to capture recurring consumable revenue. F. Hoffmann-La Roche Ltd anchors its position through deep specialization in fluorescence-based clinical assays. Agilent Technologies differentiates via advanced microarray probe architectures serving genomic research workflows.
DNA and RNA probes are single-stranded nucleic acid sequences, typically 15–50 nucleotides in length, labeled with fluorescent dyes, enzymes, or haptens for sequence-specific target detection through complementary base pairing. These probes enable quantitative and qualitative analysis of genetic material in clinical diagnostics, life science research, and environmental surveillance applications. Fluorescent probes dominate commercial volumes due to their direct detection capability and compatibility with automated platforms, while enzyme-based probes retain importance in signal amplification protocols where sensitivity thresholds demand enzymatic cascade enhancement. Real-time PCR technology sustains the largest installed base among amplification methods, though next-generation sequencing probe applications are expanding fastest as clinical laboratories adopt comprehensive genomic profiling workflows.
FDA oversight of companion diagnostic devices governs probe-based assay approvals tied to therapeutic indications, while the Clinical Laboratory Improvement Amendments regulate analytical performance standards in US testing facilities. ISO 13485 quality management requirements shape manufacturing compliance for probe suppliers serving regulated diagnostic markets. EMA's In Vitro Diagnostic Regulation in Europe imposes stricter clinical evidence and post-market surveillance obligations on probe manufacturers accessing EU member states. Stakeholders must monitor evolving harmonization between FDA and EMA premarket pathways, as divergent evidentiary requirements threaten to fragment product development timelines and regional launch sequencing.
Market Dynamics
Companion diagnostic approval pathways are compressing product development timelines while fragmenting regional launch sequencing, forcing probe manufacturers to maintain parallel regulatory dossiers across FDA and EMA jurisdictions.
Growth Catalysts
- Precision medicine workflows:Academic medical centers in the United States are expanding hybridization-based testing menus to capture oncology and infectious disease profiling volumes.
- EMA In Vitro Diagnostic Regulation:Stricter clinical evidence requirements are accelerating consolidation among probe suppliers capable of supporting post-market surveillance infrastructure.
- Next-generation sequencing integration:Clinical laboratories are adopting comprehensive genomic profiling workflows that consume probe-based library preparation reagents at scale.
Market Restraints
- Fluorophore supply concentration:Specialty dye chemistries for FISH and qPCR applications depend on concentrated manufacturing in Germany and Switzerland.
- Analytical validation costs:CLIA laboratory certification requirements impose substantial capital burdens on diagnostic facilities adopting novel probe formats.
- Enzymatic amplification substitutes:CRISPR-based detection methods are displacing hybridization probes in certain infectious disease screening applications.
Strategic Opportunities
- Liquid biopsy expansion:Circulating tumor DNA detection protocols in oncology are creating demand for ultra-sensitive probe chemistries in the United States.
- ISO 13485 manufacturing scale-up:Quality management certification enables probe suppliers to access regulated diagnostic markets with higher margin profiles.
- Environmental surveillance:Wastewater pathogen monitoring programs in Singapore and Australia are adopting multiplexed probe panels for SARS-CoV-2 variant tracking.
Industry Challenges
- Bioinformatics pipeline integration:Probe assay outputs require specialized data interpretation infrastructure that many clinical laboratories lack.
- Cross-reactivity mitigation:Sequence homology between pathogen strains demands extensive wet-lab validation that extends product development cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | DNA and RNA Probes Market |
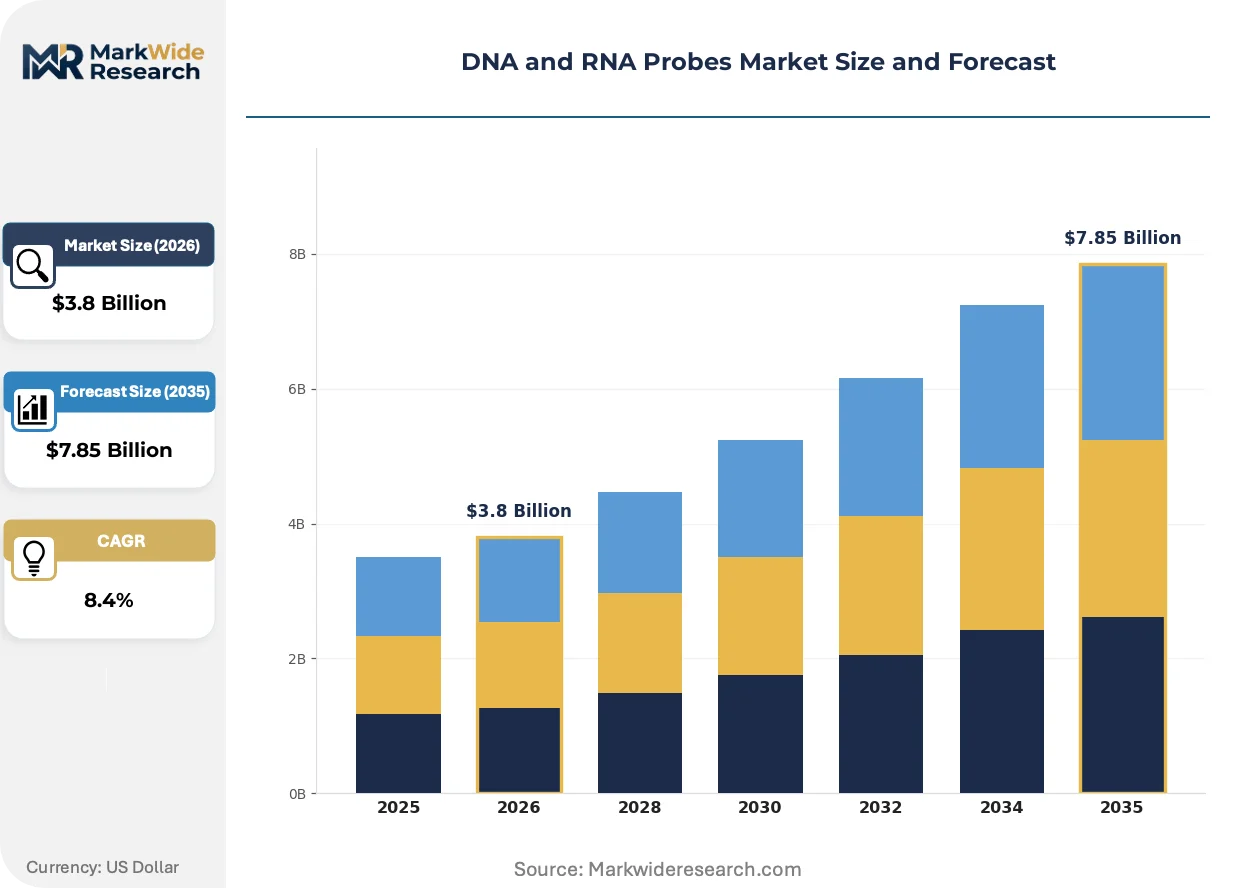
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $7.85 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fluorescent Probes, Enzyme-Based Probes, Ligation Probes, Hybridization Probes Technology: Real-Time PCR, Next-Generation Sequencing, Microarray Analysis, In Situ Hybridization Application: Clinical Diagnostics, Environmental Monitoring, Research Applications, Agricultural Biotechnology End User: Hospitals, Diagnostic Laboratories, Academic Institutions, Pharmaceutical Companies |
| Companies Covered | Thermo Fisher Scientific, F. Hoffmann-La Roche Ltd, Agilent Technologies, Merck KGaA, Bio-Rad Laboratories, QIAGEN, Abbott Molecular, Beckman Coulter, Becton Dickinson and Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
DNA and RNA Probes Market Strategic Shifts
Probe architecture innovation is bifurcating between modular panel configurations for research flexibility and locked assay designs for clinical reproducibility, with automation compatibility determining purchasing decisions.
Locked nucleic acid chemistries are expanding into clinical diagnostic workflows by improving binding affinity and specificity for challenging target sequences. Reference laboratories in the United States are adopting LNA-modified probes for detecting low-abundance fusion transcripts in solid tumor profiling. This chemistry shift is expanding into companion diagnostic development pipelines where single-nucleotide discrimination determines therapeutic eligibility.
EMA's In Vitro Diagnostic Regulation is compressing commercialization timelines for probe manufacturers by mandating prospective clinical studies prior to market authorization. European diagnostic companies are responding by pre-positioning performance dossiers across multiple member states simultaneously. Smaller probe suppliers without dedicated regulatory affairs infrastructure face exclusion from EU commercial channels.
Consolidated procurement through integrated reagent-instrument contracts is displacing standalone probe purchasing in high-volume clinical laboratories. Thermo Fisher Scientific and Roche are capturing multi-year supply agreements that bundle consumables with platform placements. This channel shift is most visible in the United States where health system consolidation has concentrated purchasing authority within centralized laboratory operations.
DNA and RNA Probes Market Segmentation
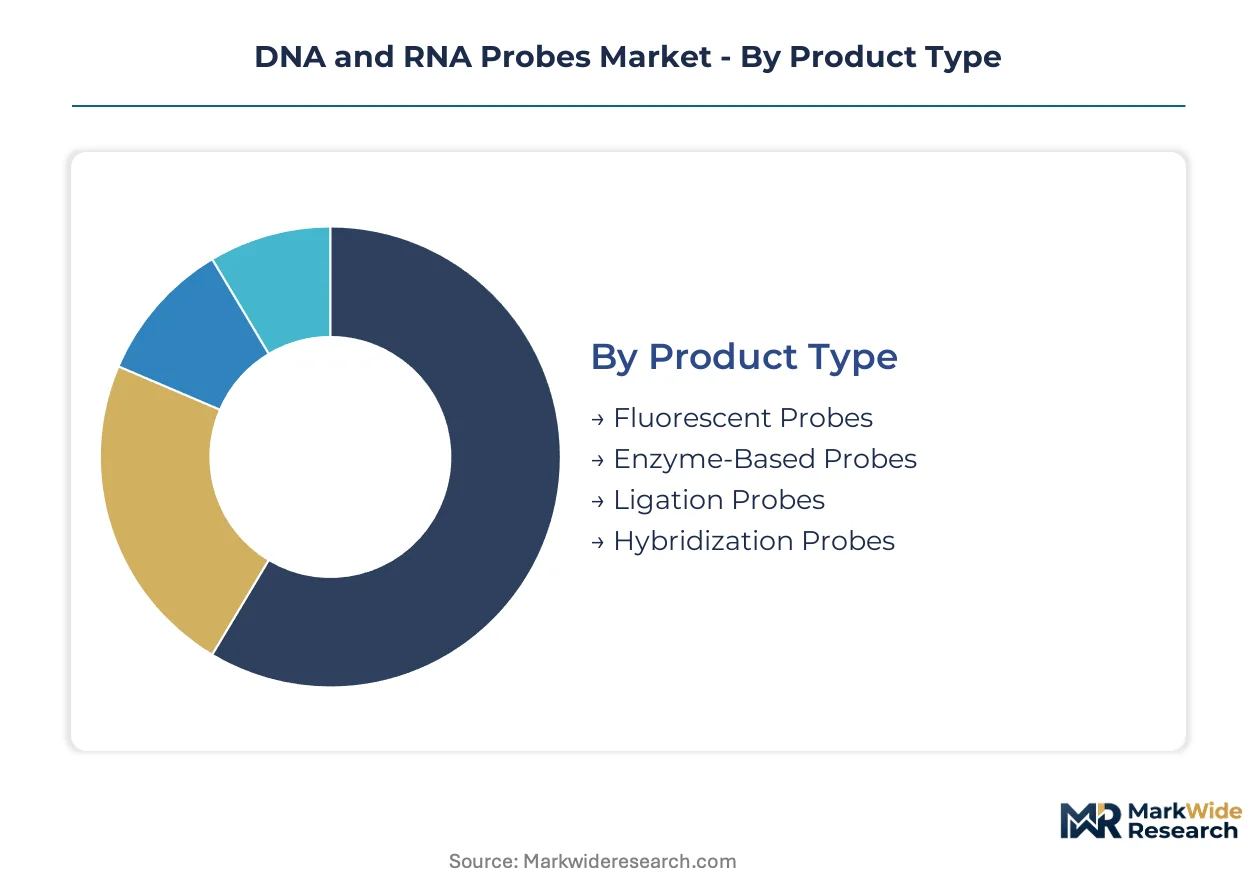
Probe manufacturers configure product portfolios around distinct workflow requirements, balancing standardization for clinical reproducibility against modular flexibility for research customization. Each segmentation dimension reflects a different axis of technical specification, regulatory burden, and purchasing authority that shapes commercial strategy and margin capture.
Product Type:
Customization intensity varies sharply across probe chemistries, from locked clinical assay designs to configurable research-grade formats.
- Fluorescent Probes:These single-stranded oligonucleotides carry direct fluorophore labels enabling immediate signal detection without enzymatic amplification. Demand concentrates in United States reference laboratories running high-throughput qPCR workflows, where automation compatibility and signal stability determine procurement decisions. CLIA-certified facilities favor these probes for their reproducible performance in companion diagnostic applications.
- Enzyme-Based Probes:Hapten-labeled sequences requiring enzymatic conversion generate amplified signals essential for detecting ultra-low target abundance. Academic medical centers in the United States deploy these in infectious disease panels where sensitivity thresholds exceed fluorescent probe capabilities. Signal amplification protocols extend assay time but enable detection of single-digit copy numbers.
- Ligation Probes:Adjacent probe pairs requiring enzymatic ligation prior to detection enable highly specific single-nucleotide discrimination. These chemistries serve mutation detection workflows in solid tumor profiling.
- Hybridization Probes:Unlabeled or minimally labeled sequences relying on post-hybridization detection support FISH and microarray applications. Research institutions favor these for custom panel development.
Most installed capacity flows through fluorescent probe formats. Expansion is steepest in enzyme-based probe segments serving liquid biopsy workflows.
Technology:
Platform maturity creates a cost-performance gradient, with established amplification methods competing against emerging sequencing integration.
- Real-Time PCR:Quantitative amplification with fluorescent readout sustains the largest installed instrument base across clinical and research settings. United States hospital laboratories depend on qPCR probes for routine infectious disease testing and pharmacogenomic screening. Platform standardization enables rapid assay validation and regulatory submission.
- Next-Generation Sequencing:Probe-based library preparation and target enrichment consume specialized oligonucleotide panels at accelerating volumes. Comprehensive genomic profiling adoption in United States academic medical centers is driving fastest segment expansion. Hybridization capture probes and amplicon panels require complex bioinformatics infrastructure.
- Microarray Analysis:High-density probe arrays enable parallel interrogation of thousands of sequences. Genomic research workflows retain demand despite sequencing displacement.
- In Situ Hybridization:Tissue-section probe hybridization provides spatial transcriptomic information. Pathology departments deploy these for fusion transcript detection in oncology.
Real-time PCR maintains dominant installed base. Next-generation sequencing applications are climbing the fastest as clinical laboratories adopt comprehensive profiling.
Application:
Regulatory intensity stratifies this category, with FDA-governed clinical applications commanding premium pricing against research and environmental segments.
- Clinical Diagnostics:FDA-cleared probe assays for companion diagnostics and infectious disease testing operate under stringent analytical validation requirements. United States reference laboratories anchor procurement volumes for oncology and pharmacogenomic applications. EMA's In Vitro Diagnostic Regulation is compressing commercialization timelines for European market entry.
- Research Applications:Non-regulated probe formats for gene expression and genomics studies prioritize flexibility over standardization. Academic institutions in the United States drive demand for modular panel configurations.
- Environmental Monitoring:Wastewater pathogen surveillance and biodiversity assessment employ multiplexed probe panels. Singapore and Australia have adopted these for SARS-CoV-2 variant tracking programs.
- Agricultural Biotechnology:Crop pathogen detection and transgenic screening utilize species-specific probe chemistries. Seed companies deploy these for quality control and trait verification.
Clinical diagnostics commands largest revenue share. Environmental monitoring is gaining share fastest as public health surveillance infrastructure expands.
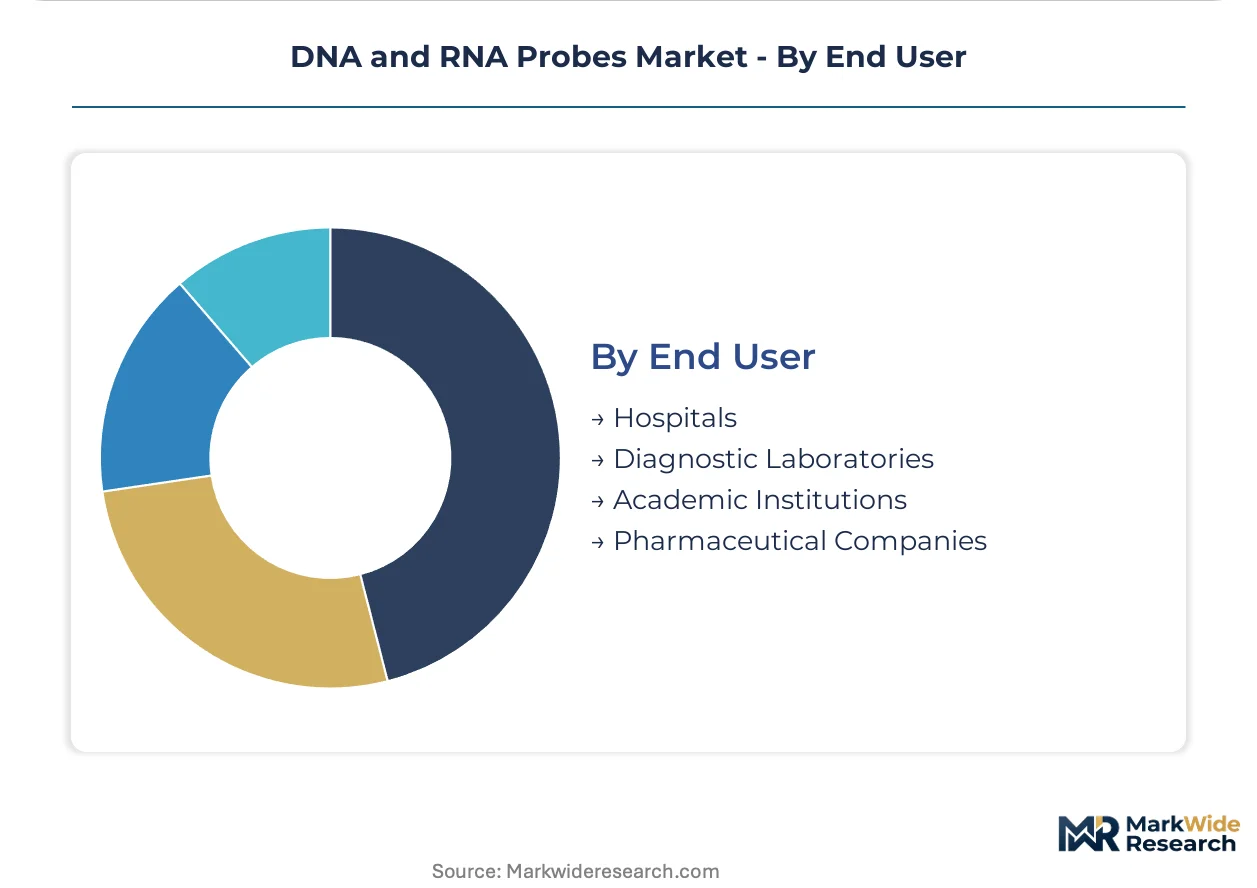
End User:
Purchasing authority concentration determines contract structure, with consolidated health systems negotiating multi-year supply agreements against fragmented academic procurement.
- Diagnostic Laboratories:High-volume reference and hospital-affiliated labs consume probe reagents at scale through integrated reagent-instrument contracts. United States health system consolidation has centralized purchasing authority within regional laboratory networks. CLIA certification requirements create switching costs that lock in supplier relationships.
- Pharmaceutical Companies:Companion diagnostic development and clinical trial biomarker testing demand probe suppliers capable of supporting regulatory dossiers. FDA submission requirements favor partners with ISO 13485 manufacturing and dedicated regulatory affairs infrastructure.
- Hospitals:In-house clinical laboratories balance standardized assay menus against point-of-care testing needs. Smaller facilities rely on reference laboratory send-outs.
- Academic Institutions:Research laboratories prioritize probe customization and technical support over price minimization. Grant-funded procurement operates on different budget cycles than commercial facilities.
Diagnostic laboratories process highest probe volumes. Pharmaceutical company demand is expanding most quickly as companion diagnostic pipelines mature.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The DNA and RNA probes industry traces its commercial roots to early nucleic acid hybridization techniques developed in academic laboratories across the United States and Europe during the 1980s. These foundational methods enabled sequence-specific detection that now underpins modern clinical diagnostics and genomic research workflows worldwide.
United States
Academic medical centers in Boston and the Research Triangle anchor procurement volumes for advanced hybridization technologies. FDA's evolving guidance on companion diagnostics compresses product development timelines while fragmenting regional launch sequencing. Reference laboratories in California and Texas are expanding probe-based testing menus to capture precision medicine workflows in oncology and infectious disease profiling.
Germany
Specialty dye chemistries for FISH and qPCR applications concentrate manufacturing in chemical clusters around Ludwigshafen and Basel-adjacent regions. EMA's In Vitro Diagnostic Regulation imposes stricter clinical evidence and post-market surveillance obligations on probe manufacturers accessing EU member states. Munich-based diagnostic companies are pre-positioning performance dossiers across multiple member states simultaneously.
China
Genomic research institutions in Shanghai and Beijing drive accelerating consumption of probe-based library preparation reagents. NMPA oversight of companion diagnostic devices shapes product registration pathways for multinational suppliers. Yangtze River Delta biotech parks are incubating domestic probe manufacturers targeting clinical diagnostic markets.
Japan
PMDA regulatory frameworks govern analytical performance standards for probe-based assays in clinical settings. METI industrial policy supports precision medicine infrastructure development in Kansai and Kanto regions. Osaka-based pharmaceutical companies are integrating companion diagnostic development with therapeutic pipelines.
Switzerland
Swissmedic quality requirements shape manufacturing compliance for probe suppliers serving regulated European diagnostic markets. Basel's life sciences cluster hosts concentrated fluorophore chemistry expertise critical for signal amplification protocols. Zürich reference laboratories are adopting locked nucleic acid chemistries for low-abundance transcript detection.
DNA and RNA Probes Market Competitive Environment
The competitive structure tilts toward integrated reagent-instrument ecosystems that capture recurring consumable revenue through multi-year supply agreements. Consolidated procurement patterns favor suppliers capable of bundling probes with platform placements and supporting regulatory dossiers across FDA and EMA jurisdictions. Two archetypes dominate: diversified life sciences conglomerates with captive probe manufacturing and specialized oligonucleotide suppliers serving modular research workflows. M&A activity concentrates on acquiring ISO 13485-certified manufacturing assets, while strategic partnerships between probe developers and sequencing platform manufacturers accelerate NGS integration.
Among diversified laboratory technology providers, Thermo Fisher Scientific exemplifies the integrated ecosystem archetype through its reagent-instrument bundling strategy. F. Hoffmann-La Roche Ltd occupies a position emphasizing fluorescence-based clinical assay specialization. Agilent Technologies represents the advanced microarray probe architecture segment serving genomic research workflows. These three anchors illustrate how competitive positioning diverges across clinical reproducibility and research flexibility vectors.
| Leading Market Players |
|---|
| Thermo Fisher Scientific |
| F. Hoffmann-La Roche Ltd |
| Agilent Technologies |
| Merck KGaA |
| Bio-Rad Laboratories |
| QIAGEN |
| Abbott Molecular |
| Beckman Coulter |
| Becton Dickinson and Company |
| Others |
Value Chain & Pricing Dynamics
Specialty fluorophore chemistries manufactured in Germany and Switzerland cascade through three distinct pricing tiers before reaching end-users, with ISO 13485-certified probes commanding substantial premiums over research-grade alternatives in United States clinical laboratories.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels dominates probe procurement, with premium tiers capturing CLIA-certified companion diagnostic applications while economy tiers serve grant-funded academic research. Price differentiation hinges on regulatory certification grade and manufacturing scale, with FDA-cleared assay formats sustaining margins despite cost compression in commoditized qPCR reagent segments. Reference laboratories exhibit lowest price sensitivity due to locked-in instrument ecosystems, while smaller research institutions drive volume through competitive tendering.
Supply Chain Analysis
Freight costs for temperature-controlled oligonucleotide shipments have intensified margin pressure on European manufacturers serving United States diagnostic markets. Supply concentrates in Germany, Switzerland, and the United States for specialty dye chemistries and synthesis reagents, with raw material flows drawing from petrochemical feedstocks and rare-earth phosphor sources. Single-source vulnerability in high-purity fluorophore production creates structural risk for FISH and qPCR probe manufacturers. Distribution runs through integrated reagent-instrument contracts that bundle consumables with platform placements in consolidated health systems.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The DNA and RNA probes market functions as a stable compounder, with recurring consumable revenue from installed qPCR and sequencing platforms generating predictable cash flows regardless of quarterly instrument placement volatility.
For Market Incumbents: Extend platform lock-in through multi-year reagent supply agreements that bundle probe panels with instrument service contracts, while accelerating ISO 13485 certification for manufacturing sites to defend against emerging Asian suppliers. CRISPR-based detection substitutes threaten hybridization probe volumes in infectious disease screening, making companion diagnostic partnerships with pharmaceutical developers the priority defensive lever. For New Entrants and Emerging Players: Launch via modular panel configurations targeting academic institutions in the United States, where procurement fragmentation and grant-funded budgets enable price undercutting of integrated incumbents. Environmental surveillance applications in Singapore and Australia represent the most penetrable white-space segment, with wastewater pathogen monitoring programs lacking established supplier relationships. For Investors and Strategic Acquirers: Roll-up economics work for specialized oligonucleotide suppliers because regulatory compliance burdens and CLIA validation costs create natural barriers that favor scaled platforms with dedicated quality infrastructure. Target acquisition archetypes include ISO 13485-certified manufacturers serving European diagnostic markets, where EMA's In Vitro Diagnostic Regulation has compressed commercialization timelines and strained smaller competitors. Watch for inflection signals in liquid biopsy test adoption rates at United States academic medical centers, as circulating tumor DNA workflows consume ultra-sensitive probe chemistries at accelerating volumes.| Strategic Initiative | Industry Significance |
|---|---|
| ISO 13485 Manufacturing Scale-Up | Quality certification unlocks regulated diagnostic markets with premium margin profiles. |
| Companion Diagnostic Partnership | FDA submission pathways with pharmaceutical developers secure multi-year revenue commitments. |
| Locked Nucleic Acid Chemistry Expansion | LNA-modified probes enable single-nucleotide discrimination for oncology fusion detection. |
| Environmental Surveillance Panel Development | Multiplexed SARS-CoV-2 variant tracking creates recurring public procurement revenue streams. |
| Integrated Reagent-Instrument Contracting | Platform bundling captures consumable revenue through multi-year supply agreements. |
Study Parameters
Coverage spans the United States, Germany, China, Japan, and Switzerland, with primary inputs from each market combining structured interviews with regulatory affairs directors at probe manufacturers, laboratory operations managers at reference facilities, and procurement leads at academic medical centers. Secondary validation draws from FDA 510(k) filings, EMA In Vitro Diagnostic Regulation guidance documents, CLIA certification databases, and ISO 13485 audit records. Bottom-up probe volume estimates triangulate against top-down market sizing derived from instrument installed base analysis.
Rate-of-change decomposition separates volume expansion from price-mix effects across the analysis window, with segmentation modeling across probe chemistry type, technology platform, application intensity, and end-user purchasing authority. CAGRs derive from weighted average growth trajectories within each segment, incorporating NGS adoption curves, companion diagnostic pipeline maturation, and environmental surveillance program expansion as industry-specific forecast inputs.
Forecast precision tightens around the base case; tail outcomes carry wider variance under scenarios of accelerated CRISPR displacement in infectious disease testing or prolonged fluorophore supply disruptions. Forecasts reflect assumptions regarding regulatory harmonization between FDA and EMA pathways, CLIA laboratory consolidation rates, and pharmaceutical companion diagnostic development timelines. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Diagnostics
India Molecular Diagnostic Controls Market
Diagnostics
Glaucoma Diagnostics Market
Diagnostics
Latent Tuberculosis Infection Detection Market
Diagnostics
Blood Ketone Test Meter Market
Diagnostics
Cellular Health Screening Market
Diagnostics
Digital Companion Diagnostics Market
Diagnostics
Cryptococcal Antigen Lateral Flow Assay Test Market
Diagnostics
Chlamydia Diagnostics Market
Diagnostics
Rapid Oral Fluid Screening Device Market
Diagnostics
Blood Grouping Reagents Market
Diagnostics
Canada Latent Tuberculosis Infection Detection Market
Diagnostics
Global Fecal Occult Blood Tests Market
Diagnostics
Global Blood Culture Tests Market
Diagnostics
Melanoma Cancer Diagnostics Market
Diagnostics
Psychosis Diagnostics Market
Diagnostics
Total Iron Binding Capacity Reagents Market