
 US Platelet Rich Plasma Market | 2026-2036
US Platelet Rich Plasma Market Size, Share, and Industry Trends Forecast 2026-2036
US Platelet Rich Plasma Market Intelligence
Hospital purchasing consortiums and ambulatory surgery center networks are reshaping how PRP collection kits and activation systems reach end users in the United States. Arthrex, Inc. leverages its orthopedic surgeon training infrastructure to sustain high procedural attachment rates for its PRP systems across sports medicine practices. Zimmer Biomet anchors its position through integrated operating room workflows that bundle PRP preparation with existing implant trays. EmCyte Corporation specializes in point-of-care centrifugation devices that compete on processing speed and platelet concentration consistency.
Platelet rich plasma is an autologous blood derivative containing concentrated platelets suspended in plasma, typically achieving platelet counts of 150,000 to 1,000,000 per microliter through density-gradient centrifugation, and functions primarily as a regenerative therapeutic that releases growth factors to accelerate tissue repair. Double spin systems dominate the product type landscape due to superior platelet yield and purity for orthopedic applications, while activation systems capture expanding margin pools as aesthetic practitioners demand standardized gel formulations for facial rejuvenation protocols. The end user base tilts toward ambulatory surgery centers and specialized clinics as these settings optimize throughput for outpatient PRP injections in tendon and wound healing indications.
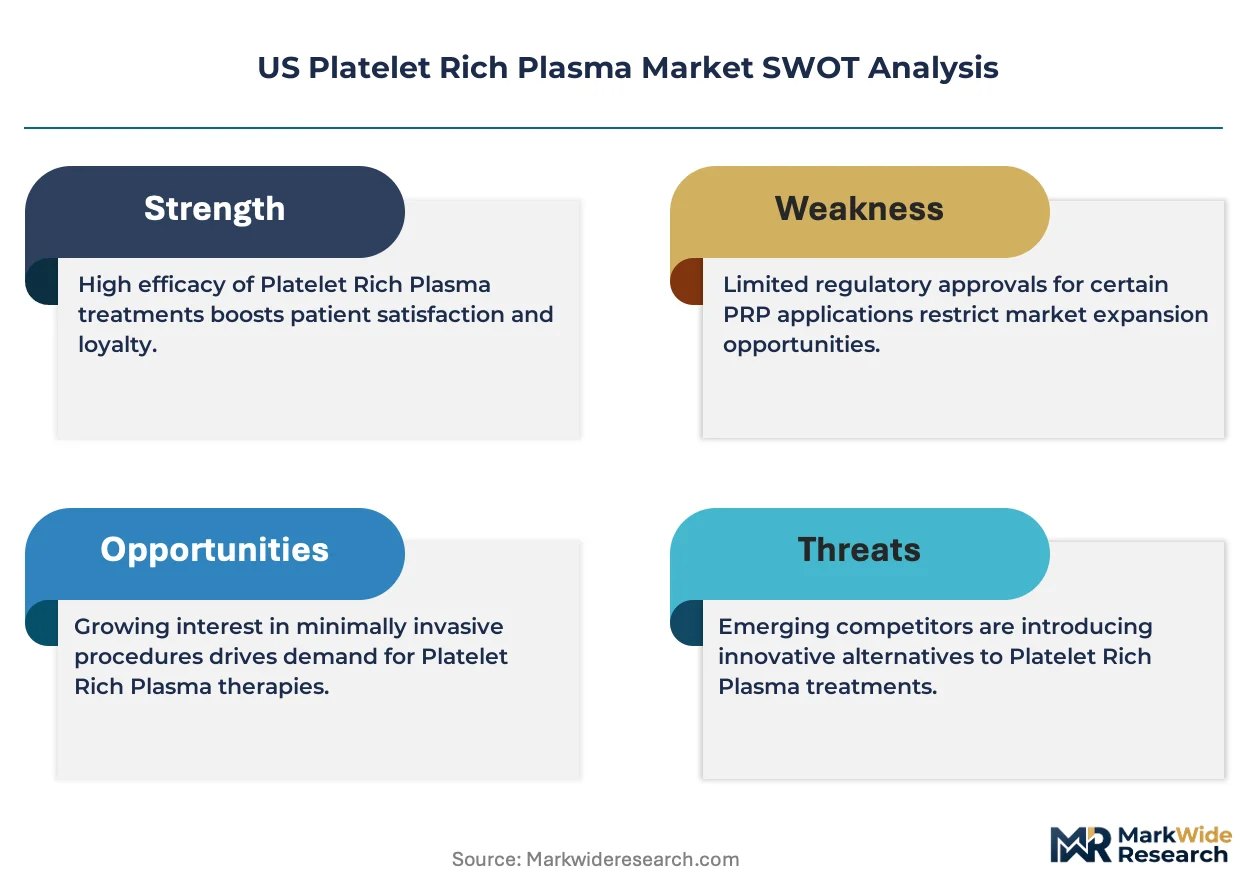
FDA 510(k) clearance requirements and CMS national coverage determination processes govern market access for PRP devices and reimbursement eligibility across the United States. The FDA regulates PRP preparation systems as medical devices while CMS decisions on Category III CPT codes directly shape physician willingness to adopt PRP protocols in Medicare populations. State-level medical board guidelines on scope of practice for nurse practitioners performing PRP injections add another compliance layer that manufacturers must navigate through training and credentialing programs. Stakeholders should monitor upcoming CMS evidence development decisions and emerging state biosimilar regulations that could recategorize certain PRP formulations.
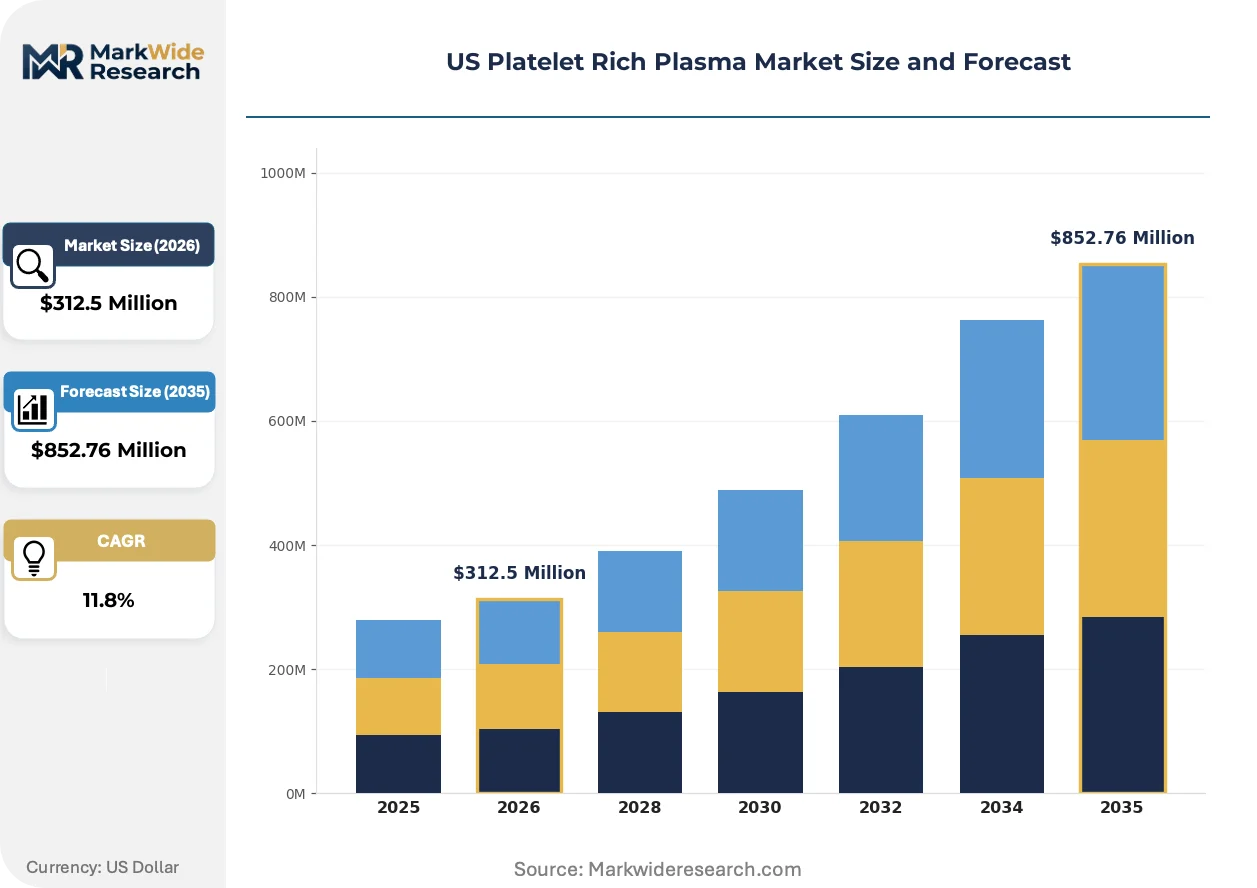
Market Dynamics
CMS national coverage determination processes for Category III CPT codes are compressing reimbursement timelines and forcing manufacturers to front-load clinical evidence generation ahead of physician adoption curves.
Growth Catalysts
- FDA 510(k) clearance pathway:Streamlined device authorization accelerates market entry for centrifugation systems targeting orthopedic surgery suites.
- Ambulatory surgery center expansion:Outpatient procedural volume in Texas, Florida, and California metropolitan corridors drives kit consumption for tendon and wound protocols.
- Autologous biologics integration:Rotator cuff repair protocols at major hospital systems anchor recurring demand for double-spin preparation systems.
Market Restraints
- Input cost volatility:Medical-grade centrifuge components and single-use collection consumables face pricing pressure from polymer supply disruptions.
- Technical standardization gaps:Platelet concentration variability between single-spin and double-spin protocols complicates clinical outcome consistency.
- Substitution threat from synthetic growth factors:Recombinant protein alternatives challenge autologous therapies in aesthetic and wound healing segments.
Strategic Opportunities
- Underpenetrated rural health systems:Community hospitals in the Mountain West and Upper Midwest lack point-of-care PRP infrastructure for sports medicine outreach.
- Technology convergence:Integration of automated cell counters with centrifugation systems enables real-time quality verification during preparation.
- Distribution innovation through GPO consolidation:Premier and Vizient purchasing networks create bundled contracting pathways for multi-hospital system rollouts.
Industry Challenges
- Capex intensity for ASCs:Point-of-care centrifugation devices require substantial upfront investment that strains independent surgery center budgets.
- Compliance timeline compression:State medical board scope-of-practice variations for nurse practitioner injection authority force manufacturer investment in credentialing infrastructure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US Platelet Rich Plasma Market |
| Market Size in 2026 | $312.5 Million |
| Market Size in 2035 | $852.76 Million |
| CAGR (2026 – 2036) | 11.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single Spin, Double Spin, Activation Systems, Collection Kits Application: Orthopedics, Aesthetic Treatments, Wound Healing, Dentistry End User: Hospitals, Clinics, Research Laboratories, Ambulatory Surgery Centers Technology: Centrifugation, Separation Kits, Point-of-Care Devices, Biomaterials |
| Companies Covered | Arthrex, Inc., EmCyte Corporation, Johnson & Johnson Services, Inc., Zimmer Biomet, Stryker, Terumo Corporation, Dr PRP USA LLC, Juventix Regenerative Medical, LLC, Apex Biologix, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US Platelet Rich Plasma Market Strategic Shifts & Innovations
Digital workflow integration and automated quality verification are compressing preparation timelines while regulatory evidence requirements reshape competitive investment priorities.
Closed-system centrifugation technology is virtualizing manual processing steps that previously required technician intervention for platelet concentration verification. Orthopedic surgery departments at academic medical centers are adopting these systems at accelerated rates to standardize output consistency across rotating resident staff. The shift is virtualizing quality control labor and compressing per-procedure preparation costs for high-volume tendon repair protocols.
FDA guidance on 510(k) substantial equivalence for blood processing devices is tightening predicate device requirements for new centrifugation system entrants. Manufacturers must now demonstrate platelet yield parity against established double-spin benchmarks rather than single-spin comparators. Orthopedic-focused device developers in California and Massachusetts are responding by expanding clinical validation cohorts ahead of pre-submission meetings.
Hospital purchasing consortiums are consolidating supplier relationships into multi-year enterprise agreements that bundle PRP preparation systems with orthopedic implant contracts. Independent ambulatory surgery centers are losing negotiating leverage as Premier and Vizient capture larger shares of procedural supply spend. The consolidation is most visible in Texas and Florida where ASC networks face margin pressure from bundled payment models.
US Platelet Rich Plasma Market Segmentation
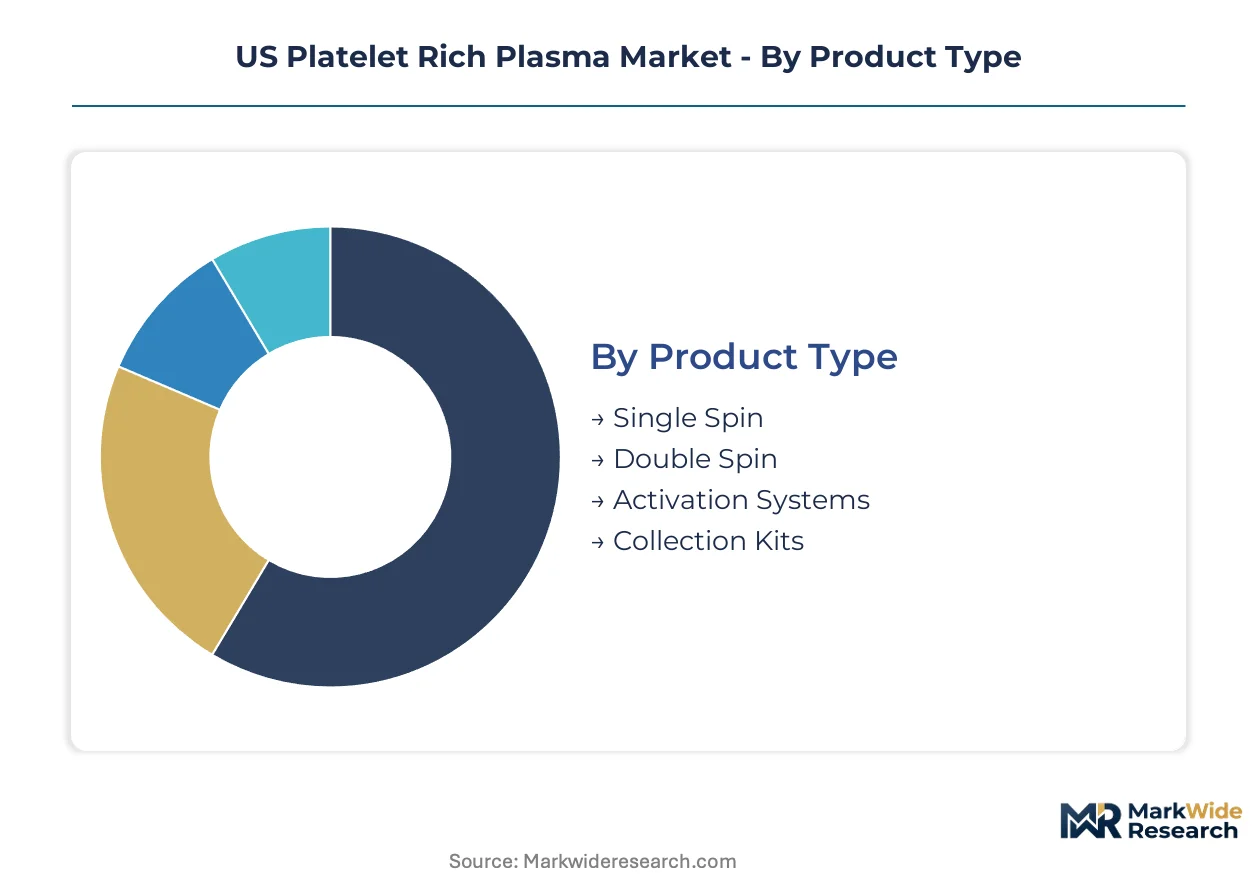
PRP market segmentation reveals divergent equipment lifecycles across preparation technologies and clinical settings. Orthopedic surgery departments and ambulatory surgery centers drive replacement demand at fundamentally different velocities, reshaping manufacturer sales cadences and service contract structures.
Product Type:
Double-spin systems turn over slowest due to capital intensity and validation requirements, while activation systems refresh fastest as aesthetic protocols demand formulation flexibility.
- Double Spin:Density-gradient centrifugation protocols achieve platelet counts of 500,000 to 1,000,000 per microliter through sequential separation cycles. Texas and Florida hospital systems anchor replacement demand as academic medical centers standardize on these systems for rotator cuff repair protocols.
- Activation Systems:Calcium chloride and thrombin-based platelet activation devices convert liquid PRP into gel formulations for localized tissue application. California aesthetic clinics drive the steepest expansion trajectory as facial rejuvenation protocols demand standardized clotting consistency.
- Single Spin:One-cycle centrifugation devices offer lower platelet yield but reduced processing time for high-throughput outpatient settings.
- Collection Kits:Single-use consumables including anticoagulant tubes and transfer syringes require continuous replenishment regardless of capital equipment age.
Double-spin systems dominate installed base. Activation systems are where expansion concentrates.
Application:
Orthopedic indications command premium pricing tiers while aesthetic applications scale through volume-based clinic networks.
- Orthopedics:Tendon repair, ligament reconstruction, and joint preservation procedures utilize PRP for growth factor delivery at injury sites. Major hospital systems in California and Texas integrate autologous biologics into rotator cuff protocols, driving recurring kit consumption.
- Wound Healing:Chronic diabetic ulcers and pressure injuries receive PRP gel applications to accelerate granulation tissue formation. CMS reimbursement deliberations for these indications directly shape physician adoption willingness in Medicare populations.
- Aesthetic Treatments:Facial rejuvenation and hair restoration protocols utilize activated PRP for dermal collagen stimulation.
- Dentistry:Oral surgery and implant integration procedures employ PRP to enhance osseointegration and soft tissue healing.
Orthopedics captures the highest per-procedure revenue. Aesthetic treatments are climbing the fastest.
End User:
Ambulatory surgery centers exhibit the shortest procurement cycles as independent operators compete on procedural throughput metrics.
- Ambulatory Surgery Centers:Outpatient facilities in Texas, Florida, and California metropolitan corridors optimize throughput for tendon injections and minor orthopedic procedures. Bundled payment models from commercial payers compress capital equipment payback timelines.
- Hospitals:Academic medical centers and community hospital systems anchor demand for double-spin systems through orthopedic surgery department budgets. FDA 510(k) clearance requirements govern device selection committees at these institutions.
- Clinics:Sports medicine and aesthetic practices concentrate in suburban healthcare corridors around Dallas, Houston, and Miami.
- Research Laboratories:University-affiliated facilities investigate platelet concentration optimization and novel activation protocols.
Hospitals dominate installed base. Ambulatory surgery centers are gaining share fastest.
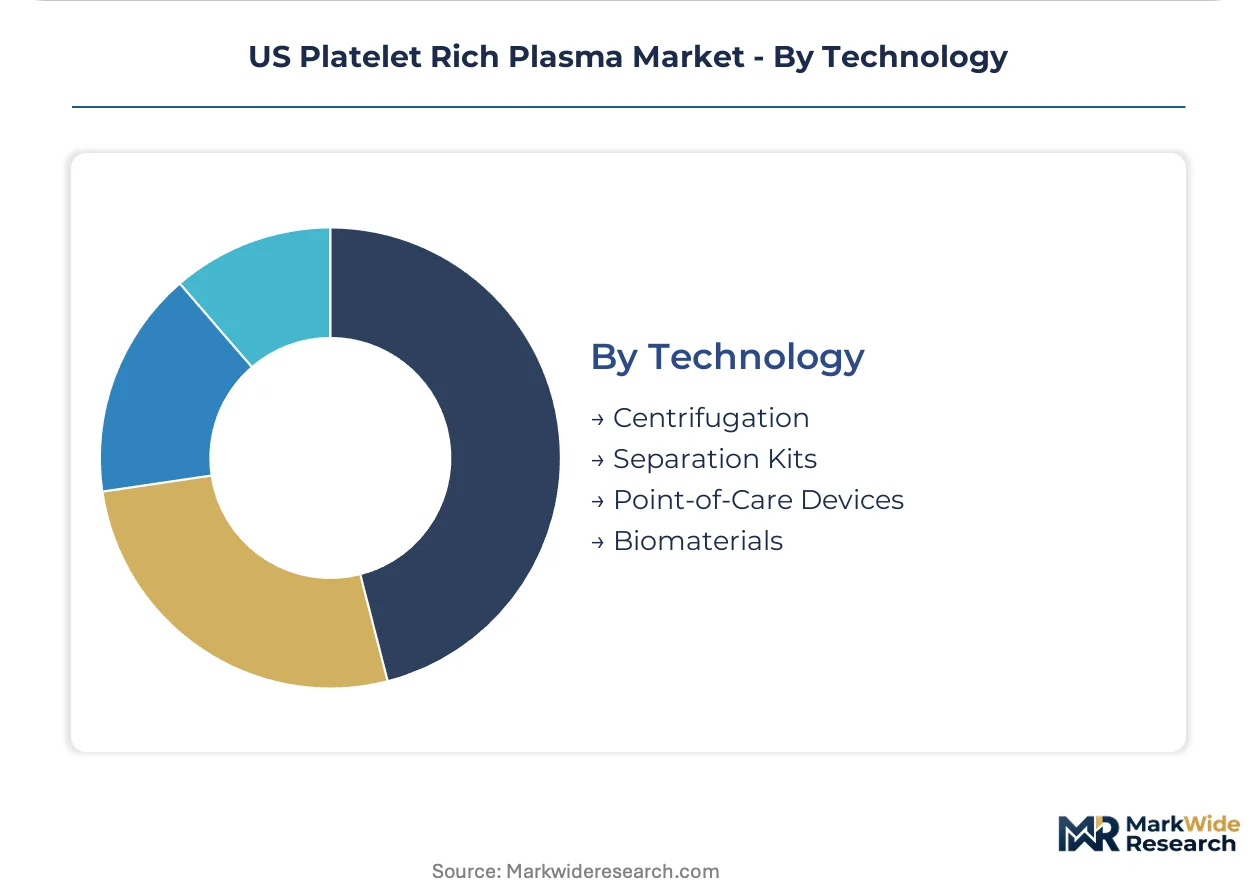
Technology:
Point-of-care devices command margin premiums while separation kits compete on disposability and sterility assurance.
- Centrifugation:Programmable density-gradient systems achieve precise platelet concentration through controlled RPM and duration parameters. Closed-system designs from California and Massachusetts manufacturers are virtualizing manual quality control steps.
- Point-of-Care Devices:Compact centrifugation units enable same-visit preparation without central laboratory processing. Rural health systems in the Mountain West represent underpenetrated demand as these devices reduce infrastructure requirements.
- Separation Kits:Pre-packaged tube sets with anticoagulant and gel density media standardize preparation protocols.
- Biomaterials:Scaffolds and carriers extending PRP retention at application sites.
Centrifugation dominates installed base. Point-of-care devices are where expansion concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Texas and Florida command pricing premiums for PRP collection systems through concentrated ASC networks, while California's aesthetic corridor extracts margin through volume-based activation device contracts.
Texas
Metropolitan Dallas and Houston anchor the nation's densest ambulatory surgery center clusters for orthopedic procedures. FDA 510(k) clearance requirements shape procurement committees at Texas Medical Center-affiliated systems. San Antonio's military medical complexes drive demand for point-of-care centrifugation in sports medicine outreach.
Florida
Miami and Tampa Bay aesthetic clinics consume activation systems at rates exceeding national per-capita averages. State medical board scope-of-practice guidelines for nurse practitioner injections compress manufacturer training timelines. Orlando's hospital purchasing consortiums bundle PRP systems with orthopedic implant contracts.
California
Los Angeles and San Francisco Bay Area academic medical centers standardize on double-spin protocols for rotator cuff repair. CMS national coverage determination processes for Category III CPT codes directly influence physician adoption in Medicare-heavy populations. San Diego's biotech corridor incubates closed-system centrifugation technology developers.
New York Metro
Manhattan and Long Island sports medicine practices concentrate demand for premium-tier preparation systems. State-level biosimilar regulations under development could recategorize certain PRP formulations. Westchester County hospital systems integrate autologous biologics into outpatient tendon repair protocols.
Pacific Northwest
Seattle and Portland represent underpenetrated demand for point-of-care devices in community hospital settings. Rural health systems in the Mountain West lack PRP infrastructure for sports medicine outreach. Washington state's medical device tax structure influences capital equipment procurement cycles.
US Platelet Rich Plasma Market Key Industry Players
Platform integrators command the system tier; component specialists sit upstream in consumables and activation chemistry. The vendor base stratifies between orthopedic-focused device developers and aesthetic-oriented formulation suppliers. Three archetypes dominate: integrated operating room workflow bundlers, point-of-care centrifugation specialists, and activation system formulators. Competitive moves concentrate on GPO contracting consolidation and clinical evidence generation ahead of CMS reimbursement decisions.
Within the orthopedic workflow tier, Arthrex, Inc. and Zimmer Biomet represent platform integrators that anchor system-level contracts through surgeon training infrastructure and implant tray bundling. EmCyte Corporation exemplifies the point-of-care specialist archetype, occupying a position centered on processing speed and platelet concentration consistency for high-throughput settings. These three entities collectively illustrate how competitive positioning in the US PRP market depends on either capturing the operating room workflow or optimizing the preparation timeline.
| Leading Market Players |
|---|
| Arthrex, Inc. |
| EmCyte Corporation |
| Johnson & Johnson Services, Inc. |
| Zimmer Biomet |
| Stryker |
| Terumo Corporation |
| Dr PRP USA LLC |
| Juventix Regenerative Medical, LLC |
| Apex Biologix |
| Others |
Cost & Logistics Intelligence
Medical-grade polymer supply disruptions determine both the premium spread between double-spin and single-spin systems and the geographic clustering of manufacturing capacity. This feedstock volatility compresses margins for consumable-dependent business models while rewarding closed-system device developers with captive component sourcing.
Pricing Analysis
The customization-premium spread separates configured-to-order double-spin systems from standard single-spin platforms. Three-tier pricing structure across premium, standard, and economy levels reflects FDA 510(k) clearance tier, platelet concentration consistency, and after-sales training bundling. Price erosion runs through the single-spin tier as California and Texas ASCs negotiate volume-based kit contracts. Ambulatory surgery centers exhibit the highest price sensitivity; academic medical centers prioritize outcome validation over unit cost.
Supply Chain Analysis
Upstream feedstock for medical-grade centrifuge housings and anticoagulant-coated tubes draws from Germany, China, and domestic US polymer processors. Critical inputs include polycarbonate resins, silicone gaskets, and sodium citrate anticoagulant formulations. Single-source vulnerability concentrates in specialty gel density media sourced from a limited German chemical supplier base. Distribution runs through Premier and Vizient GPO networks that bundle PRP systems with orthopedic implant contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation across state-level scope-of-practice regulations creates niche opportunities for credentialing-focused service providers and point-of-care device specialists. The demand-side shift toward outpatient tendon protocols in ASC networks generates white-space for preparation speed optimization.
For Market Incumbents: Harden GPO contract exclusivity through multi-year enterprise agreements that embed training infrastructure. Deepen backward integration into anticoagulant tube manufacturing to offset polymer cost volatility. Defend against EmCyte-style point-of-care specialists by accelerating automated quality verification roadmaps. For New Entrants and Emerging Players: Establish a beachhead in rural Mountain West health systems lacking PRP infrastructure for sports medicine outreach. Target community hospital systems in the Upper Midwest with compact centrifugation units requiring minimal capital outlay. Lead with same-visit preparation speed as the primary go-to-market angle against incumbent double-spin workflows. For Investors and Strategic Acquirers: CMS national coverage determination for Category III CPT codes reshapes the acquisition landscape by elevating clinical evidence generators above device-only plays. Long-term viability centers on platform integrators with surgeon training ecosystems rather than component suppliers. Target acquisition archetype: point-of-care specialists with FDA-cleared automated cell counting modules. The signal to watch is state medical board expansions of nurse practitioner injection authority that accelerate addressable market growth.| Strategic Initiative | Industry Significance |
|---|---|
| Closed-System Centrifugation Development | California and Massachusetts developers virtualize manual quality control steps for academic medical center standardization. |
| CMS Reimbursement Strategy Investment | Clinical evidence generation ahead of national coverage determination compresses physician adoption timelines in Medicare populations. |
| GPO Consolidation Participation | Premier and Vizient bundled contracting pathways lock out independent ASCs from competitive supplier access. |
| Point-of-Care Device Miniaturization | Mountain West rural health system penetration reduces infrastructure barriers for outpatient sports medicine protocols. |
| Activation System Formulation Expansion | California aesthetic clinic networks demand standardized gel consistency for facial rejuvenation volume scaling. |
Research Approach
A standing panel of orthopedic surgeons, ASC operations directors, GPO contracts managers, and biomedical engineers provided ongoing calibration across the study period. Primary interviews with these stakeholders combined with secondary validation against FDA 510(k) clearance databases, CMS Medicare reimbursement filings, and hospital procurement system records. Bottom-up demand modeling from kit consumption data triangulated against top-down market sizing from device manufacturer revenue disclosures.
Scenario-bracketing framed optimistic, baseline, and conservative trajectories across the projection horizon without year-specific anchoring. Segmentation dimensions modeled include preparation technology type, end-user facility category, clinical application indication, and geographic metropolitan corridor. CAGRs were derived from fitted growth curves against historical adoption velocity in comparable autologous biologic markets. Forecast inputs incorporated CMS evidence development timelines and state-level scope-of-practice regulatory momentum.
Stress conditions across polymer supply disruption severity, CMS reimbursement denial probability, and synthetic growth factor substitution rates were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding physician training cycle durations and ASC capital expenditure recovery timelines. Cross-checking against hospital purchasing consortium contract disclosure patterns is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Regenerative Medicine
Dural Graft Market
Regenerative Medicine
Autologous Fat Grafting Market
Regenerative Medicine
Personalized Immunotherapy Market
Regenerative Medicine
North America Longevity and Anti-Senescence Therapy Market
Regenerative Medicine
Global Vaginal Rejuvenation Market
Regenerative Medicine
Autologous Matrix Induced Chondrogenesis Market
Regenerative Medicine
Global Breast Reconstruction Market
Regenerative Medicine
Bioelectric Medicine Market
Regenerative Medicine
Longevity and Anti-Senescence Therapy for Cancer Market
Regenerative Medicine
Tenosynovial Giant Cell Tumor Treatment Market
Regenerative Medicine
Platelet Rich Plasma Market
Regenerative Medicine
Tumour-Induced Osteomalacia Market
Regenerative Medicine
North America Regenerative Medicines Market
Regenerative Medicine
US Scar Treatment Market
Regenerative Medicine
Orthopedic Regenerative Medicine Market
Regenerative Medicine
Tooth Regeneration Market