
 Dural Graft Market | 2026-2036
Dural Graft Market Size, Share, and Industry Trends Forecast 2026-2036
Dural Graft Market Insights
Modular graft kits that pair dural substitutes with fixation accessories are rebalancing procurement patterns among hospital buyers. Integra LifeSciences Corporation leverages its regenerative tissue portfolio to anchor premium positioning in neurosurgical suites. Baxter International Inc. sustains broad geographic reach through its established hospital distribution infrastructure. Medtronic plc dominates the high-volume trauma channel with integrated dural closure systems.
A dural graft is a biocompatible implant used to repair or replace the dura mater following neurosurgical or spinal procedures where the native membrane is damaged or resected; synthetic polymer variants typically employ expanded polytetrafluoroethylene layers measuring 0.1 to 0.4 millimeters in thickness to achieve watertight closure while minimizing inflammatory response. Collagen-based grafts lead the material segment due to established reimbursement pathways and surgeon familiarity with resorption profiles, whereas tissue-engineered products represent the fastest-growing category as biofabrication advances reduce batch variability. Neurosurgery anchors application demand, but spinal surgery generates disproportionate margin expansion as complex deformity cases require larger graft surface areas and specialized configurations.
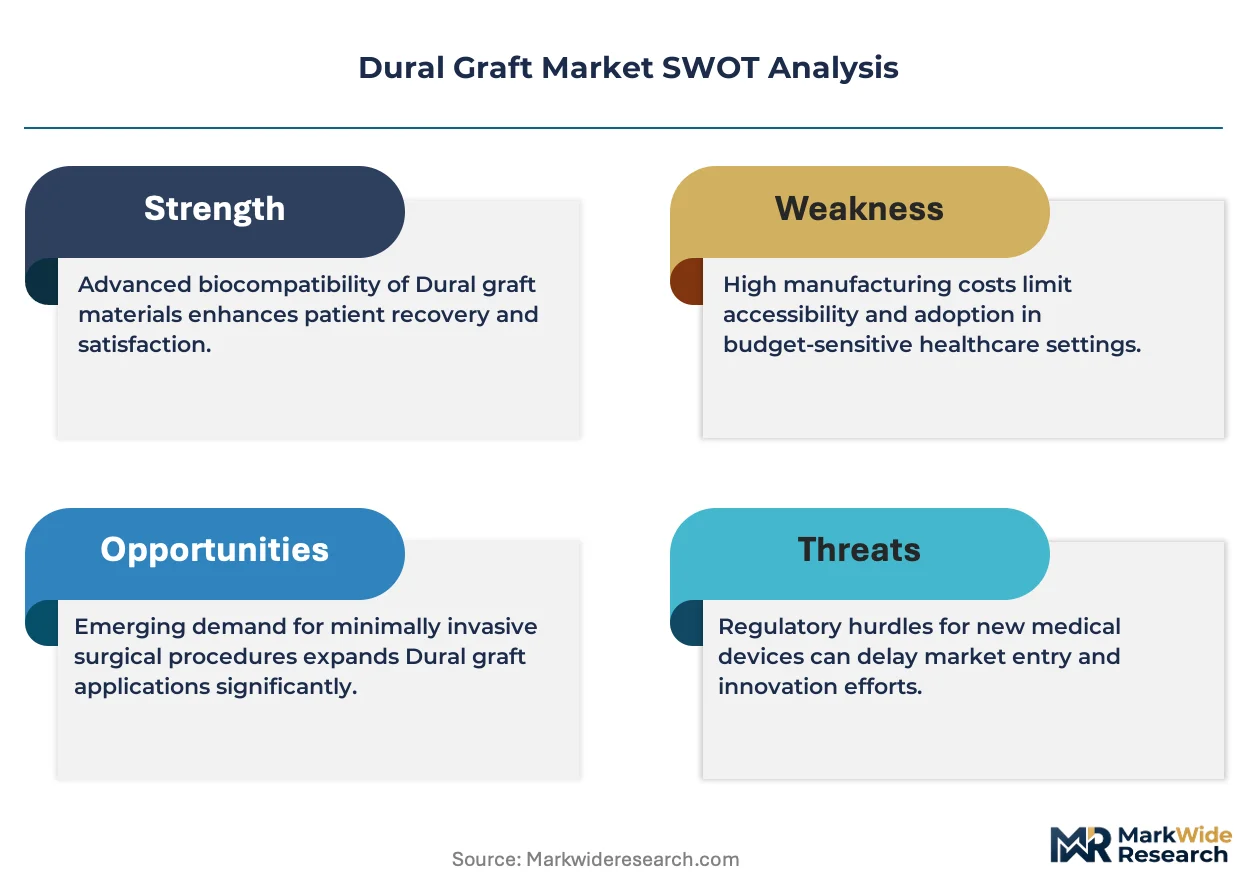
The FDA enforces Class II medical device controls with 510(k) premarket notification requirements for synthetic dural grafts, while the EMA's Medical Device Regulation mandates clinical evidence dossiers that extend market access timelines for European commercialization. ISO 10993 biocompatibility testing frameworks govern cytotoxicity and sensitization protocols that manufacturers must complete before regulatory submission. Stakeholders should monitor evolving reimbursement thresholds for tissue-engineered grafts against established collagen benchmarks.
Market Dynamics
Surgeon preference for watertight closure systems is compressing the addressable market for standalone dural patches, forcing manufacturers to bundle fixation hardware with membrane substrates to retain procurement access in consolidated hospital networks.
Growth Catalysts
- Craniotomy volume expansion:Tertiary hospital neurosurgery departments in the United States report rising case volumes for tumor resection and trauma intervention, driving consistent demand for dural replacement materials.
- ISO 10993 harmonization:Standardized biocompatibility testing protocols reduce regulatory friction for collagen-based graft submissions across multiple jurisdictions, accelerating manufacturer entry timelines.
- Biofabrication maturation:Tissue-engineered graft production is stabilizing batch-to-batch consistency, narrowing the performance gap with established allogenic sources and qualifying these products for broader reimbursement.
Market Restraints
- Bovine collagen supply concentration:Raw material sourcing for xenogenic grafts clusters in specific agricultural regions, exposing manufacturers to zoonotic disease screening disruptions and herd availability volatility.
- FDA 510(k) pathway density:Predicate device saturation for synthetic polymer grafts extends FDA review timelines as manufacturers struggle to demonstrate substantial equivalence against an expanding base of cleared alternatives.
- Autologous tissue harvesting persistence:Pericranium and fascia lata grafts remain viable zero-cost substitutes in resource-constrained settings, capping price elasticity for commercial products in emerging markets.
Strategic Opportunities
- Spinal deformity surgery penetration:Complex scoliosis and revision fusion procedures require larger graft surface areas, creating margin expansion potential for specialized configurations beyond standard neurosurgical dimensions.
- Japan's PMDA regenerative medicine framework:Accelerated approval pathways for tissue-engineered products reduce time-to-market for biofabricated dural substitutes targeting the Asia-Pacific region's aging surgical population.
- Integrated closure system bundling:Pairing dural membranes with suture clips and sealant adjuncts captures procurement budgets previously allocated to separate device categories, anchoring vendor relationships.
Industry Challenges
- Surgeon retraining requirements:Adoption of synthetic polymer grafts with distinct handling characteristics demands dedicated proctoring programs, straining medical education resources at high-volume centers.
- EMA MDR technical documentation:Clinical evidence dossier requirements for European market access extend preparation cycles by 18-24 months, compressing effective patent life for novel graft formulations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Dural Graft Market |
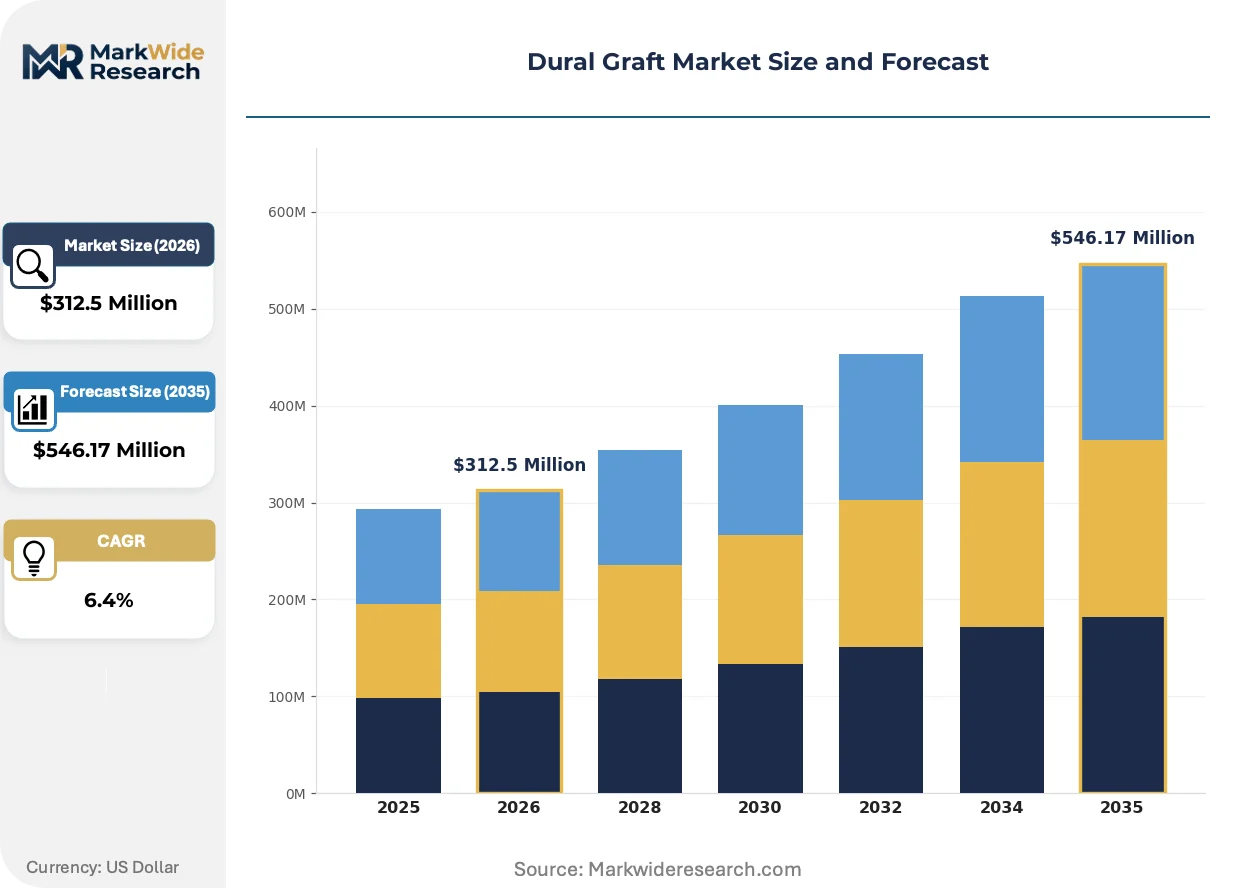
| Market Size in 2026 | $312.5 Million |
| Market Size in 2035 | $546.17 Million |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Artificial Dura, Autologous Dura, Allogenic Dura, Xenograft Dura Application: Neurosurgery, Spinal Surgery, Trauma Cases, Reconstruction Procedures Material: Collagen-based, Synthetic Polymers, Bioabsorbable Materials, Tissue-engineered Products End User: Hospitals, Surgical Clinics, Research Institutes, Specialty Centers |
| Companies Covered | B. Braun Melsungen AG, Cook Medical, Integra LifeSciences Corporation, W. L. Gore & Associates, Inc., Baxter International Inc., Medtronic plc, Johnson & Johnson, Zimmer Biomet Holdings, Inc., Stryker Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Dural Graft Market Trends and Innovations
Material science advances and regulatory pathway evolution are reconfiguring competitive positioning in dural graft supply. Manufacturers now compete on closure system integration rather than membrane performance alone.
Electrospun nanofiber scaffolds is absorbing development investment from established collagen processors seeking to match the porosity control of synthetic competitors. Neurosurgical suites at academic medical centers are piloting these substrates for complex posterior fossa reconstructions where cerebrospinal fluid leakage risk is highest. The technology is absorbing market share from woven collagen sheets by offering tunable degradation rates that align with native dura regeneration timelines.
REACH Annex XVII restrictions on perfluorinated compounds are compelling synthetic graft manufacturers to reformulate ePTFE processing aids and validate alternative chemistries for European commercialization. Industrial consequence includes extended biocompatibility retesting for existing product lines. Small-diameter synthetic graft variants face the steepest compliance burden, as these configurations rely most heavily on the affected processing technologies.
Hospital procurement committees are consolidating vendor contracts for dural closure systems, displacing the fragmented purchasing patterns that previously allowed multiple graft suppliers to coexist within single institutions. Integrated delivery networks in the United States are negotiating multi-year sole-source agreements that bundle membrane, fixation, and sealant components. This concentration is most visible in the Midwest, where regional health system mergers have reduced the number of independent purchasing entities by half over the past decade.
Dural Graft Market Segmentation
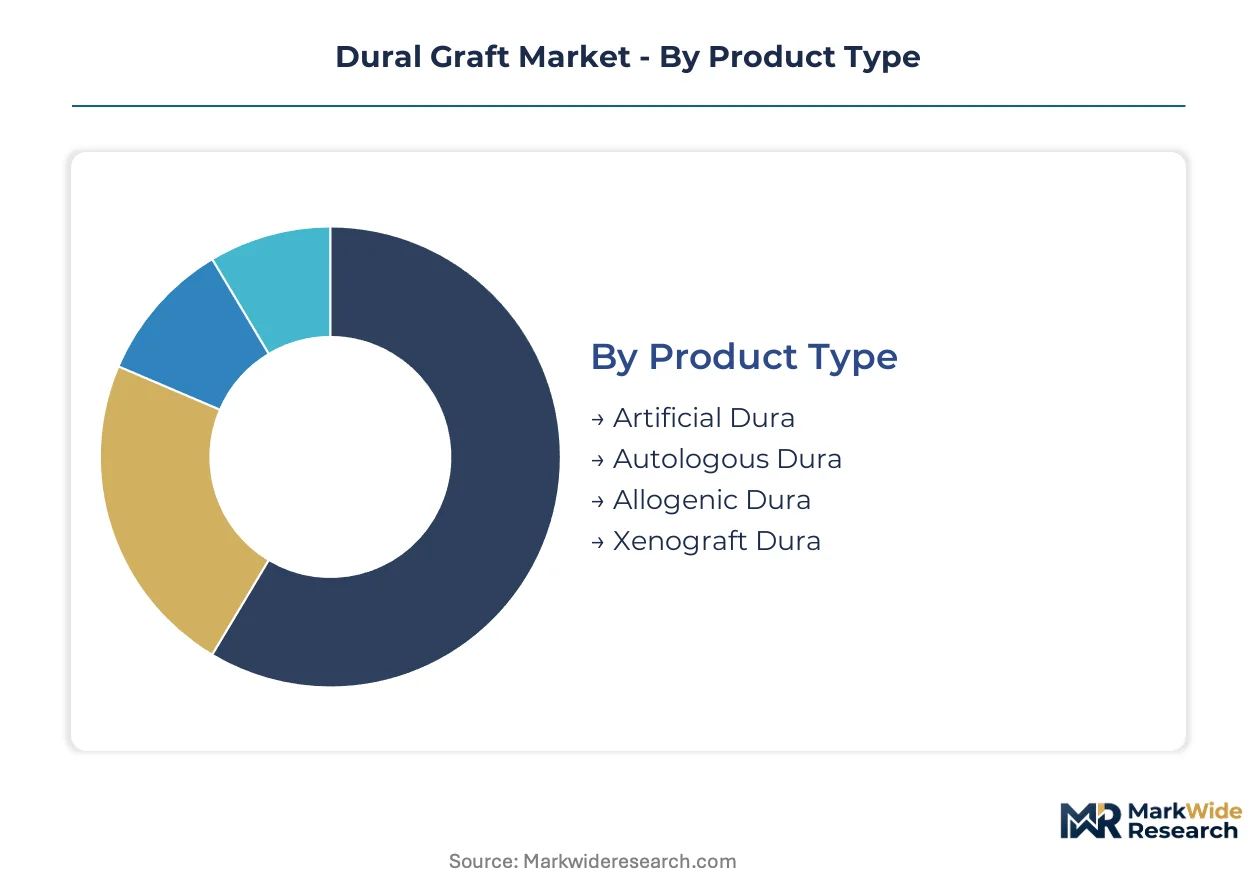
Dural graft segmentation reveals divergent capital requirements across material platforms and procurement channels. Manufacturers align R&D budgets with the clinical validation burdens specific to each product category.
Product Type:
Capital intensity peaks with synthetic polymer manufacturing lines requiring cleanroom infrastructure and precision extrusion systems.
- Artificial Dura:Expanded polytetrafluoroethylene layers demand specialized sintering equipment and sub-micron thickness control. United States neurosurgical suites at tertiary hospitals absorb the highest volumes as craniotomy procedures accelerate. FDA 510(k) clearance pathways extend development timelines for novel polymer formulations.
- Autologous Dura:Harvested pericranium or fascia lata requires minimal processing infrastructure, shifting capital burden to surgical training and harvesting tool sterilization protocols. Demand clusters in resource-constrained settings where procurement budgets limit commercial product adoption.
- Allogenic Dura:Cadaveric tissue sourcing depends on specialized procurement networks and pathogen screening laboratories.
- Xenograft Dura:Bovine and porcine collagen processing requires dedicated decellularization facilities and viral inactivation validation.
Most installed capacity flows through Artificial Dura. Expansion is steepest in Xenograft Dura.
Application:
Procedure complexity determines margin structure, with multi-level spinal reconstructions commanding premium pricing over standard neurosurgical closures.
- Neurosurgery:Tumor resection and posterior fossa procedures drive baseline demand for watertight dural closure. United States academic medical centers anchor procurement volumes through specialized neurological service lines. Surgeon preference for integrated fixation systems is compressing standalone graft margins.
- Spinal Surgery:Complex deformity corrections require larger graft surface areas and specialized configurations. Scoliosis fusion cases at dedicated orthopedic centers generate disproportionate revenue per procedure.
- Trauma Cases:Emergency craniotomy volumes fluctuate with regional trauma network density and motor vehicle incident rates.
- Reconstruction Procedures:Revision surgeries and congenital defect repairs demand customized graft geometries.
Revenue concentration sits with Neurosurgery. Margin expansion is most pronounced in Spinal Surgery.
Material:
Biocompatibility testing requirements stratify development costs, with tissue-engineered platforms demanding the most extensive clinical evidence packages.
- Collagen-based:Established xenogenic and allogenic collagen sheets dominate procurement through reimbursement familiarity and predictable resorption profiles. Hospital formularies in the United States prioritize these products for routine neurosurgical applications. ISO 10993 testing frameworks govern cytotoxicity validation.
- Synthetic Polymers:ePTFE and polyurethane variants offer tunable degradation rates and mechanical strength. REACH Annex XVII compliance costs are compelling European manufacturers to reformulate processing chemistries.
- Bioabsorbable Materials:Polylactic acid and polyglycolic acid copolymers require controlled hydrolysis validation.
- Tissue-engineered Products:Electrospun nanofiber scaffolds and biofabricated membranes represent the steepest expansion trajectory as batch consistency improves.
Procurement volume concentrates in Collagen-based. Technology investment is heaviest in Tissue-engineered Products.
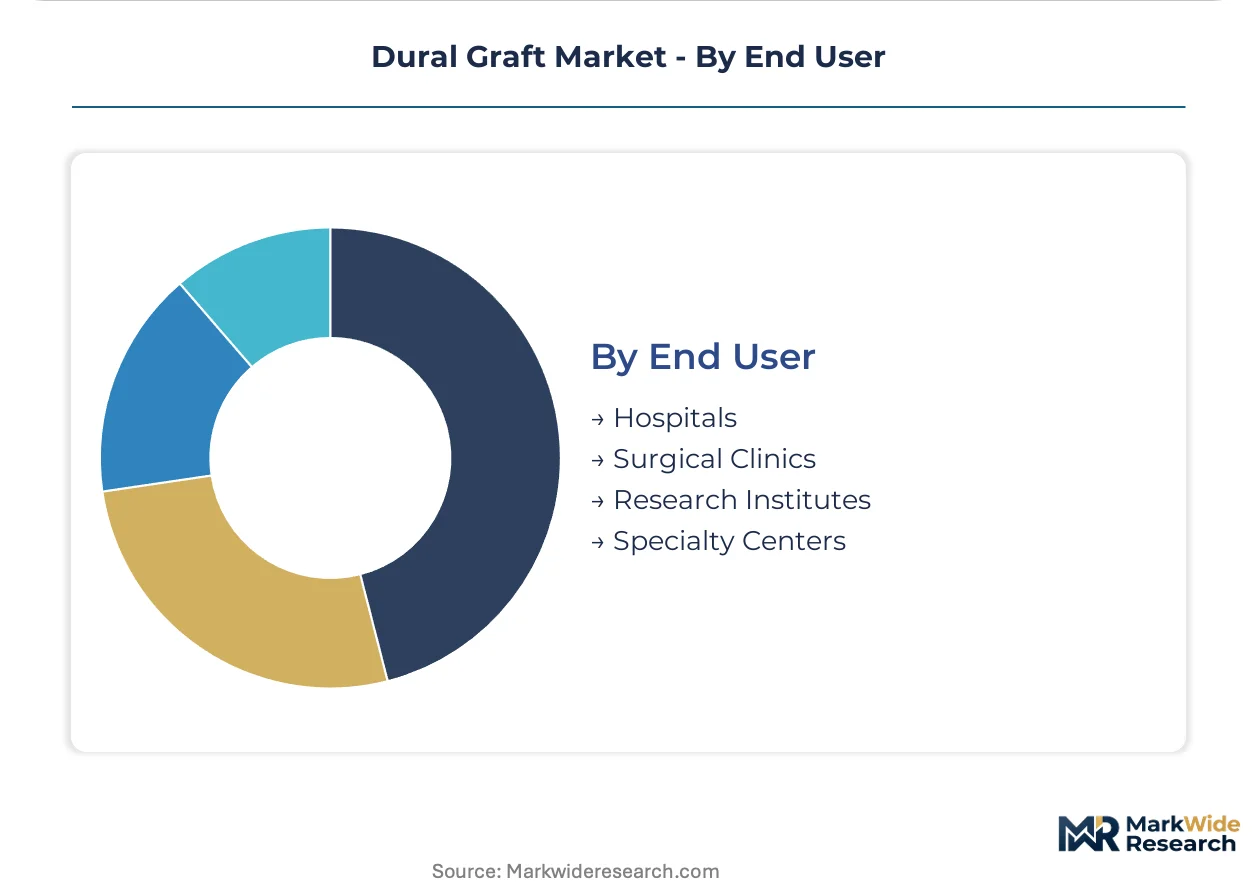
End User:
Purchasing authority distribution shapes vendor access, with consolidated hospital networks exercising greater price leverage than independent surgical clinics.
- Hospitals:Integrated delivery networks negotiate multi-year sole-source agreements bundling membranes, fixation hardware, and sealants. Midwest United States health system mergers have halved independent purchasing entities over the past decade.
- Surgical Clinics:Ambulatory surgical centers with limited neurosurgical caseloads favor lower-cost xenograft options.
- Research Institutes:Academic medical centers pilot novel electrospun scaffolds and tissue-engineered platforms.
- Specialty Centers:Dedicated neurological and spinal institutes maintain direct manufacturer relationships.
Contract value is largest through Hospitals. Relationship access is most direct at Specialty Centers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Dural graft manufacturing originated in the United States during the 1970s with the commercialization of synthetic polymer membranes for neurosurgical applications. The industry's geographic footprint now spans specialized medical device clusters across North America, Europe, and Asia-Pacific, with regulatory harmonization efforts reshaping market access patterns.
United States
Tertiary hospital neurosurgery departments in Boston, Baltimore, and Houston drive procurement volumes for craniotomy and trauma procedures. The FDA's 510(k) premarket notification pathway governs synthetic graft clearances, with predicate device saturation extending review timelines for novel formulations. The Minneapolis-St. Paul corridor anchors manufacturing concentration for collagen-based and synthetic polymer platforms.
Germany
Academic medical centers in Munich and Heidelberg pilot electrospun nanofiber scaffolds for complex posterior fossa reconstructions. The EMA's Medical Device Regulation mandates clinical evidence dossiers that extend preparation cycles by 18-24 months, compressing effective patent life. The Baden-Württemberg region hosts specialized cleanroom infrastructure for precision extrusion of ePTFE layers.
Japan
Aging surgical populations in Tokyo and Osaka generate demand for tissue-engineered dural substitutes with predictable resorption profiles. The PMDA's regenerative medicine framework offers accelerated approval pathways for biofabricated products, reducing time-to-market relative to conventional device routes. The Kansai region concentrates decellularization facility investment for xenogenic collagen processing.
Switzerland
Specialized neurological institutes in Zurich and Geneva sustain premium procurement for integrated closure systems bundling membranes with fixation hardware. Swissmedic enforces ISO 10993 biocompatibility protocols that align with REACH Annex XVII chemical restrictions. The Basel cluster supports viral inactivation validation laboratories serving European manufacturers.
China
Provincial hospital networks in Shanghai and Beijing expand craniotomy capacity for tumor resection cases. The NMPA's Class III medical device registration requirements demand domestic clinical trials for imported graft products. The Yangtze River Delta concentrates contract manufacturing for bovine collagen sourcing and decellularization.
Dural Graft Market Competitive Landscape
Premium-margin players sit above commodity-margin players across material technology and closure system integration. The market structure consolidates around three to five integrated manufacturers with full portfolio coverage, while mid-scale specialists occupy niche material segments. Strategic archetypes include diversified medical device conglomerates with neurosurgical suites, regenerative tissue pure-plays with collagen expertise, and synthetic polymer specialists with precision extrusion capabilities. Competitive moves center on multi-year sole-source procurement contracts with consolidated hospital networks and backward integration into raw material sourcing.
Among diversified medical device conglomerates, Medtronic plc and Stryker Corporation exemplify scale-driven positioning through established hospital distribution infrastructure and trauma channel dominance. Integra LifeSciences Corporation occupies a specialist tier focused on regenerative tissue platforms. Baxter International Inc. represents geographic breadth through integrated delivery network relationships. W. L. Gore & Associates, Inc. anchors synthetic polymer expertise with precision materials science heritage.
| Leading Market Players |
|---|
| B. Braun Melsungen AG |
| Cook Medical |
| Integra LifeSciences Corporation |
| W. L. Gore & Associates, Inc. |
| Baxter International Inc. |
| Medtronic plc |
| Johnson & Johnson |
| Zimmer Biomet Holdings, Inc. |
| Stryker Corporation |
| Others |
Pricing and Supply Chain Analysis
Backward integration into bovine collagen sourcing and decellularization infrastructure anchors both supply security and pricing power for xenograft manufacturers serving United States hospital networks. This captive supply of raw biological material insulates premium-tier producers from herd availability volatility while supporting margin defense against synthetic polymer competitors.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels governs procurement negotiations between manufacturers and consolidated hospital buyers. Price differentiation rests on ISO 10993 certification tier and integrated fixation system bundling rather than membrane performance alone. Cost compression in the standard tier is intensifying because integrated delivery networks are consolidating vendor contracts across Midwest health systems. Ambulatory surgical centers exhibit highest price sensitivity due to limited neurosurgical caseloads, while academic medical centers prioritize certification tier over unit cost.
Supply Chain Analysis
Single-source vulnerability sits with United States-based bovine collagen processors that dominate decellularization capacity for xenogenic graft production. Raw material sourcing draws from dedicated agricultural regions in the Midwest and Southwest, with viral inactivation validation laboratories concentrated in the Minneapolis-St. Paul corridor. Regulatory restriction through REACH Annex XVII compliance costs for ePTFE processing aids creates supply friction for European market access. Distribution runs through established hospital distribution infrastructure anchored by specialized neurological service lines at tertiary centers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The dural graft market functions as a stable compounder anchored by rising craniotomy volumes in aging populations and the irreplaceable nature of watertight dural closure in neurosurgical outcomes.
For Market Incumbents: Cement procurement access through multi-year sole-source agreements with consolidated hospital networks that bundle membranes, fixation hardware, and sealant adjuncts. Deepen backward integration into bovine collagen sourcing to defend margin position against synthetic polymer substitutes. Prioritize ISO 10993 certification maintenance as regulatory scrutiny intensifies across European and Asia-Pacific jurisdictions. For New Entrants and Emerging Players: Begin with tissue-engineered platforms targeting Japan's PMDA regenerative medicine accelerated approval pathway, where biofabrication advances narrow the performance gap with established allogenic sources. Complex spinal deformity surgery in dedicated orthopedic centers offers the most penetrable application segment due to larger graft surface area requirements and less entrenched supplier relationships. Pursue direct clinical validation partnerships with academic medical centers piloting electrospun nanofiber scaffolds. For Investors and Strategic Acquirers: Consolidation pressure builds where mid-scale specialists lack the capital intensity to complete cleanroom infrastructure for synthetic polymer manufacturing lines or decellularization facilities for xenogenic processing. The market supports long-term viability framing around regenerative medicine platform consolidation and closure system integration. Target acquisition archetypes include collagen processing pure-plays with established FDA 510(k) predicate devices and electrospun scaffold developers with academic center validation. Watch for inflection where tissue-engineered grafts achieve reimbursement parity with collagen benchmarks.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Submission | Predicate device saturation extends review timelines for novel polymer formulations seeking neurosurgical clearance. |
| CE Marking Pathway | EMA MDR clinical evidence dossiers compress effective patent life by 18-24 months for European commercialization. |
| Hospital System Partnership | Integrated delivery network sole-source agreements displace fragmented purchasing patterns across Midwest mergers. |
| Backward Integration | Captive bovine collagen sourcing insulates manufacturers from zoonotic disease screening disruptions and herd volatility. |
| Reimbursement Strategy | Tissue-engineered graft qualification for broader coverage requires batch consistency validation against collagen benchmarks. |
Research Methodology
Bottom-up neurosurgical procedure modeling reconciled against top-down hospital procurement tracking forms the analytical core of this study. Primary interviews with neurosurgeons, hospital purchasing committee chairs, biomedical engineers, and GPO contracts managers were combined with secondary validation from FDA 510(k) filings, EMA MDR submission databases, hospital procurement records, and CMS Medicare reimbursement data. Triangulation between demand-side procedure volumes and supply-side manufacturer capacity ensures statistical integrity across market size estimation.
Historical trendline analysis of craniotomy and spinal surgery volumes established baseline growth parameters across the projection horizon. Segmentation modeling incorporated material platform, application type, end-user channel, and regional regulatory cluster dimensions. CAGRs were derived from procedure volume elasticity against demographic aging patterns and technology substitution curves. Industry-specific forecast inputs included biofabrication batch consistency improvement rates and integrated delivery network consolidation trajectories.
Several conditions sit outside the modeled scope, including unforeseen zoonotic disease outbreaks affecting bovine collagen supply, radical shifts in autologous tissue harvesting preference, and regulatory pathway reclassification for tissue-engineered products. Forecasts reflect documented assumptions regarding reimbursement stability and surgeon training adoption curves. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Regenerative Medicine
Global Breast Reconstruction Market
Regenerative Medicine
Cytokine Storm Therapy Market
Regenerative Medicine
Hyper Personalized Medicine Market
Regenerative Medicine
Asia-Pacific Regenerative Medicine Market
Regenerative Medicine
Personalized Immunotherapy Market
Regenerative Medicine
Bone Regeneration Market
Regenerative Medicine
US Scar Treatment Market
Regenerative Medicine
Epidermal Cell Sheets Market
Regenerative Medicine
North America Longevity and Anti-Senescence Therapy Market
Regenerative Medicine
Next Generation Immunotherapies Market
Regenerative Medicine
Global Cartilage Repair-Cartilage Regeneration Market
Regenerative Medicine
Asia Pacific Platelet Rich Plasma Market
Regenerative Medicine
US Regenerative Medicine Market
Regenerative Medicine
Platelet Rich Plasma Market
Regenerative Medicine
Degenerative Disc Disease Treatment Market
Regenerative Medicine
Hypertrophic and Keloid Scar Treatment Market