
 Personalized Immunotherapy Market | 2026-2036
Personalized Immunotherapy Market Size, Share, and Industry Trends Forecast 2026-2036
Personalized Immunotherapy Market Analytics
Synthetic mRNA is broadening payload economics in personalized immunotherapy by displacing viral vector dependency in neoantigen vaccine production. Novartis AG sustains vertical integration across CAR-T manufacturing from leukapheresis to cryogenic distribution. Bristol-Myers Squibb Company dominates checkpoint inhibitor combinations through its nivolumab platform and companion diagnostic alliances. BioNTech positions its individualized neoantigen therapeutics pipeline toward solid-tumor expansion beyond established melanoma and colorectal programs.
Personalized immunotherapy encompasses patient-specific therapeutic interventions engineered from autologous or allogeneic biological material, including tumor-infiltrating lymphocytes, chimeric antigen receptor T-cells, and peptide-based neoantigen vaccines synthesized through next-generation sequencing and bioinformatic prediction algorithms. These modalities target malignancies by redirecting polyclonal immune recognition against patient-unique tumor mutations rather than shared antigens. CAR-T therapy leads product type revenue pools in hematologic indications while checkpoint inhibitors capture the broadest addressable patient base across solid tumors. Oncology clinics represent the fastest-growing end user channel as infusion capacity decentralizes from academic medical centers toward community-based delivery networks.
The FDA's Breakthrough Therapy Designation and Regenerative Medicine Advanced Therapy designation compress review timelines for autologous cell products, while the EMA's PRIME scheme accelerates European market access for academic spinouts. ISO 14644 cleanroom standards and WHO Good Manufacturing Practice guidelines for cellular products govern facility qualification and batch release across manufacturing sites. Stakeholders must monitor evolving pharmacovigilance requirements for long-term patient follow-up as durable remission data reshape reimbursement thresholds and competitive differentiation.
Market Dynamics
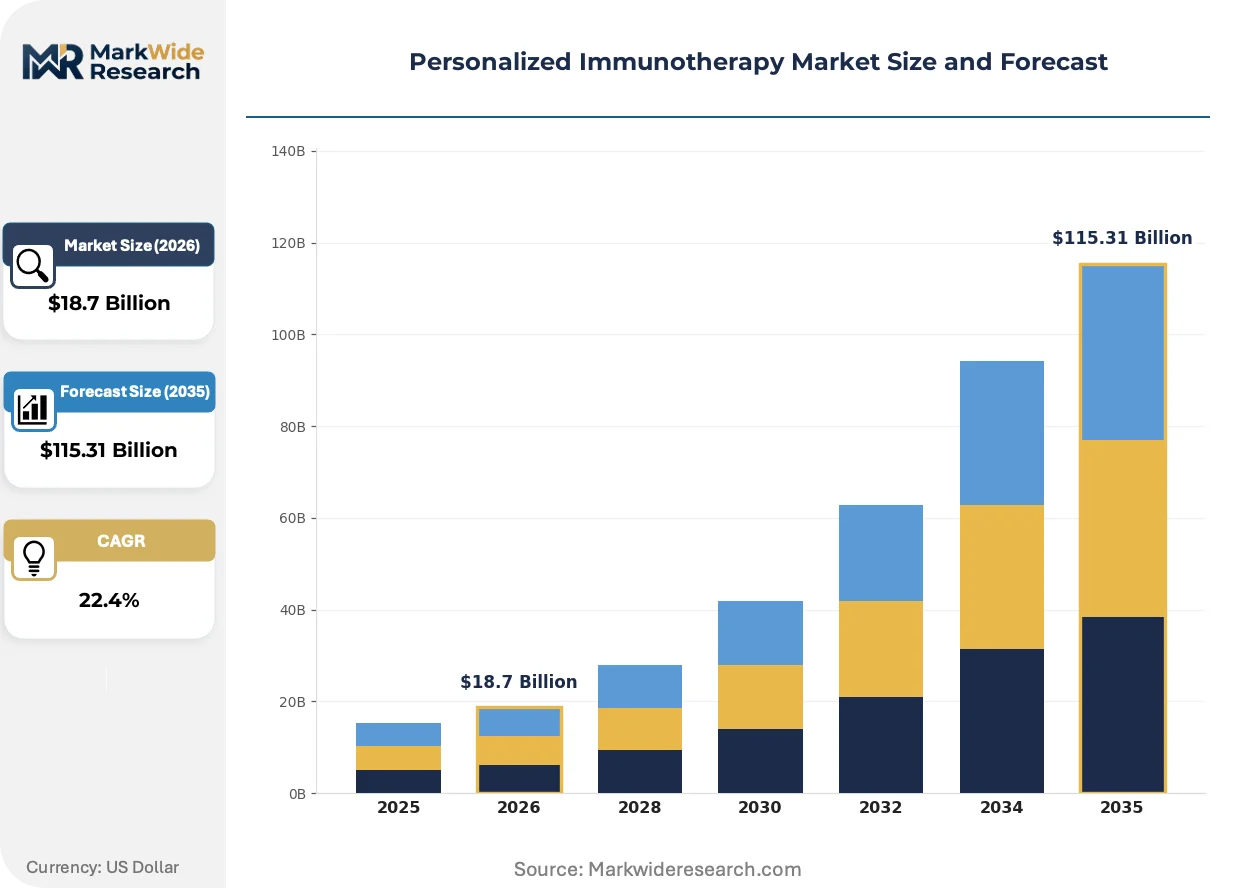
Synthetic mRNA manufacturing is compressing production timelines for neoantigen vaccines while decentralizing supply chains away from viral vector dependency. This platform shift is redrawing competitive economics across autologous cell therapy and personalized vaccine segments.
Growth Catalysts
- FDA Accelerated Approval Pathways:The Breakthrough Therapy Designation and Regenerative Medicine Advanced Therapy designation compress review timelines for autologous cell products. Hematology-oncology clinics expand infusion capacity to capture eligible patients.
- Next-Generation Sequencing Cost Collapse:Tumor exome and transcriptome profiling now enables rapid neoantigen prediction at scale. Bioinformatic pipelines integrate with manufacturing execution systems for real-time lot release.
- Germany's KBA-Anchored Logistics:Temperature-controlled distribution networks for cryogenic cellular products extend patient access across Central European markets. Manufacturing facilities cluster around Frankfurt and Munich hubs.
Market Restraints
- Autologous Manufacturing Cost Structure:Patient-specific batch production requires dedicated cleanroom suites and skilled cell processing technicians. Leukapheresis scheduling constraints limit throughput at apheresis centers.
- Viral Vector Supply Concentration:Lentiviral and retroviral vector production remains concentrated among contract manufacturers with limited GMP capacity. Plasmid DNA and transfection reagent shortages disrupt CAR-T vector supply.
- Solid-Tumor Targeting Limitations:Tumor heterogeneity and immunosuppressive microenvironments reduce durable response rates compared to hematologic malignancies. Antigen escape mechanisms compromise single-target therapies.
Strategic Opportunities
- Allogeneic Off-the-Shelf Platforms:Gene-edited donor-derived cell therapies eliminate patient-specific manufacturing delays. Healthy donor banks and HLA-matching algorithms enable inventory-based distribution models.
- Community Oncology Infusion Networks:Decentralized delivery channels extend CAR-T access beyond academic medical centers. Standalone infusion suites reduce patient travel burden and capture referral volume.
- EU PRIME Scheme for Academic Spinouts:The EMA's priority medicines pathway accelerates market access for novel personalized immunotherapy constructs. Early scientific advice and accelerated assessment compress development timelines.
Industry Challenges
- Cell Processing Technician Shortage:GMP-compliant aseptic manufacturing requires specialized training in cell culture and cryopreservation. Workforce development lags facility expansion timelines across manufacturing sites.
- Long-Term Pharmacovigilance Burden:Durable remission data requirements extend patient follow-up obligations to 15 years post-treatment. Registry infrastructure and adverse event reporting systems strain post-market surveillance capacity.
- ISO 14644 Cleanroom Qualification:Facility validation and environmental monitoring for cellular product manufacturing extend construction-to-operation timelines. Contamination control protocols demand continuous particulate and microbial surveillance.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Personalized Immunotherapy Market |
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $115.31 Billion |
| CAGR (2026 – 2036) | 22.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Monoclonal Antibodies, CAR-T Therapy, Checkpoint Inhibitors, Vaccines End User: Hospitals, Oncology Clinics, Research Institutions, Diagnostic Labs Application: Cancers, Autoimmune Disorders, Infectious Diseases, Transplant Rejections Delivery Mode: Intravenous, Subcutaneous, Oral, Intratumoral |
| Companies Covered | Novartis AG, F. Hoffmann-La Roche Ltd, Bristol-Myers Squibb Company, Merck & Co., Inc., Amgen Inc., AstraZeneca plc, Gilead Sciences, Inc., BioNTech, Moderna, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Personalized Immunotherapy Market Evolving Landscape
Artificial intelligence is compressing neoantigen prediction timelines while machine learning models integrate multi-omic data for patient stratification. Manufacturing automation and closed-system bioreactors are reducing operator-dependent variability in cell therapy production.
CRISPR-based gene editing is converging with CAR-T engineering to produce allogeneic cell therapies with reduced graft-versus-host disease risk. Contract development and manufacturing organizations are adopting platform processes for multiplexed gene knockouts. This technology convergence is enabling off-the-shelf inventory models that displace patient-specific autologous manufacturing timelines.
The FDA's Risk Evaluation and Mitigation Strategy requirements for CAR-T therapies mandate specialized certification for prescribing physicians and treatment centers. REMS infrastructure limits site expansion and concentrates treatment volume at experienced academic centers. Pediatric and young adult indications face the strictest site qualification requirements, compressing eligible prescriber pools.
Oncology clinics are consolidating procurement decisions through integrated delivery networks that negotiate directly with manufacturers. Group purchasing organizations aggregate volume across health system affiliates to extract price concessions on high-cost cellular therapies. This channel concentration is most visible in the United States, where hospital-owned specialty pharmacies capture dispensing margin and control patient access.
Personalized Immunotherapy Market Segmentation
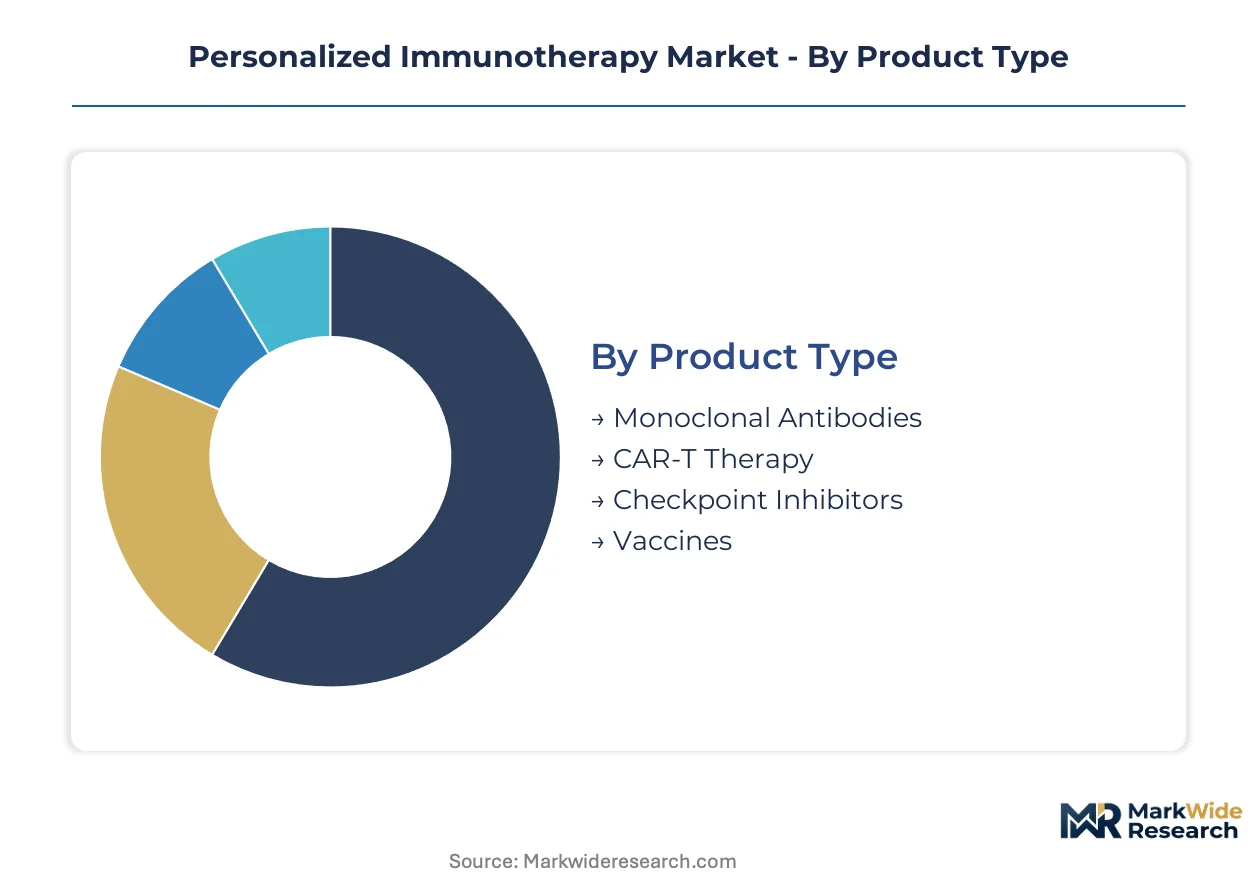
Personalized immunotherapy segmentation reveals divergent margin structures across product modalities. Delivery infrastructure and patient access requirements reshape competitive economics within each category. Manufacturing complexity varies dramatically between autologous cell therapies and off-the-shelf biologics.
Product Type:
Volume concentration sits with established biologics while premium pricing accrues to patient-specific cellular therapies. Cost tier separation reflects manufacturing scale economies versus individualized production overhead.
- Monoclonal Antibodies:Engineered immunoglobulins targeting specific tumor-associated antigens with standardized GMP production protocols. Demand concentrates in United States hospital systems where infusion center capacity and reimbursement pathways are mature. FDA biosimilar guidance compresses originator pricing power as follow-on products enter oncology portfolios.
- CAR-T Therapy:Autologous T-cells genetically modified ex vivo to express chimeric antigen receptors against patient-specific malignancies. Manufacturing requires dedicated cleanroom suites and viral vector supply chains concentrated among limited contract manufacturers. Leukapheresis scheduling constraints and cryogenic logistics limit throughput at apheresis centers.
- Checkpoint Inhibitors:Systemic immunomodulators blocking PD-1/PD-L1 or CTLA-4 signaling pathways to restore anti-tumor immunity.
- Vaccines:Patient-specific neoantigen formulations synthesized through tumor exome sequencing and computational prediction algorithms.
Today's leader: Monoclonal Antibodies. Tomorrow's challenger: CAR-T Therapy.
End User:
Patient access patterns split between centralized academic capacity and distributed community delivery. Channel concentration shapes procurement leverage and manufacturer pricing exposure.
- Hospitals:Integrated health systems with embedded transplant and cellular therapy infrastructure. Germany's university hospitals anchor European CAR-T administration alongside KBA-certified logistics networks. Group purchasing organizations aggregate volume across health system affiliates to extract price concessions on high-cost therapies.
- Oncology Clinics:Standalone infusion centers and community-based specialty practices expanding adoptive cell therapy programs. Decentralized channels extend access beyond academic medical centers in United States markets. REMS certification requirements limit site expansion and concentrate treatment volume at experienced centers.
- Research Institutions:Academic medical centers conducting early-phase clinical trials and biomarker discovery.
- Diagnostic Labs:Commercial and hospital-affiliated facilities performing companion diagnostic testing and sequencing services.
Hospitals capture the highest absolute revenue per patient. Oncology clinics are expanding most quickly as solid-tumor indications broaden eligibility.
Application:
Clinical development pipelines concentrate on oncology while autoimmune expansion diversifies addressable indications. Regulatory precedent and reimbursement infrastructure favor established therapeutic areas.
- Cancers:Hematologic malignancies and solid tumors targeted through mutation-specific immune recognition. Melanoma and colorectal programs anchor neoantigen vaccine development with established tumor-infiltrating lymphocyte protocols. Solid-tumor microenvironment immunosuppression reduces durable response rates compared to hematologic indications.
- Autoimmune Disorders:Systemic lupus erythematosus, multiple sclerosis, and rheumatoid arthritis addressed through regulatory T-cell engineering. EMA PRIME scheme accelerates European market access for academic spinouts developing novel constructs. Long-term pharmacovigilance requirements extend patient follow-up obligations to fifteen years post-treatment.
- Infectious Diseases:Pathogen-specific T-cell therapies and therapeutic vaccines for chronic viral infections.
- Transplant Rejections:Donor-specific tolerance induction and graft-versus-host disease prophylaxis using cellular immunomodulation.
Cancers dominate current revenue. Autoimmune disorders present the steepest expansion trajectory as platform technologies migrate beyond oncology.
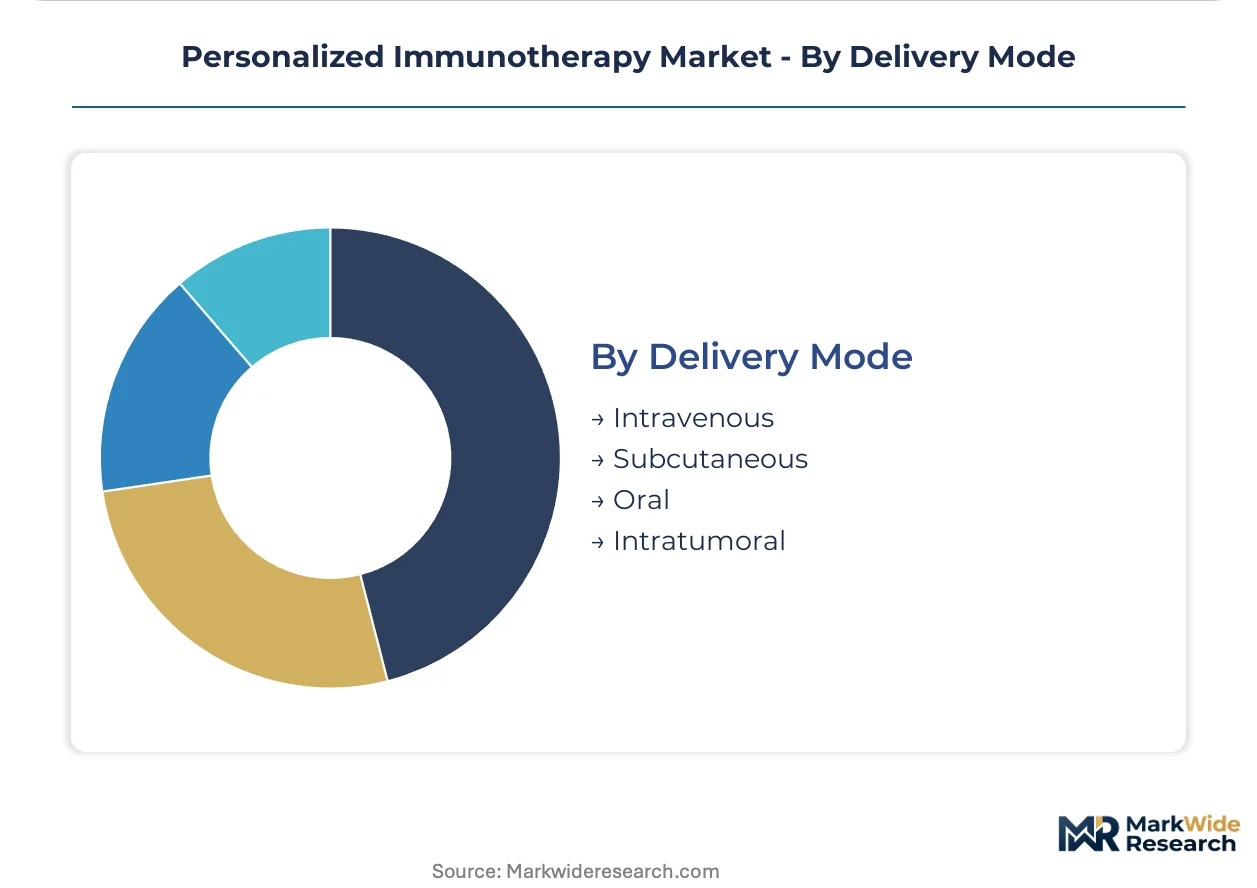
Delivery Mode:
Route selection reflects pharmacokinetic requirements and site-of-care economics. Administration complexity drives channel preference and patient compliance patterns.
- Intravenous:Systemic administration for cellular therapies and monoclonal antibodies requiring controlled infusion rates. United States oncology clinics expand infusion capacity to capture eligible patients as solid-tumor indications broaden. REMS infrastructure mandates specialized certification for prescribing physicians and treatment centers.
- Subcutaneous:Self-administered or clinic-based injection for maintenance immunotherapy and certain checkpoint inhibitors. Germany's outpatient reimbursement frameworks support community-based delivery models. Patient convenience and reduced healthcare utilization drive preference where pharmacokinetic profiles permit.
- Oral:Small-molecule immunomodulators with systemic bioavailability and patient-administered dosing flexibility.
- Intratumoral:Direct injection into tumor masses for localized immune activation and neoantigen release.
Intravenous administration commands the highest per-dose revenue. Subcutaneous delivery is gaining share fastest through patient preference and site-of-care cost reduction.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Boston-Cambridge biotech corridor anchors North American cell therapy development through dense venture capital networks and FDA-regulated clinical trial infrastructure. Manufacturing partnerships between academic medical centers and contract manufacturers concentrate capacity around Philadelphia and Durham research triangles.
United States
Oncology clinics in Texas and Florida expand CAR-T infusion suites as solid-tumor indications broaden patient eligibility. The FDA's Risk Evaluation and Mitigation Strategy mandates specialized certification for prescribing physicians, limiting site expansion to experienced academic centers. The Philadelphia corridor hosts vector manufacturing partnerships between university hospitals and contract development organizations.
Germany
BioNTech's manufacturing footprint and KBA-certified logistics infrastructure anchor European neoantigen vaccine supply chains. The EMA's PRIME scheme accelerates market access for academic spinouts developing novel personalized constructs. Frankfurt and Munich hubs cluster temperature-controlled distribution networks for cryogenic cellular products across Central European markets.
Switzerland
Basel-based pharmaceutical headquarters coordinate global clinical development for checkpoint inhibitor combinations. Swissmedic's accelerated assessment pathways compress review timelines for breakthrough autologous therapies. The Lake Geneva region concentrates precision medicine diagnostics and companion testing infrastructure.
United Kingdom
London's academic medical centers pioneer tumor-infiltrating lymphocyte protocols for melanoma and colorectal indications. The MHRA's Innovative Licensing and Access Pathway supports early commercialization for personalized immunotherapy constructs. The Oxford-Cambridge arc integrates next-generation sequencing services with bioinformatic prediction pipelines.
Japan
PMDA's Sakigake designation system prioritizes review for regenerative medicine products including allogeneic cell therapies. The Kansai region hosts manufacturing facilities serving domestic lymphoma and leukemia patient populations. Tokyo's university hospitals anchor Asia-Pacific clinical trial networks for neoantigen vaccine development.
Personalized Immunotherapy Market Competitive Landscape
Global majors compete with regional champions across manufacturing scale and therapeutic modality specialization. The vendor base stratifies between integrated pharmaceutical conglomerates with vector supply control and emerging biotech platforms focused on mRNA payload economics. Three archetypes dominate: large-cap incumbents with cryogenic distribution networks, mid-scale specialists in synthetic manufacturing, and academic spinouts leveraging accelerated regulatory pathways. Competitive intensity centers on M&A activity targeting gene-editing capabilities and strategic partnerships securing lentiviral vector supply.
Among Swiss-based integrated conglomerates, Novartis AG and F. Hoffmann-La Roche Ltd exemplify vertical control from leukapheresis through commercial distribution. Bristol-Myers Squibb Company represents the checkpoint inhibitor incumbent archetype with companion diagnostic alliances. BioNTech occupies a distinct position as the mRNA platform specialist with KBA-anchored logistics infrastructure.
| Leading Market Players |
|---|
| Novartis AG |
| F. Hoffmann-La Roche Ltd |
| Bristol-Myers Squibb Company |
| Merck & Co., Inc. |
| Amgen Inc. |
| AstraZeneca plc |
| Gilead Sciences, Inc. |
| BioNTech |
| Moderna, Inc. |
| Others |
Value Network & Pricing Analysis
Autologous-to-allogeneic manufacturing bifurcation separates premium patient-specific therapies from emerging off-the-shelf inventory models, with this divergence manifesting in both reimbursement thresholds and cryogenic logistics infrastructure. FDA REMS certification requirements and KBA-certified cold chain networks in Germany concentrate pricing power among vertically integrated manufacturers while compressing margins at contract manufacturing organizations lacking vector supply control.
Pricing Analysis
Input-cost pass-through from viral vector shortages and GMP-grade plasmid DNA scarcity is intensifying price pressure across autologous CAR-T manufacturing tiers. Three-tier pricing structure across premium autologous cellular therapies, mid-tier checkpoint inhibitor combinations, and economy-positioned biosimilar monoclonal antibodies reflects certification grade and leukapheresis scheduling complexity. Pricing softness reflects buyer consolidation through US group purchasing organizations and European hospital procurement alliances. Academic medical centers exhibit lowest price sensitivity due to REMS-mandated site qualification barriers, while community oncology clinics face acute margin compression from infusion infrastructure investments.
Supply Chain Analysis
Cryogenic freight costs and liquid nitrogen tanker availability constrain patient access beyond 300-kilometer radii from manufacturing hubs in the United States, Germany, and Switzerland. Lentiviral vector production concentrates in the United States and Germany, with plasmid DNA sourcing anchored in California and Massachusetts manufacturing corridors. Single-source vulnerability pervades GMP-grade transfection reagent supply, with distribution running through manufacturer-controlled specialty pharmacy networks and hospital-owned infusion centers. Temperature excursion risk during last-mile delivery represents the dominant supply chain failure mode across autologous cell therapy distribution.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Manufacturing cost arbitrage between FDA-regulated US facilities and EMA-accelerated European pathways creates geographic positioning advantages for vector production and cryogenic logistics infrastructure. Germany's KBA certification framework offers 12-18 month regulatory timeline compression versus standard FDA BLA review cycles.
For Market Incumbents: Anticipate allogeneic platform displacement of autologous manufacturing by securing gene-editing capabilities through targeted capability acquisitions. Vector supply concentration among limited contract manufacturers represents the primary vulnerability lever; backward integration into plasmid DNA production and captive lentiviral manufacturing capacity defends margin position against emerging biotech entrants leveraging mRNA payload economics.
For New Entrants and Emerging Players: Begin with autoimmune disorder indications where regulatory precedent is less entrenched and manufacturing scale requirements remain modest compared to oncology. Community oncology infusion networks in Texas and Florida present the most penetrable channel given REMS site qualification backlogs at academic centers. A go-to-market angle emphasizing subcutaneous delivery formats bypasses the infusion infrastructure capital intensity that limits competitor expansion.
For Investors and Strategic Acquirers: Consolidation pressure builds where CAR-T manufacturing capacity exceeds qualified prescriber pool expansion, forcing asset rationalization among mid-scale contract manufacturers. Long-term viability favors platform technologies with allogeneic inventory models that displace patient-specific batch economics. Acquisition target archetype: synthetic mRNA manufacturing specialists with integrated bioinformatic pipelines. The signal to watch is FDA guidance relaxation on allogeneic gene-editing safety thresholds, which would accelerate off-the-shelf platform adoption.
| Strategic Initiative | Industry Significance |
|---|---|
| Manufacturing Scale-Up | Closed-system bioreactor deployment at Frankfurt and Munich hubs reduces operator-dependent variability in cell therapy production. |
| Regulatory Approval Pathway | EMA PRIME scheme acceleration compresses European market access timelines for academic spinouts developing novel constructs. |
| Backward Integration | In-house plasmid DNA production insulates CAR-T manufacturers from contract manufacturer capacity constraints and transfection reagent shortages. |
| Licensing Agreement | Companion diagnostic alliances with sequencing platforms secure biomarker-driven patient stratification for checkpoint inhibitor combinations. |
| Pipeline Diversification | Autoimmune disorder expansion leverages existing cell engineering platforms beyond oncology into lupus and multiple sclerosis indications. |
Research Methodology
Coverage spans the United States, Germany, Switzerland, the United Kingdom, and Japan, with primary inputs from each market's regulatory and manufacturing clusters. Primary interviews with drug development executives, regulatory affairs leads at FDA and EMA, hospital procurement managers, and payer access specialists combined with secondary validation from FDA filings, EMA submissions, ClinicalTrials.gov records, and formulary databases. Bottom-up patient population modeling and top-down manufacturer revenue triangulation anchored volume and value estimates.
Rate-of-change decomposition separated volume drivers from pricing dynamics across the projection horizon. Segmentation dimensions modeled include product modality, end-user channel concentration, application area, and regional regulatory cluster. CAGRs derived from treatment penetration curves and manufacturing capacity expansion timelines, with neoantigen prediction algorithm accuracy and cell processing technician workforce growth as industry-specific forecast inputs.
Several conditions sit outside the modeled scope, including specific biosimilar entry dates, gene-editing regulatory guidance revisions, and vector manufacturing technology breakthroughs. Forecasts reflect documented assumptions about REMS site qualification rates and leukapheresis center expansion. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Regenerative Medicine
Tumour-Induced Osteomalacia Market
Regenerative Medicine
Cell Damage & Repair Market
Regenerative Medicine
North America Scar Treatment Market
Regenerative Medicine
Europe Regenerative Medicines Market
Regenerative Medicine
Mesotherapy Guns Market
Regenerative Medicine
Regenerative Artificial Skin Market
Regenerative Medicine
Tooth Regeneration Market
Regenerative Medicine
Autologous Fat Grafting Market
Regenerative Medicine
Global Vaginal Rejuvenation Market
Regenerative Medicine
Global Breast Reconstruction Market
Regenerative Medicine
Hypertrophic and Keloid Scar Treatment Market
Regenerative Medicine
Longevity and Anti-Senescence Therapy for Cancer Market
Regenerative Medicine
Soft Tissue Repair Market
Regenerative Medicine
Europe Longevity and Anti-Senescence Therapy Market
Regenerative Medicine
US Scar Treatment Market
Regenerative Medicine
North America Regenerative Medicines Market