
 North America Longevity and Anti-Senescence Therapy Market | 2026-2036
North America Longevity and Anti-Senescence Therapy Market Size, Share, and Industry Trends Forecast 2026-2036
North America Longevity and Anti-Senescence Therapy Market Analytics
The capital-intensity gap between well-funded discovery platforms and lean development-stage firms is collapsing as early-phase senolytic programs require comparable infrastructure. Altos Labs leverages its billion-dollar backing to sustain deep basic research into cellular reprogramming without near-term revenue pressure. Unity Biotechnology anchors its position in osteoarthritis and ophthalmology indications, navigating narrower therapeutic lanes than broad longevity plays.
Longevity and anti-senescence therapy encompasses interventions designed to delay, prevent, or reverse cellular aging processes through senolytic compounds, epigenetic reprogramming, or metabolic modulation, typically requiring parenteral delivery and cold-chain logistics due to biological instability. The primary commercial purpose centers on compressing morbidity by targeting fundamental aging mechanisms rather than individual diseases. Biological products occupy the deepest margin pools given manufacturing complexity and patent protectability, while genetic treatments represent the fastest-expanding segment as CRISPR-based epigenetic editing matures. Nutraceuticals dominate volume through direct-to-consumer channels though face thinner margins and inconsistent clinical validation.
The FDA and Health Canada shape market access through divergent cell-and-gene therapy frameworks, with the FDA's regenerative medicine advanced therapy designation accelerating review timelines while Canadian regulators impose stricter manufacturing inspections. HIPAA compliance requirements constrain real-world data collection for aging biomarker validation, limiting post-market evidence generation. State-level direct-to-consumer regulations in California and New York further fragment commercialization pathways. Stakeholders must monitor how the FDA reconciles longevity claims with traditional disease-based approval endpoints as the field presses for indication expansion beyond single-pathology frameworks.
Market Dynamics
The FDA's regenerative medicine advanced therapy designation is compressing clinical trial timelines for cellular reprogramming candidates, collapsing traditional phase-gating while demanding manufacturing infrastructure that only well-capitalized platforms can sustain.
Growth Catalysts
- FDA RMAT Pathway:Accelerated review timelines for senolytic and gene therapy candidates reduce capital-at-risk duration, enabling earlier proof-of-concept milestones.
- Venture Concentration in Bay Area Biotech Corridor:Deep capital pools around San Francisco and San Diego sustain discovery-stage cellular reprogramming programs without near-term revenue mandates.
- Epigenetic Editing Platforms:CRISPR-based interventions targeting methylation clocks are expanding addressable indications beyond single-disease frameworks.
Market Restraints
- Cold-Chain Biological Instability:Parenteral senolytic formulations require continuous refrigeration from manufacturing through administration, constraining distribution reach and elevating spoilage risk.
- HIPAA Evidence Generation Constraints:Privacy regulations limit real-world data collection for aging biomarker validation, throttling post-market surveillance capabilities.
- Single-Source Supply Concentration:Viral vector manufacturing for gene therapies concentrates among contract manufacturers in Massachusetts and North Carolina, creating bottleneck vulnerability.
Strategic Opportunities
- Direct-to-Consumer Nutraceutical Channels:California and New York state regulations permit bypass of traditional clinical distribution for certain metabolic modulators, opening volume pathways outside prescription frameworks.
- Health Canada Parallel Pathways:Stricter FDA manufacturing standards create competitive advantage for firms dual-filed under Canadian cell-and-gene therapy frameworks with faster inspection timelines.
- Osteoarthritis Indication Expansion:Narrower therapeutic lanes in joint and ophthalmology applications offer faster approval trajectories than broad longevity claims.
Industry Challenges
- Cellular Reprogramming Talent Scarcity:Deep expertise in partial reprogramming protocols remains concentrated among academic labs, constraining hiring pipelines for commercial-scale operations.
- Capex-Intensive Manufacturing Scale-Up:GMP-compliant cleanroom infrastructure for biological products demands nine-figure investments before Phase II completion.
- Longevity Claim Endpoint Definition:FDA has not established surrogate markers for aging itself, forcing sponsors to design trials around discrete disease endpoints that fragment addressable markets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Longevity and Anti-Senescence Therapy Market |
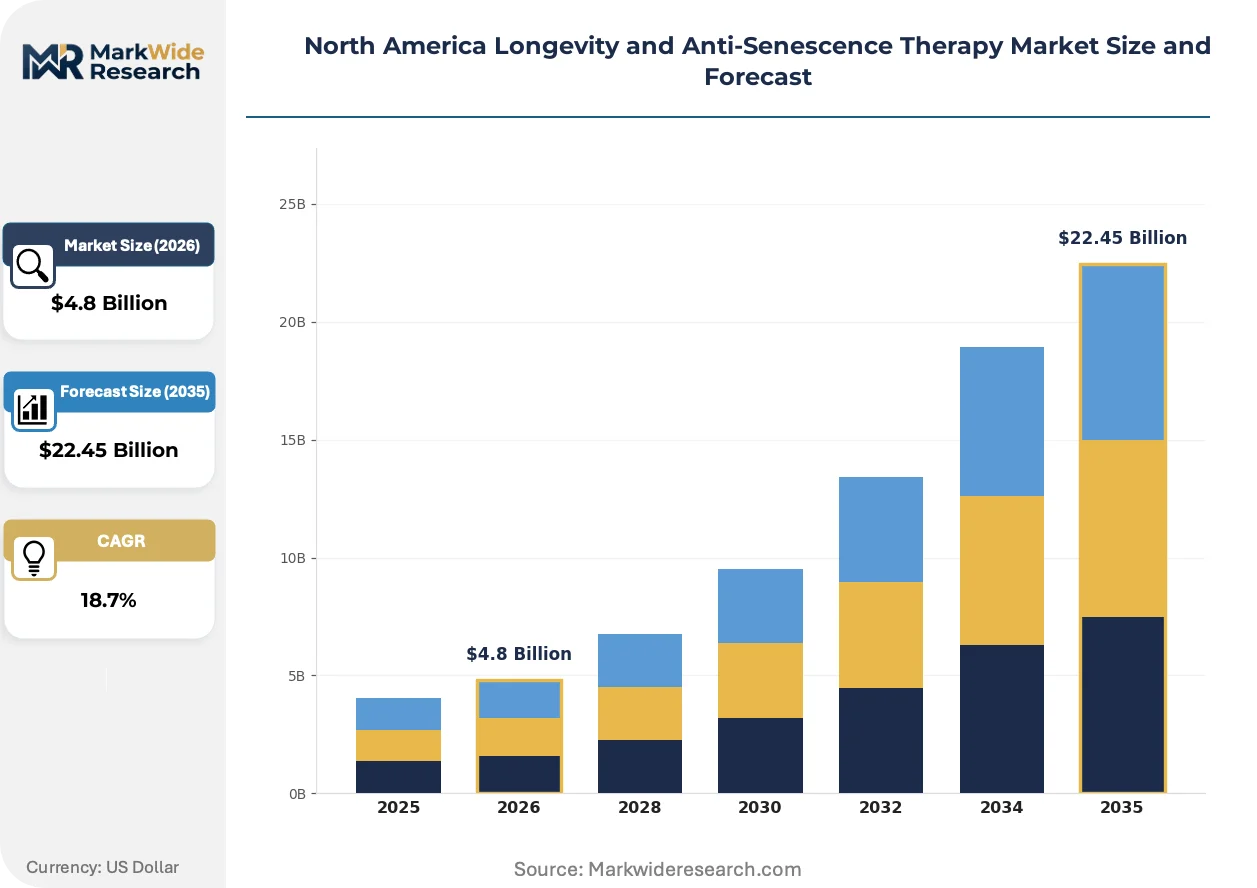
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $22.45 Billion |
| CAGR (2026 – 2036) | 18.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hormonal Therapies, Nutraceuticals, Biological Products, Genetic Treatments Therapy Area: Cardiovascular Health, Neurodegenerative Disorders, Immune Enhancement, Age-Related Diseases Target Demographic: Senior Citizens, Middle-Aged Adults, Health-Conscious Individuals, Patients with Chronic Illnesses Delivery Mode: Injections, Oral Supplements, Topical Applications, Intravenous Infusions |
| Companies Covered | Calico Life Sciences, Unity Biotechnology, Altos Labs, Life Biosciences, AgeX Therapeutics, Oisin Biotechnologies, BioAge Labs, Elysium Health, Turn Biotechnologies, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Longevity and Anti-Senescence Therapy Market Evolving Landscape
Cellular reprogramming protocols are compressing the discovery-to-clinic timeline while regulatory frameworks scramble to accommodate indication categories that do not map onto traditional disease taxonomies.
Partial reprogramming using Yamanaka factor variants restores youthful epigenetic signatures without inducing pluripotency. Biopharmaceutical development teams are advancing these candidates through IND-enabling studies at unprecedented velocity. This modality is supplanting senolytic small molecules as the dominant platform for age-related disease intervention, compressing competitive timelines and elevating manufacturing complexity requirements.
The FDA's expanding guidance on gene and cell therapies is reshaping clinical trial pathways for longevity interventions. Sponsors now navigate regenerative medicine advanced therapy designation requirements while Health Canada imposes parallel but distinct manufacturing inspection protocols. California-based biotech firms are responding by building dual-compliant quality systems from inception rather than retrofitting post-approval.
Academic medical centers are consolidating procurement authority for experimental anti-senescence protocols under centralized review boards. This concentration is displacing principal-investigator-driven purchasing that historically dominated early-phase trial supply. The shift is most visible in Boston and San Diego, where institutional review boards now negotiate master service agreements with vector manufacturers and CROs directly.
North America Longevity and Anti-Senescence Therapy Market Segmentation
Segmentation in the North America longevity and anti-senescence therapy market reveals how capital allocation, regulatory pathways, and distribution infrastructure fragment across product architectures and patient populations. Understanding these divides exposes where margin pools concentrate versus where volume scales through alternative channels.
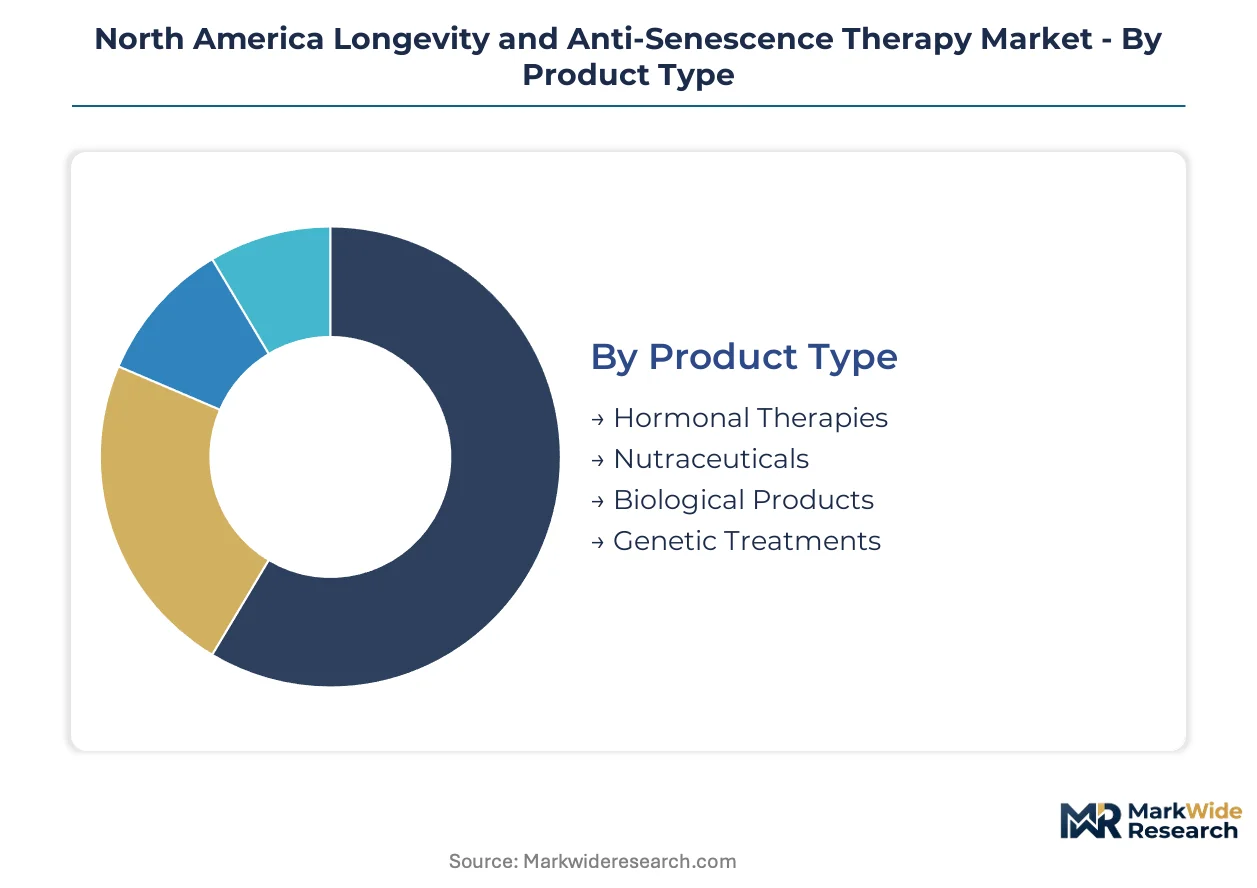
Product Type:
Biological products and genetic treatments concentrate in FDA-regulated prescription pathways requiring cold-chain infrastructure, while hormonal therapies and nutraceuticals flow through direct-to-consumer channels with lighter regulatory burdens.
- Biological Products:Recombinant proteins, monoclonal antibodies, and cell-derived formulations targeting senescent cell clearance. Manufacturing concentrates in Massachusetts and North Carolina contract facilities, constrained by viral vector production bottlenecks and nine-figure GMP infrastructure requirements.
- Genetic Treatments:CRISPR-based epigenetic editing and gene therapy vectors targeting methylation clocks. California Bay Area biotech clusters anchor discovery, with RMAT designation accelerating review timelines but demanding parallel Health Canada compliance for cross-border commercialization.
- Hormonal Therapies:Testosterone, growth hormone, and peptide analogs administered via injection protocols. Distribution runs through specialty pharmacies and anti-aging clinics in Florida and Texas.
- Nutraceuticals:Metabolic modulators, NAD+ precursors, and polyphenol compounds sold through e-commerce and retail channels. California and New York state regulations permit bypass of prescription frameworks for certain formulations.
Biological products hold installed capacity. Genetic treatments are rotating up the share rankings.
Therapy Area:
Cardiovascular and neurodegenerative applications command the deepest reimbursement codes, while immune enhancement and broad age-related disease frameworks face payer skepticism without discrete diagnostic endpoints.
- Neurodegenerative Disorders:Therapies targeting Alzheimer's and Parkinson's disease through tau clearance and neuronal regeneration mechanisms. Academic medical centers in Boston and San Diego consolidate procurement authority under centralized institutional review boards.
- Cardiovascular Health:Senolytic interventions targeting arterial stiffness and endothelial dysfunction. Medicare reimbursement pathways in the United States anchor demand, with Health Canada parallel filings enabling faster manufacturing inspection timelines.
- Immune Enhancement:Thymic regeneration and immune cell rejuvenation protocols. Clinical validation remains concentrated in early-phase trials without established surrogate markers.
- Age-Related Diseases:Broad indications spanning sarcopenia, frailty, and multimorbidity compression. FDA has not established aging itself as an approvable endpoint, fragmenting addressable markets into discrete disease categories.
Cardiovascular health commands reimbursement depth. Neurodegenerative disorders are gaining share fastest.
Target Demographic:
Senior citizens and patients with chronic illnesses drive prescription volumes through Medicare and private payer networks, while middle-aged adults and health-conscious individuals purchase through direct-to-consumer channels with thinner margins.
- Senior Citizens:Patients aged 65 and older accessing therapies through Medicare Part B and Part D coverage. Osteoarthritis and ophthalmology indications offer narrower therapeutic lanes with faster approval trajectories than broad longevity claims.
- Patients with Chronic Illnesses:Individuals with diabetes, heart failure, or COPD seeking morbidity compression through fundamental aging mechanism targeting. Real-world data collection for biomarker validation faces HIPAA constraints.
- Middle-Aged Adults:Consumers aged 45-64 pursuing preventive interventions before clinical disease onset. California's Bay Area biotech corridor channels venture funding toward cellular reprogramming platforms serving this demographic.
- Health-Conscious Individuals:Wellness-oriented consumers purchasing nutraceuticals and metabolic modulators through subscription e-commerce. Direct-to-consumer regulations vary by state, fragmenting commercialization pathways.
Senior citizens hold prescription volume concentration. Middle-aged adults are rotating up the share rankings.
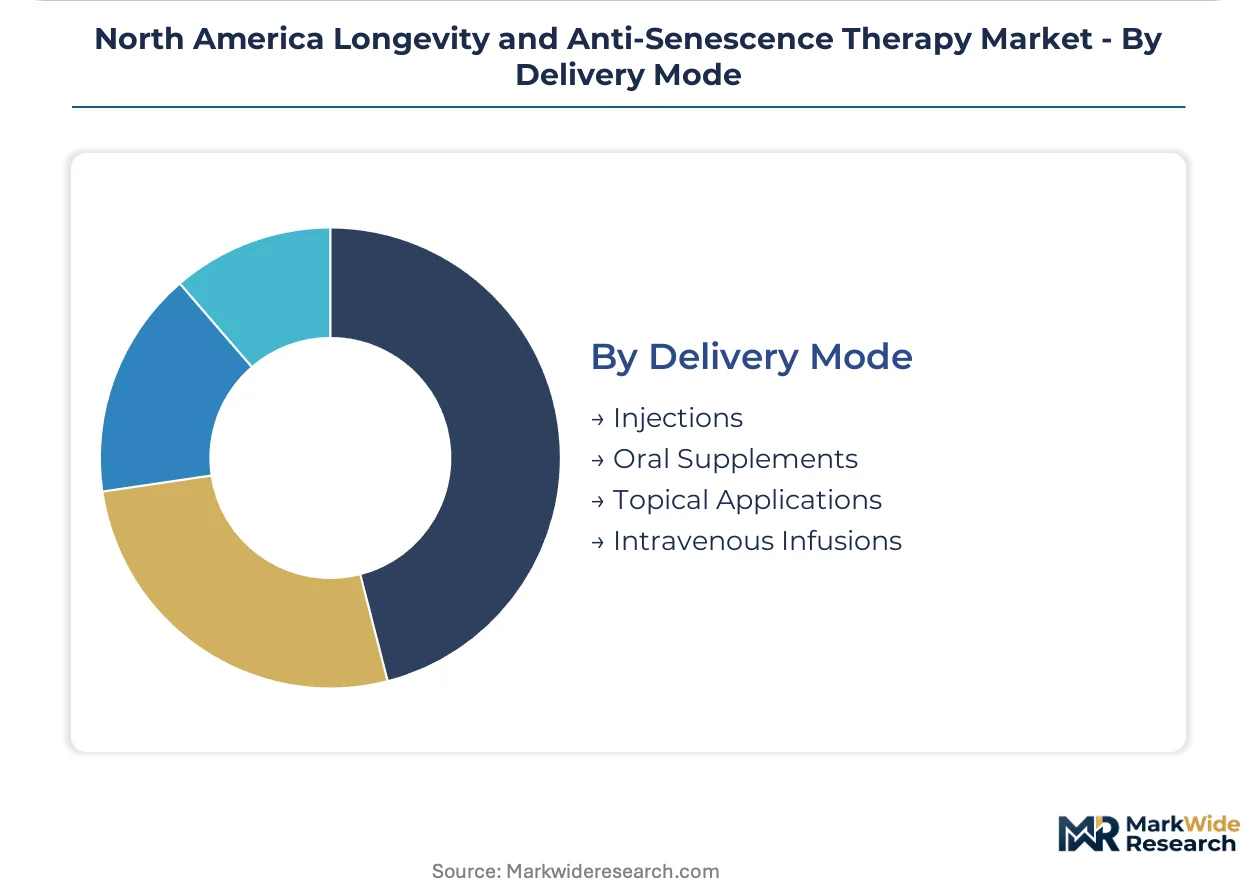
Delivery Mode:
Injections and intravenous infusions require clinical administration and cold-chain logistics, while oral supplements and topical applications scale through retail and e-commerce with lower infrastructure barriers.
- Injections:Subcutaneous and intramuscular delivery of biological products and hormonal therapies. Parenteral formulations demand continuous refrigeration from manufacturing through administration, elevating spoilage risk.
- Intravenous Infusions:Clinic-based administration of cellular therapies and high-dose metabolic protocols. GMP-compliant cleanroom infrastructure demands nine-figure investments before Phase II completion.
- Oral Supplements:Capsule and tablet formulations of nutraceuticals and small-molecule metabolic modulators. Direct-to-consumer channels in California and New York permit volume scaling outside prescription frameworks.
- Topical Applications:Transdermal delivery systems for localized anti-senescence effects. Manufacturing concentrates among contract formulators with less stringent biological handling requirements.
Injections hold clinical infrastructure concentration. Intravenous infusions are rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The North American longevity therapy market exhibits a pronounced import dependency for viral vector manufacturing, with domestic biotech clusters sourcing specialized reagents from European contract manufacturers while exporting cellular reprogramming IP through licensing frameworks.
United States
FDA's RMAT designation accelerates clinical timelines for senolytic candidates, compressing traditional phase-gating while demanding manufacturing infrastructure concentrated in Massachusetts and North Carolina. Medicare reimbursement pathways for cardiovascular applications anchor prescription volumes. California's Bay Area biotech corridor channels venture funding toward cellular reprogramming platforms serving middle-aged preventive demographics.
Canada
Health Canada imposes parallel but distinct manufacturing inspection protocols for cell-and-gene therapies, creating dual-compliance requirements for cross-border sponsors. Stricter inspection timelines under Canadian frameworks offer competitive advantage for firms filing in both jurisdictions. Toronto and Montreal academic medical centers consolidate procurement authority under centralized institutional review boards.
Mexico
COFEPRIS regulatory frameworks for advanced therapies remain less developed than US or Canadian counterparts, positioning the country primarily as a clinical trial site rather than commercial launch market. Medical tourism channels in Mexico City and Guadalajara attract US patients seeking off-label hormonal therapy protocols. Distribution infrastructure for cold-chain biological products concentrates near US border logistics hubs.
North America Longevity and Anti-Senescence Therapy Market Competitive Landscape
Concentration sits with billion-dollar discovery platforms and lean development-stage firms competing for cellular reprogramming talent. The capital-intensity gap between these archetypes is collapsing as early-phase senolytic programs require comparable GMP infrastructure. Strategic moves center on M&A for manufacturing capacity and technology licensing for epigenetic editing platforms.
Within the deep-capital discovery tier, Altos Labs and Calico Life Sciences exemplify sustained basic research models without near-term revenue pressure. Unity Biotechnology occupies a position in narrower therapeutic lanes focused on osteoarthritis and ophthalmology indications. These three entities represent contrasting approaches to longevity intervention commercialization.
| Leading Market Players |
|---|
| Calico Life Sciences |
| Unity Biotechnology |
| Altos Labs |
| Life Biosciences |
| AgeX Therapeutics |
| Oisin Biotechnologies |
| BioAge Labs |
| Elysium Health |
| Turn Biotechnologies |
| Others |
Value Network & Pricing Analysis
FDA regenerative medicine advanced therapy designation gates both supply qualification and price differentiation simultaneously, forcing sponsors to absorb nine-figure GMP infrastructure investments before revenue realization while creating tiered access based on manufacturing compliance depth.
Pricing Analysis
Customization-premium spreads separate configured-to-order cellular therapies from standard senolytic formulations. Subscription-based pricing for parenteral biological products dominates prescription channels, while direct-to-consumer nutraceuticals run on transactional per-unit models. Price differentiation hinges on cold-chain certification grade and GMP compliance tier. Pricing pressure intensifies in the nutraceutical segment due to thin clinical validation and e-commerce commoditization. Hospital procurement committees exhibit lowest price sensitivity; wellness-oriented direct consumers show highest.
Supply Chain Analysis
Viral vector manufacturing concentration in Massachusetts and North Carolina contract facilities creates a chokepoint that constrains gene therapy scale-up across the continent. Production draws from specialized reagent suppliers in Germany and Switzerland, with plasmid DNA and cell culture media as critical inputs. Single-source vulnerability pervades the viral vector tier, where three contract manufacturers service the majority of IND-enabling and commercial programs. Distribution runs through specialty pharmacy networks for biological products and e-commerce platforms for nutraceuticals.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Cellular reprogramming platforms are approaching a platform-economics inflection as Yamanaka factor IP consolidates under licensing frameworks that will determine interoperability standards across therapeutic modalities.
For Market Incumbents: Compound manufacturing capacity advantages by securing exclusive viral vector supply agreements with Massachusetts and North Carolina contract manufacturers before capacity constraints harden. Invest in dual FDA-Health Canada quality systems to capture cross-border filing premiums. Defend against lean development-stage entrants by accelerating RMAT-designated programs through Phase II before capital-intensity parity collapses competitive moats.
For New Entrants and Emerging Players: Lead with osteoarthritis and ophthalmology narrow indications that offer faster approval trajectories than broad longevity claims. Target California and New York direct-to-consumer regulatory pathways for metabolic modulator nutraceuticals to build revenue foundations without prescription infrastructure. Pursue white-space in thymic regeneration immune enhancement, where clinical validation remains early-phase and procurement authority is consolidating under academic medical center review boards.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across cellular reprogramming platforms as GMP cleanroom requirements match discovery-stage burn rates. Long-term viability favors firms with sustained basic research funding models rather than near-term revenue-dependent development shops. Target acquisition archetypes include epigenetic editing platform holders with CRISPR-based methylation clock IP. Watch for FDA guidance on aging-as-endpoint surrogate markers as the critical inflection signal.
| Strategic Initiative | Industry Significance |
|---|---|
| RMAT Designation Pursuit | FDA regenerative medicine advanced therapy status compresses clinical timelines for senolytic candidates. |
| Dual-Compliance Quality Systems | Parallel FDA-Health Canada manufacturing frameworks enable faster cross-border commercialization pathways. |
| Viral Vector Supply Agreements | Exclusive contracts with Massachusetts and North Carolina manufacturers secure scarce GMP capacity. |
| Direct-to-Consumer Channel Buildout | California and New York regulatory pathways bypass prescription frameworks for metabolic modulators. |
| Epigenetic Editing Platform Licensing | CRISPR-based methylation clock IP consolidates under interoperability-determining licensing frameworks. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with drug development executives, regulatory affairs leads, formulary directors at Medicare Advantage plans, and hospital procurement managers at academic medical centers in Boston and San Diego. Secondary validation drew from FDA filings, Health Canada submissions, ClinicalTrials.gov protocols, and CMS Medicare reimbursement databases. Bottom-up patient-flow modeling and top-down venture funding allocation analysis were triangulated against manufacturer capacity disclosures.
Across the analysis window, forecasts were derived from segment-level treatment adoption curves, pricing elasticity by payer channel, and manufacturing capacity buildout schedules. Segmentation dimensions modeled include product architecture, therapy area, target demographic, and delivery mode. CAGRs were calculated from year-over-year value progression adjusted for regulatory approval probability and reimbursement pathway uncertainty. Forecast inputs incorporated RMAT designation success rates and Health Canada inspection timeline differentials.
The analysis sits within stated boundaries; outcomes outside current FDA guidance trajectories on aging endpoints would require recalibration. Forecasts reflect documented assumptions around regulatory pathway evolution and venture capital availability. Practitioners should keep alternative scenarios live as FDA regenerative medicine guidance and Health Canada inspection protocols evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Regenerative Medicine
Artificial Blood Market
Regenerative Medicine
Hypertrophic and Keloid Scar Treatment Market
Regenerative Medicine
Atrophic Scar Treatment Market
Regenerative Medicine
Cytokine Storm Therapy Market
Regenerative Medicine
Autologous Fat Grafting Market
Regenerative Medicine
Bone Regeneration Market
Regenerative Medicine
Soft Tissue Repair Market
Regenerative Medicine
Bioelectric Medicine Market
Regenerative Medicine
Dural Graft Market
Regenerative Medicine
Mesotherapy Guns Market
Regenerative Medicine
Orthopedic Regenerative Medicine Market
Regenerative Medicine
Tooth Regeneration Market
Regenerative Medicine
Next Generation Immunotherapies Market
Regenerative Medicine
Degenerative Disc Disease Treatment Market
Regenerative Medicine
Global Vaginal Rejuvenation Market
Regenerative Medicine
Europe Longevity and Anti-Senescence Therapy Market