
 Bioelectric Medicine Market | 2026-2036
Bioelectric Medicine Market Size, Share, and Industry Trends Forecast 2026-2036
Bioelectric Medicine Market Intelligence
Germany is narrowing its manufacturing gap in implantable pulse generators through dedicated medtech clusters in Baden-Württemberg and Bavaria. Medtronic plc leverages vertically integrated electrode fabrication to sustain cost advantages across cardiac rhythm and neuromodulation portfolios. Boston Scientific Corporation anchors its European supply chain through precision manufacturing sites near regulatory hubs. Abbott Laboratories differentiates via closed-loop algorithm development for automated therapeutic adjustment.
Bioelectric medicine encompasses implantable and non-invasive devices that modulate neural or cardiac electrical signaling through controlled current delivery, typically operating at pulse widths between microseconds and milliseconds with electrode impedances below kilo-ohm thresholds. These systems treat refractory conditions by intercepting pathological electrical patterns or restoring physiological rhythms without systemic pharmacological exposure. Implantable cardioverter defibrillators and pacemakers retain the dominant revenue share due to established reimbursement and procedural volume, while neuromodulation devices for chronic pain represent the fastest-expanding margin pool as physicians shift toward opioid-sparing protocols. Closed-loop systems command premium positioning by enabling real-time biomarker-responsive therapy adjustment rather than fixed-parameter stimulation.
The FDA breakthrough device program and EU MDR conformity assessment reshape competitive access timelines, with the former compressing premarket pathways for novel bioelectronic indications and the latter imposing clinical evidence burdens on legacy implantable systems. HIPAA data governance and GDPR patient privacy frameworks constrain cloud-connected device architectures, forcing distributed processing or localized data retention in therapeutic monitoring ecosystems. Stakeholders must weigh regulatory capital requirements against the strategic imperative to secure reimbursement codes for emerging therapy areas before clinical evidence standards tighten further.
Market Dynamics
The convergence of closed-loop algorithm architectures with implantable pulse generators is compressing development cycles and forcing incumbents to restructure R&D hierarchies around real-time biomarker processing capabilities rather than hardware-centric design.
Growth Catalysts
- FDA Breakthrough Device Designation:The pathway accelerates clinical validation timelines for novel neuromodulation therapies, reducing premarket review periods for eligible implantable bioelectronic systems targeting refractory conditions.
- Cardiology Department Expansion:Hospital systems are building dedicated neuromodulation programs within cardiac service lines, creating procedural volume pull-through for spinal cord stimulation and vagus nerve therapy.
- Opioid-Sparing Clinical Protocols:Physician practice patterns in chronic pain management are shifting toward electrical neuromodulation as first-line intervention before pharmaceutical escalation.
Market Restraints
- Precious Metal Electrode Costs:Iridium and platinum feedstock volatility directly impacts implantable pulse generator manufacturing economics, compressing gross margins on high-channel-count devices.
- EU MDR Clinical Evidence Burden:Legacy implantable systems face retrospective clinical data requirements under the Medical Device Regulation, extending conformity assessment timelines and straining notified body capacity.
- Non-Invasive Transcutaneous Stimulation:External neuromodulation devices for migraine and tinnitus are capturing trial patients who might otherwise proceed to permanent implantation.
Strategic Opportunities
- German Medtech Cluster Development:Baden-Württemberg and Bavaria are cultivating vertically integrated electrode fabrication capabilities, enabling regional supply chain autonomy for European device manufacturers.
- GDPR-Compliant Edge Processing:Distributed computing architectures for therapeutic monitoring bypass cloud data transfer restrictions, unlocking real-time algorithm updates without centralized storage.
- Closed-Loop Algorithm Licensing:Automated therapeutic adjustment IP is creating new revenue streams through software-as-medical-device models independent of hardware sales.
Industry Challenges
- Biomarker Signal Processing Talent:The scarcity of engineers with combined expertise in neural electrophysiology and real-time embedded systems is constraining algorithm development velocity.
- HIPAA-GDPR Dual Compliance:US-EU patient data governance divergence forces parallel architecture development, doubling validation costs for connected therapeutic ecosystems.
- Notified Body Capacity Bottleneck:EU MDR transition has concentrated conformity assessment demand among fewer designated organizations, extending certification queues for novel implantable submissions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Bioelectric Medicine Market |
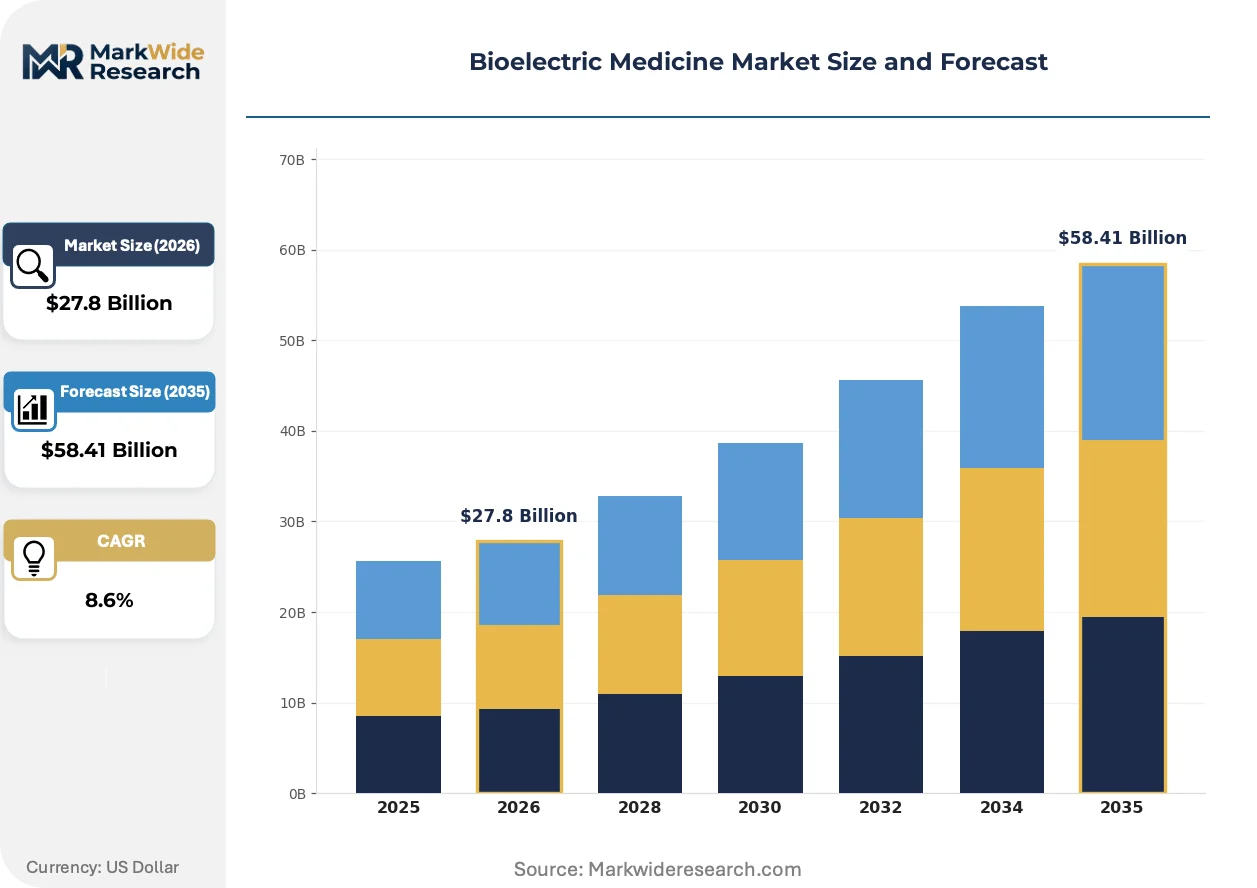
| Market Size in 2026 | $27.8 Billion |
| Market Size in 2035 | $58.41 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Neuromodulation Devices, Implantable Cardioverter Defibrillators, Pacemakers, Bioelectronic Medicines Therapy Area: Chronic Pain, Cardiovascular Diseases, Neurological Disorders, Gastrointestinal Disorders End User: Hospitals, Home Healthcare, Research Institutions, Rehabilitation Centers Technology: Microelectrode Arrays, Transcutaneous Electrical Nerve Stimulation, Closed-Loop Systems, Wireless Transmission |
| Companies Covered | Medtronic plc, Boston Scientific Corporation, Abbott Laboratories, LivaNova PLC, Cochlear Ltd., Biotronik SE & Co. KG, Nevro Corp., electroCore, Inc., SetPoint Medical, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Bioelectric Medicine Market Strategic Shifts & Innovations
Algorithm-driven therapy personalization is displacing fixed-parameter stimulation protocols across implantable neuromodulation, while regulatory data requirements and procurement model evolution reshape competitive access and commercialization economics.
Closed-loop bioelectric systems is hybridizing cardiac rhythm management with neural signal processing architectures. Electrophysiology departments in tertiary hospital systems are piloting these platforms for dual-chamber pacemakers with autonomic responsiveness. The technology is compressing the gap between diagnostic sensing and therapeutic delivery, enabling millisecond-scale intervention adjustments.
The EU Medical Device Regulation imposes clinical evidence burdens on legacy implantable systems that predate its 2017 framework. Manufacturers must generate retrospective performance data or face market withdrawal, forcing portfolio rationalization toward higher-margin platforms. Cardiac rhythm devices with decades of safety records are navigating notified body re-certification queues that now extend 18-24 months.
Hospital procurement committees are consolidating vendor relationships around full-service neuromodulation partnerships rather than device-only transactions. Integrated service agreements covering implantation training, patient monitoring, and algorithm updates are displacing traditional capital equipment purchases. This concentration is most visible in United States health systems where bundled payment models for chronic pain management incentivize single-source contracting.
Bioelectric Medicine Market Segmentation
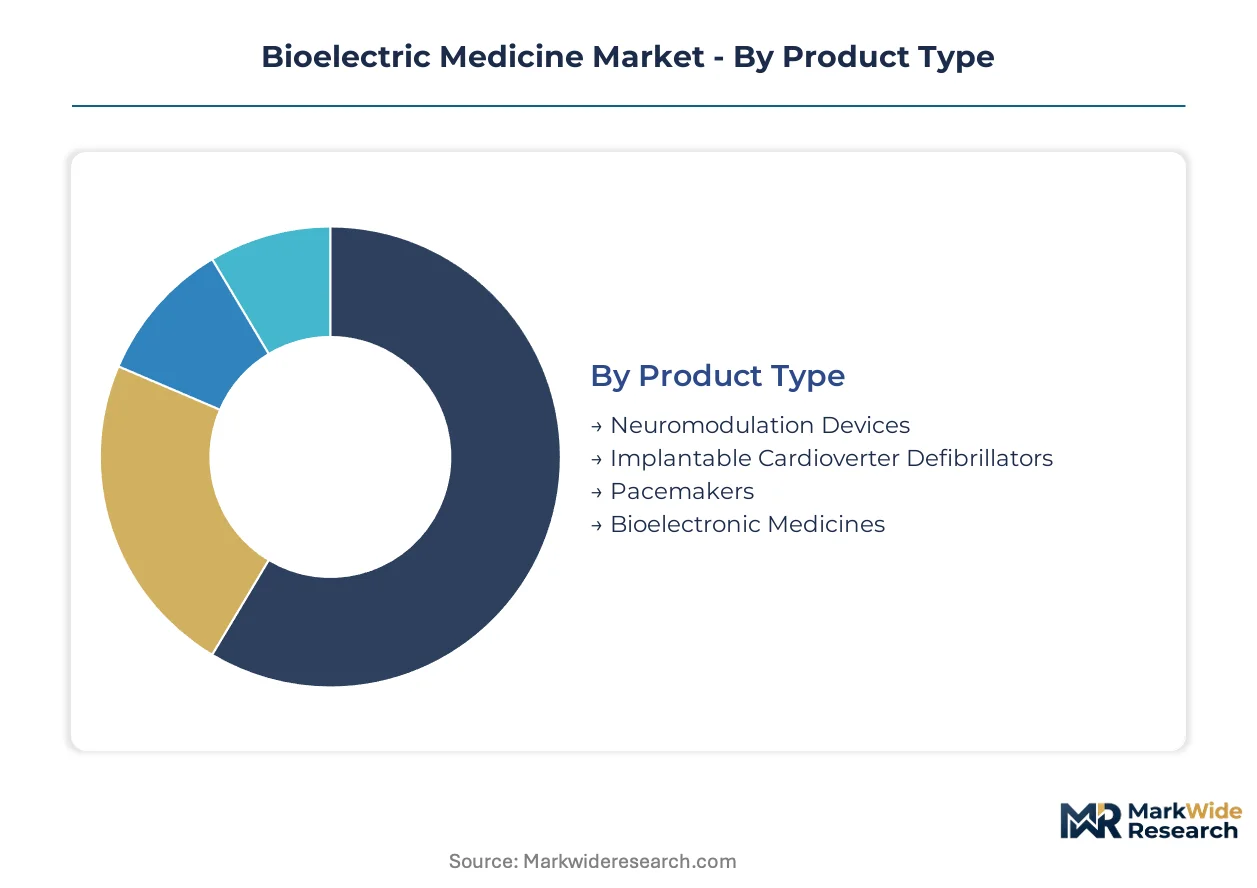
Bioelectric medicine segmentation reveals divergent service intensity requirements across implantable versus non-invasive modalities. Pulse generator longevity and algorithm update cycles create distinct aftermarket revenue profiles that reshape vendor business models.
Product Type:
After-sales-service intensity varies dramatically across product categories, with implantable systems demanding surgical follow-up and remote monitoring infrastructure while external devices require minimal technical support.
- Neuromodulation Devices:Implantable pulse generators and leads deliver targeted electrical stimulation to spinal cord or peripheral nerves through multi-channel electrode arrays. Demand concentrates in United States hospital systems expanding dedicated neuromodulation service lines as opioid-sparing protocols gain institutional priority.
- Implantable Cardioverter Defibrillators:These devices monitor cardiac rhythm and deliver high-voltage shocks to terminate ventricular fibrillation or tachycardia events. United States electrophysiology departments drive procedural volume through established reimbursement codes and mature implantation training pipelines.
- Pacemakers:Dual-chamber and leadless systems maintain heart rate through low-energy pacing pulses.
- Bioelectronic Medicines:Emerging drug-device combinations integrate electrical stimulation with localized pharmaceutical delivery.
Implantable Cardioverter Defibrillators hold the largest share; momentum sits with Neuromodulation Devices.
Therapy Area:
Cost tier stratification separates acute intervention reimbursement from chronic management protocols, with cardiovascular indications commanding premium pricing and pain management facing utilization review pressure.
- Chronic Pain:Spinal cord stimulation and dorsal root ganglion therapy interrupt nociceptive signaling through programmable waveform delivery. United States pain clinics are expanding implantation capacity as FDA breakthrough designations accelerate novel indication approvals.
- Cardiovascular Diseases:Rhythm management and heart failure resynchronization therapies dominate hospital procedural economics. German cardiology departments are piloting autonomic-responsive pacing systems that adjust stimulation parameters based on real-time biomarker feedback.
- Neurological Disorders:Deep brain stimulation and vagus nerve therapy target epilepsy, Parkinson's disease, and treatment-resistant depression.
- Gastrointestinal Disorders:Gastric electrical stimulation and sacral nerve modulation address motility dysfunction and fecal incontinence.
Cardiovascular Diseases generate the highest revenue per procedure; Chronic Pain is expanding most quickly.
End User:
Customer type determines procurement complexity, with integrated delivery networks negotiating enterprise contracts while independent practices prioritize device reliability and training support.
- Hospitals:Tertiary medical centers perform complex implantations and manage device surveillance through dedicated electrophysiology and neuromodulation service lines. United States health systems are consolidating vendor relationships around full-service partnerships covering training, monitoring, and algorithm updates.
- Home Healthcare:Remote patient monitoring and device interrogation through telemedicine platforms reduce clinic visit burden. GDPR-compliant edge processing architectures enable real-time therapeutic adjustments without cloud data transfer.
- Research Institutions:Academic medical centers conduct clinical trials for novel bioelectronic indications.
- Rehabilitation Centers:Post-implantation programming and patient optimization services.
Hospitals dominate implantation volume; Home Healthcare shows the steepest expansion trajectory.
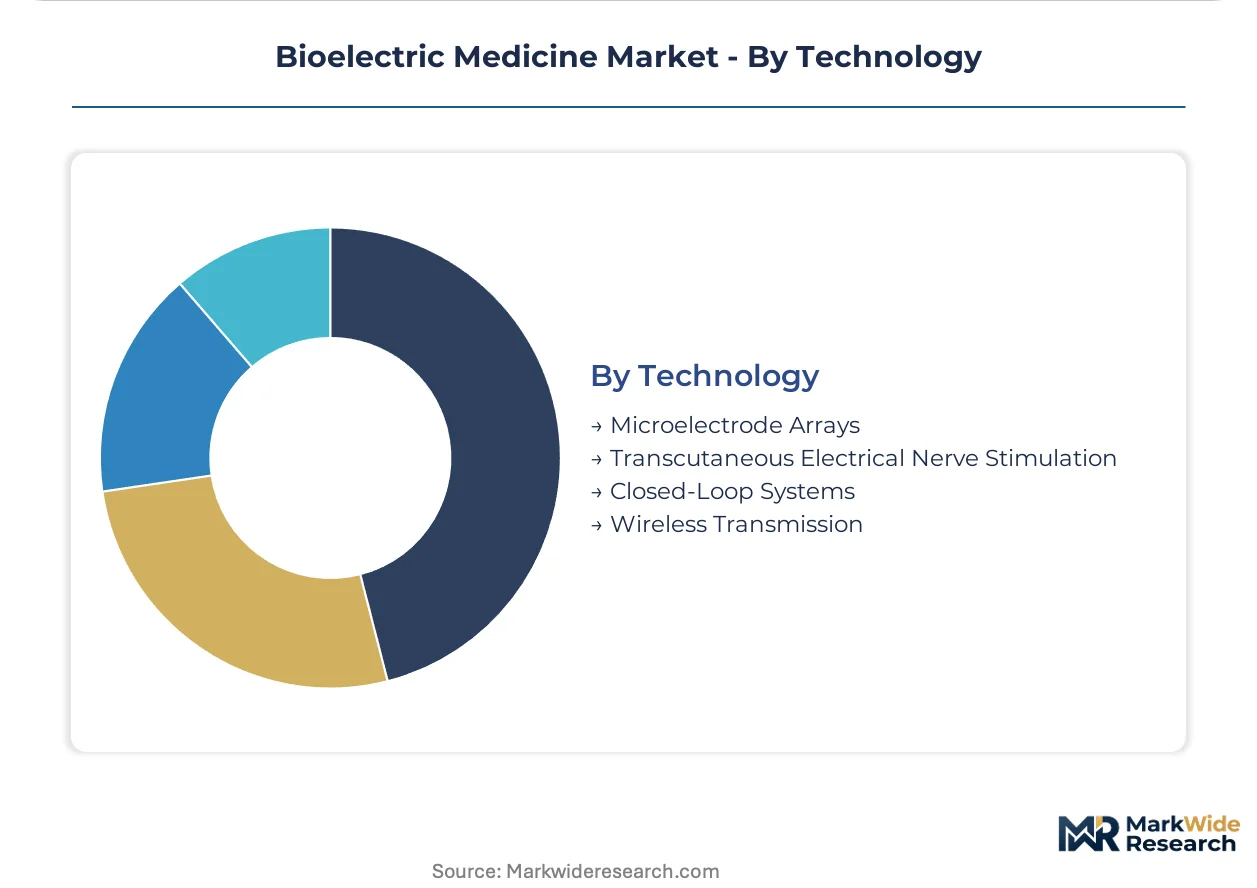
Technology:
Supply concentration in electrode fabrication and semiconductor packaging creates procurement leverage for manufacturers with captive component production.
- Closed-Loop Systems:Real-time biomarker sensing enables automated therapeutic parameter adjustment without clinician intervention. Abbott Laboratories and Medtronic plc are licensing algorithm IP through software-as-medical-device models independent of hardware sales.
- Microelectrode Arrays:High-density neural interfaces with platinum-iridium or carbon-based electrodes enable selective fiber recruitment. Baden-Württemberg manufacturing clusters are narrowing Germany's fabrication gap through dedicated medtech infrastructure.
- Transcutaneous Electrical Nerve Stimulation:Non-invasive surface electrodes deliver current through intact skin for temporary symptom relief.
- Wireless Transmission:Inductive coupling and radiofrequency links enable leadless designs and remote programming.
Microelectrode Arrays anchor current revenue; Closed-Loop Systems are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA reimbursement frameworks for spinal cord stimulation and vagus nerve therapy anchor United States demand concentration. Germany narrows manufacturing gaps through Baden-Württemberg and Bavaria medtech clusters. Japanese electrophysiology departments pilot autonomic-responsive pacing systems.
United States
Hospital systems expand dedicated neuromodulation service lines within cardiac departments as opioid-sparing protocols gain institutional priority. FDA breakthrough device designation accelerates premarket review timelines for novel implantable bioelectronic therapies targeting refractory conditions. Greater Boston and Minneapolis-St. Paul anchor electrophysiology training pipelines and device surveillance infrastructure.
Germany
Cardiology departments pilot closed-loop pacemakers with real-time biomarker feedback for heart failure resynchronization. EU MDR conformity assessment imposes retrospective clinical evidence requirements on legacy implantable systems. Baden-Württemberg manufacturing clusters cultivate vertically integrated electrode fabrication capabilities for European supply chain autonomy.
Japan
PMDA regulatory pathways emphasize long-term safety surveillance for implantable pulse generators in aging patient populations. METI industrial policy supports precision manufacturing upgrades for microelectrode array production. Kansai region medical device exporters navigate dual compliance with domestic standards and EU MDR for European market access.
United Kingdom
NHS integrated care systems consolidate vendor relationships around full-service neuromodulation partnerships covering training and remote monitoring. MHRA post-Brexit regulatory divergence from EU MDR creates parallel certification requirements for implantable device manufacturers. London and Cambridge research institutions conduct clinical trials for novel bioelectronic indications.
China
NMPA innovation approval pathways compress timelines for domestic implantable cardioverter defibrillator manufacturers. Dual carbon goals drive energy-efficient pulse generator design requirements in procurement specifications. Yangtze River Delta medical device clusters scale electrode fabrication capacity for regional supply security.
Bioelectric Medicine Market Key Industry Players
Capability concentration sits with algorithm developers; scale advantage sits with electrode fabricators. The vendor base separates into three tiers: diversified medtech conglomerates with cardiac rhythm portfolios, neuromodulation specialists with pain therapy focus, and emerging drug-device combination developers. Strategic moves center on closed-loop IP licensing and German manufacturing cluster partnerships.
Among diversified medtech conglomerates, Medtronic plc and Boston Scientific Corporation occupy positions spanning cardiac rhythm and neuromodulation portfolios. Abbott Laboratories exemplifies the algorithm-centric tier through closed-loop therapeutic adjustment development. Nevro Corp. represents the neuromodulation specialist archetype with concentrated chronic pain therapy positioning.
| Leading Market Players |
|---|
| Medtronic plc |
| Boston Scientific Corporation |
| Abbott Laboratories |
| LivaNova PLC |
| Cochlear Ltd. |
| Biotronik SE & Co. KG |
| Nevro Corp. |
| electroCore, Inc. |
| SetPoint Medical |
| Others |
Cost & Logistics Intelligence
Commodity volatility in iridium and platinum feedstocks compresses gross margins on high-channel-count implantable pulse generators while simultaneously forcing tiered pricing stratification across premium algorithm-enabled systems and standard fixed-parameter devices. This raw material risk vector determines both the spread between premium and economy pricing tiers and the geographic reconfiguration of electrode fabrication capacity toward captive supply regions.
Pricing Analysis
United States hospital systems command 15-25% price premiums over German procurement for equivalent neuromodulation systems due to mature reimbursement codes and consolidated GPO purchasing power. Pricing stratifies across premium closed-loop systems with automated therapeutic adjustment, standard programmable devices, and economy fixed-parameter generators. Cost compression in the standard tier is intensifying because precious metal electrode volatility erodes manufacturer margins without commensurate pricing power. Integrated delivery networks exhibit highest price sensitivity through bundled payment models, while academic medical centers prioritize algorithm capabilities over unit cost.
Supply Chain Analysis
Tariff exposure between the United States and China dominates supply chain risk planning for semiconductor packaging and wireless transmission components used in leadless pacemaker designs. Electrode fabrication concentrates in Germany, the United States, and Japan, with Baden-Württemberg clusters narrowing European dependency on Asian iridium processing. Manufacturing draws from platinum-group metal refiners in South Africa, precision semiconductor foundries in Taiwan, and polymer substrate suppliers in the United States. Single-source vulnerability persists in high-density microelectrode array production. Distribution runs through hospital procurement committees and GPO contracts rather than traditional device distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The bioelectric medicine market operates as a defensive-moat industry where regulatory entrenchment creates durable competitive positioning. FDA breakthrough designation pathways and EU MDR conformity requirements impose capital barriers that protect validated market positions against unproven entrants.
For Market Incumbents: Entrench algorithm IP through software-as-medical-device licensing models that decouple revenue from hardware replacement cycles. Deepen backward integration into electrode fabrication through German cluster partnerships to offset precious metal volatility. Consolidate hospital system relationships around full-service agreements covering training, remote monitoring, and algorithm updates to raise switching costs against neuromodulation specialists.
For New Entrants and Emerging Players: Japanese electrophysiology departments piloting autonomic-responsive pacing systems represent the most penetrable geography for novel closed-loop platforms seeking regulatory validation outside FDA queues. Target home healthcare monitoring ecosystems where GDPR-compliant edge processing architectures bypass incumbent cloud infrastructure advantages. Pursue licensing partnerships with established pulse generator manufacturers rather than full-stack hardware development.
For Investors and Strategic Acquirers: Algorithm development boutiques with neural electrophysiology and real-time embedded systems expertise constitute the highest-conviction acquisition archetype as capability scarcity constrains incumbent R&D velocity. Monitor FDA breakthrough designation awards as inflection indicators for platform validation timelines and reimbursement code development. Long-term viability hinges on securing proprietary biomarker signal processing IP before clinical evidence standards tighten further.
| Strategic Initiative | Industry Significance |
|---|---|
| FDA Breakthrough Designation Pursuit | Accelerates premarket review timelines for novel neuromodulation therapies targeting refractory conditions. |
| Closed-Loop Algorithm Licensing | Creates software-as-medical-device revenue streams independent of hardware replacement cycles. |
| German Manufacturing Cluster Partnership | Secures vertically integrated electrode fabrication capacity for European supply chain autonomy. |
| Hospital System Full-Service Agreement | Consolidates vendor relationships around training, monitoring, and algorithm update bundling. |
| GDPR-Compliant Edge Processing Architecture | Enables real-time therapeutic adjustments without cloud data transfer restrictions. |
Research Approach
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with electrophysiologists, hospital purchasing committee members, biomedical engineers, and GPO contracts managers. Secondary validation drew from FDA 510(k) and PMA filings, EU MDR notified body assessment reports, hospital procurement databases, and CMS Medicare reimbursement data. Bottom-up procedure volume estimates and top-down manufacturer revenue triangulation anchored market sizing across implantable and non-invasive modalities.
Calibration against historical implantation growth rates and reimbursement code expansion timelines informed trajectory assumptions across the projection horizon. Segmentation modeling captured product type, therapy area, end user, and technology dimensions including closed-loop versus open-loop architectures. CAGRs were derived from fitted growth curves applied to procedure volume forecasts and average selling price trajectories. Industry-specific inputs included opioid-sparing protocol adoption curves and EU MDR transition timelines.
Practitioners should monitor FDA breakthrough designation award velocity, notified body capacity bottlenecks, and precious metal commodity indices for early signals requiring forecast revision. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Regenerative Medicine
Th17 Driven Disease Treatment Market
Regenerative Medicine
Orthopedic Regenerative Medicine Market
Regenerative Medicine
US Scar Treatment Market
Regenerative Medicine
Stromal Vascular Fraction Market
Regenerative Medicine
Next Generation Immunotherapies Market
Regenerative Medicine
Hypertrophic and Keloid Scar Treatment Market
Regenerative Medicine
Degenerative Disc Disease Treatment Market
Regenerative Medicine
Longevity and Anti-Senescence Therapy for Cancer Market
Regenerative Medicine
North America Regenerative Medicines Market
Regenerative Medicine
Soft Tissue Repair Market
Regenerative Medicine
Mesotherapy Guns Market
Regenerative Medicine
Epidermal Cell Sheets Market
Regenerative Medicine
US Regenerative Medicine Market
Regenerative Medicine
Tumour-Induced Osteomalacia Market
Regenerative Medicine
Regenerative Artificial Skin Market
Regenerative Medicine
Asia Pacific Platelet Rich Plasma Market