
 North America Regenerative Medicines Market | 2026-2036
North America Regenerative Medicines Market Size, Share, and Industry Trends Forecast 2026-2036
North America Regenerative Medicines Market Analytics
Platform licensing revenue is reconfiguring margin pools away from one-time product sales toward recurring royalty streams in the North America regenerative medicines sector. Novartis AG leverages its CAR-T manufacturing infrastructure to dominate commercial cell therapy supply. Bristol-Myers Squibb anchors its position through sustained investment in pluripotent stem cell platforms. Vertex Pharmaceuticals differentiates via specialized gene-editing capabilities targeting sickle cell disease.
Regenerative medicines encompass biologically active therapeutics engineered to repair, replace, or regenerate human cells, tissues, or organs, typically manufactured through viral vector transduction, ex vivo cell expansion, or scaffold-guided tissue architecture. Cell therapy leads commercial value generation through autologous and allogeneic modalities, while gene therapy represents the fastest-expanding segment driven by CRISPR-enabled precision targeting. Tissue engineering occupies a mature niche in orthopedic and wound applications with stable reimbursement profiles.
FDA's regenerative medicine advanced therapy designation accelerates review timelines for qualifying products, compressing development cycles and reshaping capital allocation decisions. Health Canada and the US National Institutes of Health jointly influence trial design standards through harmonized good manufacturing practice guidelines. Stakeholders must monitor CMS coverage determination patterns for gene therapies, as these decisions will determine patient access velocity and manufacturer pricing power across the North American market.
Market Dynamics
Cell therapy manufacturing capacity constraints are forcing developers to restructure capital deployment toward distributed production networks rather than centralized facilities. FDA's regenerative medicine advanced therapy designation has compressed approval timelines, accelerating competitive entry and intensifying margin pressure across the US Northeast biotech corridor.
Growth Catalysts
- FDA Expedited Pathways:The regenerative medicine advanced therapy designation compresses clinical review timelines, enabling faster commercialization for qualifying cell and gene therapies targeting unmet oncology needs.
- Autologous Manufacturing Scale-Up:Viral vector production capacity expansion across Massachusetts and North Carolina contract manufacturing organizations is resolving prior supply bottlenecks for CAR-T programs.
- CMS Coverage Determinations:National coverage decisions for gene therapies in sickle cell disease and inherited retinal disorders are establishing reimbursement precedents that accelerate patient access velocity.
Market Restraints
- Plasmid DNA Supply Concentration:Viral vector manufacturing depends on plasmid suppliers concentrated in California and Texas, creating single-source vulnerability for CDMO networks.
- Allogeneic Immune Evasion Limits:Persistent graft-versus-host disease risks and HLA matching complexity constrain off-the-shelf cell therapy scalability beyond oncology into autoimmune indications.
- IRA Price Negotiation Exposure:Medicare drug price negotiation provisions expose approved gene therapies to mandatory price controls once small-molecule exclusivity cliffs expire.
Strategic Opportunities
- Canadian Market Expansion:Health Canada's alignment with FDA manufacturing standards creates regulatory arbitrage for US-approved therapies seeking earlier northern market entry.
- In Vivo Gene Editing:CRISPR-LNP delivery convergence enables direct liver-targeted editing without ex vivo cell manipulation, collapsing manufacturing complexity for metabolic disorders.
- Specialty Pharmacy Networks:Limited distribution channel partnerships with CVS Specialty and Accredo are capturing patient data streams that inform real-world evidence generation for payers.
Industry Challenges
- Vector Manufacturing Talent Scarcity:GMP-compliant viral vector production requires hybrid skill sets spanning molecular biology and aseptic processing that remain underrepresented in US labor markets.
- Batch Release Timeline Variability:Potency assay validation for cell therapy lots extends QC hold times, compressing shelf-life windows and complicating just-in-time logistics for hospital infusion centers.
- Cross-Border Cold Chain Integrity:Temperature excursion risks during US-Canada shipments of cryopreserved cellular products demand redundant monitoring infrastructure that elevates per-unit logistics costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Regenerative Medicines Market |
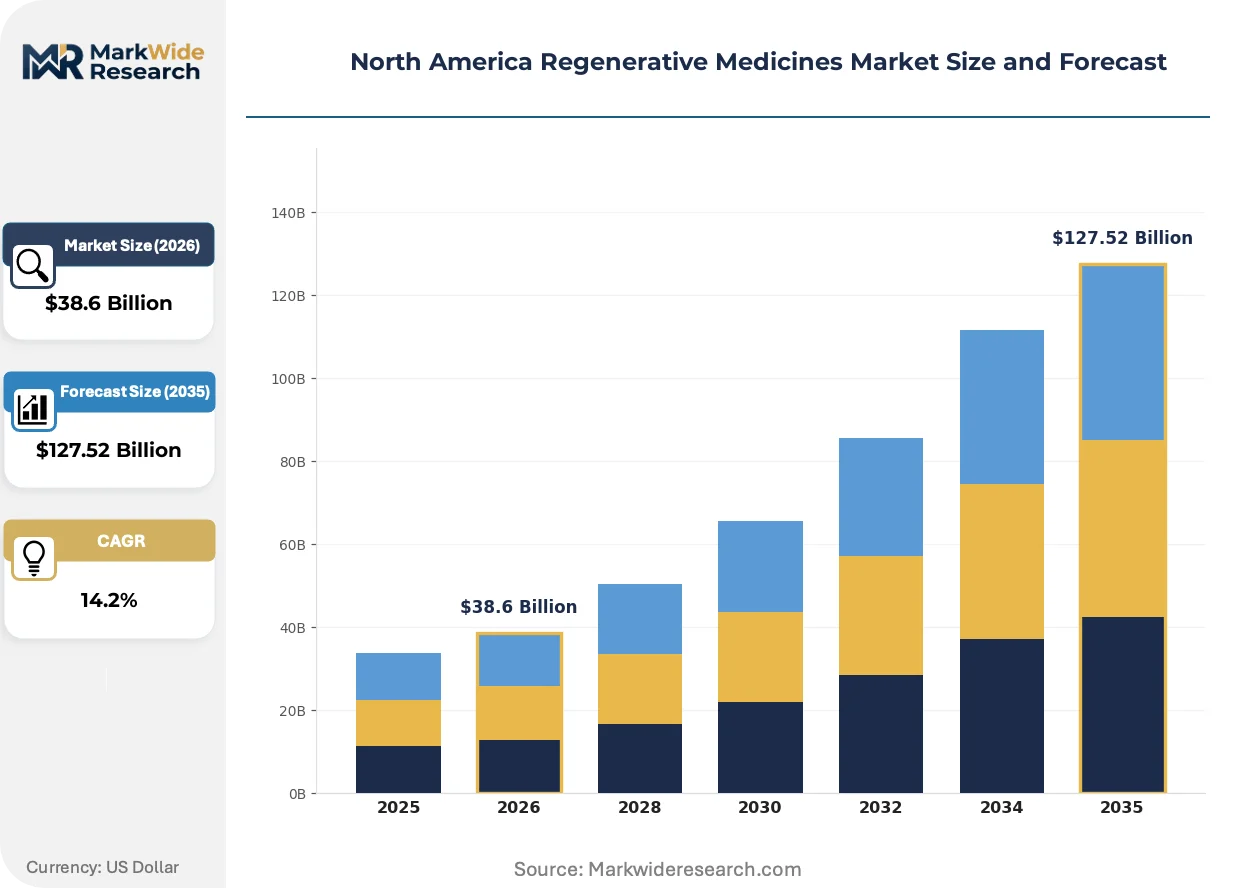
| Market Size in 2026 | $38.6 Billion |
| Market Size in 2035 | $127.52 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cell Therapy, Gene Therapy, Tissue Engineering, Platelet-Rich Plasma End User: Hospitals, Research Institutes, Biotechnology Firms, Academic Institutions Application: Orthopedics, Cardiovascular, Neurology, Dermatology Delivery Mode: Intravenous, Subcutaneous, Topical, Intra-articular |
| Companies Covered | Novartis AG, Bristol-Myers Squibb, Johnson & Johnson, Vertex Pharmaceuticals, Integra LifeSciences, Pfizer, Roche Holding AG, AstraZeneca, Organogenesis, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Regenerative Medicines Market Evolving Landscape
Manufacturing modality diversification is collapsing the cost structure of cell therapy production while regulatory science advances compress development timelines. These shifts are reconfiguring competitive positioning around operational execution rather than discovery chemistry alone.
Allogeneic cell sourcing is migrating from patient-matched autologous collection toward healthy donor-derived master cell banks. Academic medical centers in Texas and Florida are adopting these off-the-shelf platforms for lymphoma protocols, reducing vein-to-vein timelines from weeks to days. This migration from bespoke manufacturing is enabling treatment of acute indications where disease progression outpaces autologous production.
Health Canada and FDA harmonization on viral vector potency testing standards is eliminating redundant validation studies for cross-border submissions. The industrial consequence is consolidated CMC documentation that accelerates parallel approval pathways. Oncology developers targeting simultaneous US and Canadian launches are restructuring regulatory affairs teams around unified submission packages rather than sequential filings.
Hospital procurement committees are consolidating gene therapy purchasing under centralized pharmacy and therapeutics boards. This channel concentration displaces traditional physician-driven prescribing autonomy with formulary-driven access controls. The shift is most visible in US Northeast academic medical centers where value-based contracts with manufacturers now precede treatment site designation.
North America Regenerative Medicines Market Segmentation
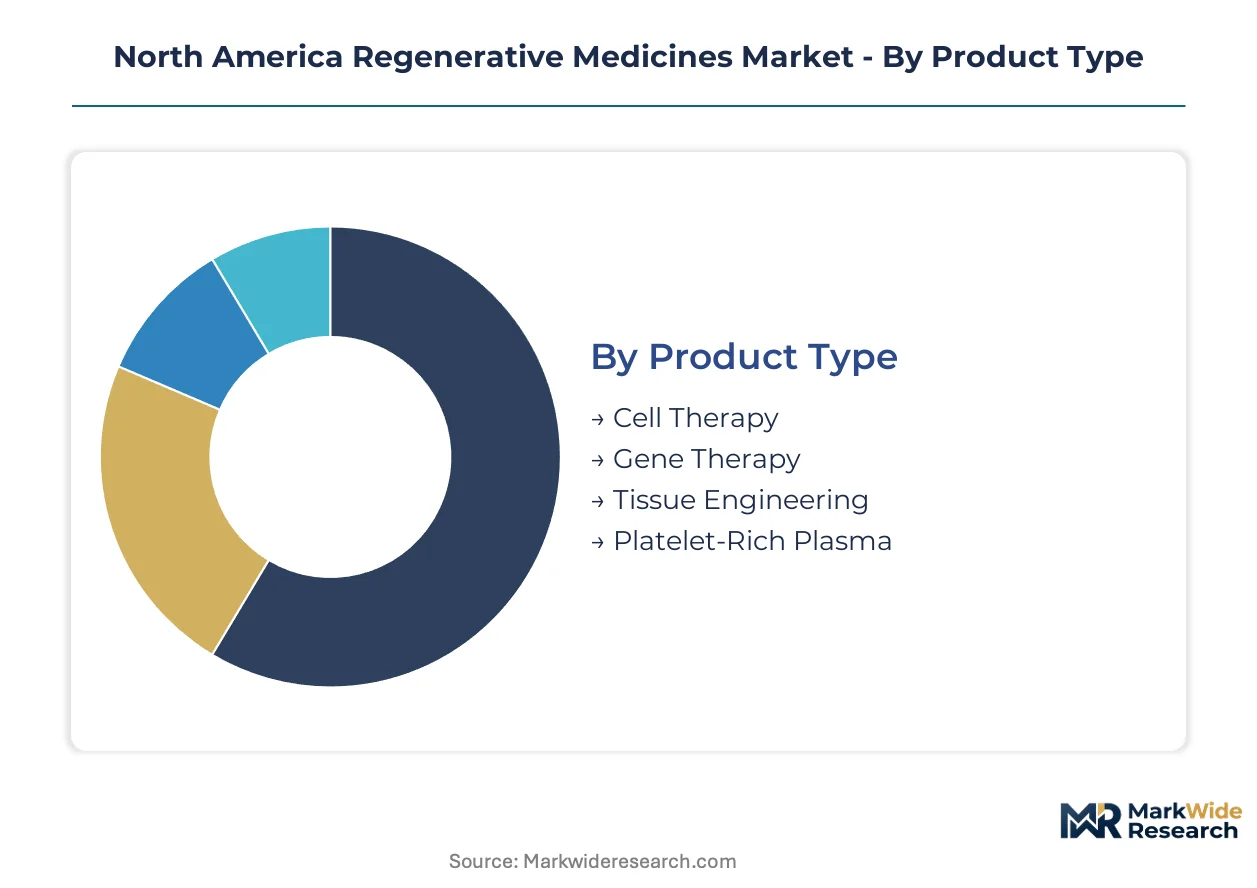
Segmentation in regenerative medicines reveals divergent margin structures and capital intensity requirements across manufacturing modalities. Each category exposes distinct supply chain vulnerabilities and reimbursement pathways that shape competitive positioning.
Product Type:
After-sales service intensity varies dramatically across product types, with autologous cell therapies demanding continuous patient monitoring infrastructure while tissue-engineered products require surgical training partnerships.
- Cell Therapy:Autologous and allogeneic modalities involve ex vivo cell expansion, viral vector transduction, and cryopreservation logistics. US Northeast academic medical centers concentrate demand for CAR-T protocols, constrained by vein-to-vein timeline compression and manufacturing slot scarcity.
- Gene Therapy:CRISPR-enabled and viral vector-delivered therapeutics target monogenic disorders with single-administration curative intent. Massachusetts and North Carolina biotech clusters anchor commercial production, driven by FDA regenerative medicine advanced therapy designation acceleration.
- Tissue Engineering:Scaffold-guided architecture for orthopedic and wound applications with established reimbursement codes.
- Platelet-Rich Plasma:Point-of-care centrifugation systems for sports medicine and aesthetic applications.
Cell therapy holds the largest share; momentum sits with gene therapy.
End User:
Cost tier stratification separates capital-intensive hospital infusion centers from research-focused institutions with grant-dependent procurement cycles.
- Hospitals:Integrated delivery networks with centralized pharmacy and therapeutics committees controlling formulary access. US Northeast corridor facilities concentrate gene therapy purchasing under value-based contracts, displacing physician-driven prescribing autonomy.
- Biotechnology Firms:Platform licensing and pipeline development operations spanning discovery through commercial manufacturing. Texas and Florida academic medical center partnerships accelerate allogeneic protocol adoption.
- Research Institutes:Early-phase translational studies and IND-enabling toxicology programs.
- Academic Institutions:Investigator-initiated trials and training program infrastructure.
Hospitals command the dominant procurement volume; biotechnology firms are climbing the fastest.
Application:
Volume concentration in orthopedic applications masks steeper expansion trajectories in neurologic indications where unmet need drives premium pricing tolerance.
- Orthopedics:Cartilage repair scaffolds and bone graft substitutes with established CPT reimbursement. Stable demand across ambulatory surgery centers and hospital outpatient departments.
- Cardiovascular:Cardiac cell therapy and angiogenic gene delivery for ischemic tissue. Clinical trial concentration in Cleveland Clinic and Texas Heart Institute networks.
- Neurology:Gene therapies for inherited neurodegenerative disorders with orphan drug economics.
- Dermatology:Bioengineered skin substitutes and PRP applications for chronic wound management.
Orthopedics holds the largest share; momentum sits with neurology.
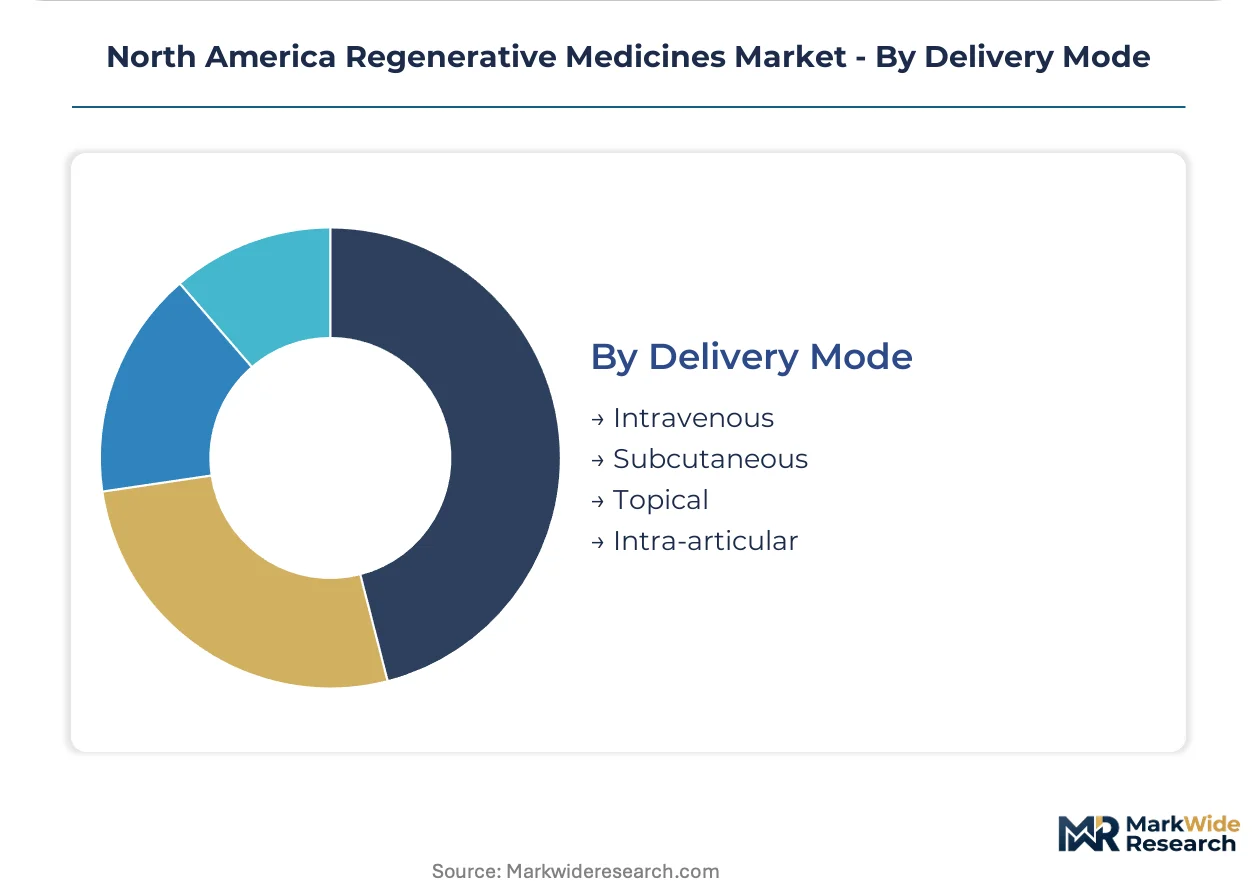
Delivery Mode:
Supply concentration in intravenous administration reflects CAR-T and gene therapy manufacturing scale, while intra-articular delivery maintains decentralized compounding pharmacy networks.
- Intravenous:Systemic distribution for hematologic malignancies and metabolic gene therapies. Cryopreserved product thaw protocols require specialized infusion center infrastructure with 30-minute administration windows.
- Subcutaneous:Depot formulations for sustained protein secretion from engineered cells. Emerging preference for reduced healthcare utilization versus inpatient infusion.
- Topical:Direct application for dermatologic and ophthalmic tissue engineering products.
- Intra-articular:Joint space injection for cartilage regeneration and osteoarthritis management.
Intravenous delivery holds the largest share; subcutaneous routes are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price sensitivity varies sharply across North America. Canadian provinces negotiate aggressively on gene therapy reimbursement, while US academic medical centers absorb premium pricing for CAR-T protocols. Mexican demand concentrates on lower-cost tissue engineering applications.
United States
FDA's regenerative medicine advanced therapy designation drives developer clustering in Massachusetts and North Carolina. CMS national coverage determinations for sickle cell gene therapies establish reimbursement precedents that accelerate patient access. The Boston-Cambridge biotech corridor anchors CAR-T manufacturing infrastructure with Novartis AG and Bristol-Myers Squibb operating commercial-scale facilities.
Canada
Health Canada's alignment with FDA good manufacturing practice standards enables parallel approval pathways for US-developed therapies. Provincial drug plans in Ontario and Quebec negotiate value-based agreements that condition reimbursement on real-world evidence generation. Toronto and Montreal academic medical centers participate in cross-border clinical trials for allogeneic cell platforms.
Mexico
COFEPRIS regulatory pathways for regenerative products remain less harmonized with FDA standards, slowing gene therapy commercial entry. Private hospital networks in Mexico City and Monterrey drive demand for orthopedic tissue engineering and platelet-rich plasma applications. Price compression limits cell therapy penetration to medical tourism segments rather than domestic reimbursement.
North America Regenerative Medicines Market Competitive Landscape
Capability concentration sits with specialized gene-editing developers; scale advantage sits with diversified pharmaceutical conglomerates. The market structures around three tiers: integrated biopharmaceuticals with manufacturing infrastructure, mid-cap platform specialists, and contract development organizations capturing outsourced production. Dominant competitive moves include strategic partnerships for viral vector capacity and technology licensing for CRISPR delivery platforms.
Within the integrated pharmaceutical tier, Novartis AG, Bristol-Myers Squibb, and Vertex Pharmaceuticals occupy positions defined by manufacturing scale and therapeutic focus. Novartis AG exemplifies the CAR-T commercial infrastructure archetype. Bristol-Myers Squibb represents sustained pluripotent stem cell platform investment. Vertex Pharmaceuticals anchors the gene-editing specialization vector targeting monogenic disorders.
| Leading Market Players |
|---|
| Novartis AG |
| Bristol-Myers Squibb |
| Johnson & Johnson |
| Vertex Pharmaceuticals |
| Integra LifeSciences |
| Pfizer |
| Roche Holding AG |
| AstraZeneca |
| Organogenesis |
| Others |
Value Network & Pricing Analysis
Plasmid DNA suppliers concentrated in California and Texas capture disproportionate margin pools from viral vector manufacturers, feeding downstream pricing power asymmetries between contract development organizations and biopharmaceutical sponsors.
Pricing Analysis
After-sales service contracts for patient monitoring and real-world evidence generation drive lifetime value in autologous cell therapy, with three-tier pricing structure across premium, standard, and economy levels tied to vein-to-vein timeline guarantees and manufacturing slot priority. Price differentiation hinges on FDA regenerative medicine advanced therapy designation status and allogeneic versus autologous processing complexity. Pricing pressure stems from CMS national coverage determinations conditioning reimbursement on outcomes data. Hospital pharmacy and therapeutics committees exhibit highest price sensitivity; biotechnology firms with platform licensing models show lowest.
Supply Chain Analysis
Single-source vulnerability in plasmid DNA supply between California contract manufacturers and East Coast viral vector producers dominates risk profiles for CAR-T programs. Geographic supply concentration spans California, Texas, and Massachusetts for plasmid production, viral vector manufacturing, and final cell processing respectively. Raw material dependencies include fetal bovine serum, synthetic growth media, and cryopreservation solutions. Distribution runs through limited specialty pharmacy networks with cold chain integrity requirements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating through hospital procurement committee consolidation, with integrated delivery networks displacing physician-driven purchasing autonomy across the US Northeast corridor.
For Market Incumbents: Insulate manufacturing margins by securing captive plasmid supply through backward integration into California-based nucleic acid production facilities. Defend against allogeneic platform disruption by accelerating autologous vein-to-vein timeline compression below fourteen days. Prioritize Health Canada parallel filing strategies to capture regulatory arbitrage before harmonization gaps close. For New Entrants and Emerging Players: Establish a beachhead in Canadian provincial drug plan negotiations where value-based agreements create lower barriers than US CMS coverage determinations. Target orthopedic tissue engineering applications in Mexico City private hospital networks where price compression limits incumbent cell therapy penetration. Lead with point-of-care platelet-rich plasma systems requiring minimal GMP infrastructure. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across in vivo gene editing sub-segments as CRISPR-LNP delivery collapses ex vivo manufacturing requirements. Long-term viability favors platform licensors with recurring royalty structures over product-centric developers facing IRA price negotiation exposure. Acquisition target archetype: mid-cap viral vector CDMOs with FDA-established GMP track records. Signal to watch: Health Canada-FDA divergence on potency assay validation standards.| Strategic Initiative | Industry Significance |
|---|---|
| Manufacturing Scale-Up | Resolves viral vector bottlenecks for Novartis AG and Bristol-Myers Squibb CAR-T programs. |
| Regulatory Approval Pathway | FDA regenerative medicine advanced therapy designation compresses review timelines for qualifying oncology therapies. |
| Platform Licensing Agreement | Shifts margin pools from one-time sales toward recurring royalty streams in gene-editing specialization. |
| Hospital System Partnership | Captures patient data streams through CVS Specialty and Accredo limited distribution channels. |
| Pipeline Diversification | Vertex Pharmaceuticals extends sickle cell gene-editing capabilities into additional monogenic disorders. |
Research Methodology
Operator-level perspectives from cell therapy manufacturing directors, FDA regulatory affairs leads, hospital formulary directors, and payer access specialists anchored the qualitative base. Primary interviews combined with secondary validation from FDA filings, ClinicalTrials.gov, CMS national coverage determination databases, and Health Canada submission records. Bottom-up patient-flow modeling and top-down revenue triangulation across product type, application, and delivery mode dimensions converged on segment sizing.
Scenario-bracketing framed sensitivity analysis across the projection horizon, with high-low ranges reflecting manufacturing capacity expansion trajectories and reimbursement policy shifts. Segmentation dimensions modeled included product type, end user archetype, therapeutic application, and regional regulatory cluster. CAGRs derived from patient population incidence curves, treatment penetration assumptions, and pricing evolution patterns. Industry-specific forecast inputs incorporated viral vector production capacity buildout schedules and CMS coverage determination timelines.
Stress conditions across plasmid supply disruption, IRA price negotiation implementation, and allogeneic immune evasion breakthroughs were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions on manufacturing yield improvements and regulatory harmonization progress. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Regenerative Medicine
Th17 Driven Disease Treatment Market
Regenerative Medicine
Global Breast Reconstruction Market
Regenerative Medicine
Hyper Personalized Medicine Market
Regenerative Medicine
Global Orthopedic Regenerative Surgical Products Market
Regenerative Medicine
Stromal Vascular Fraction Market
Regenerative Medicine
Global Cartilage Repair-Cartilage Regeneration Market
Regenerative Medicine
Europe Longevity and Anti-Senescence Therapy Market
Regenerative Medicine
Bone Regeneration Market
Regenerative Medicine
Platelet Rich Plasma Market
Regenerative Medicine
Global Vaginal Rejuvenation Market
Regenerative Medicine
Next Generation Immunotherapies Market
Regenerative Medicine
Cytokine Storm Therapy Market
Regenerative Medicine
Cartilage Degeneration Market
Regenerative Medicine
Epidermal Cell Sheets Market
Regenerative Medicine
China Longevity and Anti-Senescence Therapy Market
Regenerative Medicine
Bioelectric Medicine Market