
 Autologous Matrix Induced Chondrogenesis Market | 2026-2036
Autologous Matrix Induced Chondrogenesis Market Size, Share, and Industry Trends Forecast 2026-2036
Autologous Matrix Induced Chondrogenesis Market Intelligence
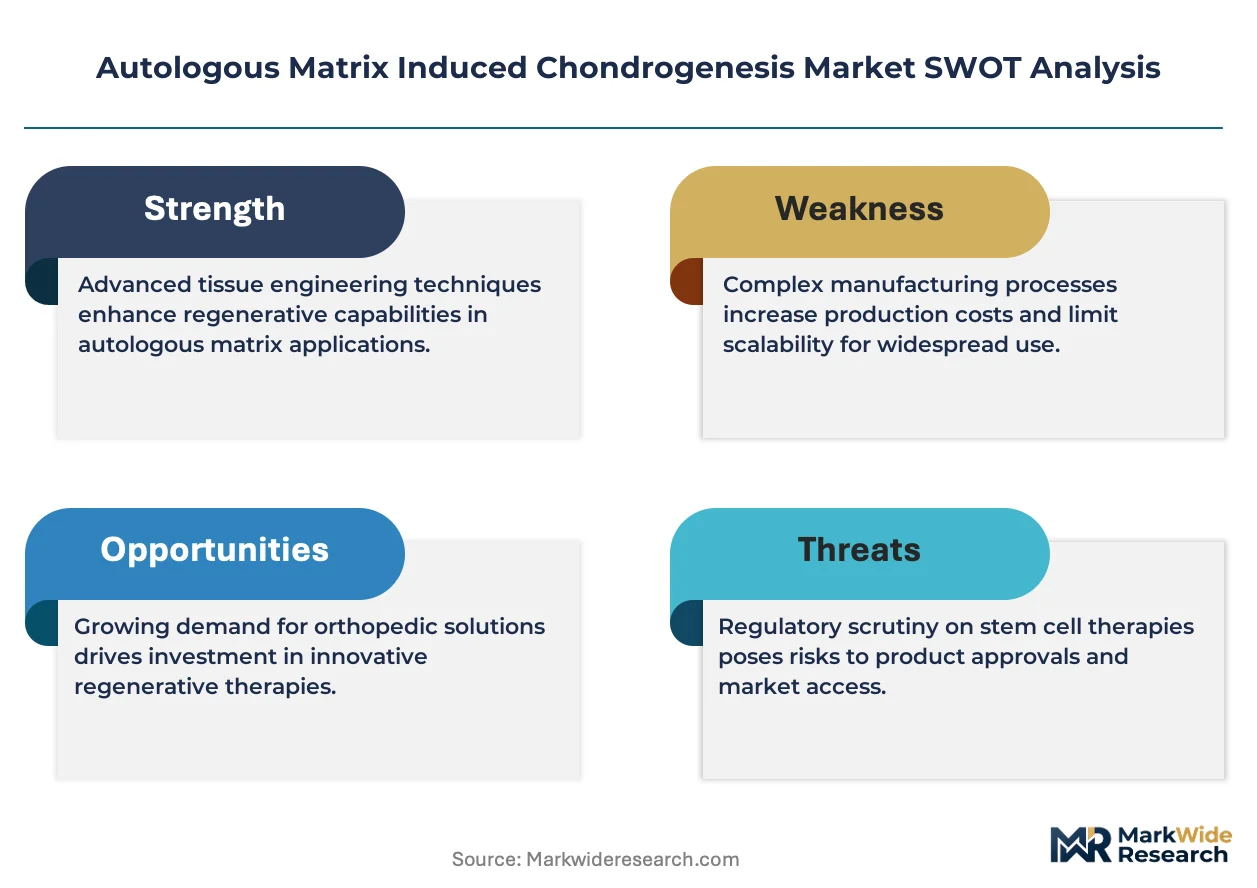
Expansion of specialized manufacturing facilities in Europe is realigning the supply chain for critical biomaterials and cell cultures. Geistlich Pharma AG leverages its deep expertise in regenerative biomaterials to command a strong market position in collagen-based scaffolds. Smith & Nephew plc competes through its extensive global distribution network and a focus on minimally invasive surgical solutions. Zimmer Biomet Holdings differentiates its offering with an integrated portfolio of orthopedic implants and complementary surgical tools.
Autologous Matrix Induced Chondrogenesis is a two-stage cartilage repair technique where a patient's own chondrocytes are expanded and seeded onto a biocompatible matrix. This construct is then implanted to promote regeneration of hyaline-like tissue. Scaffold systems represent a pivotal product type, with innovation in biomaterials driving procedural efficacy. While sports injuries are a primary application, treating degenerative osteoarthritis presents the largest long-term opportunity for specialized hospitals.
Regulatory pathways for cell-based therapies, governed by agencies like the US FDA and the EMA in Europe, impose stringent requirements for clinical trials and manufacturing. Approval processes in other key markets, such as Japan's PMDA, also demand extensive clinical data demonstrating long-term safety and efficacy. Consequently, securing favorable reimbursement codes from both public and private payers becomes essential for ensuring wider clinical adoption and surgeon uptake.
Market Dynamics
The convergence of biomaterial engineering and personalized cell therapy is the central force shaping the market. Demand for more durable and less invasive cartilage repair, particularly from athletes, is accelerating innovation in patient-specific scaffold design and cell culturing techniques.
Growth Catalysts
- Rising Sports Injury Rates:Increasing participation in amateur and professional sports in North America and Europe elevates the frequency of chondral defects, creating a consistent and growing patient pipeline for cartilage repair procedures.
- Favorable Reimbursement Frameworks:The establishment of specific procedural codes for cell-based therapies by payers in markets like Germany and the United States facilitates wider clinical adoption and improves economic viability for hospitals.
- Biomaterial Advancements:Innovation in collagen and synthetic polymer scaffolds enhances chondrocyte viability and integration with native tissue, improving surgical outcomes and reducing the risk of implant failure.
Market Restraints
- High Procedural and Input Costs:The two-stage surgical process, coupled with the significant expense of GMP-grade cell culturing and advanced biomaterials, restricts patient access in healthcare systems with limited reimbursement.
- Stringent Regulatory Pathways:Classification as an Advanced Therapy Medicinal Product (ATMP) by the EMA and similar designations by the US FDA imposes lengthy and costly clinical trial requirements, delaying market entry.
- Specialized Surgeon Skillset:Successful outcomes are highly dependent on the technical expertise of orthopedic surgeons in cell handling and implantation, creating a training bottleneck that limits the procedure's widespread availability.
Strategic Opportunities
- Expansion into Osteoarthritis Treatment:Applying AMIC technology to the vast patient population suffering from degenerative osteoarthritis, beyond acute sports injuries, represents the largest long-term market expansion opportunity.
- Penetration of Asian Markets:Developing tailored market entry strategies for countries like Japan and South Korea, where orthopedic care standards are advancing, offers significant growth potential outside of traditional markets.
- Development of Combination Therapies:Integrating AMIC with biologic agents like platelet-rich plasma or growth factors could create synergistic effects, enhancing tissue regeneration and justifying premium pricing.
Industry Challenges
- Complex Cold-Chain Logistics:Managing the time- and temperature-sensitive supply chain for harvesting, transporting, and culturing autologous chondrocytes presents significant operational risks and requires specialized infrastructure.
- Lack of Outcome Standardization:Variability in cell expansion protocols and surgical techniques across clinics leads to inconsistent patient outcomes, complicating the collection of long-term efficacy data required by regulators.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Autologous Matrix Induced Chondrogenesis Market |
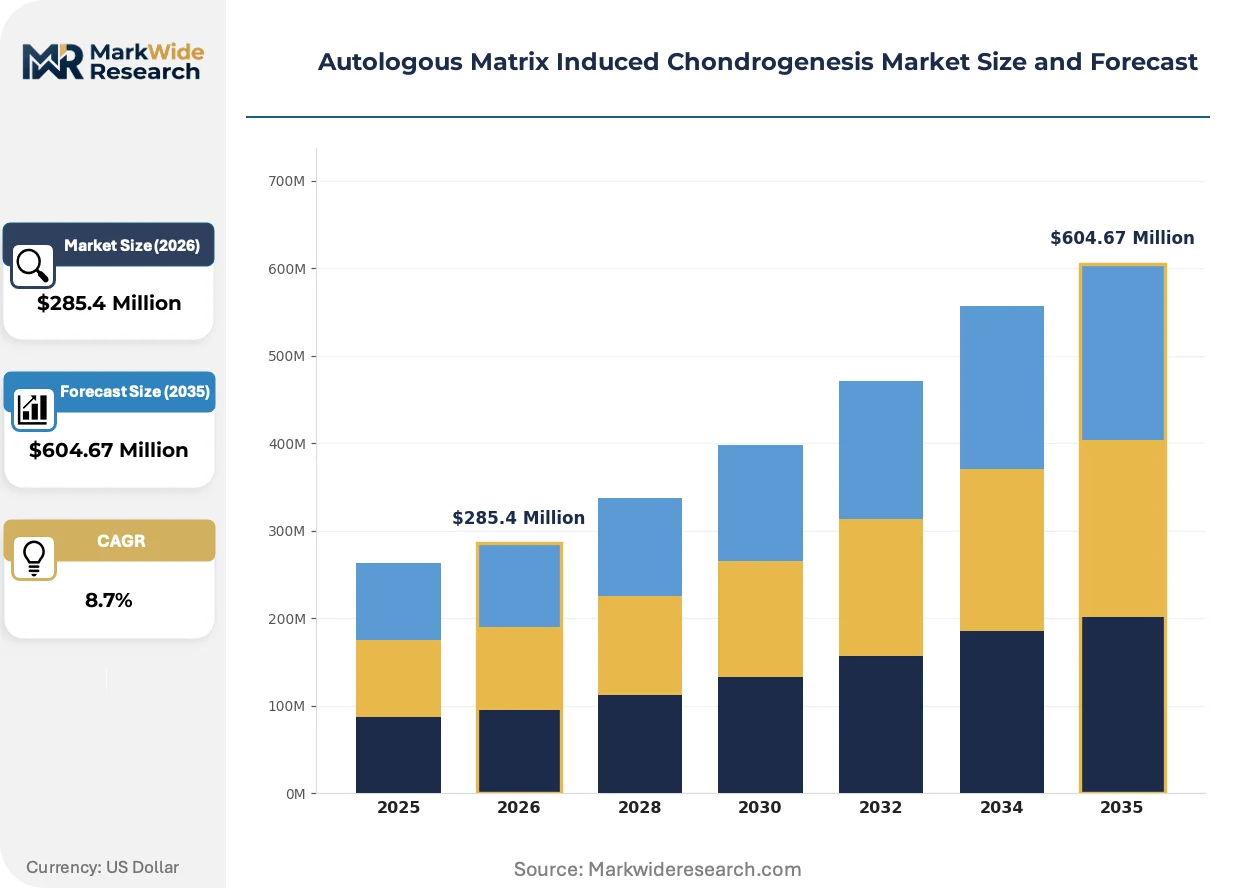
| Market Size in 2026 | $285.4 Million |
| Market Size in 2035 | $604.67 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Chondral Constructs, Cell Cultures, Biomaterials, Scaffold Systems Application: Sports Injuries, Osteoarthritis, Trauma Repair, Tissue Engineering End User: Orthopedic Clinics, Hospitals, Rehabilitation Centers, Research Institutions Delivery Mode: Invasive Procedures, Minimally Invasive Techniques, Outpatient Services, Surgical Interventions |
| Companies Covered | Anika Therapeutics, Inc., B. Braun Melsungen AG, Smith & Nephew plc, Zimmer Biomet Holdings, Geistlich Pharma AG, BioTissue AG, Arthro-Kinetics, JRI Orthopaedics Ltd., Matricel GmbH, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Autologous Matrix Induced Chondrogenesis Market Strategic Shifts & Innovations
The intersection of advanced manufacturing and cell therapy is defining the next phase of market evolution. This is creating new possibilities for patient-specific treatments while also introducing pressures to streamline complex and costly surgical workflows for wider adoption.
Advances in 3D bioprinting allow for the fabrication of custom scaffolds that mimic the patient's specific cartilage defect. Specialized orthopedic clinics in the United States and Germany are early adopters of this technology for complex cases. This capability is electrifying the field by enabling the creation of anatomically precise matrices, which improves implant integration and shortens patient recovery periods.
Europe's regulatory framework for Advanced Therapy Medicinal Products (ATMPs), administered by the EMA, establishes a harmonized pathway for cell-based therapies. It imposes rigorous requirements for manufacturing consistency, potency assays, and long-term patient follow-up. This directly impacts developers of new scaffold systems, forcing substantial investment in GMP-compliant facilities and post-market surveillance programs to gain and maintain market access.
A preference for integrated surgical solutions is altering procurement patterns within large hospital networks. Orthopedic departments are shifting away from sourcing individual components from multiple vendors toward single-supplier kits that include the scaffold, instrumentation, and cell processing services. This demand for bundled solutions is most visible in the United States, driven by a need to standardize procedures and simplify supply chain management.
Autologous Matrix Induced Chondrogenesis Market Segmentation
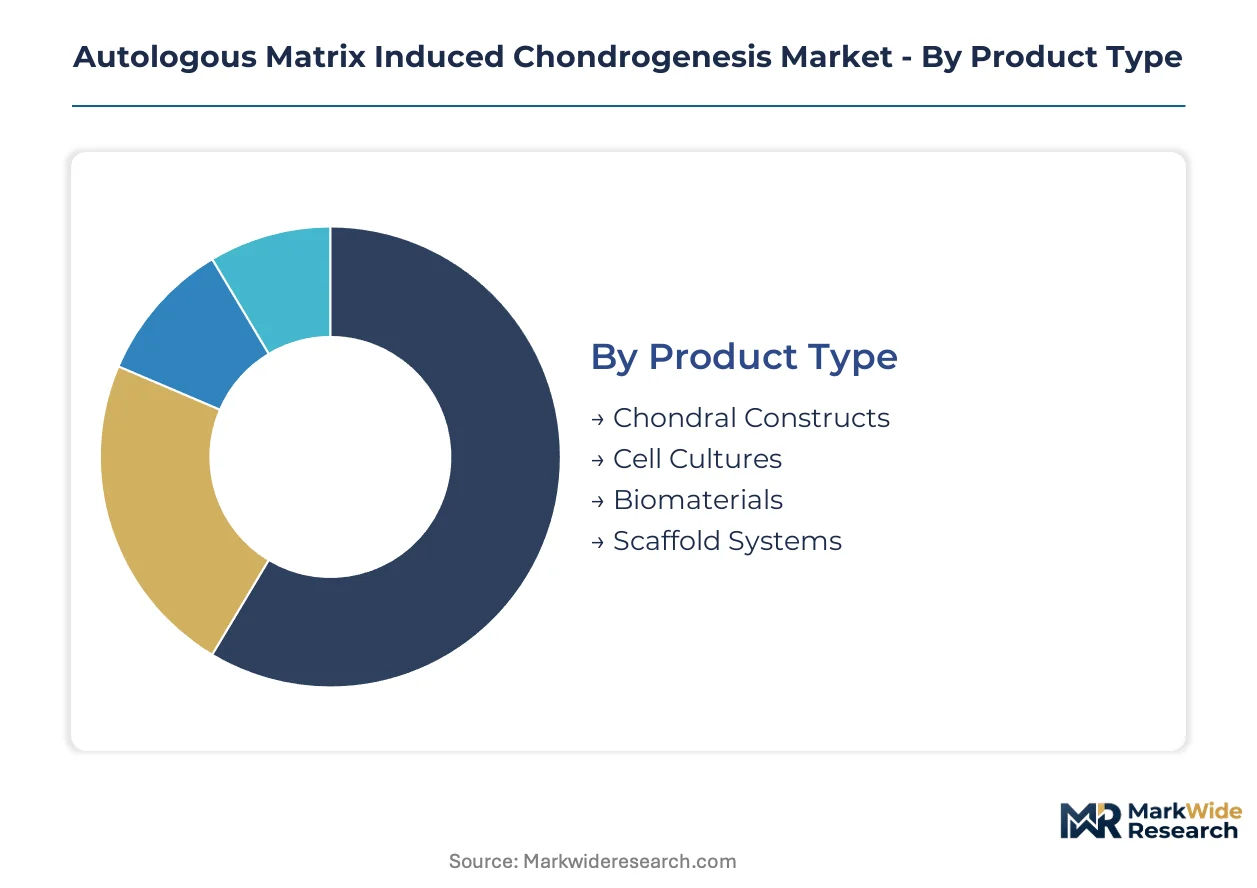
The Autologous Matrix Induced Chondrogenesis market exhibits diverse characteristics across its constituent parts, reflecting varied technological approaches, clinical applications, and end-user requirements. Understanding these segments clarifies the market's current structure and its potential for future expansion. This detailed breakdown highlights areas of innovation and established practice.
Product Type:
The market for product types reflects a critical balance between high-volume, standardized biomaterials and premium, patient-specific chondral constructs.
- Scaffold Systems:These engineered matrices provide a temporary framework for chondrocyte adhesion and proliferation, often composed of collagen or synthetic polymers. Innovation in these systems, particularly with 3D bioprinting, improves anatomical fit and integration with native tissue.
- Chondral Constructs:These advanced products combine a patient's own expanded chondrocytes seeded onto a biocompatible scaffold, forming a ready-to-implant tissue engineered graft. Demand is concentrating in specialized orthopedic centers in Germany and the United States, driven by a need for regenerative solutions.
- Cell Cultures:This segment encompasses the processes and materials required to expand autologous chondrocytes from a patient's biopsy into a sufficient quantity for implantation.
- Biomaterials:These are the raw materials, such as collagen, hyaluronic acid, or synthetic polymers, used to fabricate scaffolds and other components for cartilage repair.
Mature deployment sits with Biomaterials. Newer deployment is concentrated in Scaffold Systems.
Application:
Clinical applications for AMIC range from acute traumatic injuries to chronic degenerative conditions, each presenting distinct procedural demands and patient populations.
- Sports Injuries:This application addresses focal chondral defects resulting from athletic trauma, particularly in professional and amateur athletes. Rising participation in sports in North America and Europe elevates the frequency of these defects, creating a consistent patient pipeline.
- Osteoarthritis:This represents the largest long-term opportunity, focusing on repairing cartilage damage in patients suffering from degenerative joint disease. The vast patient population in the United States and Europe drives significant research and development efforts in this area.
- Trauma Repair:This segment includes the treatment of cartilage damage resulting from non-sports-related accidents or acute injuries.
- Tissue Engineering:This broad application encompasses the use of AMIC principles for general tissue regeneration beyond specific cartilage repair.
Sports injuries currently drive a significant portion of procedural volume. Osteoarthritis treatment holds the greatest potential for future expansion.
End User:
The end-user landscape for AMIC procedures is shaped by the need for specialized surgical environments and dedicated post-operative care.
- Hospitals:Large hospital networks, particularly those with advanced orthopedic departments, serve as primary end-users, integrating AMIC procedures into their surgical offerings. These facilities benefit from bundled solutions that simplify procurement and standardize care.
- Orthopedic Clinics:Specialized orthopedic clinics, especially those focused on sports medicine, are critical end-users due to their expertise in cartilage repair and patient-specific treatment plans. Clinics in Germany and the United States are early adopters of advanced technologies like 3D bioprinting.
- Rehabilitation Centers:These centers play a crucial role in the post-operative recovery phase, providing physical therapy and monitoring patient progress after AMIC procedures.
- Research Institutions:Academic and private research institutions are involved in developing new biomaterials, cell expansion techniques, and clinical protocols for AMIC.
Hospitals represent the primary setting for complex AMIC surgeries. Specialized orthopedic clinics are gaining share due to focused expertise.
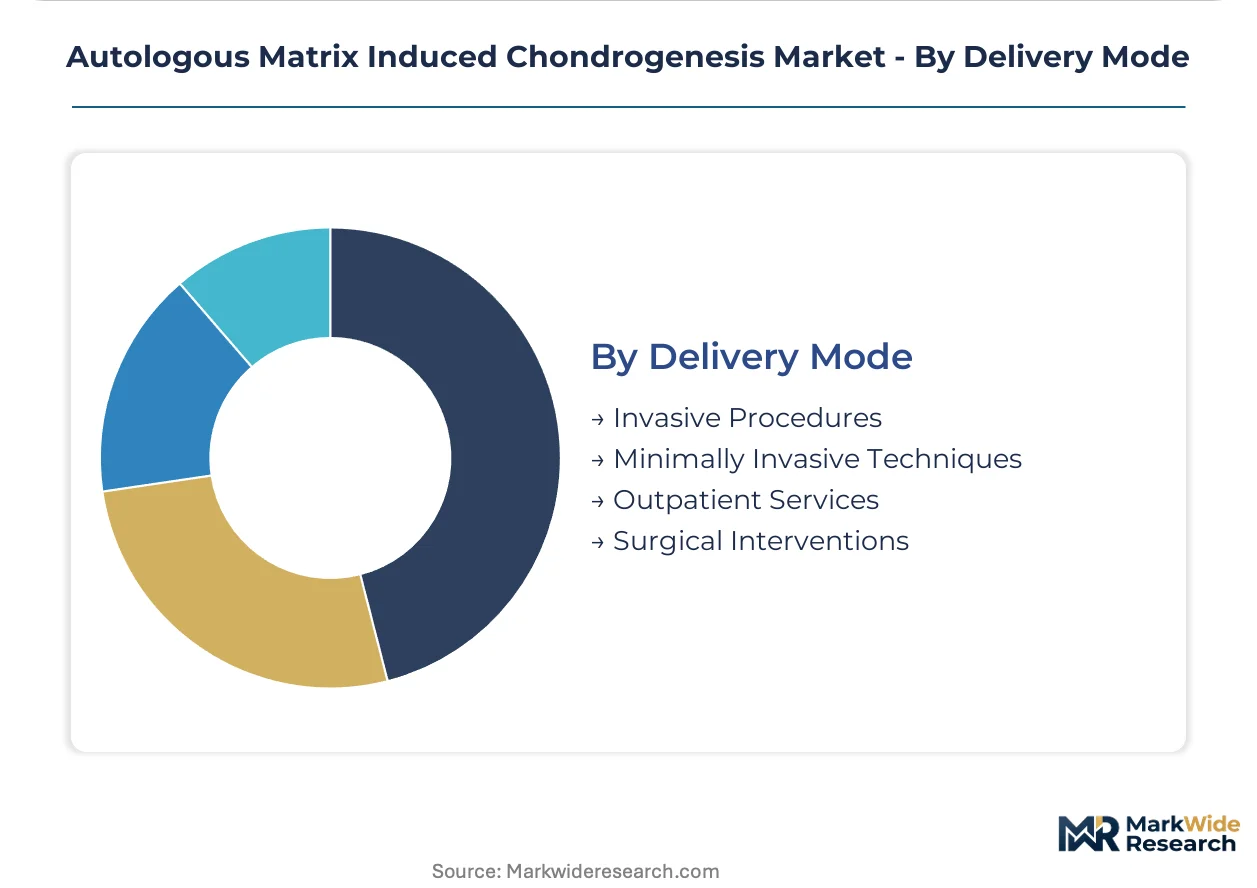
Delivery Mode:
Delivery modes for AMIC procedures are evolving, driven by efforts to reduce invasiveness and improve patient recovery times.
- Minimally Invasive Techniques:These approaches, often involving arthroscopy, aim to reduce surgical trauma and accelerate patient recovery. Demand for less invasive options is intensifying among athletes seeking quicker return to activity.
- Invasive Procedures:Traditional open surgical techniques are used for more complex or extensive cartilage defects, requiring larger incisions for direct access to the joint. These procedures remain the standard for certain intricate cases.
- Outpatient Services:This segment includes AMIC procedures that can be performed in an outpatient setting, reducing hospital stay and associated costs.
- Surgical Interventions:This category broadly covers all procedural methods where AMIC is implemented, encompassing both open and arthroscopic techniques.
Minimally invasive techniques are experiencing the steepest expansion trajectory. Invasive procedures remain foundational for complex cases.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand for specialized biomaterials in Autologous Matrix Induced Chondrogenesis technology anchors in regions with advanced orthopedic care. The United States and Germany represent significant hubs for clinical adoption and technological innovation. These markets benefit from established healthcare infrastructures and favorable reimbursement mechanisms.
United States
High participation in professional and amateur sports drives demand for AMIC procedures in the United States. The US FDA's regulatory pathways for Advanced Therapy Medicinal Products require extensive clinical data. Orthopedic clinics in Boston are early adopters of 3D bioprinting for patient-specific cartilage repair.
Germany
Germany exhibits strong demand for AMIC procedures, supported by its advanced orthopedic clinics and established reimbursement structures. The EMA's stringent ATMP regulations ensure high standards for manufacturing and clinical efficacy. Specialized hospitals in Munich actively participate in clinical trials for novel chondral constructs.
Japan
Advancing orthopedic care standards and a growing focus on regenerative medicine propel AMIC adoption in Japan. The PMDA requires comprehensive clinical data to ensure long-term safety and efficacy of new cell-based therapies. Research institutions in Tokyo are developing innovative biomaterials for enhanced tissue regeneration.
South Korea
South Korea demonstrates rapid technological adoption in healthcare, boosting interest in advanced cartilage repair techniques. The MFDS enforces rigorous clinical trial requirements for cell and gene therapy products. Biotech parks around Seoul invest in research for patient-specific scaffold designs and cell culturing methods.
Autologous Matrix Induced Chondrogenesis Market Key Industry Players
Global majors compete with regional champions across product development and market access in the Autologous Matrix Induced Chondrogenesis sector. The market exhibits a tiered structure, with large orthopedic device manufacturers alongside specialized biomaterial producers. Strategic archetypes include integrated solution providers, niche biomaterial innovators, and cell culture specialists. Companies are pursuing portfolio diversification and strategic partnerships to enhance their market presence.
On the integrated solutions vector, Zimmer Biomet Holdings exemplifies a provider offering a comprehensive portfolio of orthopedic implants and complementary surgical tools. Germany-based Geistlich Pharma AG represents a specialized biomaterial innovator, leveraging deep expertise in regenerative biomaterials for collagen-based scaffolds. Smith & Nephew plc occupies a position as a global medical technology company, focusing on minimally invasive surgical solutions and extensive distribution networks. These companies address distinct segments of the AMIC market through their varied product offerings and strategic focuses.
| Leading Market Players |
|---|
| Anika Therapeutics, Inc. |
| B. Braun Melsungen AG |
| Smith & Nephew plc |
| Zimmer Biomet Holdings |
| Geistlich Pharma AG |
| BioTissue AG |
| Arthro-Kinetics |
| JRI Orthopaedics Ltd. |
| Matricel GmbH |
| Others |
Cost & Logistics Intelligence
Family-owned mid-caps and specialized biomaterial producers influence the supply behavior, which in turn shapes the pricing discipline for advanced chondral constructs. High input costs for GMP-grade cell culturing and advanced biomaterials directly impact final procedural costs. Complex cold-chain logistics further elevate operational expenses, creating a direct link between supply chain efficiency and market pricing.
Pricing Analysis
Warranty and service bundling often differentiate offerings, with integrated solutions typically commanding a premium over unbundled components. Pricing model is predominantly per-unit transactional for scaffold systems and value-based for complex chondral constructs. Price differentiation stems from biomaterial innovation and regulatory certification levels like EMA ATMP approval. Pricing pressure stems from the high procedural costs, driving demand for cost-effective alternatives in some healthcare systems. Hospitals with budget constraints are more price-sensitive than specialized orthopedic clinics seeking advanced patient outcomes.
Supply Chain Analysis
Regional distribution centers and a hub-and-spoke pattern facilitate the movement of time-sensitive cell cultures and biomaterials. Geographic supply concentration for critical biomaterials primarily sits with Europe and the United States. Raw material dependencies include specialized collagen sources and synthetic polymer precursors. A structural risk involves complex cold-chain logistics for autologous chondrocytes, requiring specialized infrastructure. Distribution runs through a direct sales force to hospitals and specialized orthopedic clinics, often via single-supplier kits.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Autologous Matrix Induced Chondrogenesis market is in a technology-transition phase, with 3D bioprinting poised to replace traditional scaffold fabrication methods. This shift demands proactive strategies from all market participants to capitalize on emerging opportunities.
For Market Incumbents: Lock in long-term supply agreements for critical biomaterials like collagen and synthetic polymers to stabilize input costs. Companies should pursue vertical integration into cell culturing facilities to mitigate complex cold-chain logistics. This defends against margin pressure from rising input costs and emerging competition in personalized medicine. Investing in R&D for next-generation patient-specific scaffolds offers a key lever against commoditization.
For New Entrants and Emerging Players: The EMA's ATMP framework in Europe opens a window for specialized cell therapy providers focusing on novel chondral constructs. Target the osteoarthritis treatment segment in advanced orthopedic clinics, which represents a large, underserved patient population. Develop patient-specific 3D bioprinted scaffolds to differentiate from established biomaterial offerings. A go-to-market angle involves partnering with leading sports medicine centers for clinical validation and early adoption.
For Investors and Strategic Acquirers: Increased M&A activity among biomaterial specialists is the leading indicator that market consolidation is accelerating. The market demonstrates long-term viability over a 5-10 year window, driven by an aging population and sports injury rates. Acquisition targets include niche biomaterial innovators with proprietary scaffold technologies or specialized cell culture expertise. Watch for regulatory approvals of novel combination therapies as a key inflection signal.
| Strategic Initiative | Industry Significance |
|---|---|
| Clinical Trial Advancement | Securing robust long-term efficacy data for AMIC procedures strengthens market confidence and reimbursement. |
| Regulatory Approval Pathway | Navigating US FDA and EMA ATMP requirements ensures market access for new chondral constructs. |
| Manufacturing Scale-Up | Expanding GMP-compliant facilities in Europe reduces production costs for advanced biomaterials. |
| Strategic Partnership | Collaborating with orthopedic clinics accelerates adoption of 3D bioprinted patient-specific scaffolds. |
| Geographic Expansion | Penetrating Asian markets like Japan and South Korea taps into advancing orthopedic care standards. |
Research Approach
Independent corroboration across academic literature, clinical trial registries, and industry association reports underwrites the qualitative findings. This study combines primary interviews with secondary validation to construct a comprehensive market view. Stakeholders interviewed include orthopedic surgeons, biomaterial engineers, hospital procurement managers, and regulatory affairs specialists. Secondary data sources encompass FDA filings, EMA submissions, PMDA guidelines, and relevant medical journals. Bottom-up and top-down triangulation ensures data accuracy and consistency across all market segments.
Rate-of-change decomposition analyzes historical growth drivers to project future market expansion across the analysis window. The analytical framework models market segmentation by product type, application, end user, delivery mode, and biomaterial composition. Compound annual growth rates were derived by assessing individual segment trajectories and their interdependencies. Key forecast inputs include sports injury incidence rates and orthopedic procedure volumes in major economies.
The model assumes a particular technology adoption path; alternative pathways for 3D bioprinting would alter the outlook for patient-specific scaffolds. Forecasts reflect assumptions regarding regulatory changes and reimbursement policy evolution. Unforeseen advancements in regenerative medicine or shifts in healthcare spending represent specific risk factors. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Regenerative Medicine
Asia-Pacific Regenerative Medicine Market
Regenerative Medicine
Stromal Vascular Fraction Market
Regenerative Medicine
Global Breast Reconstruction Market
Regenerative Medicine
Degenerative Disc Disease Treatment Market
Regenerative Medicine
Cytokine Storm Therapy Market
Regenerative Medicine
North America Regenerative Medicines Market
Regenerative Medicine
China Longevity and Anti-Senescence Therapy Market
Regenerative Medicine
North America Scar Treatment Market
Regenerative Medicine
US Regenerative Medicine Market
Regenerative Medicine
Longevity and Anti-Senescence Therapy for Cancer Market
Regenerative Medicine
Bone Regeneration Market
Regenerative Medicine
Orthopedic Regenerative Medicine Market
Regenerative Medicine
Cartilage Degeneration Market
Regenerative Medicine
Epidermal Cell Sheets Market
Regenerative Medicine
Autologous Fat Grafting Market
Regenerative Medicine
Th17 Driven Disease Treatment Market