
 Tumour-Induced Osteomalacia Market | 2026-2036
Tumour-Induced Osteomalacia Market Size, Share, and Industry Trends Forecast 2026-2036
Tumour-Induced Osteomalacia Market Analytics
Diagnostic testing revenue is reconfiguring margin pools away from chronic phosphate replacement toward tumor localization and surgical intervention protocols. Ultragenyx Pharmaceutical specializes in rare disease therapeutics and occupies a distinctive position in metabolic bone disorder innovation. Takeda Pharmaceutical Company Limited leverages its global rare disease infrastructure to sustain leadership in orphan indication development. Kyowa Kirin Co., Ltd. competes through deep expertise in endocrinology and mineral metabolism research.
Tumour-Induced Osteomalacia is a paraneoplastic syndrome caused by fibroblast growth factor 23-secreting mesenchymal tumors, characterized by renal phosphate wasting, hypophosphatemia, and progressive bone demineralization; diagnosis requires measurement of serum FGF-23 levels alongside radiological tumor localization via functional imaging such as Gallium-68 DOTATATE PET-CT. The pharmaceuticals segment dominates current value generation through burosumab and other targeted therapies, while the diagnostics segment registers the fastest structural expansion driven by molecular imaging advances. Hospitals anchor end-user demand due to the multidisciplinary care requirements, though academic institutions are capturing growing research-related volume.
The FDA Orphan Drug program and EMA Committee for Orphan Medicinal Products jointly shape clinical trial incentives and extended market exclusivity frameworks for rare disease developers. HIPAA governs patient data flows in US referral networks, while ISO 15189 standards constrain laboratory accreditation for specialized biochemical assays. Stakeholders must monitor evolving payer policies for pre-authorization of functional imaging and balance R&D portfolios between surgical resection adjuncts and systemic phosphate-conserving therapies.
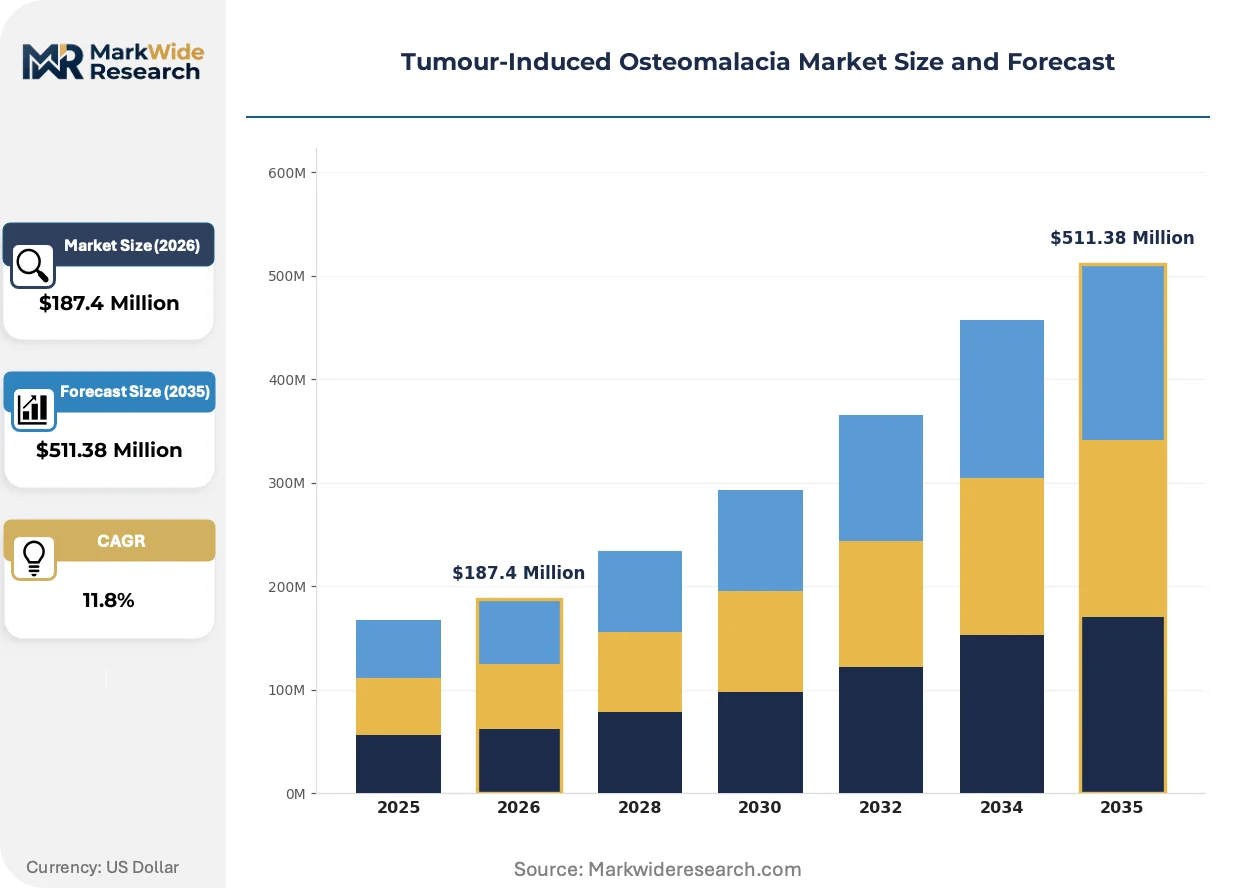
Market Dynamics
Functional imaging protocols are compressing diagnostic timelines and redistributing value capture from chronic phosphate management toward tumor localization and surgical intervention workflows.
Growth Catalysts
- Orphan Drug Incentives:The FDA's Orphan Drug Designation program and EMA's parallel framework extend market exclusivity and reduce clinical trial costs for developers targeting this phosphaturic syndrome.
- Gallium-68 DOTATATE PET-CT:This molecular imaging technology enables precise tumor localization in mesenchymal neoplasms, driving adoption across tertiary referral hospitals with established nuclear medicine departments.
- Academic Medical Center Expansion:Specialized endocrinology and oncology departments in the United States, Germany, and Japan are institutionalizing multidisciplinary care protocols for FGF-23-mediated bone disorders.
Market Restraints
- Radiotracer Supply Concentration:Gallium-68 generator production clusters among a limited set of radiopharmaceutical manufacturers, creating vulnerability in functional imaging availability.
- FGF-23 Assay Standardization Gaps:Variability in serum FGF-23 measurement methodologies across clinical laboratories limits diagnostic consistency and referral confidence.
- Surgical Resection Eligibility:Many phosphaturic mesenchymal tumors reside in anatomically challenging locations, restricting curative intervention to specialized surgical centers.
Strategic Opportunities
- Japan's Rare Disease Framework:PMDA's Sakigake designation pathway accelerates regulatory review for novel phosphate-conserving therapeutics in this high-prevalence aging population.
- Artificial Intelligence-Enhanced Imaging:Machine learning algorithms applied to DOTATATE PET-CT interpretation are hybridizing radiological workflows and reducing false-negative tumor localization rates.
- Direct-to-Specialist Diagnostic Channels:Telemedicine platforms connecting community endocrinologists with academic tumor boards are compressing referral timelines for suspected paraneoplastic osteomalacia cases.
Industry Challenges
- Nuclear Medicine Specialist Scarcity:Interpretation of functional imaging for rare neuroendocrine-appearing tumors requires radiologists with hybrid endocrine-oncology expertise that training programs underproduce.
- HIPAA-Compliant Data Integration:Multi-site referral networks for tumor localization require interoperable electronic health record systems that preserve patient privacy across institutional boundaries.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Tumour-Induced Osteomalacia Market |
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $511.38 Million |
| CAGR (2026 – 2036) | 11.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Pharmaceuticals, Supplements, Devices, Diagnostics Application: Treatment, Research, Prevention, Education End User: Hospitals, Clinics, Academic Institutions, Laboratories Distribution Channel: Pharmacies, Online Stores, Direct Sales, Wholesalers |
| Companies Covered | Takeda Pharmaceutical Company Limited, Pfizer Inc., Ultragenyx Pharmaceutical Inc., Eli Lilly and Company, Ipsen Pharma, Kyowa Kirin Co., Ltd., Novartis AG, Abbott, Amgen Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Tumour-Induced Osteomalacia Market Evolving Landscape
Diagnostic technology convergence and regulatory pathway refinement are compressing the interval between symptom onset and definitive tumor localization in this rare paraneoplastic syndrome.
Dual-tracer imaging protocols combining Gallium-68 DOTATATE with Fluorodeoxyglucose PET-CT are hybridizing functional and metabolic assessment capabilities. Tertiary referral centers in the United States and Germany are adopting these hybrid approaches to distinguish FGF-23-secreting mesenchymal tumors from mimicking lesions. This convergence is compressing the diagnostic odyssey and reducing unnecessary surgical exploration rates.
EMA's Committee for Orphan Medicinal Products has streamlined pediatric investigation plan requirements for phosphate-conserving therapies, reducing pre-approval regulatory burden. Manufacturers are responding by accelerating European trial enrollment alongside US FDA submissions. The pharmaceuticals segment captures disproportionate benefit from this harmonization, while diagnostic developers navigate divergent CE marking and 510(k) pathways.
Hospital procurement departments are unbundling after-sales service contracts from capital imaging equipment purchases, shifting toward performance-based maintenance agreements. Academic medical centers in Japan and Germany are leading this transition, pressuring original equipment manufacturers to transparently price replacement radiotracer delivery and software upgrades separately from hardware acquisition.
Tumour-Induced Osteomalacia Market Segmentation
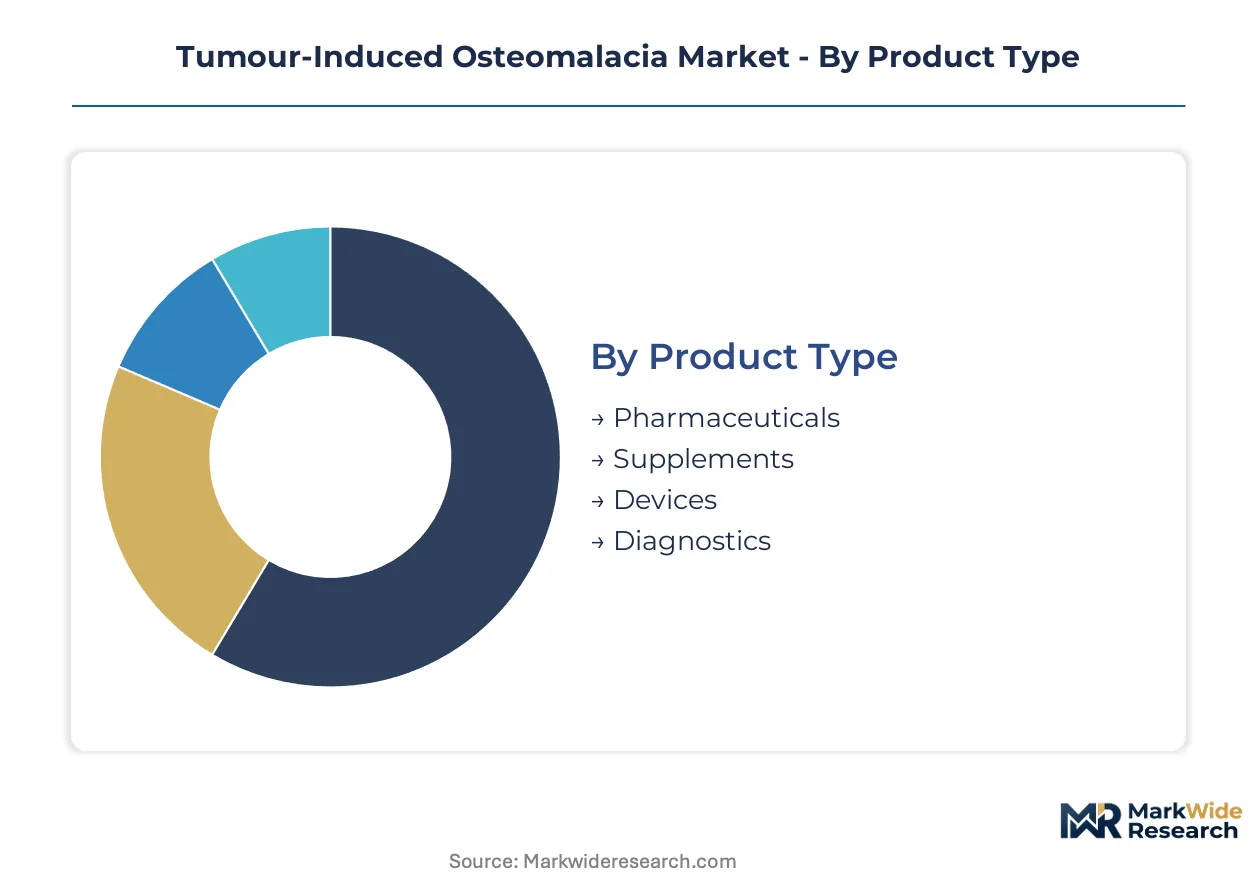
Segmentation in tumour-induced osteomalacia reflects the tension between chronic disease management and curative intervention pathways. Each dimension captures distinct value pools across the diagnostic-to-treatment continuum.
Product Type:
Product categories span the full clinical journey from biochemical confirmation through surgical cure.
- Pharmaceuticals:Targeted therapies including FGF-23-neutralizing antibodies and phosphate-conserving agents dominate revenue. Demand concentrates in tertiary hospitals with established metabolic bone disease units across the United States, Germany, and Japan, driven by orphan drug pricing frameworks and extended exclusivity periods.
- Diagnostics:Functional imaging modalities and specialized biochemical assays enable tumor localization. Academic medical centers in the United States and Germany are capturing volume fastest as Gallium-68 DOTATATE PET-CT protocols standardize.
- Supplements:Oral phosphate and active vitamin D preparations serve as bridging therapy. Community endocrinology practices in Japan maintain steady prescription volume.
- Devices:Surgical navigation and intraoperative monitoring equipment support tumor resection. Specialized oncology centers in Germany deploy these most intensively.
The dominant share belongs to Pharmaceuticals, while Diagnostics is closing the gap fastest.
Application:
Application patterns mirror the disease's paraneoplastic nature and diagnostic complexity.
- Treatment:Curative surgical resection and chronic phosphate management address distinct patient populations. Tertiary referral hospitals with multidisciplinary tumor boards in the United States handle the highest case complexity.
- Research:Academic institutions in Germany and Japan are expanding FGF-23 pathway investigation and novel tracer development.
- Prevention:Early biochemical screening in high-risk oncology populations remains limited to specialized centers.
- Education:Medical school curricula and continuing medical education programs address underdiagnosis.
Treatment commands the largest current allocation, though Research is expanding most quickly.
End User:
End-user configuration reflects the concentration of expertise required for this rare syndrome.
- Hospitals:Tertiary centers with integrated endocrinology, nuclear medicine, and surgical oncology departments anchor patient volume. The United States, Germany, and Japan host the highest concentration of qualified institutions.
- Academic Institutions:University hospitals drive protocol development and training. German academic medical centers are expanding fellowship programs fastest.
- Clinics:Community endocrinology practices manage chronic phosphate replacement. Referral networks in the United States connect these to academic centers.
- Laboratories:Specialized reference labs perform FGF-23 assays and radiotracer synthesis. ISO 15189-accredited facilities in Germany and Japan maintain quality standards.
Hospitals retain the dominant patient volume, while Academic Institutions are gaining share through research integration.
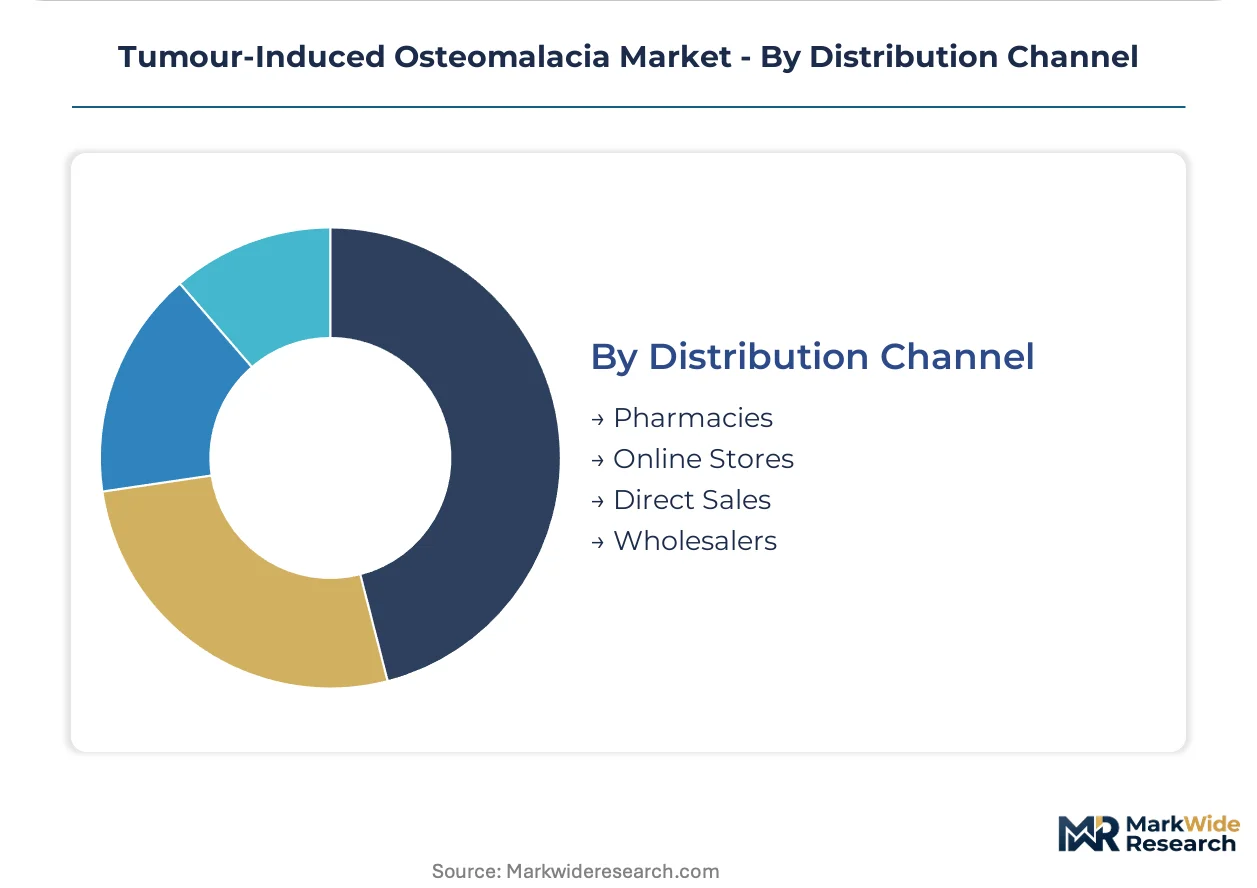
Distribution Channel:
Channel structure varies sharply by product category and regulatory classification.
- Direct Sales:Orphan drugs and capital imaging equipment move through manufacturer-specialist relationships. Takeda and Ultragenyx deploy dedicated rare disease sales forces in the United States and Japan.
- Pharmacies:Retail and hospital pharmacies dispense phosphate supplements and chronic therapies. Japan's pharmacy network maintains highest accessibility.
- Wholesalers:Specialized radiopharmaceutical distributors handle Gallium-68 generator logistics. Supply concentration in Germany creates delivery complexity.
- Online Stores:Limited to patient education materials and nutritional supplements. Regulatory constraints block pharmaceutical sales.
Direct Sales captures the highest value per transaction, while Wholesalers are expanding fastest to address radiotracer logistics.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price sensitivity in tumour-induced osteomalacia diagnostics diverges sharply by healthcare system structure. Germany and Japan demonstrate lowest elasticity due to comprehensive rare disease coverage, while out-of-pocket exposure in United States commercial plans creates higher sensitivity for functional imaging pre-authorization.
United States
Tertiary referral hospitals in Boston, Houston, and Rochester anchor the highest case volumes for FGF-23-mediated bone disorders. FDA Orphan Drug Designations for burosumab and related phosphate-conserving therapies reduce clinical trial costs and extend market exclusivity periods for developers. The Mayo Clinic in Rochester and MD Anderson Cancer Center in Houston operate the most established multidisciplinary tumor boards for phosphaturic mesenchymal neoplasms.
Germany
Academic medical centers in Munich, Heidelberg, and Berlin drive protocol standardization for Gallium-68 DOTATATE PET-CT tumor localization. EMA Committee for Orphan Medicinal Products streamlines pediatric investigation plans, accelerating European trial enrollment for novel therapeutics. The German Cancer Research Center in Heidelberg coordinates the continent's largest FGF-23 pathway research consortium.
Japan
PMDA's Sakigake designation pathway compresses regulatory review timelines for phosphate-conserving therapeutics in this aging population with elevated metabolic bone disease prevalence. University hospitals in Tokyo, Osaka, and Nagoya institutionalize endocrinology-nuclear medicine collaboration protocols. The National Center for Global Health and Medicine in Tokyo maintains the national reference laboratory for standardized FGF-23 assays.
United Kingdom
NHS England's Highly Specialised Services framework concentrates rare disease diagnostics in designated supraregional centers in London, Oxford, and Cambridge. MHRA parallel scientific advice with EMA reduces regulatory divergence for orphan drug developers seeking UK market access. The Royal National Orthopaedic Hospital in London operates the sole dedicated metabolic bone disease surgical unit nationally.
Switzerland
Swissmedic's expedited access pathway for rare disease therapies attracts European headquarters decisions from multinational developers. University hospitals in Zurich, Geneva, and Basel maintain integrated endocrinology-oncology-nuclear medicine departments for complex paraneoplastic syndrome management. The University Hospital of Zurich hosts the reference center for Gallium-68 radiotracer quality assurance across Alpine region networks.
Tumour-Induced Osteomalacia Market Competitive Landscape
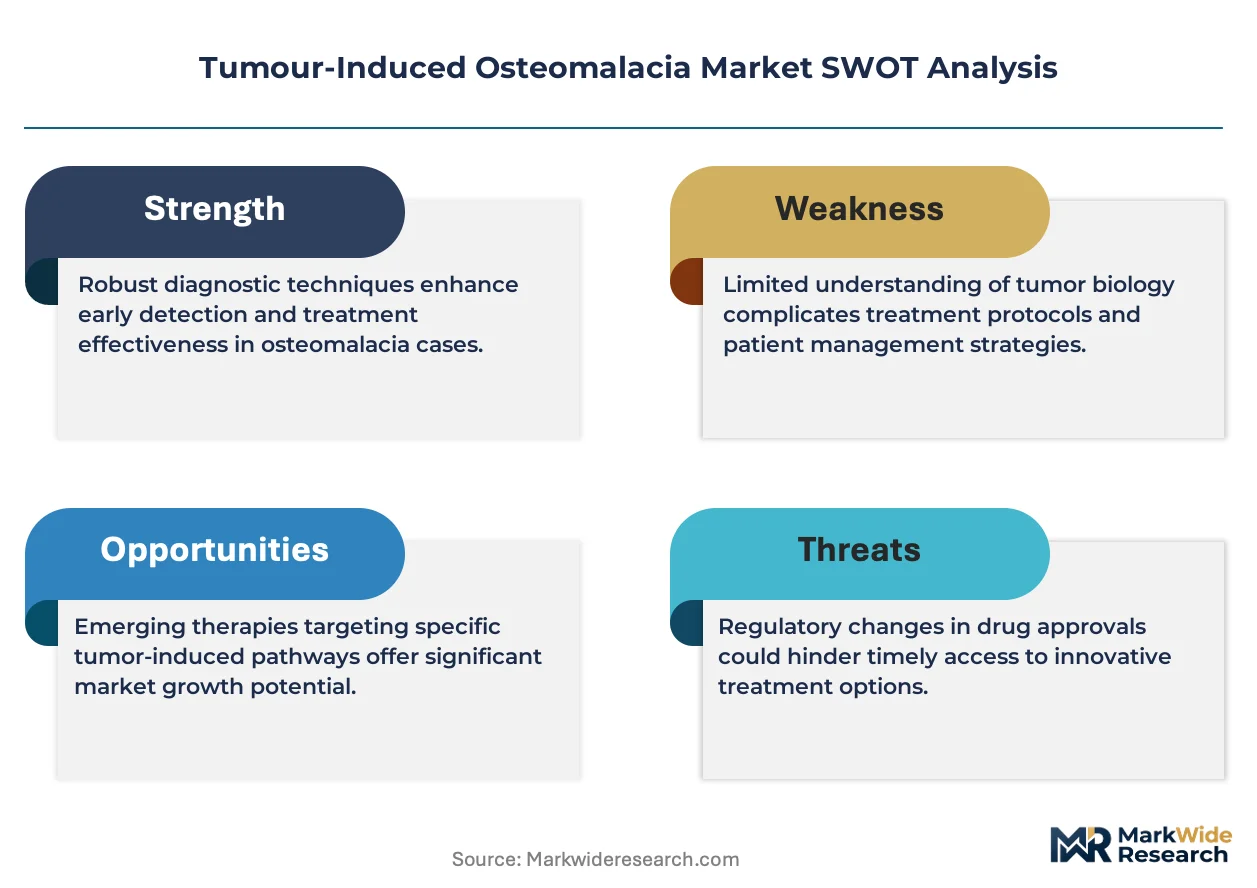
Capability concentration sits with specialized rare disease developers possessing deep FGF-23 biology expertise; scale advantage sits with diversified pharmaceutical conglomerates leveraging global commercial infrastructure. The market structures around three archetypes: orphan drug specialists with targeted metabolic bone disorder portfolios, broad-based rare disease platforms with endocrinology franchises, and diversified multinationals accessing the indication through acquisition or partnership. Dominant competitive moves include strategic licensing of Gallium-68 DOTATATE manufacturing capabilities and vertical integration into reference laboratory services for specialized biochemical assays.
Among rare disease specialists, Ultragenyx Pharmaceutical exemplifies the capability-concentrated archetype through its focused metabolic disorder innovation engine. Kyowa Kirin occupies a distinctive position rooted in Japanese endocrinology and mineral metabolism research heritage. Takeda Pharmaceutical represents the scale-advantaged multinational leveraging global orphan indication infrastructure across multiple therapeutic areas.
| Leading Market Players |
|---|
| Takeda Pharmaceutical Company Limited |
| Pfizer Inc. |
| Ultragenyx Pharmaceutical Inc. |
| Eli Lilly and Company |
| Ipsen Pharma |
| Kyowa Kirin Co., Ltd. |
| Novartis AG |
| Abbott |
| Amgen Inc. |
| Others |
Value Network & Pricing Analysis
Undercapacity in Gallium-68 generator production across Germany and the United States is tightening radiotracer availability and forcing tertiary hospitals into longer-term offtake commitments with premium pricing tiers for secured supply.
Pricing Analysis
Long-term offtake contracts dominate Gallium-68 DOTATATE procurement, with academic medical centers locking multi-year agreements to secure generator supply against spot-market volatility. Pricing stratifies across premium secured-delivery, standard scheduled-delivery, and economy shared-access tiers based on volume commitments and after-sales service bundling. Cost compression in the economy tier is intensifying because community hospitals lack negotiating leverage against concentrated radiopharmaceutical suppliers. Academic institutions with integrated nuclear medicine departments exhibit lowest price sensitivity due to bundled research funding, while standalone community clinics face highest sensitivity to functional imaging pre-authorization requirements.
Supply Chain Analysis
Tariff exposure between the United States and European Union radiopharmaceutical suppliers dominates supply chain risk planning for Gallium-68 generator logistics. Manufacturing concentrates in Germany, the United States, and Belgium, with cold-chain distribution drawing from specialized radiopharmaceutical depots in Frankfurt, Indianapolis, and Brussels. Single-source vulnerability in germanium-68 parent isotope production rests on limited nuclear reactor capacity in Russia and South Africa. Distribution runs through hospital-integrated nuclear medicine pharmacies and third-party radiopharmaceutical wholesalers with licensed handling capabilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market frames as a service-attach opportunity because performance-based maintenance agreements for PET-CT systems and reference laboratory FGF-23 assay services are expanding faster than capital hardware sales across academic medical centers.
For Market Incumbents: Harden Gallium-68 generator supply security through backward integration into parent isotope sourcing or captive production partnerships with European reactor operators. Incumbent diagnostic manufacturers face substitution threat from AI-enhanced tumor localization software that reduces scan interpretation dependency on scarce nuclear medicine specialists. Channel control through exclusive service contracts with tertiary hospital systems represents the critical defensive lever.
For New Entrants and Emerging Players: Mid-tier community hospitals in Japan and the United Kingdom with limited nuclear medicine infrastructure represent the most penetrable entry point for cloud-based DOTATATE PET-CT interpretation services. Telemedicine platforms connecting community endocrinologists with academic tumor boards offer a direct go-to-market angle that compresses diagnostic referral timelines without requiring capital-intensive imaging hardware deployment.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across AI-augmented diagnostic software sub-segments relative to traditional radiopharmaceutical manufacturing. Long-term viability over the next decade favors asset-light platform models with recurring SaaS revenue over hardware-dependent capital cycles. Acquisition target archetype: specialized reference laboratories with ISO 15189 accreditation and established FGF-23 assay protocols. The signal to watch is PMDA Sakigake designation awards accelerating Japanese regulatory timelines for phosphate-conserving therapeutics.
| Strategic Initiative | Industry Significance |
|---|---|
| Gallium-68 Generator Supply Security | Long-term offtake agreements with IRE and Eckert & Ziegler stabilize radiotracer availability for DOTATATE protocols. |
| AI-Enhanced Imaging Platform Development | Machine learning algorithms from Siemens Healthineers and GE Healthcare reduce false-negative tumor localization rates. |
| Reference Laboratory Accreditation Expansion | ISO 15189 certification enables standardized FGF-23 assays across multi-site academic referral networks. |
| Orphan Drug Exclusivity Extension | FDA and EMA market exclusivity periods protect burosumab revenue against phosphate-conserving biosimilar entry. |
| Telemedicine Diagnostic Channel Integration | Direct-to-specialist platforms connect Mayo Clinic tumor boards with community endocrinology practices nationwide. |
Research Methodology
The analysis maps pharmaceutical therapeutics, functional imaging modalities, specialized biochemical assays, and surgical intervention devices, each validated through drug development executives, nuclear medicine department heads, hospital procurement managers, and payer access specialists. Primary interviews with formulary directors at tertiary referral hospitals combined with secondary validation against FDA orphan drug filings, EMA Committee for Orphan Medicinal Products decisions, ClinicalTrials.gov enrollment data, and hospital procurement databases. Bottom-up patient volume modeling and top-down revenue triangulation cross-validated segment estimates.
Assumptions held fixed include current orphan drug incentive frameworks and Gallium-68 generator supply concentration, while variables tested included PMDA regulatory acceleration scenarios and AI imaging adoption curves. The forecast framework segments by product type, application, end user, and distribution channel, with regional regulatory clusters modeled separately. CAGRs derived from logistic diffusion curves for diagnostic technology adoption and epidemiological prevalence projections for FGF-23-mediated bone disorders. Key inputs included tertiary hospital nuclear medicine department expansion rates and radiotracer synthesis capacity utilization.
Practitioners should monitor radiopharmaceutical supply disruptions, FGF-23 assay standardization breakthroughs, and orphan drug pricing policy revisions for early signals requiring forecast adjustment. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Regenerative Medicine
Th17 Driven Disease Treatment Market
Regenerative Medicine
North America Longevity and Anti-Senescence Therapy Market
Regenerative Medicine
Hyper Personalized Medicine Market
Regenerative Medicine
Bioelectric Medicine Market
Regenerative Medicine
Global Cartilage Repair-Cartilage Regeneration Market
Regenerative Medicine
North America Scar Treatment Market
Regenerative Medicine
Europe Regenerative Medicines Market
Regenerative Medicine
North America Regenerative Medicines Market
Regenerative Medicine
Global Breast Reconstruction Market
Regenerative Medicine
Degenerative Disc Disease Treatment Market
Regenerative Medicine
Global Vaginal Rejuvenation Market
Regenerative Medicine
US Regenerative Medicine Market
Regenerative Medicine
Tenosynovial Giant Cell Tumor Treatment Market
Regenerative Medicine
Orthopedic Regenerative Medicine Market
Regenerative Medicine
Regenerative Artificial Skin Market
Regenerative Medicine
US Platelet Rich Plasma Market