
 Autologous Fat Grafting Market | 2026-2036
Autologous Fat Grafting Market Size, Share, and Industry Trends Forecast 2026-2036
Autologous Fat Grafting Market Analysis
Hospital procurement of autologous fat grafting systems is fragmenting as ambulatory surgical centers and independent cosmetic clinics build direct relationships with device manufacturers. Integra LifeSciences leverages its established wound-care distribution network to sustain shelf presence across integrated delivery networks. AbbVie Inc. competes through its Allergan Aesthetics channel, which anchors high-volume accounts in North American metropolitan markets. Genesis Biosystems, Inc. specializes in closed-system harvesting devices that differentiate on sterility assurance and operating-room workflow efficiency.
Autologous fat grafting involves the extraction, processing, and reinjection of a patient's own adipose tissue for soft-tissue volume restoration, with lipoaspirate typically harvested at sub-atmospheric pressures below 700 mmHg to preserve adipocyte viability. The procedure serves reconstructive goals such as post-mastectomy breast reconstruction and cosmetic objectives including facial volumetric enhancement. Harvesting devices lead product-type revenue due to recurring instrument replacement cycles, while tissue engineering applications within the technology dimension represent the fastest-growing segment as stromal vascular fraction isolation gains clinical traction. Plastic surgery clinics dominate the end-user landscape, though hospital-based reconstructive programs carry higher per-procedure reimbursement complexity.
The FDA regulates fat grafting systems as Class II medical devices under 21 CFR 878.3920, with additional scrutiny for adipose-derived cell therapies that trigger regenerative medicine advanced therapy designation. The EU Medical Device Regulation imposes strengthened clinical evidence requirements for long-term implantable materials, reshaping CE-marking pathways for European manufacturers. Plastic surgery clinics must navigate state-level scope-of-practice variations alongside facility accreditation standards. Stakeholders should monitor how FDA guidance on minimal manipulation criteria reshapes the boundary between standard fat grafting and regulated cell therapy products.
Market Dynamics
The FDA's regenerative medicine advanced therapy framework is compressing the pathway from bench to bedside, forcing device manufacturers to restructure clinical evidence packages while accelerating stromal vascular fraction commercialization timelines.
Growth Catalysts
- Regulatory Acceleration:The FDA's evolving guidance on minimal manipulation criteria is clarifying the boundary between standard fat grafting and regulated cell therapy, reducing submission uncertainty for adipose-derived product developers.
- Urban Clinic Density:São Paulo's private aesthetic surgery corridors are concentrating demand for closed-system harvesting devices, creating localized economies of scale in Brazil's highest-volume metropolitan markets.
- Stromal Vascular Fraction Isolation:Tissue engineering applications are gaining clinical traction as enzymatic processing protocols standardize, expanding the addressable patient population beyond traditional cosmetic indications.
Market Restraints
- Input Cost Volatility:Single-use harvesting cannulas and sterile processing kits face polyethylene and medical-grade polymer price fluctuations, compressing margins for high-volume disposable suppliers.
- Supply Concentration Risk:European manufacturers confront extended CE-marking timelines under the EU Medical Device Regulation's strengthened clinical evidence requirements for long-term implantable materials.
- Technical Limitation:Variable adipocyte viability rates across manual processing techniques create inconsistent graft retention outcomes, limiting standardized reimbursement codes.
Strategic Opportunities
- Underpenetrated Geography:India's aesthetic surgery infrastructure remains concentrated in Mumbai and Delhi, with tier-two cities presenting whitespace for ambulatory surgical center expansion.
- Technology Convergence:Integration of closed-system harvesting devices with point-of-care adipose-derived stem cell isolation is enabling same-procedure regenerative applications.
- Distribution Innovation:Direct manufacturer relationships with independent cosmetic clinics are bypassing traditional hospital procurement hierarchies, capturing margin previously allocated to integrated delivery network markups.
Industry Challenges
- Skill Standardization Gap:Lipoaspirate harvesting technique varies significantly across plastic surgery training programs, creating inconsistent adipocyte preservation outcomes that complicate device validation studies.
- Compliance Timeline Compression:State-level scope-of-practice variations for nurse practitioners performing fat grafting procedures generate facility accreditation complexity across multi-site clinic operators.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Autologous Fat Grafting Market |
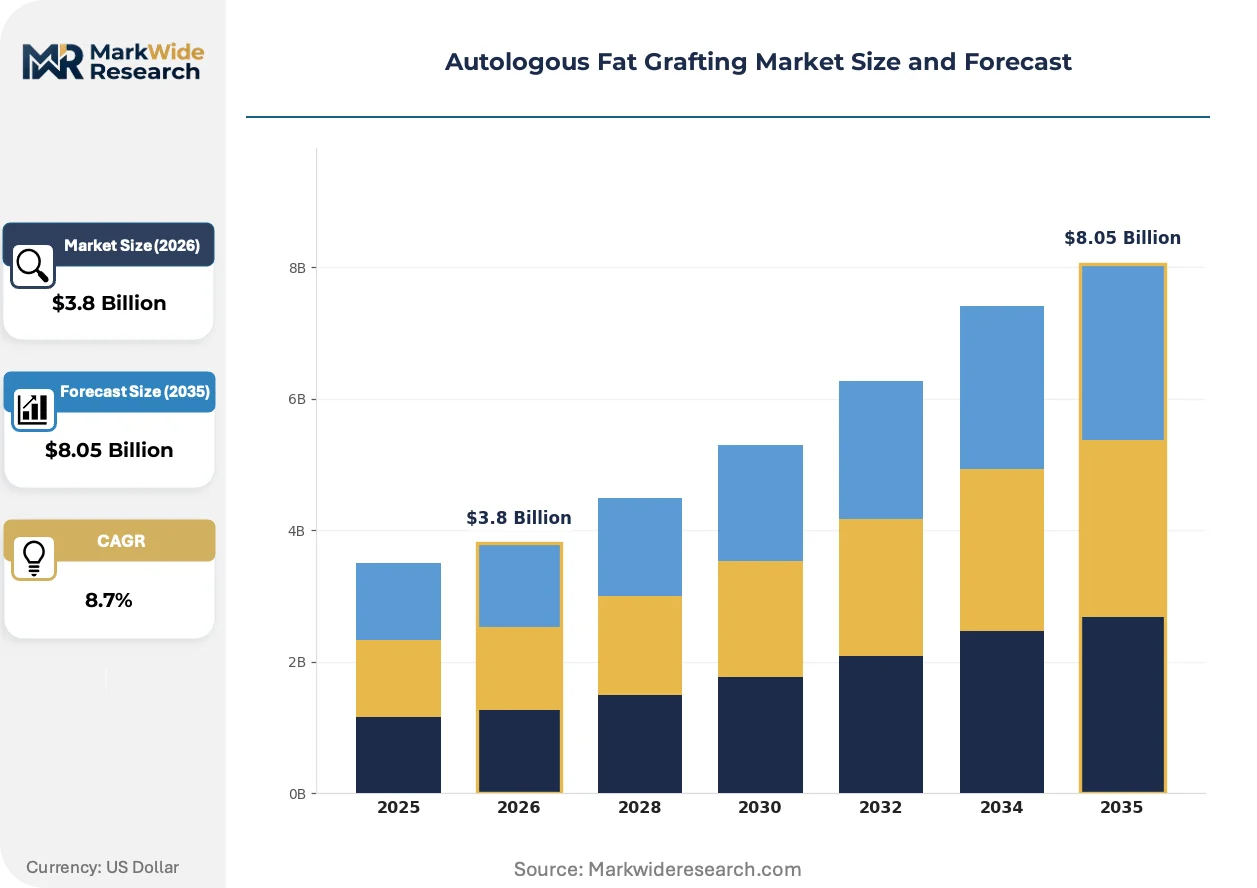
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.05 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Injectable Fillers, Surgical Instruments, Harvesting Devices, Cell Isolation Systems Application: Breast Reconstruction, Facial Augmentation, Body Contouring, Burn Treatment End User: Plastic Surgery Clinics, Hospitals, Dermatology Centers, Research Laboratories Technology: Mechanical Processing, Liposuction, Tissue Engineering, Ultrasonic Techniques |
| Companies Covered | AbbVie Inc., Integra LifeSciences, Sisram Medical Ltd, Lipogems International S.p.A., Human Med AG, Genesis Biosystems, Inc., Black Tie Medical Inc., MicroAire Surgical Instruments, Ranfac Corp., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Autologous Fat Grafting Market Emerging Trajectories
Workflow automation is penetrating adipose tissue processing, with digitized cell counting and viability assessment tools compressing operating room turnaround times while standardizing graft quality metrics.
Closed-system harvesting platforms are digitizing the lipoaspirate processing pipeline, replacing manual centrifugation and decantation steps with automated washing and concentration protocols. Ambulatory surgical centers in North American metropolitan markets are adopting these systems at accelerated replacement cycles compared to hospital-based programs. The technology is digitizing quality assurance documentation, enabling real-time graft characterization that supports outcome-based reimbursement negotiations.
The EU Medical Device Regulation's post-market surveillance requirements are mandating extended follow-up data collection for implantable adipose grafts, increasing clinical study burden for European manufacturers. Device sponsors must now demonstrate long-term biocompatibility evidence that exceeds predecessor directive standards. Plastic surgery clinics operating across Germany, France, and Italy are prioritizing suppliers with established MDR technical documentation to minimize supply disruption risk.
Service unbundling is separating device procurement from processing consumable supply agreements, allowing independent clinics to negotiate direct relationships with harvesting instrument manufacturers. Hospital-based reconstructive programs, traditionally captive to group purchasing organization contracts, are losing volume share to freestanding aesthetic centers. This pattern concentrates in Brazil's São Paulo corridor and comparable urban clusters where physician-owners control capital allocation decisions.
Autologous Fat Grafting Market Segmentation
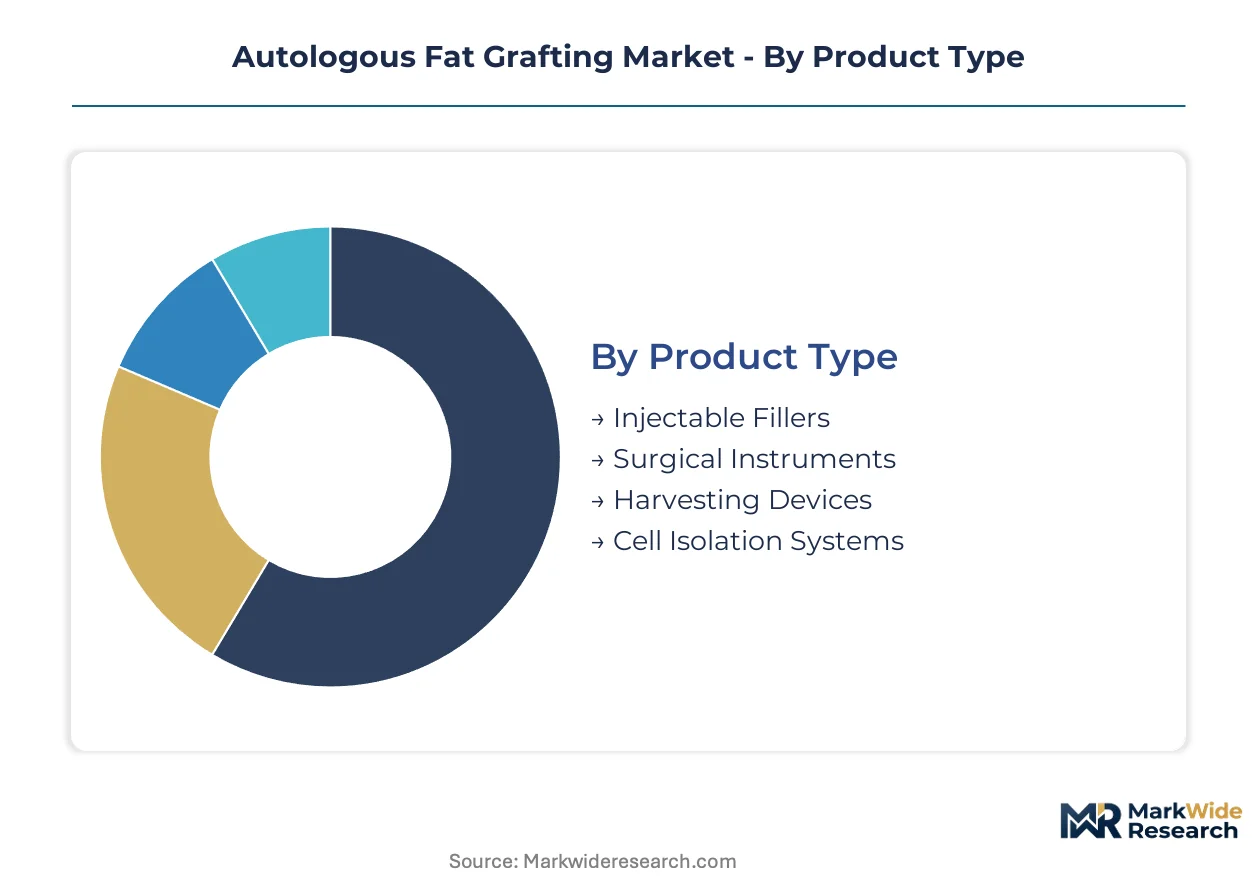
Device replacement cycles and consumable attachment rates vary sharply across product configurations, creating distinct service revenue profiles that reshape manufacturer go-to-market economics. Procurement patterns diverge between high-volume aesthetic chains and hospital-based reconstructive programs, demanding segmentation-aligned pricing architectures.
Product Type:
After-sales service intensity peaks with harvesting devices, where sterile consumable replenishment and preventive maintenance contracts generate recurring revenue streams exceeding initial hardware margins.
- Harvesting Devices:Closed-system platforms automate lipoaspirate collection at sub-atmospheric pressures below 700 mmHg, preserving adipocyte viability critical to graft retention. São Paulo's private clinic corridors concentrate demand for sterile, workflow-integrated systems that compress operating room turnaround times. Single-use cannula replacement cycles and scheduled calibration services anchor manufacturer service agreements.
- Cell Isolation Systems:Enzymatic processing equipment isolates stromal vascular fraction for regenerative applications, commanding premium positioning through point-of-care stem cell concentration capabilities. North American metropolitan ambulatory surgical centers are accelerating adoption as FDA guidance on minimal manipulation criteria clarifies regulatory boundaries for adipose-derived therapies.
- Surgical Instruments:Manual cannula sets and infiltration tumescence tools serve cost-sensitive clinic segments with lower service attachment rates.
- Injectable Fillers:Pre-processed adipose tissue formulations occupy niche positioning for revision procedures requiring standardized volume predictability.
Harvesting devices hold the largest share; momentum sits with cell isolation systems.
Application:
Reimbursement complexity stratifies applications, with reconstructive indications navigating insurance pre-authorization workflows distinct from cosmetic self-pay economics.
- Breast Reconstruction:Post-mastectomy volume restoration commands institutional procurement attention through hospital-based reconstructive programs, where bundled payment models and insurance reimbursement codes require comprehensive outcome documentation. Brazil's concentrated aesthetic surgery infrastructure processes high volumes through physician-owned facilities.
- Facial Augmentation:Periorbital and midface volumetric enhancement drives plastic surgery clinic demand for precision harvesting techniques that minimize donor-site morbidity. Urban corridor density in São Paulo and comparable metropolitan clusters supports specialized service line development.
- Body Contouring:Gluteal and extremity soft-tissue augmentation serves elective cosmetic segments with pronounced price elasticity.
- Burn Treatment:Scar contracture release and contour deformity correction occupies reconstructive niches with extended treatment timelines.
Breast reconstruction commands institutional procurement volume; facial augmentation is expanding most quickly.
End User:
Capital allocation authority and procurement sophistication diverge between physician-owned enterprises and integrated delivery network hierarchies.
- Plastic Surgery Clinics:Physician-owner control enables rapid technology adoption and direct manufacturer negotiation, bypassing group purchasing organization markups. Brazil's São Paulo corridor exemplifies concentrated demand for closed-system platforms with minimal facility infrastructure requirements.
- Hospitals:Reconstructive programs carry higher per-procedure reimbursement complexity but face procurement bureaucracy that slows replacement cycles.
- Dermatology Centers:Non-invasive facial rejuvenation focus limits penetration to superficial injection applications.
- Research Laboratories:Stromal vascular fraction isolation protocols and adipose-derived stem cell characterization drive specialized equipment demand with irregular purchase patterns.
Plastic surgery clinics dominate volume; research laboratories show the steepest expansion trajectory.
Technology:
Processing methodology determines graft viability consistency, with automation displacing manual techniques across premium market tiers.
- Tissue Engineering:Stromal vascular fraction isolation and adipose-derived stem cell concentration represent the technology frontier, with enzymatic processing protocols standardizing under FDA regenerative medicine advanced therapy frameworks. Clinical traction is accelerating as same-procedure regenerative applications demonstrate efficacy signals.
- Mechanical Processing:Centrifugation and washing protocols dominate current practice, with automated closed-system platforms displacing manual decantation in high-volume settings.
- Liposuction:Traditional suction-assisted lipectomy remains foundational to tissue harvest but faces displacement by pressure-controlled viability-preserving alternatives.
- Ultrasonic Techniques:Energy-assisted liquefaction occupies limited niches where fibrous donor sites complicate manual extraction.
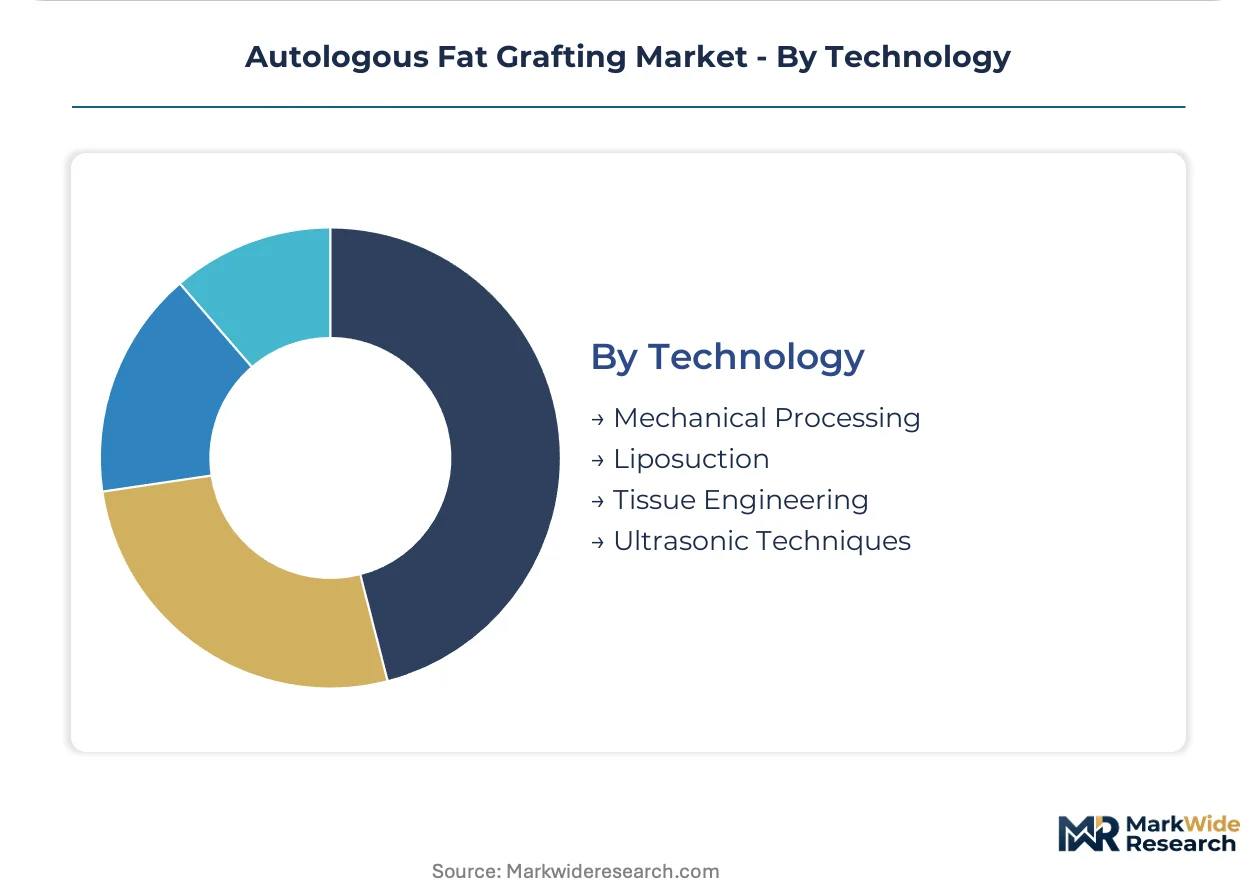
Mechanical processing anchors current practice; tissue engineering gains share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Brazilian aesthetic surgery corridors command premium pricing power against German hospital procurement, where MDR compliance costs compress device margins and elongate replacement cycles.
United States
FDA's regenerative medicine advanced therapy framework accelerates stromal vascular fraction commercialization timelines while clarifying minimal manipulation boundaries. Ambulatory surgical centers in North American metropolitan markets bypass traditional hospital procurement hierarchies through direct manufacturer relationships. Miami and Los Angeles concentrate demand for closed-system harvesting platforms with digitized quality assurance documentation.
Brazil
São Paulo's private clinic clusters generate localized economies of scale for sterile, workflow-integrated harvesting systems. ANVISA's evolving oversight of adipose-derived cell therapies shapes submission pathways for enzymatic processing equipment. Physician-owned facilities in Brazil's highest-volume aesthetic corridors control capital allocation decisions independent of group purchasing organization constraints.
Germany
EU Medical Device Regulation mandates extended follow-up data collection for implantable adipose grafts, increasing clinical study burden for domestic manufacturers. Post-market surveillance requirements exceed predecessor directive standards for long-term biocompatibility evidence. Bavarian and North Rhine-Westphalian plastic surgery clinics prioritize suppliers with established MDR technical documentation to minimize supply disruption risk.
India
Mumbai and Delhi concentrate aesthetic surgery infrastructure while tier-two cities present whitespace for ambulatory surgical center expansion. CDSCO's framework for medical device registration shapes import pathways for closed-system harvesting platforms. Hyderabad and Bangalore emerge as research laboratory hubs driving specialized equipment demand for adipose-derived stem cell characterization protocols.
Japan
PMDA's oversight of cell processing equipment influences commercialization timelines for point-of-care isolation systems. Tokyo and Osaka metropolitan areas anchor demand for automated processing platforms that compress operating room turnaround times. Kansai region reconstructive programs navigate reimbursement complexity distinct from cosmetic self-pay economics dominating private clinic volumes.
Autologous Fat Grafting Market Vendor Landscape
Platform integrators command the system tier; component specialists sit upstream with narrower attachable revenue streams. The vendor base organizes around three archetypes: multinational medical device conglomerates with established aesthetic channels, mid-cap closed-system specialists, and regional harvesting instrument fabricators. Consolidation pressure concentrates among disposable suppliers facing polyethylene price volatility, while technology licensing agreements accelerate enzymatic processing protocol standardization.
Within the multinational tier, AbbVie Inc. and Integra LifeSciences occupy positions anchored by established distribution infrastructure. Genesis Biosystems, Inc. exemplifies the closed-system specialist archetype, sitting within a segment differentiated on sterility assurance and operating-room workflow efficiency. These three entities represent distinct competitive positioning vectors: channel dominance, wound-care network leverage, and harvesting automation specialization respectively.
| Leading Market Players |
|---|
| AbbVie Inc. |
| Integra LifeSciences |
| Sisram Medical Ltd |
| Lipogems International S.p.A. |
| Human Med AG |
| Genesis Biosystems, Inc. |
| Black Tie Medical Inc. |
| MicroAire Surgical Instruments |
| Ranfac Corp. |
| Others |
Supply Flow & Price Mechanics
German and Swiss precision instrument manufacturers anchor the upstream harvesting device tier, concentrating margin capture in sterilization-grade polymer processing and automated control module fabrication. This supply concentration positions device integrators downstream to extract premium pricing through closed-system bundling, while disposable cannula suppliers face polyethylene cost volatility that compresses standard-tier margins.
Pricing Analysis
The customization-premium spread separates configured-to-order closed-system platforms from standard manual instrument sets. Three-tier pricing structure across premium, standard, and economy levels reflects FDA 510(k) clearance tier, ISO 13485 certification status, and after-sales service bundling intensity. Cost compression in single-use consumables is intensifying because medical-grade polymer feedstock prices fluctuate with petrochemical indices. Ambulatory surgical centers exhibit highest price sensitivity due to capital constraint, while hospital-based reconstructive programs absorb premium positioning through bundled reimbursement workflows.
Supply Chain Analysis
Extended payment terms from supply-chain finance facilities enable mid-cap device assemblers to manage working capital through 90-120 day procurement cycles. Manufacturing concentrates in Germany, Switzerland, and the United States for precision harvesting components, with sterile consumable fabrication distributed across Mexico and Costa Rica. Raw material dependencies include medical-grade polyethylene, stainless steel 316L cannula stock, and silicone membrane filtration media. Single-source vulnerability in enzymatic reagent supply for stromal vascular fraction isolation creates disruption risk. Distribution runs through direct manufacturer relationships with physician-owned clinic chains, bypassing traditional hospital procurement hierarchies.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The autologous fat grafting market sits in early-cycle expansion as FDA regenerative medicine advanced therapy designations accelerate stromal vascular fraction commercialization beyond traditional cosmetic indications.
For Market Incumbents: Harden regulatory submission capabilities to defend against emerging enzymatic processing specialists capturing regenerative therapy share. Deepen backward integration into sterile consumable manufacturing to offset polyethylene price volatility eroding disposable margins. Prioritize CE marking technical documentation investment to preempt EU Medical Device Regulation supply disruption risk in German and French procurement channels. For New Entrants and Emerging Players: Build out tier-two Indian city ambulatory surgical center networks where aesthetic infrastructure penetration lags Mumbai and Delhi density. Target direct-to-clinic distribution partnerships bypassing group purchasing organization markups that hospital-based programs cannot escape. Position on digitized quality assurance documentation as outcome-based reimbursement negotiations gain traction in North American metropolitan markets. For Investors and Strategic Acquirers: Capital is best deployed toward closed-system harvesting specialists with established FDA 510(k) clearances and scalable sterile consumable production. The 5-10 year viability window favors platform integrators over component suppliers as workflow automation compresses operating room turnaround times. Monitor FDA guidance publication on minimal manipulation criteria as the inflection signal separating regulated cell therapy from standard fat grafting, which would reshape addressable market boundaries.| Strategic Initiative | Industry Significance |
|---|---|
| FDA Regenerative Medicine Advanced Therapy Submission | Accelerates stromal vascular fraction commercialization timelines under clarified regulatory boundaries. |
| CE Marking Pathway Under EU MDR | Ensures continued German and French market access through strengthened clinical evidence packages. |
| Hospital System Partnership | Captures bundled reimbursement volume in post-mastectomy breast reconstruction programs. |
| Software Companion Development | Enables digitized graft characterization supporting outcome-based reimbursement negotiations. |
| Reimbursement Strategy | Secures standardized CPT codes for tissue engineering applications beyond cosmetic self-pay economics. |
Methodological Framework
A spread of perspectives from plastic surgeons, ambulatory surgical center administrators, biomedical engineers, and GPO contracts managers converged on the working assumptions underpinning this analysis. Primary interview intelligence combined with secondary validation against FDA 510(k) filings, ANVISA submission databases, EU MDR technical documentation, and hospital procurement contract records. Bottom-up device shipment modeling and top-down procedure volume estimates were triangulated to constrain forecast variance.
Demand-supply-balance framing anchored the analytical framework across the projection horizon, with segmentation dimensions spanning product type, application, end user, and technology methodology. CAGRs were derived from procedure volume elasticity modeling and hardware replacement cycle analysis. Industry-specific forecast inputs included adipocyte viability preservation rates across processing techniques and state-level scope-of-practice variation for nurse practitioner-performed procedures.
Practitioners should monitor FDA guidance publication timing, EU MDR post-market surveillance enforcement intensity, and polyethylene feedstock price indices for early signals of forecast revision necessity. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Regenerative Medicine
Global Cartilage Repair-Cartilage Regeneration Market
Regenerative Medicine
Degenerative Disc Disease Treatment Market
Regenerative Medicine
North America Scar Treatment Market
Regenerative Medicine
China Longevity and Anti-Senescence Therapy Market
Regenerative Medicine
Personalized Immunotherapy Market
Regenerative Medicine
Regenerative Artificial Skin Market
Regenerative Medicine
Global Breast Reconstruction Market
Regenerative Medicine
Asia-Pacific Regenerative Medicine Market
Regenerative Medicine
Bone Regeneration Market
Regenerative Medicine
Tumour-Induced Osteomalacia Market
Regenerative Medicine
Orthopedic Regenerative Medicine Market
Regenerative Medicine
Mesotherapy Guns Market
Regenerative Medicine
Hyper Personalized Medicine Market
Regenerative Medicine
Dural Graft Market
Regenerative Medicine
Global Orthopedic Regenerative Surgical Products Market
Regenerative Medicine
Epidermal Cell Sheets Market