
 US Scar Treatment Market | 2026-2036
US Scar Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
US Scar Treatment Market Insights
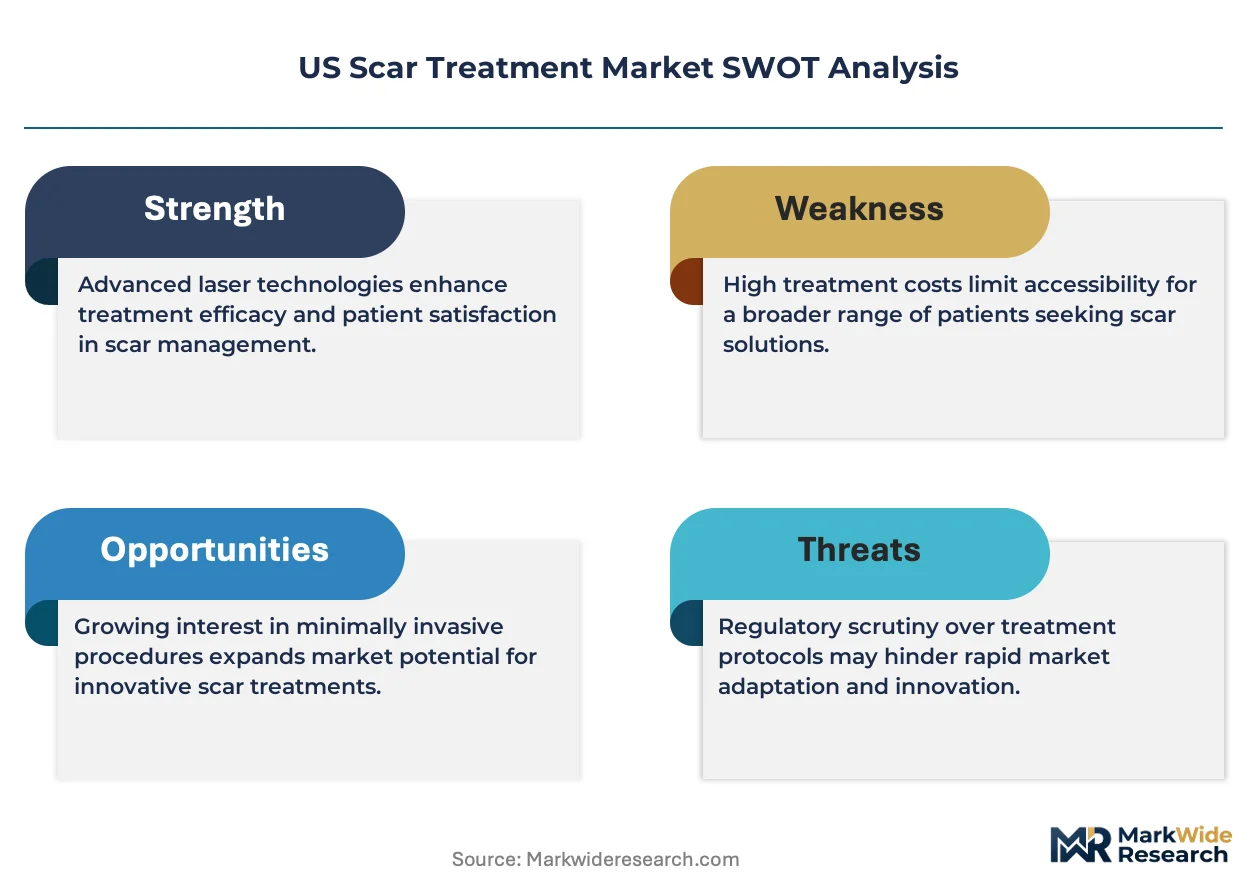
Board-certified dermatologist availability is collapsing in rural counties across the Midwest and Mountain West, forcing patients toward tele-dermatology platforms and concentrated urban clinic networks. Cynosure leverages its installed base of fractional laser systems to sustain recurring consumable revenue in metropolitan surgical centers. Merz Pharmaceuticals, LLC anchors the injectable segment with hyaluronic acid-based fillers positioned for atrophic scar revision. Sonoma Pharmaceuticals, Inc. differentiates through hypochlorous acid formulations targeting post-procedural wound care in ambulatory settings.
Scar treatment encompasses medical and aesthetic interventions designed to improve the appearance, texture, and functional mobility of fibrous tissue formed during wound healing, with laser systems typically operating at wavelengths between 585 nm and 10,600 nm depending on scar type and depth. These interventions serve both reconstructive purposes following trauma or surgery and cosmetic objectives for patients seeking texture normalization. Topical treatments occupy the largest revenue pool due to low barrier to entry and broad accessibility through retail channels. Laser therapy represents the fastest-expanding segment as fractional and picosecond platforms displace older ablative technologies in dermatology clinics. Surgical procedures retain premium pricing but face volume pressure from less invasive alternatives.
FDA 510(k) clearance requirements govern laser and energy-based devices, while the EPA regulates antimicrobial claims in topical scar formulations, creating dual compliance burdens for multi-modal product portfolios. State-level scope-of-practice laws vary significantly, with Texas and Florida permitting expanded laser use by non-physician operators under supervision, broadening addressable clinic capacity. Stakeholders must monitor reimbursement code consolidation for laser procedures and evolving FDA guidance on combination drug-device products.
Market Dynamics
Fractional and picosecond laser platforms are decomposing the historical dominance of ablative CO2 systems in US dermatology clinics, compressing capital replacement cycles and reshaping service line economics across metropolitan surgical centers.
Growth Catalysts
- State scope-of-practice expansion:Texas and Florida permit supervised non-physician laser operation, broadening clinic capacity and patient throughput in high-demand markets.
- FDA 510(k) pathway streamlining:Accelerated clearance timelines for energy-based devices reduce time-to-market for fractional platform manufacturers targeting ambulatory settings.
- Hyaluronic acid filler protocols:Injectable atrophic scar revision techniques expand addressable cases beyond surgical candidates into outpatient dermatology channels.
Market Restraints
- Capital equipment intensity:Picosecond laser systems require $150,000-$400,000 upfront investment, constraining rural and independent clinic participation.
- Physician concentration:Board-certified dermatologist availability collapses in Midwest and Mountain West rural counties, forcing patient migration to urban networks.
- Reimbursement code consolidation:CMS bundling of laser procedure codes compresses per-treatment revenue for Medicare-eligible scar revisions.
Strategic Opportunities
- Tele-dermatology integration:Remote consultation platforms enable pre-screening and post-procedural monitoring, extending specialist reach into underserved Mountain West counties.
- Hypochlorous acid expansion:Post-procedural wound care formulations target ambulatory surgical centers seeking antimicrobial alternatives to traditional antiseptics.
- Combination drug-device products:Evolving FDA guidance on integrated topical-laser protocols creates regulatory white space for synchronized treatment modalities.
Industry Challenges
- Laser technician certification gaps:State-level training hour requirements vary by 300%, creating compliance complexity for multi-state clinic operators.
- Dual EPA-FDA compliance burden:Antimicrobial topical claims trigger overlapping federal oversight, extending product development timelines for multi-modal portfolios.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US Scar Treatment Market |
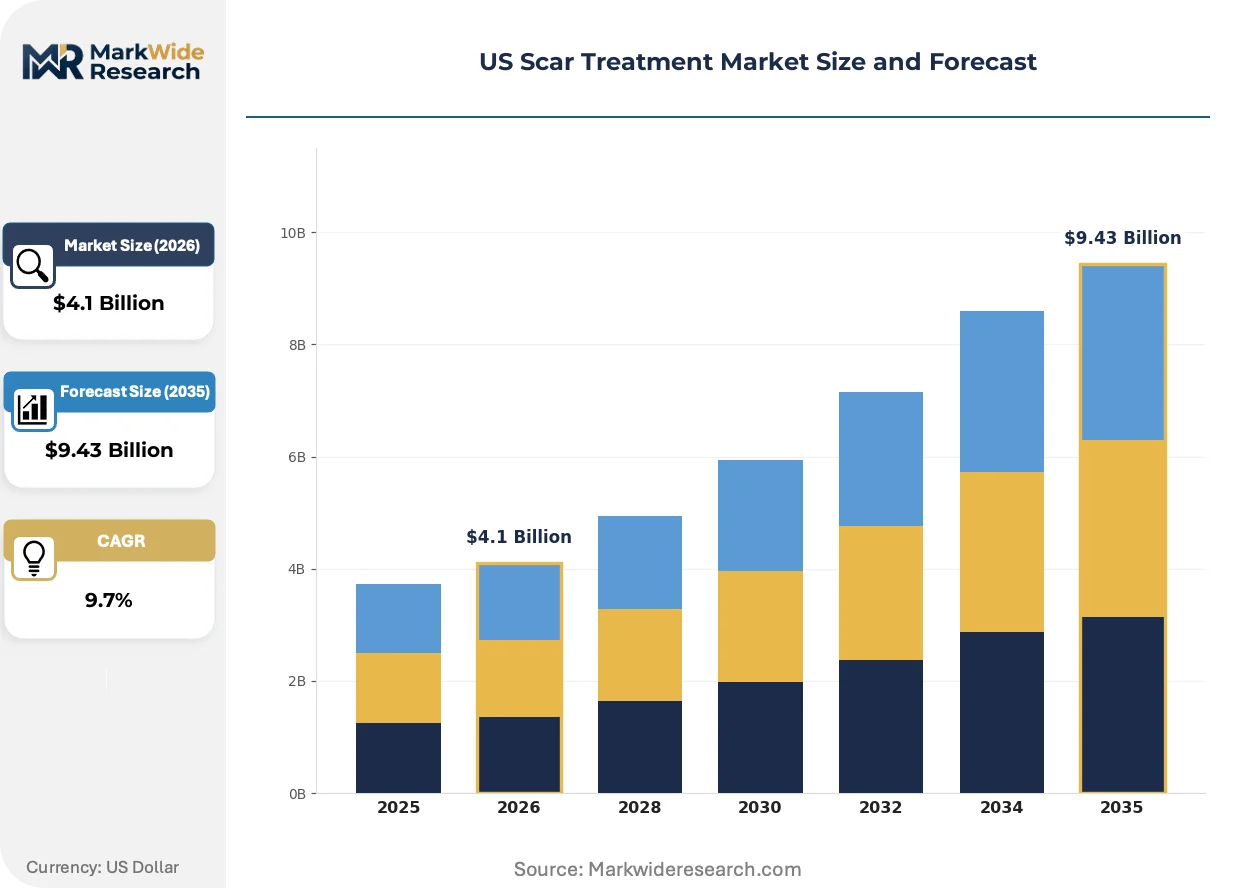
| Market Size in 2026 | $4.1 Billion |
| Market Size in 2035 | $9.43 Billion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Topical Treatments, Laser Therapy, Surgical Procedures, Injectable Fillers Application: Acne Scars, Surgical Scars, Burn Scars, Keloid Scars End User: Hospitals, Dermatology Clinics, Homecare Settings, Cosmetic Surgery Centers Distribution Channel: Online Pharmacies, Retail Pharmacies, Hospital Pharmacies, Direct Sales |
| Companies Covered | Smith & Nephew PLC, Merz Pharmaceuticals, LLC, Lumenis Be Ltd., Sonoma Pharmaceuticals, Inc., Cynosure, CCA Industries, Inc., Mölnlycke Health Care AB, Suneva Medical, Scar Heal Inc., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US Scar Treatment Market Trends and Innovations
Technology convergence and regulatory recalibration are redrawing competitive boundaries between device manufacturers, pharmaceutical formulators, and service delivery platforms across the US scar treatment landscape.
Picosecond laser systems operating at 755 nm and 1064 nm wavelengths are decomposing the market position of traditional nanosecond Q-switched platforms by enabling faster clearance of pigmented scars with reduced thermal injury. Dermatology groups in California and Florida are adopting these systems at replacement rates of 18-24 months versus 5-7 year cycles for older ablative units. The compressed capital refresh dynamic is squeezing independent clinics unable to match equipment upgrade pacing of consolidated metropolitan networks.
EPA antimicrobial claim regulations for topical scar formulations are tightening evidentiary standards for hypochlorous acid and silver-based products, forcing reformulation investments from manufacturers with legacy 510(k) clearances. The industrial consequence is a bifurcation between hospital-grade and retail-channel product lines with divergent testing requirements. Ambulatory surgical centers in Texas are responding by consolidating procurement around EPA-registered formulations with explicit post-procedural indications.
Direct-to-consumer topical kits are capturing patient segments previously routed through prescription channels, with retail pharmacy and e-commerce platforms disintermediating traditional dermatology dispensing relationships. Subscription replenishment models for silicone sheeting and pressure garment products are replacing one-time surgical center purchases. This channel shift is most pronounced in California and Florida markets where cosmetic procedure marketing density normalizes self-directed treatment initiation.
US Scar Treatment Market Segmentation
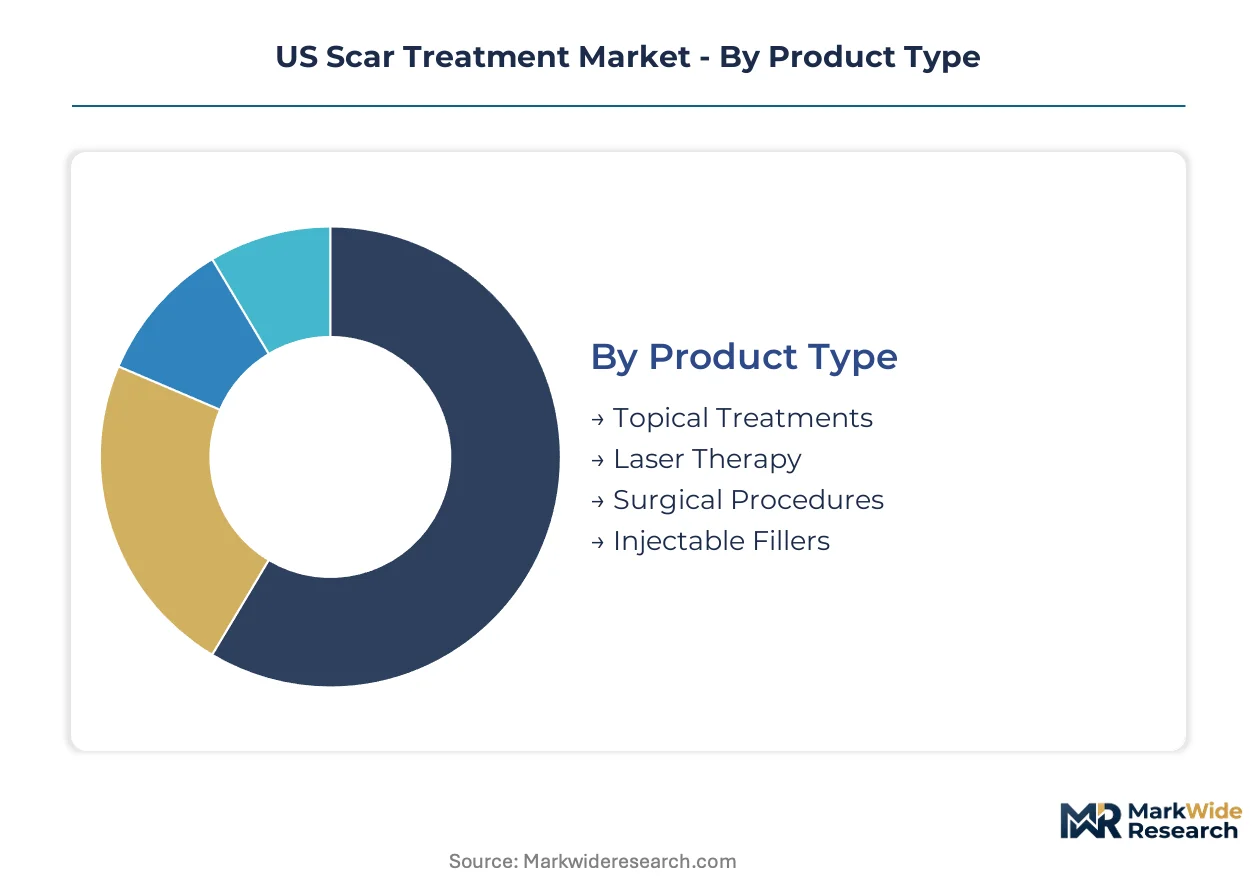
Scar treatment revenue pools fragment across four distinct category axes, with product type and application driving the steepest margin differentiation. Understanding where value concentrates within each dimension enables precise resource allocation for manufacturers and service providers competing in this $9.43 billion trajectory.
Product Type:
Margin pools concentrate in capital-intensive modalities where recurring consumables and service contracts extend lifetime customer value beyond initial equipment placement.
- Topical Treatments:Silicone-based gels and sheets dominate unit volume through retail accessibility, with California and Florida pharmacies stocking the broadest SKU assortments. The category captures walk-in demand from patients seeking non-prescription intervention before clinic consultation.
- Laser Therapy:Fractional and picosecond platforms operating at 755-1064 nm wavelengths command premium pricing per treatment session. Texas dermatology clinics are expanding fractional laser service lines fastest as supervised non-physician operation laws broaden addressable provider capacity.
- Surgical Procedures:Scar revision surgery and tissue expansion techniques retain the highest per-case revenue but face volume pressure from less invasive alternatives. Burn centers in Florida maintain surgical caseload concentration due to specialized trauma infrastructure.
- Injectable Fillers:Hyaluronic acid formulations target atrophic scar depression with outpatient convenience. The segment gains share as dermatology groups in metropolitan markets package injectables into cosmetic service bundles.
The dominant share belongs to Topical Treatments, while Laser Therapy is closing the gap fastest.
Application:
Volume distribution tracks closely with underlying condition prevalence and treatment protocol complexity across US clinical settings.
- Acne Scars:Atrophic and hypertrophic variants from adolescent and adult acne drive consistent demand for fractional laser and microneedling protocols. California cosmetic dermatology practices report the highest per-capita acne scar consultation volume nationally.
- Surgical Scars:Post-operative linear scars from abdominal, cardiac, and orthopedic procedures create steady referral flows to specialized revision centers. Texas surgical centers are integrating early-stage topical intervention into discharge protocols to reduce downstream revision needs.
- Burn Scars:Contracture management and functional restoration require multidisciplinary care coordination. Florida's burn center density supports concentrated expertise in complex graft and laser sequencing.
- Keloid Scars:Recurrence-prone fibroproliferative tissue demands combination approaches with corticosteroid injection, cryotherapy, and radiation. The segment shows elevated patient persistence due to psychological burden of visible facial and earlobe involvement.
Surgical Scars anchor the largest volume base, though Acne Scars are expanding most quickly as cosmetic procedure marketing normalizes intervention.
End User:
Service delivery economics vary sharply by setting, with reimbursement profiles and capital requirements filtering competitive participation.
- Hospitals:Burn centers and trauma units manage the most complex scar revision cases requiring anesthesia support and inpatient monitoring. Medicare reimbursement bundling shapes procedure selection toward medically necessary interventions.
- Dermatology Clinics:Ambulatory settings concentrate fractional laser and injectable volume, with California and Texas groups leading platform adoption curves. Scope-of-practice expansion enables supervised technician operation, compressing per-treatment labor costs.
- Homecare Settings:Silicone sheeting, pressure garments, and topical retinoids sustain patient-managed maintenance between clinical visits. Direct-to-consumer channels are disintermediating traditional prescription dispensing in this segment.
- Cosmetic Surgery Centers:Premium positioning and bundled aesthetic packages support pricing power for combination laser-injectable protocols. Florida centers leverage high cosmetic procedure density to cross-sell scar services.
Dermatology Clinics command the dominant service volume, while Cosmetic Surgery Centers are gaining share fastest through premium positioning.
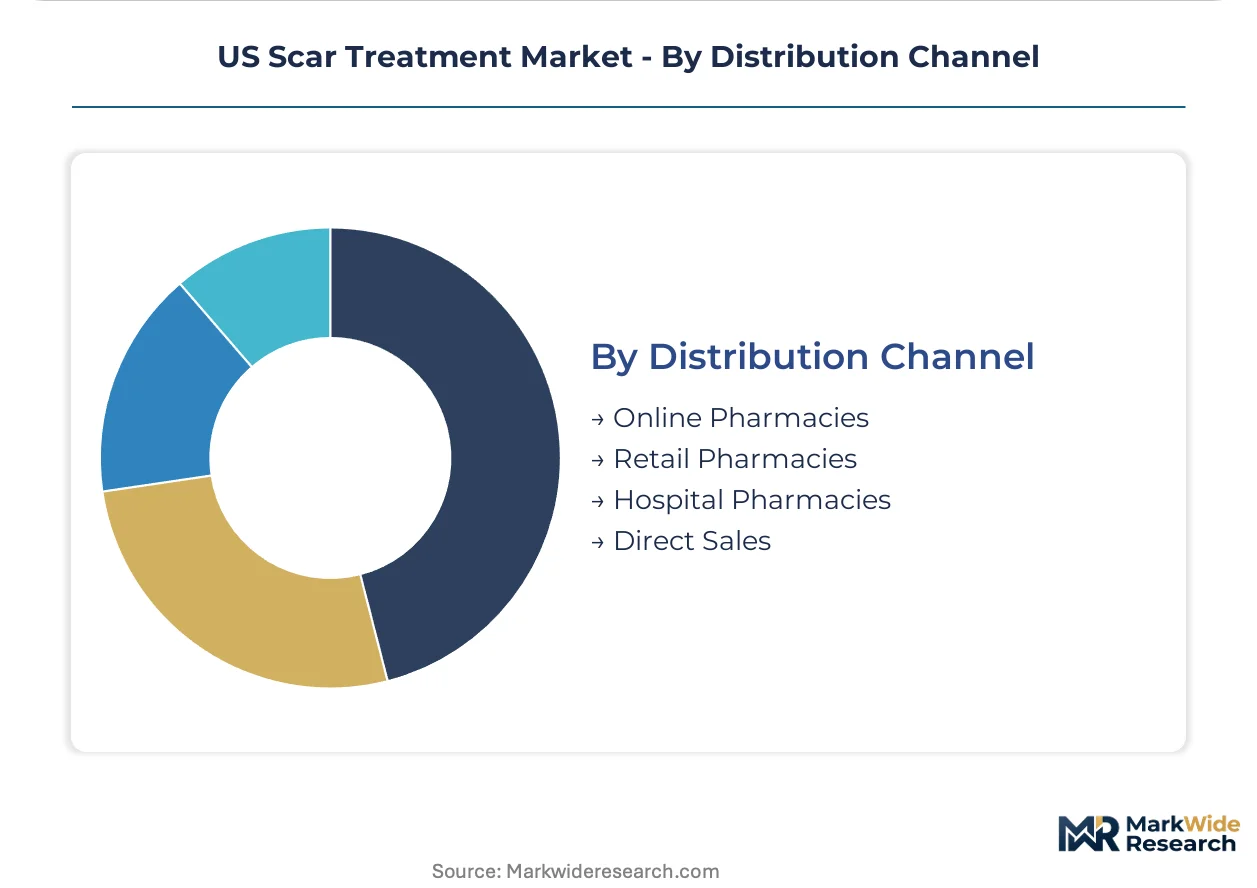
Distribution Channel:
Channel selection determines margin capture and patient relationship continuity across the treatment journey.
- Online Pharmacies:Subscription replenishment models for silicone products and topical kits are displacing one-time surgical center purchases. California and Florida markets show the highest e-commerce penetration for scar care products.
- Retail Pharmacies:Mass-market accessibility supports topical treatment volume with pharmacist counseling on OTC selection. Chain retailers are expanding dedicated wound care aisle space in high cosmetic procedure markets.
- Hospital Pharmacies:Institutional procurement governs post-surgical and burn care product flow, with formulary committees filtering vendor participation. EPA-registered antimicrobial claims carry decisive weight in selection criteria.
- Direct Sales:Device manufacturers and pharmaceutical suppliers maintain field forces targeting dermatology group purchasing organizations. Capital equipment leasing and consumable contract structures dominate laser platform transactions.
Retail Pharmacies hold the dominant position, though Online Pharmacies are climbing the fastest as subscription models reshape patient purchasing behavior.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA 510(k) clearance pathways and state-level scope-of-practice laws anchor demand concentration across US metropolitan surgical centers and dermatology networks.
California
Cosmetic dermatology practices in Los Angeles and San Francisco report the highest per-capita acne scar consultation volume nationally. EPA antimicrobial claim regulations for hypochlorous acid products shape procurement at ambulatory surgical centers. The Bay Area hosts concentrated picosecond laser adoption as dermatology groups compress capital replacement cycles to 18-24 months.
Texas
State law permits supervised non-physician laser operation, broadening clinic capacity and patient throughput in Dallas and Houston surgical centers. Texas Medical Board regulations govern technician certification requirements for fractional platform operation. Surgical centers in the Texas Medical Center cluster are integrating early-stage topical intervention into discharge protocols.
Florida
Burn center density in Miami and Tampa supports concentrated expertise in complex graft and laser sequencing for contracture management. Florida Board of Medicine regulations align with Texas on expanded laser use by non-physician operators. Cosmetic surgery centers in South Florida leverage high procedure density to cross-sell scar revision services.
Illinois
Chicago metropolitan dermatology groups anchor Midwest laser service line expansion despite rural physician availability constraints. Illinois Department of Financial and Professional Regulation maintains stricter technician supervision requirements than Sun Belt states. The city hosts regional purchasing organization concentration for silicone sheeting and pressure garment procurement.
New York
Manhattan and Long Island cosmetic practices sustain premium pricing for combination laser-injectable protocols. New York State Education Department regulations require direct physician presence for laser procedures, limiting technician delegation. The metropolitan area shows elevated direct-to-consumer topical kit penetration through pharmacy and e-commerce channels.
US Scar Treatment Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across the US scar treatment market. The vendor base clusters around three strategic tiers: multinational device manufacturers with installed base leverage, pharmaceutical formulators with topical and injectable portfolios, and regional service delivery platforms consolidating metropolitan clinic networks. Competitive dynamics center on M&A activity targeting dermatology group purchasing organizations and strategic partnerships bridging device and pharmaceutical modalities.
Within the multinational device tier, Lumenis Be Ltd. and Cynosure exemplify capital equipment specialists leveraging recurring consumable revenue models. Merz Pharmaceuticals, LLC anchors the pharmaceutical archetype with injectable positioning for atrophic scar revision. Sonoma Pharmaceuticals, Inc. represents the topical formulation specialist segment targeting post-procedural wound care in ambulatory settings.
| Leading Market Players |
|---|
| Smith & Nephew PLC |
| Merz Pharmaceuticals, LLC |
| Lumenis Be Ltd. |
| Sonoma Pharmaceuticals, Inc. |
| Cynosure |
| CCA Industries, Inc. |
| Mölnlycke Health Care AB |
| Suneva Medical |
| Scar Heal Inc. |
| Others |
Pricing and Supply Chain Analysis
FDA 510(k) clearance tiers for laser devices gate both supply qualification and price stratification across the US scar treatment market, with capital equipment vendors commanding premium positioning against commodity topical suppliers.
Pricing Analysis
California cosmetic dermatology practices charge 40-60% above Midwest rates for identical fractional laser protocols, reflecting geographic concentration of purchasing power and marketing density. Pricing stratifies across premium capital platforms, mid-tier consumable bundles, and economy topical channels. Cost compression in the laser consumable tier intensifies as metropolitan clinic networks consolidate procurement around GPO contracts. Homecare settings show highest price sensitivity, while burn centers demonstrate lowest sensitivity due to bundled reimbursement and functional outcome mandates.
Supply Chain Analysis
Strategic stockpiling of picosecond laser consumables dominates procurement behavior among Texas and Florida surgical centers facing compressed replacement cycles. Device manufacturing concentrates in Israel, Germany, and the United States, with fractional platform assembly drawing from precision optics suppliers in Japan and Switzerland. Raw material dependencies include medical-grade sapphire crystals, rare-earth doped laser rods, and pharmaceutical-grade silicone polymers. Single-source vulnerability runs through Israeli precision laser component suppliers exposed to regional geopolitical disruption. Distribution runs through dermatology group purchasing organizations consolidating metropolitan procurement decisions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Scar treatment represents an early-cycle expansion story as FDA streamlined 510(k) pathways accelerate picosecond laser adoption curves and state scope-of-practice liberalization broadens addressable provider capacity.
For Market Incumbents: Secure recurring consumable revenue through locked-in service contracts before capital replacement cycles compress further. Defend installed base leverage by backward integration into hypochlorous acid topical formulations, neutralizing pharmaceutical entrants threatening device-agnostic protocols. Prioritize certification investment in EPA-registered antimicrobial claims to maintain formulary positioning at ambulatory surgical centers.
For New Entrants and Emerging Players: Lead with tele-dermatology platforms targeting Mountain West counties where board-certified dermatologist availability has collapsed. Exploit white-space in supervised technician training certification programs, where 300% variance in state hour requirements creates compliance arbitrage. Capture homecare segment share through subscription replenishment models displacing one-time surgical center purchases.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across topical formulation segments as EPA antimicrobial testing requirements force consolidation. Long-term viability favors platforms combining device placement with consumable recurring revenue over pure-play topical suppliers facing channel disintermediation. Target acquisition archetype: regional dermatology clinic networks with concentrated Medicare Advantage contract exposure. Watch CMS reimbursement code consolidation decisions as inflection signal for laser procedure profitability.
| Strategic Initiative | Industry Significance |
|---|---|
| Combination Drug-Device Development | FDA guidance on integrated topical-laser protocols creates regulatory white space for synchronized treatment modalities. |
| Tele-Dermatology Platform Integration | Remote consultation infrastructure extends specialist reach into underserved Mountain West counties lacking physician density. |
| EPA-Registered Antimicrobial Formulation | Post-procedural wound care claims satisfy ambulatory surgical center procurement committees filtering vendor participation. |
| Technician Certification Program Standardization | Multi-state clinic operators reduce compliance complexity through unified training protocols spanning 300% regulatory variance. |
| Subscription Replenishment Model Deployment | Direct-to-consumer channels disintermediate traditional prescription dispensing for silicone sheeting and pressure garment products. |
Research Methodology
Initial hypotheses were tested against primary input from dermatology clinic operators, biomedical device procurement managers, GPO contract specialists, and FDA regulatory consultants and refined through secondary validation. Primary fieldwork encompassed structured interviews with fractional laser service line directors at metropolitan surgical centers and ambulatory network executives. Secondary sources included FDA 510(k) clearance databases, EPA antimicrobial product registrations, CMS procedure code bundling determinations, and state medical board scope-of-practice filings. Bottom-up demand modeling triangulated against top-down market sizing across product type and application dimensions.
Variance decomposition anchored the analytical framework, isolating volume drivers from price-mix effects across the projection horizon. Segmentation dimensions encompassed product type, application, end user, and distribution channel, with additional modeling of state regulatory cluster impacts. CAGRs derived from logistic adoption curves fitted to capital equipment replacement patterns and patient consultation volume trajectories. Industry-specific forecast inputs included picosecond laser platform placement rates and technician certification expansion timelines.
Underlying assumptions cover FDA clearance timeline stability and state scope-of-practice liberalization continuity, with deviation risk concentrated in CMS reimbursement compression and EPA antimicrobial claim evidentiary tightening. Forecasts reflect documented assumptions with explicit sensitivity ranges. Revision becomes warranted when Medicare bundling intensity crosses thresholds triggering metropolitan clinic service line restructuring.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Regenerative Medicine
Th17 Driven Disease Treatment Market
Regenerative Medicine
Orthopedic Regenerative Medicine Market
Regenerative Medicine
Global Orthopedic Regenerative Surgical Products Market
Regenerative Medicine
Mesotherapy Guns Market
Regenerative Medicine
North America Regenerative Medicines Market
Regenerative Medicine
Regenerative Artificial Skin Market
Regenerative Medicine
Epidermal Cell Sheets Market
Regenerative Medicine
Dural Graft Market
Regenerative Medicine
Asia-Pacific Regenerative Medicine Market
Regenerative Medicine
Cartilage Degeneration Market
Regenerative Medicine
Cell Damage & Repair Market
Regenerative Medicine
Longevity and Anti-Senescence Therapy for Cancer Market
Regenerative Medicine
Europe Longevity and Anti-Senescence Therapy Market
Regenerative Medicine
Degenerative Disc Disease Treatment Market
Regenerative Medicine
Global Vaginal Rejuvenation Market
Regenerative Medicine
Soft Tissue Repair Market