
 Global Vaginal Rejuvenation Market | 2026-2036
Global Vaginal Rejuvenation Market Size, Share, and Industry Trends Forecast 2026-2036
Global Vaginal Rejuvenation Market Foresight
Fractional CO2 and erbium:YAG laser architectures is fragmenting legacy monolithic platform designs into modular, application-specific systems. Alma Lasers leverages interchangeable handpiece ecosystems to address multiple tissue depths without capital redundancy. Hologic Inc. anchors hospital-grade reliability standards in outpatient settings through controlled thermal injury protocols. Lutronic competes with dual-wavelength platforms that reduce treatment intervals while maintaining mucosal safety margins.
Vaginal rejuvenation encompasses energy-based and mechanical interventions that restore structural integrity, vascular perfusion, or lubrication function to vaginal mucosa and supporting connective tissue; typical laser systems operate at 10,600 nm or 2,940 nm wavelengths with pulse durations between 0.3 and 1.0 milliseconds to achieve controlled ablation depths of 50-200 microns. Laser devices dominate installed base metrics across mature markets due to established reimbursement coding and physician training infrastructure. Radiofrequency devices represent the fastest-growing product category as temperature-controlled volumetric heating expands treatable patient profiles beyond photoaged mucosa. Injectable fillers concentrate margin pools in cash-pay segments where hyaluronic acid and platelet-rich plasma formulations command premium pricing independent of capital equipment amortization.
FDA 510(k) clearance requirements and the EU Medical Device Regulation reshape competitive access timelines for energy-based systems entering the United States and European markets. CE marking under MDR Class IIa rules demands expanded clinical evidence for devices claiming therapeutic outcomes beyond cosmetic indication. Japan's PMDA and South Korea's MFDS maintain distinct adverse event reporting thresholds that influence product configuration choices for Asia-Pacific market entry. Stakeholders must monitor evolving distinctions between wellness-oriented aesthetic claims and therapeutic indications as regulators recategorize devices based on primary intended use.
Market Dynamics
Non-invasive energy modalities are compressing surgical procedure volumes as aesthetic clinics retool capital equipment portfolios toward outpatient-compatible platforms. This technology substitution is redistributing margin pools from hospital operating theaters to private clinic settings.
Growth Catalysts
- Radiofrequency platform proliferation:Temperature-controlled volumetric heating expands treatable patient profiles beyond photoaged mucosa into stress urinary incontinence segments.
- CE marking pathway refinement:EU Medical Device Regulation Class IIa rules are clarifying clinical evidence standards for therapeutic indication claims, accelerating compliant product entries.
- Aesthetic clinic density in the United States:Private practice consolidation in metropolitan corridors is standardizing training infrastructure for laser and RF modalities.
Market Restraints
- Capital equipment amortization pressure:Fractional CO2 laser systems require 24-36 month payback cycles that strain independent clinic cash flows.
- FDA 510(k) clearance timelines:Predicate device requirements for energy-based systems extend regulatory review periods beyond 180 days for novel wavelength configurations.
- Injectable filler substitution:Hyaluronic acid and platelet-rich plasma formulations capture margin pools without capital equipment requirements.
Strategic Opportunities
- Brazil's private healthcare expansion:ANVISA regulatory harmonization with FDA standards is reducing market entry friction for energy-based device manufacturers.
- Telemedicine-integrated consultation models:Remote pre-screening protocols are compressing patient acquisition costs for aesthetic clinic networks.
- Dual-wavelength platform convergence:Erbium:YAG and CO2 combination systems are enabling single-session treatment protocols that reduce chair time.
Industry Challenges
- Physician training standardization:Energy-based device operation requires gynecology-dermatology cross-training that medical residency programs rarely provide.
- Adverse event documentation complexity:MFDS and PMDA maintain distinct thermal injury reporting thresholds that complicate multi-regional product configuration.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Vaginal Rejuvenation Market |
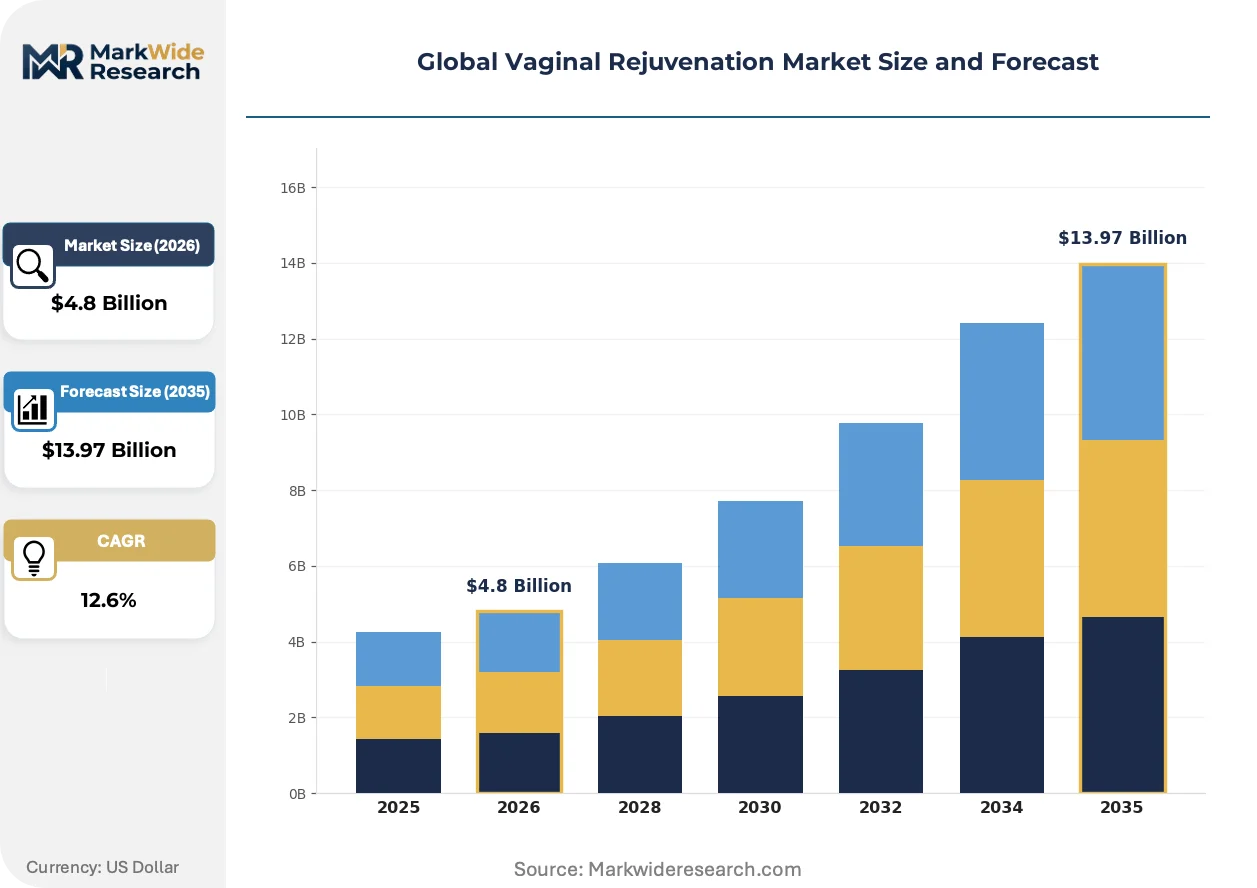
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $13.97 Billion |
| CAGR (2026 – 2036) | 12.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Laser Devices, Radiofrequency Devices, Ultrasound Devices, Surgical Instruments, Injectable Fillers Application: Postpartum Treatment, Urinary Incontinence, Vaginal Laxity, Sexual Dysfunction, Menopausal Symptoms End User: Gynecologists, Cosmetic Surgeons, Urogynecologists, Dermatologists, Aesthetic Clinics Delivery Mode: In-Clinic Procedures, Minimally Invasive, Non-Invasive, Injectable Treatments, Surgical Methods |
| Companies Covered | Hologic Inc., Cynosure Inc., InMode Ltd., BTL Industries, Lumenis Ltd., Alma Lasers, Fotona LLC, Venus Concept, Lutronic, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Vaginal Rejuvenation Market Shifts & Advancements
Modular platform architectures are fragmenting monolithic device designs into application-specific ecosystems. This shift is compressing capital redundancy while expanding tissue-depth versatility across outpatient settings.
Fractional laser systems operating at 10,600 nm and 2,940 nm wavelengths are digitizing treatment parameter libraries into cloud-connected platforms. Aesthetic clinic chains in Germany and South Korea are adopting these systems at replacement-cycle velocities of 18-24 months. The technology is digitizing outcome tracking into standardized databases that support reimbursement coding negotiations.
EU Medical Device Regulation recategorization protocols are redefining the boundary between wellness-oriented aesthetic claims and therapeutic indications. Manufacturers must now submit expanded clinical evidence for devices claiming functional restoration beyond cosmetic outcomes. Energy-based systems targeting stress urinary incontinence are most affected, with several platforms pursuing amended CE marking under Class IIa therapeutic designation.
After-sales service unbundling is disrupting traditional capital equipment procurement in the United States. Large aesthetic clinic networks are negotiating hardware-only purchases while sourcing maintenance and training through third-party specialists. This pattern is most visible in metropolitan corridors where independent service organizations have achieved critical mass in laser repair and calibration certification.
Global Vaginal Rejuvenation Market Segmentation
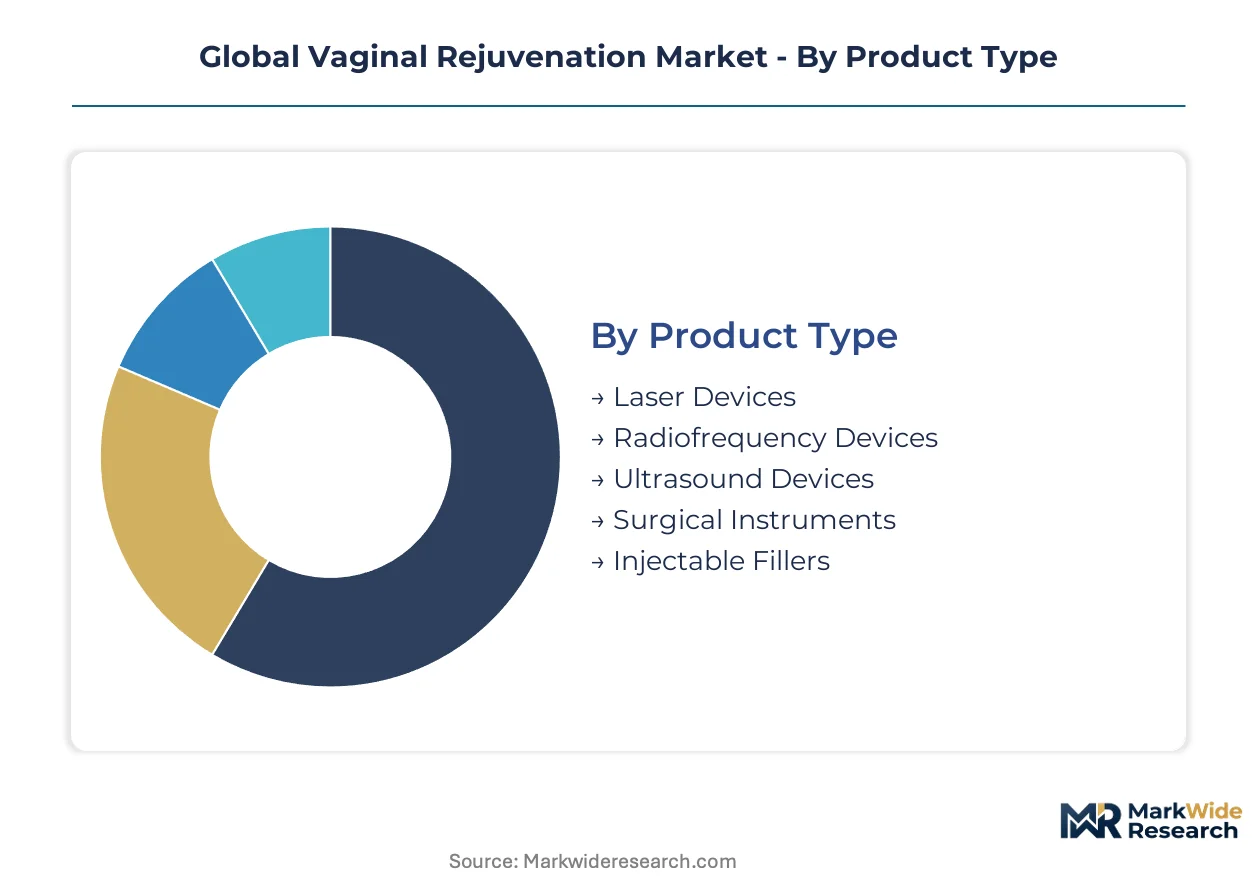
Segmentation in vaginal rejuvenation reveals how capital equipment intensity, clinical training requirements, and reimbursement pathways fragment purchasing behavior across provider types. Each dimension exposes distinct margin structures and technology substitution patterns that reshape competitive positioning.
Product Type:
After-sales service intensity varies dramatically across product categories, with laser platforms demanding specialized calibration protocols and radiofrequency systems requiring less frequent technical intervention.
- Laser Devices:Fractional CO2 and erbium:YAG systems operate at 10,600 nm or 2,940 nm wavelengths with pulse durations of 0.3-1.0 milliseconds. Demand concentrates in aesthetic clinics across the United States and Germany where established reimbursement coding supports premium pricing; these systems require 24-36 month amortization cycles that strain independent practice cash flows.
- Radiofrequency Devices:Temperature-controlled volumetric heating platforms treat patient profiles beyond photoaged mucosa into stress urinary incontinence segments. South Korean clinic networks in Seoul and Busan are expanding installed bases fastest as MFDS clearance pathways stabilize; thermal injury reporting thresholds remain less stringent than laser adverse event documentation.
- Ultrasound Devices:Micro-focused ultrasound systems penetrate deeper tissue planes without surface ablation.
- Surgical Instruments:Traditional vaginoplasty and labiaplasty tools retain hospital operating theater presence.
- Injectable Fillers:Hyaluronic acid and platelet-rich plasma formulations capture cash-pay segments without capital equipment requirements.
Laser devices hold the largest share; momentum sits with radiofrequency platforms.
Application:
Application segmentation tracks how clinical evidence requirements under FDA 510(k) and EU MDR reshape addressable market boundaries between wellness and therapeutic claims.
- Postpartum Treatment:Structural restoration procedures address tissue laxity following vaginal delivery. Demand clusters in private maternity hospitals across Brazil where ANVISA regulatory harmonization with FDA standards reduces device entry friction; patient acquisition costs compress through telemedicine-integrated consultation models.
- Urinary Incontinence:Energy-based interventions target stress incontinence through collagen remodeling and urethral support enhancement. CE marking under MDR Class IIa rules demands expanded clinical evidence for therapeutic indication claims, slowing European market entry for several platforms while accelerating compliant alternatives.
- Vaginal Laxity:Aesthetic-focused tissue tightening represents the original commercial indication for fractional laser adoption.
- Sexual Dysfunction:Vascular perfusion and lubrication function restoration claims face heightened regulatory scrutiny.
- Menopausal Symptoms:Atrophic vaginitis and dryness interventions align with gynecology practice workflows.
Vaginal laxity commands established volume; urinary incontinence applications are climbing the fastest as regulatory frameworks clarify.
End User:
End user segmentation reflects cross-training deficits in medical residency programs that fragment device purchasing authority between gynecology, dermatology, and surgical specialties.
- Gynecologists:Board-certified specialists anchor hospital outpatient department purchasing decisions with therapeutic indication focus. United States metropolitan corridors show consolidation into multi-specialty women's health networks that standardize training infrastructure; these groups negotiate hardware-only purchases while sourcing maintenance through third-party specialists.
- Cosmetic Surgeons:Plastic surgery-trained providers dominate cash-pay aesthetic segments with surgical and non-surgical modality integration.
- Urogynecologists:Subspecialists concentrate stress incontinence and pelvic floor dysfunction cases in academic medical centers.
- Dermatologists:Aesthetic-focused practitioners adopt laser and RF platforms for surface tissue applications.
- Aesthetic Clinics:Standalone facilities in Germany and South Korea drive replacement-cycle velocities of 18-24 months for digitized, cloud-connected platforms.
Gynecologists retain the largest patient access point; aesthetic clinics are gaining share fastest through capital equipment portfolio retooling.
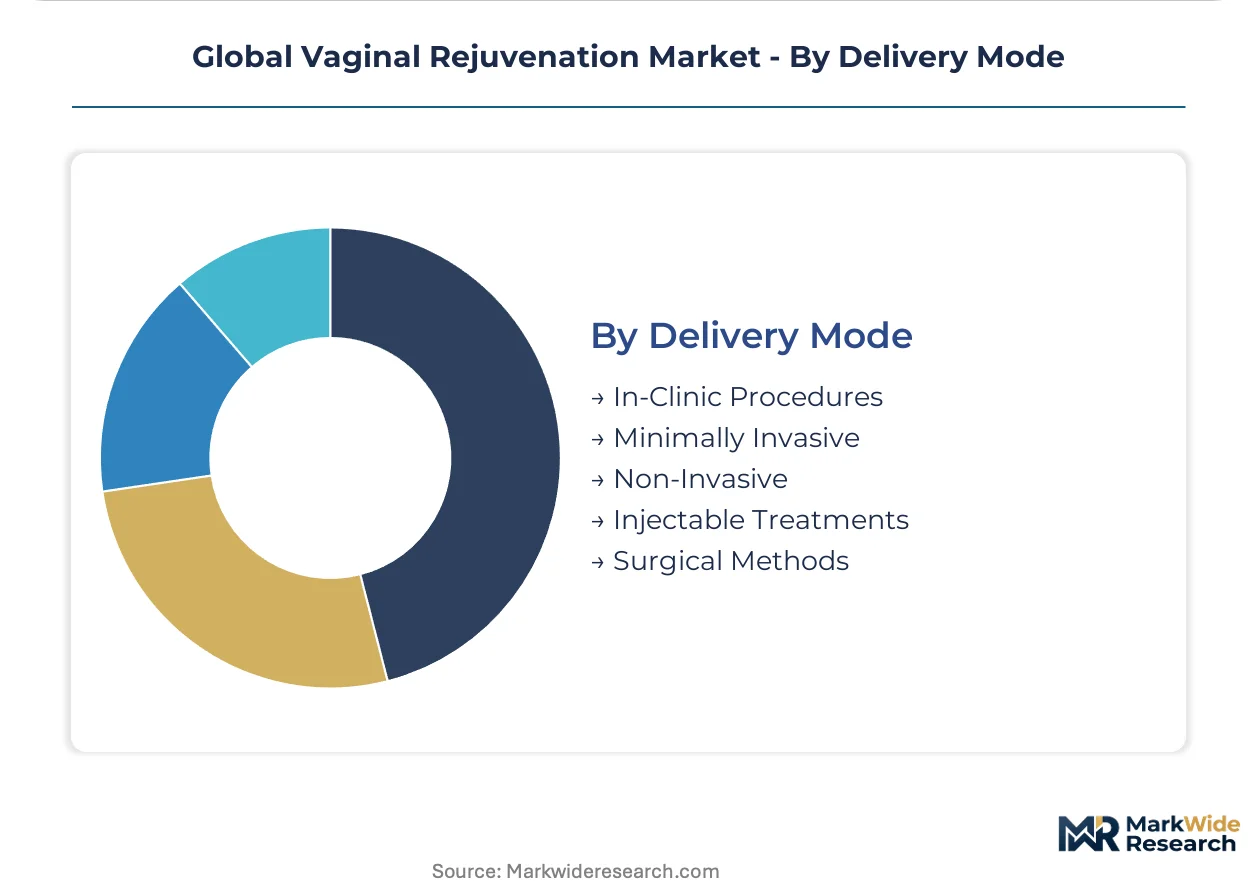
Delivery Mode:
Delivery mode segmentation captures the technology substitution wave compressing surgical volumes toward outpatient-compatible platforms.
- In-Clinic Procedures:Office-based treatments under local anesthesia or topical numbing dominate revenue concentration. South Korean and German aesthetic clinic chains adopt modular platform architectures that fragment monolithic designs into application-specific ecosystems; this shift compresses capital redundancy while expanding tissue-depth versatility.
- Minimally Invasive:Radiofrequency and laser modalities with minimal downtime requirements expand treatable patient profiles beyond surgical candidates.
- Non-Invasive:External energy delivery without penetration claims faces wellness-versus-therapeutic recategorization under evolving FDA and EU frameworks.
- Injectable Treatments:PRP and hyaluronic acid formulations require no capital equipment amortization.
- Surgical Methods:Traditional vaginoplasty and labiaplasty retain indications for severe anatomical alteration cases.
In-clinic procedures generate the highest volume; non-invasive modalities are expanding most quickly as regulatory boundaries clarify.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
South Korean device manufacturers export energy-based systems to aesthetic clinic networks across Germany and the United States, establishing the primary trade corridor for advanced laser and radiofrequency platforms.
United States
Metropolitan aesthetic clinic consolidation in Los Angeles and Miami drives replacement-cycle demand for modular laser platforms. FDA 510(k) clearance timelines for novel wavelength configurations extend regulatory review periods beyond 180 days. Private practice networks in Texas and Florida negotiate hardware-only purchases while sourcing maintenance through third-party specialists.
Germany
Established reimbursement coding for fractional CO2 procedures supports premium pricing in Munich and Berlin clinic clusters. EU Medical Device Regulation Class IIa rules demand expanded clinical evidence for therapeutic indication claims. Aesthetic chains in Hamburg and Frankfurt adopt digitized, cloud-connected platforms at 18-24 month replacement velocities.
South Korea
Seoul and Busan clinic networks expand installed bases of temperature-controlled radiofrequency systems fastest among Asia-Pacific markets. MFDS maintains distinct thermal injury reporting thresholds that influence product configuration choices. Domestic manufacturers leverage regulatory pathway stability to target export markets in Southeast Asia.
Brazil
Private maternity hospitals in São Paulo and Rio de Janeiro drive postpartum treatment demand for structural restoration devices. ANVISA regulatory harmonization with FDA standards reduces market entry friction for energy-based device manufacturers. Telemedicine-integrated consultation models compress patient acquisition costs in metropolitan corridors.
Japan
Academic medical centers in Tokyo and Osaka concentrate urogynecology subspecialists treating stress incontinence cases. PMDA adverse event reporting thresholds for thermal injury remain more stringent than South Korean requirements. Domestic distributors prioritize platforms with established clinical evidence packages for hospital outpatient department purchasing committees.
Global Vaginal Rejuvenation Market Competitive Landscape
Channel-controlling players compete with product-specialist players across tiered market strata. Hospital-grade reliability standards anchor purchasing decisions in academic medical centers, while aesthetic clinic networks prioritize modular architectures that compress capital redundancy. Three archetypes dominate: diversified medical device conglomerates with cross-specialty portfolios, laser-platform pure-plays with wavelength-specific expertise, and radiofrequency specialists leveraging temperature-control differentiation. M&A activity concentrates in modular handpiece ecosystems, and strategic partnerships link device manufacturers with third-party service organizations.
Within the hospital-grade tier, Hologic Inc. and Lumenis Ltd. exemplify diversified conglomerates with cross-specialty device portfolios. Alma Lasers occupies a position among wavelength-specialist platforms, while Lutronic represents dual-wavelength convergence strategies. These companies anchor competitive positioning through distinct regulatory clearance pathways and service unbundling negotiations with large clinic networks.
| Leading Market Players |
|---|
| Hologic Inc. |
| Cynosure Inc. |
| InMode Ltd. |
| BTL Industries |
| Lumenis Ltd. |
| Alma Lasers |
| Fotona LLC |
| Venus Concept |
| Lutronic |
| Others |
Supply & Pricing Matrix
Seoul's concentration of radiofrequency device manufacturing capacity creates asymmetric pricing power for South Korean exporters serving German and United States clinic networks. This geographic clustering compresses component procurement costs while amplifying margin capture downstream through bundled after-sales service contracts.
Pricing Analysis
Prior-generation fractional CO2 laser platforms trade at 40-60% discounts to current-generation dual-wavelength systems, while next-gen cloud-connected architectures command 25-35% premiums over installed-base replacements. The dominant pricing structure stratifies across premium, standard, and economy tiers defined by FDA clearance tier and handpiece modularity. Price differentiation centers on CE marking class and after-sales service bundling intensity. Cost compression in the standard tier intensifies as South Korean manufacturers expand direct distribution, eroding distributor markups. Independent aesthetic clinics in Brazil and metropolitan United States corridors exhibit highest price sensitivity, while consolidated German clinic networks prioritize total cost of ownership over acquisition price.
Supply Chain Analysis
Export control regimes governing laser resonator technology limit flow of erbium:YAG and CO2 gain media from United States and German suppliers to certain jurisdictions, forcing alternative sourcing strategies. Component manufacturing concentrates in South Korea, Germany, and Israel, with final assembly gravitating toward Shenzhen and Seoul clusters. Raw material dependencies include yttrium-aluminum-garnet crystals, specialty optical fibers, and precision temperature-control sensors. Single-source vulnerability in yttrium supply from Chinese processing facilities poses structural risk. Distribution runs through authorized medical device distributors with regulatory filing capabilities in destination markets, bypassing generalist logistics providers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Service-attach revenue streams expand faster than hardware sales as aesthetic clinic networks unbundle maintenance and training from capital equipment procurement, creating recurring revenue pools that outpace device replacement cycles.
For Market Incumbents: Harden regulatory defense through accelerated FDA 510(k) submissions for therapeutic indication expansions before predicate device pathways tighten further. Deepen backward integration into handpiece manufacturing to capture margin pools currently flowing to third-party optical component suppliers, insulating against yttrium supply disruptions. For New Entrants and Emerging Players: Pursue white-space opportunity in Brazil's postpartum treatment segment where ANVISA harmonization reduces entry friction and telemedicine-integrated models compress patient acquisition costs. Target urogynecology subspecialists in academic medical centers with stress urinary incontinence-focused platforms, leveraging Class IIa CE marking as credibility signal. For Investors and Strategic Acquirers: Long-term, this sits as a consolidation play because modular platform architectures favor scaled service networks over pure hardware vendors, and replacement-cycle compression to 18-24 months accelerates obsolescence of undifferentiated capital equipment. Watch MFDS adverse event reporting threshold adjustments as inflection signal for South Korean manufacturer competitiveness.| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | MDR Class IIa therapeutic designation unlocks reimbursement coding in German hospital outpatient departments. |
| Modular Handpiece Ecosystem | Interchangeable wavelength modules compress capital redundancy across Alma Lasers and Lutronic platform architectures. |
| Third-Party Service Unbundling | Independent service organizations in Los Angeles and Miami capture maintenance revenue from hardware-only clinic purchases. |
| Telemedicine-Integrated Consultation | Remote pre-screening protocols reduce patient acquisition costs for Brazilian private maternity hospital networks. |
| Dual-Wavelength Platform Convergence | Erbium:YAG and CO2 combination systems enable single-session protocols that compress chair time in Seoul clinic chains. |
Research Methodology
Cross-validation between primary interviews with aesthetic clinic operators and secondary validation through FDA 510(k) filings anchors the qualitative findings. Stakeholder engagement encompassed biomedical engineers at hospital purchasing committees, GPO contracts managers, regulatory affairs leads at device manufacturers, and aftermarket service heads at independent calibration firms. Secondary sources included CMS Medicare procedure coding databases, CE marking notifications under MDR Class IIa rules, and ANVISA regulatory harmonization documentation. Bottom-up procedure volume estimates triangulated against top-down capital equipment shipment data.
Calibration against historical replacement-cycle velocities and reimbursement coding adoption curves shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include product type, application indication, end-user specialty, and delivery mode, with regional regulatory cluster as an additional cross-cutting variable. CAGRs derived from installed base growth rates and average selling price trajectories, incorporating thermal injury reporting threshold differentials between MFDS and PMDA as demand-shaping inputs.
Macroeconomic conditions sit as an overlay; deviation in private healthcare expenditure growth and disposable income trajectories would shift the trajectory. Forecasts reflect documented assumptions regarding regulatory clearance timelines and clinic consolidation patterns. Material shifts in FDA predicate device requirements or EU MDR recategorization protocols would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Regenerative Medicine
Cell Damage & Repair Market
Regenerative Medicine
Soft Tissue Repair Market
Regenerative Medicine
Mesotherapy Guns Market
Regenerative Medicine
North America Regenerative Medicines Market
Regenerative Medicine
China Longevity and Anti-Senescence Therapy Market
Regenerative Medicine
Th17 Driven Disease Treatment Market
Regenerative Medicine
Asia-Pacific Regenerative Medicine Market
Regenerative Medicine
Regenerative Artificial Skin Market
Regenerative Medicine
Bioelectric Medicine Market
Regenerative Medicine
North America Scar Treatment Market
Regenerative Medicine
Longevity and Anti-Senescence Therapy for Cancer Market
Regenerative Medicine
Degenerative Disc Disease Treatment Market
Regenerative Medicine
Dural Graft Market
Regenerative Medicine
Stromal Vascular Fraction Market
Regenerative Medicine
Autologous Fat Grafting Market
Regenerative Medicine
North America Longevity and Anti-Senescence Therapy Market