
 US Patient Engagement Solutions Market | 2026-2036
US Patient Engagement Solutions Market Size, Share, and Industry Trends Forecast 2026-2036
US Patient Engagement Solutions Market Intelligence
A shift from fragmented point solutions toward unified platform contracts is recalibrating how hospital procurement teams evaluate vendors. Epic Systems Corporation dominates inpatient electronic health record integrations, while Oracle leverages cloud infrastructure to anchor enterprise-scale deployments. athenahealth competes on ambulatory workflow specialization, and Veradigm LLC differentiates through payer-provider data connectivity.
Patient engagement solutions encompass software and connected devices that enable individuals to access health records, communicate with care teams, and manage chronic conditions through interoperable digital interfaces. Cloud-native architectures with FHIR-compliant APIs now dominate new implementations, replacing on-premise legacy stacks that require costly maintenance. Telehealth platforms and patient portals lead product-type revenue, while artificial intelligence and big data analytics represent the fastest-expanding technology layers as providers automate outreach and risk stratification. Wearable devices remain a smaller but high-margin segment where hardware-software bundling protects pricing.
FDA oversight of software-as-a-medical-device, CMS interoperability rules under the 21st Century Cures Act, and HIPAA security requirements collectively shape product roadmaps and go-to-market timelines for vendors. State-level Medicaid expansion decisions in California, Texas, and New York further fragment addressable demand. Stakeholders must monitor how federal reimbursement policy for remote patient monitoring reshapes provider willingness to fund patient-facing technology investments.
Market Dynamics
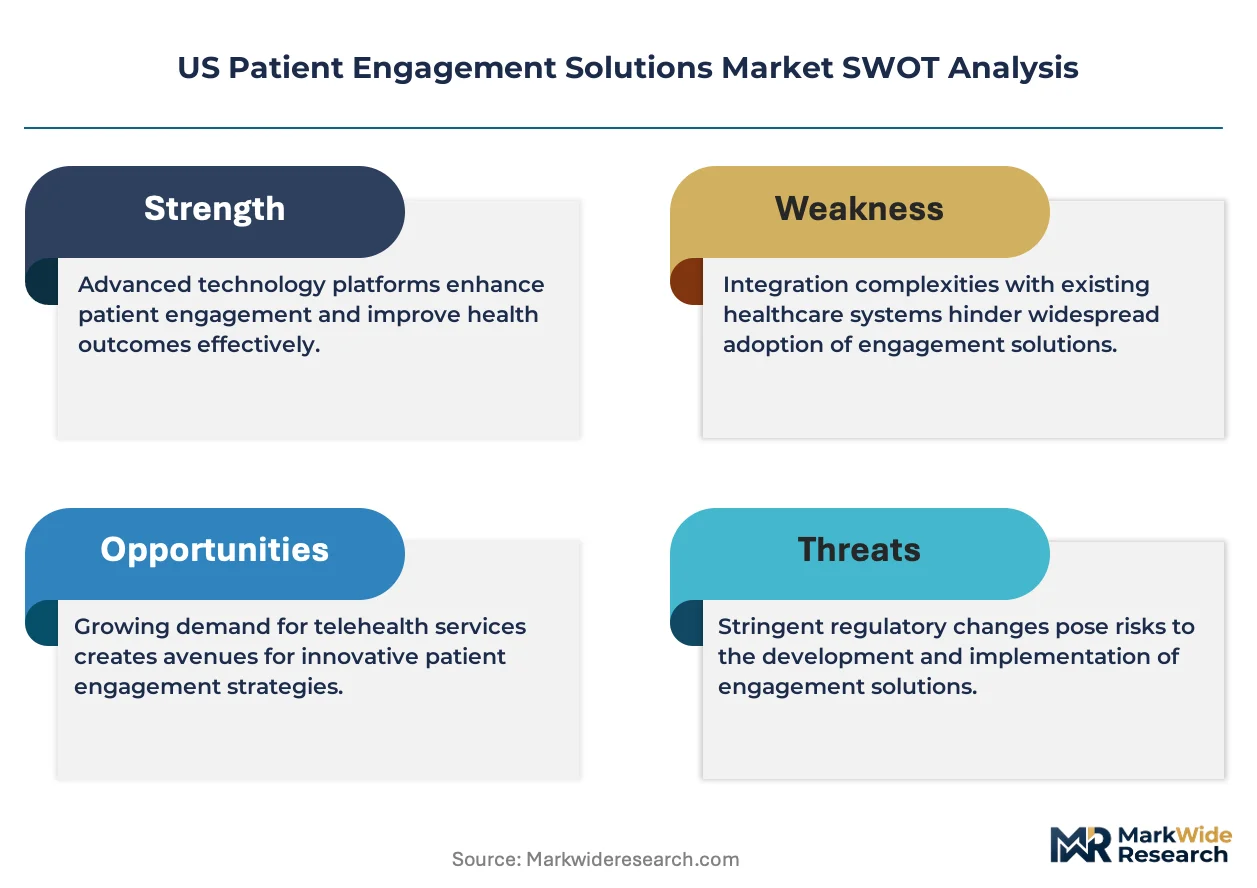
CMS interoperability mandates under the 21st Century Cures Act are forcing health systems to replace fragmented point solutions with unified platforms, compressing vendor evaluation cycles and consolidating procurement around FHIR-compliant architectures.
Growth Catalysts
- CMS Readmission Penalty Avoidance:Hospital systems deploy remote patient monitoring tools to reduce thirty-day readmission rates and protect Medicare reimbursement levels.
- Texas Medicaid Expansion Momentum:State-level coverage expansion in Texas and California creates addressable demand for patient portal infrastructure among newly enrolled populations.
- Cloud-Native API Architectures:FHIR-compliant interfaces enable seamless data exchange between EHR systems and third-party engagement applications, accelerating deployment timelines.
Market Restraints
- HIPAA Compliance Cost Burden:Security audit requirements and breach notification protocols impose ongoing operational overhead on SaaS vendors.
- Legacy System Technical Debt:On-premise EHR installations in mid-tier hospitals resist cloud migration, creating integration friction and extended sales cycles.
- Specialized Talent Scarcity:Shortage of health informaticists with dual clinical and data engineering expertise constrains implementation velocity.
Strategic Opportunities
- Rural Health Clinic Underservice:Federally Qualified Health Centers in Appalachian and Southwestern states lack patient engagement infrastructure, creating greenfield deployment potential.
- Behavioral Health Integration Mandates:New York's parity enforcement and California's Medi-Cal expansion drive demand for mental health-specific portal modules.
- Wearable-Generated Biometric Streams:Continuous glucose monitors and blood pressure cuffs feed automated care protocols, opening subscription revenue models.
Industry Challenges
- Interoperability Certification Delays:ONC testing requirements for standardized API functionality extend product launch timelines by six to twelve months.
- Workflow Integration Complexity:Ambulatory practices struggle to embed patient-facing tools into existing nurse triage and scheduling operations without productivity loss.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US Patient Engagement Solutions Market |
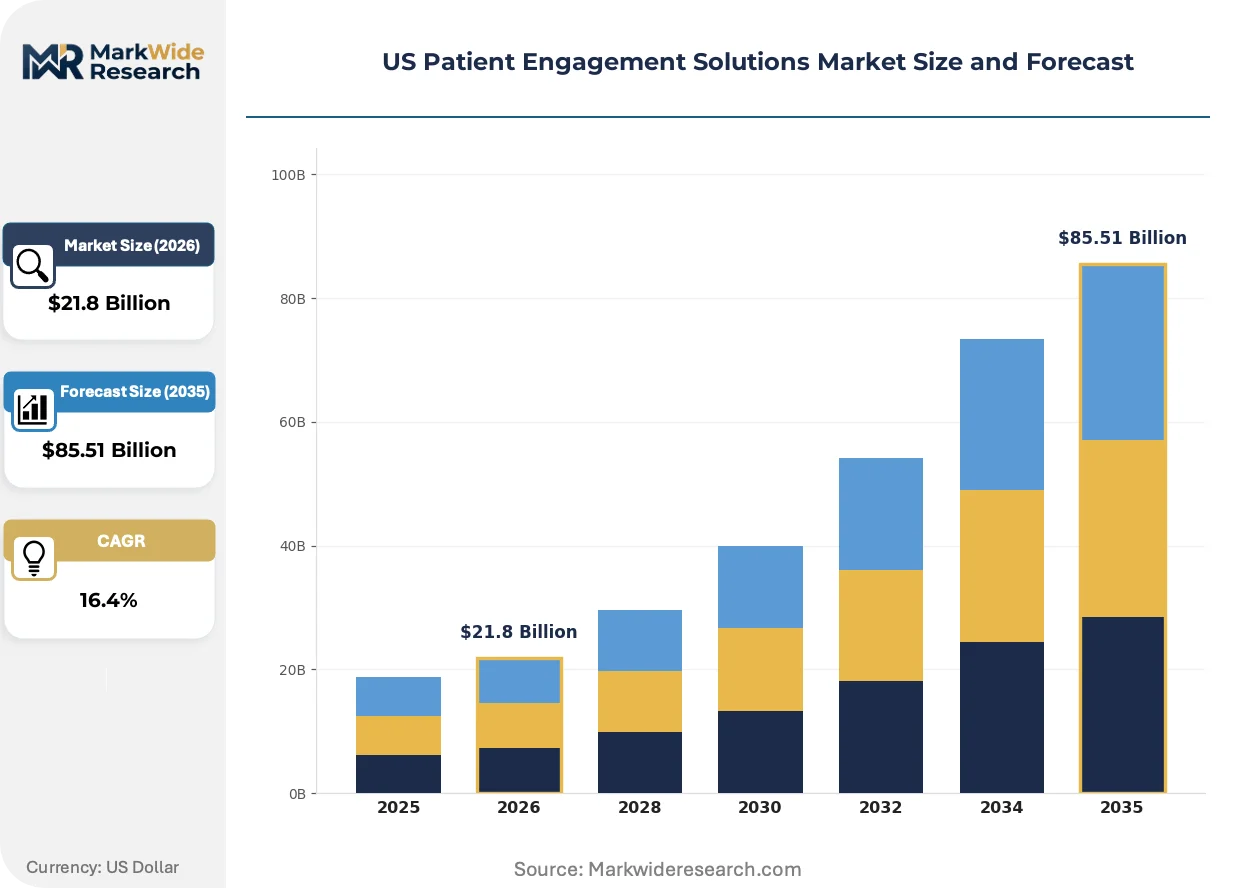
| Market Size in 2026 | $21.8 Billion |
| Market Size in 2035 | $85.51 Billion |
| CAGR (2026 – 2036) | 16.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Mobile Applications, Patient Portals, Wearable Devices, Telehealth Platforms End User: Healthcare Providers, Patients, Payers, Support Organizations Technology: Artificial Intelligence, Cloud Computing, Blockchain, Big Data Analytics Service Type: Consulting Services, Implementation Services, Training Services, Maintenance Services |
| Companies Covered | Epic Systems Corporation, Allscripts Healthcare, McKesson Corporation, Health Catalyst, NextGen Healthcare, Oracle, Veradigm LLC, GetWellNetwork, athenahealth, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US Patient Engagement Solutions Market Strategic Shifts & Innovations
Artificial intelligence layers are reshaping how providers automate patient outreach, risk stratification, and care gap closure, compressing the gap between data generation and clinical action.
FHIR-native data fabrics are unifying previously siloed EHR, claims, and device-generated information streams. Large integrated delivery networks in California and Texas are deploying these architectures to enable real-time care team coordination across acquired physician practices. This unification is collapsing the traditional boundary between inpatient and ambulatory engagement workflows.
FDA oversight of software-as-a-medical-device is tightening validation requirements for algorithm-driven diagnostic support tools. Vendors must now submit premarket documentation for AI features that influence clinical decision-making. Digital therapeutics companies targeting chronic condition management face the steepest compliance burden.
Health system procurement teams are consolidating vendor relationships around enterprise-wide platform contracts rather than departmental point solutions. Hospital CIOs in New York and Illinois now require single-vendor accountability for portal, telehealth, and remote monitoring functionality. This concentration favors vendors with proven EHR integration depth over best-of-breed specialists.
US Patient Engagement Solutions Market Segmentation
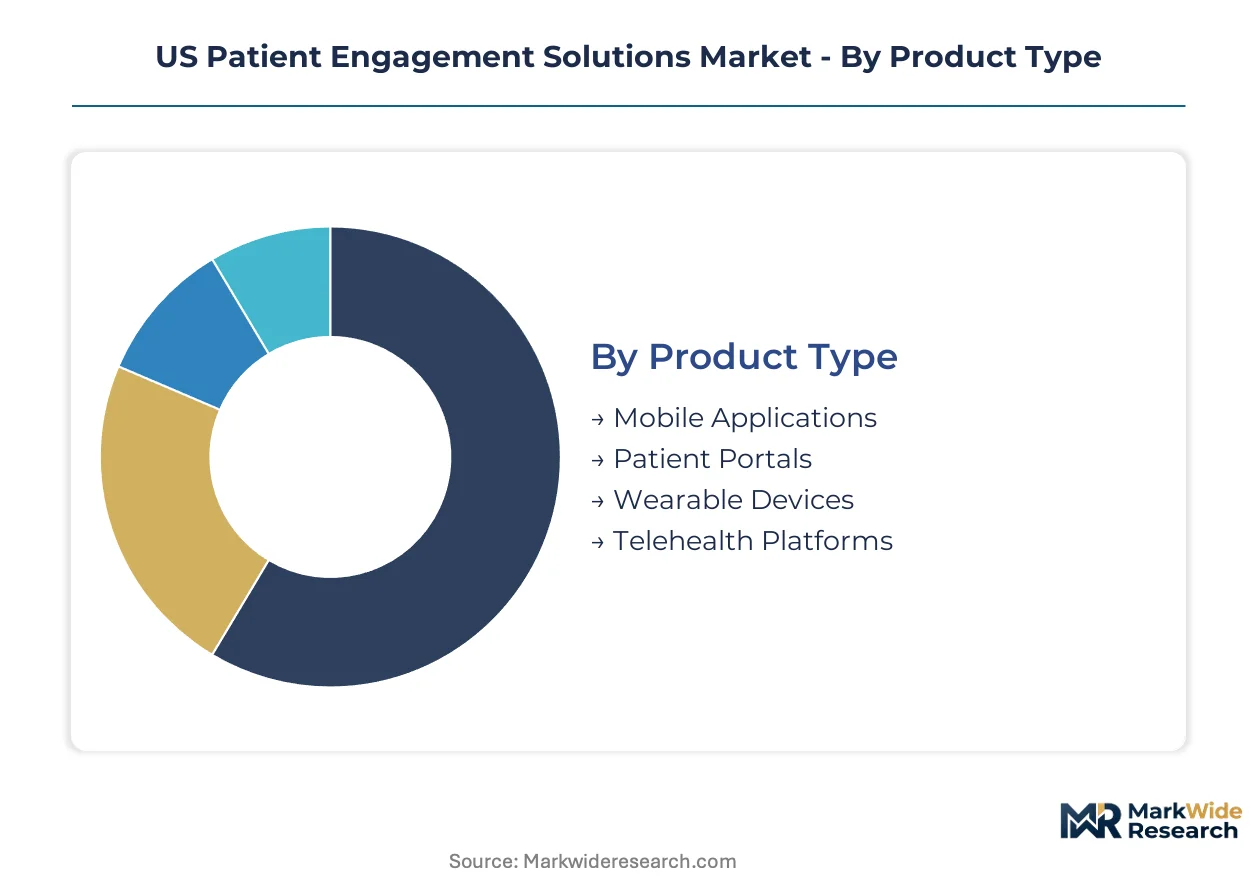
Segmentation in the US Patient Engagement Solutions Market reveals how procurement priorities diverge across health system archetypes. Understanding these fault lines enables vendors to align product roadmaps with buyer readiness and reimbursement incentives.
Product Type:
Procurement teams in California and Texas distinguish solutions by integration depth with existing EHR infrastructure and the scope of CMS reimbursement eligibility.
- Telehealth Platforms:Video-based consultation systems with embedded scheduling and billing modules dominate enterprise contracts. Texas Medicaid expansion and rural health clinic subsidies in Appalachian states concentrate demand for asynchronous visit capabilities that reduce specialist travel burdens.
- Patient Portals:FHIR-compliant web interfaces enabling record access, prescription refill, and secure messaging anchor hospital IT budgets. New York's large integrated delivery networks prioritize single-vendor portal contracts that span acquired ambulatory practices to satisfy interoperability mandates.
- Mobile Applications:Smartphone-native tools for medication adherence and symptom tracking serve younger patient demographics.
- Wearable Devices:Continuous biometric monitors with automated alert protocols command premium pricing in diabetes and hypertension management.
Volume sits with Patient Portals; growth tilts toward Telehealth Platforms.
End User:
Budget authority and technical sophistication vary sharply across stakeholder groups, shaping sales cycle length and implementation complexity.
- Healthcare Providers:Hospital systems and physician practices purchase enterprise licenses with EHR-embedded workflows. California's Kaiser Permanente and Texas's HCA anchor procurement volume through multi-year platform commitments that consolidate previously fragmented point solutions.
- Payers:Insurance carriers fund patient-facing tools to reduce emergency department utilization and improve risk adjustment accuracy. Medicare Advantage plans in Florida and Arizona subsidize remote monitoring for chronic condition cohorts to capture quality bonus payments.
- Patients:Direct-to-consumer purchases concentrate in high-deductible health plan populations seeking price transparency tools.
- Support Organizations:Disease-specific nonprofits and employer wellness programs license engagement platforms for population health campaigns.
Healthcare Providers command the largest contract values; Payers are expanding most quickly as value-based contracts mature.
Technology:
Architecture decisions determine scalability, security audit burden, and the pace of feature deployment.
- Cloud Computing:Scalable infrastructure with API-native interoperability dominates new implementations. AWS and Azure deployments in Texas and Illinois health systems displace on-premise legacy stacks that require costly maintenance and limit third-party integration.
- Artificial Intelligence:Natural language processing for automated outreach and predictive risk stratification layers atop core platforms. FDA premarket documentation requirements for algorithm-driven diagnostic support constrain vendor launch timelines.
- Big Data Analytics:Population-level pattern recognition tools aggregate claims, EHR, and device streams for care gap closure.
- Blockchain:Distributed ledger applications for consent management and audit trails remain experimental with limited production deployment.
Cloud Computing anchors current infrastructure spending; Artificial Intelligence claims the steepest expansion trajectory as providers automate outreach.
Service Type:
Professional services revenue correlates with buyer technical maturity and the complexity of legacy system migration.
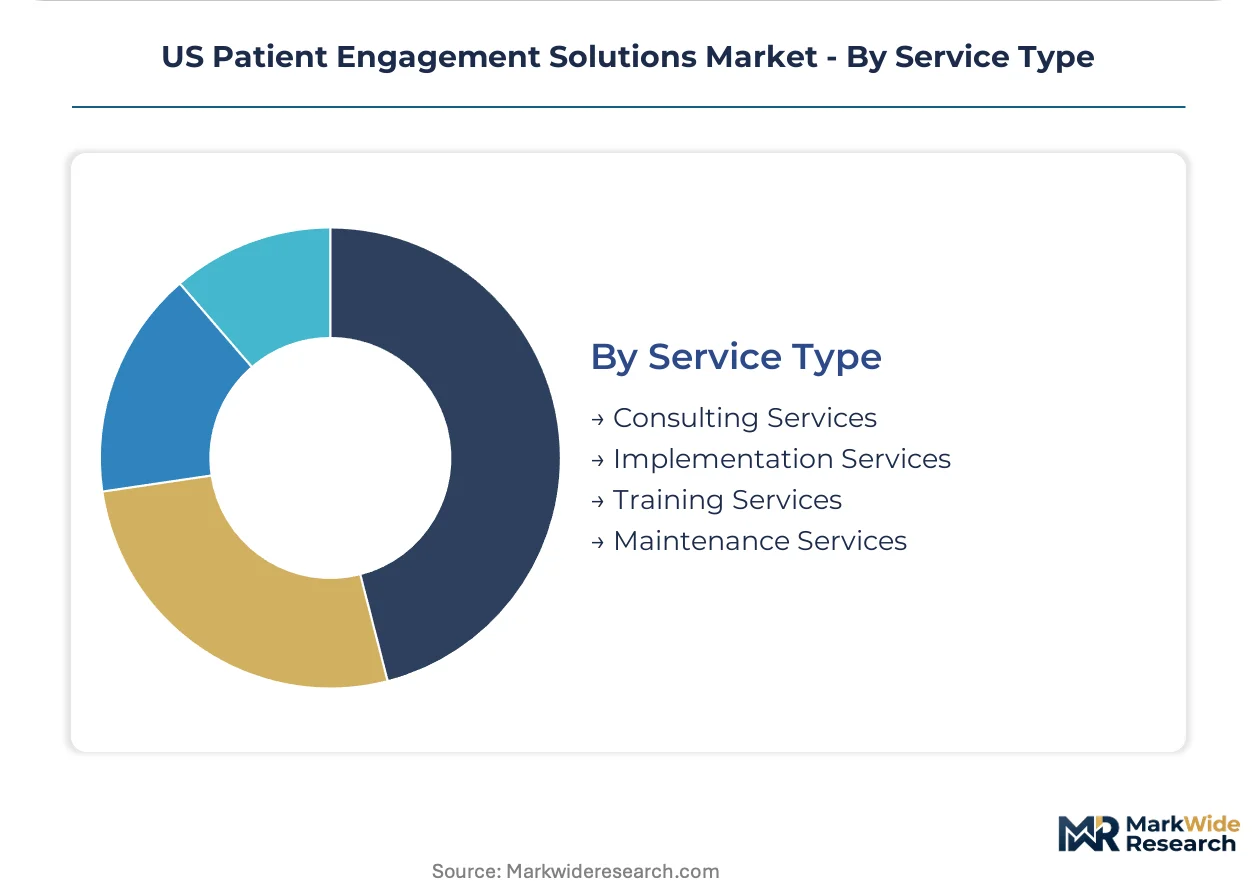
- Implementation Services:EHR integration, workflow redesign, and staff training dominate service revenue. Mid-tier hospitals in Ohio and Pennsylvania require extended deployment support to embed patient-facing tools into existing nurse triage operations without productivity loss.
- Consulting Services:Strategic advisory on vendor selection, interoperability roadmapping, and change management supports health system consolidation. New York and California IDNs engage consultants to rationalize acquired practice technology stacks.
- Training Services:Clinician and patient onboarding programs reduce technology abandonment rates.
- Maintenance Services:Ongoing security patching, API updates, and help desk support sustain recurring revenue streams.
Implementation Services capture the largest share; Consulting Services are gaining share fastest as procurement teams navigate vendor consolidation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand for patient engagement solutions concentrates in states with large integrated delivery networks and aggressive Medicaid expansion timelines. California, Texas, and New York anchor procurement volume through multi-year platform commitments.
California
Kaiser Permanente and Sutter Health drive enterprise-scale deployments across ambulatory and inpatient settings. Medi-Cal expansion creates addressable demand for patient portal infrastructure among newly enrolled populations in Los Angeles and San Francisco Bay Area corridors. Sacramento-based health systems consolidate vendor relationships around FHIR-compliant unified platforms.
Texas
HCA Healthcare and Tenet Healthcare anchor procurement through multi-hospital system contracts in Dallas-Fort Worth and Houston metropolitan clusters. State-level Medicaid momentum generates demand for remote monitoring tools among rural clinic networks in West Texas. Austin's digital health startup ecosystem supplies specialized workflow modules to mid-tier physician practices.
New York
Northwell Health and NYU Langone prioritize single-vendor accountability for portal, telehealth, and remote monitoring functionality across acquired practices. New York's behavioral health parity enforcement drives demand for mental health-specific engagement modules. Buffalo and Rochester health systems extend procurement timelines due to legacy EHR technical debt.
Florida
Medicare Advantage plans in Miami-Dade and Broward counties subsidize remote patient monitoring for chronic condition cohorts to capture quality bonus payments. Hospital systems deploy asynchronous telehealth capabilities to reduce specialist travel burdens in the Panhandle region. Tampa Bay health networks consolidate point solutions around cloud-native architectures.
Illinois
Chicago-based integrated delivery networks require single-vendor contracts spanning inpatient and ambulatory engagement workflows. Northwestern Medicine and Advocate Aurora drive standardization across acquired physician practices in the collar counties. Peoria and Springfield mid-tier hospitals resist cloud migration, creating extended sales cycles for legacy system integration.
US Patient Engagement Solutions Market Key Industry Players
Vendor consolidation dominates the current landscape as health system CIOs compress procurement cycles around enterprise-wide platform contracts. The market structure tilts toward concentrated procurement relationships with Epic Systems Corporation anchoring inpatient EHR integrations and Oracle leveraging cloud infrastructure for enterprise-scale deployments. Three strategic archetypes define positioning: EHR-native incumbents with workflow depth, cloud hyperscalers with API infrastructure, and ambulatory specialists with practice management focus. M&A activity and strategic partnerships represent the dominant competitive moves as vendors seek to collapse the boundary between inpatient and ambulatory engagement tools.
Within the EHR-native tier, Epic Systems Corporation and athenahealth exemplify divergent positioning strategies around inpatient versus ambulatory workflow specialization. Oracle occupies a position at the infrastructure layer, anchoring enterprise-scale cloud deployments that displace on-premise legacy stacks. Veradigm LLC sits within the payer-provider data connectivity archetype, representing the intersection of claims data and clinical workflow integration.
| Leading Market Players |
|---|
| Epic Systems Corporation |
| Allscripts Healthcare |
| McKesson Corporation |
| Health Catalyst |
| NextGen Healthcare |
| Oracle |
| Veradigm LLC |
| GetWellNetwork |
| athenahealth |
| Others |
Cost & Logistics Intelligence
Cloud-native FHIR architectures are displacing on-premise legacy stacks across California and Texas health systems, simultaneously collapsing maintenance cost structures and concentrating procurement leverage around vendors with proven EHR integration depth. This technology transition feeds pricing power toward platform consolidators while squeezing margins for point-solution specialists locked into fragmented hospital departmental budgets.
Pricing Analysis
Implementation and training service bundles anchor enterprise contract values, while unbundled API access and per-patient subscription tiers capture ambulatory practice segments. Three-tier pricing structure across premium, standard, and economy levels differentiates by FHIR certification depth and Epic integration maturity. Pricing pressure stems from hospital CIO consolidation mandates that compress vendor evaluation cycles and demand single-vendor accountability. Federally Qualified Health Centers in Appalachian states exhibit highest price sensitivity, while New York integrated delivery networks prioritize workflow depth over cost minimization.
Supply Chain Analysis
FDA premarket documentation and ONC interoperability certification gate vendor market access, extending product launch timelines and concentrating supply among established players with regulatory affairs infrastructure. Software development draws from India and Eastern European engineering centers, while cloud infrastructure rests on AWS and Azure domestic data center deployments. Single-source vulnerability concentrates in Epic Systems integration modules that dominate inpatient EHR connectivity. Distribution runs through direct enterprise sales teams targeting hospital procurement committees and GPO contract vehicles.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Vendor consolidation defines this market as CMS interoperability mandates and procurement rationalization force subscale point-solution vendors toward acquisition or exit.
For Market Incumbents: Lock in multi-year platform contracts with Texas and California integrated delivery networks before ambulatory workflow specialists gain EHR integration parity. Deepen FHIR-compliant API development to defend against Oracle cloud infrastructure encroachment. Acquire remote monitoring device manufacturers to capture hardware-software bundling premiums in diabetes and hypertension management segments. For New Entrants and Emerging Players: Rural health clinic networks in West Texas and Appalachian states offer lowest competitive density for greenfield patient portal deployment. Target Federally Qualified Health Centers with modular telehealth solutions that satisfy CMS reimbursement eligibility without requiring full EHR replacement. Partner with state Medicaid managed care organizations to subsidize patient-facing technology investments among newly enrolled populations. For Investors and Strategic Acquirers: Exit pathways concentrate in strategic acquisition by EHR-native incumbents seeking ambulatory workflow specialization or payer connectivity assets. Long-term viability favors vendors with demonstrated FHIR certification velocity and proven Epic integration deployment timelines. Watch FDA software-as-a-medical-device enforcement patterns as inflection indicator for algorithm-driven diagnostic support tool compliance burdens.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Epic Systems anchoring inpatient EHR connectivity collapses procurement around unified vendor accountability. |
| Strategic Partnership | Oracle cloud infrastructure partnerships displace on-premise legacy stacks in Texas and Illinois health systems. |
| Acquisition of Specialist Firm | Remote monitoring device manufacturers command hardware-software bundling premiums in chronic condition management. |
| FDA Submission | Software-as-a-medical-device premarket documentation gates AI-driven diagnostic support tool commercialization. |
| Reimbursement Strategy | Medicare Advantage quality bonus payment capture drives remote patient monitoring subsidy programs in Florida. |
Research Approach
Document review covered FDA 510(k) filings, CMS Medicare cost reports, and hospital procurement databases, complemented by interviews with health system CIOs, GPO contracts managers, and biomedical informaticists. Secondary validation drew from Epic Systems user group documentation, ONC interoperability certification records, and state Medicaid expansion policy filings. Bottom-up segmentation modeling triangulated against top-down health IT spending forecasts from federal agency disclosures.
Historical EHR adoption curves cross-referenced against panel input from hospital procurement committees informed the analytical framework across the projection horizon. Segmentation dimensions modeled encompass product type, end user archetype, technology architecture, and service delivery model. CAGRs derived from provider technology budget trajectories and CMS reimbursement policy evolution, with specific weighting applied to Texas Medicaid expansion timelines and California Medi-Cal infrastructure commitments.
Caveats apply where FDA software-as-a-medical-device enforcement intensity or ONC certification timeline extensions could materially shift vendor go-to-market economics. Forecasts reflect assumptions regarding health system consolidation velocity and cloud migration willingness among mid-tier hospitals. A model refresh is warranted upon material change in CMS remote patient monitoring reimbursement policy or state-level Medicaid expansion decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Health Solutions
Global Physical Therapy Software Market
Digital Health Solutions
Digital Health Market
Digital Health Solutions
Care Coordination Software Market
Digital Health Solutions
Global Smart Hospital Market
Digital Health Solutions
Women Digital Health Solutions Market
Digital Health Solutions
Global Real World Evidence Solutions Market
Digital Health Solutions
Eclinical Solutions Market
Digital Health Solutions
Artificial Intelligence in Medicine Market
Digital Health Solutions
Medical Animation Market
Digital Health Solutions
Connected Health and Wellness Solutions Market
Digital Health Solutions
Smart Cards in Healthcare Market
Digital Health Solutions
Prescribed Health Apps Market
Digital Health Solutions
Teleradiology Software Market
Digital Health Solutions
Women Health Applications Market
Digital Health Solutions
Connected Healthcare Market
Digital Health Solutions
Global Digital Medicines Market