
 Global Smart Hospital Market | 2026-2036
Global Smart Hospital Market Size, Share, and Industry Trends Forecast 2026-2036
Global Smart Hospital Market Outlook
Silicon photonics is realigning sensor economics in connected patient monitoring hardware, reducing power draw and miniaturizing form factors for bedside-to-home continuity. GE Healthcare leverages its imaging installed base to cross-sell AI analytics suites into radiology workflows. Siemens Healthineers anchors its smart hospital portfolio through robotics-integrated surgical platforms. Medtronic dominates cardiac remote monitoring with FDA-cleared connected devices that feed cloud-based decision support.
A smart hospital integrates IoT sensors, AI analytics, and interoperable software layers to automate clinical workflows, track medical assets, and enable real-time patient monitoring across acute and post-acute settings. These systems typically deploy edge computing nodes with sub-50ms latency for critical care alerts while centralizing longitudinal data in cloud-based electronic health records. Telemedicine and remote monitoring systems lead product type deployment as health systems seek to decarbonize patient travel and extend specialist reach. AI analytics within the technology stack captures disproportionate R&D investment as vendors compete on predictive accuracy for sepsis detection and readmission risk scoring. Robotics applications in surgery and pharmacy fulfillment represent the fastest-growing technology segment by capital commitment from hospital procurement committees.
The FDA's software-as-a-medical-device framework shapes product development timelines for AI diagnostic tools, while the EU AI Act imposes risk-classification requirements on clinical decision support systems marketed in Europe. Japan's PMDA accelerates conditional approval pathways for digital therapeutics, creating divergent regulatory arbitrage opportunities for multinational vendors. Stakeholders must monitor evolving reimbursement parity between in-person and remote encounters across national health insurance schemes to calibrate platform investment returns.
Market Dynamics
Hospital procurement committees now prioritize AI diagnostic platforms that compress clinical decision cycles, with FDA software-as-a-medical-device clearances compressing vendor go-to-market timelines from 36 months to under 18 months.
Growth Catalysts
- Reimbursement parity mandates:Germany's national health insurance now reimburses remote patient monitoring at parity with in-person cardiology consultations, accelerating telemetry hardware deployment.
- Edge computing infrastructure:Sub-50ms latency requirements for sepsis alert systems drive hospital IT budgets toward localized processing nodes rather than pure cloud architectures.
- Japan PMDA conditional approvals:Accelerated pathways for digital therapeutics reduce regulatory friction for AI-powered clinical decision support systems entering the Japanese market.
Market Restraints
- Silicon photonics supply concentration:Foundry capacity for optical sensor fabrication clusters in Taiwan and South Korea, creating single-source vulnerability for connected monitoring hardware.
- EU AI Act risk classification:Clinical decision support systems face mandatory conformity assessments that extend commercialization timelines by 8-14 months for European market entry.
- Lithium-ion battery chemistry:Wearable patient monitors depend on cell supply chains concentrated in China, exposing hardware vendors to input cost volatility and export control friction.
Strategic Opportunities
- Post-acute care extension:India's hospital networks underinvest in home-based monitoring, creating whitespace for telemetry platforms that bridge bedside-to-home continuity.
- Robotics-pharmacy convergence:Automated medication dispensing systems integrating with surgical robotics platforms represent uncaptured value in integrated operating room suites.
- US IRA hospital infrastructure incentives:Tax credits for healthcare facility decarbonization indirectly subsidize IoT sensor networks that reduce patient transport emissions.
Industry Challenges
- Interoperability engineering talent:Health systems lack sufficient HL7 FHIR integration specialists to connect legacy EHR architectures with modern AI analytics layers.
- Cybersecurity certification timelines:FDA premarket submission requirements for connected devices now mandate third-party penetration testing that extends product launch schedules by 4-6 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Smart Hospital Market |
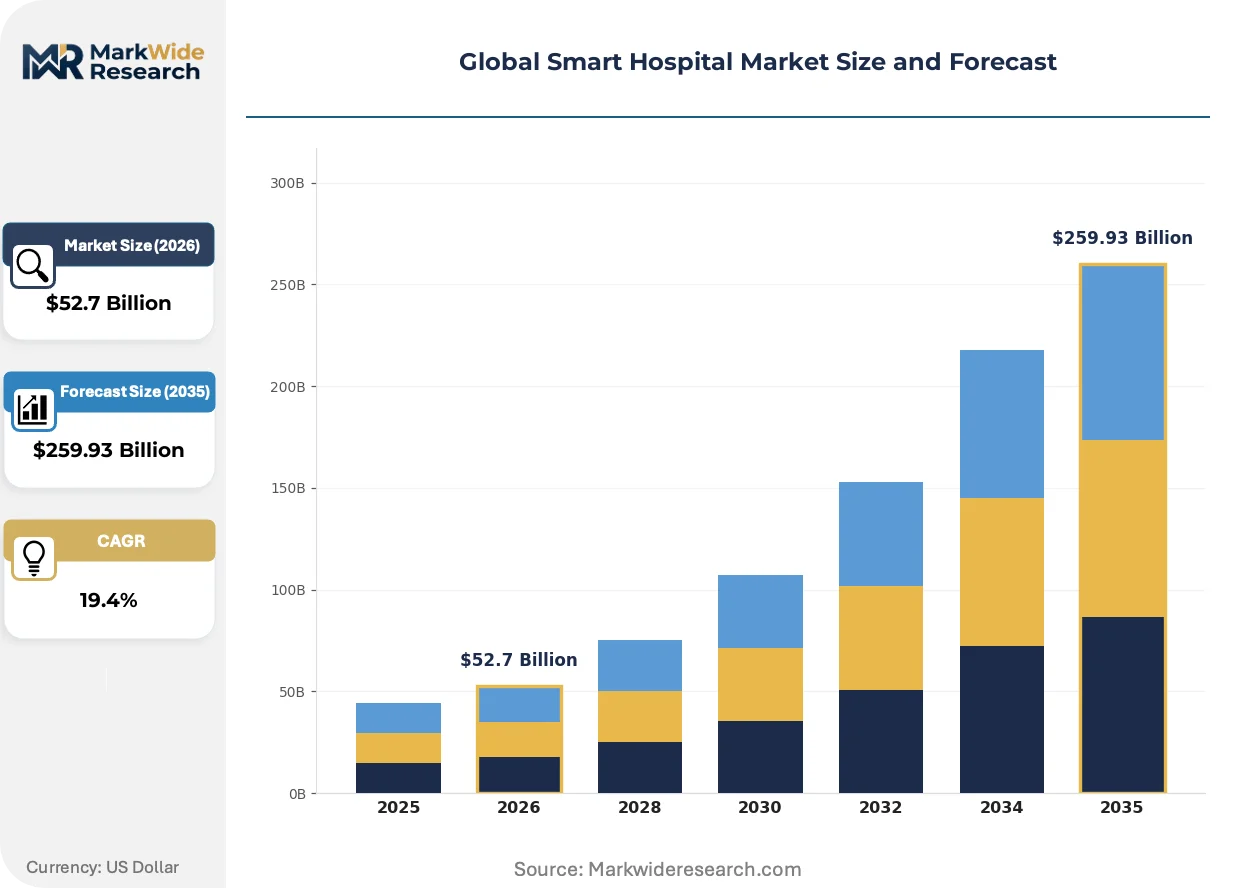
| Market Size in 2026 | $52.7 Billion |
| Market Size in 2035 | $259.93 Billion |
| CAGR (2026 – 2036) | 19.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Telemedicine, Wearable Devices, Electronic Health Records, Remote Monitoring Systems Technology: AI Analytics, IoT Devices, Blockchain Solutions, Robotics End User: Hospitals, Clinics, Rehabilitation Centers, Urgent Care Facilities Application: Patient Management, Asset Tracking, Workflow Optimization, Clinical Decision Support |
| Companies Covered | Koninklijke Philips N.V., GE Healthcare, Medtronic, Siemens Healthineers, Honeywell Life Care Solutions, Stanley Healthcare, Cerner Corporation, McKesson Corporation, IBM Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Smart Hospital Market Strategic Shifts
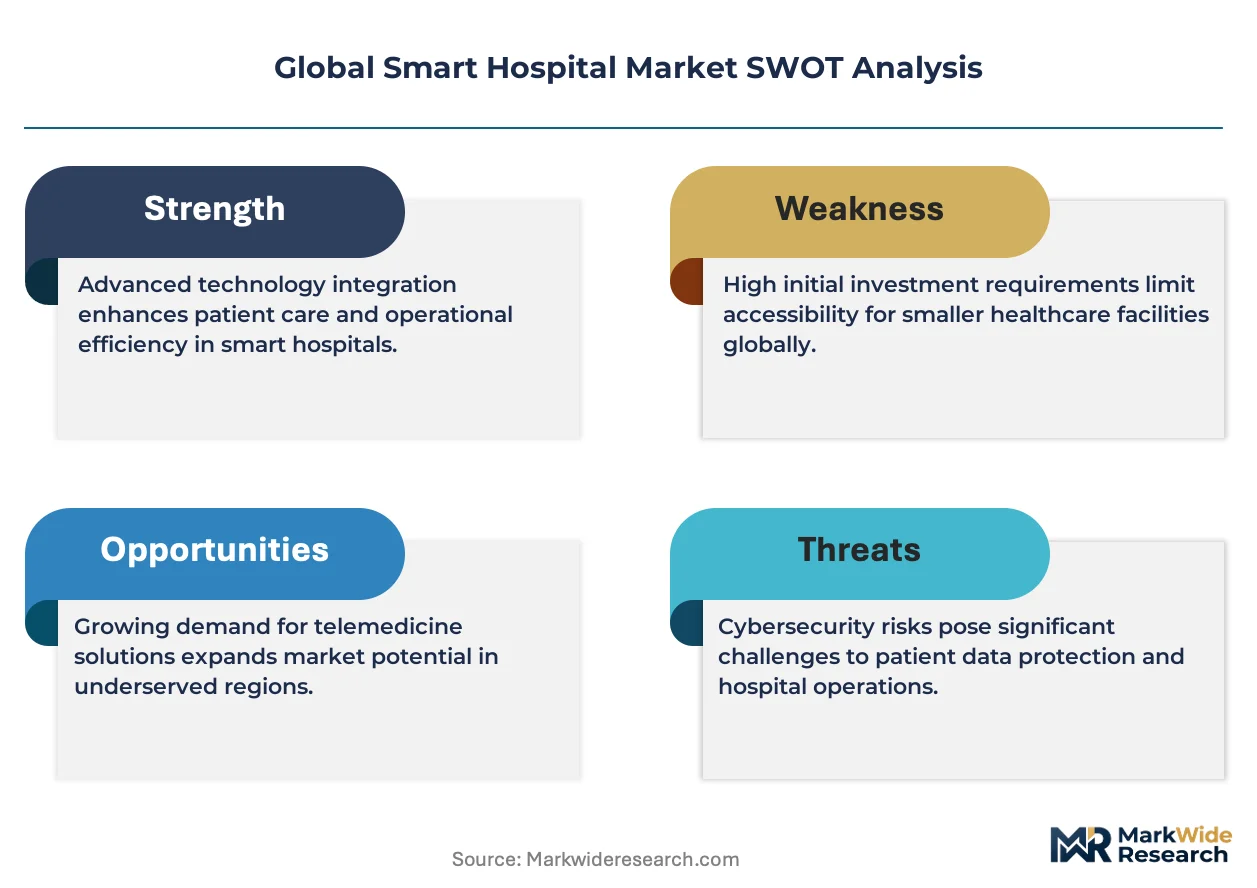
Silicon photonics is absorbing capital allocation across sensor hardware, while regulatory frameworks in the US, EU, and Japan diverge on AI medical device classification, creating compliance complexity for multinational vendors.
Silicon photonics modulators and transceivers now enable optical biosensors that draw under 10 milliwatts during continuous glucose and cardiac monitoring. Acute care hospitals in Germany and Japan are absorbing these components into wearable telemetry patches that maintain bedside-to-home data continuity. The technology is absorbing market share from electrochemical sensor architectures by eliminating battery replacement cycles and enabling sub-millimeter form factors.
The EU AI Act imposes risk-classification tiers on clinical decision support systems, with high-risk applications requiring notified body intervention and post-market surveillance protocols. Vendors targeting European health systems must maintain technical documentation repositories that satisfy both MDR device requirements and AI Act algorithmic transparency mandates. Radiology AI platforms face the steepest compliance burden, as image analysis tools fall under Annex III high-risk categories requiring conformity assessment before CE marking.
Hospital procurement committees now unbundle hardware acquisition from software subscription fees, reversing the bundled capital equipment models that dominated radiology and surgical robotics for two decades. Specialist departments in US academic medical centers negotiate separate contracts for imaging hardware, AI analytics licenses, and implementation services. This disaggregation is most visible in cardiology service lines, where electrophysiology labs source mapping systems from one vendor while subscribing to cloud-based ablation planning tools from competing software specialists.
Global Smart Hospital Market Segmentation
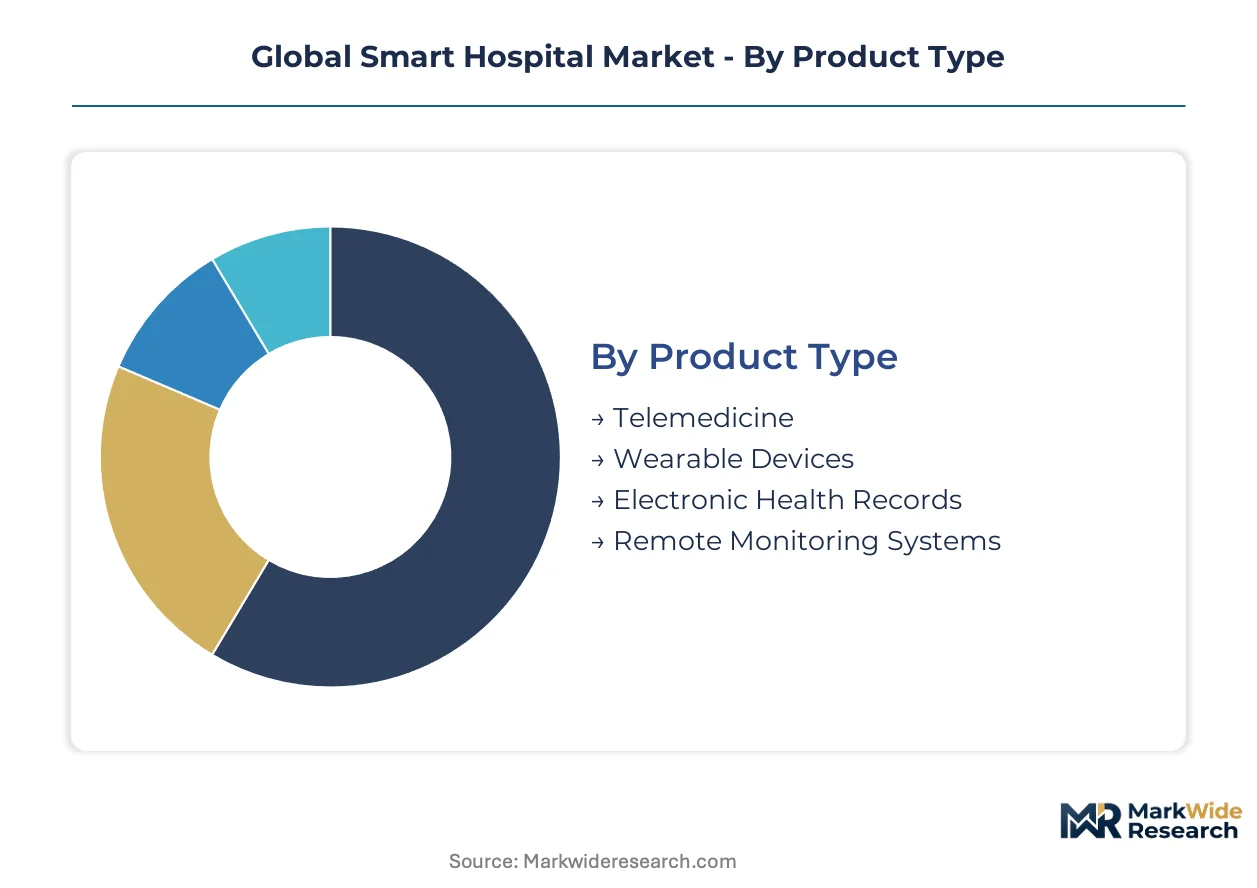
Smart hospital procurement patterns diverge sharply across product architectures and technology maturity curves. Hospital committees allocate capital differently when evaluating connectivity hardware versus algorithmic software layers.
Product Type:
Procurement committees weight capital intensity against recurring revenue models when selecting connected care infrastructure.
- Telemedicine:Video consultation platforms integrate with existing EHR architectures through HL7 FHIR protocols. German hospital networks deploy these systems most aggressively following reimbursement parity mandates for remote cardiology encounters.
- Wearable Devices:Continuous telemetry patches leverage silicon photonics sensors drawing under 10 milliwatts for bedside-to-home glucose and cardiac monitoring. Japanese acute care facilities absorb these components fastest due to PMDA accelerated approval pathways reducing regulatory friction.
- Electronic Health Records:Cloud-native architectures replace on-premise legacy systems in US academic medical centers seeking interoperability with AI analytics layers.
- Remote Monitoring Systems:Telemetry hubs aggregate multi-parameter patient data for centralized nursing station oversight in post-acute settings.
Volume sits with Electronic Health Records; growth tilts toward Wearable Devices.
Technology:
Hospital IT budgets concentrate spending where latency requirements and predictive accuracy determine clinical utility.
- AI Analytics:Sepsis detection algorithms and readmission risk scoring models process edge-computed data streams with sub-50ms alert latency. FDA software-as-a-medical-device clearances compress vendor commercialization timelines from 36 months to under 18 months for US market entry.
- Robotics:Surgical platforms and pharmacy automation systems capture the steepest capital commitment growth trajectory from hospital procurement committees prioritizing labor substitution and precision outcomes.
- IoT Devices:Asset tracking tags and environmental sensors feed real-time location systems for medical equipment inventory management.
- Blockchain Solutions:Distributed ledger architectures secure patient consent management and pharmaceutical supply chain provenance tracking.
Capital deployment favors AI Analytics; Robotics claims the fastest-expanding budget share.
End User:
Facility scale and care acuity determine technology stack complexity and integration requirements.
- Hospitals:Multi-specialty acute care institutions deploy full-stack IoT sensor networks, edge computing nodes, and interoperable AI analytics across radiology, cardiology, and surgical service lines. US health systems lead procurement volume following IRA infrastructure incentives for facility decarbonization.
- Clinics:Outpatient settings prioritize lightweight telemedicine and remote patient monitoring to extend specialist reach without physical expansion.
- Rehabilitation Centers:Post-acute facilities leverage wearable telemetry for continuous functional recovery assessment during patient discharge transitions.
- Urgent Care Facilities:Rapid-throughput centers deploy streamlined diagnostic AI and asset tracking for high-volume episodic care.
Revenue concentrates in Hospitals; expansion tilts toward Rehabilitation Centers bridging acute-to-home continuity.
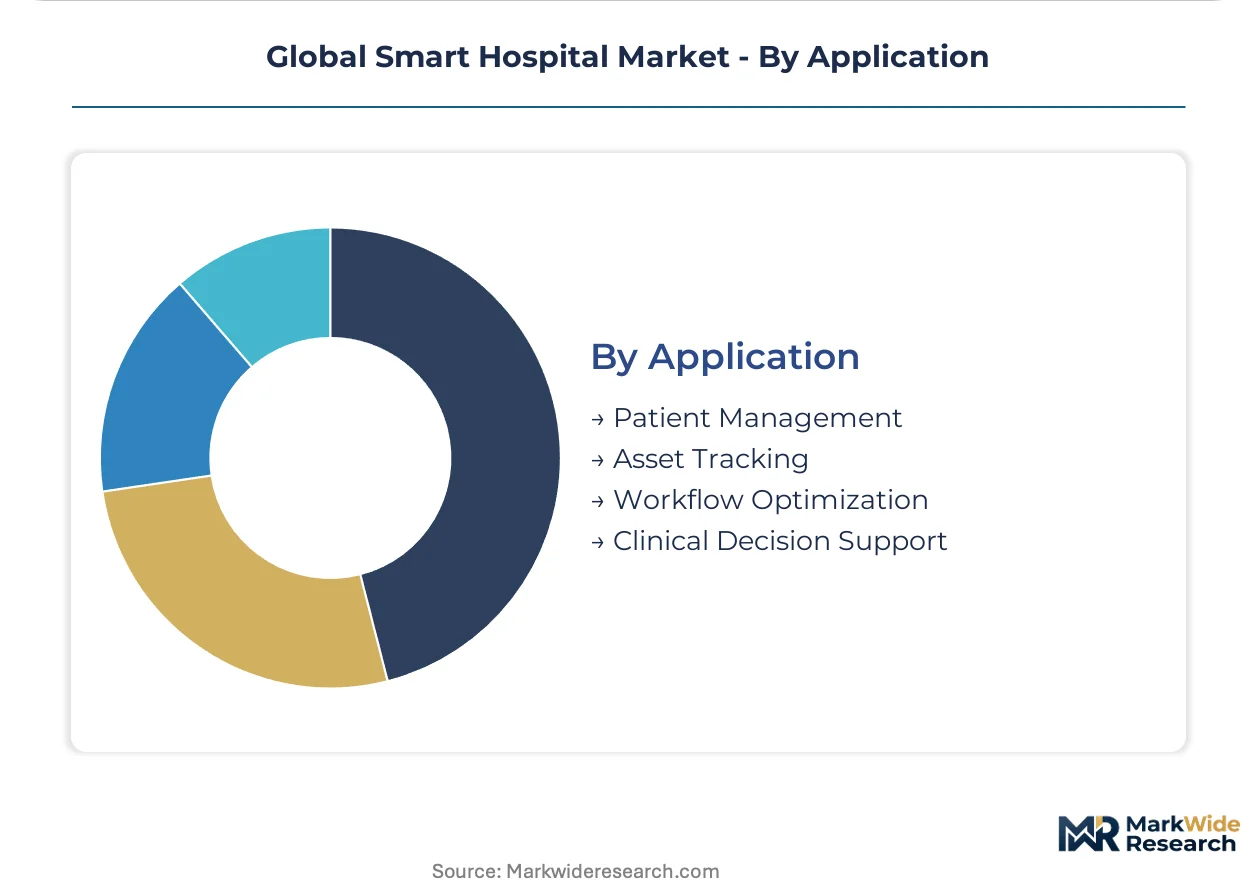
Application:
Workflow automation priorities separate early-stage connectivity investments from advanced predictive system deployments.
- Clinical Decision Support:AI-powered diagnostic assistance and treatment recommendation engines face the steepest EU AI Act compliance burden, with high-risk radiology applications requiring notified body conformity assessment extending European commercialization timelines 8-14 months.
- Workflow Optimization:Automated scheduling, staffing allocation, and operating room turnover systems reduce administrative overhead in capacity-constrained US and German health systems.
- Patient Management:Admission-to-discharge tracking platforms coordinate multidisciplinary care teams across acute and post-acute settings.
- Asset Tracking:Real-time location systems for infusion pumps, ventilators, and mobile imaging equipment reduce capital expenditure through utilization optimization.
Deployment volume favors Patient Management; regulatory headwinds slow Clinical Decision Support expansion in European markets.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hospital procurement concentrates in the United States, Germany, and Japan where reimbursement codes now cover remote patient monitoring. These three markets absorb the majority of AI-powered clinical platform deployments. Regulatory divergence across FDA, EU AI Act, and PMDA frameworks shapes vendor commercialization strategies.
United States
Academic medical centers drive cloud-native EHR replacement cycles and edge computing infrastructure for sepsis alert systems. The FDA's software-as-a-medical-device framework compresses AI diagnostic clearances from 36 months to under 18 months. The Greater Boston cluster anchors health IT R&D concentration with proximity to NIH funding pipelines.
Germany
Hospital networks accelerate telemetry hardware deployment following national health insurance reimbursement parity for remote cardiology consultations. The EU AI Act imposes high-risk classification on clinical decision support systems requiring notified body conformity assessment. Baden-Württemberg's medical device manufacturing belt concentrates surgical robotics production capacity.
Japan
Acute care facilities absorb silicon photonics-enabled wearable telemetry fastest due to PMDA conditional approval pathways for digital therapeutics. METI funding programs subsidize IoT sensor network deployment in tertiary hospitals. The Kanto region around Tokyo hosts the densest concentration of connected device pilot programs bridging bedside-to-home continuity.
India
Hospital networks underinvest in home-based monitoring, creating whitespace for telemetry platforms extending post-acute care. The country's national pharmaceutical regulator maintains abbreviated approval pathways for software-as-a-medical-device imports. Maharashtra's Mumbai-Pune corridor concentrates health IT implementation services for multinational vendor partnerships.
South Korea
Electronics conglomerates pivot semiconductor fabrication capacity toward medical sensor foundry services. MFDS streamlined review processes for AI diagnostic algorithms accelerate product registration timelines. Seoul Capital Area hospitals lead deployment of robotics-integrated surgical platforms across multi-specialty service lines.
Global Smart Hospital Market Competitive Environment
Branded specialists and contract manufacturers split share differently across segments, with imaging incumbents leveraging installed bases to cross-sell AI analytics while pure-play software vendors compete on algorithmic accuracy. The vendor landscape organizes around three archetypes: diversified health technology conglomerates with imaging heritage, connected device specialists with cardiac telemetry dominance, and cloud-native health IT platforms with interoperability middleware. M&A activity concentrates on AI analytics tuck-ins and robotics capability acquisition. Geographic expansion into underpenetrated post-acute markets represents the second dominant competitive move.
Within the diversified health technology tier, Koninklijke Philips N.V. and GE Healthcare exemplify archetypes leveraging imaging installed bases for AI analytics cross-selling. Siemens Healthineers occupies a position representing robotics-integrated surgical platform concentration. Medtronic anchors the connected device specialist archetype with cardiac remote monitoring cloud infrastructure. These three entities collectively represent the scale-driven end of vendor segmentation, though no single company commands dominant share across the full technology stack.
| Leading Market Players |
|---|
| Koninklijke Philips N.V. |
| GE Healthcare |
| Medtronic |
| Siemens Healthineers |
| Honeywell Life Care Solutions |
| Stanley Healthcare |
| Cerner Corporation |
| McKesson Corporation |
| IBM Corporation |
| Others |
Value Chain & Pricing Dynamics
Silicon photonics foundry costs cascade through three pricing tiers for connected patient monitoring hardware, with optical sensor wafers fabricated in Taiwan and South Korea commanding premium positioning against electrochemical alternatives while battery chemistry volatility in China's cell supply chains compresses margins at the economy tier.
Pricing Analysis
Volume concentrates in subscription-based AI analytics licensing while margin capture tilts toward surgical robotics capital equipment. Three-tier pricing structure across premium, standard, and economy levels separates FDA-cleared algorithm suites from CE-marked clinical decision support and uncertified workflow tools. Pricing pressure stems from hospital procurement committees unbundling hardware from software fees. Academic medical centers exhibit lowest price sensitivity; post-acute rehabilitation networks face acute budget constraints.
Supply Chain Analysis
Freight cost inflation for lithium-ion cells shipped from Chinese manufacturing hubs is reshaping total landed cost calculations for wearable telemetry vendors. Foundry capacity for silicon photonics sensors clusters in Taiwan and South Korea; battery cell production centers on China. Optical modulators, electrochemical substrates, and edge computing processors constitute critical component inputs. Single-source vulnerability in Taiwan semiconductor fabrication exposes hardware vendors to geopolitical disruption. Distribution runs through hospital procurement committees and group purchasing organizations with multi-year framework agreements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The smart hospital sector sits in a technology-transition phase as silicon photonics displaces electrochemical sensing architectures across patient monitoring hardware, creating asymmetric opportunity for vendors with optical foundry relationships.
For Market Incumbents: Acquire AI analytics specialist firms with FDA software-as-a-medical-device clearances to defend against cloud-native health IT platforms eroding imaging hardware attach rates. Deepen backward integration into silicon photonics foundry partnerships in Taiwan and South Korea to secure sensor supply against tariff exposure. Prioritize HL7 FHIR interoperability certification investments to maintain EHR integration leverage. For New Entrants and Emerging Players: Capture India's post-acute care whitespace where hospital networks underinvest in home-based telemetry bridging bedside-to-home continuity. Target Maharashtra's Mumbai-Pune corridor for health IT implementation partnerships with multinational vendors lacking local deployment capacity. Lead with robotics-pharmacy convergence solutions for integrated operating room suites where procurement committees seek uncaptured value. For Investors and Strategic Acquirers: FDA software-as-a-medical-device clearance velocity exceeding 18-month median timelines is the leading indicator that AI diagnostic platforms are achieving scalable commercial traction. Position acquisition screening around cardiac remote monitoring cloud infrastructure and surgical robotics platform specialists with PMDA conditional approvals in Japan. Watch EU AI Act notified body conformity assessment bottlenecks as the signal for European market entry friction.| Strategic Initiative | Industry Significance |
|---|---|
| FDA Software-as-a-Medical-Device Submission | Accelerated clearance pathways compress commercialization timelines for AI diagnostic tools entering US hospital procurement cycles. |
| CE Marking Pathway Under EU AI Act | Notified body conformity assessments for high-risk radiology applications extend European market entry by 8-14 months. |
| Hospital System Partnership | Academic medical center alliances in the Greater Boston cluster anchor health IT R&D concentration with NIH funding proximity. |
| Software Companion Development | Cloud-native analytics layers cross-sell into GE Healthcare and Siemens Healthineers imaging installed bases. |
| Reimbursement Strategy | Germany's national health insurance parity for remote cardiology consultations accelerates telemetry hardware deployment. |
Study Parameters
Document review covered FDA 510(k) and De Novo clearance databases, EU MDR technical documentation repositories, and Japanese PMDA approval registries, complemented by interviews with hospital procurement committee chairs, biomedical engineering directors, GPO contracts managers, and health system CIOs. Secondary validation drew from CMS Medicare reimbursement data, hospital capital expenditure surveys, and semiconductor foundry capacity disclosures. Bottom-up unit economics for connected device deployments were triangulated against top-down health IT budget allocation models.
Cross-referencing historical FDA clearance velocity against panel input from regulatory affairs specialists shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include product architecture, technology maturity curve, care acuity tier, and regional regulatory cluster. CAGRs were derived from iterative convergence between supply-side capacity expansion plans and demand-side procurement pipeline visibility. Forecast inputs incorporated PMDA conditional approval pathway utilization rates and EU AI Act risk-classification implementation timelines.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to foundry capacity constraints in Taiwan, lithium-ion export control friction with China, and reimbursement parity expansion across national health insurance schemes. Outputs reflect documented assumptions around regulatory clearance velocity and hospital capital budget cyclicality. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Health Solutions
AI-Powered Clinical Decision Support Market
Digital Health Solutions
Middle East and Africa Heart Failure Software Market
Digital Health Solutions
Occupational Therapy Software Market
Digital Health Solutions
Global Preventive Healthcare Technologies and Services Market
Digital Health Solutions
Patient Engagement Technology Market
Digital Health Solutions
AI in Patient Engagement Market
Digital Health Solutions
Long Term Care Software Market
Digital Health Solutions
Global Patient Centric Healthcare App Market
Digital Health Solutions
Global Plastic Surgery Software Market
Digital Health Solutions
VR in Healthcare Market
Digital Health Solutions
Global Mhealth Solutions Market
Digital Health Solutions
Teleradiology Software Market
Digital Health Solutions
Healthcare Mobile Application Market
Digital Health Solutions
Europe Digital Health Market
Digital Health Solutions
Prescribed Health Apps Market
Digital Health Solutions
Digital Health Tracking Apps Market