
 Emergency Hospital Beds Market | 2026-2036
Emergency Hospital Beds Market Size, Share, and Industry Trends Forecast 2026-2036
Emergency Hospital Beds Market Insights
Hospital procurement channels is reconfiguring as group purchasing organizations consolidate supplier contracts across multi-hospital networks. Stryker Corporation leverages its direct sales force to anchor large-scale contracts with integrated delivery networks. LINET Group competes through specialized ICU-compatible emergency bed platforms designed for rapid deployment. Getinge AB sustains manufacturing scale advantages in Europe while extending service networks into Asia-Pacific markets.
Emergency hospital beds are height-adjustable medical platforms engineered for rapid patient stabilization, typically supporting loads exceeding 500 pounds with hydraulic or electric lift mechanisms and integrated side-rail systems. These beds serve critical care workflows where seconds determine outcomes, requiring seamless compatibility with cardiac monitors, ventilators, and infusion pumps. Electric beds command the widest installed base among product types due to nursing efficiency mandates, while stretchers retain the fastest replacement cycles driven by ambulance fleet turnover. Smart beds with weight monitoring and anti-collision sensors capture expanding margin pools as hospitals prioritize fall-prevention protocols and real-time patient data integration.
The FDA enforces 510(k) clearance and cybersecurity benchmarks for connected bed systems, compelling manufacturers to embed encrypted data transmission modules. EPA guidelines on antimicrobial surface coatings shape material selection for bed frames and mattresses in US facilities. India's CDSCO and BIS certification requirements for medical electronics create compliance thresholds that filter import competition. Stakeholders must monitor how evolving cybersecurity mandates and regional certification divergence affect product development roadmaps and market access timelines.
Market Dynamics
Hospital cybersecurity mandates are forcing immediate hardware refresh cycles across installed bed fleets, compressing replacement timelines from decade-long cycles to five-year rotations as FDA 510(k) clearance now requires encrypted data transmission modules.
Growth Catalysts
- India's Ayushman Bharat health infrastructure schemes:Government procurement of electric and smart-enabled beds accelerates through centralized tenders targeting district hospital upgrades.
- FDA cybersecurity guidance updates:Connected bed systems must embed hardware-level encryption, compelling US facilities to replace legacy hydraulic platforms.
- Fall-prevention protocol mandates:Weight monitoring and anti-collision sensor integration drives premium bed adoption in emergency departments handling high-acuity trauma.
Market Restraints
- Steel and aluminum input cost volatility:Frame manufacturing faces margin compression from commodity price swings in medical-grade alloys.
- Integrated delivery network procurement consolidation:Multi-hospital systems squeeze supplier pricing through group purchasing organization volume aggregation.
- Stretcher substitution in ambulatory settings:Lightweight transport platforms displace full-featured beds in fast-turnover outpatient emergency zones.
Strategic Opportunities
- Smart bed convergence with EMR systems:Real-time patient data streaming into Epic and Cerner workflows creates new software-enabled revenue streams.
- Rural India bed penetration gaps:Tier-2 and Tier-3 district hospitals operate below recommended bed-to-population ratios, opening greenfield deployment zones.
- EPA antimicrobial coating standards:US facilities must replace non-compliant surface materials, creating aftermarket retrofit and replacement demand.
Industry Challenges
- Biomedical technician certification bottlenecks:Electric and smart bed maintenance requires specialized training that outpaces workforce pipeline output.
- Legacy hydraulic fleet integration friction:New connected beds must interface with non-digital nurse call systems and analog power infrastructure.
- CDSCO-BIS dual certification timelines:Import manufacturers face extended approval windows for medical electronics in Indian market entry.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Emergency Hospital Beds Market |
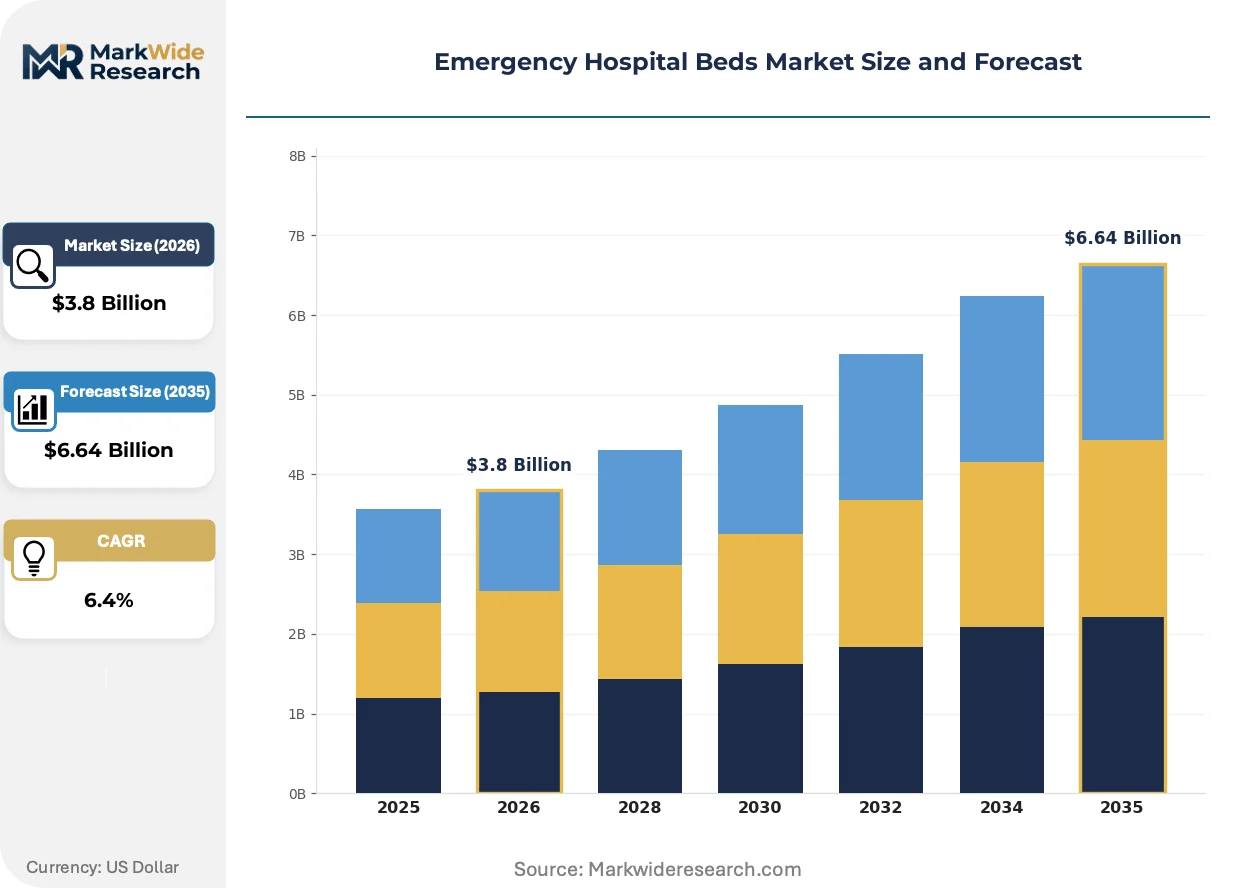
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.64 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Manual Beds, Electric Beds, Bariatric Beds, Stretchers End User: Public Hospitals, Private Hospitals, Emergency Clinics, Ambulance Services Installation: Stationary Beds, Portable Beds, Convertible Beds, Modular Beds Technological Features: Smart Beds, Anti-Collision Sensors, Weight Monitoring, Adjustable Heights |
| Companies Covered | Baxter International (Hill-Rom), Stryker Corporation, Arjo, Invacare Corporation, LINET Group, Getinge AB, Paramount Bed Co. Ltd., Stiegelmeyer, Medline Industries, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Emergency Hospital Beds Market Trends and Innovations
Bed technology is pivoting from passive furniture to active patient monitoring nodes, with sensor integration and cybersecurity hardening commanding R&D priority over mechanical refinement.
Smart bed platforms with continuous weight sensing and automated position logging are rendering obsolete manual patient turning schedules and paper-based pressure ulcer documentation. Emergency departments in academic medical centers deploy these systems to satisfy Joint Commission fall-prevention metrics. The shift compresses liability exposure while demanding IT infrastructure upgrades that strain capital budgets.
REACH restrictions on persistent organic pollutants and RoHS substance limits are tightening material specifications for mattress foams and frame coatings across European procurement. Manufacturers reformulate polyurethane formulations and migrate to halogen-free flame retardants. German hospital networks now require full material disclosure documentation as a contract prerequisite, filtering supplier pools.
After-sales service unbundling is disrupting traditional equipment leasing models as IDNs negotiate separate contracts for maintenance, software updates, and cybersecurity patches. Third-party clinical engineering firms capture service revenue previously retained by manufacturers. This pattern concentrates in US markets where health system consolidation has centralized procurement decision-making.
Emergency Hospital Beds Market Segmentation
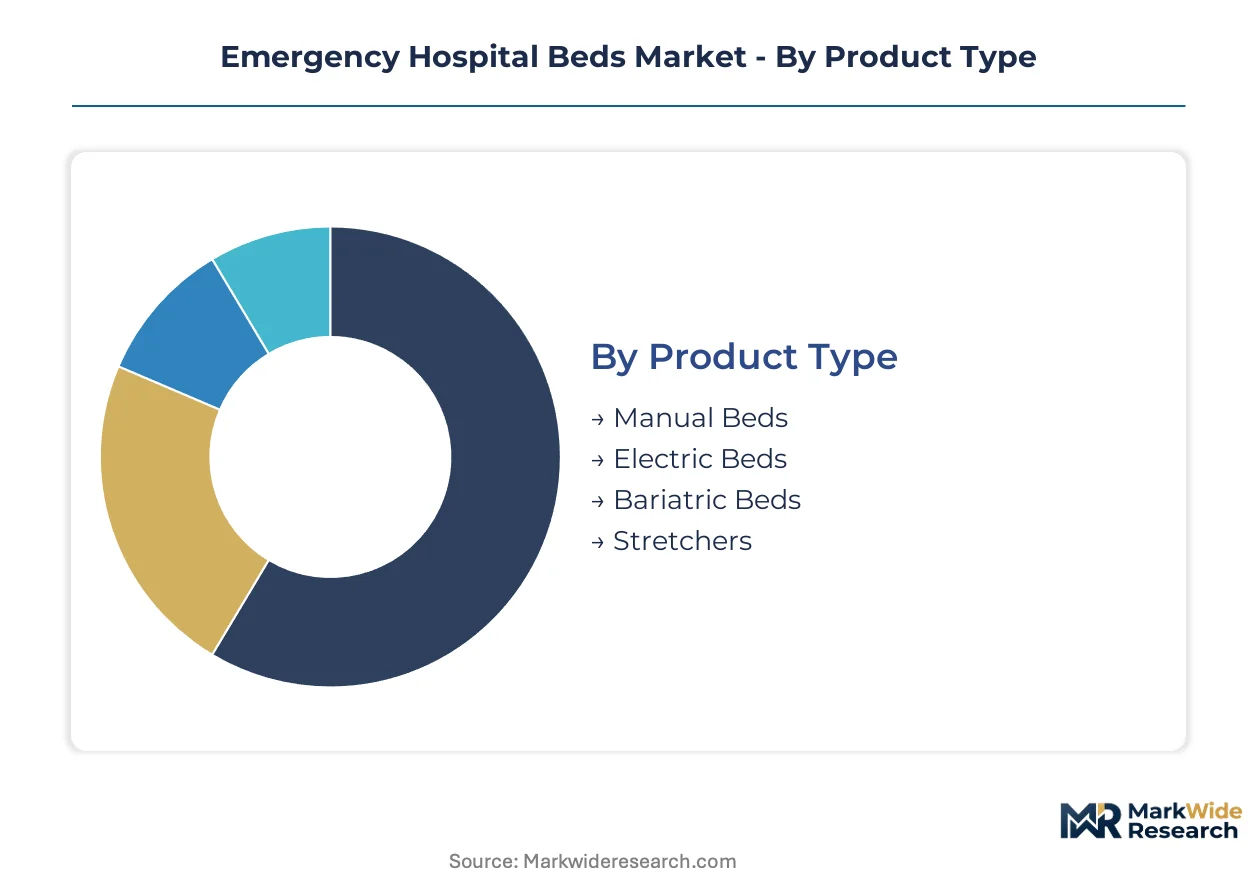
Emergency hospital bed procurement diverges sharply across care settings, with replacement cycles ranging from three-year ambulance stretcher rotations to decade-long stationary installations. Understanding these temporal patterns reveals where capital concentrates and where margin pools shift fastest.
Product Type:
Stretcher fleets turn over fastest due to ambulance wear-and-tear, while stationary platforms in emergency departments endure longest—creating divergent supplier strategies around service contracts versus new unit sales.
- Electric Beds:Motorized lift mechanisms with battery backup systems support loads exceeding 500 pounds for rapid patient positioning. Demand concentrates in US academic medical centers where nursing efficiency mandates and FDA cybersecurity guidance compel hardware upgrades. These units command the widest installed base among all product types due to Joint Commission fall-prevention protocols.
- Stretchers:Lightweight aluminum-framed transport platforms with hydraulic height adjustment and collapsible side rails. Replacement concentrates in ambulance services across India where government fleet expansion under Ayushman Bharat accelerates procurement cycles. These units experience the fastest turnover as road vibration degrades mechanical components.
- Manual Beds:Hand-crank hydraulic systems for budget-constrained facilities with minimal IT infrastructure requirements. Rural district hospitals in emerging markets.
- Bariatric Beds:Reinforced frame construction supporting patient weights above 700 pounds with expanded mattress surface area. Obesity treatment centers and tertiary emergency departments.
Electric beds dominate installed base. Stretchers are where expansion concentrates.
End User:
Procurement authority varies dramatically—public systems run centralized tenders while private networks negotiate direct with manufacturers, creating price tier dispersion that exceeds 40% for identical specifications.
- Public Hospitals:Government-funded emergency departments with capital budgets tied to health ministry allocations. India's district hospital upgrade schemes concentrate demand here, with CDSCO certification requirements filtering import competition. These facilities prioritize electric and smart-enabled beds for trauma center accreditation.
- Private Hospitals:Investor-owned acute care networks with integrated delivery organization purchasing power. US-based systems leverage group purchasing organization volume to squeeze supplier pricing on premium bed platforms with EMR integration capabilities.
- Emergency Clinics:Freestanding urgent care facilities with lower acuity caseloads and compressed capital cycles. Cost-optimized manual and semi-electric configurations.
- Ambulance Services:Municipal and private transport fleets requiring lightweight, corrosion-resistant stretchers with rapid patient loading mechanisms. Fastest replacement cycles driven by vehicle mileage accumulation.
Public hospitals anchor volume procurement. Private networks capture technology leadership.
Installation:
Physical mounting requirements determine facility infrastructure investment, with ceiling-mounted lifts and power integration creating divergent total cost of ownership calculations across greenfield and retrofit projects.
- Stationary Beds:Permanently anchored platforms with hardwired electrical connections and fixed nurse call system integration. Emergency department core capacity in tertiary hospitals where patient throughput exceeds 50,000 annual visits.
- Portable Beds:Battery-powered units with wireless data transmission and quick-release wheel locks. Surge capacity deployment and temporary overflow wards during mass casualty events.
- Convertible Beds:Dual-mode platforms transitioning between chair and flat configurations for emergency department observation units. Space-constrained urban hospitals.
- Modular Beds:Component-based systems with interchangeable head/foot boards and accessory rails for specialty procedure adaptation. Academic medical centers with diverse service line requirements.
Stationary beds represent the largest capital commitment. Portable configurations are gaining share fastest.
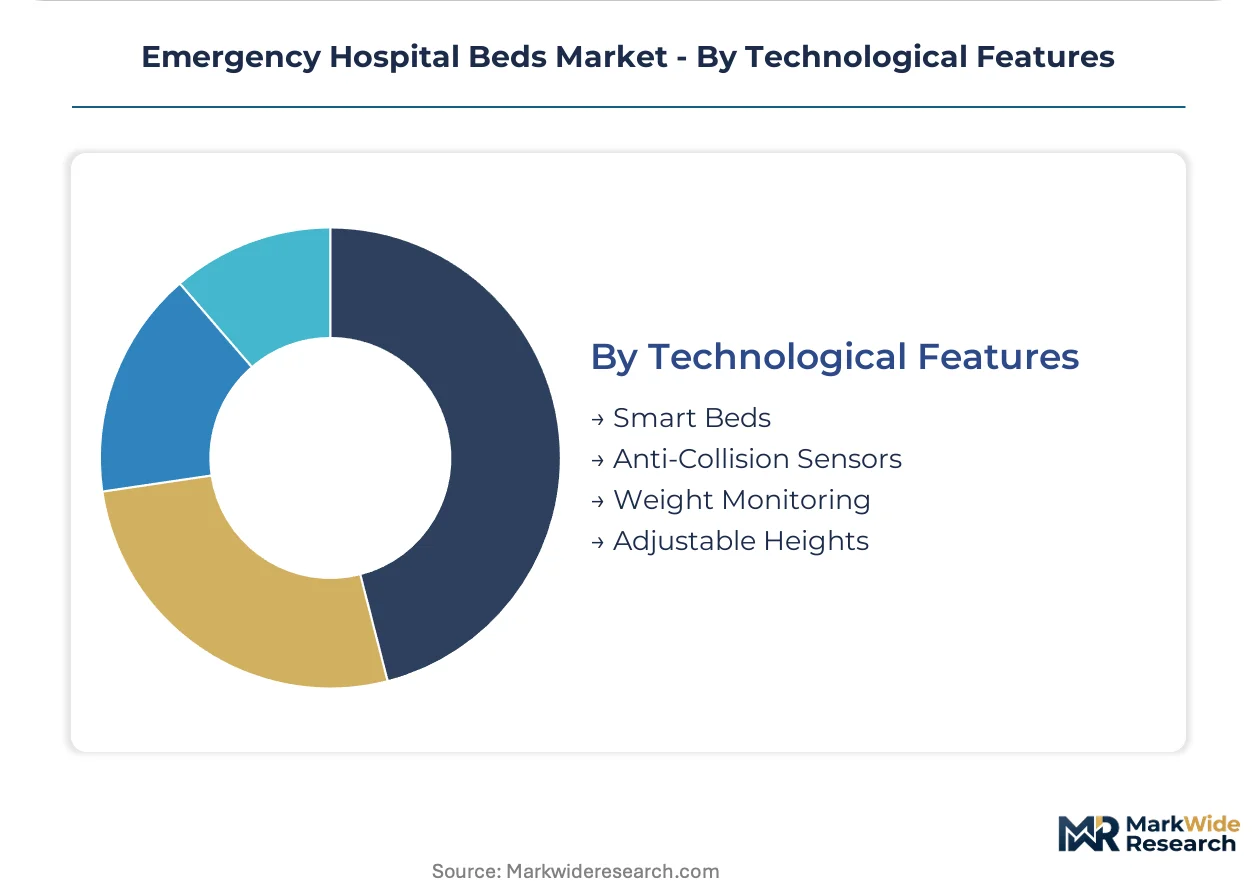
Technological Features:
Software-enabled functionality now commands premium pricing multiples of 2-3x over mechanical equivalents, with cybersecurity hardening and EMR connectivity becoming non-negotiable in US procurement specifications.
- Smart Beds:Continuous patient monitoring with automated position logging, pressure ulcer risk algorithms, and real-time weight sensing. Academic medical centers in the US deploy these to satisfy Joint Commission metrics while generating liability reduction.
- Weight Monitoring:Load cell integration enabling automated fluid balance tracking and medication dosing verification. Critical care emergency bays with sepsis and trauma protocols.
- Anti-Collision Sensors:Proximity detection systems preventing bed-to-equipment and bed-to-wall contact during rapid transport. High-density emergency department layouts.
- Adjustable Heights:Motorized vertical positioning for fall prevention and ergonomic nursing access. Standard configuration across all electric bed platforms.
Adjustable heights represent baseline functionality. Smart beds concentrate margin expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Rotterdam's medical equipment distribution hub underwrites Europe's central stocking role for emergency bed fleets serving hospitals from Lisbon to Warsaw.
United States
FDA cybersecurity guidance and Joint Commission fall-prevention mandates drive hardware refresh cycles in academic medical centers. The 510(k) clearance process now requires encrypted data transmission modules in connected bed systems. Boston's Longwood Medical Area anchors procurement concentration for tertiary emergency departments.
Germany
REACH restrictions on persistent organic pollutants and RoHS substance limits reshape material specifications for mattress foams and frame coatings. The country's national pharmaceutical regulator enforces MDR compliance timelines for connected medical devices. The Rhine-Ruhr industrial corridor concentrates manufacturing scale for ICU-compatible platforms.
India
Ayushman Bharat health infrastructure schemes accelerate government procurement of electric and smart-enabled beds through centralized tenders. CDSCO and BIS dual certification requirements filter import competition for medical electronics. Maharashtra's Mumbai-Pune corridor hosts the densest cluster of district hospital upgrade projects.
Japan
PMDA approval pathways and JIS standards compliance shape product development for aging-population care settings. METI industrial policy supports domestic manufacturing of sensor-integrated bed platforms. The Kansai region around Osaka maintains specialized production capacity for compact emergency department configurations.
United Kingdom
NHS procurement frameworks consolidate supplier contracts across integrated care systems, compressing pricing on premium bed platforms. The Medicines and Healthcare products Regulatory Agency enforces cybersecurity benchmarks for connected devices. London's Imperial College Health Partners cluster drives early adoption of EMR-integrated smart beds.
Emergency Hospital Beds Market Competitive Landscape
On the supply side, the industry is consolidating around multi-product medical device conglomerates with captive distribution networks and specialized regional champions with deep service infrastructure. Three strategic archetypes dominate: full-line hospital equipment suppliers with direct sales forces, regional specialists with regulatory navigation expertise, and component-focused fabricators with cost-optimized manufacturing. M&A activity concentrates on cybersecurity capability acquisition and geographic footprint extension into India's district hospital tier.
Among North American-based conglomerates, Baxter International (Hill-Rom) and Stryker Corporation exemplify the full-line supplier archetype with integrated delivery network anchoring positions. LINET Group represents the European specialist model with ICU-compatible platform concentration. These three occupy positions across the premium-tier vector where smart-bed functionality and regulatory compliance create defendable margin pools.
| Leading Market Players |
|---|
| Baxter International (Hill-Rom) |
| Stryker Corporation |
| Arjo |
| Invacare Corporation |
| LINET Group |
| Getinge AB |
| Paramount Bed Co. Ltd. |
| Stiegelmeyer |
| Medline Industries |
| Others |
Pricing and Supply Chain Analysis
German steel and aluminum fabrication clusters anchor frame manufacturing, concentrating margin capture in downstream bed assembly and smart-system integration tiers where FDA cybersecurity mandates justify premium positioning.
Pricing Analysis
Volume-discount tiering structures separate integrated delivery network contracts from single-facility procurement, with GPO-aggregated pricing running 25-40% below direct hospital negotiations. Price differentiation hinges on FDA 510(k) certification tier and EMR integration depth, with cybersecurity-hardened platforms commanding substantial premiums over legacy hydraulic equivalents. Cost compression in manual and semi-electric tiers intensifies as Indian government tenders prioritize lowest-compliant-bid award criteria. Ambulance services exhibit highest price sensitivity due to fleet-scale replacement cycles, while academic medical centers prioritize liability reduction over unit cost.
Supply Chain Analysis
Tariff exposure between China and the United States dominates supply chain risk calculations for electronic control modules and sensor arrays. Component sourcing draws from Germany for precision hydraulic systems, China for motor drives and circuit boards, and India for aluminum extrusions and mattress textiles. Single-source vulnerability concentrates in encrypted data transmission chipsets where qualified supplier pools remain narrow. Distribution runs through manufacturer-direct sales forces for IDN accounts and specialized medical equipment distributors for independent facilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Emergency hospital beds are transitioning from capital equipment to software-enabled patient monitoring platforms, with Epic and Cerner interoperability emerging as the decisive ecosystem battleground.
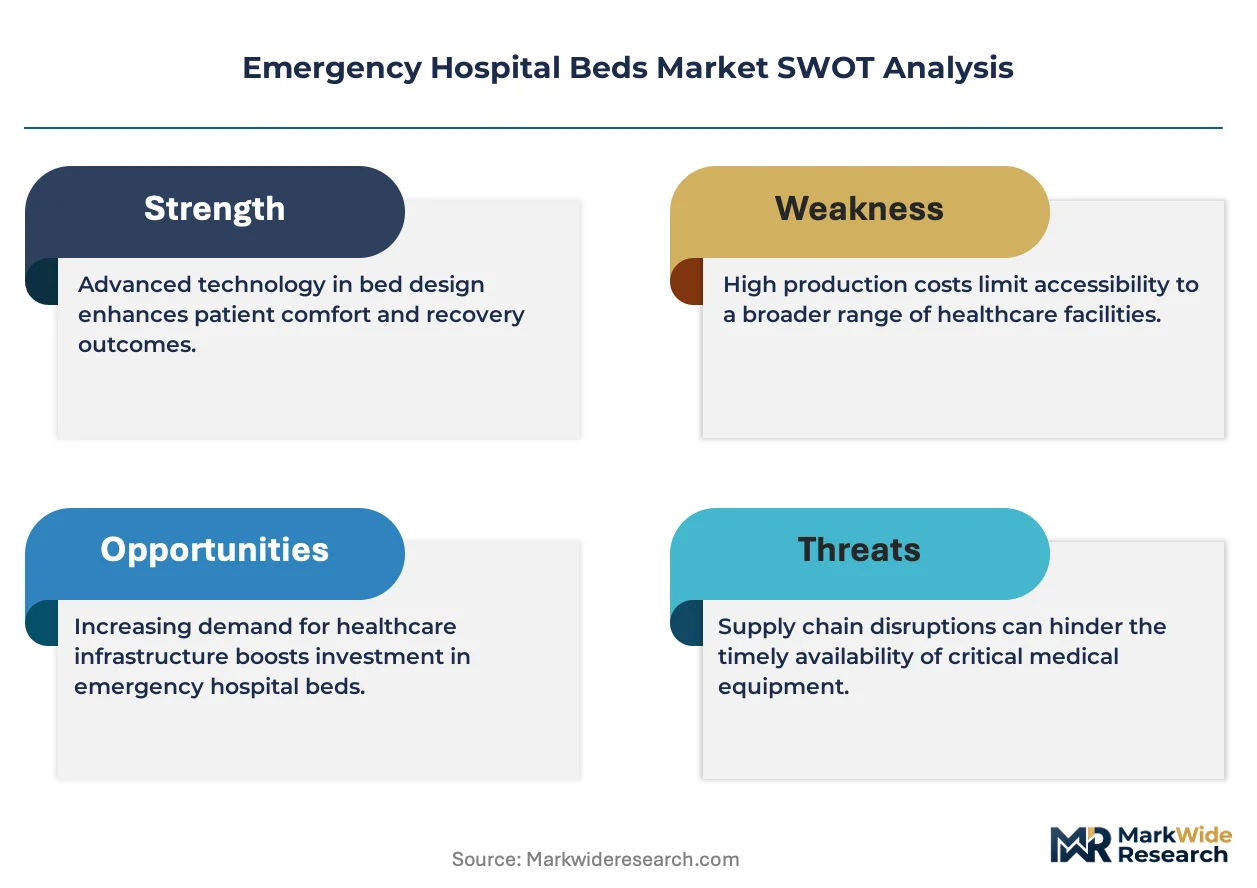
For Market Incumbents: Harden cybersecurity certification pipelines to maintain 510(k) clearance velocity as FDA guidance tightens hardware encryption requirements. Anchor integrated delivery network contracts through captive clinical engineering service infrastructure that third-party competitors cannot replicate. Defensive consolidation should prioritize smart-sensor technology acquisitions over mechanical manufacturing capacity. For New Entrants and Emerging Players: Rural India's district hospital tier offers the most penetrable white-space opportunity, with bed-to-population ratios running below WHO thresholds in Maharashtra and Uttar Pradesh. CDSCO-BIS dual certification expertise becomes the critical go-to-market enabler, with local partnership structures accelerating approval timelines that disqualify direct import competitors. Portable bed configurations for surge capacity deployment represent the fastest-adoption segment for unestablished brands. For Investors and Strategic Acquirers: Capital is best deployed toward mid-cap specialists with proven cybersecurity module integration and existing FDA 510(k) portfolios. Long-term viability favors platforms with recurring software revenue streams over pure hardware manufacturers. Monitor Joint Commission fall-prevention protocol updates as the signal for accelerated smart-bed replacement cycles.| Strategic Initiative | Industry Significance |
|---|---|
| FDA Cybersecurity Compliance Pathway | 510(k) clearance with encrypted data modules opens US academic medical center procurement channels. |
| Hospital System Partnership | Integrated delivery network anchoring contracts secure decade-long replacement cycle visibility. |
| Software Companion Development | Epic and Cerner integration creates recurring revenue streams beyond hardware margins. |
| CE Marking Pathway | MDR compliance unlocks German hospital network procurement requiring REACH-certified materials. |
| Backward Integration into Sensor Arrays | In-house production of weight monitoring and anti-collision systems protects margin from component volatility. |
Research Methodology
Operator-level perspectives from hospital purchasing committee directors, biomedical engineering managers, GPO contracts specialists, and ambulance fleet procurement officers anchored the qualitative base. Secondary validation drew from FDA 510(k) clearance databases, hospital procurement tender records, CDSCO medical device registration filings, and GPO contract disclosure documents. Bottom-up unit economics triangulated against top-down health infrastructure spending allocations across modeled geographies.
Scenario-bracketing framed volume and value outputs across the projection horizon, with segmentation dimensions spanning product type, end-user category, installation configuration, and technological feature tier. CAGRs derived from fitted growth curves applied to replacement cycle analysis and greenfield penetration assumptions. Forecast inputs incorporated cybersecurity mandate implementation timelines and Ayushman Bharat district hospital upgrade pacing.
Macroeconomic conditions sit as an overlay; deviation in steel and aluminum commodity indices, health ministry budget allocations, or medical device tariff schedules would shift the trajectory. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Healthcare Equipment
Middle East and Africa Hospital Furniture Market
Healthcare Equipment
India Healthcare Machine Vision System Market
Healthcare Equipment
Skin Cooling Systems Market
Healthcare Equipment
Veterinary Furniture Market
Healthcare Equipment
Healthcare Cold Chain Monitoring Market
Healthcare Equipment
Iraq Intensive Care Unit (ICU) Beds and Surfaces Market
Healthcare Equipment
Ophthalmic Examination Chairs Market
Healthcare Equipment
Bedpan Washer Disinfectors Market
Healthcare Equipment
Clinical Mobility Market
Healthcare Equipment
Healthcare Personal Protection Equipment Market
Healthcare Equipment
Medical Waste Supervision Solution Market
Healthcare Equipment
North America Healthcare Machine Vision System Market
Healthcare Equipment
Patient Recliner Chair Market
Healthcare Equipment
Specialty Medical Chairs Market
Healthcare Equipment
Medical Cold Storage Market
Healthcare Equipment
Medical Chairs Market