
 Smart Cards in Healthcare Market | 2026-2036
Smart Cards in Healthcare Market Size, Share, and Industry Trends Forecast 2026-2036
Smart Cards in Healthcare Market Intelligence
The EU Green Deal's emphasis on sustainable product lifecycles is realigning material sourcing and manufacturing processes for the plastic and electronic components in smart cards. Thales Group leverages its extensive cybersecurity expertise to secure healthcare data on these devices. Giesecke+Devrient specializes in high-security identity and connectivity solutions for national eID and health programs. NXP Semiconductors dominates the supply of secure microcontrollers, a critical component for card functionality and data protection.
A smart card in healthcare is a device, typically credit-card-sized, containing an embedded microprocessor or memory chip compliant with ISO/IEC 7816 standards. This chip securely stores, encrypts, and processes patient information. Its primary purpose is to enable secure access to medical records and services. While Patient Identification remains the largest application, the market is seeing rapid expansion in Dual Interface Smart Cards, which offer both contact and contactless functionality for improved usability in hospital environments.
Regulatory frameworks are central to market access and product design. In the United States, HIPAA sets strict rules for patient data privacy, while Europe's GDPR governs personal data handling. National initiatives, such as Germany's electronic health card project overseen by Gematik, define technical specifications. Stakeholders must now focus on ensuring their solutions are interoperable across disparate health IT systems while also defending against increasingly sophisticated cybersecurity threats.
Market Dynamics
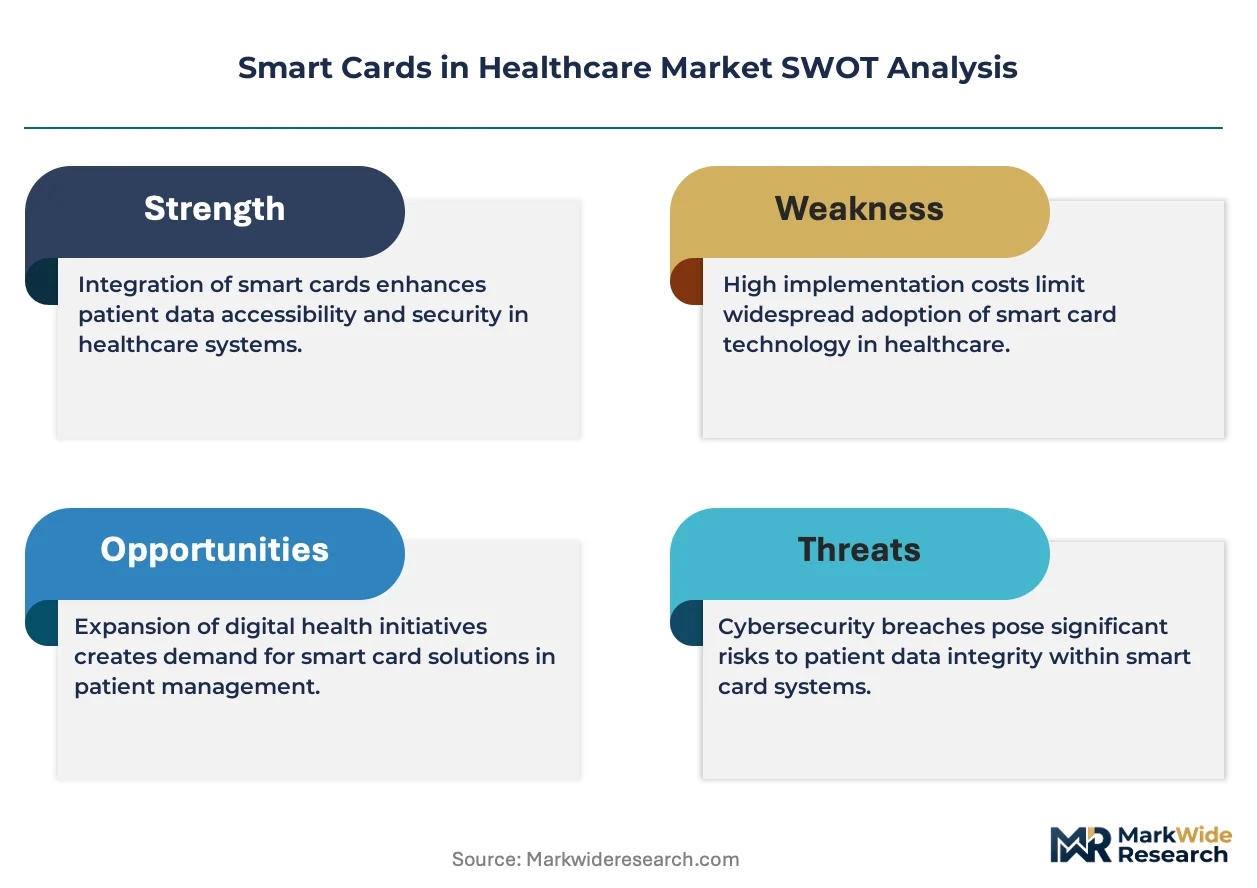
The market's central dynamic involves reconciling the push for interoperable health data with the imperative for decentralized, patient-centric security. Regulations like HIPAA and GDPR create the foundational push for secure electronic health records, defining this core tension.
Growth Catalysts
- National Digital Health Initiatives:Government-led projects, such as Germany's electronic health card program managed by Gematik, mandate nationwide adoption and create a large, unified market for compliant smart card solutions.
- Advanced Card Technologies:The development of Dual Interface smart cards, offering both contact and contactless access, enhances usability in fast-paced hospital environments, accelerating adoption for clinical staff and patient access.
- Patient Safety Imperatives:Demand for secure patient identification to reduce medical errors and prevent insurance fraud is a primary driver, particularly within large-scale hospital networks and national health systems.
Market Restraints
- High Implementation Costs:The substantial initial investment required for card readers, software, and integration with existing Electronic Health Record (EHR) systems acts as a significant barrier for smaller healthcare facilities.
- Interoperability Hurdles:Despite standards like ISO/IEC 7816, achieving seamless data exchange between different vendors' systems and across regional health networks remains a persistent technical challenge limiting utility.
- Mobile-Based Alternatives:The emergence of secure smartphone applications for digital identity and health record access presents a long-term substitution threat, potentially bypassing the need for a physical card.
Strategic Opportunities
- Emerging Market Modernization:Countries like Brazil are building national health IT infrastructures, creating new markets for smart card systems that comply with regulations from bodies like ANVISA.
- Clinical Trial Management:Applying smart cards to manage patient consent and secure data collection in clinical trials offers an opportunity to enhance data integrity and regulatory compliance for pharmaceutical research.
- Integration with IoT:There is an opportunity for smart cards to serve as a secure authentication key for patient data collected from remote monitoring devices and other connected health IoT endpoints.
Industry Challenges
- Legacy System Integration:Connecting modern smart card infrastructure with outdated hospital information systems is complex, often requiring custom development and causing potential disruptions to clinical workflows during deployment.
- Evolving Cybersecurity Threats:Defending against sophisticated ransomware and data breach attacks requires continuous investment in advanced encryption and threat detection, elevating operational costs for vendors and providers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Smart Cards in Healthcare Market |
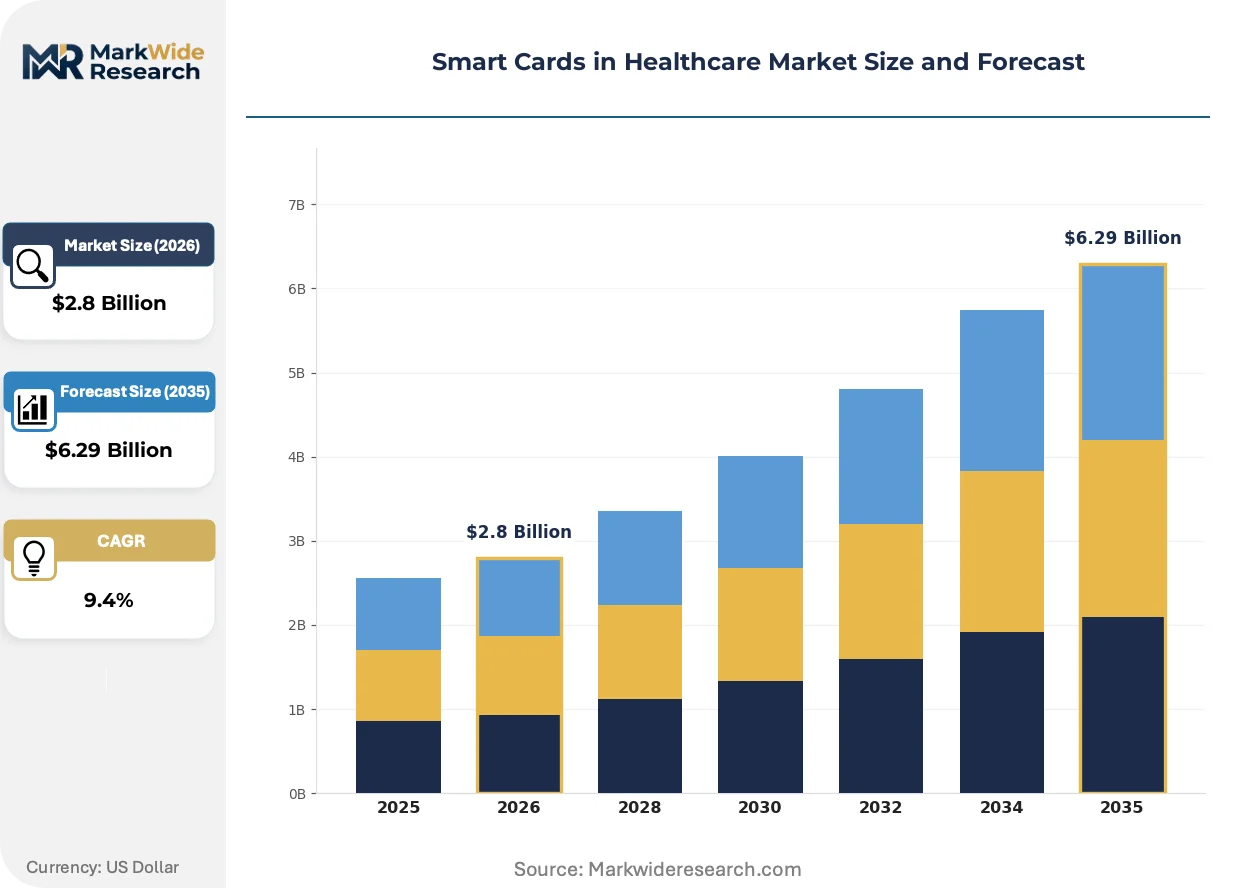
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $6.29 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Contact Smart Cards, Contactless Smart Cards, Dual Interface Smart Cards, Biometric Smart Cards Application: Patient Identification, Electronic Health Records, Medication Tracking, Access Control End User: Hospitals, Clinics, Laboratories, Insurance Providers Technology: RFID, NFC, Magnetic Stripe, Microprocessor |
| Companies Covered | Thales Group, Giesecke+Devrient, NXP Semiconductors, Infineon Technologies, IDEMIA, Atos SE, CardLogix Corporation, HID Global, Texas Instruments, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Smart Cards in Healthcare Market Strategic Shifts & Innovations
The market is transitioning from cards as simple data containers to their role as secure endpoints in a distributed digital health ecosystem. This evolution redefines the card's function as a key for accessing and managing dynamic health information across multiple platforms.
Biometric-on-card technology embeds fingerprint matching directly onto the card's secure microprocessor, eliminating the need for an external database. Healthcare organizations are adopting this for high-assurance identity verification in sensitive applications. This on-device processing is converging with existing secure element architectures to create a passwordless authentication layer, bolstering security beyond simple PIN codes.
India's Ayushman Bharat Digital Mission (ABDM) is creating a national framework for a federated digital health architecture. The policy mandates a unique health identifier (UHID) for every citizen. The patient identification segment is directly impacted, as vendors must ensure their card solutions are compliant with ABDM specifications to participate in the national ecosystem.
A significant shift in purchasing involves bundling smart card issuance with long-term managed identity services. This model moves from one-time hardware procurement towards subscription contracts that include security updates and system support. This trend is prominent in large hospital consortia in countries like France, where total cost of ownership is a key decision factor.
Smart Cards in Healthcare Market Segmentation
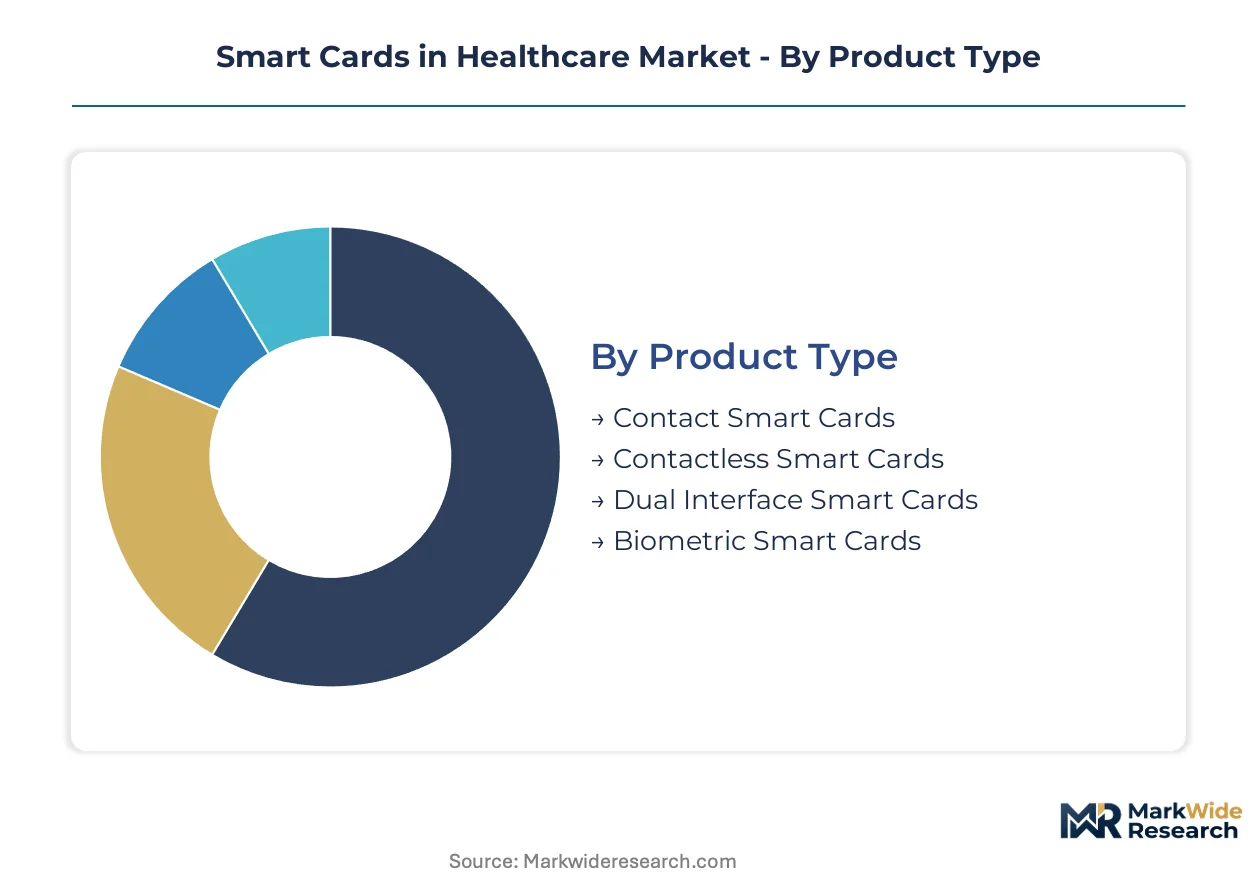
Understanding the distinct segments within the smart cards in healthcare market is crucial for stakeholders to align product development and market strategies effectively. This granular view reveals where specific functionalities and technologies are gaining traction, informing investment decisions for providers and technology suppliers.
Product Type:
Healthcare providers prioritize product type based on the required security level, interoperability, and user experience for patient interactions.
- Dual Interface Smart Cards:These cards offer both contact and contactless functionality, enhancing usability in busy hospital environments by allowing quick data access through tap-and-go readers while retaining high-security contact chip capabilities. Demand for these cards is expanding most quickly in Europe, driven by national digital health initiatives seeking versatile patient identification solutions.
- Biometric Smart Cards:Embedding fingerprint matching directly onto the card's secure microprocessor provides high-assurance identity verification, eliminating reliance on external databases. Healthcare organizations in countries like Germany are adopting this technology for sensitive applications, bolstering data protection and patient privacy.
- Contact Smart Cards:These devices require physical insertion into a reader to establish an electrical connection, securing data access for applications requiring stringent authentication protocols.
- Contactless Smart Cards:Utilizing radio frequency identification (RFID) technology, these cards enable data exchange over short distances without physical contact, streamlining patient check-ins and access control.
Dual Interface Smart Cards lead on scale; Biometric Smart Cards lead on momentum.
Application:
The utility of smart cards is defined by their specific application within the healthcare ecosystem, driving adoption across various operational needs.
- Patient Identification:This application involves using smart cards to securely verify a patient's identity, reducing medical errors and preventing insurance fraud. Large hospital networks in the United States and national health systems in France are concentrating demand for these secure identification solutions.
- Electronic Health Records:Smart cards provide secure, portable access to a patient's comprehensive medical history, facilitating data sharing among authorized healthcare providers. Regulations like HIPAA in the United States and GDPR in Europe heavily influence the design and security features required for this application.
- Medication Tracking:Smart cards can store and manage patient medication histories, improving prescription accuracy and preventing adverse drug interactions. This application supports enhanced patient safety within clinical settings.
- Access Control:Utilizing smart cards for physical and logical access control restricts entry to sensitive areas and secures access to digital health systems, protecting patient data and infrastructure.
Patient Identification remains the largest application; Electronic Health Records is expanding most quickly.
End User:
Different end-user segments adopt smart card solutions based on their operational scale, regulatory compliance needs, and existing IT infrastructure.
- Hospitals:Large hospital systems require robust smart card solutions for comprehensive patient identification, secure EHR access, and streamlined administrative processes across multiple departments. These institutions often demand interoperable solutions that integrate with complex legacy systems.
- Insurance Providers:These entities utilize smart cards for verifying patient eligibility, processing claims, and combating healthcare fraud, necessitating high-security features and integration with billing systems. Insurance providers in countries with high rates of medical fraud are driving demand.
- Clinics:Smaller healthcare facilities adopt smart cards primarily for patient identification and basic EHR access, often seeking cost-effective and easy-to-implement systems. Their procurement patterns prioritize ease of integration over extensive customization.
- Laboratories:Smart cards secure patient samples, track test results, and manage access to sensitive laboratory equipment and data. Data integrity and regulatory compliance are critical for this segment.
Hospitals represent the largest end-user segment; Insurance Providers are showing the steepest expansion trajectory.
Technology:
The underlying technology dictates the card's functionality, security features, and compatibility with existing infrastructure, influencing procurement decisions.
- Microprocessor:These smart cards contain an embedded chip that securely stores, encrypts, and processes patient information, compliant with ISO/IEC 7816 standards. This technology forms the backbone for advanced security features and on-card data processing, critical for secure electronic health records.
- NFC:Near Field Communication (NFC) technology enables contactless data exchange over very short distances, facilitating quick patient check-ins and secure transactions. The integration of NFC into smartphones is reshaping competitive positioning for physical cards.
- RFID:Radio Frequency Identification (RFID) technology allows for wireless data transfer, primarily used for tracking assets, inventory, and sometimes for basic patient identification in specific environments. This technology offers convenience for large-scale tracking operations.
- Magnetic Stripe:While older technology, magnetic stripe cards are still used for basic identification and administrative tasks due to their low cost and widespread reader infrastructure. Their security limitations are leading to displacement by chip-based solutions.
Microprocessor technology provides foundational security; NFC technology is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The smart cards in healthcare market traces its significant scaling to early national digital health initiatives in Europe. Countries like Germany and France pioneered the use of secure electronic health records, establishing foundational demand. This early adoption laid the groundwork for broader global expansion in patient identification solutions.
Germany
Germany's demand for smart cards is driven by its national electronic health card program, managed by Gematik. This initiative mandates widespread adoption of compliant solutions for secure patient data. Major technology hubs like Berlin and Munich are seeing increased development of integrated smart card systems for healthcare.
France
French national health systems concentrate demand for secure patient identification to reduce medical errors. GDPR heavily influences the design of these solutions, ensuring stringent data privacy. Large hospital consortia in Paris and Lyon are implementing bundled smart card issuance with managed identity services.
United States
United States demand for smart cards stems from the need for secure patient identification within large hospital networks. HIPAA regulations set strict standards for patient data privacy, influencing product design. Technology clusters in Silicon Valley and Boston are developing interoperable solutions for EHR integration.
India
India's Ayushman Bharat Digital Mission (ABDM) creates substantial demand for smart card systems compliant with its unique health identifier. This national framework mandates secure patient identification for all citizens. Technology centers in Bangalore and Hyderabad are developing solutions tailored to ABDM specifications.
Brazil
Brazil is building national health IT infrastructures, creating new markets for smart card systems that comply with ANVISA regulations. This modernization effort focuses on secure patient data management across the healthcare ecosystem. Major urban centers like São Paulo and Rio de Janeiro are key areas for system deployment.
Smart Cards in Healthcare Market Key Industry Players
Capital-heavy producers compete with asset-light designers in the smart cards in healthcare market, reflecting varied investment models. This market exhibits a tiered structure, with established technology giants providing core components and specialized firms offering tailored healthcare solutions. Strategic archetypes include secure microcontroller manufacturers, identity solution providers, and system integrators. Companies frequently engage in strategic partnerships to enhance interoperability and expand geographic reach, alongside continuous investment in advanced encryption technologies.
Specialists in high-security components and identity solutions anchor the market. NXP Semiconductors, for instance, exemplifies a leading provider of secure microcontrollers, a critical component for card functionality and data protection. Thales Group, a French multinational, represents a major player leveraging extensive cybersecurity expertise to secure healthcare data on these devices. German-based Giesecke+Devrient occupies a position focused on high-security identity and connectivity solutions for national eID and health programs, showcasing a deep-rooted commitment to secure data handling.
| Leading Market Players |
|---|
| Thales Group |
| Giesecke+Devrient |
| NXP Semiconductors |
| Infineon Technologies |
| IDEMIA |
| Atos SE |
| CardLogix Corporation |
| HID Global |
| Texas Instruments |
| Others |
Cost & Logistics Intelligence
Strategic bundling of smart card issuance with managed identity services anchors both vendor supply positions and their long-term pricing power. This model shifts revenue from one-time hardware sales to recurring subscription contracts for comprehensive solutions.
Pricing Analysis
Managed service subscription models dominate pricing for advanced smart card solutions. Price differentiation stems from the level of embedded biometric security features and the extent of interoperability with diverse health IT systems. Pricing pressure affects basic contact cards due to competition from lower-cost, mobile-based alternatives. Smaller clinics exhibit higher price sensitivity compared to large hospital consortia seeking comprehensive, long-term identity solutions and system support.
Supply Chain Analysis
Secure microcontroller supply primarily draws from specialized manufacturers in Germany, the Netherlands, and France. Production relies on critical components such as high-grade silicon wafers, secure embedded memory, and specialized plastic substrates. A structural risk involves single-source vulnerabilities for advanced biometric-on-card microprocessors. Distribution runs through direct sales to national health systems and large hospital consortia, often via system integrators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The smart cards in healthcare market acts as a stable compounder, driven by continuous national digital health initiatives. This foundational demand ensures predictable, long-term growth across diverse applications.
For Market Incumbents: Anticipate the long-term substitution threat from secure smartphone applications by investing heavily in biometric-on-card R&D. Deepen interoperability with disparate Electronic Health Record (EHR) systems to consolidate market share. Secure existing client relationships through bundled managed identity services, ensuring continuous revenue streams. Explore vertical integration opportunities into core component manufacturing to mitigate supply chain risks.
For New Entrants and Emerging Players: Smaller clinics in emerging markets represent a significant underserved buyer archetype for basic smart card solutions. Target clinical trial management and secure authentication for connected health IoT endpoints as white-space opportunities. The medication tracking application offers a penetrable entry point due to patient safety imperatives. Offer cost-effective, easily integrable systems with strong local support as a primary go-to-market angle.
For Investors and Strategic Acquirers: Roll-up economics work for system integrators because of the fragmented health IT landscape and the need for seamless interoperability. This market offers long-term viability, driven by regulatory mandates for secure electronic health records. Target specialized cybersecurity firms or biometric-on-card technology developers for their intellectual property. The signal to watch is the pace and scale of national digital health infrastructure investments in emerging economies.
| Strategic Initiative | Industry Significance |
|---|---|
| Enhance Biometric-on-Card R&D | Bolsters patient data protection and facilitates passwordless authentication for healthcare organizations. |
| Expand Managed Identity Services | Shifts revenue models from hardware sales to recurring subscription contracts for large hospital consortia. |
| Deepen EHR System Interoperability | Addresses legacy system integration challenges and streamlines data exchange for healthcare providers. |
| Target Clinical Trial Management | Improves data integrity and regulatory compliance for pharmaceutical research using secure identification. |
| Pursue Emerging Market Infrastructure Deals | Captures new demand from countries like Brazil building national digital health systems compliant with ANVISA. |
Research Approach
Coverage spans Germany, France, the United States, India, and Brazil, with primary inputs from each region. This involved interviews with hospital procurement managers, IT directors, smart card manufacturers, and regulatory affairs specialists, validated by secondary research. Secondary sources included HIPAA guidelines, GDPR documents, Gematik reports, and ANVISA regulations. Analysts employed both bottom-up and top-down triangulation for data accuracy.
Granularity across the analysis window included detailed modeling by product type, application, end-user, technology, and regional adoption patterns. The analytical framework integrated historical performance with projected market dynamics throughout the forecast period. Compound annual growth rates were derived from a comprehensive assessment of market drivers and restraints. Key forecast inputs included regulatory mandates like HIPAA and GDPR, alongside national digital health infrastructure investment.
Underlying measurement precision varies by segment; Patient Identification and Hospitals carry tighter precision than others due to established data. Forecasts reflect assumptions regarding regulatory stability and technological advancements, though evolving cybersecurity threats and mobile-based alternatives pose specific risk factors. A small set of named triggers warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Health Solutions
Digital Assistants in Healthcare Market
Digital Health Solutions
North America Digital Health Market
Digital Health Solutions
Digital Healthcare Solutions Market
Digital Health Solutions
AI in Patient Engagement Market
Digital Health Solutions
Mhealth Applications Market
Digital Health Solutions
Mobile Health (Mhealth) Market
Digital Health Solutions
Global Clinical Workflow Solutions Market
Digital Health Solutions
Cardiac AI Monitoring and Diagnostic Market
Digital Health Solutions
Digital Brain Health Market
Digital Health Solutions
Teleradiology Software Market
Digital Health Solutions
US Patient Engagement Solutions Market
Digital Health Solutions
Women Digital Health Solutions Market
Digital Health Solutions
Healthcare Chatbots Market
Digital Health Solutions
North America Patient Support Technology Market
Digital Health Solutions
Medical Animation Market
Digital Health Solutions
Asia-Pacific Eclinical Solutions Market