
 Healthcare Cold Chain Monitoring Market | 2026-2036
Healthcare Cold Chain Monitoring Market Size, Share, and Industry Trends Forecast 2026-2036
Healthcare Cold Chain Monitoring Market Outlook
EU Good Distribution Practice revision is shifting compliance burdens onto last-mile distributors across the European Economic Area. Sensitech anchors its European presence through GDP-certified service depots in Switzerland and Germany. Thermo Fisher Scientific extends its monitoring portfolio into cryogenic plasma logistics through specialized ultra-low sensor arrays. Honeywell International competes on manufacturing scale, producing multi-parameter loggers at volume for third-party logistics providers serving the Nordics.
Healthcare cold chain monitoring encompasses the real-time tracking of temperature, humidity, and location parameters for thermosensitive medical products, typically employing calibrated digital sensors with accuracy thresholds of ±0.5°C and wireless telemetry intervals under five minutes to prevent excursion-induced spoilage. Its primary commercial purpose is to maintain product efficacy and regulatory compliance across pharmaceutical distribution networks from manufacture through patient administration. Wireless monitoring systems now capture the largest installed base among product types, though RFID solutions are gaining fastest in high-value biologics lanes where automated chain-of-custody documentation reduces insurance premiums. Among applications, vaccines retain the deepest penetration due to national immunization program mandates, while clinical samples represent an emerging margin pool as decentralized trial networks proliferate.
FDA enforcement of the Drug Supply Chain Security Act and EU GDP guidelines through national competent authorities like Germany's BfArM and France's ANSM are elevating sensor validation requirements and documentation granularity for cross-border shipments. WHO Performance Quality and Safety prequalification standards for temperature monitoring devices further constrain vendor eligibility in emerging market procurement. Stakeholders must decide whether to absorb these compliance costs through captive monitoring infrastructure or outsource to specialized platform providers whose audit trails satisfy multiple regulatory regimes simultaneously.
Market Dynamics
The FDA's Drug Supply Chain Security Act serialization mandates are forcing pharmaceutical distributors to upgrade temperature-monitoring infrastructure at every handoff node, compressing equipment replacement cycles from seven years to three.
Growth Catalysts
- WHO PQ Standards:Prequalification requirements for temperature monitoring devices in vaccine procurement programs are expanding the addressable market for validated sensor manufacturers across Sub-Saharan Africa and Southeast Asia.
- Germany's BfArM Enforcement:Intensified GDP compliance audits along the Rhine-Main corridor are mandating redundant sensor deployments for cross-border biologics shipments.
- mRNA Platform Expansion:Thermosensitive nucleic acid therapies require ultra-low temperature monitoring from -80°C through last-mile administration, extending sensor duty cycles.
Market Restraints
- Sensor Calibration Costs:Annual ISO 17025 recertification for ±0.5°C accuracy thresholds consumes 15-20% of total device lifecycle expenditure for third-party logistics operators.
- Lithium Cell Supply Concentration:Dependence on Chinese cathode material processing creates input volatility for wireless logger battery packs.
- Interoperability Friction:Proprietary data formats between competing telemetry platforms prevent seamless handoff documentation across multi-carrier pharmaceutical lanes.
Strategic Opportunities
- Decentralized Clinical Trials:Direct-to-patient sample collection networks in the United States and Western Europe require portable temperature loggers with cellular connectivity for home healthcare settings.
- EU F-Gas Regulation Phase-Down:Transition toward natural refrigerant cold rooms creates demand for corrosion-resistant sensor housings and expanded humidity monitoring.
- Blockchain Integration:Immutable chain-of-custody records combined with real-time sensor telemetry are reducing insurance premiums for high-value oncology biologics.
Industry Challenges
- GDP Auditor Shortage:Qualified personnel for European Economic Area compliance verification are concentrated in Germany and the Netherlands, creating bottlenecks for rapid facility certification.
- Legacy System Integration:Pharmaceutical warehouses running 1990s-era warehouse management software require custom API development to ingest streaming sensor data.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Healthcare Cold Chain Monitoring Market |
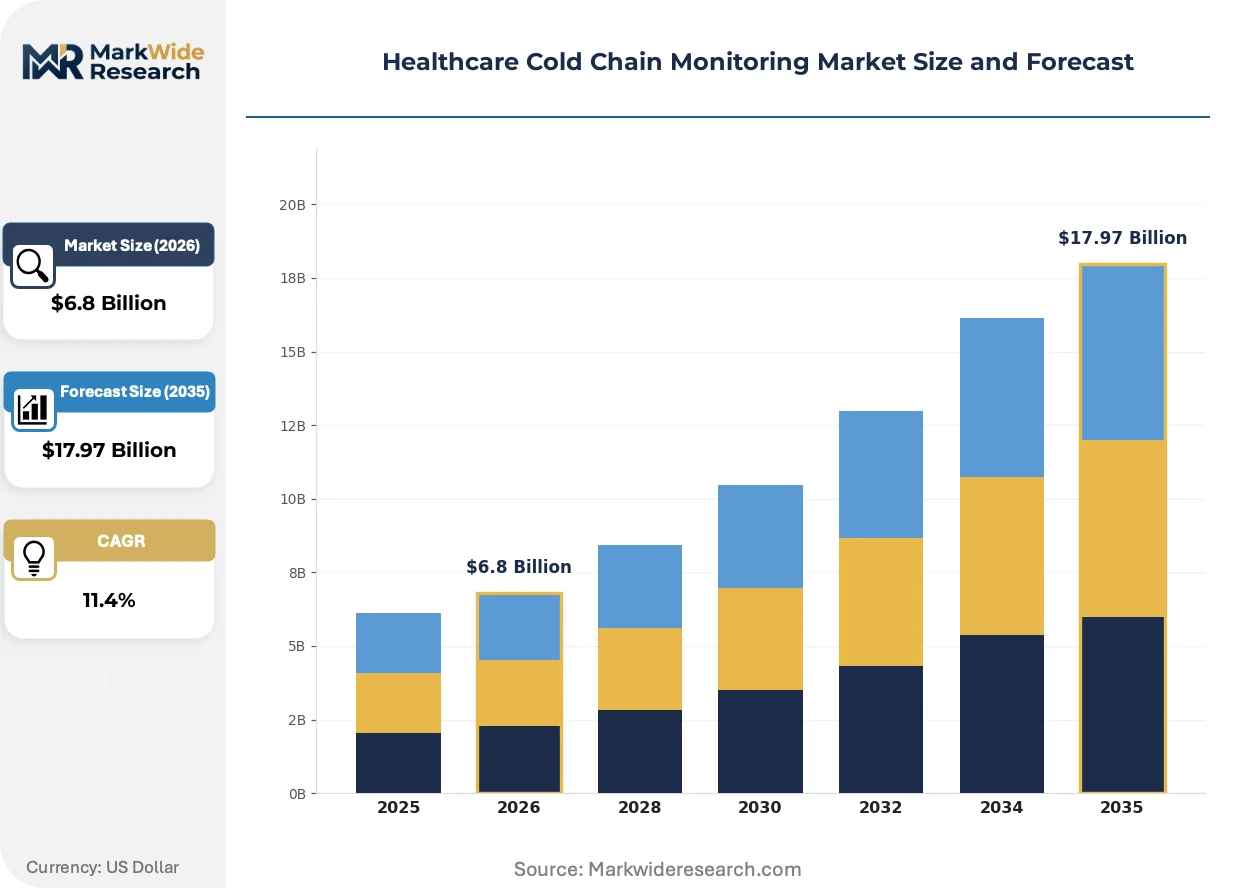
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $17.97 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Data Loggers, Temperature Sensors, RFID Solutions, Wireless Monitoring Systems End User: Pharmaceutical Companies, Hospitals, Clinics, Research Laboratories Technology: IoT-Based Solutions, Cloud Monitoring, Bluetooth Tracking, GPS Systems Application: Vaccines, Biologics, Blood Products, Clinical Samples |
| Companies Covered | Honeywell International, Monnit Corporation, Sensitech, Elpro-Buchs AG, Berlinger & Co. AG, Thermo Fisher Scientific, Zebra Technologies, Cold Chain Technologies, Emerson Electric, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Healthcare Cold Chain Monitoring Market Strategic Shifts
Digital sensor miniaturization and edge computing architectures are compressing the cost-performance frontier for real-time cold chain telemetry, enabling deployment density previously uneconomical for mid-value pharmaceuticals.
LoRaWAN connectivity protocols are electrifying last-mile monitoring economics for rural vaccine distribution. National immunization programs in India and Brazil are deploying solar-powered gateway infrastructure to eliminate cellular subscription costs. This technology is electrifying coverage expansion into regions where satellite telemetry was previously cost-prohibitive.
EU MDR Annex I technical documentation requirements are elevating sensor validation burden for medical device-adjacent cold storage. Manufacturers must now demonstrate electromagnetic compatibility and software lifecycle processes under notified body scrutiny. In-vitro diagnostic reagent producers face the steepest compliance ramp, with many outsourcing validation to specialized platform providers.
Buyer consolidation among contract development and manufacturing organizations is compressing vendor qualification cycles. Large CDMOs are demanding unified dashboards spanning multiple carrier networks and manufacturing sites. This pattern is most pronounced in the United States, where three major pharmacy benefit managers now control distribution specifications for temperature-sensitive specialty drugs.
Healthcare Cold Chain Monitoring Market Segmentation
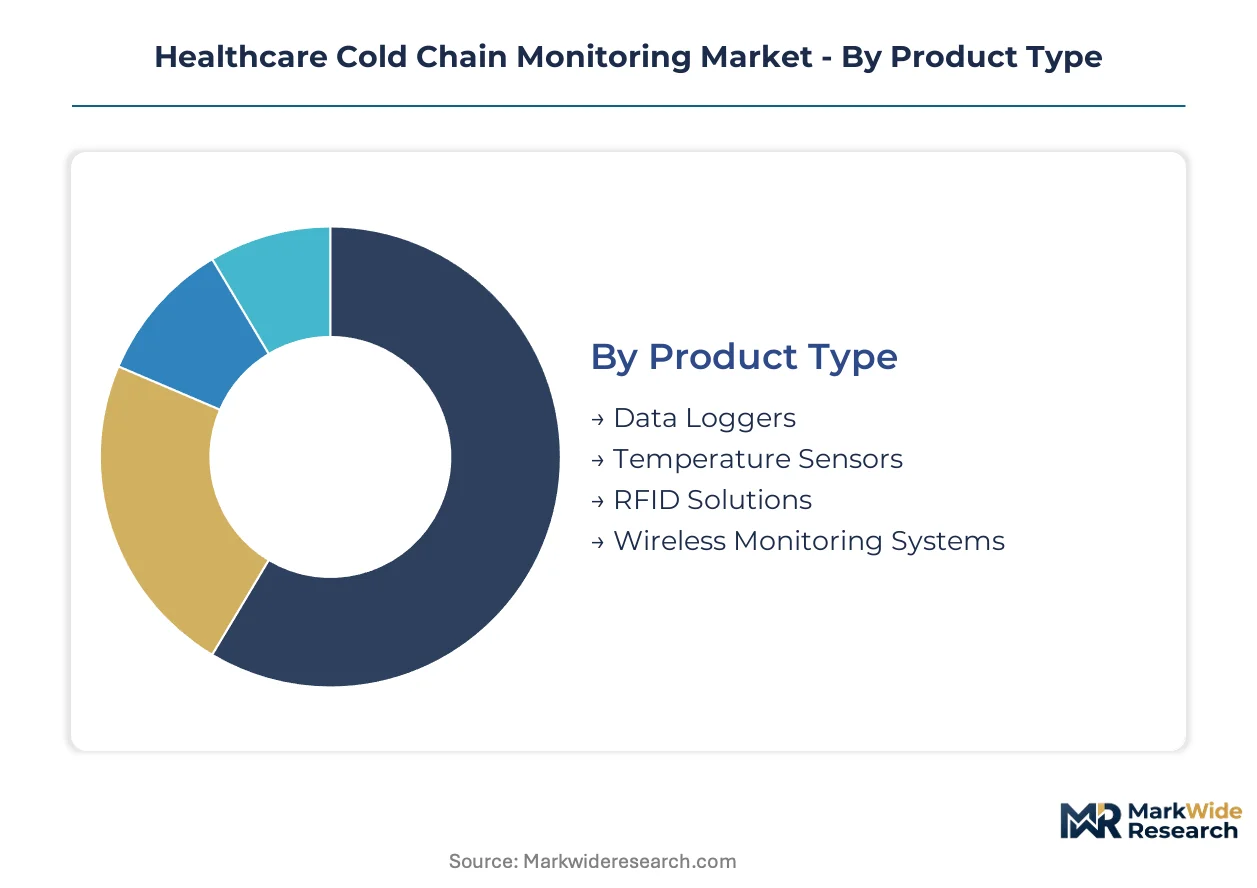
Cold chain monitoring architectures diverge sharply across product classes, with sensor modality selection determining regulatory compliance pathways and total cost of ownership. Technology choices now dictate whether pharmaceutical distributors absorb infrastructure investment or outsource telemetry to platform providers.
Product Type:
Sensor hardware specifications define calibration burdens and deployment density economics across pharmaceutical distribution networks.
- Wireless Monitoring Systems:Multi-parameter telemetry platforms integrate temperature, humidity, and location data through cellular or LoRaWAN connectivity. Hospital pharmacy networks in Germany and the United States deploy these most intensively to satisfy FDA DSCSA documentation requirements at every handoff node.
- RFID Solutions:Passive and active radio-frequency identification tags enable automated chain-of-custody logging without manual scanning. High-value oncology biologics lanes in Switzerland and the Netherlands adopt these fastest where insurance premium reductions justify hardware costs.
- Data Loggers:Standalone USB or Bluetooth devices store excursion data for retrospective audit trails. Budget-constrained vaccine programs in India and Brazil favor these for primary healthcare center cold boxes.
- Temperature Sensors:Discrete thermocouple or thermistor probes require integration with external telemetry infrastructure. CDMO consolidation in the United States is driving demand for unified sensor dashboards across multiple manufacturing sites.
Wireless monitoring systems lead on scale; RFID solutions lead on momentum.
End User:
Customer procurement sophistication ranges from enterprise platform contracts to single-site hardware purchases.
- Pharmaceutical Companies:Multinational manufacturers mandate redundant sensor deployments and validated audit trails for FDA, EMA, and WHO PQ compliance. Serialization upgrades under the Drug Supply Chain Security Act compress their equipment replacement cycles substantially.
- Research Laboratories:Decentralized clinical trial networks require portable loggers with cellular connectivity for direct-to-patient sample collection. Sites in the United States and Western Europe represent the steepest adoption curve.
- Hospitals:Pharmacy departments balance capital budgets against Joint Commission accreditation requirements for medication storage documentation.
- Clinics:Primary care and specialty infusion centers prioritize low-cost disposable loggers for vaccine refrigerator compliance.
Pharmaceutical companies command the deepest penetration; research laboratories exhibit the steepest expansion trajectory.
Technology:
Connectivity protocol selection determines coverage economics and data sovereignty compliance.
- IoT-Based Solutions:Internet of Things architectures aggregate sensor streams through edge gateways into centralized analytics platforms. India's national immunization program deploys solar-powered LoRaWAN infrastructure to eliminate recurring cellular subscription costs.
- Cloud Monitoring:Software-as-a-service platforms host validated audit trails satisfying multiple regulatory regimes simultaneously. EU GDP compliance audits are accelerating outsourcing to specialized providers with pre-certified documentation systems.
- Bluetooth Tracking:Short-range wireless protocols suit last-meter verification in hospital pharmacy workflows. Germany's BfArM enforcement of redundant monitoring drives secondary Bluetooth backup deployments.
- GPS Systems:Satellite telemetry enables real-time location tracking for cross-border biologics shipments. Rhine-Main corridor distributors rely on these for customs documentation and theft recovery.
IoT-based solutions anchor current deployment volume; cloud monitoring platforms gain share fastest among mid-cap pharmaceutical distributors.
Application:
Thermal sensitivity thresholds and regulatory scrutiny intensity vary dramatically across product categories.
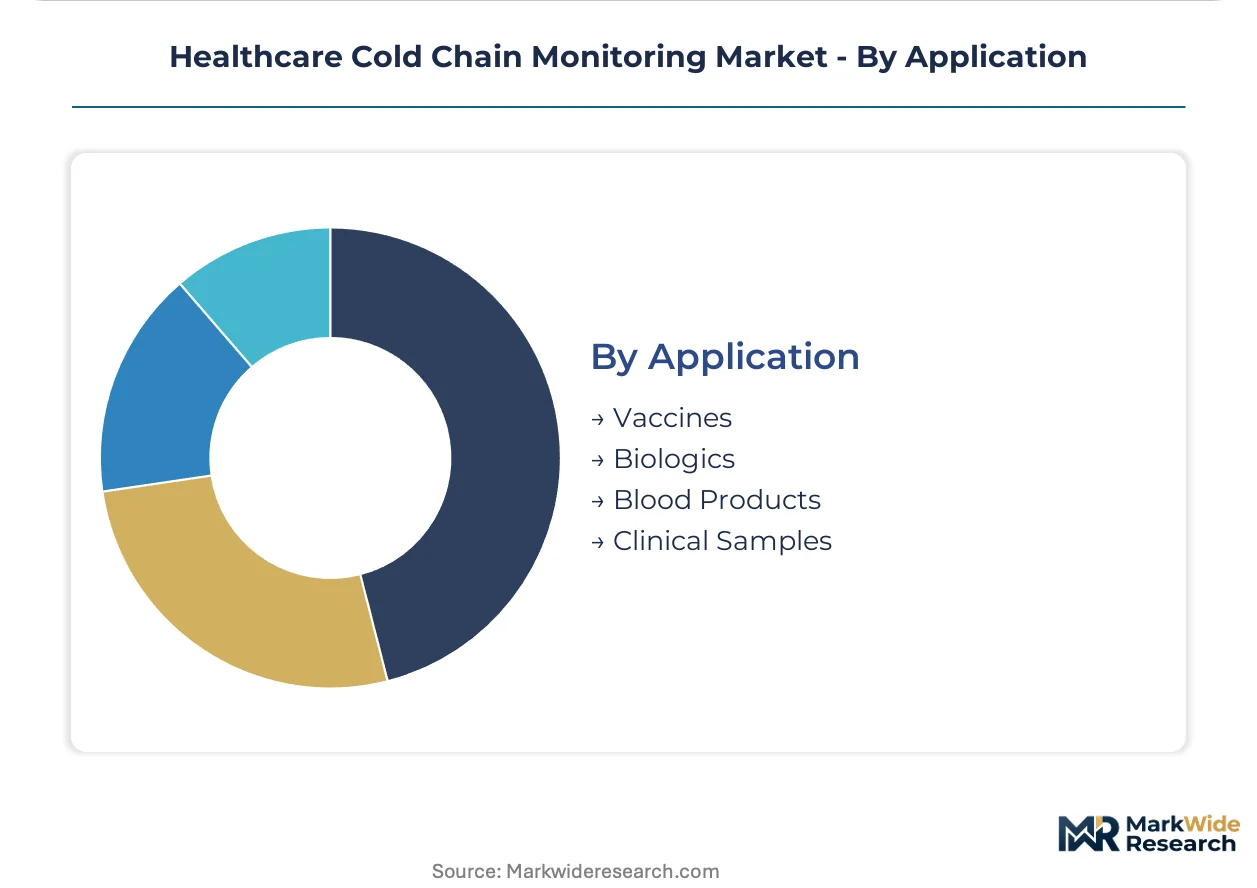
- Vaccines:National immunization program mandates drive the deepest sensor penetration globally. WHO PQ standards for temperature monitoring devices constrain vendor eligibility in Sub-Saharan Africa and Southeast Asia procurement.
- Biologics:mRNA nucleic acid therapies require ultra-low temperature monitoring from -80°C through last-mile administration. Cryogenic plasma logistics in the United States and Germany extend sensor duty cycles and calibration frequency.
- Blood Products:Red cell and platelet storage regulations mandate continuous temperature documentation with ±0.5°C accuracy thresholds. Hospital blood banks absorb substantial ISO 17025 recertification costs.
- Clinical Samples:Decentralized trial networks proliferate direct-to-patient collection, creating demand for portable cellular-enabled loggers. This segment represents an emerging margin pool as sponsor-site relationships fragment.
Vaccines dominate installed base; clinical samples climb the fastest as trial decentralization accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The healthcare cold chain monitoring industry traces its modern scaling to pharmaceutical distribution networks established in the United States during the 1990s biologics boom, with subsequent regulatory frameworks in Europe and Asia institutionalizing sensor deployment standards across international supply corridors.
United States
FDA enforcement of the Drug Supply Chain Security Act mandates serialization upgrades at every temperature-controlled handoff node, compressing equipment replacement cycles from seven years to three. Pharmacy benefit managers now control distribution specifications for specialty drugs, driving unified dashboard demands across carrier networks. The Greater Boston biotech corridor anchors cryogenic plasma logistics with ultra-low temperature sensor arrays.
Germany
BfArM intensified GDP compliance audits along the Rhine-Main vaccine logistics cluster, mandating redundant sensor deployments for cross-border biologics shipments. The country's national pharmaceutical regulator enforces ±0.5°C accuracy thresholds with annual ISO 17025 recertification requirements. Frankfurt's pharmaceutical distribution hubs absorb substantial compliance infrastructure investment.
Switzerland
Swissmedic oversight of medical device-adjacent cold storage elevates sensor validation burdens under EU MDR Annex I technical documentation requirements. High-value oncology biologics lanes through Basel and Geneva adopt RFID solutions fastest where insurance premium reductions justify hardware costs. GDP-certified service depots cluster around Zurich's pharmaceutical corridor.
India
The national immunization program deploys solar-powered LoRaWAN gateway infrastructure to eliminate cellular subscription costs in rural vaccine distribution. CDSCO alignment with WHO Performance Quality and Safety standards constrains vendor eligibility in public procurement. Maharashtra's pharmaceutical manufacturing belt drives demand for validated sensor manufacturers.
Brazil
ANVISA enforcement of temperature documentation requirements for blood products and vaccines expands sensor deployment in public health cold chains. The national immunization program replicates India's solar-powered telemetry model for Amazon basin coverage. São Paulo's hospital pharmacy networks balance capital budgets against Joint Commission accreditation requirements.
Healthcare Cold Chain Monitoring Market Competitive Environment
The competitive structure tilts toward diversified instrumentation conglomerates with captive pharmaceutical verticals. Tier-one players combine manufacturing scale with regulatory pre-certification across multiple jurisdictions. Three archetypes dominate: sensor hardware specialists with ISO 17025 calibration infrastructure, cloud platform providers with multi-tenant GDP compliance systems, and diversified industrial conglomerates with volume manufacturing for third-party logistics. M&A activity concentrates on telemetry software assets, while capacity expansion targets LoRaWAN gateway production for emerging market immunization programs.
Within the diversified conglomerate tier, Honeywell International and Emerson Electric exemplify manufacturing-scale competition for Nordic third-party logistics providers. Sensitech anchors the sensor-specialist archetype through GDP-certified service depots in Switzerland and Germany. Thermo Fisher Scientific occupies a position bridging hardware and cryogenic logistics expertise. These three represent distinct strategic postures: volume manufacturing, regulatory proximity, and vertical integration into ultra-low temperature applications.
| Leading Market Players |
|---|
| Honeywell International |
| Monnit Corporation |
| Sensitech |
| Elpro-Buchs AG |
| Berlinger & Co. AG |
| Thermo Fisher Scientific |
| Zebra Technologies |
| Cold Chain Technologies |
| Emerson Electric |
| Others |
Value Chain & Pricing Dynamics
Captive calibration infrastructure anchors both supply security and pricing power for cold chain monitoring vendors serving FDA and EMA jurisdictions. Vertically integrated sensor manufacturers with in-house ISO 17025 laboratories command premium positioning against third-party logistics operators facing 15-20% annual recertification cost burdens.
Pricing Analysis
Bundled SaaS telemetry subscriptions dominate enterprise pharmaceutical contracts, while unbundled hardware-only transactions persist in budget-constrained national immunization programs. Price differentiation rests on GDP certification tier and cellular versus LoRaWAN connectivity modules. Cost compression in economy-tier data loggers is intensifying because Indian and Brazilian procurement authorities are consolidating vendor panels under WHO PQ standards. Third-party logistics providers exhibit the highest price sensitivity due to thin operating margins, whereas multinational pharmaceutical manufacturers prioritize audit trail reliability over unit economics.
Supply Chain Analysis
Direct-to-pharmaceutical OEM channels handle hyperscale sensor deployments for North American and European biologics distributors, while value-added resellers serve fragmented clinic and hospital pharmacy networks. Manufacturing concentrates in Germany, Switzerland, and the United States for precision sensor fabrication. Chinese cathode material processing feeds lithium cell production for wireless logger battery packs. Single-source vulnerability in rare earth magnet supply for GPS-enabled trackers creates exposure to export restriction risk. Distribution runs through GDP-certified service depots clustered around Frankfurt, Basel, and Zurich pharmaceutical corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in healthcare cold chain monitoring rests on sensor miniaturization cost curves and the shift toward premium-tier cloud monitoring platforms that amortize compliance infrastructure across multiple regulatory regimes.
For Market Incumbents: Extend calibration service revenue streams through multi-year ISO 17025 certification contracts that lock in pharmaceutical manufacturer relationships. Deepen LoRaWAN gateway production capacity for India's national immunization program solar-powered deployments. Consolidate telemetry software assets to preempt platform fragmentation threats from emerging cloud-native entrants.
For New Entrants and Emerging Players: The premium-to-economy price-point gap in clinical sample monitoring creates white-space opportunity for portable cellular-enabled loggers targeting decentralized trial networks. Brazil's Amazon basin vaccine distribution and Southeast Asia's WHO PQ-constrained procurement represent the most penetrable geographies. Pursue direct-to-CDMO sales channels that bypass established distributor markups in the United States pharmacy benefit manager ecosystem.
For Investors and Strategic Acquirers: Roll-up economics work for cloud platform providers because GDP compliance audit trail standardization creates natural consolidation pressure among mid-cap pharmaceutical distributors. Target acquisition archetypes include telemetry software specialists with pre-certified multi-tenant documentation systems. Watch for inflection when BfArM enforcement spreads redundant sensor mandates beyond the Rhine-Main corridor into France and Benelux jurisdictions.
| Strategic Initiative | Industry Significance |
|---|---|
| GDP Certification Investment | BfArM audits in Germany now mandate redundant sensor deployments for cross-border biologics. |
| LoRaWAN Infrastructure Deployment | India's solar-powered gateway model eliminates cellular costs for rural vaccine cold chains. |
| Cryogenic Sensor Array Development | mRNA platform expansion requires -80°C monitoring from manufacture through last-mile administration. |
| Blockchain Audit Trail Integration | Immutable chain-of-custody records reduce insurance premiums for high-value oncology biologics shipments. |
| Calibration Service Expansion | ISO 17025 recertification contracts capture 15-20% lifecycle expenditure from third-party logistics operators. |
Study Parameters
Multiple input streams — regulatory filing analysis, pharmaceutical distribution operator interviews, and cold chain equipment procurement databases — were reconciled to construct market sizing and competitive positioning assessments. Primary conversations with cold chain logistics directors, biomedical engineering managers at hospital pharmacy networks, GDP compliance auditors, and sensor manufacturer product strategists were validated against secondary sources including FDA DSCSA guidance documents, EMA GDP inspection reports, WHO PQ device prequalification listings, and national immunization program tender records. Bottom-up installed base estimates and top-down pharmaceutical logistics spend allocations were triangulated to resolve segmentation discrepancies.
Data-stream reconciliation across product type, end user, technology, and application dimensions produced volume and value outputs spanning the projection horizon. Segmentation modeling incorporated connectivity protocol adoption curves, regulatory enforcement intensity by national competent authority, and thermal sensitivity thresholds across vaccine, biologic, blood product, and clinical sample categories. CAGRs were derived from equipment replacement cycle compression under serialization mandates and emerging market immunization program expansion trajectories. Cryogenic plasma logistics growth and decentralized clinical trial network proliferation served as industry-specific demand drivers.
Caveats apply where lithium cell supply disruption, GDP auditor personnel shortages, or proprietary telemetry platform interoperability failures could materially shift the outlook. Forecasts reflect assumptions regarding regulatory enforcement continuity and pharmaceutical distributor outsourcing preferences. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Healthcare Equipment
Patient Infotainment Terminals Market
Healthcare Equipment
Physiotherapy Equipment Market
Healthcare Equipment
Global Hospital Asset Management Market
Healthcare Equipment
Middle East and Africa Hospital Furniture Market
Healthcare Equipment
Clinical Mobility Market
Healthcare Equipment
North America Nurse Call Systems Market
Healthcare Equipment
Veterinary Furniture Market
Healthcare Equipment
Iraq Intensive Care Unit (ICU) Beds and Surfaces Market
Healthcare Equipment
Skin Cooling Systems Market
Healthcare Equipment
Specialty Medical Chairs Market
Healthcare Equipment
India Healthcare Machine Vision System Market
Healthcare Equipment
Medical Cold Storage Market
Healthcare Equipment
North America Healthcare Machine Vision System Market
Healthcare Equipment
Medical Chairs Market
Healthcare Equipment
Patient Recliner Market
Healthcare Equipment
Medical Waste Supervision Solution Market