
 Global Physical Therapy Software Market | 2026-2036
Global Physical Therapy Software Market Size, Share, and Industry Trends Forecast 2026-2036
Global Physical Therapy Software Market Foresight
North American EMR infrastructure investment is rebalancing toward specialty-specific platforms. WebPT leverages its domain focus in outpatient rehabilitation to sustain high retention among independent practices. SimplePractice anchors its position through integrated telehealth and billing workflows designed for solo and small-group therapists. Net Health Systems competes via deep workflow customization for hospital-affiliated rehabilitation departments.
Physical therapy software encompasses clinical documentation, exercise prescription, scheduling, and revenue cycle management tools built on interoperable data standards such as HL7 FHIR. These systems automate patient intake, treatment planning, and claims submission while supporting outcomes measurement for value-based reimbursement. Cloud-based deployment leads adoption due to lower capital requirements and automatic regulatory updates, while on-premise installations persist in military healthcare settings with stringent data sovereignty rules. Exercise prescription modules represent the fastest-growing solution type as remote therapeutic monitoring gains payer acceptance. Billing and invoicing functionality remains the most mature segment, with margin pools shifting toward analytics-driven outcomes reporting.
FDA oversight of software as a medical device intersects with HIPAA privacy and security rules to create layered compliance obligations for vendors serving US providers. ONC certification requirements under the 21st Century Cures Act mandate standardized APIs, forcing legacy systems toward interoperability investments. Stakeholders must monitor CMS reimbursement policy evolution for remote therapeutic monitoring codes, as coverage determinations will directly shape feature investment priorities across the vendor landscape.
Market Dynamics
Medicare reimbursement policy for remote therapeutic monitoring codes is compressing vendor development timelines and forcing rapid feature parity across outpatient rehabilitation platforms.
Growth Catalysts
- ONC Certification Mandates:The 21st Century Cures Act requires standardized APIs, compelling legacy EMR vendors toward interoperability investments that expand addressable market for connected physical therapy tools.
- Cloud Infrastructure Maturation:Automatic regulatory updates and lower capital requirements accelerate replacement cycles among independent practices previously locked into on-premise installations.
- United States:Private payer digitization mandates and Medicare reimbursement rule changes create synchronized demand pull across hospital-affiliated and independent rehabilitation settings.
Market Restraints
- HIPAA Compliance Layering:FDA software-as-medical-device oversight intersects with privacy rules, creating multi-jurisdictional audit burdens that extend vendor certification timelines by 12-18 months.
- Data Sovereignty Requirements:Military healthcare settings in the United States maintain on-premise mandates, fragmenting deployment model standardization and compressing cloud-native vendor margins.
- HL7 FHIR Implementation Gaps:Legacy system architectures lack native interoperability, forcing expensive middleware development that stalls mid-market practice upgrades.
Strategic Opportunities
- Exercise Prescription Modules:Remote therapeutic monitoring code coverage expansion creates white space for vendors integrating motion capture and adherence tracking into clinical workflows.
- Analytics-Driven Outcomes Reporting:Value-based reimbursement contracts reward providers demonstrating functional improvement metrics, shifting margin pools from billing automation toward predictive outcome tools.
- Germany:The EU Medical Device Regulation creates certification bottlenecks for US vendors, opening acquisition opportunities for compliant European platforms serving rehabilitation chains.
Industry Challenges
- Interoperability Talent Scarcity:HL7 FHIR implementation expertise concentrates among health informatics specialists, inflating vendor R&D costs and delaying API standardization.
- Legacy System Integration Friction:Hospital-affiliated rehabilitation departments require deep workflow customization, extending implementation cycles and straining professional services capacity.
- Dual Certification Timelines:Concurrent FDA and ONC approval pathways demand parallel documentation streams, compressing product launch windows for feature updates.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Physical Therapy Software Market |
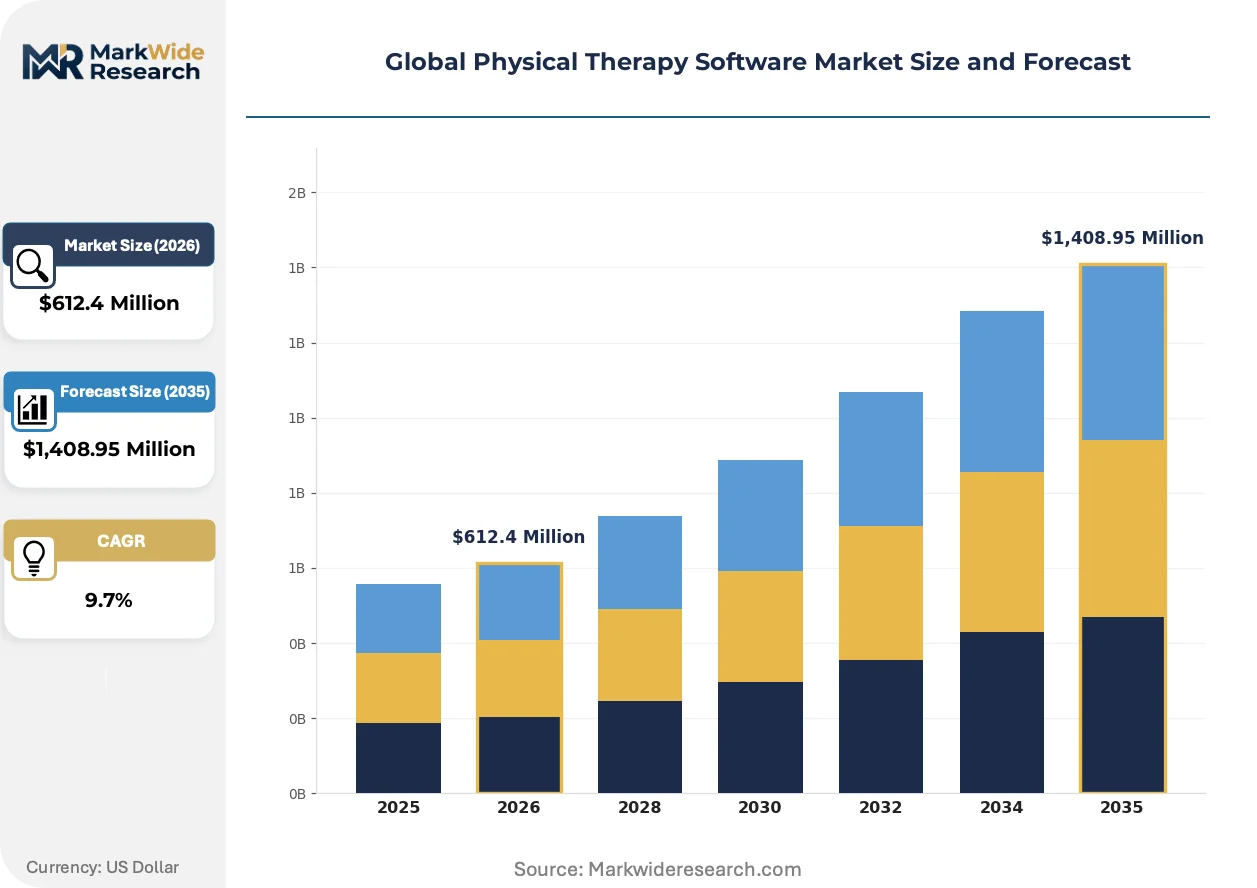
| Market Size in 2026 | $612.4 Million |
| Market Size in 2035 | $1,408.95 Million |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: Cloud-based, On-premise, Hybrid, Web-based, Mobile Applications Solution Type: Patient Management, Scheduling, Billing & Invoicing, Reporting & Analytics, Exercise Prescription End User: Outpatient Clinics, Rehabilitation Centers, Home Care Providers, Sports Therapy Facilities, Military Healthcare Application: Post-surgical Rehabilitation, Chronic Pain Management, Orthopedic Therapy, Neurological Rehabilitation, Pediatric Therapy |
| Companies Covered | SimplePractice, Net Health Systems, WebPT, SPRY PT, TheraPlatform, AdvancedMD, Clinicient, Noterro, Athenahealth, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Physical Therapy Software Market Shifts & Advancements
Artificial intelligence and machine learning architectures are modularizing traditional physical therapy software stacks, separating exercise prescription engines from documentation cores and enabling point-solution competition.
Machine learning algorithms trained on kinematic data are modularizing exercise prescription functionality, allowing standalone vendors to compete against integrated suites. Outpatient clinic operators in the United States pilot these tools for remote therapeutic monitoring reimbursement capture. This modularization compresses pricing power for legacy EMR vendors while expanding vendor choice for independent practices.
The EU Medical Device Regulation reclassifies software with diagnostic or treatment planning functions as Class IIa medical devices, imposing clinical validation requirements previously absent. Vendors serving European rehabilitation chains must now submit technical documentation and post-market surveillance plans. Germany and France see accelerated consolidation as smaller platforms lack resources for notified body engagement.
Subscription-based procurement displaces perpetual licensing across independent physical therapy practices, unbundling implementation and support costs from software access. Value-based care contracts in the United States drive preference for outcomes-contingent pricing models tied to functional improvement metrics. This shift favors vendors with native analytics over billing-focused legacy platforms.
Global Physical Therapy Software Market Segmentation
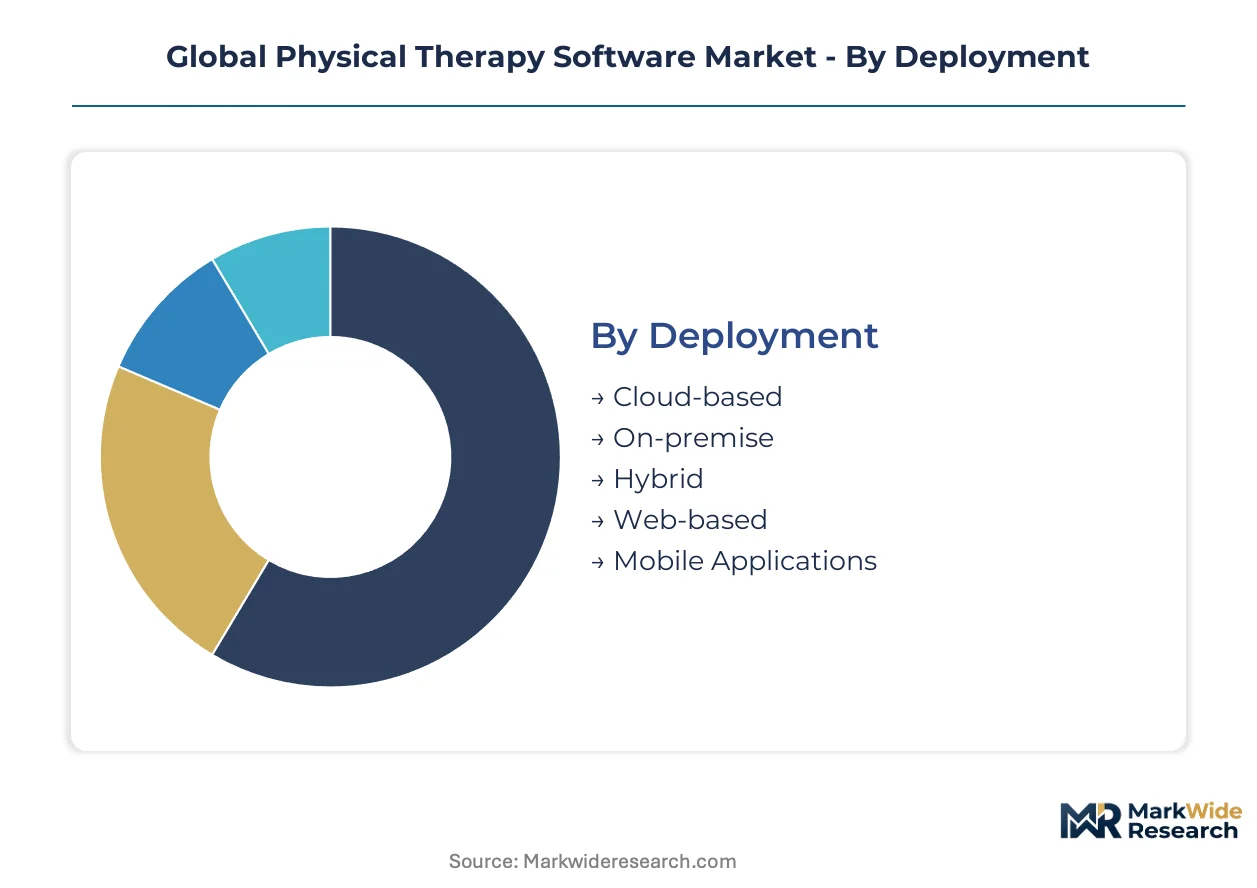
Physical therapy software segments reflect divergent compliance burdens and capital constraints across healthcare delivery settings. Deployment models separate cloud-native vendors from legacy infrastructure specialists, while solution types trace the shift from administrative automation toward clinical decision support.
Deployment:
Cloud infrastructure architectures determine regulatory update velocity and total cost of ownership for practice operators.
- Cloud-based:Multi-tenant SaaS platforms deliver automatic HIPAA security patches and ONC certification updates without client-side IT intervention. Demand concentrates among independent outpatient clinics in the United States seeking zero-capital deployment and predictable subscription economics.
- On-premise:Local server installations maintain complete data sovereignty through physical infrastructure control. Military healthcare facilities in the United States mandate this architecture under stringent data residency requirements that prohibit third-party cloud access.
- Hybrid:Split architectures keep protected health information on local servers while routing analytics workloads to cloud environments.
- Web-based:Browser-delivered applications reduce client-side hardware requirements without full SaaS backend dependencies.
- Mobile Applications:Native iOS and Android clients enable point-of-care documentation and patient engagement through smartphone interfaces.
Mature deployment sits with On-premise installations in restricted environments. Newer deployment is concentrated in Cloud-based platforms among cost-sensitive independent practices.
Solution Type:
Functional modules align with specific workflow automation priorities and reimbursement capture opportunities.
- Exercise Prescription:Motion capture integration and adherence tracking tools support remote therapeutic monitoring billing codes. Sports therapy facilities in the United States pilot these modules for Medicare reimbursement expansion, with kinematic data pipelines enabling outcomes documentation.
- Billing & Invoicing:Claims scrubbing, eligibility verification, and denial management form the most mature software category. Revenue cycle automation dominates procurement decisions for multi-site rehabilitation chains facing complex payer mix challenges.
- Patient Management:Electronic intake, consent capture, and communication portals streamline front-office operations.
- Scheduling:Calendar optimization and automated reminder systems reduce no-show rates across high-volume practices.
- Reporting & Analytics:Functional outcome dashboards and predictive risk stratification support value-based contract negotiation.
Margin pools are deepest in Billing & Invoicing due to mature feature commoditization. Steepest expansion trajectory belongs to Exercise Prescription as remote monitoring codes gain coverage.
End User:
Customer scale and affiliation status drive customization requirements and pricing tolerance.
- Outpatient Clinics:Independent physical therapy practices prioritize interoperable scheduling and billing with minimal IT overhead. Cloud-native platforms dominate this segment due to subscription affordability and automatic regulatory compliance.
- Rehabilitation Centers:Hospital-affiliated departments demand deep EMR integration and specialized workflow mapping for interdisciplinary care teams.
- Home Care Providers:Mobile-first documentation tools support therapists delivering services in patient residences.
- Sports Therapy Facilities:Performance optimization and return-to-play protocols differentiate requirements from medical rehabilitation.
- Military Healthcare:Department of Defense and Veterans Affairs installations impose data sovereignty and security classification mandates.
Procurement standardization is highest among Rehabilitation Centers with enterprise IT governance. Procurement flexibility concentrates in Outpatient Clinics with owner-operator decision structures.
Application:
Clinical indication determines documentation complexity and outcomes measurement protocols.
- Orthopedic Therapy:Post-operative protocols and joint replacement pathways generate structured assessment requirements. United States orthopedic practices drive demand for implant registry integration and bundled payment documentation.
- Neurological Rehabilitation:Stroke and traumatic brain injury programs require standardized functional independence measures with longitudinal tracking. Academic medical centers in Germany and the United States invest heavily in these specialized documentation tools.
- Post-surgical Rehabilitation:Procedure-specific protocols align with surgeon preferences and institutional pathways.
- Chronic Pain Management:Multidisciplinary care coordination and opioid monitoring compliance shape software requirements.
- Pediatric Therapy:Developmental milestone tracking and family engagement features address early intervention programs.
Documentation standardization is most advanced in Post-surgical Rehabilitation with protocol-driven care. Documentation complexity is expanding fastest in Neurological Rehabilitation as value-based contracts proliferate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Silicon Valley venture capital flows anchor software innovation for rehabilitation technology, with cloud infrastructure investments cascading through healthcare IT clusters worldwide. Regulatory divergence across jurisdictions fragments vendor certification pathways while creating acquisition arbitrage for compliant platforms.
United States
Medicare reimbursement rule changes for remote therapeutic monitoring compress vendor development timelines and accelerate replacement cycles among independent outpatient clinics. HIPAA security rules intersect with FDA software-as-medical-device oversight to create layered compliance obligations that extend certification timelines. The Dallas-Fort Worth metroplex hosts concentrated rehabilitation chain headquarters driving enterprise software procurement standardization.
Germany
The EU Medical Device Regulation reclassifies diagnostic and treatment planning software as Class IIa medical devices, imposing clinical validation requirements that stall smaller platform vendors. Notified body bottlenecks concentrate compliance expertise among larger rehabilitation chains seeking acquisition targets. The Munich-Stuttgart corridor anchors medical technology clusters where rehabilitation software vendors integrate with industrial automation expertise.
United Kingdom
NHS digitization mandates for allied health professions synchronize procurement timelines across hospital-affiliated rehabilitation departments. GDPR data processing requirements shape cloud deployment decisions for vendors serving European patient populations. London's health tech cluster concentrates startup activity in exercise prescription modules targeting private sports therapy facilities.
Japan
Aging demographic pressures expand rehabilitation service capacity while METI industrial policy promotes healthcare IT exports. PMDA software regulations create distinct certification pathways that favor domestic-vendor partnerships for international platforms. The Osaka-Kobe medical device corridor integrates physical therapy software with robotics rehabilitation systems for export markets.
India
Cost-sensitive outpatient clinic operators drive demand for lightweight mobile-first documentation tools with minimal IT overhead. CDSCO medical device regulations increasingly align with international standards, opening pathways for US and European vendor market entry. Bangalore's health tech startup ecosystem concentrates engineering talent for remote therapeutic monitoring feature development.
Global Physical Therapy Software Market Competitive Landscape
Global majors compete with regional champions across deployment model specialization and compliance certification depth. The vendor landscape organizes around three tiers: cloud-native platforms serving independent practices, enterprise suites for hospital-affiliated departments, and modular point solutions for exercise prescription. Strategic moves concentrate on interoperability certification investments and specialty-specific workflow customization capabilities.
Within the cloud-native tier, SimplePractice and WebPT exemplify domain-focused positioning through integrated telehealth and billing workflows designed for solo and small-group therapists. Net Health Systems anchors the enterprise-customization archetype with deep workflow mapping for hospital-affiliated rehabilitation departments. These three vendors collectively represent divergent responses to Medicare reimbursement compression and ONC certification mandates.
| Leading Market Players |
|---|
| SimplePractice |
| Net Health Systems |
| WebPT |
| SPRY PT |
| TheraPlatform |
| AdvancedMD |
| Clinicient |
| Noterro |
| Athenahealth |
| Others |
Supply & Pricing Matrix
Private-equity-rolled-up rehabilitation software specialists anchor supply concentration across cloud-native platform development, tightening pricing discipline through standardized subscription tiers while compressing margins for legacy on-premise vendors facing interoperability mandates.
Pricing Analysis
Warranty and implementation service bundling separates cloud-native SaaS tiers from unbundled legacy licensing models. Three-tier pricing structure across premium, standard, and economy levels dominates procurement, with differentiation driven by ONC certification completeness and customization depth. Pricing pressure stems from Medicare reimbursement compression forcing feature parity investments. Independent outpatient clinics exhibit highest price sensitivity, while hospital-affiliated rehabilitation departments tolerate premium tiers for deep EMR integration.
Supply Chain Analysis
Reverse-logistics flows for on-premise server refreshes and data migration services create secondary revenue streams for implementation partners. Engineering talent concentrates in the United States, India, and Germany, with cloud infrastructure services drawing from hyperscaler data center networks in these jurisdictions. Supply chain risk centers on single-source vulnerability for HL7 FHIR interoperability specialists. Distribution runs through direct sales teams for enterprise suites and self-service digital channels for independent practice segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a consolidation play where ONC certification mandates and dual FDA compliance timelines force weaker vendors into strategic exits or acquisition.
For Market Incumbents: Cement dominance through backward integration into proprietary exercise prescription engines and captive supply of HL7 FHIR implementation talent. Defensive positioning requires deepening workflow customization for hospital-affiliated rehabilitation departments while automating regulatory patch delivery for cloud-native subscribers. Threat from modular AI point-solution vendors demands accelerated R&D in kinematic data pipelines.
For New Entrants and Emerging Players: Capture white space in remote therapeutic monitoring code optimization for sports therapy facilities and motion-capture adherence tracking for orthopedic rehabilitation. Germany's EU MDR certification bottleneck presents the most penetrable geography for compliant platforms serving rehabilitation chains. Go-to-market leverage rests on outcomes-contingent pricing models tied to functional improvement metrics.
For Investors and Strategic Acquirers: Distressed-cycle entries favor European platforms with notified body relationships in Germany and France facing capital constraints from MDR compliance costs. Long-term viability centers on vendors with native analytics architectures supporting value-based reimbursement contracts. Watch CMS coverage determinations for additional remote therapeutic monitoring codes as the inflection signal for feature investment prioritization.
| Strategic Initiative | Industry Significance |
|---|---|
| ONC Certification Investment | FDA-aligned API standardization opens Medicare reimbursement pathways for connected rehabilitation tools. |
| Exercise Prescription Module Launch | Motion capture integration captures remote therapeutic monitoring code expansion in United States sports therapy. |
| Acquisition of European Compliant Platforms | Notified body relationships in Germany bypass MDR bottlenecks for rehabilitation chain penetration. |
| Strategic Partnership with Hyperscaler Cloud | Automatic HIPAA security patches reduce certification timeline burdens for mid-market practices. |
| Reimbursement Strategy Development | CMS code coverage expertise shapes product roadmaps for Medicare-dependent outpatient clinics. |
Research Methodology
Multi-period observation of vendor certification timelines, reimbursement code adoption curves, and platform replacement cycles anchored the trend analysis, supplemented by interviews with physical therapy practice owners, hospital rehabilitation department directors, health informatics specialists, and GPO contracts managers. Secondary validation drew from CMS Medicare reimbursement databases, ONC certification registries, FDA software-as-medical-device filings, and hyperscaler healthcare cloud expenditure disclosures. Bottom-up practice-level demand modeling and top-down vendor revenue triangulation refined segment weightings.
Segment-weighting approaches distributed value across deployment models, solution types, and end-user scales with regional adoption patterns calibrated to reimbursement environment maturity. CAGRs were derived from fitted growth curves against historical replacement cycle data and projected regulatory compliance deadlines. Forecast inputs incorporated remote therapeutic monitoring code coverage expansion scenarios and EU MDR certification bottleneck severity assumptions.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to CMS reimbursement policy reversals and FDA software classification precedents. Practitioners should monitor ONC interoperability rule enforcement intensity and notified body capacity expansion in Germany for early signals of competitive repositioning.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Health Solutions
Mhealth Services Market
Digital Health Solutions
Smart Cards in Healthcare Market
Digital Health Solutions
Global Patient Portal Market
Digital Health Solutions
Global Clinical Decision Support System Market
Digital Health Solutions
North America Patient Support Technology Market
Digital Health Solutions
UAE Mhealth Market
Digital Health Solutions
GCC E-Health Market
Digital Health Solutions
Digital Biomarkers Market
Digital Health Solutions
Smart Healthcare Market
Digital Health Solutions
Connected Health and Wellness Solutions Market
Digital Health Solutions
Asia-Pacific Heart Failure Software Market
Digital Health Solutions
AI in Patient Engagement Market
Digital Health Solutions
Asia-Pacific Eclinical Solutions Market
Digital Health Solutions
Medically Prescribed Apps Market
Digital Health Solutions
Electronic Data Capture Systems Market
Digital Health Solutions
Artificial Intelligence in Medicine Market