
 US Oral Solid Dosage Contract Manufacturing Market | 2026-2036
US Oral Solid Dosage Contract Manufacturing Market Size, Share, and Industry Trends Forecast 2026-2036
US Oral Solid Dosage Contract Manufacturing Market Insights
The gap between high-complexity modified-release formulations and standard immediate-release tablets is broadening. Catalent, Inc. leverages integrated development-to-commercialization pathways for sophisticated oral dosage forms. Lonza anchors its position through microbial and chemical API-to-dosage continuity. Patheon Pharma Services competes via global network density with substantial North American capacity.
US oral solid dosage contract manufacturing encompasses the outsourced production of tablets, capsules, powders, and granules through direct compression, wet granulation, dry granulation, or coating processes, typically achieving batch uniformity within tight weight-variation specifications for bioequivalence. The primary commercial purpose centers on enabling pharmaceutical sponsors to access validated manufacturing infrastructure without capital-intensive facility ownership. Tablets dominate current volume throughput due to established tooling flexibility and high-speed press economics, while capsule demand accelerates fastest among biotech sponsors seeking combination products with poorly soluble APIs. Wet granulation retains the largest installed base but continuous direct compression is displacing batch methods for high-volume generic programs.
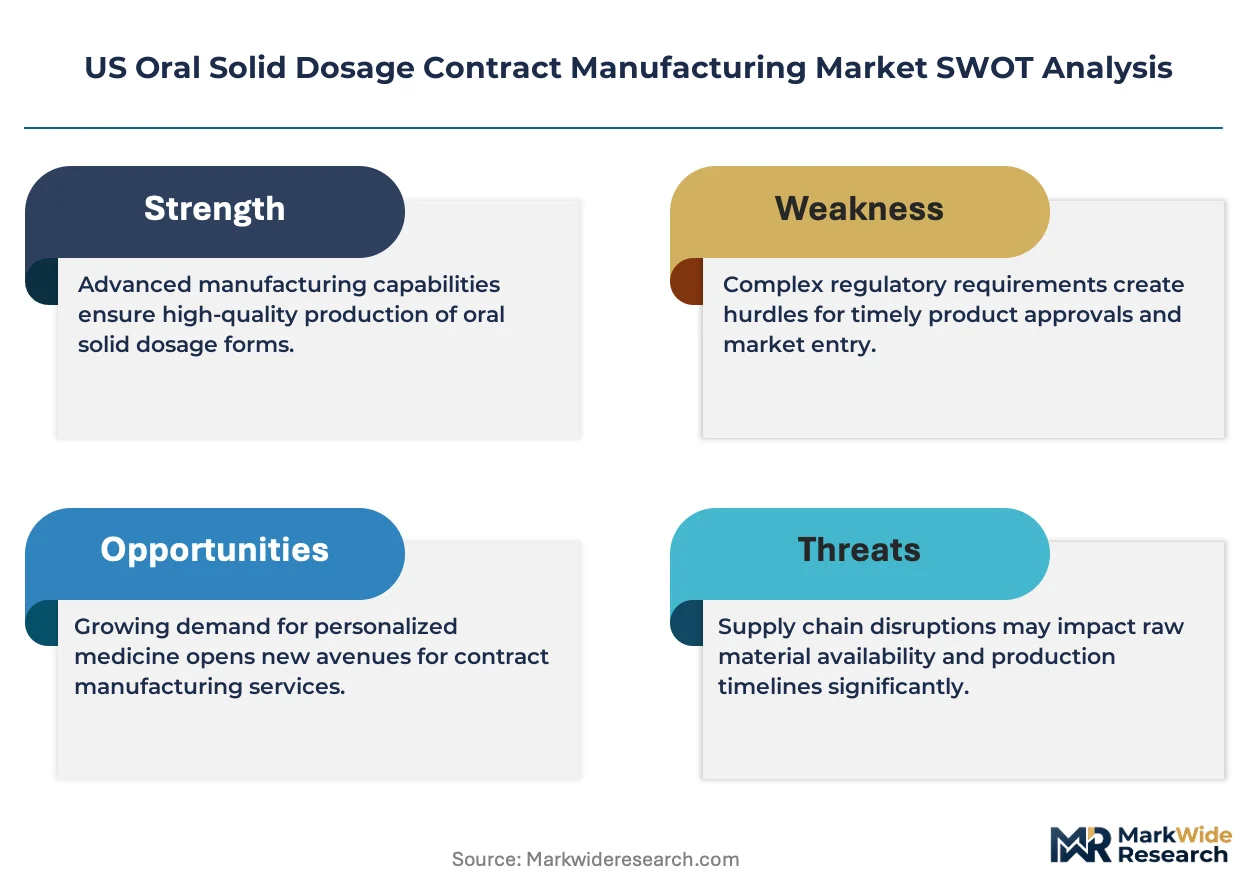
FDA Current Good Manufacturing Practice enforcement and USP dissolution standards shape facility qualification requirements, with OSHA process safety mandates adding operational compliance layers for potent compound handling. The Drug Enforcement Administration controls Schedule II through V substance scheduling, directly constraining production scheduling and site licensing for controlled-release oral solids. Stakeholders must monitor how FDA advanced manufacturing designations and IRA Medicare price negotiation timelines reshape sponsor outsourcing calculus.
Market Dynamics
Continuous manufacturing adoption is fragmenting the traditional batch-processing economics that long dominated US oral solid dosage production, forcing CDMOs to rebuild facility footprints around real-time release testing and modular production trains.
Growth Catalysts
- IRA Medicare Price Negotiation:The Inflation Reduction Act's pricing timelines are compressing sponsor commercialization schedules, accelerating outsourced manufacturing decisions to preserve capital for R&D.
- Specialty Biotech Pipeline:Emerging biotech sponsors with poorly soluble API portfolios are driving demand for high-complexity modified-release formulations requiring CDMO expertise.
- Northeast Corridor Cluster Density:Concentrated CDMO infrastructure across New Jersey and Pennsylvania reduces logistics costs and enables rapid tech transfer for innovator sponsors.
Market Restraints
- API Import Dependency:Reliance on offshore active pharmaceutical ingredient supply, particularly from India and China, exposes production schedules to customs delays and geopolitical friction.
- Controlled Substance Scheduling:DEA Schedule II through V licensing constraints create site-specific production bottlenecks and limit capacity allocation flexibility for opioid and stimulant formulations.
- Continuous Manufacturing Capex:Retrofitting legacy batch facilities with real-time process analytical technology requires capital outlays that strain mid-tier CDMO balance sheets.
Strategic Opportunities
- Advanced Manufacturing Designations:FDA Emerging Technology Program approvals are creating competitive moats for early adopters of continuous direct compression and 3D printing processes.
- Combination Product Convergence:Integration of drug-device combinations, particularly for oral films and orally disintegrating tablets, opens premium pricing segments beyond conventional solids.
- Midwest Capacity Gap:Underdeveloped CDMO infrastructure in Ohio and Illinois presents first-mover advantages for sponsors seeking geographic diversification beyond the Northeast corridor.
Industry Challenges
- Process Analytical Technology Talent:Scarcity of engineers trained in PAT implementation and multivariate data analysis is constraining continuous manufacturing scale-up timelines.
- Legacy Equipment Integration:Retrofitting existing batch suites with continuous processing skids requires complex validation protocols that extend facility qualification schedules.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US Oral Solid Dosage Contract Manufacturing Market |
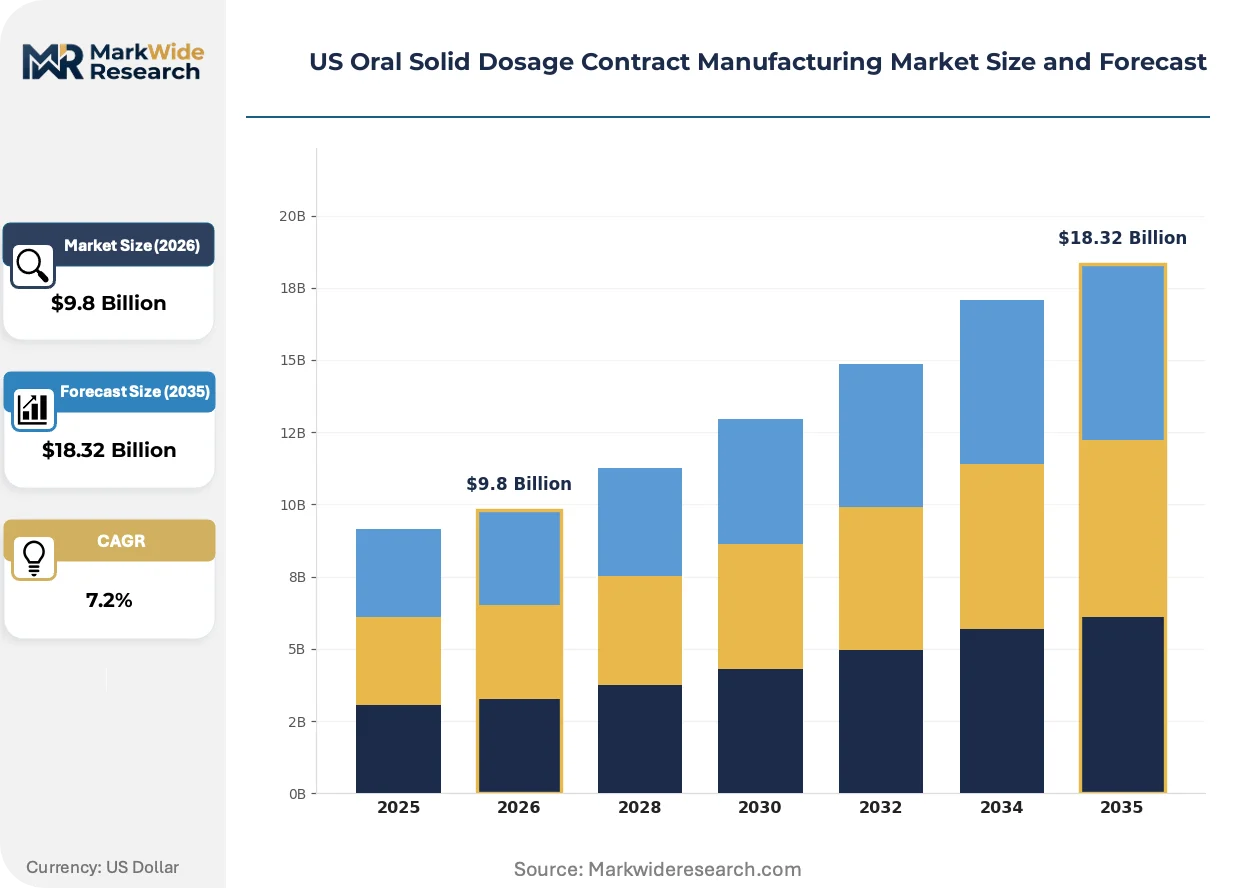
| Market Size in 2026 | $9.8 Billion |
| Market Size in 2035 | $18.32 Billion |
| CAGR (2026 – 2036) | 7.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Tablets, Capsules, Powders, Granules End User: Pharmaceutical Companies, Biotech Firms, Contract Research Organizations, Generic Drug Manufacturers Technology: Direct Compression, Wet Granulation, Dry Granulation, Coating Packaging Type: Blister Packs, Bottles, Sachets, Pouches |
| Companies Covered | Catalent, Inc., Lonza, Aenova Group, Patheon Pharma Services, Corden Pharma International, Jubilant Pharmova Limited, Boehringer Ingelheim International GmbH, Siegfried Holding AG, Recipharm AB, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US Oral Solid Dosage Contract Manufacturing Market Trends and Innovations
Digital twin modeling and real-time release testing are converging to compress batch release timelines from weeks to hours, fundamentally altering how sponsors evaluate CDMO partnerships and capacity commitments.
Continuous direct compression technology is decentralizing production economics away from high-volume, centralized batch facilities toward smaller, modular manufacturing trains that can be deployed closer to demand centers. Mid-sized generic sponsors are adopting these systems fastest, drawn by reduced working capital requirements and faster product changeovers. This distributed architecture is compressing the minimum efficient scale for viable oral solid manufacturing, enabling regional CDMOs to compete for programs previously reserved for national-scale operators.
FDA's advanced manufacturing designations under the Emerging Technology Program are accelerating regulatory pathways for sponsors deploying continuous processing and 3D-printed dosage forms. The agency's quality-by-design emphasis is shifting inspection protocols toward data integrity and process understanding rather than end-product testing alone. Oral solid CDMOs with validated continuous trains are securing preferential review timelines, particularly for complex modified-release formulations where batch-to-batch consistency is critical.
Biotech sponsors are consolidating procurement around integrated development-to-commercialization partnerships rather than transactional project-based contracting. This bundling is displacing traditional fee-for-service relationships with outcome-aligned fee structures that tie CDMO compensation to regulatory approval milestones and commercial launch success. The Northeast corridor, with its density of integrated CDMOs offering formulation through packaging services, is capturing the majority of these consolidated contracts.
US Oral Solid Dosage Contract Manufacturing Market Segmentation
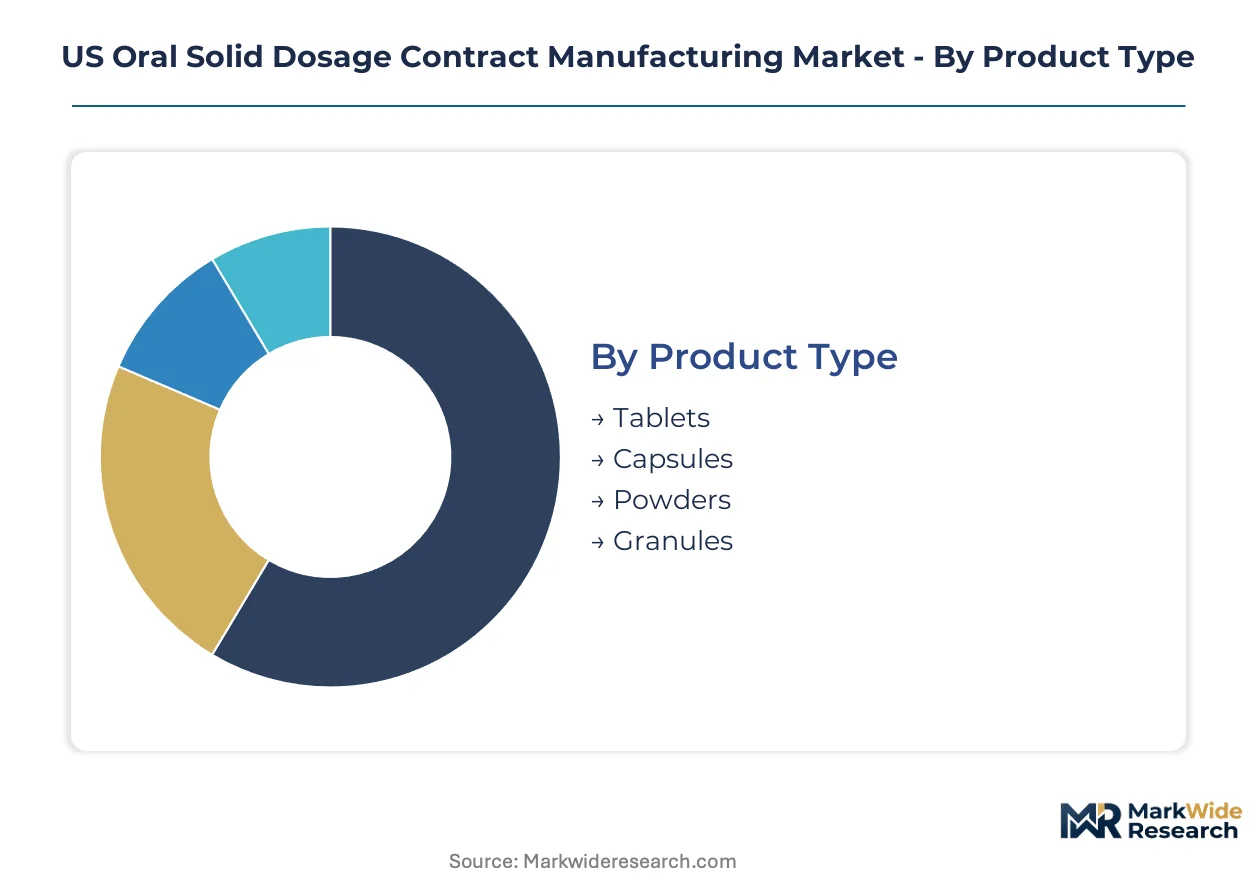
Segmentation in US oral solid dosage contract manufacturing reveals distinct procurement patterns across sponsor types, with complexity tolerance and volume scale driving CDMO selection criteria more than price alone. Understanding these divides enables manufacturers to align capacity investments with sponsor pipeline characteristics and FDA pathway requirements.
Product Type:
Form complexity separates sponsor segments by validation burden and equipment specialization needs.
- Tablets:Compressed solids formed through direct compression or granulation processes, accommodating diverse release profiles from immediate to extended. Demand concentrates among generic manufacturers in New Jersey and Pennsylvania pursuing high-volume, validated tooling economies for bioequivalence programs.
- Capsules:Gelatin or HPMC shells encapsulating powders, pellets, or liquids, enabling combination products with poorly soluble APIs. Biotech sponsors in the Northeast corridor are driving fastest adoption for modified-release formulations requiring CDMO expertise in pellet coating and multiparticulate systems.
- Powders:Fine particulate blends for reconstitution or direct administration, demanding containment infrastructure for potent compounds. Niche demand from specialty pharmaceutical sponsors with pediatric or geriatric dosage requirements.
- Granules:Agglomerated particles intermediate between powders and tablets, produced via wet or dry granulation for improved flow and compression. Serves sponsors requiring intermediate processing steps before final dosage form commitment.
Tablets lead volumes today; capsules are gaining share fastest.
End User:
Sponsor size and pipeline maturity determine outsourcing depth, from transactional manufacturing to integrated development partnerships.
- Pharmaceutical Companies:Large innovators with established FDA approval pathways, outsourcing to preserve capital for late-stage clinical programs. These sponsors prioritize CDMOs with demonstrated FDA inspection history and commercial-scale continuous manufacturing trains.
- Biotech Firms:Emerging sponsors with limited manufacturing infrastructure, requiring integrated formulation-through-commercialization partnerships. Northeast corridor CDMOs capture majority share through bundled service offerings and proximity to Boston and New York biotech clusters.
- Contract Research Organizations:Development-stage service providers extending into manufacturing through strategic CDMO alliances. Demand centers on rapid tech transfer capabilities and flexible batch sizing for clinical trial supply.
- Generic Drug Manufacturers:Cost-sensitive sponsors pursuing ANDA approvals, prioritizing high-throughput batch efficiency and validated bioequivalence data packages. Midwest capacity seekers represent emerging geographic diversification beyond traditional Northeast sourcing.
Pharmaceutical companies dominate contract value; biotech firms are expanding most quickly.
Technology:
Process selection reflects sponsor risk tolerance for regulatory novelty versus proven validation pathways.
- Wet Granulation:Liquid binder addition to powder blends followed by drying and milling, producing uniform granules for compression. Retains largest installed base among conservative sponsors avoiding continuous manufacturing validation risks.
- Direct Compression:Powder blending and immediate compression without granulation, suited for moisture-sensitive APIs. Continuous direct compression adoption is accelerating among generic sponsors seeking reduced working capital and faster changeovers.
- Dry Granulation:Mechanical compaction of powders into ribbons or slugs before milling, eliminating moisture exposure. Serves sponsors with heat- or moisture-labile actives requiring alternative agglomeration approaches.
- Coating:Functional or aesthetic film application to tablets or pellets, enabling modified-release profiles and moisture protection. Demand concentrates in modified-release programs requiring sophisticated pan or fluid bed coating expertise.
Wet granulation maintains the broadest deployment; continuous direct compression is climbing the fastest.
Packaging Type:
Packaging selection balances patient compliance requirements with supply chain durability and DEA controlled-substance security mandates.
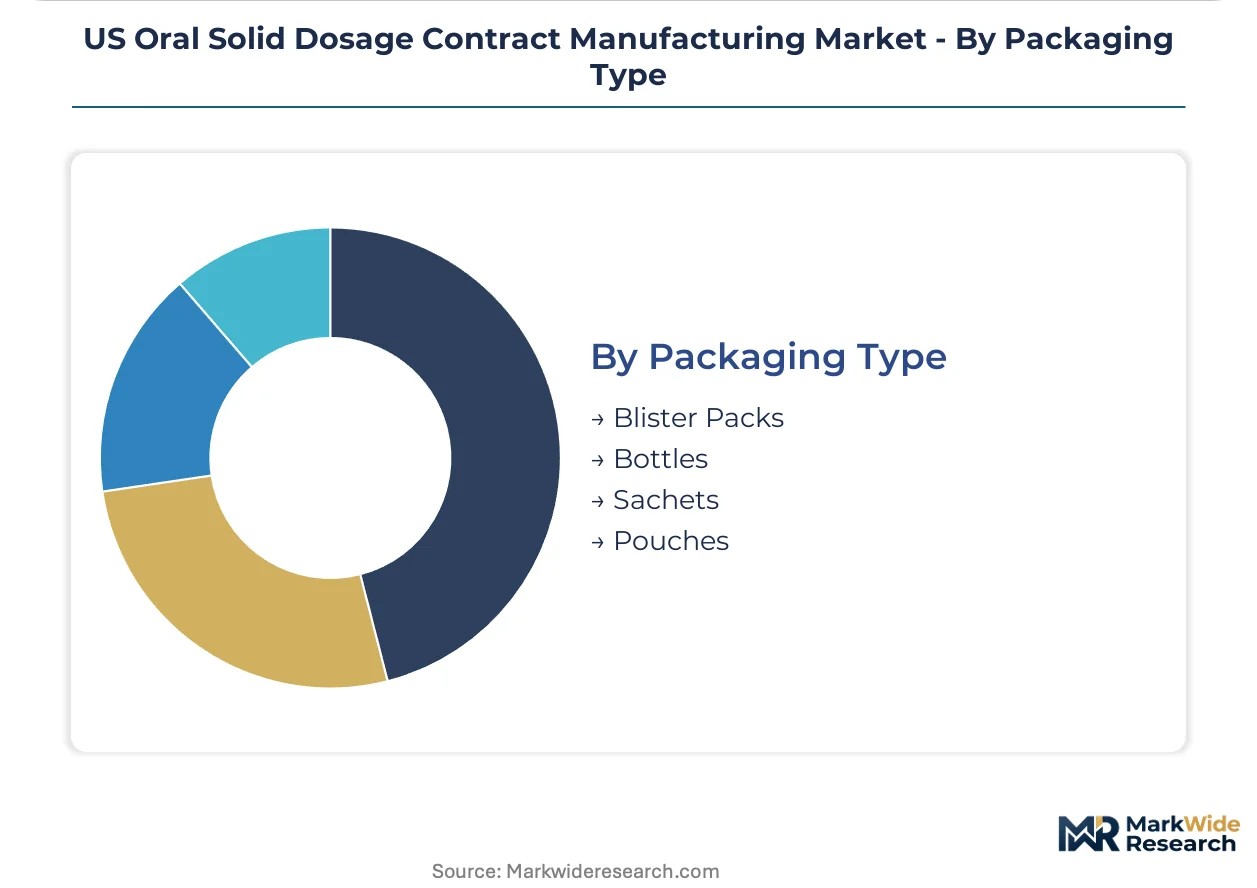
- Blister Packs:Pre-formed plastic or aluminum cavities with lidding foil, providing unit-dose compliance and tamper evidence. Dominates commercial prescription volumes through high-speed form-fill-seal automation and child-resistant senior-friendly designs.
- Bottles:Rigid containers with desiccant-cap closures, suited for bulk dispensing and long-term stability protection. Retail pharmacy and institutional channels prefer bottles for counting efficiency and label readability.
- Sachets:Small sealed pouches for single-dose powders or granules, enabling portability and precise dosing. Pediatric and over-the-counter segments drive demand for convenience-oriented formats.
- Pouches:Flexible multi-layer film containers for bulk powder or granule supply, reducing packaging material intensity versus rigid alternatives. Hospital and long-term care facilities favor pouches for unit-dose repackaging workflows.
Blister packs command the largest volume share; sachets are expanding most rapidly in patient-centric segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India and China dominate API supply for US oral solid dosage manufacturers, while domestic production concentrates in the Northeast corridor where CDMO infrastructure clusters around FDA inspection history and continuous manufacturing expertise.
New Jersey
Specialty pharmaceutical sponsors and generic manufacturers drive tablet and capsule demand across the state. FDA Current Good Manufacturing Practice enforcement shapes facility qualification timelines for Trenton and Princeton-area CDMOs. The Interstate 95 corridor hosts the densest concentration of validated continuous manufacturing trains serving innovator drug sponsors.
Pennsylvania
Biotech firms from Philadelphia and Pittsburgh outsource modified-release formulation development to regional CDMOs. OSHA process safety mandates add compliance layers for potent compound handling in southeastern counties. The Philadelphia suburbs anchor integrated development-to-commercialization partnerships spanning formulation through packaging.
Massachusetts
Cambridge and Boston biotech clusters generate demand for high-complexity multiparticulate systems and poorly soluble API formulations. The state's life sciences tax incentive programs support CDMO facility expansions in Worcester County. Route 128 corridor infrastructure enables rapid tech transfer from development labs to commercial-scale continuous direct compression lines.
North Carolina
Research Triangle Park pharmaceutical sponsors seek geographic diversification beyond Northeast sourcing for ANDA manufacturing programs. The state's workforce development initiatives train process analytical technology engineers for continuous manufacturing scale-up. RTP-area CDMOs compete on cost positioning for high-volume generic tablet programs.
Ohio
Midwest capacity gaps attract first-mover CDMO investments for sponsors seeking supply chain resilience outside coastal corridors. The state's manufacturing heritage supports equipment integration expertise for legacy batch facility retrofits. Cleveland and Cincinnati metropolitan areas develop underutilized industrial sites for modular continuous processing trains.
US Oral Solid Dosage Contract Manufacturing Market Competitive Landscape
Top-tier vendors anchor integrated development-to-commercialization pathways, while mid-tier specialists compete on formulation complexity and regional proximity. The market structure reflects consolidation around FDA inspection history and continuous manufacturing certification, with fragmentation persisting in batch-processing capacity for commodity generics. Three archetypes dominate: integrated global CDMOs with API-to-dosage continuity, regional specialists in modified-release technologies, and scale-driven generic manufacturers. Competitive moves center on strategic partnerships with biotech sponsors and selective capacity expansion in underpenetrated geographies.
Within the integrated global tier, Catalent, Inc. and Lonza occupy positions exemplifying end-to-end service bundling from preformulation through commercial supply. Patheon Pharma Services anchors a scale-driven archetype through network density and substantial North American capacity. These three entities represent contrasting strategic postures: development-centric partnership models, chemical and microbial API integration, and manufacturing footprint breadth.
| Leading Market Players |
|---|
| Catalent, Inc. |
| Lonza |
| Aenova Group |
| Patheon Pharma Services |
| Corden Pharma International |
| Jubilant Pharmova Limited |
| Boehringer Ingelheim International GmbH |
| Siegfried Holding AG |
| Recipharm AB |
| Others |
Pricing and Supply Chain Analysis
Biotech sponsors with limited manufacturing infrastructure concentrate procurement decisions among Northeast corridor CDMOs, anchoring pricing power in integrated development-to-commercialization bundles rather than transactional per-batch rates. This buyer concentration rewards service unbundling for commodity generics while penalizing mid-tier players lacking FDA advanced manufacturing designations.
Pricing Analysis
Unbundled fee-for-service contracts dominate generic manufacturer procurement, while integrated partnerships capture premium positioning among biotech sponsors. Pricing stratifies across FDA Emerging Technology Program certification, continuous manufacturing validation, and geographic proximity to Boston and New York clusters. Cost compression in standard immediate-release tablet programs is intensifying because ANDA sponsors prioritize high-throughput batch efficiency over formulation complexity. Generic drug manufacturers exhibit the highest price sensitivity; specialty pharmaceutical innovators seeking modified-release expertise demonstrate the lowest.
Supply Chain Analysis
Domestic-content mandates under FDA Current Good Manufacturing Practice enforcement are reshaping API sourcing away from offshore dependency. Active pharmaceutical ingredient supply draws from India, China, and domestic microbial fermentation capacity. Excipient and packaging component inputs rest on cellulose derivatives, gelatin, and aluminum foil supply. Single-source vulnerability concentrates in offshore API channels subject to customs delays and geopolitical friction. Distribution runs through direct sponsor-CDMO contractual relationships with limited third-party logistics intermediation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The US oral solid dosage contract manufacturing market reads as a late-cycle quality story, with sponsor demand shifting toward CDMOs possessing validated continuous manufacturing trains and FDA advanced manufacturing designations.
For Market Incumbents: Hedge against margin erosion in commodity immediate-release tablets by accelerating continuous direct compression certification through FDA's Emerging Technology Program. Anchor defensive positioning in the Northeast corridor through integrated formulation-to-packaging service bundles that emerging regional players cannot replicate without capital-intensive facility retrofits. For New Entrants and Emerging Players: The Inflation Reduction Act's Medicare price negotiation timelines in the United States opens a window for mid-tier CDMOs offering accelerated commercialization schedules to generic sponsors facing compressed launch windows. Target Ohio and Illinois for first-mover capacity advantages in geographic diversification away from coastal corridor concentration. Lead with modular continuous processing trains requiring lower capital deployment than legacy batch facility acquisitions. For Investors and Strategic Acquirers: Specialty pharmaceutical companies pursuing pipeline externalization are the most active acquirer in this space, seeking captive manufacturing capacity for complex modified-release programs. Long-term viability favors targets with validated PAT implementation and FDA inspection history over pure-play batch processors. Watch FDA advanced manufacturing designation awards as the signal for which CDMOs will secure preferential sponsor procurement consolidation.| Strategic Initiative | Industry Significance |
|---|---|
| FDA Emerging Technology Program Certification | Validates continuous manufacturing trains for preferential regulatory review timelines under FDA quality-by-design protocols. |
| Continuous Manufacturing Scale-Up | Reduces working capital requirements and accelerates product changeovers for generic sponsors facing IRA pricing pressure. |
| Integrated Development Partnership | Bundles formulation through commercialization to capture biotech sponsor procurement consolidation in the Northeast corridor. |
| Geographic Capacity Expansion | Addresses Midwest supply chain resilience demand from sponsors diversifying beyond New Jersey and Pennsylvania clusters. |
| Process Analytical Technology Investment | Enables real-time release testing that compresses batch release timelines from weeks to hours for competitive differentiation. |
Research Methodology
Coverage spans the United States with primary inputs from each major CDMO cluster, combining structured interviews with drug development executives, regulatory affairs leads, and formulary directors at biotech and pharmaceutical sponsors. Secondary validation draws from FDA filings, USP dissolution standards documentation, ClinicalTrials.gov protocol registries, and OSHA process safety enforcement records. Bottom-up capacity modeling triangulates against top-down sponsor outsourcing spend estimates.
Rate-of-change decomposition separates volume growth from pricing dynamics across the analysis window. Segmentation dimensions include product type complexity, sponsor archetype, manufacturing technology, and regional regulatory cluster. CAGRs derive from sponsor pipeline forecasting, ANDA approval velocity, and continuous manufacturing adoption curves. Industry-specific inputs incorporate DEA Schedule II through V licensing constraints and IRA Medicare price negotiation timeline impacts.
Forecast precision tightens around the base case; tail outcomes carry wider variance under FDA enforcement intensity shifts or API import disruption scenarios. Forecasts reflect assumptions regarding sponsor outsourcing propensity and continuous manufacturing scale-up timelines. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Oral Anti-Diabetic Drugs Market
Pharmaceuticals
Guaifenesin Market
Pharmaceuticals
HIV Antivirals Market
Pharmaceuticals
Antibody Therapy Market
Pharmaceuticals
Fucosidosis Therapeutics Market
Pharmaceuticals
Global Lifestyle Drugs Market
Pharmaceuticals
Global Gout Therapeutics Market
Pharmaceuticals
New Zealand Diabetes Drugs Market
Pharmaceuticals
Dual Migraine Treatment Market
Pharmaceuticals
Multiple System Atrophy (MSA) Therapeutics Market
Pharmaceuticals
Chemotherapy Induced Anemia Market
Pharmaceuticals
Global Thin Film Drugs Market
Pharmaceuticals
Large Molecule Contract Development and Manufacturing Organization Market
Pharmaceuticals
Global Pericarditis Drugs Market
Pharmaceuticals
Pharmacovigilance (PV) Market
Pharmaceuticals
Ramipril Market