
 Guaifenesin Market | 2026-2036
Guaifenesin Market Size, Share, and Industry Trends Forecast 2026-2036
Guaifenesin Market Analysis
Retail pharmacy consolidation is expanding as a buyer-concentration force across the guaifenesin supply base. Granules India Ltd. leverages its large-scale API manufacturing to serve contract manufacturing needs for North American distributors. Perrigo Company sustains its position through backward integration into generic formulation production and dominant shelf presence in major retail chains. Yuan Cheng Group anchors its competitiveness on cost-efficient bulk chemical synthesis exported to formulation houses worldwide.
Guaifenesin is a guaiacol glyceryl ether expectorant with the chemical formula C10H14O4, typically manufactured through etherification of guaiacol with glycerol using acid catalysis at controlled temperature and pressure, functioning primarily to thin bronchial secretions and facilitate mucus clearance in respiratory therapeutics. Tablet form dominates volume due to manufacturing simplicity and extended shelf stability, while extended release formulations command premium positioning through differentiated pharmacokinetic profiles and higher patient compliance rates. Combination therapy segments are gaining structural importance as fixed-dose pairings with dextromethorphan or pseudoephedrine expand formulary placements across hospital procurement systems.
The FDA maintains stringent monograph requirements for over-the-counter expectorant labeling and efficacy substantiation, while the EPA governs solvent discharge limits from guaiacol etherification facilities, and USP-NF standards define purity thresholds that determine batch release eligibility for pharmaceutical-grade material. These overlapping frameworks elevate compliance costs for smaller API producers and create barriers to market access for non-domestic suppliers lacking established regulatory dossiers. Stakeholders must monitor evolving monograph revisions and environmental enforcement intensity to anticipate shifts in viable supplier geography and product format prioritization.
Market Dynamics
Retail pharmacy consolidation concentrates buyer power across the guaifenesin supply base, forcing API manufacturers to absorb margin compression while meeting stricter private-label specifications. This structural concentration reshapes contract terms, batch sizing, and geographic sourcing priorities.
Growth Catalysts
- FDA OTC Monograph Modernization:The FDA's updated expectorant efficacy requirements accelerate reformulation investments, favoring suppliers with established bioequivalence dossiers.
- Respiratory Disease Prevalence:Chronic obstructive pulmonary disease and seasonal influenza patterns sustain baseline demand for mucolytic therapies in hospital and retail channels.
- Extended-Release Technology:Hydrophilic matrix tablet platforms enable once-daily dosing, improving patient adherence and commanding formulary preference.
Market Restraints
- Guaiacol Feedstock Volatility:Crude oil derivatives and forestry byproduct supply fluctuations destabilize etherification input costs.
- Indian API Dominance Risk:Granules India and a concentrated cluster of Hyderabad manufacturers control bulk chemical synthesis, creating single-geography dependency.
- Substitution by Acetylcysteine:Mucolytic alternatives with stronger antioxidant positioning erode guaifenesin's share in hospital procurement.
Strategic Opportunities
- Pediatric Liquid Formulations:Underpenetrated demand for alcohol-free, palatable expectorants in children ages 2-6 offers white space for taste-masked suspensions.
- Direct-to-Consumer Subscription:Amazon Pharmacy and CVS CarePass models enable recurring revenue capture outside traditional wholesale.
- EPA Green Chemistry Incentives:Solvent recovery and catalytic process innovations qualify for environmental tax credits, lowering compliance burden.
Industry Challenges
- USP-NF Purity Testing Bottlenecks:Chromatographic method validation delays extend batch release timelines by 15-30 days.
- Skilled Catalytic Chemist Shortage:Etherification process expertise concentrates among retiring specialists, constraining capacity expansion.
- Legacy Equipment Integration:Continuous manufacturing retrofits conflict with existing batch reactor infrastructure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Guaifenesin Market |
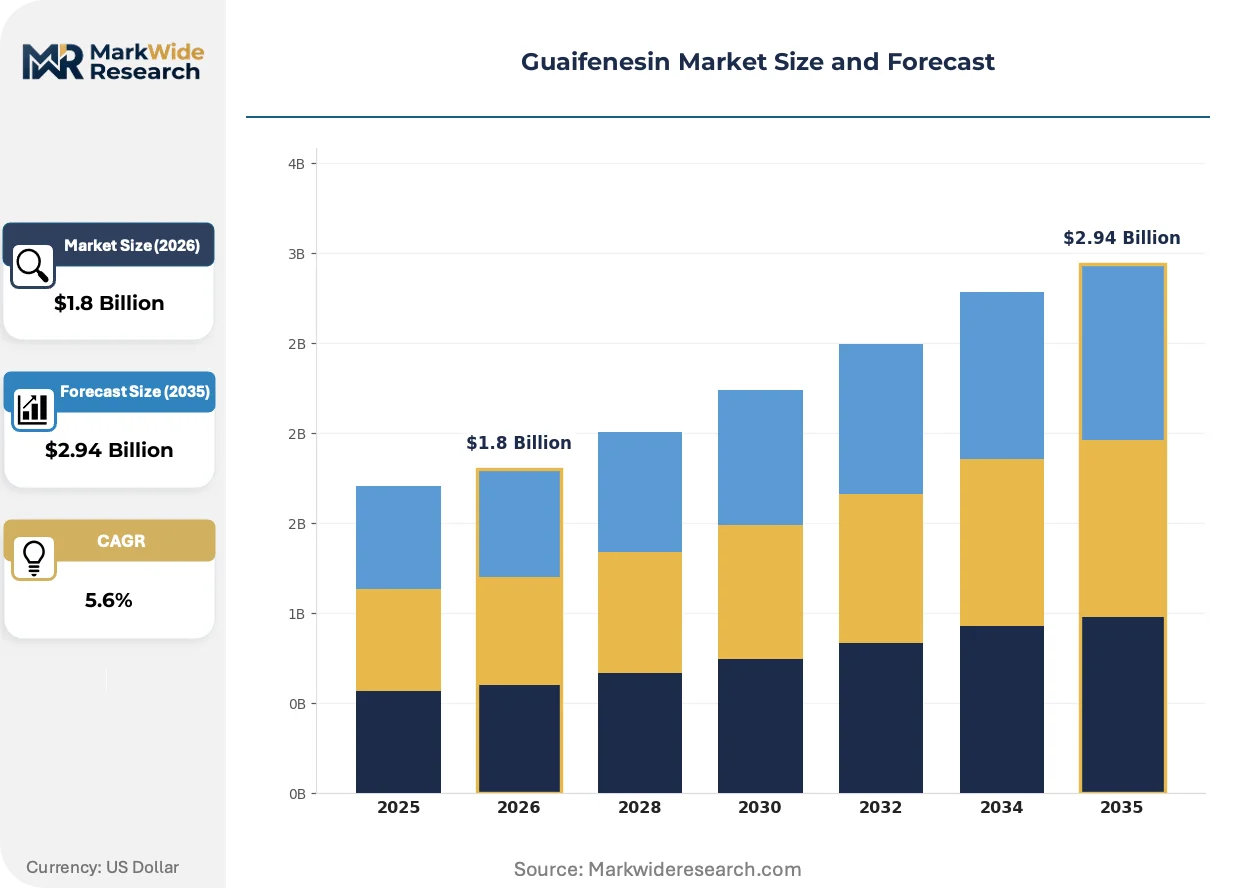
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.94 Billion |
| CAGR (2026 – 2036) | 5.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Liquid Form, Tablet Form, Capsule Form, Syrup End User: Pharmacies, Hospitals, Clinics, Online Retailers Packaging Type: Bottles, Blisters, Jars, Sachets Dose Form: Standard Dose, Extended Release, Combination Therapy, Children’s Dose |
| Companies Covered | Granules India Ltd., Perrigo Company, Stellar Chemical Pvt. Ltd., Haizhou Pharma Co. Ltd., Yuan Cheng Group, Seven Star Pharma Ltd., Biesterfeld AG, Synthokem Labs Pvt. Ltd., Gennex Lab, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Guaifenesin Market Emerging Trajectories
Formulation technology and regulatory stringency are converging to reshape competitive advantage in expectorant manufacturing, with differentiation shifting from cost to pharmacokinetic performance and environmental compliance.
Continuous direct compression is overtaking wet granulation as the dominant tablet manufacturing method for immediate-release guaifenesin. Contract manufacturers serving CVS Health and Walgreens Boots Alliance have adopted rotary press lines with real-time near-infrared monitoring. This technology is overtaking batch processing by compressing production cycle times from 48 hours to 6 hours while reducing solvent waste.
REACH Annex XVII restrictions on residual solvents are tightening specifications for glycerol etherification byproducts exported to EU formulation houses. The European Chemicals Agency's updated guidance on genotoxic impurities forces API producers to implement additional purification steps. German and French generic distributors now require certificates of analysis with sub-ppm solvent specifications that exceed USP-NF thresholds.
Hospital procurement committees are consolidating formularies around fixed-dose combinations, displacing single-ingredient guaifenesin SKUs. Pharmacy benefit managers at UnitedHealth and Cigna steer prescribing toward dextromethorphan-guaifenesin pairings through prior authorization design. This concentration is most visible in United States integrated delivery networks, where therapeutic interchange protocols mandate combination therapy first-line.
Guaifenesin Market Segmentation
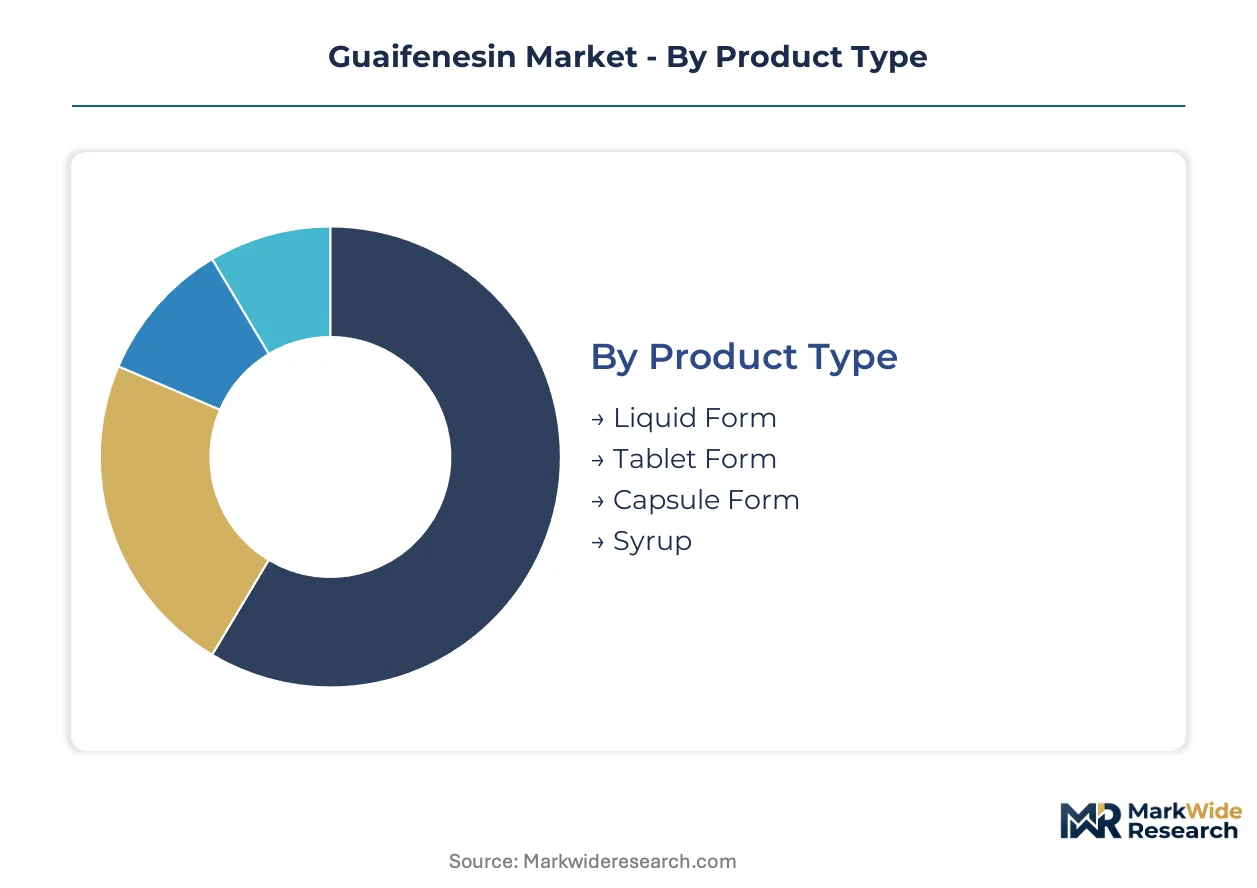
Guaifenesin demand fragments across formulation technologies, distribution channels, and patient populations. Upgrade cycles in manufacturing equipment and dosing convenience reshape competitive positioning within each slice.
Product Type:
Reformulation investments concentrate where manufacturing lines can pivot between immediate-release and modified-release outputs without full retooling.
- Liquid Form:Alcohol-free suspensions with taste-masking excipients serve pediatric populations ages 2-6. Demand concentrates in US pharmacy chains where private-label sourcing emphasizes palatability benchmarks over brand premiums.
- Tablet Form:Hydrophilic matrix platforms enable once-daily extended-release dosing. Hospital procurement committees in Germany and France prioritize these SKUs for formulary placement due to adherence advantages in chronic respiratory management.
- Capsule Form:Gelatin and HPMC shells accommodate moisture-sensitive API with desiccant integration. Niche positioning in Japanese retail pharmacy.
- Syrup:High-osmolality formulations with sucrose or sorbitol bases dominate over-the-counter cough and cold aisles. Volume concentration in North American mass merchandisers.
Tablet form sits at the top of the volume ranking, with liquid form climbing the fastest.
End User:
Channel consolidation and direct-to-consumer models redistribute margin capture away from traditional wholesale intermediaries.
- Pharmacies:CVS Health and Walgreens Boots Alliance drive private-label specification tightening. Shelf-space negotiations favor suppliers with backward integration into API production.
- Hospitals:Integrated delivery networks in the United States mandate therapeutic interchange protocols. Formulary committees steer prescribing toward fixed-dose combinations through prior authorization design.
- Clinics:Urgent care chains and respiratory specialty practices stock single-ingredient guaifenesin for diagnostic clarity. Regional concentration in Texas and Florida metro corridors.
- Online Retailers:Amazon Pharmacy and CVS CarePass subscription models enable recurring revenue capture. Logistics infrastructure favors manufacturers with direct fulfillment capabilities.
Pharmacies anchor absolute volume, with online retailers expanding most quickly.
Packaging Type:
Child-resistant and senior-friendly compliance standards drive material selection and line-speed investments.
- Bottles:HDPE containers with tamper-evident closures dominate liquid and syrup formats. US EPA guidelines on plastic resin sourcing influence supplier qualification.
- Blisters:Cold-form aluminum and PVC/PVDC laminates protect moisture-sensitive tablets. European REACH Annex XVII restrictions on residual solvents tighten specifications for imported stock.
- Jars:Wide-mouth PET containers serve bulk institutional packaging. Concentration in hospital system central pharmacies.
- Sachets:Single-unit foil pouches enable portability and dose precision. Growth in direct-to-consumer trial packs and travel-size SKUs.
Bottles lead volume rankings, with sachets gaining share fastest.
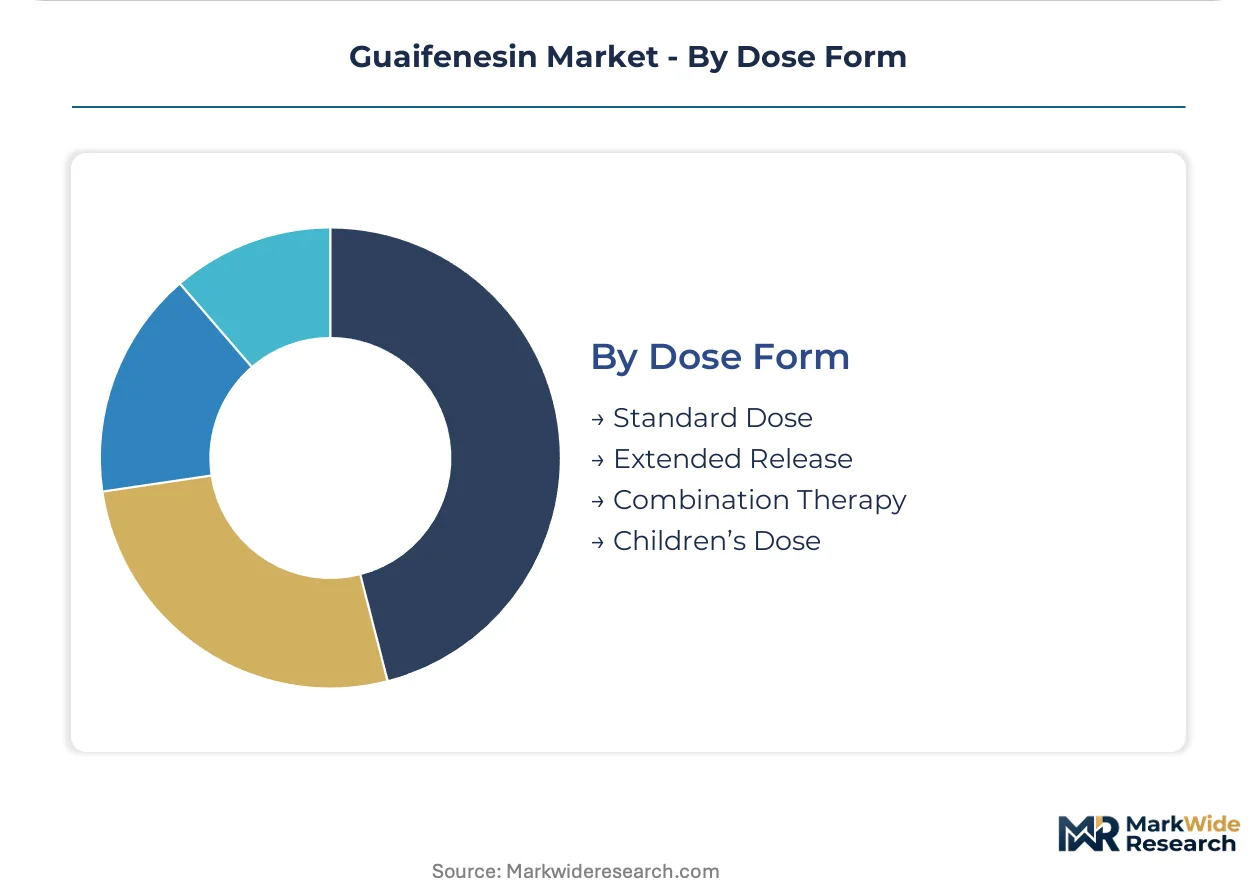
Dose Form:
Pharmacokinetic differentiation and combination therapy protocols reshape R&D prioritization and bioequivalence investment.
- Standard Dose:Immediate-release 200mg and 400mg tablets manufactured through direct compression. Cost-efficient positioning in generic substitution markets.
- Extended Release:600mg and 1200mg matrix tablets with HPMC or carbomer gelling systems. FDA bioequivalence requirements favor suppliers with established dissolution profile dossiers.
- Combination Therapy:Fixed-dose pairings with dextromethorphan or pseudoephedrine displace single-ingredient SKUs. Pharmacy benefit managers at UnitedHealth and Cigna steer prescribing through prior authorization.
- Children's Dose:Weight-calibrated liquids with calibrated dosing cups. Underpenetrated white space for alcohol-free, dye-free formulations in ages 2-6.
Standard dose holds volume leadership, with combination therapy climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States pharmacy chains command higher private-label specifications than German hospital procurement committees, yet both markets enforce solvent purity thresholds that reshape supplier qualification. This divergence in channel concentration versus formulary consolidation creates distinct competitive arenas across major economies.
United States
CVS Health and Walgreens Boots Alliance drive private-label consolidation for guaifenesin tablets and liquids. FDA OTC monograph modernization accelerates reformulation investments among API suppliers seeking bioequivalence dossier approval. New Jersey and Pennsylvania host contract manufacturing clusters serving mass merchandiser shelf-space negotiations.
Germany
Hospital procurement committees in Bavaria and North Rhine-Westphalia prioritize extended-release guaifenesin for chronic respiratory management. ECHA REACH Annex XVII restrictions on residual solvents tighten import specifications beyond USP-NF thresholds. Frankfurt-based generic distributors now require sub-ppm solvent certificates for API batch release.
India
Hyderabad and Visakhapatnam concentrate guaifenesin API synthesis for North American contract manufacturing. CDSCO manufacturing facility inspections align with FDA data integrity expectations for export-oriented producers. Andhra Pradesh's bulk chemical parks absorb margin compression from concentrated buyer power abroad.
China
Yuan Cheng Group anchors cost-efficient bulk synthesis exported to formulation houses worldwide. NMPA environmental compliance audits intensify for guaiacol etherification facilities in Jiangsu and Zhejiang provinces. Yangtze River Delta chemical parks invest in catalytic process recovery systems to qualify for green chemistry incentives.
Japan
PMDA-approved HPMC capsule formulations serve moisture-sensitive API niches in Tokyo and Osaka retail pharmacy. METI industrial standards for pharmaceutical excipients elevate purification step requirements. Kanto region formulation specialists integrate desiccant technologies for humidity-stable finished goods.
Guaifenesin Market Vendor Landscape
Diversified conglomerates compete with focused pure-play specialists across the guaifenesin supply base. Tiered market structure separates backward-integrated API manufacturers from formulation-dependent distributors. Three archetypes dominate: large-scale Indian API producers, North American private-label specialists, and Chinese bulk chemical exporters. Capacity expansion and regulatory dossier accumulation represent the dominant competitive moves.
Among Indian API manufacturers, Granules India Ltd. and Stellar Chemical Pvt. Ltd. exemplify scale-driven contract supply positions. Perrigo Company occupies a position within North American private-label distribution. Yuan Cheng Group represents cost-anchored bulk synthesis export competitiveness. These three entities illustrate the geographic and functional segmentation pressuring mid-tier European and North American suppliers.
| Leading Market Players |
|---|
| Granules India Ltd. |
| Perrigo Company |
| Stellar Chemical Pvt. Ltd. |
| Haizhou Pharma Co. Ltd. |
| Yuan Cheng Group |
| Seven Star Pharma Ltd. |
| Biesterfeld AG |
| Synthokem Labs Pvt. Ltd. |
| Gennex Lab |
| Others |
Supply Flow & Price Mechanics
Guaiacol spot prices on specialty chemical indices cascade through etherification costs into finished API tiers, with bulk chemical exporters absorbing volatility while formulation houses pass through specification premiums to pharmacy chains.
Pricing Analysis
Capacity additions in China are reshaping price floors for pharmaceutical-grade guaifenesin API. Three-tier pricing structure across premium, standard, and economy levels separates FDA-registered suppliers from CDSCO-certified exporters and non-dossier bulk traders. Cost compression in standard-tier tablet formulations is intensifying because CVS Health and Walgreens Boots Alliance consolidate private-label sourcing. Hospital procurement committees demonstrate least price sensitivity due to formulary lock-in, while independent pharmacies face margin pressure from generic substitution mandates.
Supply Chain Analysis
Domestic-content mandates in Indian pharmaceutical parks are reshaping sourcing patterns for North American contract manufacturers. API synthesis concentrates in India, China, and the United States, with Hyderabad and Visakhapatnam clusters feeding formulation houses in New Jersey and Pennsylvania. Etherification draws from guaiacol feedstocks, glycerol derivatives, and acid catalysts, creating exposure to crude oil derivative volatility. Single-source vulnerability runs through concentrated Hyderabad API manufacturing. Distribution runs through wholesale distributors to retail pharmacy chains and direct-to-consumer subscription platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in guaifenesin manufacturing rests on hydrophilic matrix technology premiums and solvent recovery tax credits lowering compliance burdens.
For Market Incumbents: Deepen backward integration into guaiacol etherification to defend against Indian API dominance risk. Invest in continuous direct compression lines with real-time near-infrared monitoring to compress cycle times from 48 hours to 6 hours. Lock in multi-year private-label contracts with CVS Health and Walgreens Boots Alliance before FDA monograph modernization raises bioequivalence dossier barriers. For New Entrants and Emerging Players: Amazon Pharmacy subscription models offer the most penetrable channel for direct-to-consumer recurring revenue capture. Target pediatric liquid formulations ages 2-6 with alcohol-free, taste-masked suspensions where demand remains underpenetrated. Pursue EPA green chemistry incentives through catalytic process innovations to offset capital intensity disadvantages against established API producers. For Investors and Strategic Acquirers: Asymmetric upside sits with contract manufacturers holding FDA bioequivalence dossiers for extended-release 600mg and 1200mg matrix tablets. Five-to-ten-year viability favors suppliers with backward integration into API production and direct fulfillment capabilities for online retail channels. Watch for FDA OTC monograph modernization implementation as the inflection signal for dossier-deficient supplier exits.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into API Synthesis | Captures etherification margins and insulates against guaiacol feedstock volatility from crude oil derivatives. |
| Extended-Release Technology Investment | Hydrophilic matrix platforms command formulary preference through once-daily dosing adherence advantages. |
| Direct-to-Consumer Subscription Launch | Amazon Pharmacy and CVS CarePass models enable recurring revenue outside wholesale margin compression. |
| EPA Green Chemistry Certification | Solvent recovery systems qualify for environmental tax credits lowering compliance cost burdens. |
| Pediatric Formulation Development | Alcohol-free suspensions ages 2-6 address underpenetrated white space with palatability differentiation. |
Methodological Framework
Coverage spans North America, Europe, and Asia-Pacific, with primary inputs from each region combined with secondary validation. Interviews with API manufacturing executives, regulatory affairs leads at CDSCO and FDA-registered facilities, hospital formulary directors, and pharmacy chain procurement managers triangulate against customs data, SEC 10-K pharmaceutical filings, EPA environmental compliance records, and USP-NF monograph databases. Bottom-up volume modeling and top-down value reconciliation cross-validate segment outputs.
Rate-of-change decomposition separates volume growth from mix-shift effects across the projection horizon. Segmentation dimensions include formulation technology, distribution channel, dose form, and regional regulatory cluster. CAGRs derive from weighted average of historical trajectory and forward-looking capacity expansion schedules. Forecast inputs incorporate FDA monograph modernization timelines and ECHA REACH Annex XVII solvent specification tightening.
Revisions become necessary when FDA bioequivalence requirement changes, guaiacol feedstock price shocks, or Indian API manufacturing disruption materialize. Forecasts reflect documented assumptions about pharmacy chain consolidation pace and extended-release formulary adoption curves. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Throat Sprays Market
Pharmaceuticals
Blood Coagulants Market
Pharmaceuticals
Tranquilizer Drugs Market
Pharmaceuticals
Global Bronchodilators Market
Pharmaceuticals
Global Antacids Market
Pharmaceuticals
Topical Acne Medication Market
Pharmaceuticals
Europe Dipeptide Peptidase 4 (DPP-4) Inhibitors Market
Pharmaceuticals
India Pharmaceutical Contract Sales Organizations Market
Pharmaceuticals
Multiple Myeloma Drugs Market
Pharmaceuticals
Europe Anesthesia Drugs Market
Pharmaceuticals
Global Human Rotavirus Vaccine Market
Pharmaceuticals
Antidiarrhoeal Market
Pharmaceuticals
Global Specialty Pharmaceuticals Market
Pharmaceuticals
Nicorandil Market
Pharmaceuticals
Decongestants Market
Pharmaceuticals
Xerostomia Therapeutics Market