
 Global Thin Film Drugs Market | 2026-2036
Global Thin Film Drugs Market Size, Share, and Industry Trends Forecast 2026-2036
Global Thin Film Drugs Market Foresight
Pharmacy distribution networks for thin film formulations is tilting toward specialized treatment centers and mail-order channels. Pfizer leverages its manufacturing scale to supply oral thin film platforms across multiple therapy areas. Aquestive Therapeutics anchors its position through proprietary PharmFilm technology and partnerships with central nervous system drug developers. Indivior dominates the sublingual buprenorphine film segment through channel control and regulatory exclusivity in addiction medicine.
Thin film drugs are polymeric dosage forms, typically 50 to 500 microns thick, engineered to dissolve on mucosal surfaces or permeate skin barriers for systemic drug delivery. These formulations employ hydrophilic polymers such as pullulan, hydroxypropyl methylcellulose, or polyvinylpyrrolidone as film-forming matrices, with active pharmaceutical ingredients dispersed or layered within the matrix to achieve rapid onset or sustained release profiles. Orally disintegrating films lead product type volume due to pediatric and geriatric compliance advantages, while buccal films capture premium margins through enhanced bioavailability for poorly soluble compounds. Neurology commands the largest therapy area share driven by anti-addiction and antiemetic applications, with cardiovascular films representing the fastest-expanding segment as manufacturers develop nitroglycerin and antihypertensive transdermal alternatives.
The FDA maintains stringent dissolution and bioequivalence requirements for abbreviated new drug applications referencing listed thin film products, while the EMA's MDR and REACH frameworks govern polymer excipient safety and device-drug combination classifications in Europe. WHO prequalification standards increasingly influence procurement decisions for HIV and malaria thin film therapies in low-income markets. Stakeholders must monitor evolving pharmacopeial monographs for novel excipients and prepare for region-specific stability testing protocols as regulatory divergence between FDA and EMA pathways widens.
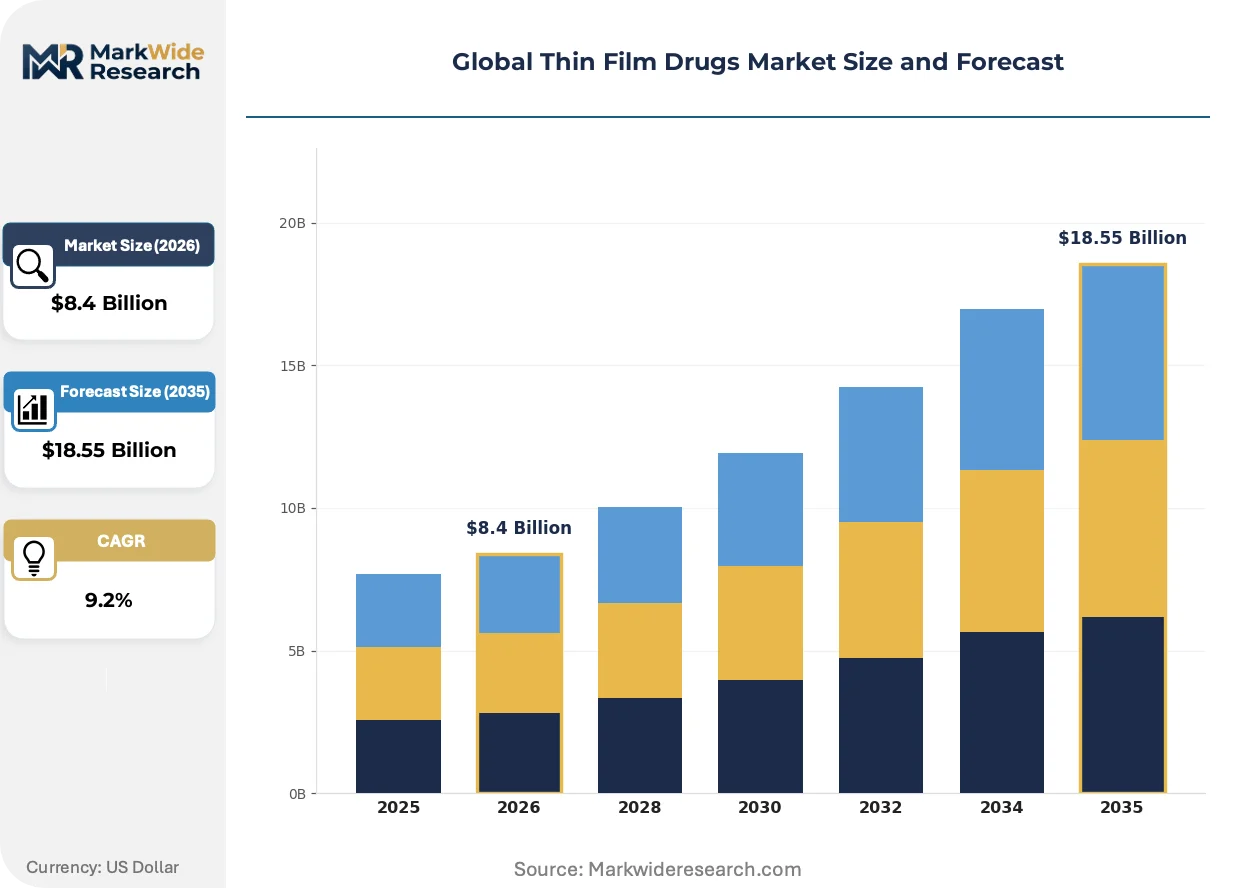
Market Dynamics
FDA bioequivalence tightening for novel dosage forms is compressing development timelines while forcing manufacturers to invest in specialized dissolution testing infrastructure ahead of abbreviated new drug application submissions.
Growth Catalysts
- REACH polymer safety frameworks:ECHA classification of hydrophilic film-forming excipients as device-drug combinations is clarifying regulatory pathways and accelerating European market entry for buccal film developers.
- Pediatric compliance advantages:Orally disintegrating films eliminate swallowing difficulties in geriatric and pediatric populations, expanding addressable patient pools for chronic neurological therapies.
- Specialized treatment center concentration:United States addiction medicine clinics are driving prescription volume for sublingual anti-addiction films through controlled distribution networks and prescriber certification programs.
Market Restraints
- Pullulan supply concentration:Film-forming polymer production concentrates in Southeast Asian agricultural processing regions, exposing manufacturers to crop yield volatility and input cost spikes.
- MDR device classification friction:EMA's Medical Device Regulation creates ambiguous boundaries between drug and device oversight for transdermal films, extending approval timelines and legal consultation costs.
- Conventional tablet substitution:Generic immediate-release oral solids maintain formulary preference in cost-sensitive markets, limiting thin film penetration in cardiovascular and pain management segments.
Strategic Opportunities
- Brazil chronic disease expansion:ANVISA streamlined pathways for fixed-dose combination films targeting hypertension and diabetes are opening Latin America's largest pharmaceutical market to transdermal antihypertensive developers.
- Mail-order channel maturation:Direct-to-patient distribution models bypass traditional pharmacy networks, capturing margin and adherence data for sublingual addiction therapy prescribers.
- ISO pharmacopeial convergence:WHO prequalification standards for HIV and malaria thin film therapies are harmonizing stability testing protocols, enabling single-registration multi-market access in low-income regions.
Industry Challenges
- Dissolution method development talent scarcity:Specialized analytical chemists capable of designing FDA-acceptable in vitro release tests for mucosal films command premium compensation and extended recruitment cycles.
- Excipient-master-file coordination complexity:Polymer supplier Type II DMF amendments require synchronized timing with sponsor ANDA submissions, creating documentation synchronization risks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Thin Film Drugs Market |
| Market Size in 2026 | $8.4 Billion |
| Market Size in 2035 | $18.55 Billion |
| CAGR (2026 – 2036) | 9.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Orally Disintegrating Films, Buccal Films, Sublingual Films, Transdermal Films, Vaginal Films Therapy Area: Neurology, Cardiovascular, Oncology, Dermatology, Respiratory Administration Route: Oral, Topical, Vaginal, Intraoral, Nasal End User: Pharmacies, Hospitals, Clinics, Specialized Treatment Centers |
| Companies Covered | Pfizer, Novartis AG, Aquestive Therapeutics, AbbVie, ZIM Laboratories Limited, IntelGenx Corp, Indivior, Solvay, Tesa Labtec, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Thin Film Drugs Market Shifts & Advancements
Formulation science is converging with digital health infrastructure to create dose-verifiable thin film systems, while regulatory divergence between FDA and EMA pathways is fragmenting development strategies.
Multilayer film architectures are hybridizing rapid-dissolve surface layers with sustained-release substructures to achieve pulsatile pharmacokinetic profiles. CNS drug developers are adopting these platforms for addiction therapies requiring both immediate craving suppression and extended maintenance dosing. This hybridizing capability is compressing the competitive window for conventional oral dosage forms in neurological applications.
EMA's MDR and REACH frameworks are tightening polymer excipient safety documentation requirements for device-drug combination classifications. European manufacturers are restructuring supply chains to secure ECHA-registered hydroxypropyl methylcellulose grades with full toxicological dossiers. Buccal film segments face the steepest compliance cost escalation as notified body involvement becomes mandatory for higher-risk classifications.
Patient-administered dosing verification through smartphone-connected packaging is displacing traditional pharmacy-based adherence monitoring. Addiction medicine prescribers in United States specialized treatment centers are piloting digital companion systems for sublingual buprenorphine films. Germany and Australia are emerging as secondary adoption markets where reimbursement authorities are testing outcome-linked payment models for digitally enabled therapy regimens.
Global Thin Film Drugs Market Segmentation
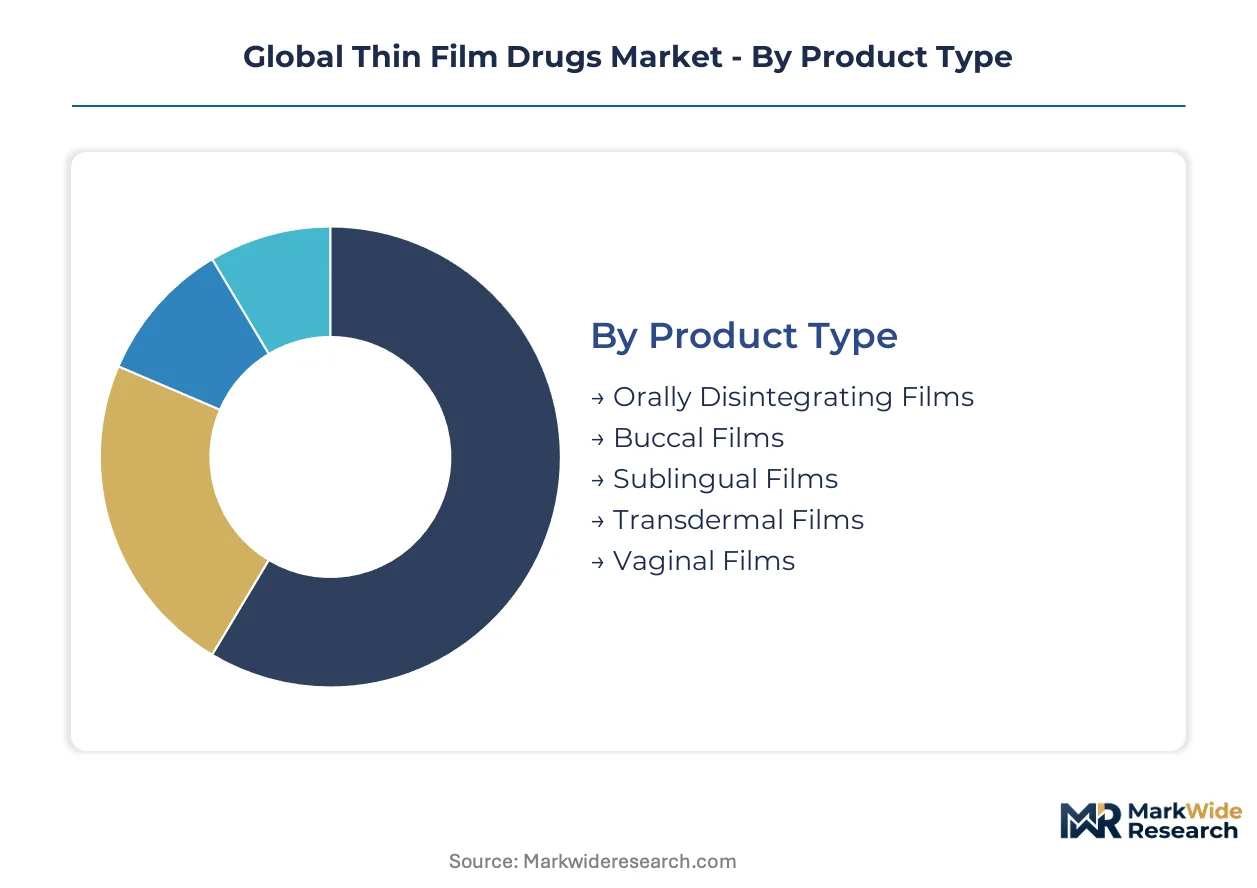
Thin film drug manufacturers compete across distinct technical platforms and clinical settings. Each segment demands specialized polymer matrices, dissolution profiles, and regulatory pathways that reshape competitive positioning and margin structure.
Product Type:
Use-case spectrum spans rapid symptom relief through sustained transdermal delivery, with mucosal and dermal absorption kinetics driving formulation complexity and pricing tiers.
- Orally Disintegrating Films:Hydrophilic polymer matrices of pullulan or hydroxypropyl methylcellulose dissolve within seconds on the tongue, bypassing gastrointestinal degradation. Pediatric and geriatric populations in United States long-term care facilities drive prescription volume for antiemetic and neurological applications. Established volume favors orally disintegrating films; emerging adoption favors sublingual films.
- Buccal Films:Adhesive layers adhere to the buccal mucosa for 15-30 minutes, enabling direct systemic absorption of poorly soluble compounds. European CNS drug developers leverage these platforms for enhanced bioavailability in anti-addiction therapies under EMA device-drug combination frameworks.
- Sublingual Films:Ultra-rapid dissolution beneath the tongue delivers immediate plasma concentration spikes for craving suppression. United States specialized treatment centers dominate prescription volume through controlled distribution networks for buprenorphine-based addiction medicine.
- Transdermal Films:Multi-layer polymer constructions with rate-controlling membranes provide 24-72 hour sustained release. Cardiovascular applications in nitroglycerin and antihypertensive delivery are expanding most quickly as manufacturers develop alternative routes to oral solids.
- Vaginal Films:Bioadhesive formulations target local or systemic delivery for hormonal and antimicrobial therapies. HIV prevention research programs in low-income markets are piloting pre-exposure prophylaxis applications under WHO prequalification standards.
Margin concentration aligns with bioavailability enhancement difficulty; buccal and sublingual platforms command premium positioning over conventional oral routes.
Therapy Area:
Clinical application diversity stretches from emergency craving suppression to chronic disease maintenance, with regulatory intensity varying by therapeutic risk classification.
- Neurology:Anti-addiction films and antiemetic formulations lead prescription volume through non-invasive delivery advantages. United States addiction medicine clinics generate concentrated demand for sublingual buprenorphine products through prescriber certification requirements.
- Cardiovascular:Transdermal nitroglycerin and antihypertensive alternatives are gaining share fastest as clinicians seek adherence improvements over oral solid regimens. ANVISA streamlined pathways in Brazil are accelerating market entry for fixed-dose combination films.
- Oncology:Mucosal films deliver breakthrough cancer pain management and chemotherapy-induced nausea control. Formulation challenges center on stability of cytotoxic agents within hydrophilic polymer matrices.
- Dermatology:Topical films provide localized corticosteroid and antimicrobial delivery with occlusion benefits. European REACH compliance costs for polymer excipients are reshaping supplier qualification requirements.
- Respiratory:Nasal and oral thin films target allergic rhinitis and smoking cessation through rapid mucosal absorption. Pediatric compliance advantages expand addressable patient pools for seasonal allergy therapies.
Neurology anchors current revenue concentration; cardiovascular applications are climbing the fastest as transdermal technology matures.
Administration Route:
Patient capability and clinical setting determine route selection, with self-administration potential driving preference toward non-invasive alternatives.
- Oral:Encompasses both rapid-disintegrating tongue films and slower-dissolving buccal formulations. Geriatric populations in Japan and Germany favor these platforms for chronic neurological maintenance dosing.
- Topical:Transdermal patches and films require intact skin surfaces and patient education on rotation protocols. Cardiovascular applications in United States mail-order channels are expanding patient self-management capabilities.
- Vaginal:Self-inserted films target localized hormonal delivery and antimicrobial prophylaxis. Reproductive health programs in low-income regions are evaluating HIV prevention film distribution under WHO guidelines.
- Intraoral:Sublingual and buccal absorption bypass hepatic first-pass metabolism for immediate systemic effect. Addiction medicine protocols in Australia and Germany are piloting digital adherence monitoring for these routes.
- Nasal:Rapid absorption through olfactory mucosa enables emergency intervention and vaccine delivery. Respiratory allergy applications are expanding in European markets with seasonal prescription patterns.
Intraoral routes concentrate in controlled clinical settings; oral and topical alternatives dominate retail pharmacy and mail-order distribution.
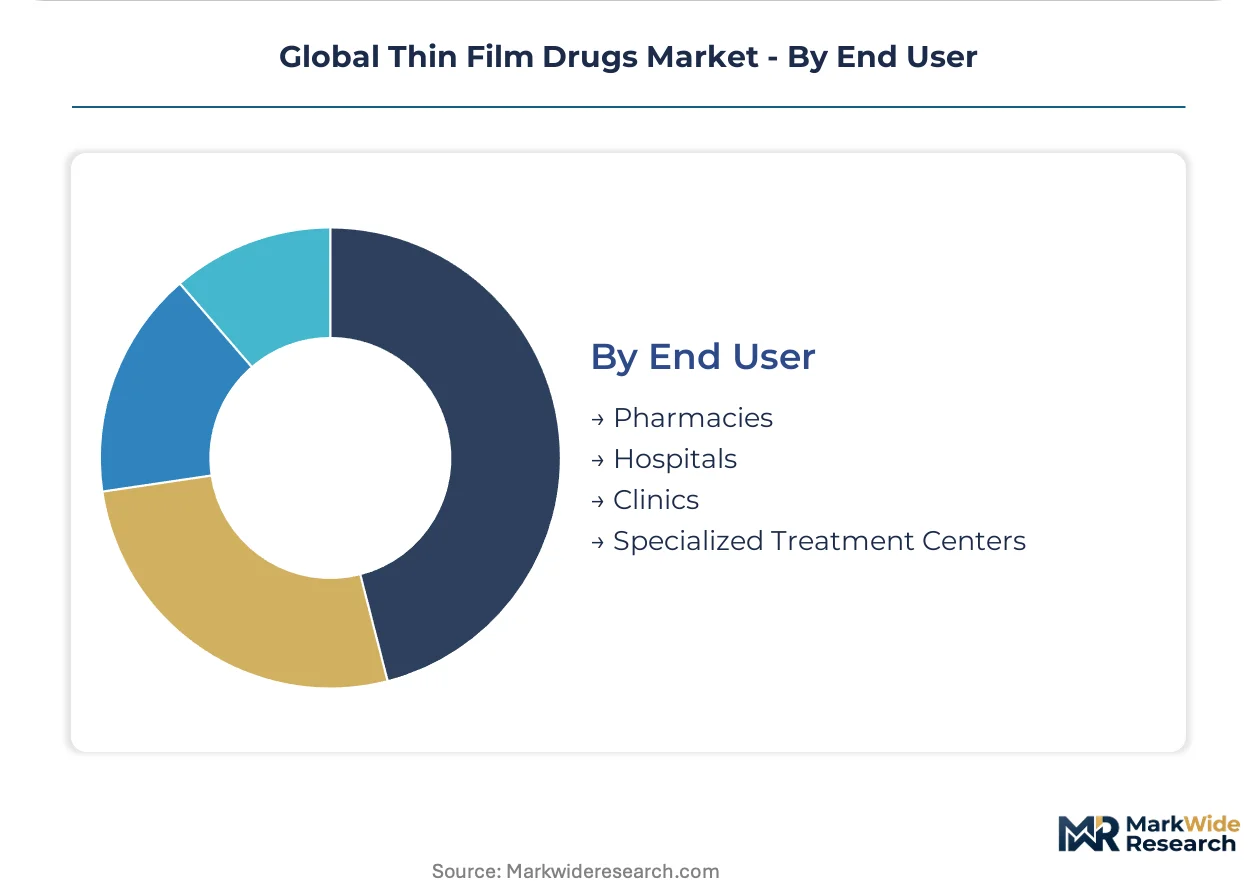
End User:
Procurement authority and patient acuity differentiate channel economics, with specialized settings commanding premium pricing for controlled substances.
- Pharmacies:Community and hospital dispensaries handle the majority of oral disintegrating film volume for chronic neurological and cardiovascular therapies. United States retail chains are consolidating formulary influence through centralized purchasing.
- Hospitals:Acute care settings utilize rapid-onset films for post-surgical nausea and emergency craving suppression. Formulary committees prioritize bioequivalence documentation under FDA abbreviated new drug application standards.
- Clinics:Outpatient facilities manage stable chronic conditions with transdermal maintenance therapies. Brazilian hypertension management programs are expanding clinic-based film prescribing under ANVISA simplified registration.
- Specialized Treatment Centers:United States addiction medicine clinics dominate sublingual buprenorphine film distribution through prescriber certification and patient registry requirements. These channels capture premium margins through controlled substance scheduling and reimbursement alignment.
Pharmacy volume sustains broad market penetration; specialized treatment centers concentrate value capture for regulated neurological therapies.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Rotterdam's pharmaceutical cold chain infrastructure underwrites European distribution efficiency for temperature-sensitive film formulations. Specialized treatment centers in the United States and manufacturing clusters in Germany and India concentrate production capacity and prescription volume.
United States
Specialized addiction medicine clinics drive prescription volume for sublingual buprenorphine films through prescriber certification requirements. The FDA maintains stringent bioequivalence standards for abbreviated new drug applications referencing listed thin film products. Greater Boston anchors formulation R&D activity where Aquestive Therapeutics operates proprietary PharmFilm technology development.
Germany
Geriatric populations in long-term care facilities favor orally disintegrating films for chronic neurological maintenance dosing. EMA's Medical Device Regulation and REACH frameworks govern polymer excipient safety and device-drug combination classifications. The Rhine-Ruhr industrial corridor concentrates pharmaceutical polymer processing and ECHA-registered hydroxypropyl methylcellulose supply.
India
Contract manufacturing organizations supply pullulan-based film matrices to global generic developers seeking cost-competitive production. CDSCO streamlined registration pathways for fixed-dose combination oral films accelerate domestic market entry. Hyderabad and Ahmedabad cluster pharmaceutical excipient production and thin film contract research services.
Brazil
ANVISA simplified registration pathways for transdermal antihypertensive films target hypertension management programs in outpatient clinics. Chronic disease burden and expanding clinic infrastructure drive demand for adherence-improving cardiovascular delivery systems. São Paulo state concentrates pharmaceutical distribution networks and specialized cardiovascular treatment centers.
Japan
PMDA guidelines for novel dosage form bioequivalence align with FDA standards, facilitating multi-regional development strategies for orally disintegrating platforms. Aging demographics expand addressable patient pools for geriatric-compliant neurological films. The Kansai region around Osaka hosts polymer processing capabilities and pharmaceutical packaging innovation clusters.
Global Thin Film Drugs Market Competitive Landscape
On the supply side, the industry is tiered between multinational pharmaceutical conglomerates with manufacturing scale and specialized thin film technology developers with proprietary polymer platforms. Large-cap drug manufacturers leverage existing distribution networks to supply oral thin film platforms across multiple therapy areas. Three strategic archetypes dominate: technology licensors with proprietary film-forming matrices, vertically integrated pharmaceutical manufacturers, and contract development organizations serving generic entrants. Competitive moves concentrate on strategic partnerships with central nervous system drug developers and capacity expansion for specialized dissolution testing infrastructure.
Within the technology licensor tier, Aquestive Therapeutics and IntelGenx Corp exemplify platform-based business models that supply proprietary film technologies to pharmaceutical partners. Pfizer and Novartis AG occupy positions among scale-driven manufacturers with cross-therapy area supply capabilities. Indivior represents the specialized regulatory strategy archetype, anchoring position through channel control in controlled-substance distribution. ZIM Laboratories Limited and Tesa Labtec sit within the contract manufacturing and transdermal systems segments respectively.
| Leading Market Players |
|---|
| Pfizer |
| Novartis AG |
| Aquestive Therapeutics |
| AbbVie |
| ZIM Laboratories Limited |
| IntelGenx Corp |
| Indivior |
| Solvay |
| Tesa Labtec |
| Others |
Supply & Pricing Matrix
The Port of Rotterdam's pharmaceutical cold chain corridors govern freight cost dynamics for temperature-sensitive pullulan and hydroxypropyl methylcellulose shipments, amplifying price differentiation between Southeast Asian polymer suppliers and European formulation facilities while compressing margins for manufacturers lacking backward integration into excipient sourcing.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates FDA-certified sublingual addiction films from EMA-registered buccal platforms and unbranded orally disintegrating generics. Certification tier and volume scale drive price differentiation, with prescriber-certified distribution channels capturing premium positioning. Cost compression in the generic oral disintegrating segment is intensifying as Indian contract manufacturers expand pullulan-based capacity. Specialized treatment centers exhibit lowest price sensitivity due to reimbursement alignment, while retail pharmacy chains face acute margin pressure from formulary consolidation.
Supply Chain Analysis
Contract manufacturing concentration rests with ZIM Laboratories Limited and Tesa Labtec alongside Indian CMO clusters in Hyderabad and Ahmedabad. Geographic supply concentration centers on India, Germany, and the United States for film-forming polymer processing and finished dose production. Raw material dependencies draw from Southeast Asian pullulan agricultural processing, ECHA-registered European hydroxypropyl methylcellulose grades, and Japanese packaging films. Single-source vulnerability in pullulan crop yields creates supply chain risk. Distribution runs through specialized treatment centers and mail-order channels for controlled substances, with retail pharmacy networks handling chronic neurological maintenance therapies.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specialized dissolution method development capabilities have become the binding constraint for abbreviated new drug application submissions, with analytical chemists capable of designing FDA-acceptable in vitro release tests commanding extended recruitment cycles and premium compensation.
For Market Incumbents: Pre-empt generic erosion in sublingual buprenorphine by securing prescriber certification program exclusivity and expanding proprietary PharmFilm technology partnerships with CNS drug developers. Channel control in United States addiction medicine clinics remains the priority defensive lever against emerging transdermal substitution threats. For New Entrants and Emerging Players: Brazil's hypertension management clinics represent the most penetrable white-space target, with ANVISA streamlined pathways for fixed-dose combination transdermal films enabling clinic-based prescribing without legacy formulary entrenchment. Target digital adherence monitoring pilots in Germany and Australia as secondary entry angles, leveraging WHO prequalification standards for multi-market registration efficiency. For Investors and Strategic Acquirers: Proprietary film-forming matrix developers with established Type II DMF libraries and ECHA-registered polymer grades offer the strongest acquisition target archetype for long-term viability across the analysis window. Monitor FDA bioequivalence guidance revisions for novel dosage forms as the critical inflection signal for development timeline compression and infrastructure investment requirements.| Strategic Initiative | Industry Significance |
|---|---|
| Specialized Dissolution Testing Infrastructure Investment | FDA bioequivalence tightening forces ANDA sponsors to build captive analytical capabilities ahead of submissions. |
| ECHA-Registered Polymer Supply Agreement | EMA REACH compliance costs favor manufacturers with pre-qualified hydroxypropyl methylcellulose grades and full toxicological dossiers. |
| Prescriber Certification Program Partnership | United States addiction medicine clinic networks concentrate volume for sublingual buprenorphine through controlled distribution. |
| Digital Adherence Monitoring Platform Development | Smartphone-connected packaging pilots in Germany and Australia enable outcome-linked reimbursement models for addiction therapies. |
| ANVISA Registration Pathway Navigation | Brazilian chronic disease expansion rewards early movers in transdermal antihypertensive film registration. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted across primary interviews with regulatory affairs leads at thin film developers, formulary directors at United States retail chains, polymer procurement managers at European manufacturers, and prescriber certification program administrators at specialized treatment centers. Secondary validation drew from FDA ANDA filings, EMA MDR classification decisions, CDSCO registration databases, ANVISA simplified pathway announcements, and WHO prequalification standards for HIV and malaria therapies. Bottom-up prescription volume modeling and top-down therapy area expenditure analysis were triangulated to cross-verify segment sizing.
Calibration against historical regulatory approval timelines and commercial launch trajectories anchored growth projections across the modeling period. Segmentation dimensions encompassed product type, therapy area, administration route, and regional regulatory cluster. CAGRs were derived from patent expiry schedules, generic entry assumptions, and therapy area expansion rates. Industry-specific forecast inputs included prescriber certification program enrollment curves and mail-order channel penetration trajectories for controlled substances.
Practitioners should monitor FDA bioequivalence guidance revisions, EMA MDR device classification rulings, and Southeast Asian pullulan crop yield reports for early signals of forecast deviation. Quarterly review of ANDA submission backlogs, ECHA polymer registration amendments, and specialized treatment center reimbursement alignment is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Global Central Nervous System (CNS) Stimulant Drugs Market
Pharmaceuticals
Global Transdermal Drug Delivery Systems Market
Pharmaceuticals
Small Molecule Innovator CDMO Market
Pharmaceuticals
Global Encephalitis Vaccine Market
Pharmaceuticals
Carbetocin Injection Market
Pharmaceuticals
Cough Syrup Market
Pharmaceuticals
Acetaminophen Injection Market
Pharmaceuticals
Computer-Aided Drug Discovery Market
Pharmaceuticals
Fibroblast Activation Protein Inhibitors Market
Pharmaceuticals
Fertility Drug and Surgery Market
Pharmaceuticals
Antidepressant Drugs Market
Pharmaceuticals
Human Immunodeficiency Virus Therapeutics Market
Pharmaceuticals
Paclitaxel Injection Market
Pharmaceuticals
Inotropic Agent Market
Pharmaceuticals
Next-Generation Immunology Drugs Market
Pharmaceuticals
Pharmaceutical Pellets Market