
 Pharmacovigilance (PV) Market | 2026-2036
Pharmacovigilance (PV) Market Size, Share, and Industry Trends Forecast 2026-2036
Pharmacovigilance (PV) Market Intelligence
A transition from in-house pharmacovigilance departments to outsourced service models is consolidating the market, with pharmaceutical companies seeking specialized expertise and cost efficiencies. IQVIA leverages its extensive clinical trial data to provide integrated safety and real-world evidence services. Accenture competes by embedding artificial intelligence and automation into its PV platforms to accelerate case processing. Meanwhile, Parexel specializes in managing complex safety reporting for biologics and advanced therapies, navigating intricate global regulatory pathways for its clients.
Pharmacovigilance encompasses the science and activities relating to the detection, assessment, understanding, and prevention of adverse effects or any other drug-related problem. This process involves the continuous monitoring of a drug's safety profile, from initial clinical trials through its entire lifecycle in the market. Within the service landscape, case processing and signal detection form the core, high-volume activities for most providers. The adoption of artificial intelligence and advanced data analytics represents the fastest-growing technology segment, enabling more efficient identification of safety signals from vast datasets.
Regulatory frameworks from the FDA in the United States and the EMA in Europe mandate rigorous and timely adverse event reporting, directly shaping demand for PV services. Global standards, such as the guidelines from the International Council for Harmonisation (ICH), create a consistent structure for safety data management and electronic submission. Stakeholders must decide whether to develop internal AI and automation capabilities or partner with specialized vendors to manage escalating data volumes and evolving regulatory scrutiny.
Market Dynamics
The pharmacovigilance market's structure is defined by the outsourcing of safety monitoring functions to specialized service providers. This shift is driven by the escalating complexity and volume of safety data generated by biologics and advanced therapies, which strains in-house resources.
Growth Catalysts
- Advanced Therapy Mandates:Stringent post-approval safety monitoring requirements from the EMA and FDA for cell and gene therapies necessitate continuous, long-term pharmacovigilance, creating dedicated demand for specialized service providers.
- Biologic Drug Pipeline:The expanding pipeline of biologics, biosimilars, and monoclonal antibodies, which possess complex adverse event profiles, requires more sophisticated signal detection and risk management than traditional small-molecule drugs.
- R&D Hub Concentration:Pharmaceutical R&D and clinical trial activities are heavily concentrated in the United States and Germany, creating dense ecosystems of demand for PV services to support drug development and regulatory submissions.
Market Restraints
- High Implementation Costs:The significant capital investment required to deploy and validate AI-enabled pharmacovigilance platforms, including software licensing and infrastructure, presents a barrier for small to mid-sized pharmaceutical companies.
- Data Interoperability Gaps:A lack of standardization across electronic health record (EHR) systems and real-world data sources complicates the aggregation of safety information, hindering the efficiency of large-scale signal analysis.
- Divergent Privacy Laws:Navigating conflicting data privacy regulations, such as Europe's GDPR and the US HIPAA, creates compliance and operational friction for the global transfer and processing of patient safety data.
Strategic Opportunities
- Personalized Medicine Services:Developing bespoke PV solutions tailored to personalized medicines and orphan drugs, which often involve small patient populations and require novel long-term safety monitoring approaches.
- Real-World Evidence Integration:Combining safety data from traditional sources with real-world evidence from patient registries and digital health devices to build more comprehensive and predictive risk profiles for new therapies.
- Emerging Market Expansion:Targeting pharmaceutical markets in countries like India and Brazil, where regulatory bodies such as CDSCO and ANVISA are strengthening their safety reporting standards in alignment with ICH guidelines.
Industry Challenges
- Specialized Talent Scarcity:A critical shortage of professionals with combined expertise in regulatory science, clinical safety, and data analytics limits the ability of organizations to effectively manage and interpret data from AI-powered PV systems.
- Legacy System Integration:The operational difficulty and cost associated with integrating modern, cloud-based PV platforms with entrenched legacy safety databases and enterprise resource planning systems hinders technology adoption.
- Unstructured Data Quality:Ensuring the accuracy and consistency of safety data extracted from unstructured sources like social media and medical literature remains a significant challenge for reliable signal detection.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Pharmacovigilance (PV) Market |
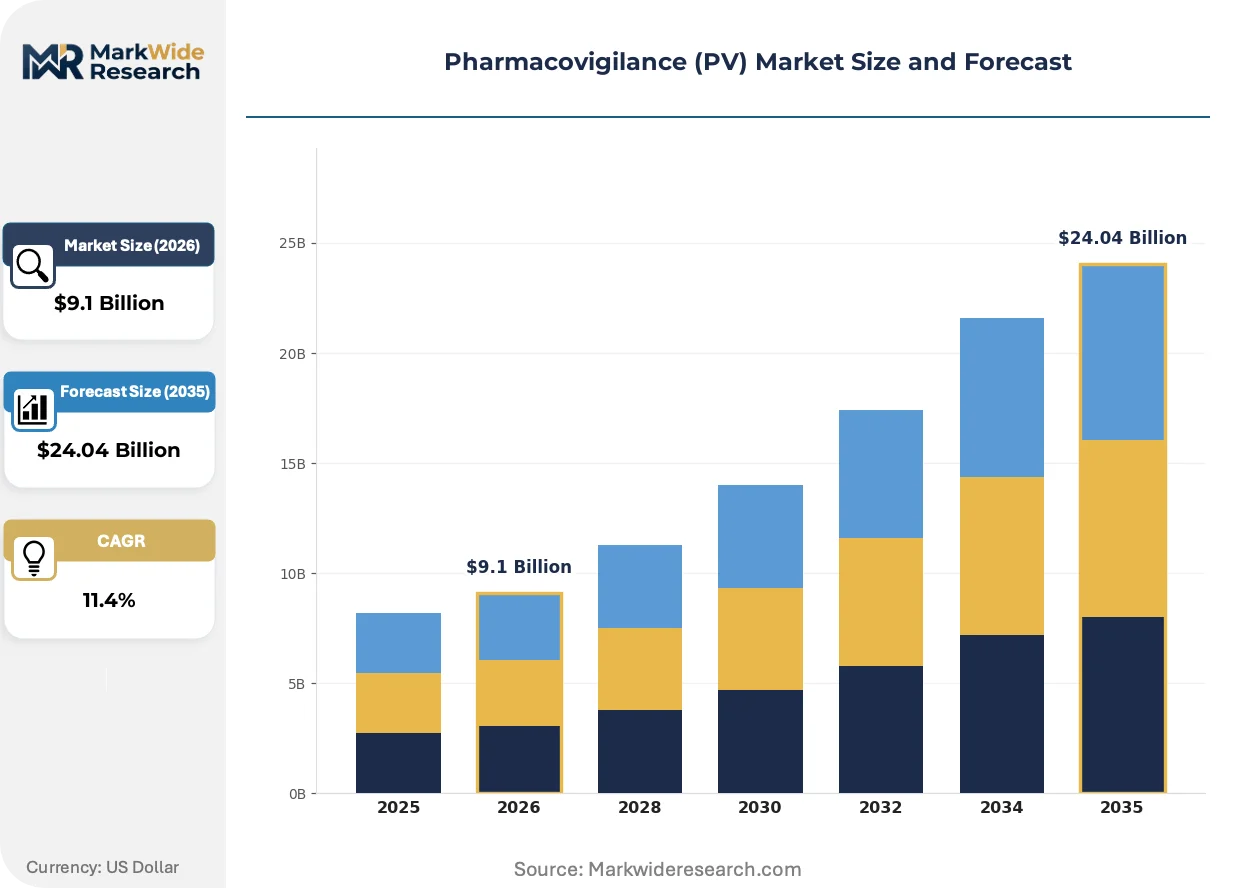
| Market Size in 2026 | $9.1 Billion |
| Market Size in 2035 | $24.04 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Signal Detection, Risk Management, Case Processing, Literature Screening, Periodic Safety Update Reports, Benefit-Risk Analysis Technology: Artificial Intelligence, Cloud Computing, Automation, Data Analytics, Blockchain, Natural Language Processing End User: Pharmaceutical Companies, Biotech Firms, Contract Research Organizations, Regulatory Agencies, Healthcare Institutions Deployment: On-Premises, Cloud-Based, Hybrid, Software as a Service, Platform as a Service, Infrastructure as a Service |
| Companies Covered | Accenture, IQVIA, Cognizant, Parexel, ICON, Syneos Health, Capgemini, Wipro, ArisGlobal, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Pharmacovigilance (PV) Market Strategic Shifts & Innovations
The industrialization of safety surveillance is transforming pharmacovigilance from a reactive, compliance-driven function into a proactive, data-centric discipline. This evolution is centered on leveraging advanced analytics to predict and mitigate drug-related risks earlier in the product lifecycle.
Artificial intelligence and natural language processing (NLP) provide the technical foundation for next-generation PV platforms. Pharmaceutical firms and contract research organizations are adopting these tools to analyze vast quantities of unstructured text from sources like call center logs and scientific publications. This technology is automating routine case intake and data entry, freeing pharmacovigilance specialists to concentrate on complex causality assessment and risk-benefit analysis.
Global regulatory harmonization, guided by standards from the International Council for Harmonisation (ICH), is a powerful force. The ICH E2B(R3) guideline, which specifies a common electronic format for individual case safety reports, compels organizations to modernize their data management and submission infrastructure. This standard particularly affects multinational corporations that must report to diverse authorities like the FDA, EMA, and Japan's PMDA, driving investment in unified global safety databases.
A fundamental shift is occurring in how PV services are purchased and delivered. Pharmaceutical sponsors are moving from transactional, fee-for-service arrangements toward strategic partnerships with providers offering end-to-end safety solutions. This model bundles services across clinical trial safety, post-market surveillance, and regulatory reporting into a single, integrated framework. This trend is most visible in North America and Europe, where the complexity of managing biologics portfolios necessitates deeper collaboration.
Pharmacovigilance (PV) Market Segmentation
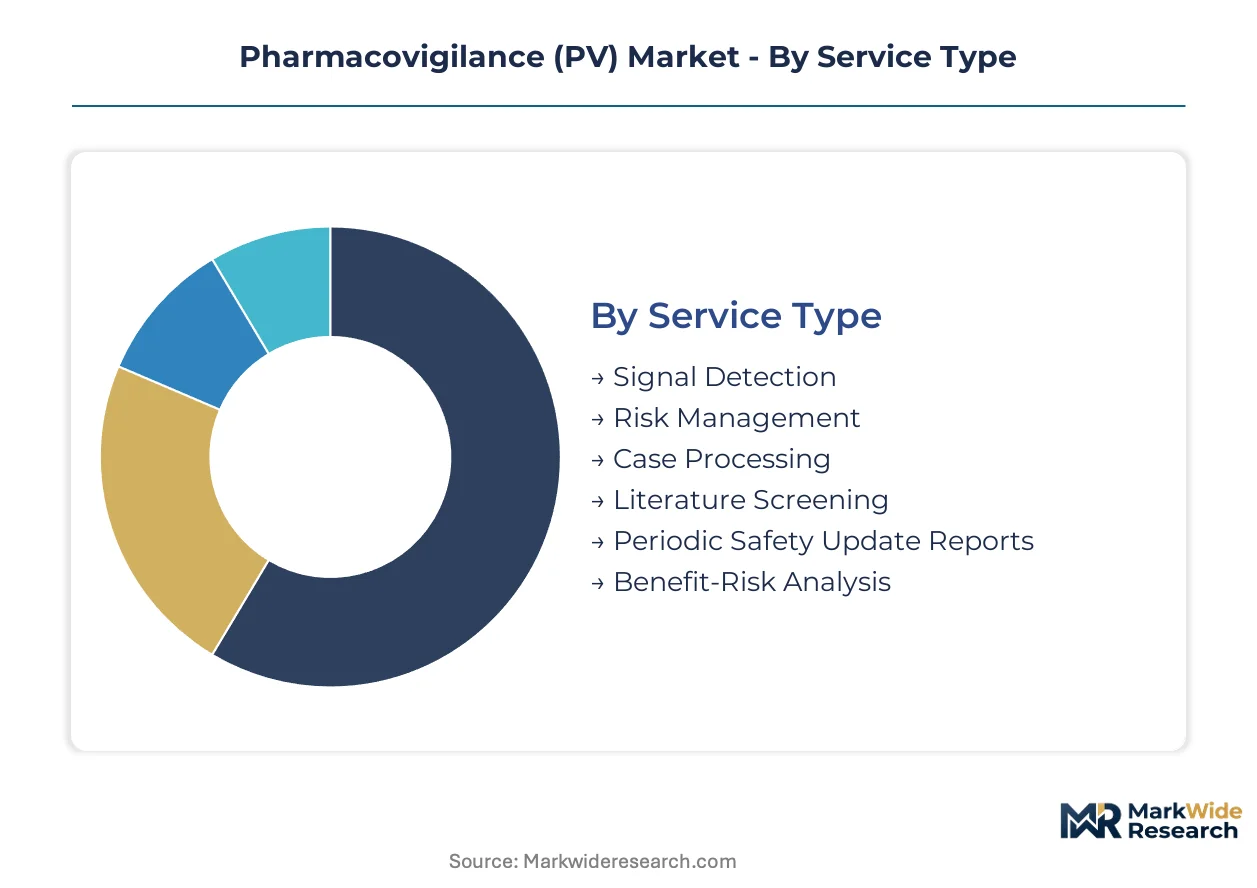
The Pharmacovigilance (PV) Market structure reflects the diverse operational and technological needs of drug safety monitoring. This segmentation highlights how specialized services and advanced platforms are deployed across the pharmaceutical ecosystem. Understanding these distinct market segments is crucial for strategic planning within the evolving regulatory landscape.
Service Type:
The supply of pharmacovigilance services is concentrating around high-volume, repetitive tasks that benefit from automation and specialized expertise.
- Case Processing:Involves collecting, validating, and reporting individual case safety reports (ICSRs) from various sources. Demand is high in the United States, driven by rigorous FDA reporting mandates for clinical trials.
- Signal Detection:Focuses on identifying new adverse drug reactions or changes in known frequencies from large datasets. Biotech firms in Germany utilize this for complex biologic therapies, requiring sophisticated analytical tools.
- Risk Management:Develops and implements strategies to minimize identified drug risks throughout their product lifecycle.
- Literature Screening:Systematically reviews scientific publications and medical literature for adverse event identification.
- Periodic Safety Update Reports:Compiles aggregate safety data at defined intervals, providing comprehensive risk-benefit overviews to regulators.
- Benefit-Risk Analysis:Evaluates a drug's therapeutic benefits against associated risks for regulatory decisions and patient care.
Case Processing absorbs the bulk of installed capacity; Signal Detection is expanding most quickly.
Technology:
Technology application in pharmacovigilance is redefining how safety data is managed and analyzed, enhancing efficiency and predictive capabilities.
- Artificial Intelligence:Leverages machine learning to automate case processing, identify safety signals, and predict adverse events from vast datasets. Pharmaceutical companies in Japan invest in AI for PMDA compliance.
- Data Analytics:Systematically analyzes safety data to discover meaningful patterns and interpret drug safety information. This technology is critical for post-market surveillance of biologics in Europe, aligning with EMA guidelines.
- Cloud Computing:Provides scalable and flexible infrastructure for hosting PV platforms, enabling global access.
- Automation:Automates repetitive tasks like data entry and report generation, improving safety case handling efficiency.
- Blockchain:Offers a secure, decentralized ledger for managing drug supply chain and patient safety records.
- Natural Language Processing:Extracts information from unstructured text sources, aiding signal detection and case intake.
Artificial Intelligence drives the largest volume of new technology investment; Natural Language Processing shows significant potential for future expansion.
End User:
The customer base for pharmacovigilance solutions spans a diverse range of organizations, each with unique compliance and operational requirements.
- Pharmaceutical Companies:Represent the largest end-user group, requiring comprehensive PV services for their extensive drug portfolios. Companies in the United States depend on robust PV systems for FDA compliance.
- Biotech Firms:Focus on novel therapies, necessitating specialized PV solutions for complex safety profiles and stringent post-market surveillance. Firms in Germany drive demand for advanced signal detection.
- Contract Research Organizations:Provide outsourced PV services, leveraging specialized expertise and scalable resources.
- Regulatory Agencies:Utilize PV data to monitor drug safety, evaluate risk-benefit profiles, and enforce reporting standards.
- Healthcare Institutions:Contribute to PV by reporting adverse drug reactions and integrating safety data from EHRs.
Pharmaceutical Companies represent the largest market share; Regulatory Agencies influence the market's compliance and data standards.
Deployment:
Deployment models for pharmacovigilance platforms reflect varying levels of technological maturity and infrastructure preferences among clients.
- Cloud-Based:Hosts PV software and data on remote servers, offering scalability, reduced infrastructure costs, and global accessibility. This model is favored by multinational corporations in Europe for GDPR compliance.
- Software as a Service (SaaS):Delivers PV applications over the internet as a subscription, eliminating customer management of infrastructure. Small to mid-sized pharmaceutical companies in India adopt SaaS for cost efficiency and rapid deployment.
- On-Premises:PV software installed on local servers within client data centers, offering maximum control and customization.
- Hybrid:Combines on-premises and cloud deployments, maintaining sensitive data locally while leveraging cloud resources.
- Platform as a Service (PaaS):Provides a platform for developing, running, and managing applications without infrastructure complexity.
- Infrastructure as a Service (IaaS):Offers virtualized computing resources over the internet, giving users control over operating systems and storage.
Cloud-Based solutions offer significant operational flexibility; On-Premises deployments continue for organizations with specific data sovereignty requirements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand for pharmacovigilance services concentrates in nations with significant pharmaceutical research and development investment. These countries, including the United States and Germany, host numerous clinical trials and drug development activities. Rigorous regulatory reporting mandates from bodies like the FDA and EMA further shape this specialized demand.
United States
The United States drives substantial pharmacovigilance demand due to its expansive pharmaceutical R&D pipeline. Stringent FDA reporting mandates for clinical trials and post-market surveillance necessitate advanced PV solutions. Major pharmaceutical clusters in areas such as Boston and San Francisco actively utilize sophisticated signal detection tools for novel biologics.
Germany
Germany represents a core market for pharmacovigilance services, particularly for biotech firms. The country's strong focus on advanced therapies and biologics requires specialized safety monitoring under EMA guidelines. Pharmaceutical hubs in cities like Munich and Berlin are adopting AI-powered PV platforms to manage complex adverse event profiles.
Japan
Japan demonstrates a growing investment in pharmacovigilance technology, particularly artificial intelligence. Pharmaceutical companies prioritize PMDA compliance, demanding efficient and accurate adverse event reporting. Research institutions and drug developers in the Tokyo area increasingly integrate NLP tools for literature screening and case processing.
India
India presents a strategic opportunity for pharmacovigilance market expansion, driven by strengthening regulatory standards. The CDSCO is aligning its safety reporting requirements with ICH guidelines, increasing demand for structured PV services. Major pharmaceutical manufacturing centers in Hyderabad and Ahmedabad are adopting SaaS solutions for cost-efficient safety management.
Switzerland
Switzerland maintains a high demand for specialized pharmacovigilance solutions, particularly for personalized medicines and orphan drugs. Swissmedic mandates rigorous long-term safety monitoring for these innovative therapies. Global pharmaceutical headquarters in Basel and Zurich are integrating real-world evidence to build comprehensive risk profiles.
Pharmacovigilance (PV) Market Key Industry Players
Strategic partnerships dominate the current landscape, as pharmaceutical companies increasingly outsource their safety monitoring functions. The market structure consolidates around large contract research organizations and specialized technology providers. Archetypes include full-service PV providers, technology-centric solution developers, and niche regulatory compliance specialists. Technology adoption and portfolio diversification are key competitive moves among market participants.
Specialists in integrated safety and real-world evidence services like IQVIA leverage extensive clinical trial data. Accenture, a global professional services company, exemplifies a technology-centric approach by embedding artificial intelligence and automation into its PV platforms. Parexel, a prominent clinical research organization, represents an archetype focused on managing complex safety reporting for biologics and advanced therapies, navigating intricate global regulatory pathways for its clients.
| Leading Market Players |
|---|
| Accenture |
| IQVIA |
| Cognizant |
| Parexel |
| ICON |
| Syneos Health |
| Capgemini |
| Wipro |
| ArisGlobal |
| Others |
Cost & Logistics Intelligence
Pharmacovigilance specialists in high-cost regions like the United States and Germany drive labor-cost differentials, which directly influence pricing-tier spreads for advanced safety services. This concentration of expertise shapes the market's value proposition.
Pricing Analysis
Service bundling, encompassing case processing and signal detection, often dictates pricing structures for pharmacovigilance solutions. Project-based fees dominate for complex, bespoke engagements, while SaaS subscriptions govern technology platform access. Customization levels for novel therapies and the volume scale of case handling are primary price differentiation drivers. Pricing softness stems from the increasing adoption of automation for routine tasks. Small to mid-sized pharmaceutical companies exhibit the highest price sensitivity, seeking cost-efficient outsourced models.
Supply Chain Analysis
Outsourced service providers, including Contract Research Organizations and specialized technology firms, form the dominant distribution model for pharmacovigilance services. Geographic supply concentration for operational delivery centers exists in India and the Philippines for cost-efficient BPO, alongside the United States for high-end analytics. The supply chain relies heavily on skilled PV professionals and advanced AI/NLP software. A critical supply chain risk involves the specialized talent scarcity, particularly for professionals adept in both regulatory science and data analytics.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The pharmacovigilance market is undergoing a technology-transition phase, moving from manual, compliance-driven tasks to predictive safety intelligence. Artificial intelligence is replacing traditional rule-based safety monitoring, enabling proactive risk identification.
For Market Incumbents: Extend investment in integrated AI and Natural Language Processing capabilities to automate routine tasks, thereby enhancing efficiency and reducing operational costs. Deepen strategic partnerships with technology providers to leverage real-world evidence platforms, addressing the increasing complexity of biologic drug safety profiles. Focus on talent development programs to mitigate the specialized talent scarcity, which remains a significant operational bottleneck.
For New Entrants and Emerging Players: A price-point gap exists between premium, full-service providers and basic, compliance-focused solutions, creating opportunities for niche players. Target under-served segments such as personalized medicine and orphan drug pharmacovigilance, which require highly specialized and agile safety monitoring approaches. A focused go-to-market angle involves offering scalable, cloud-based SaaS platforms tailored for small and mid-sized biotech firms, emphasizing rapid deployment and regulatory alignment.
For Investors and Strategic Acquirers: Re-rating potential sits with technology-centric PV providers given the accelerating shift towards AI and automation in drug safety. Long-term viability for this market remains robust, driven by expanding drug pipelines and stringent global regulatory mandates. Target acquisition archetypes include specialized AI/NLP technology firms and CROs with deep expertise in advanced therapy safety reporting. The successful integration of real-world evidence platforms into core PV operations serves as a critical inflection signal to watch.
| Strategic Initiative | Industry Significance |
|---|---|
| Deepen AI/NLP Integration | Automates case processing and signal detection, enhancing efficiency and reducing human error in safety reporting. |
| Strategic Partnerships for RWE | Combines traditional safety data with real-world evidence, building more comprehensive and predictive risk profiles. |
| Specialized Talent Development | Addresses the critical shortage of professionals with combined regulatory, clinical, and data analytics expertise. |
| Offer SaaS-based PV Platforms | Provides cost-effective and scalable solutions for small to mid-sized pharmaceutical companies and biotech firms. |
| Expand into Emerging Markets | Captures demand in regions strengthening safety reporting standards, aligning with international guidelines like ICH. |
Research Approach
Document review covered FDA guidance documents, EMA scientific opinions, and International Council for Harmonisation (ICH) guidelines, complemented by interviews with industry stakeholders. This primary research involved discussions with regulatory affairs leads, clinical safety officers, PV technology developers, and pharmaceutical procurement managers. Secondary data from company annual reports and scientific publications further validated initial findings, employing both bottom-up and top-down data triangulation.
Historical data trends were cross-referenced with expert panel input to construct the forecast framework over the projection horizon. The analytical framework modeled segmentation dimensions including service type, technology, end user, deployment model, and therapeutic area. Compound Annual Growth Rates were derived through regression analysis and market share projections. Key forecast inputs included global drug pipeline growth and evolving regulatory changes for biologics and advanced therapies.
Inputs from regulatory bodies and industry reports were available through the study window; gaps in real-time market adoption data for niche technologies introduce uncertainty bands. Forecasts reflect assumptions regarding technological advancements and regulatory stability. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Calcitriol Capsules Market
Pharmaceuticals
Artificial Intelligence in Drug Screening Market
Pharmaceuticals
Germany Opioids Market
Pharmaceuticals
North America Obsessive-Compulsive Disorder (OCD) Drugs Market
Pharmaceuticals
Global Histone Deacetylase Inhibitors Market
Pharmaceuticals
Global Novel Drug Delivery Systems (NDDS) Market
Pharmaceuticals
Global Transdermal Drug Delivery Systems Market
Pharmaceuticals
Leflunomide Market
Pharmaceuticals
Global Ceftiofur Market
Pharmaceuticals
Repurposed Human Immunosuppressants Market
Pharmaceuticals
Metoprolol Tartrate Market
Pharmaceuticals
Brazil Diabetes Drugs Market
Pharmaceuticals
US Plasma Fractionation Market
Pharmaceuticals
Parenteral Drugs Market
Pharmaceuticals
Middle East and Africa Psychedelic Drugs Market
Pharmaceuticals
Cough and Cold Preparations Market