
 Global Gout Therapeutics Market | 2026-2036
Global Gout Therapeutics Market Size, Share, and Industry Trends Forecast 2026-2036
Global Gout Therapeutics Market Foresight
Hospital pharmacy sales is tilting toward specialty biologic fulfillment as payers tighten prior authorization controls for high-cost gout therapies. Takeda Pharmaceutical Company Limited anchors its position through deep integration with infusion center networks. Horizon Therapeutics plc differentiates via concentrated investment in refractory gout indications. Novartis AG competes through established immunology infrastructure that extends into rheumatology prescriber relationships.
Gout therapeutics comprise pharmacological agents targeting uric acid metabolism, inflammatory cascade modulation, or cytokine inhibition, with biologics such as IL-1 antagonists requiring refrigerated cold-chain distribution and subcutaneous or intravenous administration. These therapies serve to reduce serum urate burden, abort acute flares, or prevent chronic joint destruction in hyperuricemic patients. Biologics command concentrated margin pools due to manufacturing complexity and orphan-disease pricing structures, while uric acid lowering agents sustain volume leadership through generic allopurinol and febuxostat prescribing. Anti-inflammatories occupy a mature position with colchicine and corticosteroids serving as first-line acute flare management across ambulatory settings.
FDA orphan drug designations and EMA conditional marketing authorizations shape biologic development economics by extending exclusivity periods and streamlining review for refractory gout populations. REACH compliance and EU GMP standards govern active pharmaceutical ingredient sourcing for European manufacturing, while Japan's PMDA maintains distinct pharmacovigilance requirements for xanthine oxidase inhibitors. Stakeholders must monitor IL-1 and IL-6 pathway competitive dynamics alongside biosimilar entry timelines for existing biologic franchises.
Market Dynamics
The gout therapeutics market is restructuring around biologic cold-chain fulfillment networks as specialty infusion centers displace traditional hospital pharmacy dispensing for IL-1 antagonist therapies. This shift concentrates margin capture with integrated logistics providers and tightens prescriber loyalty to hub-and-spoke distribution models.
Growth Catalysts
- Orphan drug incentives:FDA accelerated approval pathways compress development timelines for refractory gout biologics. EMA conditional marketing authorizations extend exclusivity periods for European launches.
- Specialty clinic expansion:Rheumatology centers in the United States drive biologic infusion volume through dedicated gout management protocols. These facilities anchor demand for refrigerated cytokine inhibitors.
- Japan's aging demographic:PMDA pharmacovigilance frameworks for xanthine oxidase inhibitors align with elevated hyperuricemia prevalence. Domestic prescribing patterns favor sustained-release formulations.
Market Restraints
- Prior authorization friction:US commercial payers impose multi-step approval gates for biologic gout therapies. Reimbursement delays extend treatment initiation timelines by 30-60 days.
- Active pharmaceutical ingredient concentration:European REACH compliance requirements constrain supplier pools for febuxostat and colchicine precursors. Single-source dependencies elevate supply disruption risk.
- Biosimilar pipeline pressure:Pending entry of IL-1 antagonist copies threatens pricing power for existing biologic franchises. Manufacturing complexity provides only temporary moat protection.
Strategic Opportunities
- Home infusion channels:Subcutaneous biologic formulations enable migration from clinic-based to patient-administered delivery. Germany's outpatient reimbursement codes support this channel expansion.
- Combination therapy protocols:Concurrent uric acid lowering and anti-inflammatory regimens address refractory patient segments. Clinical data packages targeting this white space attract priority FDA review.
- India's generic febuxostat market:CDSCO manufacturing incentives and domestic cost structures position Indian suppliers for volume export contracts. Local production capacity exceeds current regional demand.
Industry Challenges
- Cold-chain logistics talent scarcity:Qualified technicians for temperature-controlled biologic distribution remain concentrated in legacy vaccine supply networks. Gout-specific fulfillment requires specialized training investments.
- Legacy EHR integration:Rheumatology practices struggle to embed biologic monitoring protocols into existing workflow systems. Interoperability gaps delay adverse event reporting compliance.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Gout Therapeutics Market |
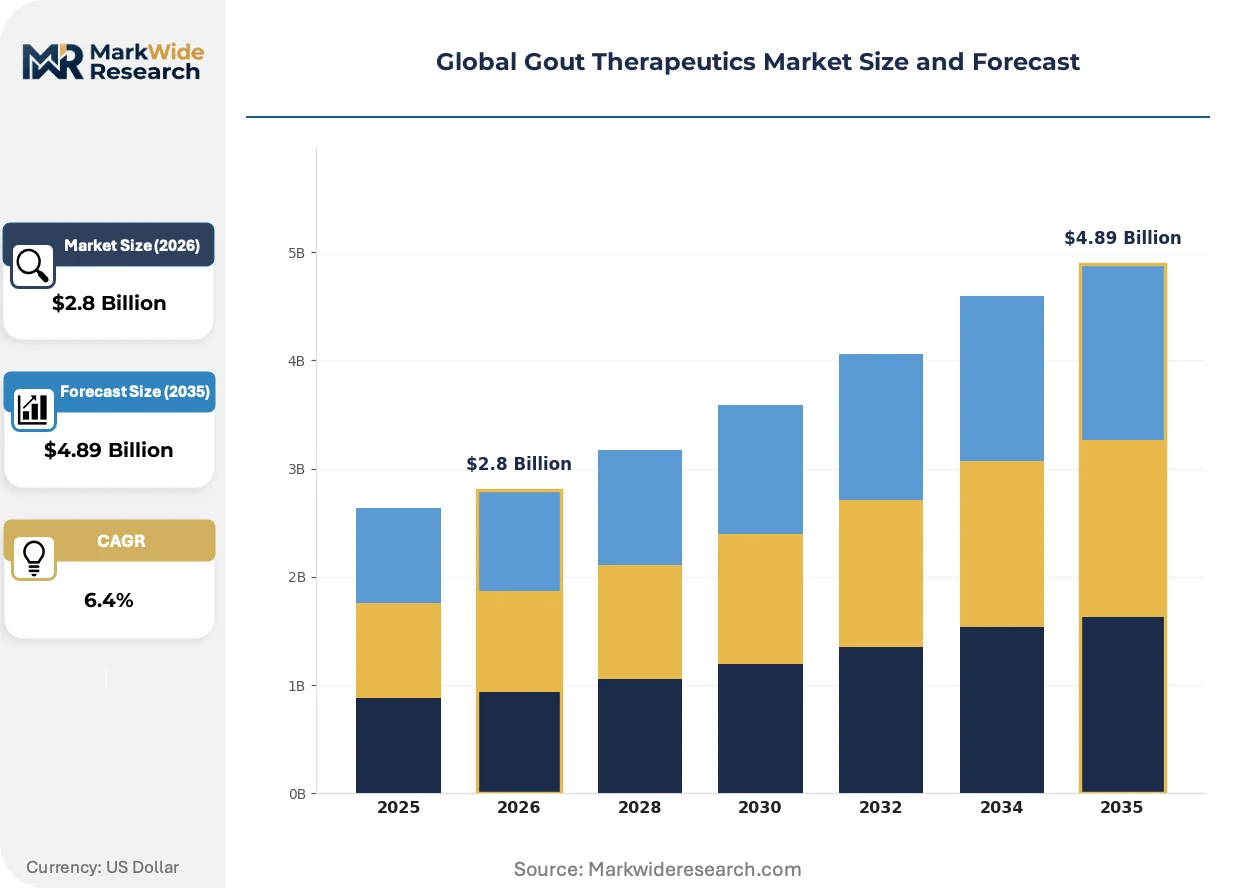
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $4.89 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Uric Acid Lowering Agents, Anti-Inflammatories, Colchicine, Corticosteroids, Biologics Therapy Area: Acute Gout, Chronic Gout, Intercritical Gout, Gouty Arthritis, Hyperuricemia Treatment End User: Specialty Clinics, Rheumatology Centers, Hospital Pharmacies, Ambulatory Care, Research Facilities Distribution Channel: Retail Pharmacies, Hospital Pharmacy Sales, Online Pharmacies, Wholesalers, Direct Sales |
| Companies Covered | Takeda Pharmaceutical Company Limited, Horizon Therapeutics plc, AstraZeneca, Novartis AG, Merck & Co., Inc., Teva Pharmaceutical Industries Ltd., Regeneron Pharmaceuticals Inc., GSK plc, Teijin Pharma Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Gout Therapeutics Market Shifts & Advancements
Biologic manufacturing platforms are converging with precision dosing algorithms to reshape how gout therapies reach refractory patient populations. This convergence compresses development cycles while elevating regulatory scrutiny on real-world evidence requirements.
Subcutaneous IL-1 antagonist delivery systems are hybridizing with connected health monitoring to enable remote flare management. Rheumatology practices in Germany and the United States are piloting these integrated platforms for high-frequency gout patients. The technology is compressing emergency department utilization while shifting reimbursement risk to managed care organizations.
EMA's expanded pharmacovigilance mandates for biologic immunomodulators now require 15-year post-market safety registries. This regulatory burden elevates compliance costs for European launches but creates competitive moats against undercapitalized entrants. Manufacturers are responding by pre-positioning real-world evidence contracts with national health technology assessment bodies.
Patient-administered therapy preferences are fragmenting traditional infusion center relationships. Subcutaneous biologics displace intravenous alternatives in ambulatory settings across France and the United Kingdom. This behavioral shift is most visible among employed patient populations where clinic visit opportunity costs exceed copay differentials.
Global Gout Therapeutics Market Segmentation
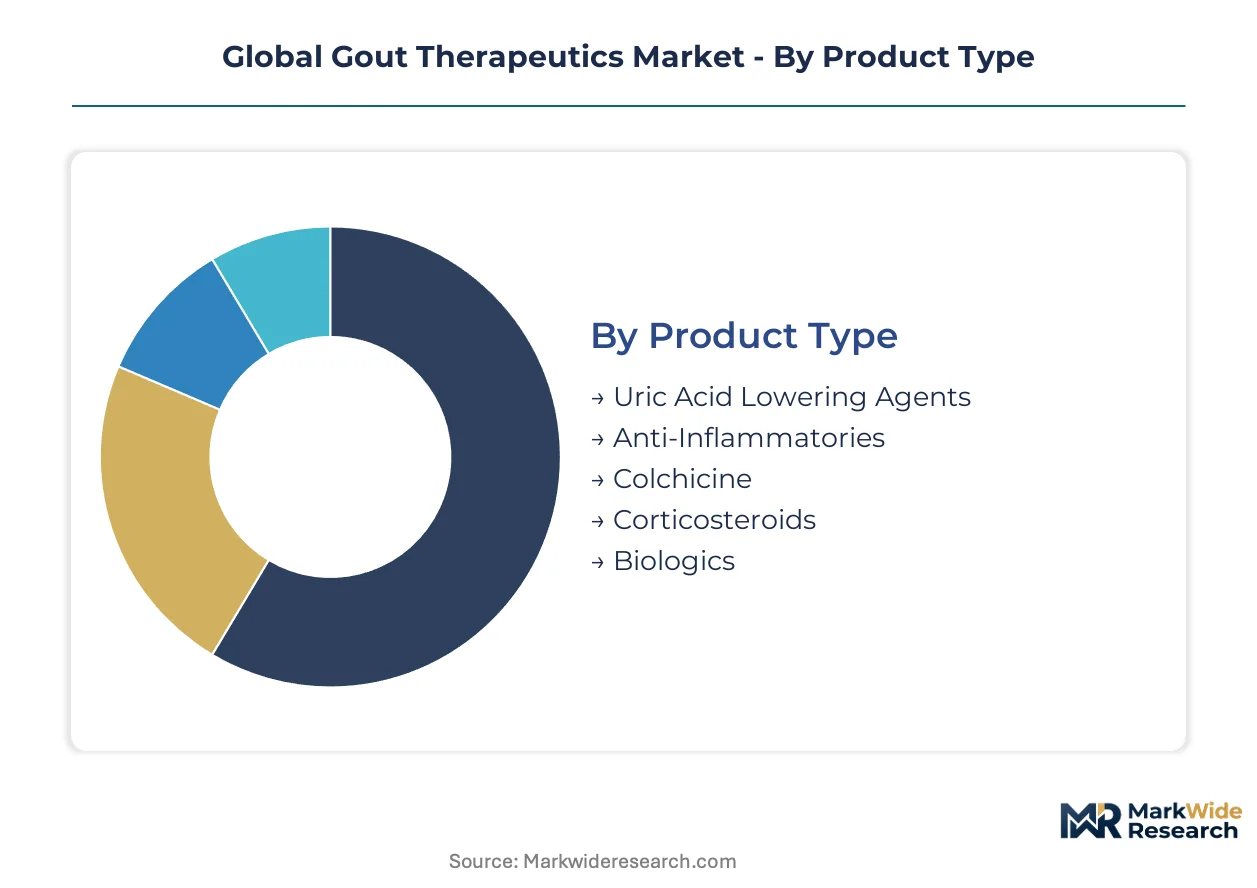
Segmentation in gout therapeutics reveals how treatment complexity stratifies across patient severity, prescriber specialty, and fulfillment infrastructure. Each dimension exposes distinct margin pools and regulatory exposure that shape competitive positioning.
Product Type:
Use-case spectrum spans from generic urate reduction to precision cytokine inhibition, with each tier carrying fundamentally different manufacturing economics and cold-chain requirements.
- Biologics:Recombinant IL-1 antagonists and monoclonal antibodies require refrigerated distribution and subcutaneous or intravenous administration. Demand concentrates in United States rheumatology centers where prior authorization protocols favor orphan-disease pricing structures for refractory cases.
- Uric Acid Lowering Agents:Xanthine oxidase inhibitors including allopurinol and febuxostat form the pharmacological backbone of chronic management. Volume leadership persists through generic prescribing in Germany and Japan where sustained-release formulations align with aging demographic treatment adherence.
- Anti-Inflammatories:NSAID-class agents serve first-line acute flare interruption across ambulatory settings.
- Colchicine:Microtubule inhibitor with established efficacy for acute flare prophylaxis during urate-lowering therapy initiation.
- Corticosteroids:Intra-articular and systemic formulations for patients with contraindications to NSAID or colchicine use.
The dominant share belongs to Uric Acid Lowering Agents, while Biologics is closing the gap fastest.
Therapy Area:
Cost tier stratification separates commodity acute management from premium chronic disease modification, with reimbursement intensity scaling directly with joint destruction risk.
- Chronic Gout:Long-term urate-lowering therapy with target serum urate below 6 mg/dL to prevent tophaceous deposits. Germany's outpatient reimbursement codes support combination protocols integrating febuxostat with anti-inflammatory prophylaxis.
- Acute Gout:Sudden monoarticular inflammatory attacks requiring rapid cytokine cascade interruption. Emergency department utilization in United States drives corticosteroid and colchicine demand during overnight hours.
- Intercritical Gout:Asymptomatic hyperuricemia management between flares with lifestyle modification adjuncts.
- Gouty Arthritis:Erosive joint disease with chronic pain and functional limitation requiring rheumatology specialist referral.
- Hyperuricemia Treatment:Asymptomatic serum urate elevation management in cardiovascular comorbidity populations.
Chronic Gout commands the deepest prescriber relationships, yet Acute Gout generates the highest per-episode pharmacy spend.
End User:
Customer type concentration determines whether fulfillment runs through cold-chain biologic networks or generic wholesale distribution.
- Rheumatology Centers:Academic and community specialty practices with infusion capacity and biologic prior authorization expertise. United States hub-and-spoke models anchor IL-1 antagonist volume through dedicated gout management protocols.
- Specialty Clinics:Focused outpatient facilities with rheumatology subspecialty certification and refrigerated storage infrastructure.
- Hospital Pharmacies:Inpatient and outpatient dispensing with 340B pricing exposure and formulary committee governance.
- Ambulatory Care:Primary care and urgent care settings managing uncomplicated acute flares.
- Research Facilities:Clinical trial sites and academic medical centers investigating novel urate-lowering mechanisms.
Rheumatology Centers capture the highest biologic revenue per prescriber, while Hospital Pharmacies handle the greatest prescription volume.
Distribution Channel:
Supply concentration separates temperature-controlled specialty fulfillment from ambient generic wholesale.
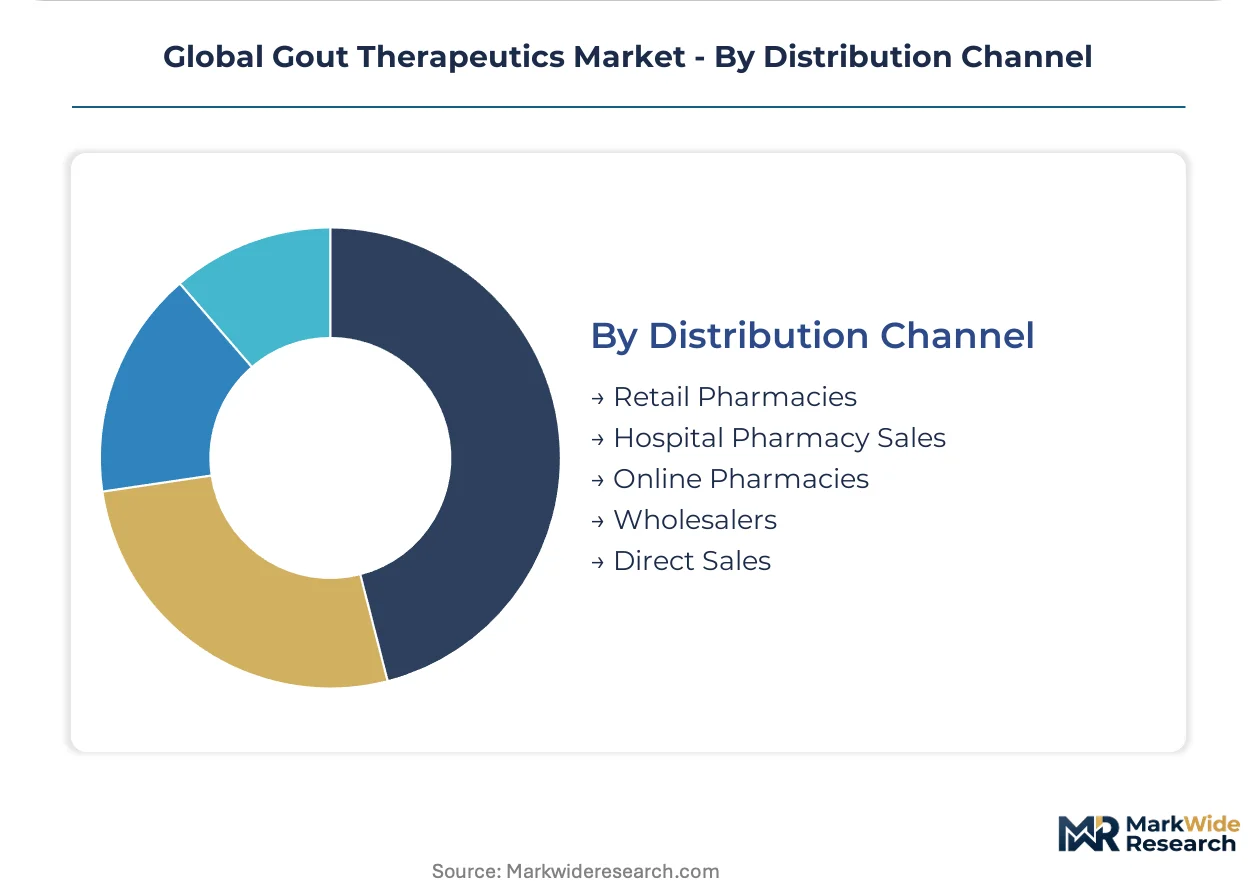
- Hospital Pharmacy Sales:Inpatient discharge and outpatient specialty dispensing with integrated EHR prior authorization workflows. Payer tightening on high-cost gout therapies is tilting volume toward specialty biologic fulfillment.
- Retail Pharmacies:Community dispensing of generic allopurinol, colchicine, and oral corticosteroids with 90-day supply programs.
- Online Pharmacies:Mail-order fulfillment with cold-chain logistics partnerships for patient-administered subcutaneous biologics.
- Wholesalers:Three-tier distribution of ambient-storage small molecules to institutional and retail accounts.
- Direct Sales:Manufacturer-to-provider contracting for orphan-designated biologics with risk-sharing arrangements.
Hospital Pharmacy Sales retains volume leadership, though Online Pharmacies is expanding most quickly through subcutaneous formulation migration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power for biologic gout therapies concentrates in the United States, where orphan-disease designations sustain premium reimbursement, while European markets operate under tighter health technology assessment constraints that compress net prices for identical molecules.
United States
Rheumatology centers in Boston, New York, and Philadelphia anchor biologic infusion volume through dedicated gout management protocols. FDA accelerated approval pathways compress development timelines for refractory gout biologics, extending exclusivity periods for manufacturers. The Southeast corridor from Atlanta to Miami shows fastest adoption growth for subcutaneous IL-1 antagonist formulations.
Germany
Outpatient reimbursement codes support combination protocols integrating febuxostat with anti-inflammatory prophylaxis, driving sustained-release formulation demand. EMA conditional marketing authorizations align with Germany's health technology assessment requirements for orphan indications. The Rhine-Ruhr metropolitan cluster concentrates specialty pharmacy fulfillment infrastructure for temperature-controlled biologics.
Japan
PMDA pharmacovigilance frameworks for xanthine oxidase inhibitors align with elevated hyperuricemia prevalence among aging demographics. METI industrial policy supports domestic sustained-release manufacturing capacity. The Kansai region around Osaka anchors prescription volume for febuxostat generics, while Tokyo's rheumatology centers pilot home-infusion channels for subcutaneous biologics.
United Kingdom
NICE technology appraisals constrain biologic access to refractory cases with documented treatment failure, creating tiered prescribing hierarchies. MHRA post-Brexit regulatory autonomy enables accelerated pathways for novel urate-lowering mechanisms. The Greater Manchester and West Midlands hospital networks concentrate infusion center capacity outside London's saturated market.
India
CDSCO manufacturing incentives and domestic cost structures position Indian suppliers for volume export contracts in generic febuxostat. Local production capacity exceeds current regional demand, enabling surplus allocation to Southeast Asian markets. The Hyderabad-Bengaluru pharmaceutical corridor houses active pharmaceutical ingredient synthesis for colchicine precursors under REACH-compliant supply arrangements.
Global Gout Therapeutics Market Competitive Landscape
Integrated biologic manufacturers and generic urate-lowering specialists split the market along therapy complexity lines. The structure tilts toward consolidation at the biologic tier, where cold-chain infrastructure requirements and prior authorization expertise erect entry barriers, while commoditized small-molecule segments sustain fragmented competition. Two archetypes dominate: orphan-disease biologic developers with infusion center partnerships, and volume-scale generic fabricators with backward integration into active pharmaceutical ingredients. Competitive moves concentrate on M&A for refrigerated distribution capabilities and strategic partnerships with rheumatology practice networks.
Within the integrated biologic tier, Takeda Pharmaceutical Company Limited and Horizon Therapeutics plc occupy positions defined by infusion center network depth and refractory indication focus respectively. Novartis AG sits within the immunology infrastructure archetype, leveraging established rheumatology prescriber relationships that extend into gout management protocols. These three companies exemplify how manufacturing complexity and distribution integration separate premium-tier competitors from commodity-positioned alternatives.
| Leading Market Players |
|---|
| Takeda Pharmaceutical Company Limited |
| Horizon Therapeutics plc |
| AstraZeneca |
| Novartis AG |
| Merck & Co., Inc. |
| Teva Pharmaceutical Industries Ltd. |
| Regeneron Pharmaceuticals Inc. |
| GSK plc |
| Teijin Pharma Ltd. |
| Others |
Supply & Pricing Matrix
The Rhine-Ruhr pharmaceutical corridor's cold-chain logistics costs concentrate margin capture among integrated biologic manufacturers while compressing pricing power for generic urate-lowering agents that compete on ambient distribution economics. This freight-cost divergence separates orphan-disease biologic pricing from commodity small-molecule markets, with downstream price differentiation tracking directly to refrigerated fulfillment infrastructure ownership.
Pricing Analysis
The customization-premium spread between patient-administered subcutaneous formulations and clinic-based intravenous delivery spans three-tier pricing structure across premium, standard, and economy levels. Quality grade and certification level—specifically FDA orphan-drug designation versus standard NDA pathways—drive price differentiation, while volume scale compresses margins for generic allopurinol. Pricing pressure stems from biosimilar pipeline entry threatening IL-1 antagonist franchises. Hospital pharmacies exhibit highest price sensitivity due to 340B pricing exposure, whereas rheumatology centers demonstrate lowest sensitivity given prior authorization insulation.
Supply Chain Analysis
Upstream feedstock concentration for xanthine oxidase inhibitor precursors centers on India, China, and Germany under REACH-compliant sourcing arrangements. Active pharmaceutical ingredient synthesis draws from colchicine alkaloid extraction and recombinant protein fermentation platforms. Single-source dependencies for febuxostat intermediates create vulnerability to ECHA regulatory restriction. Distribution runs through three-tier wholesale for ambient small molecules and direct-to-infusion-center for cold-chain biologics.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The gout therapeutics market is recovering from biosimilar anticipation cyclicality, with refractory patient population expansion providing demand floor support through the analysis window.
For Market Incumbents: Insulate biologic pricing power through captive cold-chain infrastructure investment in United States hub-and-spoke networks. Deepen formulary committee relationships before IL-1 antagonist copies reach FDA submission. Prioritize backward integration into active pharmaceutical ingredient supply for febuxostat to offset European REACH compliance cost inflation. For New Entrants and Emerging Players: Establish a beachhead in India's generic febuxostat export market where CDSCO manufacturing incentives and surplus production capacity create white-space opportunity. Target Southeast Asian distribution partnerships leveraging Hyderabad-Bengaluru pharmaceutical corridor supply. Deploy direct-to-hospital contracting to bypass established wholesale markups. For Investors and Strategic Acquirers: Orphan-disease biologic developers with embedded infusion center partnerships represent the most defensible acquisition archetype against biosimilar displacement. Long-term viability hinges on real-world evidence generation capabilities satisfying EMA pharmacovigilance mandates. Watch for FDA accelerated approval pathway utilization rates as inflection indicator for development timeline compression.| Strategic Initiative | Industry Significance |
|---|---|
| Clinical Trial Advancement | Refractory gout protocols attract FDA priority review through orphan designation pathways. |
| Manufacturing Scale-Up | Sustained-release febuxostat capacity expansion serves Japan's aging demographic demand. |
| Regulatory Approval Pathway | EMA conditional marketing authorizations extend European exclusivity for biologic launches. |
| Licensing Agreement | Subcutaneous formulation technology partnerships enable home-infusion channel migration. |
| Pipeline Diversification | IL-6 pathway assets hedge against IL-1 antagonist biosimilar entry timelines. |
Research Methodology
A standing panel of drug development executives, regulatory affairs leads, formulary directors, and hospital procurement managers provided ongoing calibration across primary interview rounds. Secondary validation drew from FDA filings, EMA submissions, ClinicalTrials.gov records, and formulary databases. Bottom-up prescription volume modeling and top-down therapeutic category sizing were triangulated against payer claims data.
Scenario-bracketing framed demand projections across the analysis window, with segmentation dimensions spanning treatment line, dosage form, administration route, and regional regulatory cluster. CAGRs were derived from patient population epidemiology and therapy penetration curves. Forecast inputs incorporated prior authorization approval rate trajectories and biosimilar entry probability assessments.
Stress conditions across biosimilar launch timing, REACH compliance cost inflation, and cold-chain logistics disruption were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding orphan-drug pricing durability and rheumatology center expansion rates. Cross-checking against national health technology assessment body reimbursement decisions is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
North America Obsessive-Compulsive Disorder (OCD) Drugs Market
Pharmaceuticals
Loxoprofen Market
Pharmaceuticals
Global Oxytocin Market
Pharmaceuticals
Paclitaxel Injection Market
Pharmaceuticals
Global Pharmaceutical Drug Delivery Market
Pharmaceuticals
Artificial Intelligence in Drug Screening Market
Pharmaceuticals
North America SGLT2 Inhibitors Market
Pharmaceuticals
Global Alteplase Market
Pharmaceuticals
Oligonucleotide Therapeutics Market
Pharmaceuticals
Inhalation and Nasal Spray Generic Drugs Market
Pharmaceuticals
Africa Generic Pharmaceutical Market
Pharmaceuticals
Postmenopausal Vaginal Atrophy Drugs Market
Pharmaceuticals
Global Non-Small Cell Lung Cancer Drugs Market
Pharmaceuticals
Blood Coagulants Market
Pharmaceuticals
Calcineurin Inhibitor Drugs Market
Pharmaceuticals
Global Immune Checkpoint Inhibitors Market