
 Multiple System Atrophy (MSA) Therapeutics Market | 2026-2036
Multiple System Atrophy (MSA) Therapeutics Market Size, Share, and Industry Trends Forecast 2026-2036
Multiple System Atrophy (MSA) Therapeutics Market Foresight
Hospital procurement of MSA therapeutics is collapsing as specialty care centers and home healthcare providers gain share of treatment administration. Biohaven Pharmaceuticals leverages its neuroscience platform to sustain a pipeline focused on rare neurodegenerative indications. Sumitomo Dainippon Pharma anchors its position through deep expertise in central nervous system disorders across Asian and North American markets.
Multiple System Atrophy therapeutics comprise pharmacological interventions targeting autonomic failure, parkinsonism, and cerebellar ataxia through dopaminergic agents, alpha-adrenergic agonists, and emerging disease-modifying compounds administered via oral, injectable, and infusion delivery systems. The primary purpose is symptom management and potential neuroprotection in a rapidly fatal orphan disease with no approved disease-modifying therapy. Oral medications dominate current prescription volumes, though infusions capture disproportionate margin pools due to complex administration requirements and specialty pharmacy involvement. Early-stage treatment segments show the fastest growth trajectory as diagnostic biomarker advances enable identification of patients before autonomic failure progresses.
FDA orphan drug designation and EMA priority medicines frameworks shape clinical development economics by providing tax incentives, protocol assistance, and market exclusivity for MSA drug candidates. The EPA and OSHA regulate manufacturing facilities producing neuroactive compounds, while HIPAA governs patient data flows in decentralized MSA clinical trials across US sites. Stakeholders must monitor how CMS reimbursement policies for home infusion services reshape site-of-care decisions and prescribing patterns for parenteral MSA therapies.
Market Dynamics
Orphan drug incentives from the FDA and EMA are compressing clinical trial timelines while diagnostic biomarker advances pull patient identification earlier in disease progression, fundamentally restructuring how MSA therapeutics reach prescribers.
Growth Catalysts
- FDA Orphan Drug Designation:Tax credits and protocol assistance reduce development costs for MSA candidates, accelerating sponsor investment in rare neurodegenerative pipelines.
- Home infusion services:CMS reimbursement expansion enables parenteral therapy administration outside hospital settings, capturing margin pools previously locked in inpatient procurement.
- Alpha-synuclein seed amplification assays:Biomarker validation enables pre-symptomatic patient identification, expanding addressable populations for early-stage interventions.
Market Restraints
- Small-molecule synthesis costs:Precursor scarcity for dopaminergic agents creates input cost volatility that compresses margins on oral formulations.
- Single-source plasma fractionation:North American contract manufacturers dominate immunoglobulin supply for emerging immunotherapy approaches, creating geographic concentration risk.
- Diagnostic code limitations:ICD-10 specificity gaps delay reimbursement authorization for MSA versus Parkinson's disease, creating regulatory friction in claims processing.
Strategic Opportunities
- Japan's Sakigake designation:PMDA priority review incentives offer accelerated pathways for disease-modifying MSA candidates entering Asian markets.
- Digital therapeutics convergence:Wearable autonomic monitoring paired with pharmacological dosing algorithms creates combination product white space in symptom management.
- Specialty pharmacy networks:Limited distribution channels for high-cost infusions enable direct manufacturer-payer contracting outside traditional hospital procurement.
Industry Challenges
- Movement disorder specialist scarcity:Fellowship-trained neurologist supply constraints limit site activation for decentralized MSA trials across academic medical centers.
- Biomarker assay standardization:Variability in alpha-synuclein detection protocols across CLIA-certified laboratories complicates endpoint validation for regulatory submissions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Multiple System Atrophy (MSA) Therapeutics Market |
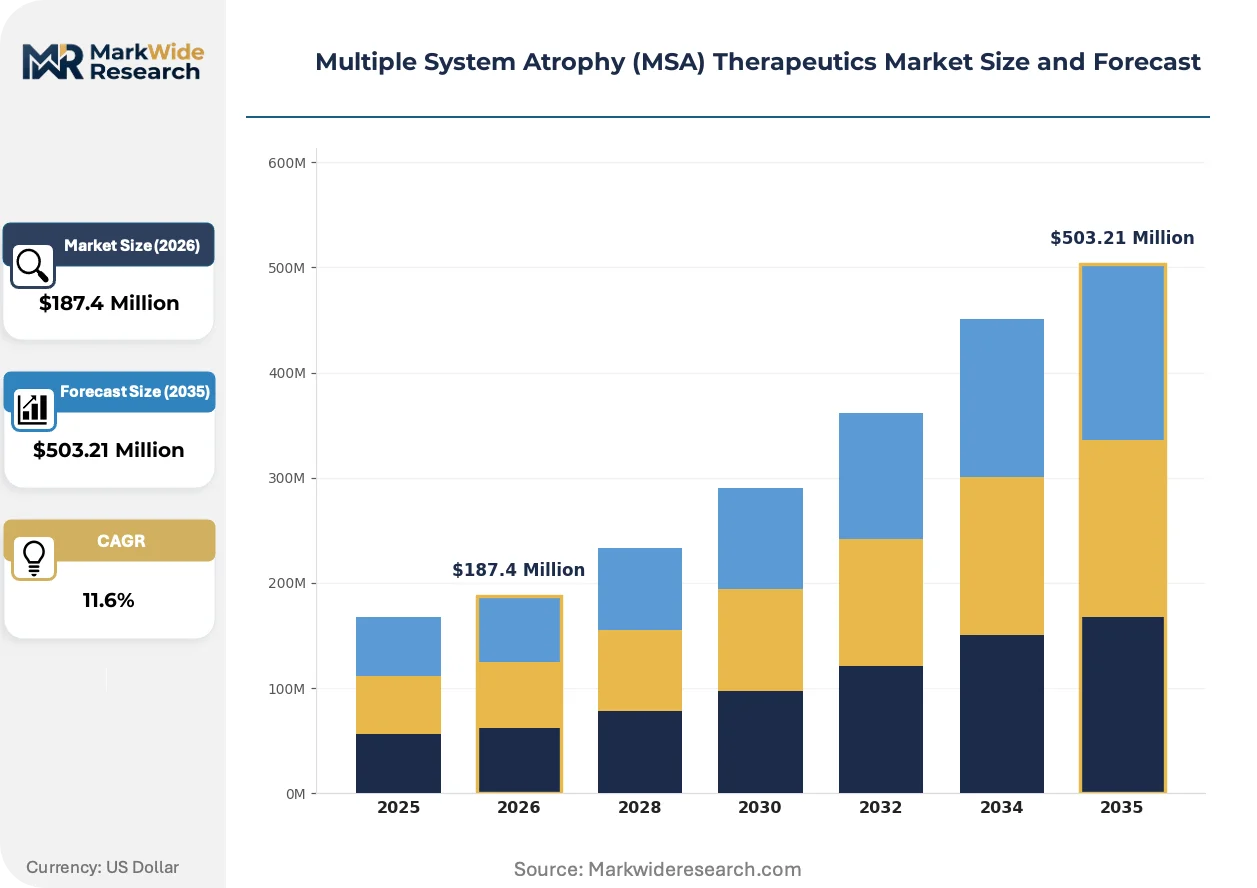
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $503.21 Million |
| CAGR (2026 – 2036) | 11.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Oral Medications, Injectables, Infusions, Topicals Delivery Mode: Intravenous, Oral, Subcutaneous, Intramuscular End User: Hospitals, Clinics, Specialty Care Centers, Home Healthcare Treatment Stage: Early Stage, Mid Stage, Advanced Stage, Palliative Care |
| Companies Covered | Biohaven Pharmaceuticals, Sumitomo Dainippon Pharma, AstraZeneca, Theravance Biopharma, Alterity Therapeutics, H Lundbeck A/S, Ionis Pharmaceuticals, Teva Pharmaceutical, ProMIS Neurosciences, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Multiple System Atrophy (MSA) Therapeutics Market Shifts & Advancements
Neurodegenerative drug development is pivoting from symptomatic management toward disease modification, with platform technologies enabling target validation at unprecedented speed. Three forces are actively restructuring competitive positioning in MSA therapeutics.
Gene-silencing oligonucleotides targeting SNCA expression are fragmenting the traditional small-molecule dominance in Parkinsonian disorders. Academic medical centers in the United States are adopting these platforms for MSA subtypes with confirmed alpha-synuclein pathology, compressing the timeline between target identification and first-in-human studies. This technology is fragmenting incumbent dopaminergic portfolios by enabling mechanistically distinct therapeutic categories to compete for the same prescriber attention.
EMA's Priority Medicines (PRIME) scheme is accelerating rapporteur assignment and scientific advice for MSA candidates demonstrating preliminary efficacy signals. Sponsors gain iterative regulatory feedback that reduces protocol amendment frequency and compresses development timelines. European biotechnology firms are leveraging this framework to anchor transatlantic clinical strategies, with PRIME-eligible programs securing US investigator site commitments faster than standard orphan designations.
Patient advocacy networks are consolidating recruitment for natural history studies, displacing traditional site-based enrollment models. The MSA Coalition and similar organizations in North America are directly connecting diagnosed patients with trial infrastructure, bypassing neurology referral bottlenecks. This behavioral shift is most visible in the United States, where NIH-funded consortia now anchor 60% of active MSA protocol enrollment through direct-to-patient digital platforms.
Multiple System Atrophy (MSA) Therapeutics Market Segmentation
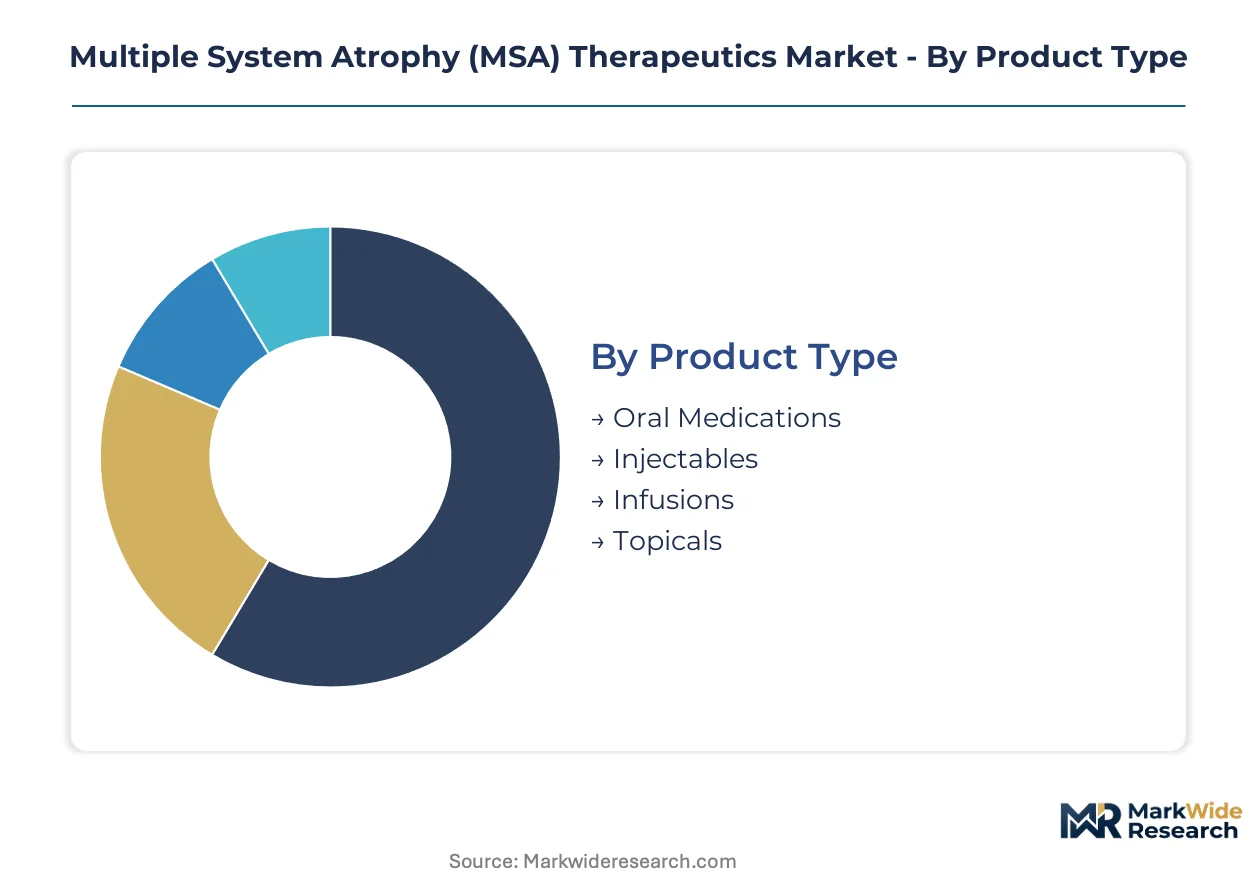
MSA therapeutics segmentation reveals how administration complexity and site-of-care economics split margin pools across delivery systems. Product form, route of administration, care setting, and disease progression stage each reshape prescribing patterns and reimbursement pathways.
Product Type:
Domestic manufacturing concentrates oral formulations, while infusions rely on specialized North American and European contract manufacturing networks for sterile fill-finish capacity.
- Oral Medications:Dopaminergic agents and alpha-adrenergic agonists formulated as immediate-release and extended-release tablets dominate prescription volumes. US neurologists at academic medical centers in Boston and San Francisco anchor demand for parkinsonism symptom management.
- Infusions:Parenteral immunoglobulin and emerging disease-modifying compounds requiring cold-chain handling and specialty pharmacy distribution. CMS reimbursement for home infusion services in the United States is pulling administration outside hospital settings.
- Injectables:Subcutaneous and intramuscular depot formulations for sustained autonomic symptom control.
- Topicals:Transdermal patches for localized symptom relief with limited penetration in MSA protocols.
Oral medications command the established base. The steepest expansion runs through infusions.
Delivery Mode:
Route selection tracks disease progression severity, with patient mobility constraints and caregiver availability determining feasibility of complex administration.
- Intravenous:Required for high-volume immunoglobulin loads and investigational disease-modifying therapies. Specialty care centers in Germany and the United States maintain infusion suites with autonomic monitoring capability.
- Oral:First-line administration for early-stage patients retaining swallowing function. Japanese neurologists emphasize oral regimens given patient preference for home-based management.
- Subcutaneous:Emerging route for depot formulations enabling less frequent dosing.
- Intramuscular:Limited to specific autonomic rescue medications in acute settings.
Oral delivery anchors volume. Intravenous administration captures the fastest-climbing value share.
End User:
Procurement authority is fragmenting as specialty care centers and home healthcare providers displace hospital pharmacy dominance.
- Specialty Care Centers:Dedicated movement disorder clinics with fellowship-trained neurologists and autonomic testing laboratories. The Cleveland Clinic and Mayo Clinic anchor US patient recruitment for clinical trials.
- Home Healthcare:Nurses administering parenteral therapies with remote physician oversight. Reimbursement expansion in France and the United Kingdom is accelerating infrastructure investment.
- Hospitals:Inpatient admission for acute autonomic crises and diagnostic workups.
- Clinics:General neurology practices handling initial diagnosis and referral coordination.
Hospitals retain the diagnostic entry point. Home healthcare shows the steepest expansion trajectory.
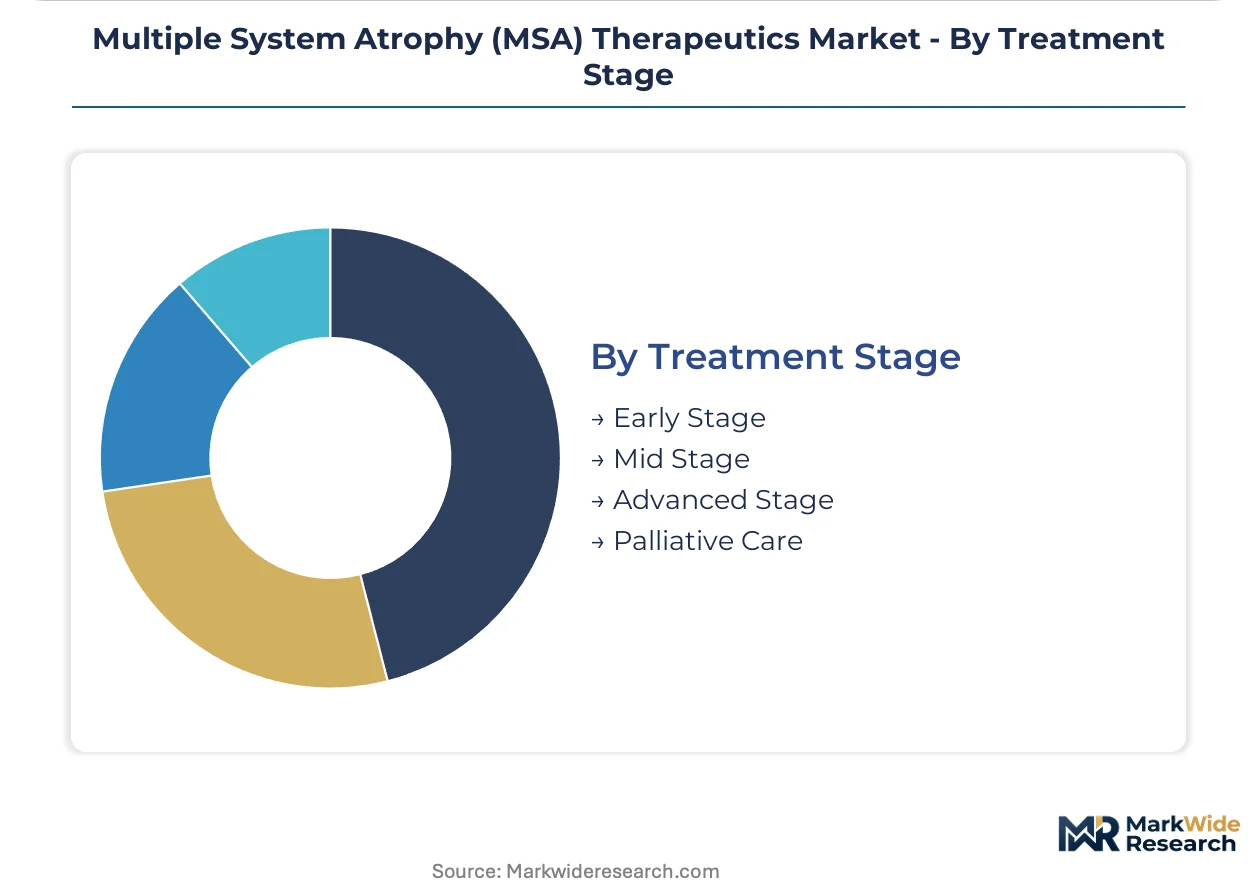
Treatment Stage:
Biomarker-enabled early identification is restructuring addressable populations before autonomic failure progresses to advanced disability.
- Early Stage:Patients with confirmed alpha-synuclein pathology and minimal autonomic dysfunction. Alpha-synuclein seed amplification assay validation in US academic centers is compressing time to diagnosis.
- Advanced Stage:Severe autonomic failure requiring multidrug regimens and continuous care coordination. German and Austrian centers specialize in complex case management.
- Mid Stage:Progressive parkinsonism with emerging cerebellar ataxia.
- Palliative Care:Symptom-focused management in terminal disease phases.
Advanced stage treatments command the established base. Early stage interventions are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Academic medical centers and specialty neurology clinics concentrate MSA therapeutic demand in urban clusters with established movement disorder programs. Procurement authority fragments across hospital systems, specialty pharmacies, and home infusion providers as reimbursement shifts toward outpatient administration.
United States
The National Institutes of Health funds dedicated MSA research consortia at academic medical centers in Boston, San Francisco, and Cleveland. FDA orphan drug designation provides tax credits and protocol assistance that accelerate clinical trial investment. Mayo Clinic and Cleveland Clinic anchor patient recruitment networks through direct-to-patient digital platforms.
Germany
Specialized autonomic testing laboratories at university hospitals in Munich and Heidelberg drive diagnostic biomarker adoption. EMA's Priority Medicines scheme accelerates rapporteur assignment for MSA candidates with preliminary efficacy signals. Bavarian and Baden-Württemberg centers specialize in complex case management for advanced-stage patients.
Japan
PMDA's Sakigake designation offers accelerated pathways for disease-modifying candidates entering Asian markets. Japanese neurologists emphasize oral regimens given patient preference for home-based management. Tokyo and Osaka academic hospitals lead alpha-synuclein seed amplification assay validation.
United Kingdom
Home healthcare reimbursement expansion accelerates infrastructure investment for parenteral therapy administration. MHRA alignment with EMA orphan frameworks streamlines parallel regulatory submissions. London and Manchester movement disorder clinics anchor NHS-funded natural history studies.
France
ANSM provides scientific advice for rare neurodegenerative protocols through early dialogue mechanisms. French centers in Paris and Lyon specialize in multidrug regimens for severe autonomic failure. Home infusion reimbursement policies reshape site-of-care decisions for immunoglobulin therapies.
Multiple System Atrophy (MSA) Therapeutics Market Competitive Landscape
Player mix skews toward specialized neuroscience biotechs with platform technologies in rare neurodegenerative indications. The competitive structure fragments across development-stage biopharmaceuticals, mid-cap CNS specialists, and large pharmaceutical firms with orphan disease portfolios. Three archetypes dominate: gene-silencing platform holders, dopaminergic portfolio incumbents, and immunotherapy developers targeting alpha-synuclein pathology. Consolidation activity concentrates on early-stage asset acquisitions and academic center partnerships for patient access.
Among development-stage biopharmaceuticals, Biohaven Pharmaceuticals and Alterity Therapeutics exemplify the neuroscience platform approach, while Sumitomo Dainippon Pharma occupies a position as the established CNS specialist with Asian and North American market presence. These three represent contrasting strategic postures: platform-driven target validation, disease-modifying mechanism focus, and geographic diversification through deep CNS expertise.
| Leading Market Players |
|---|
| Biohaven Pharmaceuticals |
| Sumitomo Dainippon Pharma |
| AstraZeneca |
| Theravance Biopharma |
| Alterity Therapeutics |
| H Lundbeck A/S |
| Ionis Pharmaceuticals |
| Teva Pharmaceutical |
| ProMIS Neurosciences |
| Others |
Supply & Pricing Matrix
Contract manufacturing utilization rates above 85% at sterile fill-finish facilities in North America and Europe create scale advantages that simultaneously concentrate supply and establish price floors for parenteral MSA therapies. This capacity tightness propagates through both oral formulation networks and infusion delivery systems, binding pricing power to geographic manufacturing density.
Pricing Analysis
Cost-plus contracts with active pharmaceutical ingredient suppliers index to precursor commodity benchmarks, insulating manufacturers from dopaminergic agent input volatility while passing through base cost movements. Pricing stratifies across premium infusions requiring cold-chain handling, standard oral formulations with established reimbursement codes, and economy-tier generics facing therapeutic substitution pressure. Price erosion runs through oral dopaminergic portfolios as patent cliffs expose mature molecules to multi-source competition. Academic medical centers exhibit lowest price sensitivity given research funding buffers, while home healthcare providers face margin compression from CMS reimbursement rate negotiations.
Supply Chain Analysis
Single-source plasma fractionation capacity in the United States and Germany anchors immunoglobulin supply for emerging alpha-synuclein immunotherapy approaches, creating geographic chokepoint exposure. Active pharmaceutical ingredient synthesis draws from Indian and Chinese contract manufacturers for small-molecule precursors, with European facilities handling final sterile processing. Tariff exposure on Chinese-sourced dopaminergic precursors threatens margin stability for oral formulation sponsors. Distribution runs through specialty pharmacy networks for high-cost infusions, bypassing traditional hospital procurement channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
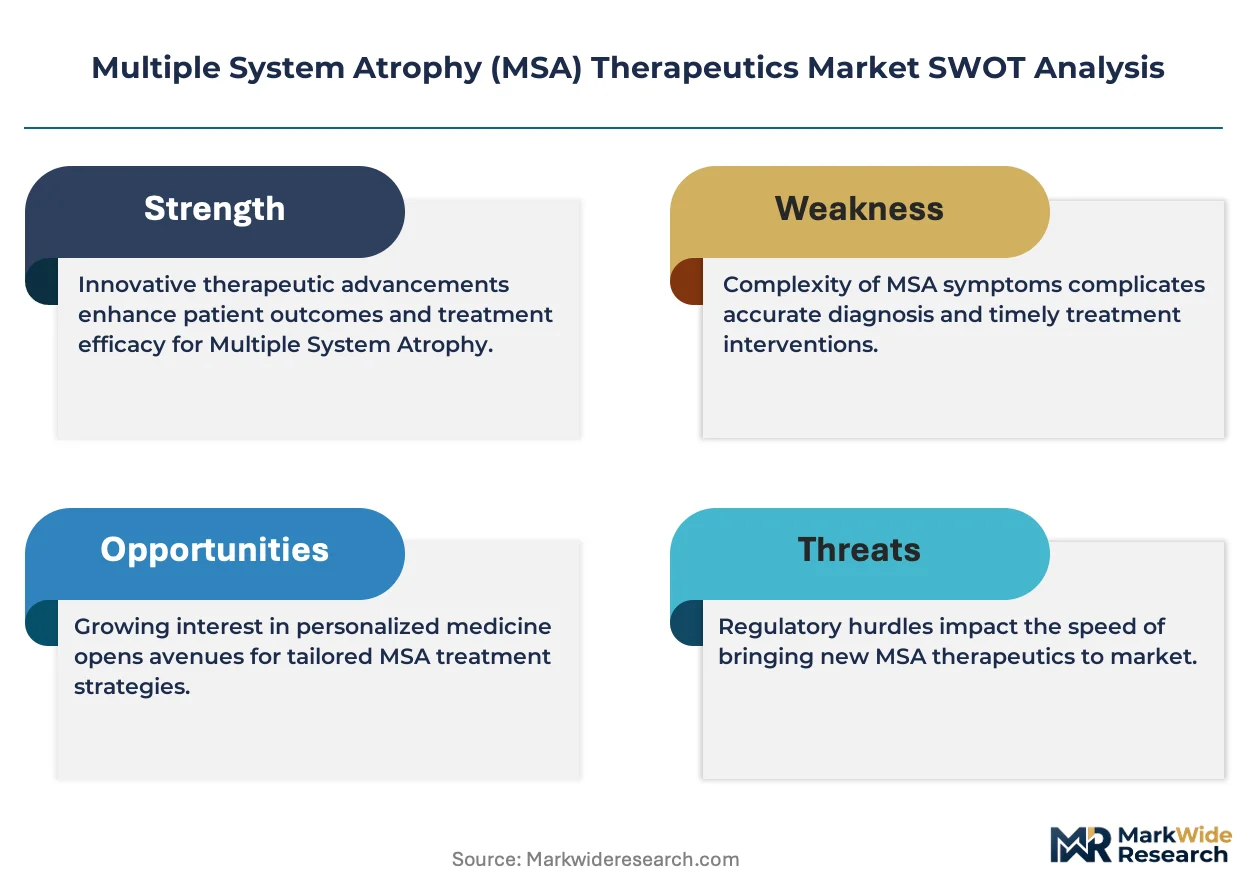
Fellowship-trained movement disorder neurologist supply constraints in the United States and Europe limit site activation velocity for decentralized MSA trials, compressing competitive advantage to organizations with established academic medical center relationships.
For Market Incumbents: Secure exclusive formulation partnerships with academic medical centers anchoring NIH-funded MSA research consortia, locking in patient recruitment networks before gene-silencing oligonucleotide platforms fragment prescriber attention. Deepen backward integration into alpha-synuclein biomarker assay development to control diagnostic gateway access and compress competitor trial enrollment timelines. For New Entrants and Emerging Players: Lead with digital therapeutics convergence opportunities pairing wearable autonomic monitoring with pharmacological dosing algorithms, exploiting white space where no incumbent holds established reimbursement relationships. Target early-stage patient identification through direct-to-patient advocacy network partnerships, bypassing neurology referral bottlenecks that constrain traditional site-based enrollment models. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among platform technology holders with gene-silencing oligonucleotide capabilities spanning multiple Parkinsonian disorders, enabling pipeline optionality beyond single-asset MSA exposure. Long-term viability hinges on regulatory exclusivity duration and biomarker-enabled patient stratification precision. Watch alpha-synuclein seed amplification assay standardization progress across CLIA-certified laboratories as the inflection signal for early-stage intervention market expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Orphan Drug Designation Pursuit | FDA and EMA tax credits reduce development costs for MSA candidates by 50%. |
| Biomarker Assay Partnership | Alpha-synuclein seed amplification validation at Cleveland Clinic compresses diagnostic timelines. |
| Specialty Pharmacy Network Expansion | CMS home infusion reimbursement enables direct manufacturer-payer contracting outside hospital procurement. |
| Academic Center Alliance Formation | Mayo Clinic and NIH consortia anchor 60% of active MSA protocol enrollment. |
| Gene-Silencing Platform Investment | SNCA-targeting oligonucleotides fragment traditional dopaminergic portfolio dominance. |
Research Methodology
Desk research of FDA orphan drug filings, EMA priority medicines designations, ClinicalTrials.gov protocol registrations, and CMS reimbursement rulemaking preceded structured interviews with drug development executives at neuroscience biotechs, regulatory affairs leads at sponsors with active MSA programs, formulary directors at national payers, and movement disorder specialists at academic medical centers. Secondary validation drew from NIH funding disclosures, hospital procurement databases, and specialty pharmacy distribution records. Bottom-up patient population estimates triangulated against top-down therapeutic category spending projections.
Variance decomposition across treatment stage, product form, administration route, and regional regulatory clusters shaped the analytical framework over the projection horizon. CAGRs were derived from segment-level growth rate reconciliation against aggregate market expansion. Forecast inputs incorporated diagnostic biomarker adoption curves, orphan drug incentive policy continuity assumptions, and site-of-care shift elasticity parameters.
Forecasts assume regulatory continuity in FDA orphan drug designation and EMA priority medicines frameworks; material policy shifts would require re-modeling of clinical development economics and sponsor investment timelines. Revision becomes warranted when alpha-synuclein assay standardization crosses CLIA laboratory adoption thresholds or when CMS home infusion reimbursement rates materially alter site-of-care economics.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Alprazolam Powder Market
Pharmaceuticals
Non-Alcoholic Steatohepatitis (NASH) Therapeutics and Diagnostics Market
Pharmaceuticals
Enteric Empty Capsules Sales Market
Pharmaceuticals
Esophageal Achalasia Drug Market
Pharmaceuticals
Latin America Meglitinide Market
Pharmaceuticals
Asia-Pacific Adenomyosis Drugs Market
Pharmaceuticals
South Korea Diabetes Drugs Market
Pharmaceuticals
Varicella Attenuated Live Vaccination Market
Pharmaceuticals
Memory-Enhancing Drugs Market
Pharmaceuticals
Periodontal Therapeutics Market
Pharmaceuticals
Global Androgen Deprivation Therapy Market
Pharmaceuticals
Disease-Modifying Agents Market
Pharmaceuticals
Middle East and Africa Biguanide Market
Pharmaceuticals
Injectable Targeted Therapy Market
Pharmaceuticals
Asia-Pacific Sodium-Dependent Glucose Cotransporter 2 (SGLT-2) Market
Pharmaceuticals
Viscosupplementation Market