
 Ramipril Market | 2026-2036
Ramipril Market Size, Share, and Industry Trends Forecast 2026-2036
Ramipril Market Analysis
The Ramipril market is splitting along a clear fault line between premium branded formulations and commoditized generic supply. Dr. Reddy's Laboratories leverages its vertically integrated API-to-finished-dose model to compete aggressively on cost in regulated export markets. Sanofi anchors its position through sustained investment in physician-facing brand equity and clinical data generation for its originator product. Teva Pharmaceutical Industries specializes in complex generic formulations that navigate tighter bioequivalence standards in the United States and European Union.
Ramipril is an angiotensin-converting enzyme (ACE) inhibitor, specifically a prodrug hydrolyzed in the liver to its active metabolite ramiprilat, with standard oral dosing typically ranging from 2.5 mg to 10 mg daily for hypertension management. Its primary therapeutic purpose centers on reducing blood pressure and cardiovascular mortality risk through inhibition of the renin-angiotensin-aldosterone system. Generic oral tablets dominate volume due to payer-driven substitution policies, while combination therapy pairing ramipril with hydrochlorothiazide or amlodipine captures expanding share in polypharmacy protocols for resistant hypertension. Hospital procurement channels for injectable delivery modes remain concentrated among a narrower supplier base with higher compliance burdens.
FDA bioequivalence standards and EMA's quality-by-design frameworks collectively elevate manufacturing barriers for new market entrants, while India's CDSCO enforces escalating local clinical trial requirements for imported formulations. These regulatory layers shape demand toward established manufacturers with proven compliance track records and dedicated regulatory affairs infrastructure. Stakeholders must monitor evolving pharmacovigilance obligations and tightening environmental standards for ACE inhibitor API synthesis as determinants of sustainable competitive position.
Market Dynamics
Generic commoditization of oral ACE inhibitors has compressed margins across the value chain while simultaneously expanding volume access, forcing manufacturers to compete on bioequivalence documentation speed and API synthesis cost rather than clinical differentiation.
Growth Catalysts
- EMA Quality-by-Design Mandates:Accelerated adoption of continuous manufacturing platforms reduces batch failure rates and shortens regulatory review timelines for generic filers.
- Polypharmacy Protocols:Fixed-dose combinations pairing ramipril with hydrochlorothiazide or amlodipine capture expanding prescription volume in resistant hypertension management.
- India:Domestic API production capacity and finished-dose export infrastructure both scale rapidly, lowering landed costs in regulated markets.
Market Restraints
- API Supply Concentration:Key intermediate manufacturing for ACE inhibitor precursors clusters in specific coastal industrial zones, creating single-point vulnerability.
- FDA Bioequivalence Standards:Tightening pharmacokinetic equivalence thresholds for highly variable drugs extend development timelines and raise clinical trial costs for new entrants.
- ARB Substitution:Angiotensin receptor blockers with superior side-effect profiles displace ACE inhibitors in first-line hypertension protocols across several national formularies.
Strategic Opportunities
- Hospital Injectable Segment:Narrow supplier base and higher compliance burdens create defensive margin pools for manufacturers with sterile fill-finish capabilities.
- CDSCO Localization Requirements:India's escalating domestic clinical trial mandates for imported formulations advantage local manufacturers with established investigator networks.
- Renal Indication Expansion:Diabetic nephropathy protocols beyond hypertension represent underpenetrated therapeutic positioning for ACE inhibitor therapy.
Industry Challenges
- Pharmacovigilance Infrastructure:Post-market surveillance obligations for generic ACE inhibitors require dedicated adverse event processing capabilities that strain mid-tier regulatory affairs teams.
- Environmental Compliance:API synthesis for ACE inhibitors involves solvent-intensive steps now subject to tightening MEE discharge standards and carbon intensity tracking.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Ramipril Market |
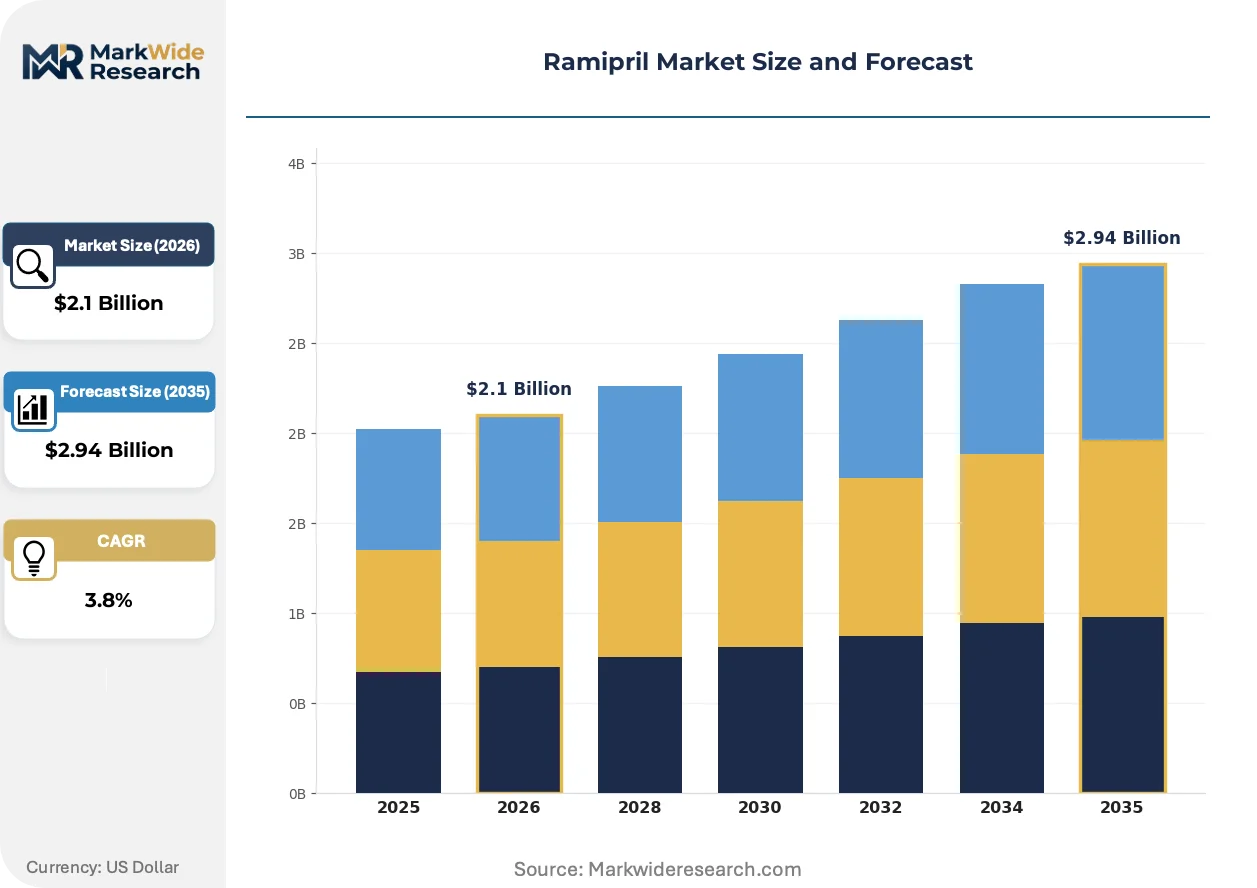
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $2.94 Billion |
| CAGR (2026 – 2036) | 3.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Generic, Branded, Combination Therapy, Extended Release End User: Clinics, Hospitals, Pharmacies, Home Care Delivery Mode: Oral, Injectable, Sublingual, Transdermal Therapy Area: Hypertension, Heart Failure, Cardiovascular Disease, Kidney Disease |
| Companies Covered | Dr. Reddy's Laboratories, Cipla, Sanofi, Teva Pharmaceutical Industries, Sun Pharmaceutical Industries, Novartis AG, Lupin, Sandoz, Pfizer Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Ramipril Market Emerging Trajectories
Continuous processing technologies and real-time release testing protocols are compressing manufacturing cycle times while regulatory convergence around ICH guidelines is harmonizing submission requirements across major markets.
Continuous direct compression platforms for oral solid dosage forms are unifying granulation, drying, and tableting into integrated single-pass systems. Contract manufacturers serving the generic ACE inhibitor market adopt these platforms to reduce equipment footprint and accelerate batch release. This technology is unifying quality control with production execution, enabling real-time release testing that eliminates traditional quarantine periods.
EMA's revised guideline on bioequivalence for highly variable drugs now permits reference-scaled average bioequivalence approaches that reduce sample size requirements for certain ACE inhibitor formulations. This regulatory evolution lowers clinical development costs for generic sponsors while maintaining statistical rigor. European Union filers with established quality management systems capture first-mover advantage under the streamlined framework.
Hospital procurement consortia in Germany and France now aggregate purchasing for injectable cardiovascular therapies through single-tender frameworks that favor dual-source supply security over lowest-unit-cost bids. This buyer concentration displaces fragmented hospital-level contracting and rewards manufacturers with redundant manufacturing sites. The shift is most visible in university hospital networks where pharmacy committees prioritize supply continuity metrics.
Ramipril Market Segmentation
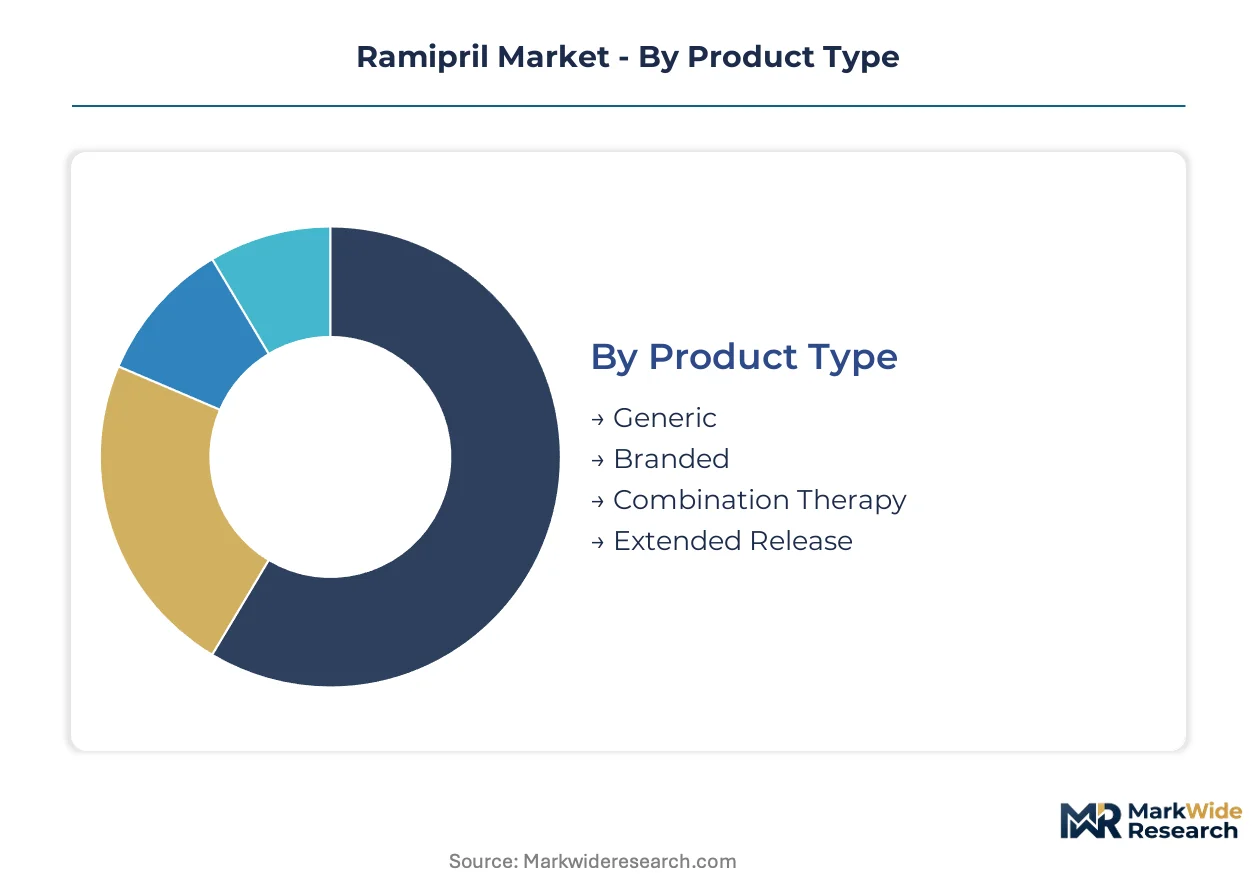
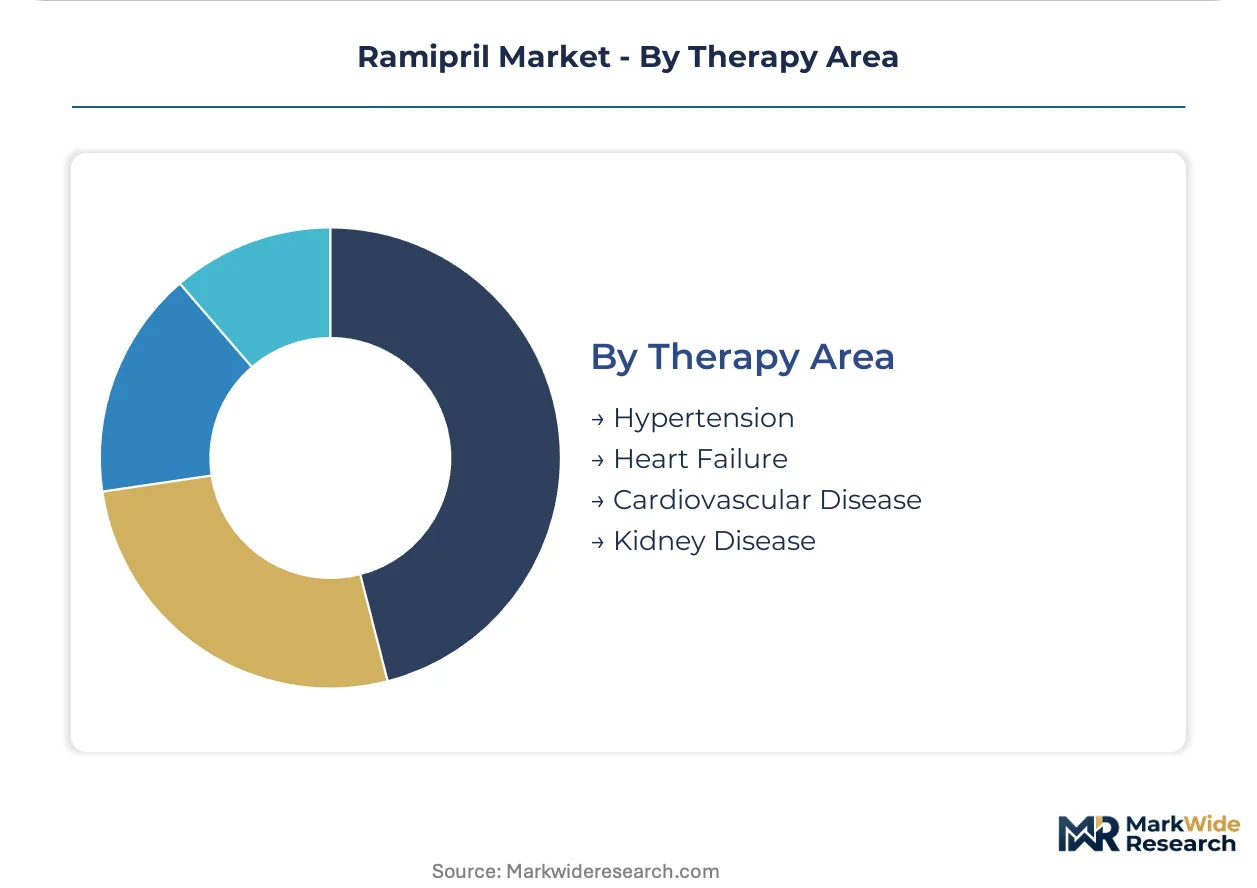
Ramipril market segmentation reveals distinct competitive battlegrounds where regulatory compliance, reimbursement policy, and clinical protocol preferences determine commercial outcomes. Each dimension carries unique margin structures and entry barriers that shape manufacturer positioning strategies.
Product Type:
Payer substitution policies and bioequivalence documentation requirements drive procurement decisions across formulation categories.
- Generic:Standard oral tablets and capsules manufactured to FDA and EMA bioequivalence standards dominate prescription volume through mandatory pharmacy-level substitution. India's CDSCO-registered manufacturers capture expanding export share to regulated markets through cost-competitive API-to-finished-dose supply chains.
- Combination Therapy:Fixed-dose formulations pairing ramipril with hydrochlorothiazide or amlodipine address resistant hypertension protocols. German and French hospital consortia increasingly specify these combinations in cardiovascular therapy tenders to simplify polypharmacy regimens.
- Branded:Originator formulations maintain position through physician-facing clinical data generation and formulary retention in markets with weaker generic substitution mandates.
- Extended Release:Modified-release technologies improve dosing compliance in chronic therapy settings, though bioequivalence demonstration for these formulations demands more complex pharmacokinetic studies.
Generic formulations lead on scale; combination therapy leads on momentum.
End User:
Procurement authority and compliance burden intensity vary sharply across care settings, fragmenting pricing and service requirements.
- Hospitals:Injectable ramipril concentrates in acute cardiovascular and perioperative settings where pharmacy committees prioritize supply continuity and sterile manufacturing validation. German university hospital networks now aggregate purchasing through single-tender frameworks favoring dual-source suppliers.
- Pharmacies:Retail dispensing channels process the majority of oral generic volume under mandatory substitution policies, with reimbursement rates set by national health technology assessment bodies.
- Clinics:Outpatient cardiology and nephrology practices prescribe combination therapies and branded formulations where prior authorization requirements permit.
- Home Care:Long-term hypertension management in aged populations drives demand for simplified dosing regimens and blister packaging for medication adherence support.
Pharmacies lead on scale; hospitals lead on margin capture.
Delivery Mode:
Manufacturing complexity and regulatory pathway requirements create tiered competitive entry barriers.
- Oral:Tablets and capsules represent the standard-of-care delivery mechanism, with continuous direct compression platforms enabling real-time release testing that shortens batch quarantine periods.
- Injectable:Sterile fill-finish capabilities for intravenous ramipril concentrate supply in emergency hypertension and acute heart failure settings. Narrow supplier base and higher compliance burdens protect margins for established manufacturers.
- Sublingual:Rapid-onset formulations for acute blood pressure management in pre-hospital and emergency department settings, though clinical adoption remains limited by taste masking challenges.
- Transdermal:Patch-based delivery systems under development for geriatric populations with swallowing difficulties, facing skin permeation and adhesion consistency hurdles.
Oral delivery leads on scale; injectable leads on defensive margin pools.
Therapy Area:
Clinical guideline positioning and comorbidity prevalence patterns determine addressable patient populations.
- Hypertension:Primary indication driving the majority of ramipril prescriptions, with first-line ACE inhibitor protocols varying across national formularies based on comparative effectiveness data against ARB alternatives.
- Cardiovascular Disease:Secondary prevention indications post-myocardial infarction where ramipril's mortality benefit documentation supports continued preference despite generic availability.
- Heart Failure:Reduced ejection fraction protocols incorporating ACE inhibitors as foundational therapy, with dosing titration requirements favoring flexible tablet strengths.
- Kidney Disease:Diabetic nephropathy and chronic kidney disease progression slowing represent underpenetrated positioning opportunities where albuminuria reduction data could expand clinical utility.
Hypertension leads on scale; kidney disease leads on expansion potential.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized formulation chemists and regulatory affairs professionals concentrate in pharmaceutical manufacturing clusters across India, Germany, the United States, France, and Japan. These talent pools anchor production capacity and compliance infrastructure for ACE inhibitor supply chains.
India
Domestic API synthesis and finished-dose export infrastructure both scale rapidly, with CDSCO escalating local clinical trial requirements for imported formulations. The country's national pharmaceutical regulator enforces bioequivalence documentation standards that align with FDA and EMA precedents. Hyderabad and Mumbai host vertically integrated manufacturers supplying regulated markets in North America and Europe.
Germany
University hospital procurement consortia aggregate purchasing for injectable cardiovascular therapies through single-tender frameworks favoring dual-source suppliers. EMA quality-by-design mandates accelerate adoption of continuous manufacturing platforms among domestic filers. The Rhine-Main and Bavarian industrial corridors concentrate sterile fill-finish capabilities for hospital-grade ramipril supply.
United States
Payer-driven pharmacy substitution policies channel prescription volume toward FDA-approved generic tablets and capsules. The national pharmaceutical regulator maintains tightening pharmacokinetic equivalence thresholds for highly variable drugs that extend development timelines. New Jersey and North Carolina host contract manufacturers with dedicated regulatory affairs infrastructure for ANDA submissions.
France
Hospital pharmacy committees prioritize supply continuity metrics for acute cardiovascular therapies in university hospital networks. ANSM pharmacovigilance obligations require dedicated adverse event processing capabilities for generic ACE inhibitors. The Paris-Saclay cluster anchors clinical trial infrastructure supporting originator brand positioning.
Japan
PMDA review timelines for generic formulations compress as quality management system certifications streamline approval pathways. The national pharmaceutical regulator harmonizes bioequivalence standards with ICH guidelines. The Kanto region around Tokyo concentrates formulation development talent serving both domestic and export markets.
Ramipril Market Vendor Landscape
Top-tier vendors anchor originator and complex generic positions, while mid-tier specialists compete on API cost and bioequivalence documentation speed. The vendor base spans vertically integrated Indian conglomerates, European hospital-focused suppliers, and North American generic filers with sterile manufacturing capabilities. Three archetypes dominate: originator brand defenders, high-volume generic exporters, and hospital injectable specialists. Consolidation pressure and continuous manufacturing technology licensing represent the dominant competitive moves reshaping positioning.
Within the originator-brand tier, Sanofi anchors physician-facing clinical data generation for its established ACE inhibitor portfolio. Dr. Reddy's Laboratories and Teva Pharmaceutical Industries exemplify the generic-filer archetype, with the former representing vertically integrated API-to-finished-dose supply chains and the latter occupying a position in complex formulation navigation of tightened bioequivalence standards. Cipla, Lupin, and Sun Pharmaceutical Industries sit within the Indian export-specialist cluster competing on landed cost in regulated markets.
| Leading Market Players |
|---|
| Dr. Reddy's Laboratories |
| Cipla |
| Sanofi |
| Teva Pharmaceutical Industries |
| Sun Pharmaceutical Industries |
| Novartis AG |
| Lupin |
| Sandoz |
| Pfizer Inc. |
| Others |
Supply Flow & Price Mechanics
Hospital procurement consortia in Germany and France demanding dual-source supply security for injectable cardiovascular therapies are forcing manufacturers to duplicate sterile fill-finish capacity, elevating fixed cost absorption and compressing margins for single-site operators while rewarding redundant infrastructure investments with pricing power in acute care channels.
Pricing Analysis
Bundled sterile manufacturing validation and unbundled commodity tablet supply define the pricing architecture. Three-tier pricing structure across premium, standard, and economy levels separates originator brands with clinical data packages from FDA-approved generics and unregistered export alternatives. Price differentiation hinges on bioequivalence documentation completeness and sterile manufacturing certification tier. Cost compression in oral generic tablets is intensifying because India's CDSCO-registered manufacturers scale API-to-finished-dose exports. Retail pharmacy chains exhibit highest price sensitivity through mandatory substitution policies, while hospital pharmacy committees prioritize supply continuity over unit cost.
Supply Chain Analysis
Freight cost volatility for temperature-controlled pharmaceutical shipments is reshaping regional sourcing preferences among European hospital networks. API synthesis for ACE inhibitors concentrates in India, China, and Italy, with Hyderabad and Mumbai anchoring vertically integrated export infrastructure. Key intermediate manufacturing draws from solvent-intensive chemical precursors, specialized catalysts, and purified water systems. Single-source vulnerability clusters in coastal industrial zones exposed to extreme weather disruption. Distribution runs through national wholesale distributors serving retail pharmacies, with direct-to-hospital contracts dominating injectable channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Ramipril market functions as a stable compounder anchored by chronic disease prevalence that sustains replacement demand regardless of economic cycles.
For Market Incumbents: Hedge against ARB substitution pressure by accelerating fixed-dose combination development with hydrochlorothiazide or amlodipine, capturing polypharmacy protocol share. Secure redundant sterile manufacturing sites to qualify for German and French hospital consortia tenders. Backward integration into API synthesis insulates margin from intermediate supply shocks. For New Entrants and Emerging Players: The gap between premium branded formulations and economy unregistered imports creates white-space opportunity in mid-tier FDA-approved generics with accelerated bioequivalence documentation. Target India's escalating CDSCO localization requirements by establishing domestic clinical trial investigator networks. Pursue contract manufacturing partnerships with European hospital-focused suppliers lacking Indian API access. For Investors and Strategic Acquirers: Asymmetric upside sits with sterile injectable specialists possessing dual-source manufacturing validation and established European hospital consortia relationships. Long-term viability over a multi-year horizon favors manufacturers with captive API supply and continuous manufacturing platform adoption. Monitor EMA quality-by-design implementation timelines as inflection indicator for regulatory compliance cost escalation.| Strategic Initiative | Industry Significance |
|---|---|
| Continuous Manufacturing Platform Adoption | EMA quality-by-design mandates reward early adopters with shortened regulatory review timelines. |
| Fixed-Dose Combination Development | Polypharmacy protocols for resistant hypertension expand addressable prescription volume beyond monotherapy. |
| Sterile Fill-Finish Capacity Expansion | Hospital consortia tenders favor dual-source suppliers with redundant manufacturing site validation. |
| API Synthesis Backward Integration | Captive intermediate production insulates margin from coastal industrial zone supply disruptions. |
| CDSCO Clinical Trial Infrastructure | India's localization requirements advantage manufacturers with established domestic investigator networks. |
Methodological Framework
Coverage spans North America, Europe, and Asia-Pacific, with primary inputs from each region combined with secondary validation across regulatory filings and trade databases. Primary interviews engaged regulatory affairs directors at generic filers, hospital procurement managers in German university networks, formulary directors at French ANSM, and API synthesis plant managers in Hyderabad and Mumbai. Secondary sources triangulated FDA ANDA approvals, EMA bioequivalence guidelines, CDSCO import registration data, and customs export statistics from India's DGFT. Bottom-up prescription volume modeling and top-down pharmaceutical market sizing were cross-validated.
Granularity-level modeling operated at dosage form, delivery mode, therapy area, and regional regulatory cluster dimensions throughout the forecast period. CAGRs were derived from patient population epidemiology, treatment protocol evolution, and generic substitution elasticity by market. Industry-specific inputs incorporated ACE inhibitor protocol share displacement by ARBs, continuous manufacturing adoption curves, and hospital consortia tender aggregation patterns.
Caveats apply where ARB substitution acceleration, bioequivalence standard tightening, or environmental compliance cost spikes could materially shift the outlook. Forecasts reflect assumptions around regulatory pathway stability and chronic disease prevalence trends. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Meglitinide Market
Pharmaceuticals
Repurposed Human Immunosuppressants Market
Pharmaceuticals
Spain Opioids Market
Pharmaceuticals
Iceland Pharmaceutical Market
Pharmaceuticals
Traumatic Brain Injury Drugs Market
Pharmaceuticals
Global Rx to OTC Switches Market
Pharmaceuticals
Intravenous Solution Compounders Market
Pharmaceuticals
Allergic Rhinitis Drugs Market
Pharmaceuticals
Short-Acting Beta-Agonists Market
Pharmaceuticals
Pentoxyverine Market
Pharmaceuticals
Global Pharmaceutical Drug Delivery Market
Pharmaceuticals
Oligonucleotide Therapeutics Market
Pharmaceuticals
Germany Pharmaceutical Cold Chain Logistics Market
Pharmaceuticals
Long-Acting Insulin Market
Pharmaceuticals
Ebola Drug and Vaccine Market
Pharmaceuticals
Monkeypox Vaccine and Treatment Market