
 New Zealand Diabetes Drugs Market | 2026-2036
New Zealand Diabetes Drugs Market Size, Share, and Industry Trends Forecast 2026-2036
New Zealand Diabetes Drugs Market Foresight
Project finance for hospital pharmacy formularies is reshaping competitive access for diabetes drug suppliers in New Zealand. Novo Nordisk leverages its insulin manufacturing scale to secure tender contracts with district health boards. Sanofi anchors its position through broad portfolio coverage across both basal insulin and GLP-1 segments. Eli Lilly differentiates via concentrated R&D investment in next-generation peptide therapeutics.
New Zealand diabetes drugs comprise synthetic and biological pharmaceutical agents formulated to modulate glucose metabolism, including recombinant insulin analogs with defined amino acid substitutions and small-molecule inhibitors targeting renal sodium-glucose cotransporters. These agents serve to reduce hyperglycemia-associated microvascular and macrovascular complications in diagnosed patient populations. Insulin and GLP-1 agonists command the dominant share of product-type revenue, reflecting established reimbursement pathways and clinician familiarity. SGLT-2 inhibitors represent the fastest-expanding delivery-mode category, driven by cardiovascular outcome data that reshapes prescribing patterns in outpatient clinics. Subcutaneous injection maintains volume leadership, though oral tablet formulations gain share where patient self-administration preferences align with glycemic targets.
Medsafe, Pharmac, and the Medicines Act 1981 collectively govern market authorization, subsidy listing, and post-market surveillance for diabetes therapeutics distributed in New Zealand. Pharmac's sole-purchaser model directly shapes demand through restricted brand schedules and reference pricing mechanisms. Clinicians and procurement officers must monitor Pharmac's annual tender cycles and evolving Special Authority criteria for novel drug classes.
Market Dynamics
Pharmac's sole-purchaser tender model concentrates procurement power within district health boards, compressing supplier margins while expanding access to subsidized glucose-lowering therapies across New Zealand's public health system.
Growth Catalysts
- Cardiovascular outcome data:SGLT-2 inhibitor trials demonstrating heart failure risk reduction are reshaping prescribing protocols in Auckland's specialist clinics.
- Pharmac Special Authority expansions:Relaxed eligibility criteria for GLP-1 agonists are accelerating patient access to injectable therapies beyond insulin-dependent populations.
- Hospital outpatient expansion:Metropolitan health networks in Wellington and Christchurch are deploying dedicated diabetes pharmacotherapy units.
Market Restraints
- Reference pricing mechanisms:Pharmac's benchmark pricing against Australian PBS listings caps reimbursement rates for novel analog insulins.
- Import dependency:Biological API manufacturing concentrates in European and North American contract facilities, exposing supply chains to shipping disruptions.
- Medsafe pharmacovigilance requirements:Post-market cardiovascular safety monitoring mandates delay market entry for next-generation peptide therapeutics.
Strategic Opportunities
- Regional health board consolidation:The planned merger of 20 district health boards into 15 entities creates centralized formulary negotiation leverage.
- Māori and Pacific health equity mandates:Ministry of Health disparities reduction targets channel dedicated funding toward culturally tailored diabetes management programs.
- Continuous glucose monitoring integration:Sensor-augmented pump therapy convergence with cloud-based dosing algorithms opens reimbursement pathways for integrated device-drug bundles.
Industry Challenges
- Specialist endocrinologist scarcity:Fellowship training bottlenecks at University of Auckland and Otago Medical School constrain prescriber capacity outside major centers.
- Cold chain integrity:Temperature-controlled distribution across the Cook Strait and to rural South Island territories demands redundant logistics infrastructure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | New Zealand Diabetes Drugs Market |
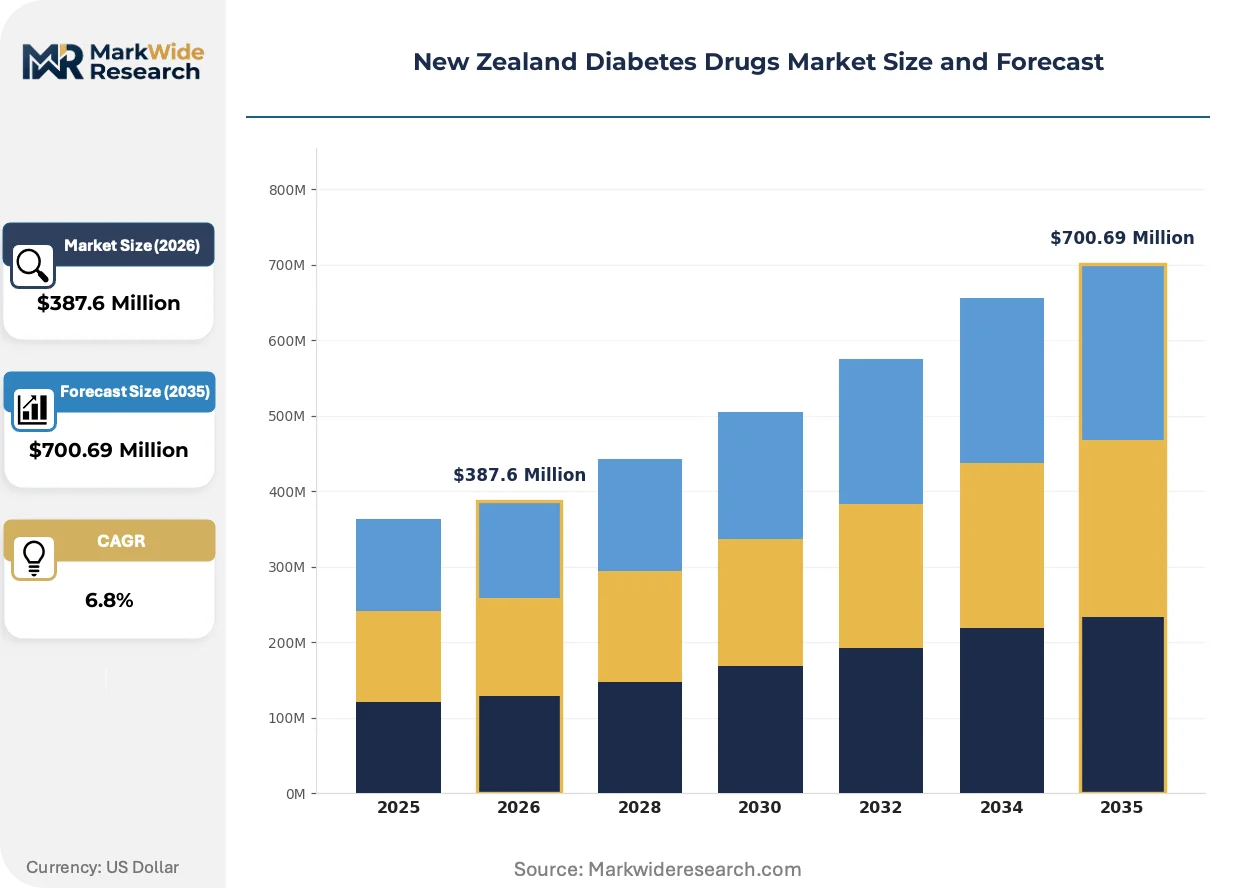
| Market Size in 2026 | $387.6 Million |
| Market Size in 2035 | $700.69 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Insulin, GLP-1 Agonists, SGLT-2 Inhibitors, DPP-4 Inhibitors Delivery Mode: Subcutaneous Injection, Oral Tablets, Inhaled, Continuous Infusion End User: Outpatient Clinics, Home Care, Hospitals, Pharmacies Formulation: Extended Release, Immediate Release, Combination Therapy, Premixed |
| Companies Covered | AstraZeneca, Janssen Pharmaceuticals, Novo Nordisk, Boehringer Ingelheim, Merck & Co., Sanofi, Takeda, Novartis, Eli Lilly, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
New Zealand Diabetes Drugs Market Shifts & Advancements
Digital health infrastructure is embedding algorithmic dosing support into routine diabetes care, compressing the gap between clinical trial efficacy and real-world glycemic outcomes across New Zealand's dispersed patient populations.
Continuous glucose monitoring systems paired with smartphone applications are digitizing patient self-management workflows. Primary care networks in Waikato and Counties Manukau are deploying these platforms at scale. The technology is digitizing how clinicians adjust insulin titration protocols, reducing HbA1c variability through real-time feedback loops.
Medsafe's tightened adverse event reporting requirements for novel glucose-lowering agents are extending post-approval surveillance timelines. Manufacturers must submit cardiovascular outcome data as a condition of provisional consent. The GLP-1 agonist segment is responding by front-loading safety database construction prior to New Zealand regulatory submission.
Patient self-administration preferences are driving demand for oral formulations over subcutaneous injection where glycemic targets permit. Community pharmacies in Auckland's metropolitan health networks are expanding medication therapy management services to support adherence. This shift is most visible among working-age type 2 diabetes patients prioritizing therapy discretion during employment hours.
New Zealand Diabetes Drugs Market Segmentation
Pharmac's sole-purchaser tender model compresses supplier margins across all diabetes drug segments, forcing manufacturers to optimize portfolio positioning within restricted brand schedules. Segmentation clarity determines which therapeutic classes secure formulary placement in Auckland's metropolitan health networks versus rural South Island territories.
Product Type:
Mature biologics dominate volume while emerging small-molecule classes reshape prescribing protocols through cardiovascular outcome data.
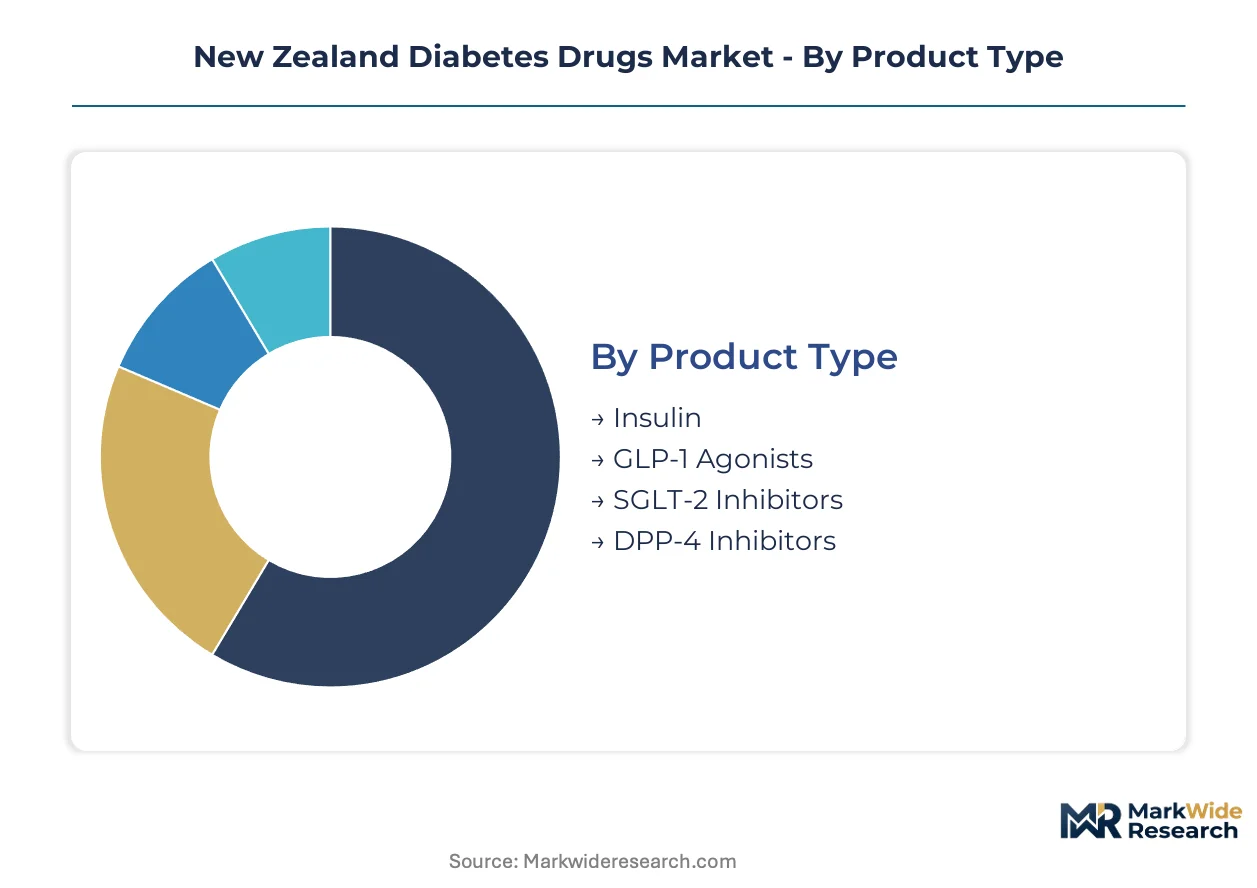
- Insulin:Recombinant analogs with defined amino acid substitutions remain the backbone of type 1 diabetes management and advanced type 2 cases. Demand concentrates in hospital outpatient departments across Auckland, Wellington, and Christchurch, where specialist endocrinology services cluster and Pharmac's tender cycles secure multi-year supply contracts.
- GLP-1 Agonists:Injectable peptide therapeutics stimulating glucose-dependent insulin secretion. Auckland's metropolitan health networks drive uptake as relaxed Special Authority criteria expand access beyond insulin-dependent populations, though cold chain requirements constrain rural distribution.
- SGLT-2 Inhibitors:Oral small-molecule inhibitors targeting renal sodium-glucose cotransporters. Heart failure risk reduction trials are accelerating prescribing in specialist clinics.
- DPP-4 Inhibitors:Oral gliptins enhancing incretin hormone activity. Well-established reimbursement pathways support steady utilization in primary care networks.
Insulin handles the majority of throughput; SGLT-2 Inhibitors are climbing the fastest on share.
Delivery Mode:
Patient self-administration preferences and cold chain logistics create divergent cost-to-serve profiles across New Zealand's dispersed geography.
- Subcutaneous Injection:Pen devices and vials for insulin and GLP-1 agonists. Volume leadership persists in Auckland's health networks where medication therapy management services support adherence, though patient discretion concerns limit uptake among working-age populations.
- Oral Tablets:Small-molecule formulations for SGLT-2 and DPP-4 inhibitors. Waikato and Counties Manukau primary care networks are deploying these at scale where glycemic targets permit therapy discretion during employment hours.
- Inhaled:Pulmonary insulin delivery systems. Limited formulary placement due to Pharmac's reference pricing mechanisms.
- Continuous Infusion:Insulin pump therapy integrated with sensor-augmented systems. Specialist diabetes pharmacotherapy units in Wellington and Christchurch are expanding protocols.
Subcutaneous Injection captures the dominant volume position; Oral Tablets are gaining share fastest among type 2 populations.
End User:
Procurement authority concentrates in district health boards while patient flow patterns shift toward community-based management.
- Outpatient Clinics:Hospital-based specialist diabetes units. Auckland's metropolitan health networks anchor demand through dedicated pharmacotherapy protocols and continuous glucose monitoring integration.
- Home Care:Self-managed therapy with remote clinician oversight. Digital health infrastructure embedding algorithmic dosing support is compressing efficacy gaps across dispersed populations.
- Hospitals:Inpatient glycemic management and acute complications. Concentrated in tertiary centers with endocrinology fellowships.
- Pharmacies:Community dispensing with medication therapy management services. Auckland networks are expanding adherence support programs.
Outpatient Clinics manage the heaviest patient load; Home Care is expanding most quickly on utilization.
Formulation:
Release kinetics and combination strategies differentiate products within Pharmac's reference pricing framework.
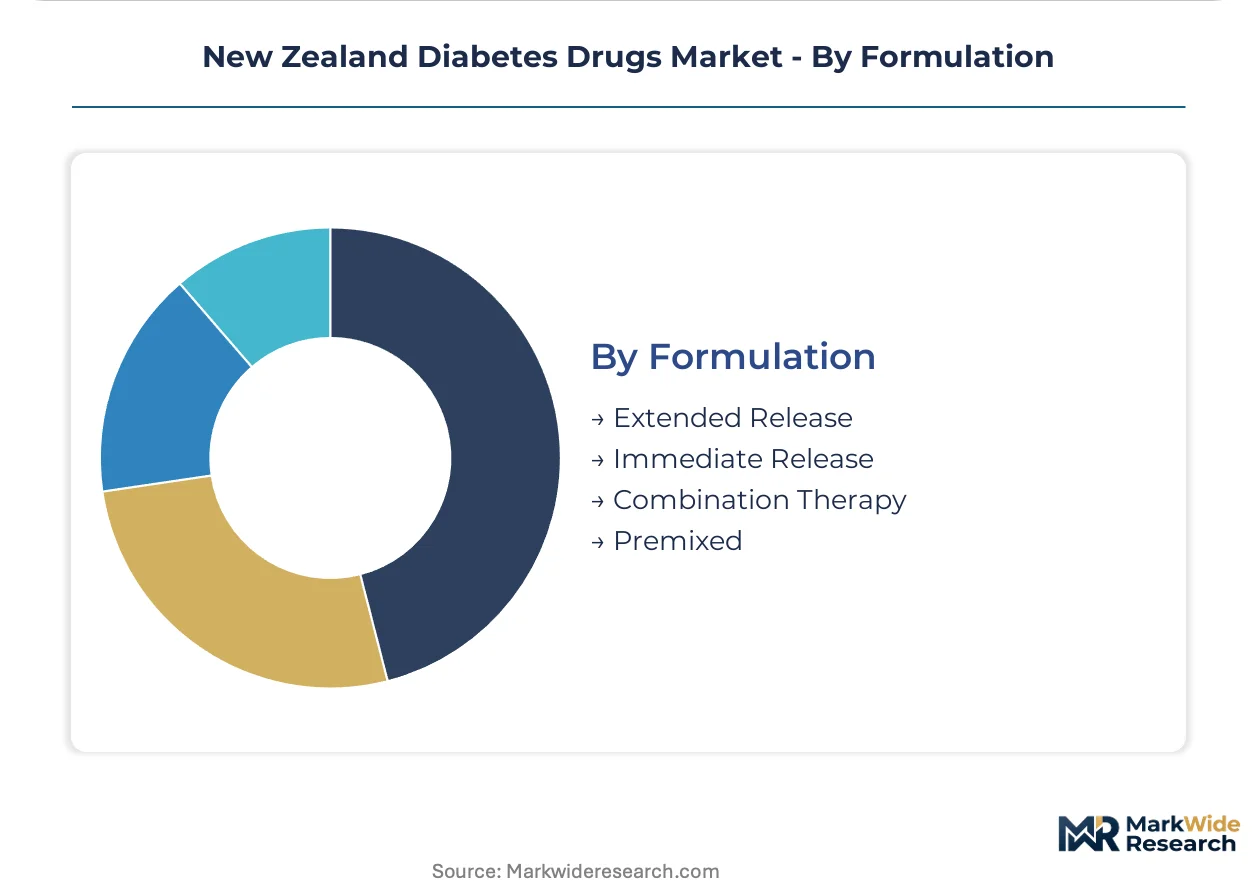
- Extended Release:Long-acting insulin analogs and depot formulations. Reduces injection frequency for rural patients facing specialist scarcity outside major centers.
- Immediate Release:Rapid-acting prandial insulins. Essential for flexible dosing in sensor-augmented pump therapy convergence.
- Combination Therapy:Fixed-ratio insulin-GLP-1 or oral dual-therapy products. Simplifies regimens where prescriber capacity is constrained.
- Premixed:Biphasic insulin formulations. Standard in primary care where titration resources are limited.
Extended Release handles the majority of basal insulin demand; Combination Therapy is gaining formulary traction fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
New Zealand's diabetes drugs market operates as a net importer of biological APIs and finished formulations, with supply chains threading through Australian transshipment hubs and direct European manufacturing links. Export activity remains minimal given domestic consumption scale and Pharmac's sole-purchaser procurement model.
Auckland Metropolitan Health Networks
Specialist endocrinology services cluster across Auckland City, Waitematā, and Counties Manukau district health boards, driving concentrated demand for insulin analogs and GLP-1 agonists. Medsafe's provisional consent pathways enable accelerated access to novel agents in these tertiary centers. Auckland's hospital outpatient departments anchor national prescribing protocols for continuous glucose monitoring integration.
Wellington Region
Capital & Coast and Hutt Valley district health boards are deploying dedicated diabetes pharmacotherapy units with embedded clinical pharmacy services. Pharmac's Special Authority criteria relaxations for SGLT-2 inhibitors are accelerating uptake in these facilities. Wellington's proximity to Medsafe headquarters facilitates rapid regulatory consultation for post-market surveillance requirements.
Canterbury and Christchurch
The South Island's largest health network manages complex diabetes cases through Christchurch Hospital's endocrinology fellowship program. Cold chain logistics across the Cook Strait create distribution cost premiums for temperature-sensitive biologicals. Rural Canterbury's general practice networks rely on extended-release insulin formulations where specialist prescriber capacity is scarce.
Waikato and Bay of Plenty
Primary care networks in Hamilton and Tauranga are scaling oral small-molecule therapies where glycemic targets permit patient self-management. The Ministry of Health's Māori health equity mandates channel dedicated funding toward culturally tailored diabetes programs in these regions. Community pharmacies are expanding medication therapy management services to support adherence outside hospital settings.
New Zealand Diabetes Drugs Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in API manufacturing and delivery device engineering. New Zealand's market structure concentrates around multinational pharmaceutical houses with established tender relationships with Pharmac, compressing margins for second-tier entrants. Two strategic archetypes dominate: scale-driven insulin manufacturers leveraging manufacturing depth, and cardiovascular-outcome-focused innovators front-loading safety databases. Competitive moves center on securing multi-year district health board contracts and building Medsafe regulatory relationships ahead of provisional consent applications.
Among the scale-driven insulin houses, Novo Nordisk and Sanofi occupy positions as anchor suppliers to Pharmac's tender cycles, while Eli Lilly represents the cardiovascular-innovation archetype through concentrated peptide therapeutic development. These three multinationals exemplify the market's bifurcation between volume-driven basal insulin supply and next-generation GLP-1 agonist differentiation. Their collective presence shapes formulary negotiation dynamics across Auckland's metropolitan health networks and determines reference pricing benchmarks for subsequent entrants.
| Leading Market Players |
|---|
| AstraZeneca |
| Janssen Pharmaceuticals |
| Novo Nordisk |
| Boehringer Ingelheim |
| Merck & Co. |
| Sanofi |
| Takeda |
| Novartis |
| Eli Lilly |
| Others |
Supply & Pricing Matrix
Single-source dependency on European biological API manufacturing exposes New Zealand's diabetes drugs market to shipping disruption cascades that compress supplier margins through Pharmac's reference pricing while simultaneously forcing inventory carrying cost premiums across district health board tender cycles.
Pricing Analysis
Hospital procurement officers anchor pricing negotiations through Pharmac's sole-purchaser tender model, which imposes contract-based long-term offtake structures with benchmark pricing against Australian PBS listings. Price differentiation rests on cardiovascular outcome certification tiers and cold chain logistics complexity, with margins tightening in novel analog insulin segments due to Medsafe's extended pharmacovigilance requirements. Specialist endocrinology services in Auckland's metropolitan health networks exhibit lowest price sensitivity, while rural primary care networks face acute cost compression from reference pricing caps.
Supply Chain Analysis
Extended payment terms from district health boards strain supplier working capital, particularly for temperature-sensitive biological shipments threading through Australian transshipment hubs. Active pharmaceutical ingredient manufacturing concentrates in Denmark, Germany, and the United States, with recombinant insulin analogs, GLP-1 peptide backbones, and SGLT-2 small-molecule precursors as critical dependencies. Single-source vulnerability in European contract manufacturing facilities threatens continuity, while distribution runs through Auckland's centralized hospital pharmacy depots before Cook Strait ferry routes to South Island territories.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating through the planned merger of 20 district health boards into 15 entities, consolidating formulary negotiation leverage and compressing supplier margins across glucose-lowering therapeutic categories.
For Market Incumbents: Entrench tender relationships by embedding clinical pharmacy services within Wellington and Christchurch diabetes pharmacotherapy units, countering emerging biosimilar entrants through cardiovascular safety database depth. Secure multi-year district health board contracts ahead of regional consolidation completion, leveraging manufacturing scale to absorb Pharmac's reference pricing compression.
For New Entrants and Emerging Players: Rural Canterbury and South Island general practice networks represent the most penetrable entry point, where specialist endocrinologist scarcity constrains prescriber capacity and extended-release insulin formulations face formulary gaps. Oral small-molecule SGLT-2 inhibitors in Waikato primary care networks offer secondary access through medication therapy management service partnerships with community pharmacies.
For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors platform integrators with established Medsafe regulatory relationships and tender-track records over component specialists lacking district health board contract history. Acquisition targets should demonstrate provisional consent pathway expertise and cardiovascular outcome trial infrastructure. Watch Pharmac's annual Special Authority criteria relaxations as volume inflection signals for GLP-1 agonist exposure.
| Strategic Initiative | Industry Significance |
|---|---|
| Regulatory Approval Pathway | Medsafe provisional consent accelerates novel agent access in Auckland's tertiary centers. |
| Hospital System Partnership | Embedded clinical pharmacy services in Wellington pharmacotherapy units secure formulary placement. |
| Manufacturing Scale-Up | Cold chain capacity expansion reduces Cook Strait distribution cost premiums for biologicals. |
| Pipeline Diversification | Cardiovascular outcome data packages front-load safety databases for SGLT-2 inhibitor submissions. |
| Reimbursement Strategy | Pharmac Special Authority alignment opens patient access beyond insulin-dependent populations. |
Research Methodology
A standing panel of formulary directors, hospital procurement managers, regulatory affairs leads, and specialist endocrinologists provided ongoing calibration across primary interview cycles, validated against Medsafe adverse event databases, Pharmac tender documentation, ClinicalTrials.gov cardiovascular outcome filings, and district health board annual reports. Bottom-up prescription volume modeling and top-down therapeutic class expenditure analysis were triangulated to anchor market sizing.
Scenario bracketing around Pharmac's Special Authority relaxation timelines and regional health board merger completion framed the projection horizon, with segmentation across product type, delivery mode, end user, and formulation dimensions. CAGRs were derived from prescription volume trajectories and reimbursement rate assumptions, incorporating continuous glucose monitoring integration pace and Māori health equity funding flows as industry-specific inputs.
Stress conditions across Pharmac reference pricing compression, Cook Strait logistics disruption, and Medsafe pharmacovigilance timeline extension were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions, with macroeconomic, regulatory, or technological deviation prompting revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Acetaminophen Injection Market
Pharmaceuticals
Global 3D Printed Drugs Market
Pharmaceuticals
China Plasma Protein Therapeutics Market
Pharmaceuticals
Pharma PLM Market
Pharmaceuticals
Vutrisiran Market
Pharmaceuticals
Over-The-Counter (OTC) Analgesics Market
Pharmaceuticals
US Sex Reassignment Hormone Therapy Market
Pharmaceuticals
Global Acyclovir Market
Pharmaceuticals
Asia-Pacific Obsessive-Compulsive Disorder (OCD) Drugs Market
Pharmaceuticals
Global Lyophilized Injectable Drugs Market
Pharmaceuticals
Obsessive Compulsive Disorder (OCD) Drug Market
Pharmaceuticals
Large Molecule Contract Development and Manufacturing Organization Market
Pharmaceuticals
Desloratadine Market
Pharmaceuticals
Calcitriol Capsules Market
Pharmaceuticals
GLP-1 Receptor Agonist Market
Pharmaceuticals
Global Gastroparesis Drug Market