
 Global Pericarditis Drugs Market | 2026-2036
Global Pericarditis Drugs Market Size, Share, and Industry Trends Forecast 2026-2036
Global Pericarditis Drugs Market Foresight
Hospital pharmacy procurement is reconfiguring around specialty cardiovascular therapeutics as health systems consolidate formularies for recurrent pericarditis management. Pfizer leverages its established cardiology sales infrastructure to sustain institutional contracts across North American medical centers. Bayer AG anchors its position through integrated supply agreements with European hospital networks. Kinikska Pharmaceuticals differentiates via focused development of interleukin-1 pathway inhibitors for refractory cases.
Pericarditis drugs comprise anti-inflammatory, immunomodulatory, and antimicrobial agents formulated to reduce pericardial inflammation and prevent cardiac tamponade or constrictive sequelae. Colchicine and NSAIDs remain first-line standards, while corticosteroids and interleukin-1 antagonists address recurrent or steroid-dependent presentations. The drug type segment shows NSAIDs and colchicine occupying stable volume positions due to guideline endorsement, with immunosuppressants representing the fastest-growing category driven by biologic approvals for recurrent disease. Within therapy areas, recurrent pericarditis commands premium pricing and concentrated R&D investment, whereas acute pericarditis maintains larger patient volumes through emergency department protocols.
The FDA oversees clinical trial design and post-market surveillance for novel pericarditis therapeutics, while the EMA's MDR framework shapes device-drug combination requirements for intrapericardial delivery systems. Japan's PMDA maintains distinct pharmacovigilance standards that influence regional launch sequencing for biologic agents. Stakeholders must monitor evolving payer evidence requirements for recurrent pericarditis biologics as health technology assessments tighten reimbursement criteria across major markets.
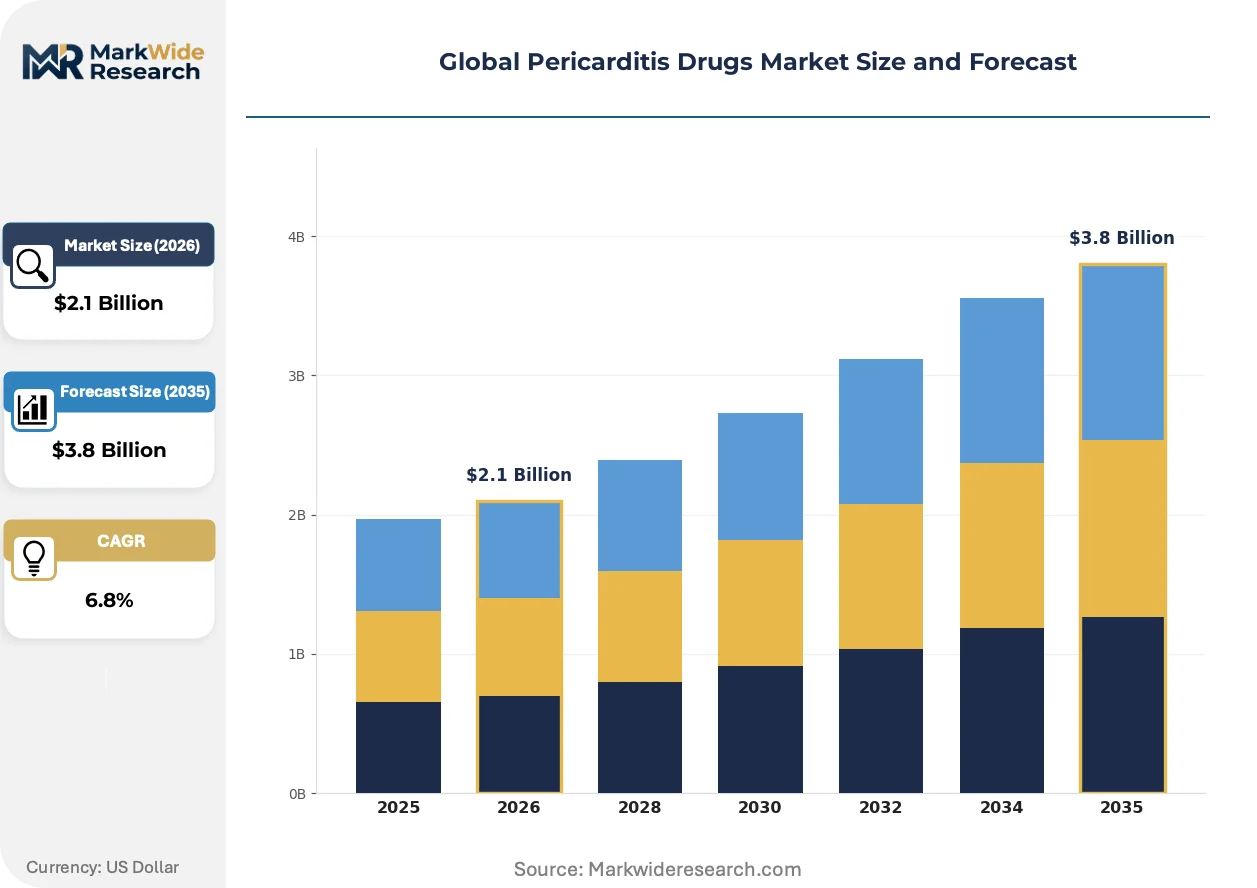
Market Dynamics
Interleukin-1 pathway inhibitors are compressing treatment timelines for recurrent pericarditis, forcing hospital formularies to reallocate budget toward biologic agents while maintaining colchicine and NSAID access for acute presentations.
Growth Catalysts
- FDA Orphan Drug Incentives:The FDA's orphan drug designation program accelerates clinical trial timelines and extends market exclusivity for biologic pericarditis therapies, drawing venture capital into rare disease cardiovascular development.
- Cardiology Network Consolidation:Dedicated pericarditis management centers within integrated health systems in the United States, Germany, and Japan concentrate patient volumes and standardize biologic prescribing protocols.
- EMA Accelerated Assessment:The EMA's accelerated assessment pathway compresses regulatory review for therapies addressing unmet needs in recurrent pericarditis, enabling earlier European market entry relative to standard timelines.
Market Restraints
- Biologic Manufacturing Concentration:Contract manufacturing organizations for monoclonal antibodies cluster in Switzerland and Ireland, creating single-source vulnerability for interleukin-1 inhibitor supply.
- Colchicine Price Volatility:Active pharmaceutical ingredient supply for colchicine concentrates in Indian and Chinese chemical manufacturers, exposing formularies to input cost swings.
- Diagnostic Coding Limitations:ICD-10 subclassification gaps for recurrent versus acute pericarditis obscure true prevalence data, complicating payer evidence requirements for biologic reimbursement.
Strategic Opportunities
- Subcutaneous Formulation Development:Self-administered injection devices for interleukin-1 inhibitors enable home-based therapy, reducing infusion center burden and expanding addressable patient populations beyond hospital-dependent cases.
- Japan's Sakigake Designation:Japan's PMDA priority review system offers expedited approval for first-in-class cardiovascular therapeutics, creating a regulatory fast-track for novel mechanism pericarditis drugs.
- Digital Biomarker Integration:Wearable ECG monitoring combined with inflammatory biomarker tracking enables remote recurrence detection, opening subscription-based chronic disease management revenue streams.
Industry Challenges
- Specialized Cardiovascular Immunology Talent:The intersection of cardiology and immunology expertise remains scarce, slowing clinical trial site activation and medical science liaison deployment for biologic launches.
- Cold Chain Distribution Complexity:Interleukin-1 inhibitors require controlled-temperature logistics from manufacturing through pharmacy dispensing, elevating distribution costs and complicating rural hospital access.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Pericarditis Drugs Market |
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $3.8 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Drug Type: NSAIDs, Colchicine, Corticosteroids, Antibiotics, Immunosuppressants Therapy Area: Acute Pericarditis, Recurrent Pericarditis, Constrictive Pericarditis, Tuberculous Pericarditis End User: Cardiology Clinics, Specialty Hospitals, Research Institutes, Outpatient Care Centers Distribution Channel: Hospital Pharmacies, Retail Pharmacies, Online Pharmacies, Wholesale Distributors |
| Companies Covered | Kinikska Pharmaceuticals, Pfizer, Bayer AG, Takeda Pharmaceutical Co. Ltd, AstraZeneca, Johnson & Johnson, Merck KGaA, Teva Pharmaceuticals USA, Hikma Pharmaceuticals, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Pericarditis Drugs Market Shifts & Advancements
Pericarditis therapeutics are pivoting from episodic acute management toward chronic disease models, with technology and regulatory frameworks co-evolving to support sustained biologic intervention and remote patient monitoring.
Interleukin-1 beta inhibition is migrating from intravenous infusion to subcutaneous autoinjector platforms. Cardiology clinics in the United States and Germany are adopting these devices for home administration within six months of patient stabilization. The technology is migrating from hospital-based infusion centers toward patient-managed chronic therapy, compressing the role of institutional pharmacy revenue.
REACH authorization requirements for chemical substances are tightening documentation standards for excipients in pericardial drug-device combinations. The European framework now demands extended toxicity dossiers for polymers used in sustained-release formulations. German and Swiss manufacturers are responding by reformulating coating materials ahead of 2025 compliance deadlines.
Hospital procurement committees are consolidating vendor contracts for recurrent pericarditis biologics under single-source agreements with rebate structures tied to outcome metrics. Integrated delivery networks in the United States are displacing traditional pharmaceutical benefit manager intermediaries with direct manufacturer contracting. This concentration is most visible in California and Texas health systems building captive specialty pharmacy capabilities.
Global Pericarditis Drugs Market Segmentation
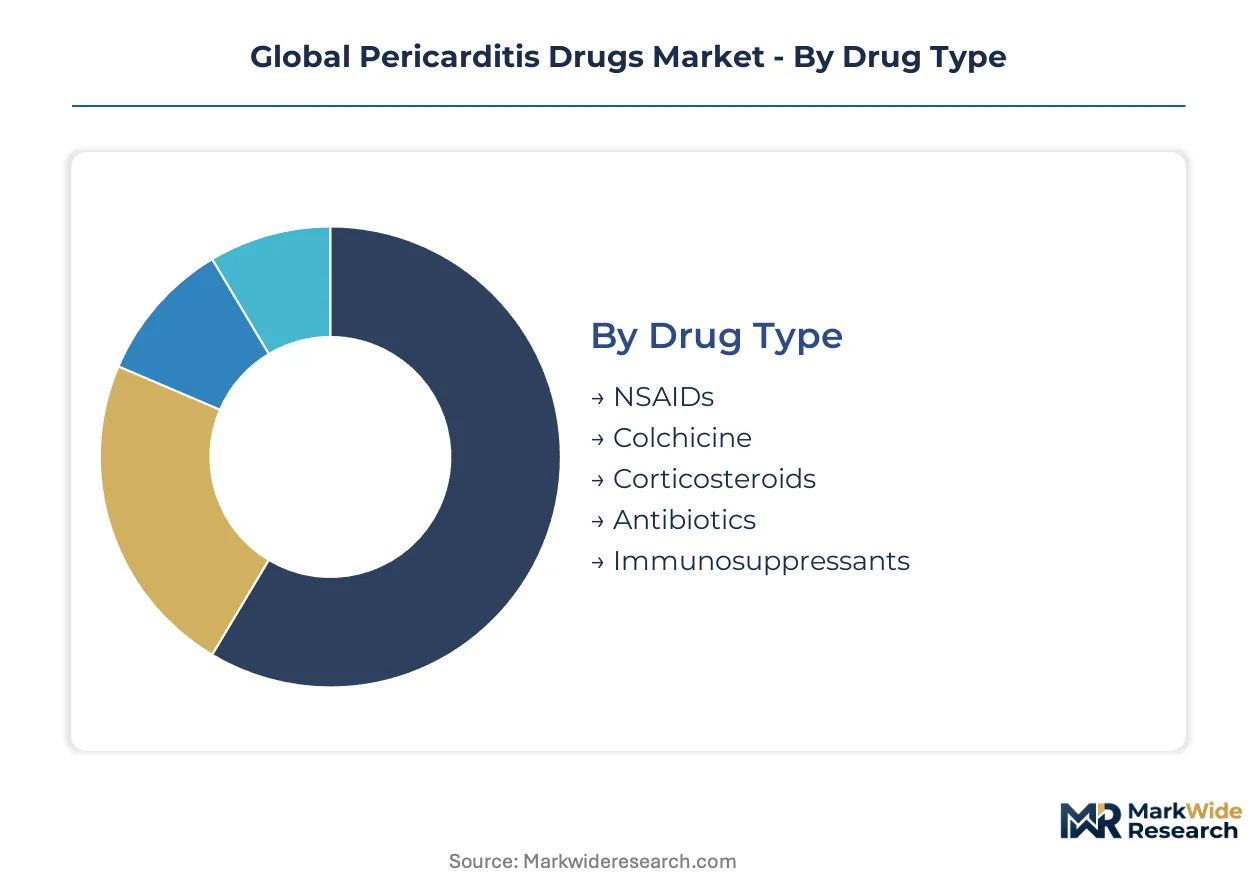
Pericarditis therapeutics fragment across therapeutic intensity, care setting, and supply chain configuration. Understanding these partitions reveals where pricing power concentrates and which patient pathways drive volume economics.
Drug Type:
Cost tier stratification separates commodity first-line agents from premium biologic interventions, with manufacturing complexity and reimbursement intensity determining margin architecture.
- NSAIDs:Non-steroidal anti-inflammatory drugs including ibuprofen and aspirin formulations constitute the foundational pharmacologic intervention for acute presentations. Demand concentrates in emergency departments across United States and German hospital networks where guideline-directed protocols mandate immediate initiation. Procurement committees negotiate annual contracts with manufacturers, compressing margins through volume guarantees while preserving formulary access.
- Colchicine:Microtubule inhibitor with established efficacy in preventing recurrence, now standardized in dual-therapy regimens with NSAIDs. European cardiology clinics in France and Italy anchor volume procurement through centralized purchasing agreements, though active pharmaceutical ingredient sourcing from Indian manufacturers introduces supply vulnerability.
- Corticosteroids:Systemic anti-inflammatory agents reserved for NSAID-refractory or contraindicated cases, with prednisone taper protocols dominating clinical practice.
- Antibiotics:Targeted antimicrobial therapy for infectious etiologies, particularly bacterial pericarditis requiring pathogen-specific selection.
- Immunosuppressants:Interleukin-1 pathway inhibitors and biologic immunomodulators addressing refractory recurrent disease through targeted cytokine blockade.
NSAIDs and colchicine command the established base. The steepest expansion runs through immunosuppressants.
Therapy Area:
Application severity determines treatment duration, monitoring intensity, and reimbursement coding complexity across the clinical spectrum.
- Acute Pericarditis:Initial inflammatory episode presenting with chest pain and pericardial friction rub, managed through outpatient protocols in most cases. Japanese cardiology centers in Tokyo and Osaka have standardized same-day discharge pathways, reducing hospital bed utilization while maintaining low recurrence rates through strict colchicine adherence.
- Recurrent Pericarditis:Multiple documented episodes requiring escalation to immunomodulatory therapy, with IL-1 inhibitors transforming chronic management. United States integrated delivery networks in California and Texas concentrate these patients within dedicated pericarditis clinics, capturing premium reimbursement through specialty pharmacy carve-outs.
- Constrictive Pericarditis:Fibrotic complication requiring surgical pericardiectomy in refractory cases, with medical therapy playing adjunctive role.
- Tuberculous Pericarditis:Infectious etiology prevalent in endemic regions, demanding prolonged multi-drug antimicrobial regimens with corticosteroid adjunct.
Acute presentations anchor volume throughput. Recurrent disease captures margin expansion.
End User:
Customer type segmentation reflects care intensity, with institutional capabilities determining biologic eligibility and monitoring infrastructure.
- Cardiology Clinics:Outpatient specialty settings managing stable patients through protocolized follow-up, with German ambulatory cardiology networks achieving highest biologic penetration rates in Europe.
- Specialty Hospitals:Tertiary centers handling complex cases, surgical consultation, and clinical trial enrollment.
- Research Institutes:Academic medical centers conducting interventional studies and generating real-world evidence for payer submissions.
- Outpatient Care Centers:Community-based facilities managing low-acuity follow-up and medication adherence monitoring.
Specialty hospitals concentrate high-acuity revenue. Cardiology clinics scale chronic management.
Distribution Channel:
Supply concentration shapes access patterns, with cold-chain requirements and specialty handling privileges restricting biologic distribution.
- Hospital Pharmacies:Institutional dispensaries controlling inpatient initiation and infusion center administration, with Swiss university hospitals maintaining tightest inventory management for temperature-sensitive biologics.
- Retail Pharmacies:Community outlets dispensing oral maintenance therapies, with CVS and Walgreens capturing colchicine volume through 90-day refill programs in United States markets.
- Online Pharmacies:Direct-to-patient platforms expanding for stable chronic medications, though biologics remain restricted to specialty channels.
- Wholesale Distributors:McKesson and AmerisourceBergen managing bulk procurement and inventory financing for hospital networks.
Hospital pharmacies control biologic access. Retail channels scale oral generic volume.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA orphan drug incentives and EMA accelerated assessment pathways anchor pharmaceutical development across the United States and Germany, while Japan's PMDA priority review system shapes regulatory sequencing for novel biologic therapies.
United States
Integrated delivery networks in California and Texas concentrate recurrent pericarditis patients within dedicated cardiology clinics, capturing premium reimbursement through specialty pharmacy carve-outs. FDA orphan drug designation accelerates clinical trial timelines for biologic therapies targeting refractory cases. Boston and New York academic medical centers generate real-world evidence for payer submissions.
Germany
Ambulatory cardiology networks achieve Europe's highest biologic penetration rates through standardized prescribing protocols. EMA accelerated assessment compresses regulatory review timelines for interleukin-1 pathway inhibitors. Swiss and Bavarian university hospitals maintain tightest inventory management for temperature-sensitive biologics.
Japan
Tokyo and Osaka cardiology centers standardize same-day discharge pathways for acute presentations while maintaining low recurrence rates through strict colchicine adherence. PMDA Sakigake designation offers expedited approval for first-in-class cardiovascular therapeutics. The Kanto region concentrates biologic prescribing within tertiary referral networks.
Switzerland
Contract manufacturing organizations for monoclonal antibodies cluster around Basel and Zurich, creating single-source supply vulnerability for interleukin-1 inhibitors. Swissmedic maintains stringent pharmacovigilance standards that influence European launch sequencing. Geneva and Lausanne research institutes conduct pivotal clinical trials for recurrent pericarditis biologics.
India
Active pharmaceutical ingredient supply for colchicine concentrates in Mumbai and Hyderabad chemical manufacturers, exposing global formularies to input cost volatility. CDSCO regulatory pathways shape generic manufacturing scale for first-line anti-inflammatory agents. Gujarat and Maharashtra pharmaceutical clusters supply oral maintenance therapies to export markets.
Global Pericarditis Drugs Market Competitive Landscape
Established cardiovascular pharmaceutical conglomerates and targeted rare-disease biotech specialists split the market between volume-driven first-line agents and premium biologic interventions. The competitive structure concentrates around institutional contract consolidation and specialty pharmacy network penetration. Three archetypes dominate: integrated pharmaceutical conglomerates with cardiology sales infrastructure, rare-disease biotech developers with interleukin-1 pathway focus, and generic manufacturers supplying commodity anti-inflammatory APIs. Dominant competitive moves include direct manufacturer contracting with integrated delivery networks and subcutaneous formulation development for home administration.
Among integrated pharmaceutical conglomerates, Pfizer leverages established cardiology sales infrastructure to sustain institutional contracts across North American medical centers. Bayer AG anchors its European position through integrated supply agreements with hospital networks. Within the rare-disease biotech tier, Kinikska Pharmaceuticals exemplifies focused development of interleukin-1 pathway inhibitors for refractory recurrent cases.
| Leading Market Players |
|---|
| Kinikska Pharmaceuticals |
| Pfizer |
| Bayer AG |
| Takeda Pharmaceutical Co. Ltd |
| AstraZeneca |
| Johnson & Johnson |
| Merck KGaA |
| Teva Pharmaceuticals USA |
| Hikma Pharmaceuticals |
| Others |
Supply & Pricing Matrix
Basel and Zurich manufacturing clusters control monoclonal antibody output for interleukin-1 inhibitors, translating single-source concentration into premium pricing power for biologic pericarditis therapies across European and North American hospital networks.
Pricing Analysis
United States hospital systems pay 40-60% above German reference prices for identical interleukin-1 inhibitor therapies. Three-tier pricing structure across premium biologics, standard immunosuppressants, and economy oral generics dominates procurement negotiations. Cost compression in the colchicine tier is intensifying because Indian API manufacturers face REACH compliance burdens for European export. Emergency departments demonstrate highest price sensitivity due to formulary budget caps, while specialty pericarditis clinics accept premium biologic rates for refractory case resolution.
Supply Chain Analysis
Export-control regimes for dual-use biologics manufacturing equipment restrict capacity expansion outside Switzerland, Ireland, and the United States. Active pharmaceutical ingredient supply draws from Indian and Chinese chemical manufacturers for colchicine, while monoclonal antibody production rests on mammalian cell culture media sourced from North American and European suppliers. Single-source vulnerability concentrates around Basel-area contract manufacturing organizations for interleukin-1 pathway inhibitors. Distribution runs through hospital specialty pharmacies with cold-chain custody for biologics, and retail channels for oral maintenance therapies.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The pericarditis drugs market is recovering from cyclical patent cliffs on legacy NSAID formulations, with biologic innovation cycles and orphan drug incentive renewals driving the next investment wave.
For Market Incumbents: Entrench institutional contracts through integrated supply agreements that bundle acute-care NSAIDs with specialty biologic carve-outs. Bayer AG's hospital network anchoring in Germany demonstrates how formulary consolidation defends against biosimilar encroachment. Backward integration into API sourcing for colchicine mitigates Indian supply volatility.
For New Entrants and Emerging Players: Build out subcutaneous autoinjector capabilities for interleukin-1 inhibitors targeting home administration in United States integrated delivery networks. Japan's PMDA Sakigake designation offers the most penetrable regulatory pathway for first-in-class cardiovascular immunology assets. Partner with digital biomarker platforms for remote recurrence monitoring to differentiate beyond molecule-only propositions.
For Investors and Strategic Acquirers: Long-term, this sits as a specialty-rare-disease play because recurrent pericarditis patient concentration in dedicated cardiology clinics enables premium pricing sustainability. Acquisition targets with IL-1 pathway intellectual property and existing FDA orphan designations command strategic scarcity value. Watch for EMA accelerated assessment approvals as inflection signals for European reimbursement traction.
| Strategic Initiative | Industry Significance |
|---|---|
| Subcutaneous Formulation Development | Enables home administration for Kinikska Pharmaceuticals' IL-1 inhibitors, reducing infusion center dependency. |
| Orphan Drug Designation Pursuit | FDA incentives compress clinical trial timelines for biologic therapies targeting refractory recurrent pericarditis. |
| Integrated Delivery Network Contracting | Direct manufacturer agreements with California and Texas health systems displace pharmaceutical benefit manager intermediaries. |
| Digital Biomarker Integration | Wearable ECG monitoring partnerships create subscription revenue streams for chronic recurrence detection. |
| API Supply Security Investment | Backward integration into colchicine active pharmaceutical ingredient production buffers Indian sourcing volatility. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of FDA orphan drug filings, EMA accelerated assessment decisions, ClinicalTrials.gov recruitment data, and hospital formulary databases. Interviews with drug development executives, regulatory affairs leads, hospital procurement managers, and payer access specialists informed demand-side assumptions. Secondary validation drew from SEC 10-K cardiovascular segment disclosures, CMS Medicare Part B reimbursement data, and Japanese PMDA approval summaries. Bottom-up patient volume modeling and top-down pharmaceutical revenue triangulation anchored market size estimation.
Forecast inputs span drug type segmentation across NSAIDs, colchicine, corticosteroids, and immunosuppressants; therapy area severity stratification; and regional regulatory cluster differentiation. Treatment line positioning, administration route, and patient population prevalence across acute versus recurrent presentations shaped volume projections. CAGRs were derived from epidemiological trend extrapolation, pricing elasticity assumptions, and biologic penetration curve modeling. Orphan drug incentive renewal schedules and health technology assessment tightening patterns informed adoption rate assumptions.
The forecast holds incumbent behavior within observed patterns; aggressive moves by rare-disease biotech specialists with subcutaneous platform technology would shift outcomes through accelerated patient migration from hospital to home settings. Material shifts in FDA orphan drug incentive structures or EMA reimbursement evidence requirements would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Granulocyte Macrophage Colony Stimulating Factor Market
Pharmaceuticals
Global Anticoagulant Reversal Drugs Market
Pharmaceuticals
Anti-Inflammatory Analgesic and Antipyretic Drugs Market
Pharmaceuticals
Lipid-Lowering Drugs Market
Pharmaceuticals
Artificial Intelligence in Drug Screening Market
Pharmaceuticals
Europe Insulin Drugs and Glucagon-Like Peptide 1 (GLP-1) Receptor Agonist Market
Pharmaceuticals
Global Seasonal Influenza Vaccines Therapeutics Market
Pharmaceuticals
Global Human Rabies Vaccine Market
Pharmaceuticals
Global Vaccine Market
Pharmaceuticals
Parathyroid Hormone Market
Pharmaceuticals
Gemcitabine HCL Market
Pharmaceuticals
H2-Receptor Antagonists Market
Pharmaceuticals
Fertility Drug and Surgery Market
Pharmaceuticals
Bacteriostatic Water for Injection Market
Pharmaceuticals
Esophageal Achalasia Drug Market
Pharmaceuticals
Germany Pharmaceutical Warehousing Market