
 Large Molecule Contract Development and Manufacturing Organization Market | 2026-2036
Large Molecule Contract Development and Manufacturing Organization Market Size, Share, and Industry Trends Forecast 2026-2036
Large Molecule Contract Development and Manufacturing Organization Market Insights
FDA biosimilar guidance is expanding the cost-of-entry calculus for new biologics entrants. Lonza Group leverages its mammalian cell culture infrastructure to dominate high-complexity antibody production. Samsung Biologics anchors massive single-use bioreactor capacity in South Korea. Thermo Fisher Scientific extends analytical testing services across the development lifecycle.
Large Molecule Contract Development and Manufacturing Organizations provide outsourced biologics development and production services utilizing mammalian or microbial cell culture systems, with batch sizes ranging from laboratory-scale to multi-thousand liter bioreactor volumes, primarily serving pharmaceutical and biotech clients seeking to commercialize protein therapeutics without capital-intensive manufacturing infrastructure. Process development commands premium pricing due to technical complexity and regulatory scrutiny, while fill and finish operations concentrate margin pools through aseptic handling requirements. Pharmaceutical companies represent the dominant client type by revenue contribution, though biotech firms generate faster engagement velocity as pipeline candidates advance.
FDA, EMA, and China's NMPA each enforce distinct chemistry, manufacturing, and controls standards that shape facility qualification timelines and cross-border supply strategies for CDMO operators. ISO 14644 cleanroom classifications and ICH Q5D guidelines further constrain facility design and viral clearance validation protocols. Stakeholders must monitor evolving cell and gene therapy regulatory pathways that will redraw CDMO capability requirements and investment priorities.
Market Dynamics
Biopharmaceutical patent cliffs and biosimilar entry waves are forcing originators to shed fixed manufacturing assets, accelerating CDMO demand for mammalian cell culture capacity. This structural shift concentrates production expertise among operators with validated viral clearance platforms and multi-product facility flexibility.
Growth Catalysts
- FDA Biosimilar Guidance:The FDA's tightened analytical similarity requirements compel biosimilar developers to outsource process characterization to CDMOs with established comparability protocols.
- Single-Use Bioreactor Adoption:Stainless steel replacement campaigns across biologics manufacturing reduce cross-contamination risk and enable faster product changeovers for multi-tenant facilities.
- China NMPA Harmonization:China's adoption of ICH Q5D viral safety guidelines accelerates international sponsor confidence in domestic CDMO partnerships for global supply.
Market Restraints
- Plasma-Derived Media Supply Concentration:Bovine serum albumin and recombinant insulin sourcing depends on a narrow supplier base concentrated in North America and Europe, exposing batch cost volatility.
- Fill-Finish Capacity Scarcity:Aseptic isolator technology and robotic vial handling systems require capital deployment timelines exceeding 36 months, constraining rapid scale-up.
- ICH Q5A Viral Clearance Validation:Regulatory demands for orthogonal viral inactivation studies extend facility qualification periods and defer revenue recognition.
Strategic Opportunities
- Cell and Gene Therapy CDMO Services:Viral vector manufacturing and plasmid DNA production represent whitespace segments with limited qualified capacity and premium pricing power.
- India Biologics Manufacturing:The country's PLI scheme for pharmaceuticals incentivizes greenfield biologics facilities serving export markets with cost-competitive operating structures.
- Continuous Manufacturing Integration:Perfusion cell culture coupled with real-time release testing compresses cycle times and enables adaptive process control for personalized medicine scales.
Industry Challenges
- Bioprocess Engineer Talent Pipeline:The specialized skill set spanning cell line development, scale-up modeling, and regulatory filing preparation faces acute shortage across all major manufacturing clusters.
- Multi-Product Facility Scheduling Complexity:Campaign changeover validation and cleaning verification protocols create utilization inefficiencies that erode margin at sub-optimal batch frequencies.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Large Molecule Contract Development and Manufacturing Organization Market |
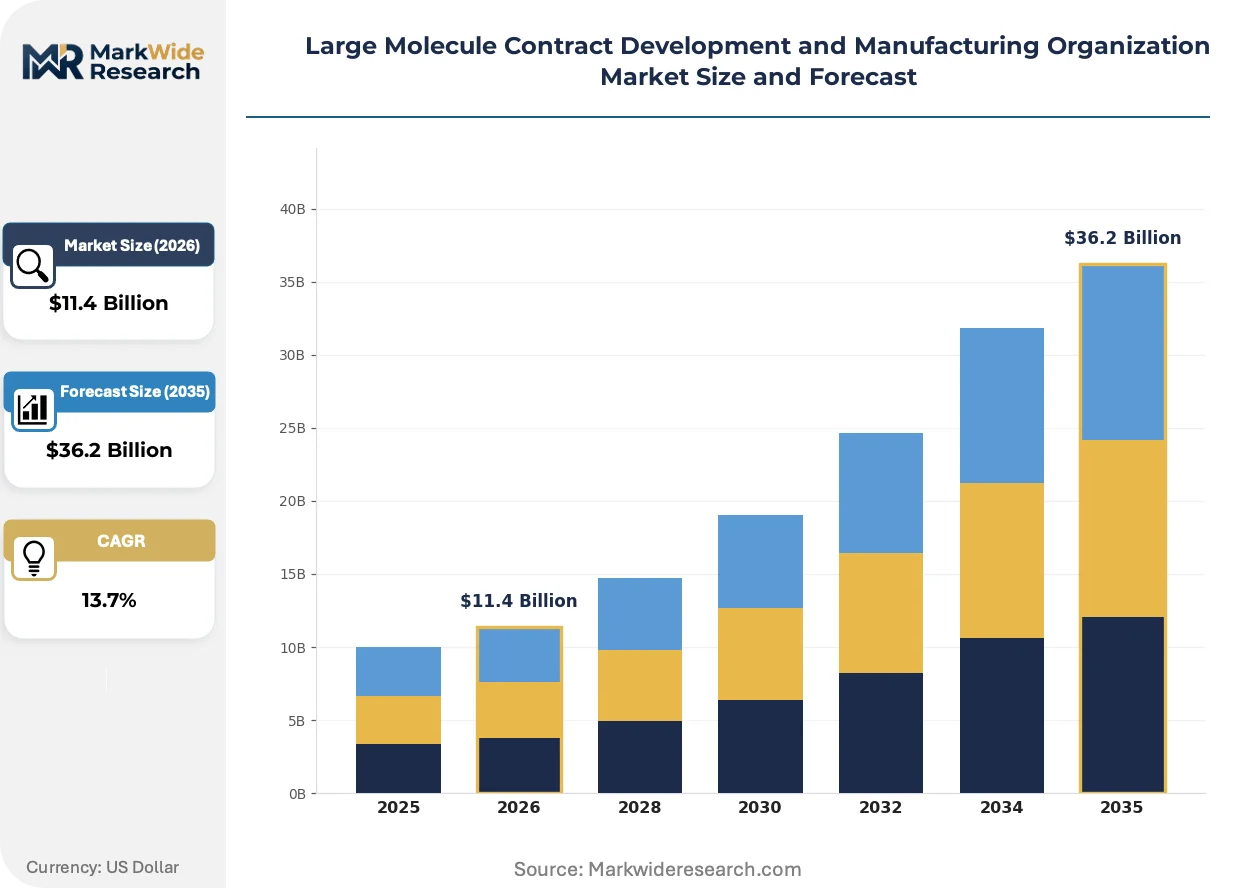
| Market Size in 2026 | $11.4 Billion |
| Market Size in 2035 | $36.2 Billion |
| CAGR (2026 – 2036) | 13.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Process Development, Analytical Testing, Fill & Finish, Quality Assurance Client Type: Pharmaceutical Companies, Biotech Firms, Research Institutions, Academic Entities Delivery Model: On-site Manufacturing, Contract Manufacturing, Outsourced Services, Joint Ventures Technology: Cell Culture, Protein Engineering, Purification Techniques, Bioreactor Systems |
| Companies Covered | Thermo Fisher Scientific Inc, Lonza Group, Catalent, Inc, Samsung Biologics, Wuxi Biologics, Eurofins Scientific, FUJIFILM Diosynth Biotechnologies, Boehringer Ingelheim, Recipharm, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Large Molecule Contract Development and Manufacturing Organization Market Trends and Innovations
Process intensification and digital biomanufacturing platforms are compressing development timelines while regulatory convergence around ICH standards enables geographic arbitrage in clinical trial material supply.
Continuous bioprocessing technology is modularizing traditional fed-batch workflows into interconnected unit operations with real-time process analytical technology. Mid-sized biotech sponsors are adopting perfusion-based seed trains and integrated continuous downstream processing to reduce facility footprints by 40-60%. This architecture is modularizing capital deployment, allowing CDMOs to scale capacity incrementally rather than through monolithic stainless steel investments.
The EU's revised Annex 1 GMP guidelines for sterile manufacturing impose stricter contamination control requirements on aseptic processing environments. The regulation mandates barrier isolation systems and enhanced environmental monitoring protocols for all new biologics fill-finish operations. European CDMOs are responding with isolator retrofit programs and single-use closed-system technologies to avoid facility reconstruction.
Biopharmaceutical sponsors are unbundling analytical testing from manufacturing contracts, establishing direct relationships with specialized contract research organizations for release and stability studies. This disintermediation of quality control functions allows sponsors to retain data ownership while compressing decision timelines for lot release. The pattern is most visible among US-based virtual biotech companies with limited internal quality infrastructure.
Large Molecule Contract Development and Manufacturing Organization Market Segmentation
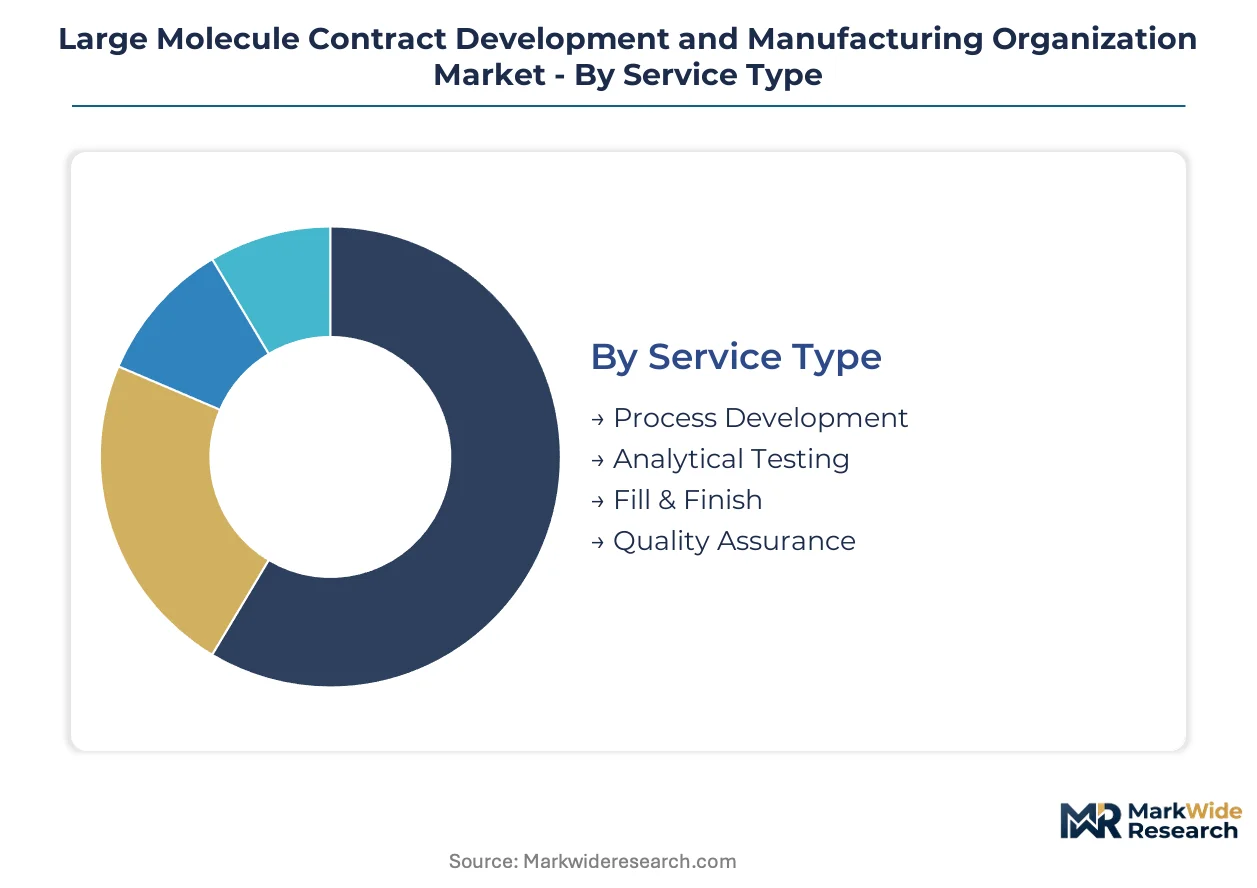
Large molecule CDMOs structure service portfolios around distinct technical capabilities and client risk profiles. Each segment carries different margin structures, capital intensity, and regulatory exposure that shape partnership terms and facility investment priorities.
Service Type:
Upgrade cycles in service portfolios follow biopharmaceutical pipeline maturation, with sponsors shifting spend from early-stage process development toward commercial-scale manufacturing and quality functions as assets approach regulatory filing.
- Process Development:Cell line optimization, media formulation, and scale-up modeling for mammalian and microbial expression systems. Pharmaceutical sponsors in the US and Germany concentrate demand here as FDA and EMA comparability protocols tighten for biosimilar submissions.
- Analytical Testing:Release testing, stability studies, and characterization assays using mass spectrometry and chromatography platforms. Biotech firms without captive quality infrastructure drive fastest engagement velocity for outsourced analytical services.
- Fill & Finish:Aseptic vial and syringe filling under isolator or restricted access barrier systems.
- Quality Assurance:Batch record review, deviation investigations, and regulatory filing support.
Fill & Finish sits at the top of the volume ranking, with Analytical Testing climbing the fastest.
Client Type:
Cost tier differentiation separates clients by internal manufacturing maturity and capital access, with fully integrated pharmaceutical sponsors demanding integrated service packages while capital-constrained biotechs unbundle functions across multiple vendors.
- Pharmaceutical Companies:Large-cap sponsors with approved biologics portfolios seeking capacity flexibility and geographic redundancy. US and Swiss originators dominate contract value, outsourcing to de-risk supply continuity and convert fixed costs to variable spend.
- Biotech Firms:Venture-backed and publicly traded developers with clinical-stage pipelines but no commercial manufacturing infrastructure. South Korea and China's emerging biotech clusters generate steepest expansion trajectory for CDMO partnerships.
- Research Institutions:Academic medical centers and nonprofit research organizations requiring GMP manufacturing for investigator-initiated trials.
- Academic Entities:University technology transfer offices commercializing early-stage discoveries through CDMO-mediated IND-enabling studies.
Pharmaceutical Companies anchor revenue concentration, with Biotech Firms expanding most quickly.
Delivery Model:
Application context determines delivery model selection, with high-complexity biologics requiring embedded on-site teams while standardized antibody production tolerates arm's-length contract structures.
- On-site Manufacturing:Dedicated facility suites or campus-adjacent operations with sponsor personnel embedded in quality oversight. FDA-inspected sites in Massachusetts and North Carolina host concentrated demand for this model among US-based sponsors.
- Contract Manufacturing:Fee-for-service arrangements with defined batch schedules and release timelines. European sponsors leverage this model to access capacity in Ireland and Switzerland without equity commitments.
- Outsourced Services:Project-based engagements for discrete development or manufacturing campaigns.
- Joint Ventures:Equity partnerships combining sponsor molecule rights with CDMO operational expertise.
Contract Manufacturing holds the largest transaction volume, with On-site Manufacturing gaining share fastest.
Technology:
Technology segmentation reflects the underlying bioproduction platform, with each system demanding distinct facility design, workforce specialization, and supplier relationships that lock in multi-year capability investments.
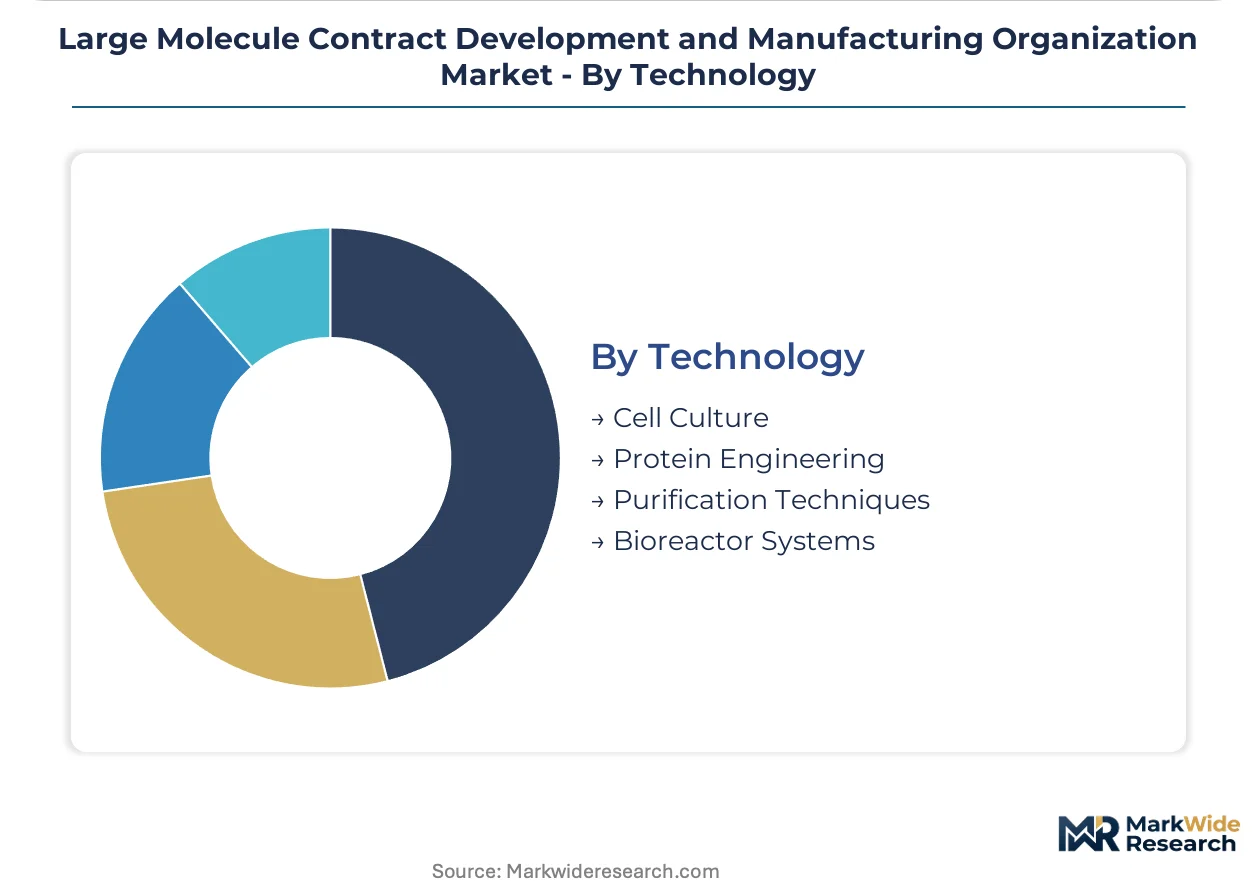
- Cell Culture:Mammalian and microbial fermentation systems for protein therapeutic production. Chinese hamster ovary platforms dominate monoclonal antibody manufacturing, with perfusion-based continuous culture expanding most quickly among Singapore and South Korea facilities.
- Protein Engineering:Molecular design, construct optimization, and expression vector development for novel biologic formats. US and UK biotech clusters concentrate demand for these services as bispecific and fusion protein pipelines mature.
- Purification Techniques:Chromatography, filtration, and viral clearance unit operations.
- Bioreactor Systems:Stainless steel and single-use vessel configurations for upstream production.
Cell Culture commands the greatest installed capacity, with Protein Engineering expanding most rapidly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The large molecule CDMO industry traces its commercial scale to Swiss and German pharmaceutical engineering traditions, with subsequent waves of capacity building in US biotechnology corridors and East Asian manufacturing clusters reshaping geographic supply distribution.
United States
FDA biosimilar guidance and IRA drug pricing provisions drive sponsor outsourcing of mammalian cell culture operations. Massachusetts and North Carolina regulators maintain the country's densest concentration of FDA-inspected multi-product facilities. Greater Boston anchors process development demand as virtual biotechs concentrate in Kendall Square and the Route 128 corridor.
Switzerland
Swissmedic's alignment with EMA centralized procedures sustains Basel and Zürich as high-complexity antibody production hubs. The country's bilateral recognition agreements with FDA accelerate cross-Atlantic supply validation timelines. Lonza Group's Visp campus exemplifies the integrated development-to-commercial model that attracts US and European originators seeking regulatory continuity.
Germany
Boehringer Ingelheim's legacy operations and emerging CDMO entrants absorb EMA MDR compliance costs through shared facility qualification frameworks. The BfArM's streamlined biosimilar approval pathways concentrate demand in Bavaria and Hesse. Frankfurt-Rhine-Main logistics infrastructure enables just-in-time cold chain distribution across EU markets.
China
NMPA's ICH Q5D harmonization and dual carbon policy targets reshape facility investment toward single-use technologies and renewable energy sourcing. Wuxi Biologics anchors the Yangtze River Delta biologics manufacturing cluster. Shanghai and Suzhou municipalities compete for multinational sponsor partnerships through tax incentives and streamlined environmental permitting.
South Korea
MFDS GMP mutual recognition agreements with FDA and EMA position Incheon and Songdo as export-oriented biologics manufacturing platforms. Samsung Biologics' Songdo campus represents the largest single-use bioreactor installation outside Western markets. Government R&D tax credits under the Bio-Health Industry Development Strategy sustain pipeline expansion for domestic biotech sponsors.
Large Molecule Contract Development and Manufacturing Organization Market Competitive Landscape
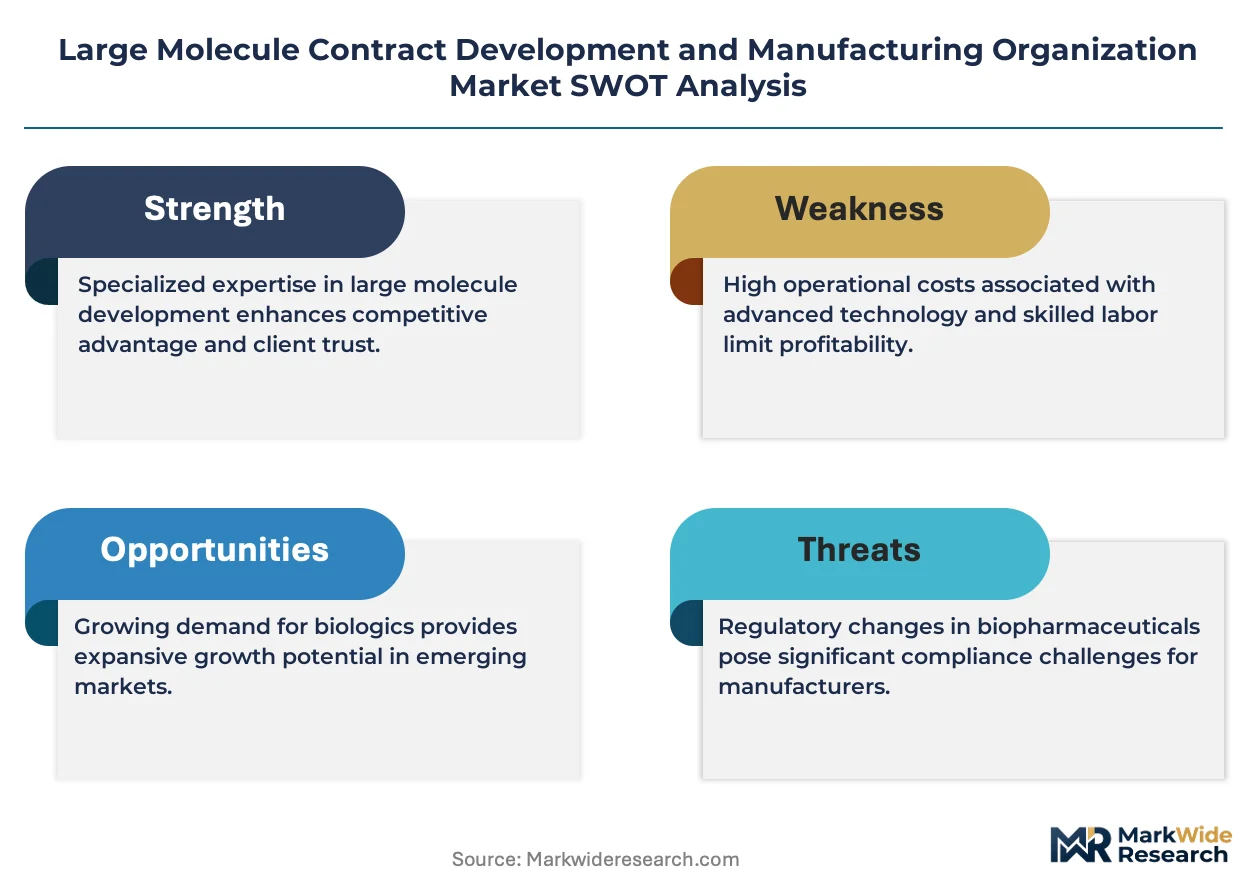
The competitive structure tilts toward integrated mammalian cell culture specialists with validated viral clearance platforms. Tiering separates full-service operators with end-to-end capabilities from niche analytical testing and fill-finish providers. Three archetypes dominate: Swiss-German engineering-led integrated platforms, US diversified life science conglomerates, and East Asian scale-focused manufacturing specialists. Capacity expansion and strategic technology licensing constitute the primary competitive vectors as sponsors prioritize supply security over unit cost minimization.
Within the integrated platform tier, Lonza Group and Boehringer Ingelheim exemplify European engineering heritage applied to high-complexity biologics production. Thermo Fisher Scientific occupies a position bridging analytical instrumentation dominance with CDMO service integration. Samsung Biologics represents the East Asian scale archetype, leveraging single-use infrastructure to compress capacity deployment timelines. Wuxi Biologics anchors Chinese-origin global supply capabilities. Catalent and FUJIFILM Diosynth Biotechnologies sit within the diversified pharmaceutical services segment, extending legacy small-molecule expertise into biologics modalities.
| Leading Market Players |
|---|
| Thermo Fisher Scientific Inc |
| Lonza Group |
| Catalent, Inc |
| Samsung Biologics |
| Wuxi Biologics |
| Eurofins Scientific |
| FUJIFILM Diosynth Biotechnologies |
| Boehringer Ingelheim |
| Recipharm |
| Others |
Pricing and Supply Chain Analysis
Bovine serum albumin and recombinant insulin feed from concentrated North American and European suppliers, cascading through plasma-derived media formulations into tiered service pricing for mammalian cell culture campaigns. CDMOs pass batch cost volatility downstream to sponsors through project-based contracts with volume-scaled unit economics, while FDA-inspected facilities command premium positioning against emerging-market competitors.
Pricing Analysis
Project-based fee structures with milestone-linked payments dominate commercial manufacturing engagements, separating GMP-certified facilities with validated viral clearance platforms from pre-qualified development-stage operations. Price differentiation hinges on regulatory inspection history and single-use technology adoption, with Massachusetts and North Carolina sites holding firm against cost compression from Chinese and South Korean entrants. Biotech firms without captive quality infrastructure exhibit highest price sensitivity, while large-cap pharmaceutical sponsors prioritize supply continuity over unit cost minimization.
Supply Chain Analysis
ISO 14644 cleanroom certification and ICH Q5D viral safety compliance gate facility qualification timelines, concentrating qualified capacity among Switzerland, Germany, and US biotechnology corridors. Raw material dependencies center on Chinese-manufactured single-use bioreactor components, German-engineered chromatography resins, and North American-sourced recombinant growth factors. Single-source vulnerability in plasma-derived media exposes batch cost volatility. Distribution runs through cold-chain logistics networks anchored in Frankfurt-Rhine-Main and Singapore free-trade zones.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Large Molecule CDMO market represents a late-cycle quality story as biopharmaceutical sponsors prioritize validated viral clearance platforms and regulatory continuity over cost minimization, with demand shifting toward premium specifications for cell and gene therapy manufacturing capabilities.
For Market Incumbents: Anticipate margin compression from South Korean and Chinese scale players by deepening backward integration into proprietary cell line development platforms and securing dedicated multi-year supply agreements with top-twenty pharmaceutical sponsors. Prioritize isolator technology retrofit programs ahead of EU Annex 1 GMP enforcement timelines to defend premium positioning in European fill-finish markets. For New Entrants and Emerging Players: Enter via viral vector manufacturing and plasmid DNA production whitespace, where qualified capacity scarcity supports premium pricing power and regulatory qualification timelines deter rapid competitive replication. Target India's PLI-incentivized biologics manufacturing zones with cost-competitive perfusion-based continuous culture offerings for export-market sponsors seeking geographic supply diversification. For Investors and Strategic Acquirers: Roll-up economics work for mid-cap CDMOs with validated mammalian cell culture platforms because biopharmaceutical patent cliffs are forcing originators to shed fixed manufacturing assets and outsource to qualified operators. Monitor FDA biosimilar guidance enforcement intensity as the inflection signal for accelerated comparability protocol outsourcing demand.| Strategic Initiative | Industry Significance |
|---|---|
| Single-Use Technology Retrofit | Reduces cross-contamination risk and accelerates product changeovers for multi-tenant facilities under FDA scrutiny. |
| Viral Clearance Platform Validation | Enables orthogonal inactivation studies that satisfy ICH Q5A requirements and compress facility qualification timelines. |
| Cell and Gene Therapy Capacity Buildout | Captures whitespace demand for viral vector manufacturing as CAR-T and gene therapy pipelines advance toward commercial scale. |
| India Manufacturing Footprint Expansion | Leverages PLI scheme incentives to serve export markets with cost-competitive operating structures outside traditional Western hubs. |
| Continuous Manufacturing Integration | Compresses cycle times through perfusion cell culture coupled with real-time release testing for personalized medicine scales. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with bioprocess engineering directors, regulatory affairs leads at CDMO operators, pharmaceutical sponsor procurement executives, and biotech development officers with secondary validation against FDA 483 inspection observations, EMA centralized procedure assessments, ClinicalTrials.gov manufacturing location disclosures, and ICH guideline revision tracking. Bottom-up capacity utilization modeling and top-down sponsor outsourcing spend analysis provided cross-verification.
The forecast window anchored historical reference periods to documented facility qualification timelines and sponsor pipeline maturation curves, with segmentation modeling across service type, client archetype, delivery model, and underlying bioproduction technology. CAGRs derived from capacity expansion announcements, regulatory filing velocity, and sponsor outsourcing contract value patterns, incorporating viral clearance validation duration and single-use technology adoption curves as industry-specific inputs.
Inputs from FDA and EMA regulatory databases were available through the study window; gaps in real-time sponsor outsourcing contract terms introduce uncertainty bands around capacity utilization assumptions. Forecasts reflect documented facility commissioning timelines and sponsor pipeline advancement rates. A model refresh is warranted upon material change in FDA biosimilar guidance enforcement or ICH Q5D harmonization progress in emerging manufacturing clusters.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Global Cytotoxic Drugs Market
Pharmaceuticals
Europe FMD Vaccine Market
Pharmaceuticals
Cefdinir API Market
Pharmaceuticals
Focal Segmental Glomerulosclerosis (FSGS) Therapeutics Market
Pharmaceuticals
Global Urothelial Cancer Drugs Market
Pharmaceuticals
Germany Diabetes Drugs Market
Pharmaceuticals
Global Preventive Vaccines Market
Pharmaceuticals
Pharma 4.0 Market
Pharmaceuticals
Fibroblast Growth Factor Receptor Inhibitor Market
Pharmaceuticals
Global Pharmaceutical Drug Delivery Market
Pharmaceuticals
Global Equine Pharmaceuticals and Supplements Market
Pharmaceuticals
Stanozolol Market
Pharmaceuticals
PARP Inhibitors Market
Pharmaceuticals
Latin America Glucagon-Like Peptide-1 (GLP-1) Agonists Market
Pharmaceuticals
G Protein Coupled Receptors (Gpcrs) Market
Pharmaceuticals
Adenosine Market